
 Sanded Grout Market | 2026-2036
Sanded Grout Market Size, Share, and Industry Trends Forecast 2026-2036
Sanded Grout Market Analysis
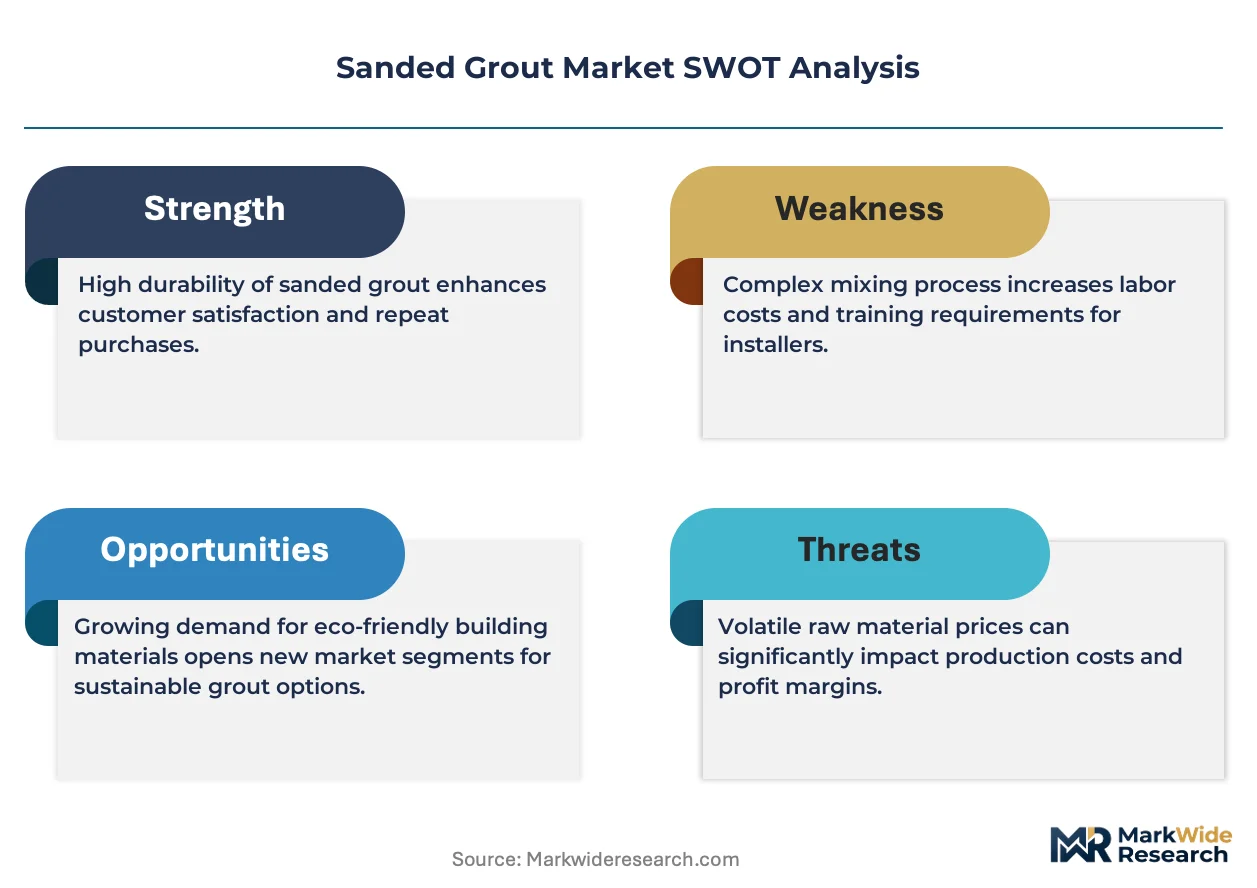
Pre-mixed bucket packaging is realigning contractor purchasing patterns toward convenience-oriented jobsite delivery. Sika AG leverages its construction chemicals distribution network to sustain bulk supply relationships with national flooring installers. MAPEI S.p.A. anchors its position through specialized color-matching systems that differentiate specification-grade offerings from commodity alternatives.
Sanded grout is a cementitious or epoxy-based joint filler containing uniformly graded silica sand, typically formulated with water-retentive additives to control curing shrinkage in joints wider than one-eighth inch. Its primary purpose is to lock tile assemblies structurally while resisting moisture infiltration in wet-area installations. Polymer modified formulations command premium positioning due to enhanced flexibility and reduced efflorescence risk in exterior applications. Ready-to-mix bag formats dominate volume in commercial flooring, where contractors prioritize batch consistency and transport efficiency over shelf-stable convenience.
EPA VOC emission standards and OSHA silica exposure limits shape formulation chemistry and jobsite handling protocols across the United States. State-level building codes in California and New York impose additional testing requirements that filter smaller suppliers from specification channels. Stakeholders must monitor evolving silica PEL enforcement patterns and polymer resin cost volatility to calibrate inventory and pricing strategies.
Market Dynamics
Polymer-modified formulations are restructuring competitive positioning as waterproofing specifications tighten under EPA VOC limits and state-level silica exposure rules. Contractors now face dual compliance pressures that favor suppliers with integrated testing and certification capabilities.
Growth Catalysts
- EPA VOC emission standards:Tighter thresholds for solvent content in construction materials are disqualifying traditional cementitious formulations from commercial specification channels.
- Residential bathroom renovation contractors:Waterproofing mandates in wet-area installations are expanding specification of polymer-enhanced systems with superior crack resistance.
- Southeastern United States construction clusters:Florida, Georgia, and Texas outpace national remodeling activity, concentrating demand for high-performance joint fillers.
Market Restraints
- Silica sand input volatility:OSHA permissible exposure limit enforcement is raising raw material processing costs and triggering supplier qualification delays.
- Epoxy resin supply concentration:Polymer feedstock availability depends on petrochemical corridor capacity in the Gulf Coast region.
- Pre-mixed shelf stability:Water-retentive additive chemistry limits distribution radius for ready-to-use bucket formats versus powder alternatives.
Strategic Opportunities
- Color-matching system integration:Digital spectrophotometry tools enable specification-grade differentiation from commodity gray alternatives.
- California and New York state testing requirements:Additional certification layers filter smaller competitors from premium channels.
- Exterior facade applications:Efflorescence-resistant polymer formulations open specification in freeze-thaw climate zones previously served by sealants.
Industry Challenges
- Silica PEL compliance training:Contractors must implement engineering controls and respiratory protection programs for dry-mix handling.
- Batch-to-batch consistency verification:Commercial flooring installers demand documented additive dispersion uniformity across multi-site projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sanded Grout Market |
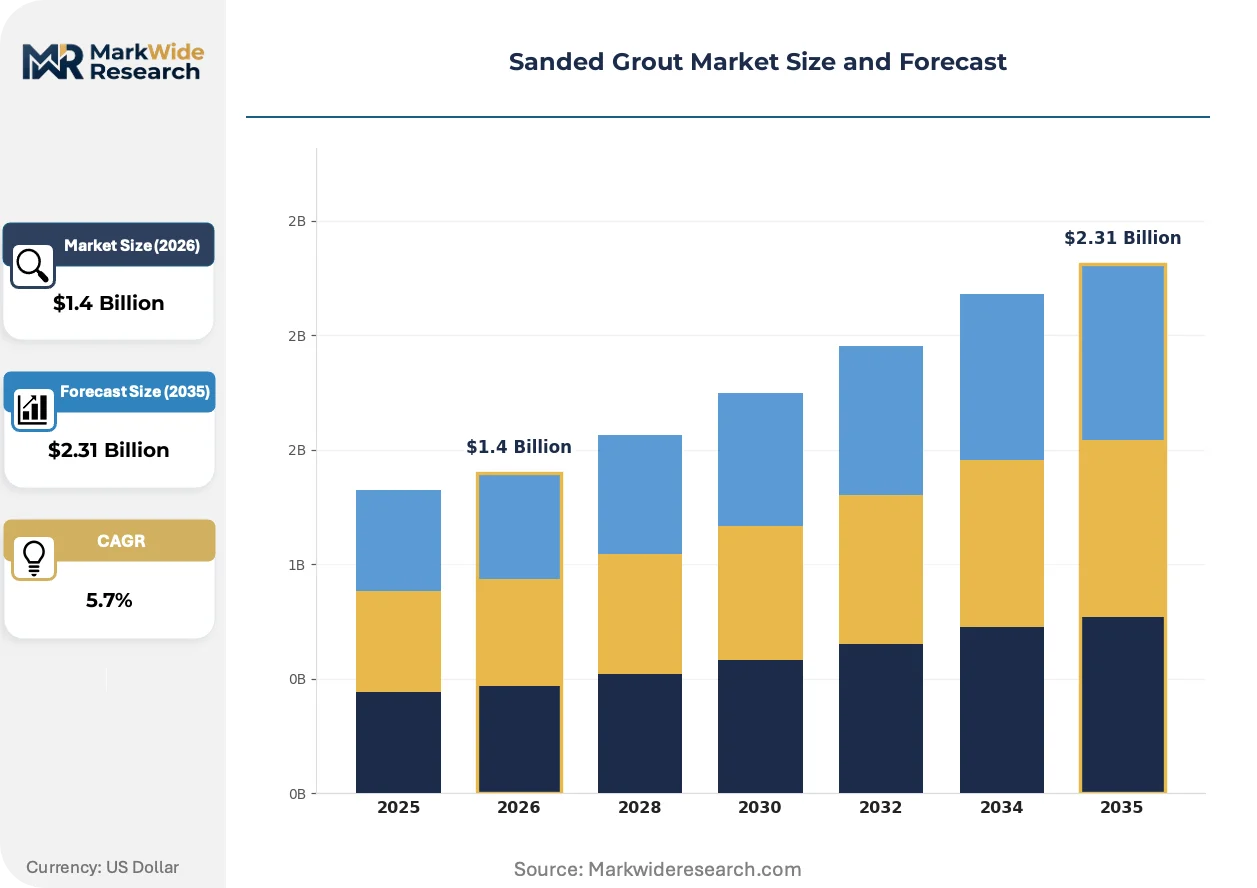
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.31 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Modified, Ready-to-Mix, Pre-Mixed, Epoxy Application: Flooring, Wall Tiles, Countertops, Swimming Pools End User: Contractors, DIY Enthusiasts, Industrial Applications, Commercial Projects Packaging Type: Bags, Buckets, Cartons, Tubs |
| Companies Covered | RPM International, Bostik, Sika AG, Ardex Group, Laticrete, Saint-Gobain, Custom Building Products, Parex USA, MAPEI S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sanded Grout Market Emerging Trajectories
Formulation chemistry and packaging formats are converging to reshape how contractors source and apply joint fillers. Three developments are compressing traditional supply relationships while opening specification pathways for differentiated offerings.
Polymer-modified sanded grout is consolidating specification authority among suppliers with integrated waterproofing certification. Commercial flooring contractors in multi-family and hospitality verticals are specifying these systems at accelerating rates for exterior balcony and pool deck installations. The technology is consolidating demand around suppliers capable of delivering batch-consistent, pre-qualified formulations that eliminate field-mix variability liability.
OSHA silica exposure limits are forcing dry-mix producers toward wet-process alternatives and pre-mixed bucket formats. The industrial consequence is a bifurcation between large-format commercial projects that can justify on-site engineering controls and residential renovation segments migrating to dust-free application systems. Residential bathroom contractors in California and Texas are responding fastest, specifying pre-mixed products that eliminate dry-cutting and mixing phases entirely.
Jobsite delivery logistics are compressing contractor purchasing cycles toward just-in-time replenishment models. National flooring installation networks are replacing distributor stock-up patterns with direct-to-site fulfillment coordinated through construction chemicals suppliers. This behavioral shift is most visible in Florida and Georgia metropolitan corridors where project density supports route-optimized delivery scheduling.
Sanded Grout Market Segmentation
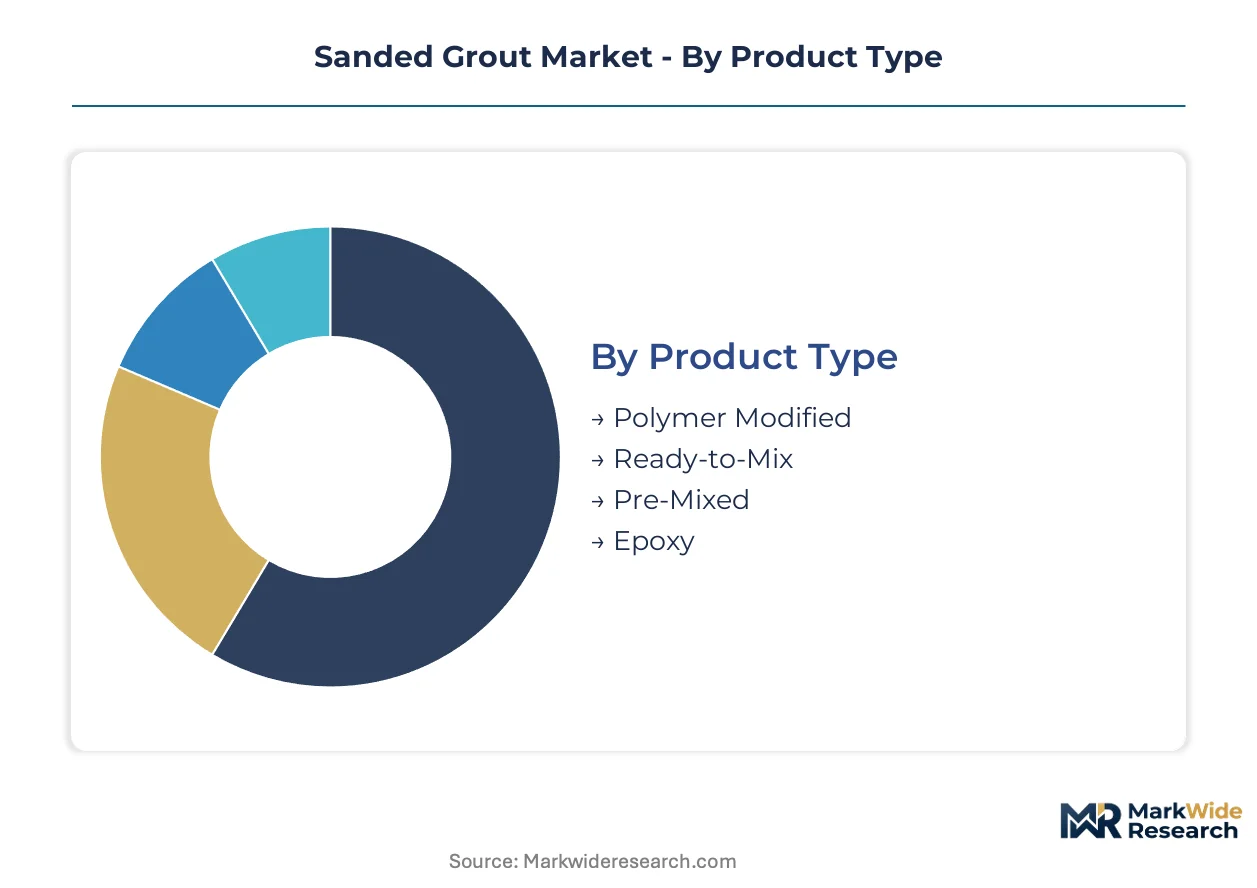
Sanded grout segmentation reveals divergent supply chain economics across formulation chemistry and packaging formats. Specification authority concentrates with suppliers capable of matching performance tier to application risk exposure.
Product Type:
Formulation chemistry separates specification-grade applications from commodity replacement cycles.
- Polymer Modified:Cementitious base incorporating acrylic or latex polymers for enhanced flexibility and bond strength. Waterproofing mandates in Florida and Texas multi-family construction are accelerating specification of these systems for exterior balcony installations.
- Ready-to-Mix:Dry powder format requiring on-site water addition with batch-to-batch consistency dependent on mixing discipline. Commercial flooring contractors in Georgia prioritize this format for transport efficiency across distributed job sites.
- Pre-Mixed:Shelf-stable wet formula eliminating field variability but constraining distribution radius due to water-retentive additive chemistry.
- Epoxy:Two-component resin system delivering chemical resistance for industrial environments and commercial kitchen specifications.
Volume sits with Ready-to-Mix; growth tilts toward Polymer Modified.
Application:
Moisture exposure severity dictates performance tier selection and warranty requirements.
- Flooring:High-traffic commercial and residential installations subject to point loading and thermal cycling. Polymer-modified formulations are gaining specification share fastest in Texas hospitality and retail verticals where crack resistance reduces callback liability.
- Wall Tiles:Vertical installations with reduced structural load but heightened aesthetic requirements. Georgia residential bathroom contractors are specifying color-matched systems for open-concept wet areas.
- Countertops:Kitchen and vanity surfaces demanding stain resistance and food-safe certification.
- Swimming Pools:Constant immersion environments requiring efflorescence-resistant chemistry and freeze-thaw durability.
Flooring commands installed volume; Swimming Pools carry the steepest expansion trajectory.
End User:
Purchasing sophistication and compliance burden shape channel access and pricing realization.
- Contractors:Professional installers with established supplier relationships and bulk procurement leverage. OSHA silica PEL compliance programs and engineering controls are filtering smaller operators toward pre-mixed alternatives in California renovation markets.
- DIY Enthusiasts:Retail-dependent segment prioritizing convenience and application guidance over batch consistency.
- Industrial Applications:Chemical processing and food manufacturing facilities specifying epoxy systems for regulatory compliance.
- Commercial Projects:Multi-site developers demanding documented additive dispersion uniformity and warranty backing.
Contractors anchor volume throughput; Commercial Projects are climbing the fastest on specification-grade conversion.
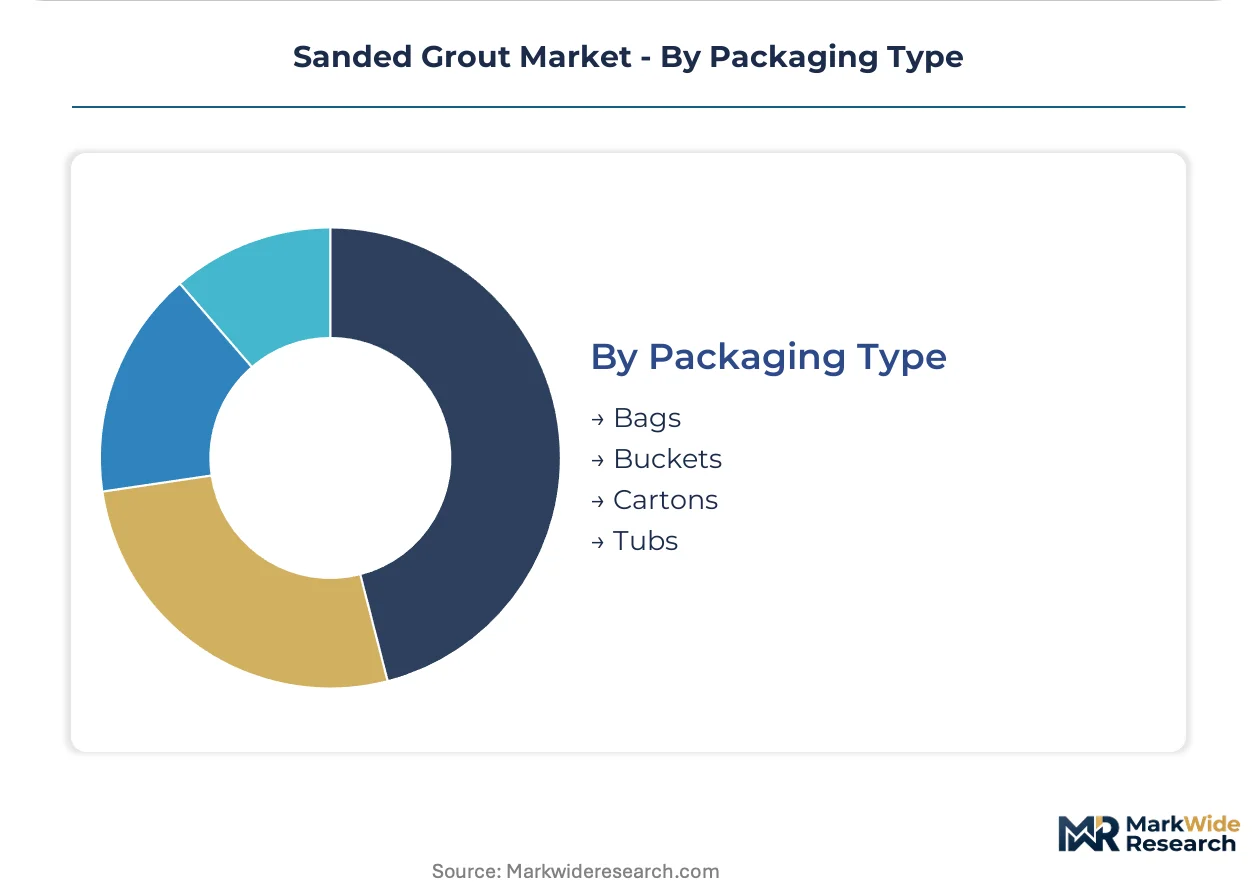
Packaging Type:
Unit economics and jobsite logistics determine format selection across project scales.
- Bags:Standard multi-kilogram dry-mix packaging dominating commercial flooring volume. Florida metropolitan corridors with high project density support palletized delivery direct to job sites.
- Buckets:Pre-mixed wet format gaining share among residential bathroom contractors in Texas and California seeking dust-free application.
- Cartons:Retail-oriented smaller units for DIY and spot repair applications.
- Tubs:Intermediate volume containers for renovation contractors with limited on-site storage.
Bags retain volume leadership; Buckets are expanding most quickly on convenience-driven conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in industrialized economies with established construction chemical infrastructure, while consumption concentrates in high-growth housing markets with active renovation cycles. The United States dominates both manufacturing and demand, though regional supply imbalances persist between Gulf Coast petrochemical corridors and coastal construction clusters.
United States
Residential bathroom renovation contractors in Florida, Georgia, and Texas are expanding polymer-modified grout specification as waterproofing standards tighten. OSHA silica permissible exposure limits and EPA VOC emission thresholds are disqualifying traditional cementitious formulations from commercial specification channels. The southeastern metropolitan corridor from Miami to Atlanta anchors the fastest demand concentration, with contractors prioritizing pre-mixed bucket formats for dust-free application.
Germany
Commercial flooring contractors specify high-performance joint fillers for multi-family and hospitality verticals with accelerating frequency. REACH compliance and CE marking requirements filter smaller suppliers from premium specification channels, consolidating authority among integrated construction chemical producers. The industrial cluster around Cologne-Leverkusen supports formulation chemistry innovation for freeze-thaw resistant exterior applications.
China
Rapid urbanization in tier-one and tier-two cities is expanding ceramic tile installation volume for residential and commercial interiors. GB standards for construction materials and MIIT industrial policy directives shape local formulation requirements and import substitution patterns. The Yangtze River Delta manufacturing belt around Shanghai supplies both domestic consumption and export markets with cost-optimized dry-mix alternatives.
India
Growing metro rail infrastructure and commercial real estate development in Maharashtra, Karnataka, and Telangana are expanding specification-grade grout demand. BIS certification requirements and state-level building codes create compliance barriers that favor established construction chemical suppliers with testing capabilities. The Mumbai-Pune industrial corridor concentrates distribution infrastructure for western and southern regional markets.
Brazil
Hospitality and retail construction in São Paulo and Rio de Janeiro is driving specification of efflorescence-resistant formulations for high-humidity installations. ANVISA regulatory frameworks for construction materials and state environmental agencies impose additional testing layers that slow market entry for unqualified suppliers. The southeastern industrial triangle anchors both domestic production capacity and import distribution for specialized epoxy systems.
Sanded Grout Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation chemistry tiers, creating a bifurcated structure where scale-driven commodity supply coexists with specification-grade differentiation. The vendor base clusters around three strategic archetypes: integrated construction chemical conglomerates with global distribution networks, regional specialists with color-matching and application technical capabilities, and private-label manufacturers serving retail and contractor channels. Dominant competitive moves include backward integration into polymer resin supply and geographic expansion through construction chemicals distribution partnerships.
Among diversified construction chemical conglomerates, Sika AG and Saint-Gobain exemplify the integrated archetype with broad formulation portfolios spanning multiple building material categories. MAPEI S.p.A. occupies a specialist position within the specification-grade tier, differentiated by technical application support and color system capabilities. RPM International represents the holding-company model, aggregating multiple branded construction product lines under centralized distribution infrastructure.
| Leading Market Players |
|---|
| RPM International |
| Bostik |
| Sika AG |
| Ardex Group |
| Laticrete |
| Saint-Gobain |
| Custom Building Products |
| Parex USA |
| MAPEI S.p.A. |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up flooring specialists have consolidated regional distributor networks across Florida and Texas, tightening supply discipline while enforcing three-tier pricing structures across premium polymer-modified, standard cementitious, and economy dry-mix tiers. This ownership concentration links silica sand procurement leverage directly to contractor rebate programs and specification-grade premium capture.
Pricing Analysis
Margin tightening in standard cementitious tiers reflects OSHA silica PEL compliance costs and wet-process conversion investments. Three-tier pricing structure across premium, standard, and economy levels separates polymer-modified waterproofing systems from commodity dry-mix alternatives, with certification grade and volume scale as primary differentiation drivers. Pricing pressure intensifies in economy tiers as Gulf Coast petrochemical volatility feeds resin cost uncertainty. DIY enthusiasts show highest price sensitivity; commercial multi-site developers prioritize batch consistency over unit cost.
Supply Chain Analysis
Freight cost escalation from Gulf Coast polymer resin corridors to southeastern construction clusters compresses distribution radius for pre-mixed bucket formats. Supply concentrates in the United States, Germany, and China, with raw material dependencies on silica sand, acrylic latex polymers, and epoxy resins. Single-source vulnerability in Gulf Coast petrochemical feedstock creates exposure to hurricane disruption and capacity allocation decisions. Distribution runs through construction chemicals specialists with route-optimized jobsite delivery capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polymer-modified formulation chemistry is displacing traditional cementitious systems as waterproofing mandates tighten, creating a technology-transition window where integrated certification capabilities determine competitive survival.
For Market Incumbents: Cement specification authority through backward integration into polymer resin supply and captive control over color-matching system IP. Invest in California and New York state testing certifications to filter smaller competitors from premium channels. Defend against pre-mixed bucket entrants by accelerating dust-free application training programs for contractor networks.
For New Entrants and Emerging Players: Begin with exterior facade applications in freeze-thaw climate zones where efflorescence-resistant polymer formulations open specification pathways previously served by sealants. Target residential bathroom renovation contractors in Texas and Georgia metropolitan corridors with route-optimized jobsite delivery partnerships. Lead with digital spectrophotometry tools that enable specification-grade color differentiation from commodity gray alternatives.
For Investors and Strategic Acquirers: Accelerating specification of pre-mixed bucket formats among California residential contractors is the leading indicator that dust-free application systems are crossing the adoption threshold. Construction chemical specialists with integrated testing laboratories and state-level certification capabilities represent the most defensible acquisition profile. Watch OSHA silica PEL enforcement patterns as the signal for wet-process conversion investment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Resin Supply | Gulf Coast petrochemical corridor access secures formulation cost stability against feedstock volatility. |
| State-Level Certification Investment | California and New York testing requirements filter smaller competitors from premium specification channels. |
| Color-Matching System Development | Digital spectrophotometry tools differentiate specification-grade offerings from commodity gray alternatives. |
| Route-Optimized Jobsite Delivery | Florida and Georgia metropolitan density supports just-in-time replenishment for contractor convenience conversion. |
| Dust-Free Application Training Programs | OSHA silica PEL compliance positioning captures residential renovation contractors migrating from dry-mix handling. |
Methodological Framework
Independent corroboration across flooring contractor procurement directors, construction chemicals distribution managers, and state regulatory affairs specialists underwrites the qualitative findings. Primary interviews with residential bathroom renovation contractors, commercial flooring installers, and polymer resin procurement leads combined with secondary validation from EPA VOC emission filings, OSHA enforcement pattern databases, and state building code amendments. Bottom-up project pipeline analysis and top-down construction spending triangulation anchored volume estimates.
Comparable-period anchoring to historical installation volumes and formulation mix shifts structured the projection framework across the analysis window. Segmentation dimensions modeled include formulation chemistry tier, packaging format, application risk exposure, and end-user procurement sophistication. CAGRs derived from weighted average of segment growth trajectories, with inputs including southeastern United States housing starts volatility and polymer resin cost indices.
Underlying measurement precision varies by segment; polymer-modified and pre-mixed categories carry tighter precision than commodity dry-mix tiers due to concentrated supplier reporting. Forecasts reflect assumptions about EPA VOC threshold stability and OSHA silica PEL enforcement intensity. Stakeholders should weight assumptions against their own operating context and regional regulatory exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Polymer Concrete Market
Building Materials
Qatar Facade Market
Building Materials
Global FRP Rebar Market
Building Materials
Bolt (Fastener) Market
Building Materials
Germany Architectural Coatings Market
Building Materials
Construction Stone Market
Building Materials
Precast Concrete Retaining Walls Market
Building Materials
France Architectural Coatings Market
Building Materials
Blended Cement Market
Building Materials
Global Facade Market
Building Materials
Roofing and Tile Underlayment Market
Building Materials
North America Construction Aggregates Market
Building Materials
Cribbing Blocks Market
Building Materials
Europe Acrylic Resin Dispersion Based Primers in Construction Market
Building Materials
Calcium Aluminate Cement Market
Building Materials
Asia-Pacific Facade Market