
 Earthen Plasters Market | 2026-2036
Earthen Plasters Market Size, Share, and Industry Trends Forecast 2026-2036
Earthen Plasters Market Analysis
France is reshaping earthen plaster supply chains through expanded artisan training centers and regional clay sourcing cooperatives. American Clay Enterprises LLC leverages domestic mineral deposits to sustain vertically integrated production across the American Southwest. Clayworks Ltd anchors British specification through heritage conservation partnerships and museum-grade finish credentials. Claytec Baustoffe Aus Lehm dominates German-speaking markets with DIN-certified clay board and plaster systems engineered for passive house assemblies.
Earthen plaster denotes a breathable wall finish composed primarily of unfired clay, sand, and natural fiber binders, applied in wet layers that harden through desiccation rather than hydraulic set, typically achieving vapor permeability ratings exceeding 5 SD value. Its primary commercial purpose lies in regulating indoor humidity and thermal mass within energy-efficient envelopes. Clay plaster commands the largest product type share where heritage compatibility and moisture buffering drive architect specification. Interior application outpaces exterior volumes due to lower weathering risk and simpler substrate preparation, though thermal insulation segments gain traction where straw-clay composites meet Passivhaus criteria. Direct sales channels control premium project flows while distributors occupy mid-market renovation trade.
EU Green Deal building renovation targets and REACH compliance for natural additive chemistry shape product formulation decisions across member states. ECHA oversight of biocide-free preservatives intersects with national heritage codes in Italy and Spain, where traditional lime-cocciopesto recipes require material passport documentation. Stakeholders must monitor how emerging carbon accounting rules for embodied construction materials redefine competitive positioning between regional clay pit operators and imported cement-lime alternatives.
Market Dynamics
The EU Green Deal's building renovation targets are compressing specification timelines for breathable envelope materials as member states transpose energy performance mandates into national building codes.
Growth Catalysts
- EU Green Deal building renovation targets:Member states must renovate millions of square meters annually, accelerating architect specification of clay-lime systems for thermal mass and humidity control.
- Passive house certification proliferation:German and Austrian certifiers now mandate vapor-permeable finishes for wall assemblies, elevating DIN-certified clay plaster to default specification status.
- Heritage restoration pipelines:France's regional conservation authorities have expanded material passport requirements for traditional lime-cocciopesto recipes, locking in artisan clay sourcing.
Market Restraints
- Regional clay deposit concentration:Premium kaolin and illite deposits cluster in specific French and German quarry districts, exposing formulators to localized supply interruptions.
- Biocide-free preservative chemistry costs:ECHA oversight of natural additive compliance under REACH elevates raw material expenses versus conventional cement-lime alternatives.
- Cement-lime substitution pressure:Lower-cost hydraulic plaster systems capture mid-market renovation trade where breathability specifications remain discretionary.
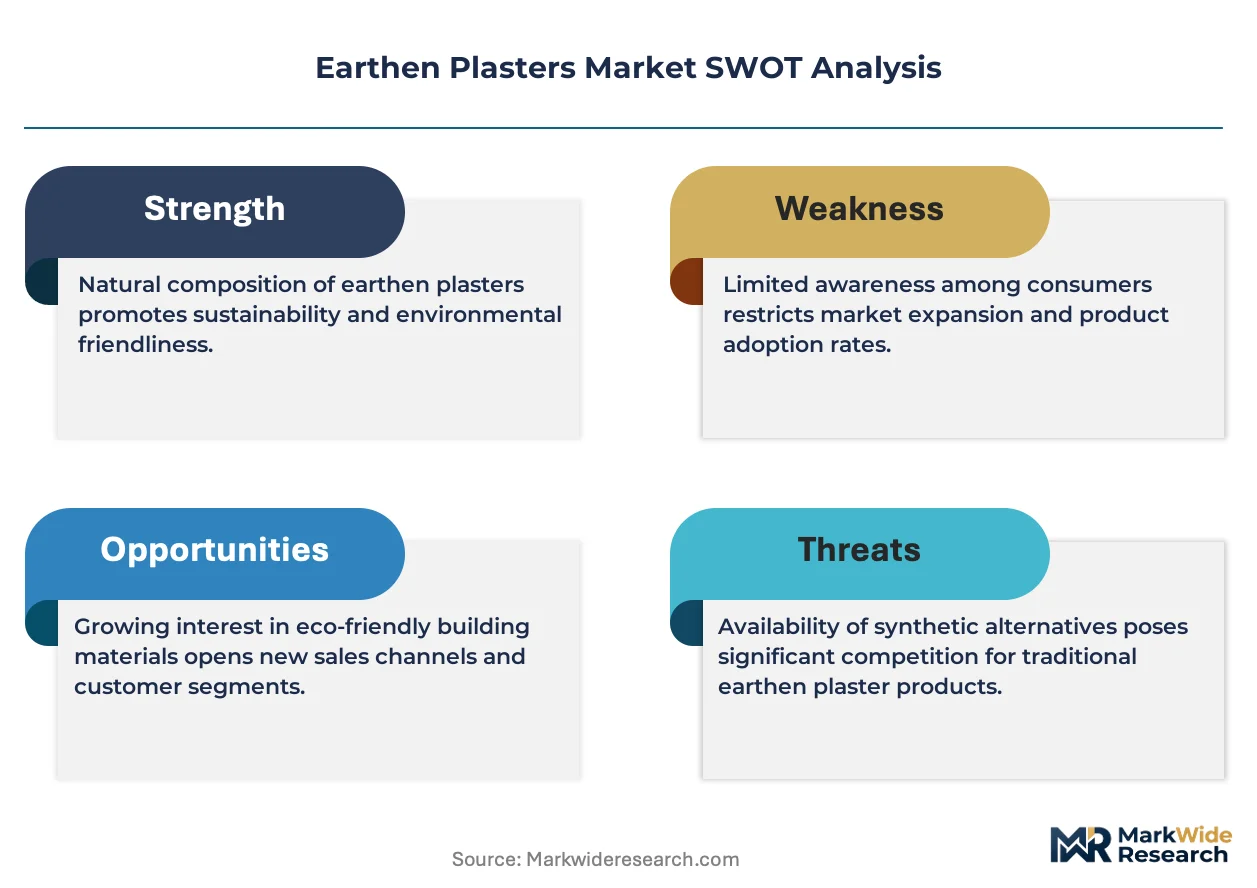
Strategic Opportunities
- Underpenetrated Nordic markets:Sweden and Finland maintain minimal earthen plaster specification despite stringent moisture management requirements in timber-frame construction.
- Carbon accounting integration:Emerging embodied carbon rules for construction materials reward unfired clay systems with near-zero process emissions versus calcined alternatives.
- Straw-clay composite thermal insulation:Passivhaus-certified straw-clay boards create new specification entry points for exterior envelope applications previously dominated by mineral wool.
Industry Challenges
- Artisan training pipeline gaps:Traditional wet-application techniques require multi-year apprenticeships, constraining installation capacity as project volumes accelerate.
- Material passport documentation burdens:Italian and Spanish heritage codes demand batch-level traceability for regional clay and natural fiber inputs, extending project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Earthen Plasters Market |
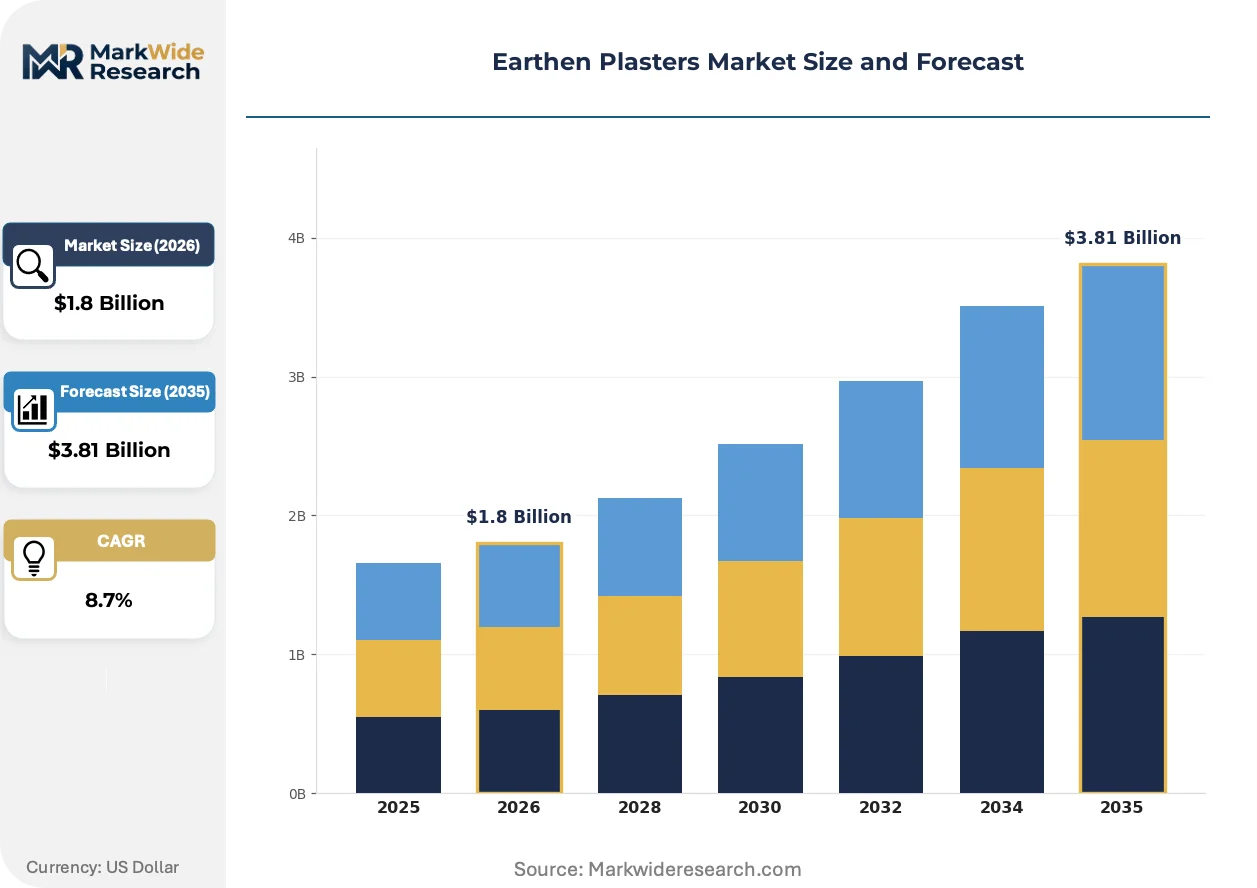
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clay Plaster, Lime Plaster, Natural Fiber Plaster, Cement-Based Plaster End Use: Residential, Commercial, Industrial, Agricultural Application: Interior, Exterior, Decorative, Thermal Insulation Distribution Channel: Direct Sales, Online Retail, Distributors, Hardware Stores |
| Companies Covered | American Clay Enterprises LLC, Clayworks Ltd, Claytec Baustoffe Aus Lehm, Clay.lt, Conluto, Armourcoat Limited, Earth Plaster Pvt Ltd, Natural Building Technologies, Bauwerk Colour, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Earthen Plasters Market Emerging Trajectories
Formulation science and specification workflows are converging to compress the performance gap between traditional craft methods and industrial-scale envelope engineering.
Pre-mixed clay plaster with engineered mineral grading and stabilized fiber reinforcement is collapsing the traditional trade-off between artisan application quality and project schedule certainty. German passive house developers now specify factory-blended systems for multi-unit residential blocks, eliminating on-site mixing variability. This standardization is collapsing price premiums previously attached to heritage-certified application methods.
REACH compliance for natural biocide-free preservatives is redirecting R&D expenditure toward plant-based stabilizers and enzymatic processing aids. ECHA's 2023 guidance on construction product additive safety triggered reformulation cycles across French and Italian suppliers. The heritage restoration segment bears the highest compliance burden, where traditional recipes must demonstrate modern toxicological profiles without sacrificing aesthetic authenticity.
Architects in Belgium and the Netherlands now bundle earthen plaster specification with whole-building moisture modeling services, shifting procurement from product-only transactions to performance-guaranteed envelope packages. This unbundling of material supply from hygrothermal consulting is compressing distributor margins while elevating specialist contractors with in-house building physics capability. The trend concentrates in Flemish residential clusters where municipal energy coaches mandate vapor-permeable retrofits.
Earthen Plasters Market Segmentation
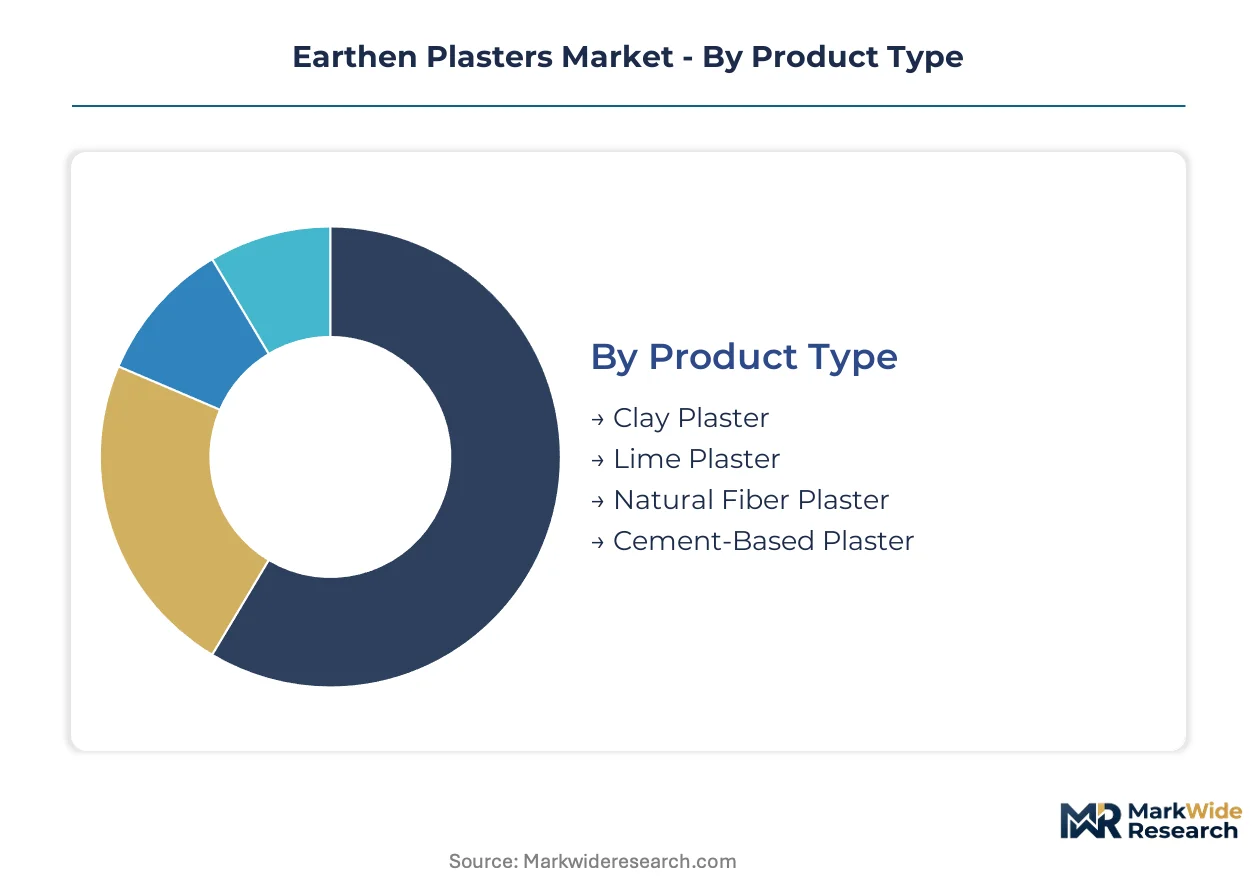
Segmentation in earthen plasters reveals how specification flows through distinct technical, end-use, and channel pathways. Product chemistry determines breathability ratings and heritage compatibility. Application context governs weathering risk and substrate preparation requirements.
Product Type:
Material composition defines vapor permeability thresholds, thermal mass contribution, and regulatory alignment with EU Green Deal energy standards.
- Clay Plaster:Unfired clay-sand-fiber blends achieve SD values above 5, enabling moisture buffering in passive house assemblies. German residential developers specify DIN-certified systems for multi-unit retrofits under national building code transpositions.
- Lime Plaster:Carbonating calcium hydroxide systems provide heritage-compatible finishes with moderate breathability. French conservation authorities mandate material passports for traditional lime-cocciopesto recipes in regional restoration pipelines.
- Natural Fiber Plaster:Hemp, straw, or cellulose-reinforced blends enhance crack resistance and thermal performance.
- Cement-Based Plaster:Hydraulic set systems trade breathability for compressive strength and weathering durability.
Clay plaster commands the established base. The steepest expansion runs through natural fiber composites meeting Passivhaus thermal insulation criteria.
End Use:
Construction sector exposure determines specification urgency, with regulatory deadlines compressing procurement timelines for envelope upgrades.
- Residential:Single-family and multi-unit housing drives volume through EU Green Deal renovation targets. Flemish municipal energy coaches mandate vapor-permeable retrofits in Belgium's timber-frame clusters.
- Commercial:Office and hospitality projects prioritize indoor air quality certification. Dutch architects bundle earthen plaster with whole-building moisture modeling for performance-guaranteed packages.
- Industrial:Warehouse and manufacturing facilities specify where humidity control protects process equipment or inventory.
- Agricultural:Barn conversions and food storage buildings leverage hygrothermal stability for crop preservation.
Residential construction anchors current specification volumes. Commercial applications are expanding most quickly as ESG reporting requirements elevate indoor environmental quality metrics.
Application:
Exposure conditions dictate formulation durability requirements and installation complexity, creating tiered margin structures across use cases.
- Interior:Protected environments enable simpler substrate preparation and lower weathering risk. German passive house certifiers mandate vapor-permeable finishes for wall assemblies, standardizing interior clay-lime specification.
- Exterior:Rain, freeze-thaw, and UV exposure demand stabilized formulations with enhanced fiber reinforcement. French regional clay sourcing cooperatives supply weather-resistant blends for heritage facade restoration.
- Decorative:Pigmented and textured finishes command artisan application premiums in high-end residential and hospitality.
- Thermal Insulation:Straw-clay composites create monolithic envelope solutions replacing mineral wool in Passivhaus-certified assemblies.
Interior application holds the volume base. Thermal insulation is climbing the fastest as straw-clay boards penetrate exterior envelope specifications previously closed to earthen systems.
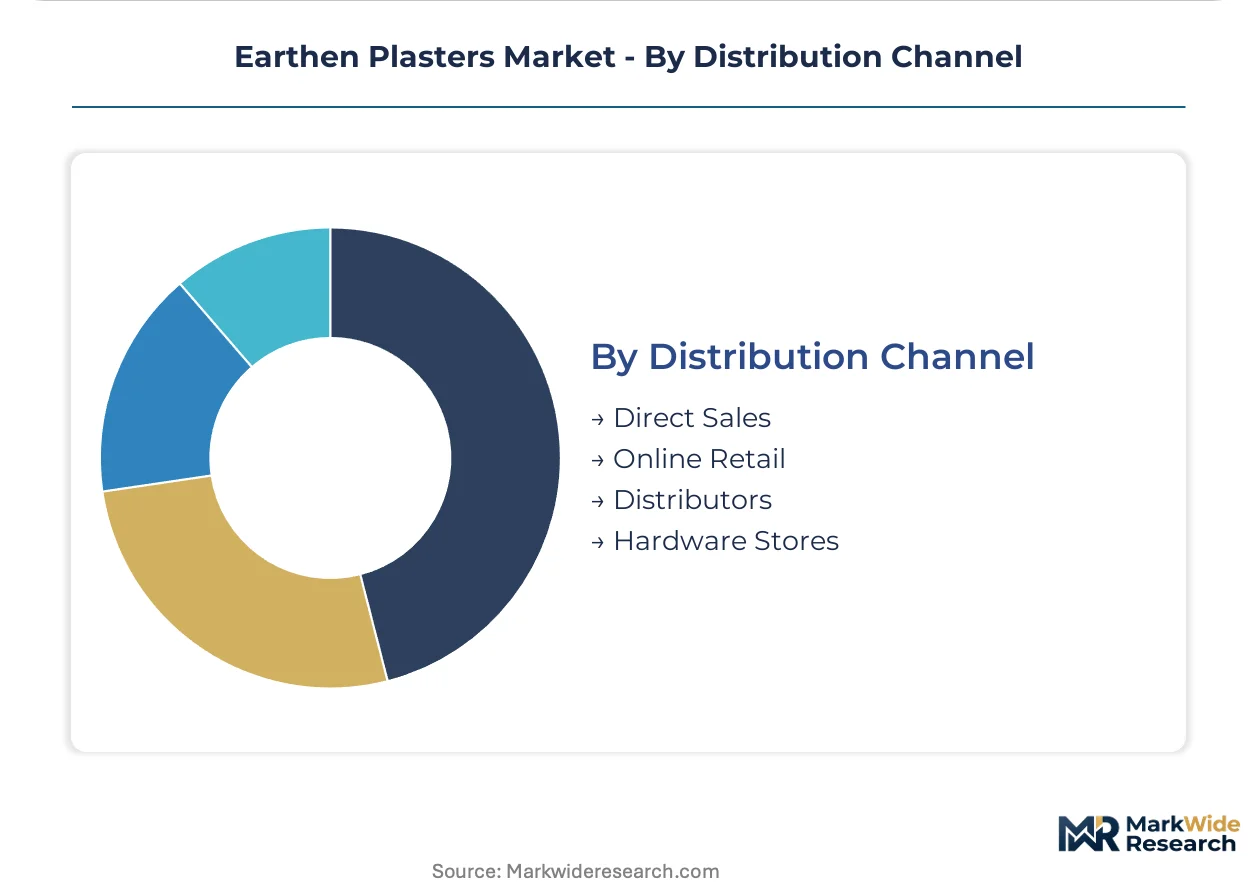
Distribution Channel:
Channel selection reflects project scale, specification complexity, and the unbundling of material supply from technical consulting services.
- Direct Sales:Manufacturer-to-contractor relationships control premium project flows with batch traceability and building physics support. Italian heritage codes demand material passport documentation that direct channels facilitate.
- Distributors:Regional building material wholesalers occupy mid-market renovation trade where breathability specifications remain discretionary.
- Online Retail:Pre-mixed bagged products reach DIY renovators and small-scale professional applicators.
- Hardware Stores:Limited shelf presence for basic clay and lime formulations in markets with established artisan traditions.
Direct sales capture the specification-intensive segment. Distributor channels are gaining share fastest as factory-blended systems standardize and compress price premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Central European clay logistics, connecting Bavarian quarry districts to North Sea ports and Mediterranean outlets. This infrastructure backbone positions the region as the dominant supply basin for heritage-compatible plasters.
Germany
Passive house certifiers in Berlin and Munich mandate vapor-permeable finishes for wall assemblies, elevating DIN-certified clay plaster to default specification status. The country's national building code transposes EU Green Deal renovation targets into enforceable energy performance standards. The Stuttgart-Karlsruhe corridor hosts specialized clay board manufacturing clusters serving multi-unit residential retrofits.
France
Regional conservation authorities in Île-de-France and Provence-Alpes-Côte d'Azur have expanded material passport requirements for traditional lime-cocciopesto recipes. ANSM and heritage code administrators enforce batch-level traceability for regional clay inputs. Lyon-based artisan training centers and Auvergne clay sourcing cooperatives are reshaping supply chain localization.
United Kingdom
Heritage conservation partnerships in London and Edinburgh drive specification of museum-grade finishes for listed building renovations. The country's building regulations increasingly reference hygrothermal performance metrics for breathable envelope materials. Cotswolds and Devon regional clay deposits support domestic formulators serving high-end residential restoration pipelines.
Italy
ECHA REACH compliance intersects with regional heritage codes in Tuscany and Veneto, where traditional lime-cocciopesto recipes require toxicological documentation without aesthetic compromise. The country's national pharmaceutical regulator framework extends to construction product additive safety assessments. Bologna and Florence host specialist applicator networks certified for historic facade restoration.
Belgium
Flemish municipal energy coaches mandate vapor-permeable retrofits in timber-frame construction clusters around Antwerp and Ghent. The country's building physics consulting sector bundles earthen plaster specification with whole-building moisture modeling services. Brussels-based architects now procure performance-guaranteed envelope packages rather than product-only transactions.
Earthen Plasters Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in raw material extraction and pre-mix formulation. The vendor base organizes around three archetypes: heritage-certified artisan suppliers, factory-blended system manufacturers, and vertically integrated clay pit operators. Consolidation pressure concentrates among mid-scale regional formulators facing REACH compliance cost escalation. Dominant competitive moves include backward integration into captive clay deposits and strategic partnerships with passive house certifiers for specification lock-in.
Among heritage-focused specialists, Clayworks Ltd and Claytec Baustoffe Aus Lehm exemplify the premium-tier archetype through regional conservation partnerships and DIN-certified system engineering. American Clay Enterprises LLC occupies a position within the geographically anchored tier, leveraging domestic mineral deposits for in-house production control across the American Southwest. These three entities represent distinct strategic postures: British heritage credentialing, German technical certification dominance, and American vertical supply chain control.
| Leading Market Players |
|---|
| American Clay Enterprises LLC |
| Clayworks Ltd |
| Claytec Baustoffe Aus Lehm |
| Clay.lt |
| Conluto |
| Armourcoat Limited |
| Earth Plaster Pvt Ltd |
| Natural Building Technologies |
| Bauwerk Colour |
| Others |
Supply Flow & Price Mechanics
The Rhine-Main-Danube waterway corridor shapes cost dynamics across earthen plaster supply chains, compressing logistics expenses for Bavarian clay pit operators while elevating delivered prices for British and Nordic buyers lacking equivalent inland freight infrastructure. This geographic asymmetry concentrates pricing power among Central European formulators and forces peripheral markets to absorb premium transport costs or accept lower-grade local substitutes.
Pricing Analysis
Three-tier pricing structure across heritage-certified artisan, factory-blended system, and bulk commodity levels governs transaction values in this market. Price differentiation rests on DIN certification status and batch-level material passport documentation, with heritage-grade products commanding substantial premiums over standardized alternatives. Cost compression in the factory-blended tier is intensifying because German passive house developers now specify pre-mixed systems for multi-unit blocks, collapsing schedule premiums previously attached to artisan application. Mid-market renovation trade exhibits highest price sensitivity, while museum-grade heritage projects demonstrate lowest elasticity due to regulatory mandate and aesthetic non-substitutability.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from German clay board manufacturers are stabilizing cash flow for regional artisan training centers and Auvergne sourcing cooperatives. Geographic supply concentration centers on France, Germany, and Italy, where premium kaolin and illite deposits cluster in specific quarry districts. Raw material dependencies include unfired clay grades, natural fiber binders, and biocide-free plant-based stabilizers. Single-source vulnerability from localized deposit concentration exposes formulators to supply interruptions. Distribution runs through direct manufacturer-to-contractor relationships for premium specification flows, with regional building material wholesalers occupying mid-market renovation channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Earthen plaster specification sits at early-cycle expansion, with EU Green Deal building renovation targets accelerating architect adoption of breathable envelope materials across member states. Penetration remains below saturation even in heritage-active markets, creating runway for volume growth.
For Market Incumbents: Build certification moats around DIN-standard clay board systems and material passport documentation capabilities. Cement-lime substitution pressure threatens mid-market positioning, requiring incumbents to anchor premium tiers through heritage conservation partnerships. Backward integration into captive Auvergne or Bavarian clay deposits secures input cost control against regional supply interruptions.
For New Entrants and Emerging Players: Swedish and Finnish timber-frame construction clusters offer underpenetrated white-space where moisture management requirements outpace earthen plaster specification. Straw-clay composite thermal insulation for Passivhaus exterior envelopes represents the most penetrable product entry point. A go-to-market angle bundling material supply with whole-building moisture modeling services bypasses established distributor relationships.
For Investors and Strategic Acquirers: Heritage-certified regional formulators with established artisan training pipelines represent the optimal acquisition target archetype for long-term viability across a 5-10 year holding window. Carbon accounting integration into embodied construction materials rules serves as the critical inflection signal, rewarding near-zero process emission systems with competitive positioning against calcined alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Clay Deposits | Auvergne and Bavarian quarry control insulates formulators from regional supply interruptions and ECHA REACH compliance cost escalation. |
| Artisan Training Pipeline Expansion | Lyon-based centers address installation capacity constraints as EU Green Deal renovation targets compress project timelines. |
| Material Passport Documentation Systems | Batch-level traceability meets ANSM and Italian heritage code requirements for traditional lime-cocciopesto recipes. |
| Straw-Clay Composite Thermal Insulation Development | Passivhaus-certified boards penetrate exterior envelope specifications previously closed to earthen systems. |
| Whole-Building Moisture Modeling Service Bundling | Flemish municipal energy coaches mandate vapor-permeable retrofits, elevating specialist contractors with in-house building physics capability. |
Methodological Framework
Initial hypotheses were tested against primary input from heritage conservation architects, passive house certifiers, clay pit operators, and regional building material distributors, then refined through secondary validation. Primary engagement encompassed specification decision-makers at conservation authorities in France and Italy, procurement leads at German multi-unit residential developers, and technical directors at DIN-certified clay board manufacturers. Secondary sources included EU Green Deal implementation documents, ECHA REACH guidance on construction product additive safety, national building code transpositions across member states, and trade flow data for unfired clay and natural fiber inputs. Bottom-up project pipeline enumeration was triangulated against top-down envelope material spend estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled by product chemistry, application exposure condition, end-use construction sector, and distribution channel complexity. CAGRs were derived from installed base growth in heritage restoration pipelines, EU renovation target transposition timelines, and Passivhaus certification proliferation rates. Industry-specific forecast inputs included artisan training center graduation volumes and regional clay deposit extraction permit approvals.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by cement-lime system manufacturers would shift outcomes toward substitution acceleration. Macroeconomic deviation in construction activity, regulatory acceleration of carbon accounting rules, or breakthrough stabilization chemistry for hydraulic alternatives would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Singapore Architectural Coatings Market
Building Materials
Asia-Pacific Kinetic Tiles Market
Building Materials
India Dry Mix Mortar Market
Building Materials
Africa Green Cement Market
Building Materials
Fire Resistant Mortar Market
Building Materials
Global Pozzolan Market
Building Materials
North America Cement Market
Building Materials
Block Paving Market
Building Materials
Europe Exterior Sheathing Market
Building Materials
Bio-Based Structural Wood Adhesives for Modular Construction Market
Building Materials
North America Architectural Coatings Market
Building Materials
Construction Glass Market
Building Materials
Composite Decking and Railing Market
Building Materials
Mexico Architectural Coatings Market
Building Materials
Foam Concrete Market
Building Materials
Germany Aluminum Door and Window Market