
 Granite Market | 2026-2036
Granite Market Size, Share, and Industry Trends Forecast 2026-2036
Granite Market Analysis
Brazilian dimension-stone quarries is pivoting toward premium slab output as Asian buyers tighten specification requirements. Paradigm Granite Pvt Ltd leverages captive quarry access in southern India to sustain consistent block supply. Cambria anchors North American engineered-stone demand while competing against natural granite in countertop specifications. PT Bintang Indokarya Gemilang dominates Indonesian export channels to Middle Eastern commercial projects.
Granite is a coarse-grained igneous rock composed primarily of quartz, feldspar, and mica, formed through slow crystallization of magma beneath Earth's surface, with Mohs hardness ratings between 6 and 7 making it suitable for high-wear surfaces. Its primary commercial purpose centers on dimension stone applications where compressive strength, polish retention, and aesthetic variation command premium positioning. Granite slabs leads product-type revenue pools due to fabrication flexibility in kitchen and bath environments, while custom cut granite captures escalating margins from luxury hospitality fit-outs. Residential end users anchors volume throughput, though commercial applications in corporate lobbies and retail facades drives specification-grade pricing.
India's BIS dimension-stone standards and Brazil's DNPM mining licensing framework collectively shape extraction economics and export market access for quarried material. REACH chemical restrictions in Europe limits certain resin-based surface treatments, redirecting demand toward untreated or water-based finished slabs. Stakeholders must monitor evolving carbon-footprint disclosure requirements from major import jurisdictions as embodied-emissions accounting penetrates construction procurement decisions.
Market Dynamics
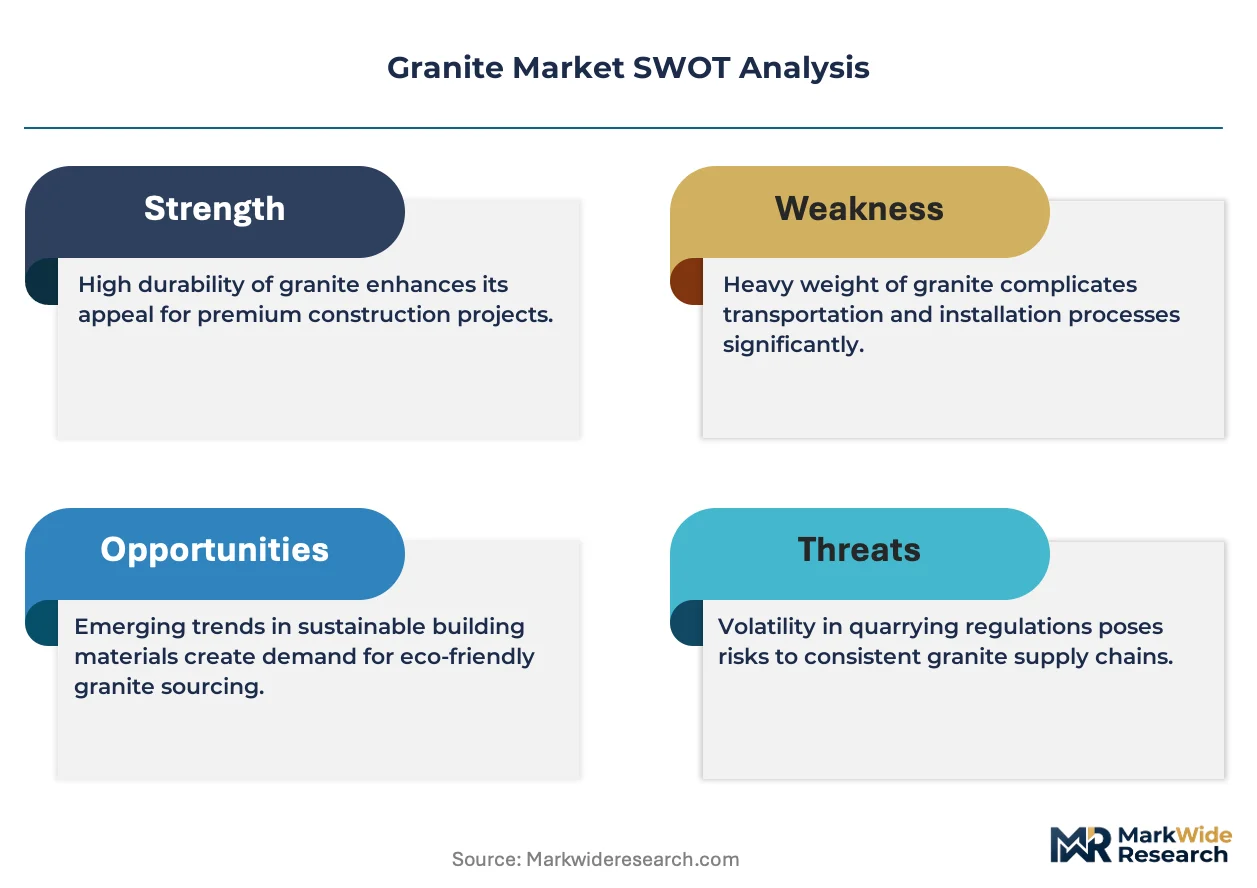
India's BIS certification tightening for dimension stone is compressing quality variance across import and domestic supply channels, forcing specification-grade producers to consolidate block sourcing or absorb testing costs.
Growth Catalysts
- Urban housing stock expansion in India:Residential construction in tier-2 and tier-3 cities sustains block demand for kitchen and bath surfacing. BIS quality mandates reinforce specification-grade pricing power for certified domestic quarries.
- REACH chemical restrictions in Europe:Resin-based surface treatments face disclosure and usage limits, redirecting specification demand toward water-based or untreated slab finishes that command premium positioning in commercial fit-outs.
- Carbon-footprint disclosure requirements:Embodied-emissions accounting in construction procurement decisions in Germany, France, and the UK is favoring quarries with verified low-carbon extraction and regional processing proximity.
Market Restraints
- Energy cost volatility in slab fabrication:Diamond-wire sawing and automated polishing lines in Minas Gerais and Tamil Nadu face input cost pressure from diesel and electricity tariffs that erode margin on standard-grade material.
- Quarry concentration risk:High-specification ornamental grades concentrate in Brazil's Minas Gerais state, creating supply vulnerability from localized licensing delays or infrastructure bottlenecks at the Port of Vitória.
- Engineered-stone substitution:Quartz surfacing from North American and Asian producers captures specification share in residential countertop segments where consistency and seam minimization outweigh natural variation preferences.
Strategic Opportunities
- Middle Eastern commercial project pipelines:Hospitality and retail facade specifications in Saudi Arabia and the UAE favor large-format granite cladding, opening export channels for Indian and Brazilian block suppliers with G623 and Santa Cecilia inventory.
- EU Green Deal procurement incentives:Public construction tenders with embedded circular-economy criteria create preferential access for quarries demonstrating water recycling, quarry-rehabilitation bonds, and renewable energy in processing.
- Water-jet cutting convergence with CNC routing:Fabricators integrating these technologies enable complex edge profiles and integrated sink cutouts that differentiate custom-cut granite from templated engineered-stone alternatives in luxury residential segments.
Industry Challenges
- Skilled CNC operator scarcity:Digital templating and automated cutting equipment in fabrication shops require trained technicians that quarries and mid-size processors struggle to recruit in Rajasthan and Espírito Santo production clusters.
- BIS certification timeline compression:Laboratory testing and documentation requirements for dimension stone imports extend order-to-delivery cycles, forcing inventory carrying costs on distributors serving project-specification deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Granite Market |
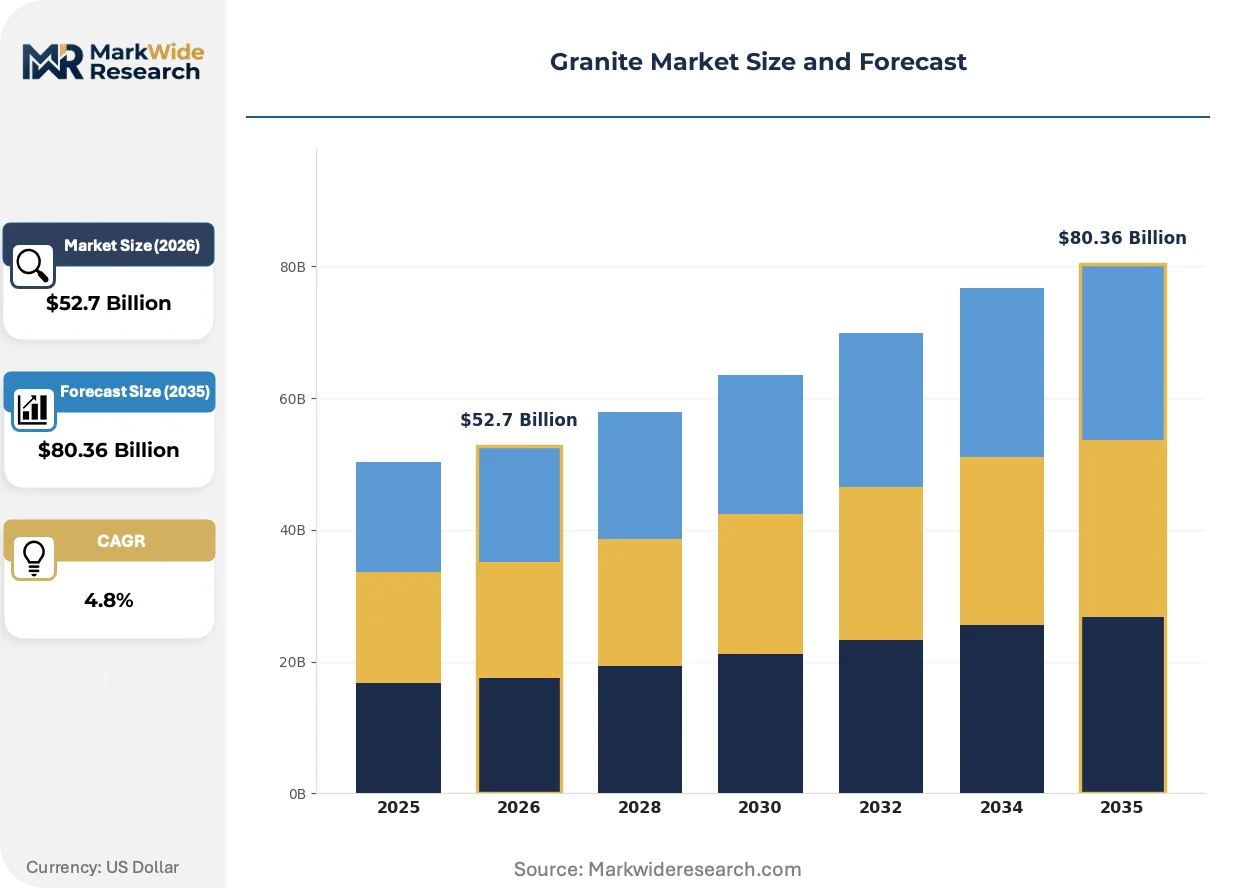
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $80.36 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granite Slabs, Granite Tiles, Granular Granite, Custom Cut Granite End User: Residential, Commercial, Industrial, Municipal Application: Countertops, Flooring, Wall Cladding, Monuments Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesale |
| Companies Covered | Paradigm Granite Pvt Ltd, PT Bintang Indokarya Gemilang, Golden Rock Granites Pvt Ltd, PT Pacific Granitamama, Pacific Granites India Pvt Ltd, Rajyog International Pvt Ltd, Amman Granites, Cambria, AG Granites Private Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Granite Market Emerging Trajectories
Diamond-wire extraction and digital inventory matching are compressing block-to-slab lead times while regulatory disclosure mandates reshape procurement qualification criteria across specification-grade supply chains.
Multi-wire gang saws with diamond-impregnated cables is overtaking traditional steel-shot blasting in primary block reduction. High-volume fabricators in Minas Gerais and Andhra Pradesh deploy this technology to improve yield rates from irregular quarry blocks. The structural consequence is overtaking margin recovery for quarries previously constrained by high waste factors in lower-grade deposits.
EU CSRD corporate sustainability reporting requirements now extend to construction material suppliers with EU revenue thresholds. Dimension stone importers must document quarry-level water usage, energy intensity, and rehabilitation bonding. Italian and German distributors are consolidating supplier bases to reduce verification burden, favoring vertically integrated quarries with existing EPD certifications.
Direct-to-fabricator digital marketplaces are compressing traditional distributor layers in North American and European supply chains. These platforms match quarry block inventory with fabricator capacity, disintermediating regional stone yards that previously controlled specification access. The shift is most visible in US residential countertop procurement, where builders and remodelers source slabs through photographed inventory rather than physical slab yards.
Granite Market Segmentation
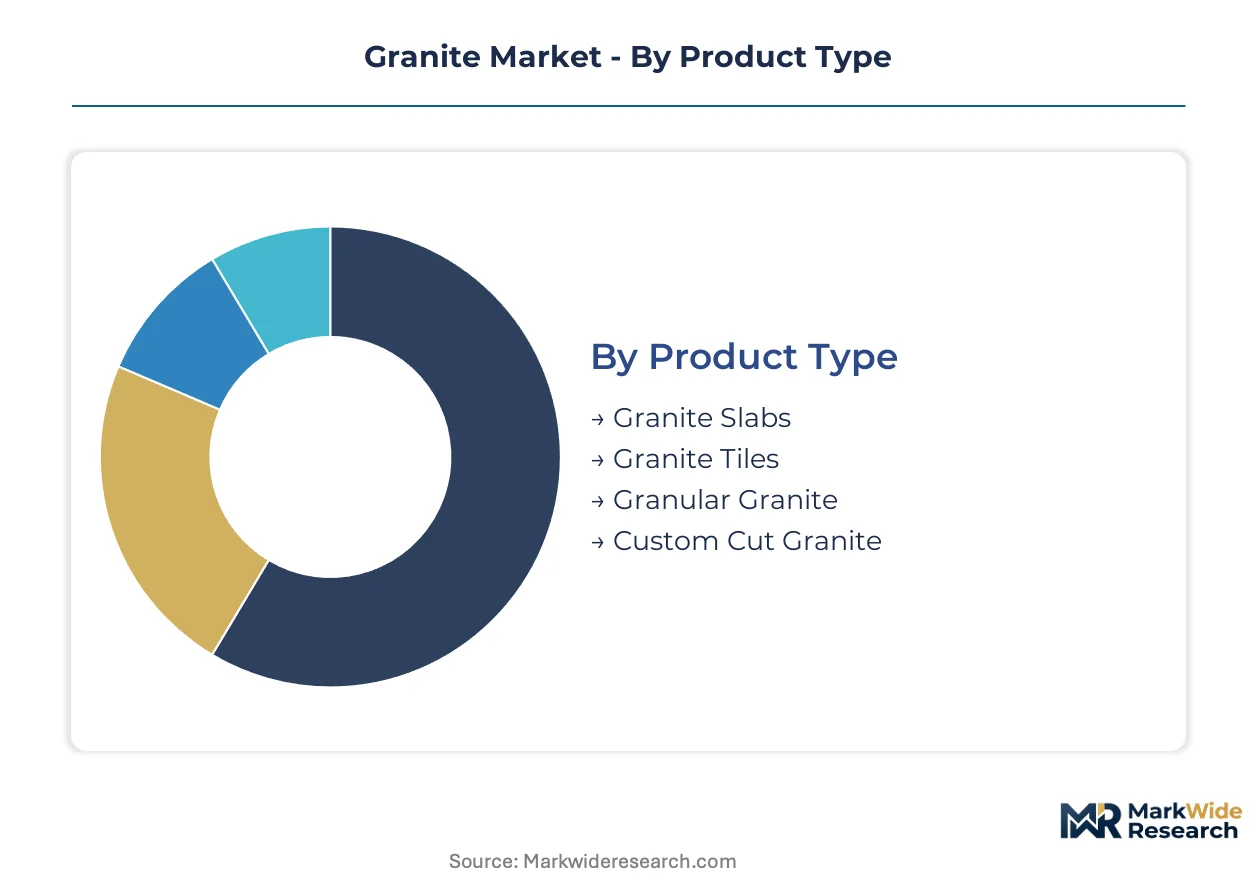
Granite's commercial value crystallizes through distinct product forms and specification pathways that separate commodity bulk from premium surfacing. Each segmentation axis reveals divergent margin structures and procurement behaviors that reshape competitive positioning across extraction, fabrication, and distribution layers.
Product Type:
Standalone slab formats dominate specification-grade revenue pools, while embedded granular forms serve infrastructure and composite manufacturing with different margin profiles.
- Granite Slabs:Large-format sawn blocks with polished or honed surfaces serve kitchen and bath countertop specifications where fabrication flexibility commands premium positioning. Demand concentrates in North American residential remodeling and Middle Eastern commercial fit-outs, with BIS-certified Indian quarries and Minas Gerais extraction clusters supplying specification-grade material.
- Custom Cut Granite:CNC-routed dimensional pieces with complex edge profiles and integrated cutouts target luxury hospitality and high-end residential installations where templated engineered stone cannot replicate natural variation. European procurement offices in Germany and France favor these pieces for circular-economy certified projects requiring documented quarry rehabilitation bonds.
- Granite Tiles:Standardized modular units with calibrated thickness serve flooring applications in commercial lobbies and retail environments where installation speed outweighs seamless aesthetics.
- Granular Granite:Crushed and screened aggregate fractions embed in concrete overlays, railway ballast, and composite stone manufacturing, operating at volume-driven margin structures distinct from dimension stone.
Volume placements concentrate in Granite Slabs; the faster expansion belongs to Custom Cut Granite.
End User:
Cost tier stratification separates project-scale procurement with extended qualification cycles from transactional residential purchasing.
- Residential:Individual homeowners and production builders drive countertop and flooring specifications through fabricator networks and big-box retail channels, with preference for consistent color lots and rapid templating turnaround.
- Commercial:Corporate offices, hospitality developers, and retail chains specify large-format cladding and reception surfacing through architectural bid processes that emphasize LEED certification and embodied-carbon documentation.
- Industrial:Manufacturing facilities and processing plants deploy granite for chemical-resistant work surfaces and heavy-duty flooring where abrasion resistance supersedes aesthetic considerations.
- Municipal:Public works departments and monument commissions source memorial stone and civic plaza surfacing through competitive bidding with domestic preference requirements in certain jurisdictions.
Commercial end users extract the steepest pricing premiums; residential channels sustain the deepest volume throughput.
Application:
Application maturity varies from established countertop specifications to emerging facade systems with diverging technical qualification demands.
- Countertops:Horizontal surfacing in kitchens and baths represents the most penetrated application, with fabricators competing against quartz and solid-surface alternatives through natural variation marketing and seam-minimization capabilities.
- Wall Cladding:Vertical exterior and interior panel installations in commercial towers and hospitality lobbies favor large-format slabs with anchoring system compatibility, driving demand for G623 and Santa Cecilia grades from Indian and Brazilian quarries.
- Flooring:High-traffic commercial and institutional installations specify flamed or bush-hammered finishes for slip resistance, with maintenance cost considerations influencing material selection over initial procurement price.
- Monuments:Memorial and civic sculpture applications concentrate in specific quarry regions with established carving traditions, operating on project timelines that buffer short-term demand fluctuations.
Countertops anchor current revenue pools; wall cladding applications are climbing the fastest as Middle Eastern commercial construction accelerates.
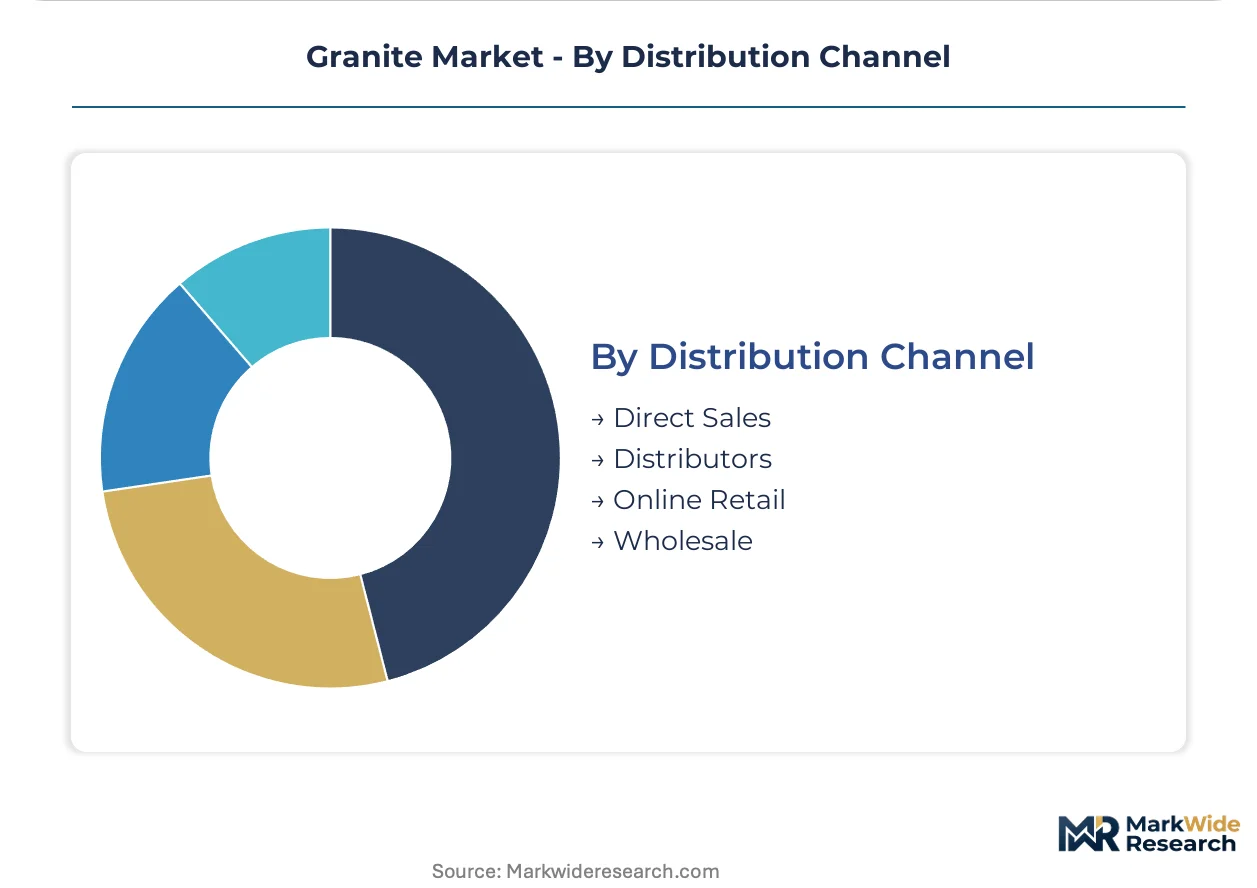
Distribution Channel:
Channel configuration determines inventory risk allocation and specification access, with digital platforms compressing traditional intermediary layers.
- Direct Sales:Quarry-direct and fabricator-direct relationships serve large-scale commercial projects with dedicated block selection and volume pricing structures that bypass distributor markups.
- Distributors:Regional stone yards maintain slab inventory for specification viewing and hold fabrication relationships, though their role compresses as digital marketplaces enable direct quarry-to-fabricator matching.
- Wholesale:Bulk material flows to construction supply houses and countertop fabricator cooperatives serving production builders with standardized grade requirements and rapid turnaround demands.
- Online Retail:Photographed inventory platforms and templating software enable residential customers to select slabs remotely, disintermediating physical slab yard visits in North American metropolitan markets.
Distributor channels still carry the heaviest volume; online retail is gaining share fastest as templating technology matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minas Gerais state anchors Brazilian extraction for high-specification ornamental grades, while India's southern quarry belts sustain block supply for Asian residential construction. Urban housing stock expansion across tier-2 and tier-3 Indian cities drives specification-grade demand for kitchen and bath surfacing.
India
Residential construction in tier-2 and tier-3 cities sustains block demand for kitchen countertops and bathroom vanities. BIS certification mandates for dimension stone tighten quality thresholds for both imports and domestic production, forcing testing cost absorption. Tamil Nadu and Karnataka quarry clusters concentrate extraction activity for G623 and Black Galaxy grades serving Middle Eastern export channels.
Brazil
High-specification ornamental granite production concentrates in Minas Gerais state quarries supplying Asian and North American premium slab markets. DNPM mining licensing frameworks shape extraction economics and export market access timelines. The Port of Vitória infrastructure handles bulk block shipments to China, Italy, and the United States, though localized bottlenecks create supply vulnerability.
China
Construction material procurement for commercial towers and hospitality fit-outs drives large-format slab imports from India and Brazil. GB standards for building materials intersect with evolving carbon-footprint disclosure requirements in provincial tendering. Xiamen and Quanzhou processing clusters dominate import block fabrication for domestic distribution and re-export to Southeast Asia.
United States
Residential remodeling and new construction sustain countertop specification demand through fabricator networks and direct-to-consumer digital platforms. EPA and OSHA regulations govern quarry dust exposure and fabrication shop silica standards. Wisconsin and Minnesota engineered-stone producers compete against natural granite in specification-grade residential segments.
Germany
Commercial construction procurement with embedded circular-economy criteria creates preferential market access for quarries demonstrating water recycling and quarry-rehabilitation bonds. REACH chemical restrictions limit certain resin-based surface treatments, redirecting demand toward water-based finishes. NRW and Bavaria fabrication clusters import Indian and Brazilian blocks for EU distribution.
Granite Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue custom-cut specialization and digital marketplace integration. The vendor base stratifies across captive-quarry operators, regional fabricators, and import-dependent distributors. Three archetypes dominate: vertically integrated quarry-to-slab processors, technology-enabled custom fabricators, and digital inventory platforms disintermediating traditional stone yards. Competitive moves center on M&A for quarry access and strategic partnerships for carbon-verified supply chains.
Among Indian captive-quarry operators, Paradigm Granite Pvt Ltd exemplifies upstream control over block supply for consistent slab production. Cambria anchors North American engineered-stone demand while occupying a competitive position against natural granite in countertop specifications. PT Bintang Indokarya Gemilang represents Indonesian export-channel dominance for Middle Eastern commercial project supply.
| Leading Market Players |
|---|
| Paradigm Granite Pvt Ltd |
| PT Bintang Indokarya Gemilang |
| Golden Rock Granites Pvt Ltd |
| PT Pacific Granitamama |
| Pacific Granites India Pvt Ltd |
| Rajyog International Pvt Ltd |
| Amman Granites |
| Cambria |
| AG Granites Private Limited |
| Others |
Supply Flow & Price Mechanics
Captive quarry access in southern India and Minas Gerais anchors both supply security and specification-grade pricing power for dimension stone producers. This upstream control insulates block costs from spot-market volatility while enabling certified producers to command premium positioning against import-dependent competitors absorbing BIS testing overhead.
Pricing Analysis
Warranty and surface-treatment bundling separates certified Indian quarries from unbundled commodity traders serving spot buyers. Three-tier pricing structure across premium, standard, and economy levels tracks BIS certification status and finish complexity. Cost compression in standard-grade material intensifies as energy tariffs in Tamil Nadu and Espírito Santo erode fabrication margins. Production builders in Indian tier-2 cities exhibit acute price sensitivity, while Middle Eastern hospitality developers prioritize specification-grade consistency over unit cost.
Supply Chain Analysis
Direct-to-fabricator digital channels handle North American residential demand, while distributor networks retain Middle Eastern commercial project access. Block supply concentrates in Brazil, India, and China, with Xiamen processing clusters re-exporting Indian and Brazilian material throughout Southeast Asia. Diamond-wire sawing equipment and resin-based surface treatments constitute critical input dependencies. Single-source vulnerability from Minas Gerais licensing delays threatens ornamental-grade availability. Distribution runs through quarry-direct relationships for large-format cladding specifications and regional stone yards for residential countertop selection.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-wire gang saw technology is displacing traditional steel-shot blasting in primary block reduction, compressing yield recovery timelines and reshaping competitive viability for quarries with lower-grade deposits.
For Market Incumbents: Acquire undeveloped quarry leases in Karnataka and Andhra Pradesh to secure block supply ahead of BIS certification expansion. Integrate water-recycling infrastructure to qualify for EU Green Deal procurement preferences. Engineered-stone substitution from Cambria and Asian quartz producers threatens countertop specification share. For New Entrants and Emerging Players: Begin with custom-cut CNC fabrication for luxury hospitality fit-outs where templated alternatives fail. Water-jet cutting convergence with digital templating creates service differentiation in European circular-economy certified projects. Target Saudi Arabian and UAE commercial facade specifications through G623 and Santa Cecilia inventory partnerships. For Investors and Strategic Acquirers: Exit pathways concentrate in vertical integration plays by engineered-stone producers seeking natural stone diversification. Quarries with verified EPD certifications and captive renewable energy in processing offer durable positioning across the medium-term horizon. Monitor carbon-footprint disclosure mandate adoption rates in German and French public construction tendering as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Quarry Lease Acquisition | Secures block supply continuity for BIS-certified producers facing certification timeline compression. |
| Water Recycling Infrastructure | Qualifies Indian and Brazilian quarries for EU Green Deal circular-economy procurement preferences. |
| Digital Marketplace Integration | Enables direct quarry-to-fabricator matching that disintermediates traditional regional stone yards. |
| CNC Routing Capability Expansion | Differentiates custom-cut granite through complex edge profiles unavailable from engineered-stone alternatives. |
| EPD Certification Investment | Reduces verification burden for Italian and German distributors consolidating supplier bases under CSRD requirements. |
Methodological Framework
Independent corroboration across quarry operators, fabrication shop managers, and architectural specification consultants underwrites the qualitative findings in this study. Primary interviews with DNPM licensing officials in Brazil, BIS certification laboratory directors in India, and Middle Eastern procurement officers for hospitality developers combined with secondary validation from customs trade data, dimension stone association reports, and SEC filings from publicly traded surfacing manufacturers. Bottom-up block production estimates and top-down construction material demand projections triangulate volume conclusions.
Comparable-period anchoring to historical extraction and fabrication capacity utilization rates established baseline assumptions across the analysis window. Segmentation modeling incorporated product type, end-user category, application, and distribution channel dimensions. CAGRs derived from regression analysis against construction output indices and urban housing stock expansion metrics. Industry-specific forecast inputs included BIS certification adoption curves and EU carbon-footprint disclosure implementation timelines.
Underlying measurement precision varies by segment; custom-cut granite and commercial end-use categories carry tighter precision than granular aggregate and municipal applications. Forecasts reflect assumptions regarding regulatory enforcement consistency and infrastructure investment continuity. Quarry rehabilitation bond requirements and REACH chemical restriction scope represent specific risk factors that could revise projections. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Brick Adhesive Market
Building Materials
East Africa Wall Putty Market
Building Materials
Radiant Barriers and Reflective Insulation Market
Building Materials
India Concealed Cistern Market
Building Materials
Fiber Reinforced Polymer Composites (FRP) Market
Building Materials
US Cement Tiles Market
Building Materials
Construction Glass Market
Building Materials
Thin Brick Market
Building Materials
Natural Stone Slab Market
Building Materials
Roof Cover Boards Market
Building Materials
United States White Cement Market
Building Materials
Europe Fireproof Cladding Market
Building Materials
Steel Products Market
Building Materials
Global Glass Fiber Reinforced Concrete Market
Building Materials
North America Cement Market
Building Materials
Fly Ash Bricks Market