
 Glass Facade Market | 2026-2036
Glass Facade Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Facade Market Intelligence
The consolidation of large-scale developers and contractors in major metropolitan markets is recalibrating supplier relationships and procurement criteria. Compagnie de Saint-Gobain S.A. leverages its extensive product portfolio to serve these large, complex projects. Meanwhile, AGC Inc. specializes in high-performance coated glass, targeting premium architectural applications. Nippon Sheet Glass Co., Ltd. sustains its market position through strong distribution networks in key Asian and European markets.
A glass facade is an exterior, non-structural building envelope system composed of glass panels and a supporting frame. These systems often incorporate double or triple glazing with inert gas fills, like argon, to achieve specific thermal U-values and solar heat gain coefficients. Demand for insulated glass units is particularly high in commercial buildings, where energy efficiency is paramount. Laminated glass products are gaining share in institutional structures due to superior safety and acoustic insulation properties.
Building energy codes, such as those influenced by the EPA in the United States and the EU Green Deal, mandate higher thermal performance for building envelopes. In parallel, China's dual carbon goals are pushing architects and developers toward facade solutions that reduce operational energy consumption. Suppliers must now decide whether to focus on compliance-grade products or invest in premium, performance-differentiated systems to capture value.
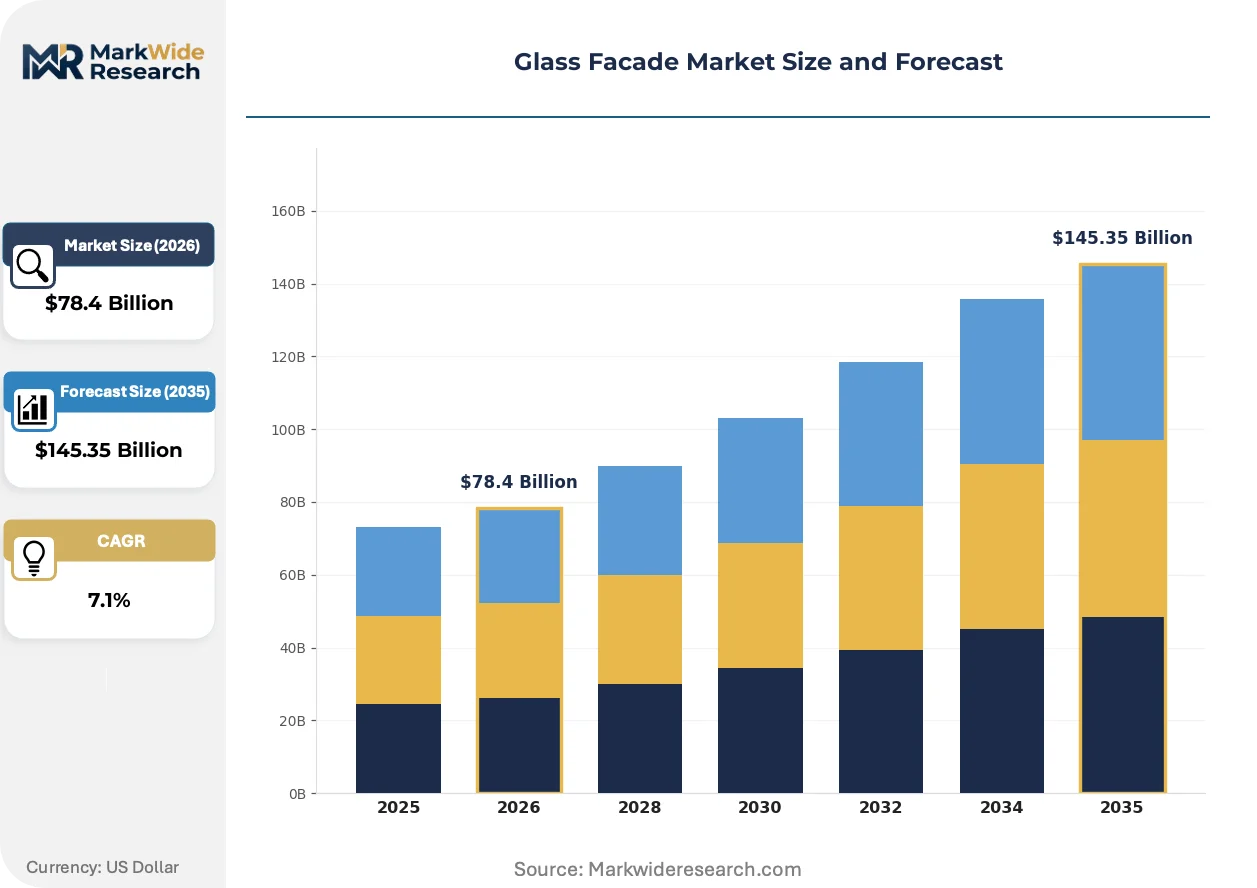
Market Dynamics
The imperative to reduce building operational energy consumption, driven by stringent national and regional energy codes, is the central force shaping investment and product development in the glass facade market. This pressure compels a move toward higher-performing, integrated systems.
Growth Catalysts
- Energy Performance Mandates:The EU Green Deal and similar frameworks require deep energy retrofits and higher standards for new construction, directly boosting demand for advanced facade systems.
- Rapid Urbanization:New commercial and high-rise residential construction in urban centers across India and Southeast Asia creates consistent, large-scale demand for facade products.
- Safety & Acoustic Requirements:Demand for laminated glass is rising in institutional buildings like schools and hospitals due to its superior safety performance and acoustic dampening properties.
Market Restraints
- High Initial Cost:The significant upfront capital investment for high-performance systems, such as triple-glazed or electrochromic facades, can be a barrier for budget-constrained projects.
- Specialized Material Sourcing:The supply chain for critical components like high-performance coatings, inert gases such as argon, and specialized interlayers for laminated glass is highly concentrated.
- Structural & Weight Constraints:The increased weight and complexity of advanced multi-glazed facade units can pose significant engineering challenges, particularly in retrofitting older structures.
Strategic Opportunities
- Building-Integrated Photovoltaics (BIPV):The convergence of solar technology and facade design allows for the creation of energy-generating building envelopes, opening a new value-added market segment.
- Building Stock Retrofitting:Mandates to upgrade the energy efficiency of existing commercial buildings in North America and Europe represent a vast, underpenetrated market for facade replacement.
- Government Incentives:Financial incentives for energy-efficient upgrades, such as tax credits associated with the US Inflation Reduction Act (IRA), create direct market pull for qualifying facade systems.
Industry Challenges
- Installer Skill Gap:A shortage of trained professionals capable of installing complex, unitized curtain wall systems correctly creates project delays and quality control risks for contractors.
- Fragmented Building Codes:Suppliers face increased costs and complexity in testing and certifying products to meet a diverse and evolving set of local, state, and national building codes.
- Manufacturing Capex:Re-tooling production lines to manufacture next-generation products like vacuum-insulated glass or large-format panels requires substantial capital investment and long lead times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Facade Market |
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $145.35 Billion |
| CAGR (2026 – 2036) | 7.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tinted Glass, Laminated Glass, Insulated Glass, Tempered Glass Installation Type: New Construction, Retrofit, Renovation, Expansion Building Type: Commercial Buildings, Residential Complexes, Institutional Structures, Industrial Facilities End User: Architects, Builders, Contractors, Developers |
| Companies Covered | Nippon Sheet Glass Co., Ltd., Xinyi Glass Holdings Limited, AGC Inc., China Glass Holdings Limited, Fuyao Glass Industry Group Co., Ltd., Compagnie de Saint-Gobain S.A., SCHOTT AG, Vitro S.A.B. de C.V., Guardian Industries Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Facade Market Strategic Shifts & Innovations
A fundamental transition from glass as a passive cladding material to an active, multifunctional building envelope component defines current innovation. This shift prioritizes dynamic performance, energy generation, and integration with smart building systems over purely aesthetic considerations.
Dynamic glass, including electrochromic and thermochromic variants, actively modulates solar heat gain and visible light transmission. Premium commercial and healthcare buildings are the primary adopters of this technology for enhanced occupant comfort and energy management. This technology is expanding into integrated smart building platforms, allowing facades to respond automatically to sensor data and predictive analytics.
China’s dual carbon goals are being implemented through more stringent GB standards for building energy performance. This directly compels developers to specify facade systems with lower thermal U-values, increasing material and construction costs. The policy most acutely impacts new high-rise construction in Tier 1 cities, accelerating the specification of high-performance insulated glass units.
Strategic partnerships are replacing transactional, project-based procurement for large-scale developments. This model favors suppliers capable of providing end-to-end design, engineering, and logistics support, displacing traditional distributors. The shift is most pronounced in master-planned urban centers across India and Southeast Asia, where consolidated developers manage vast project portfolios.
Glass Facade Market Segmentation
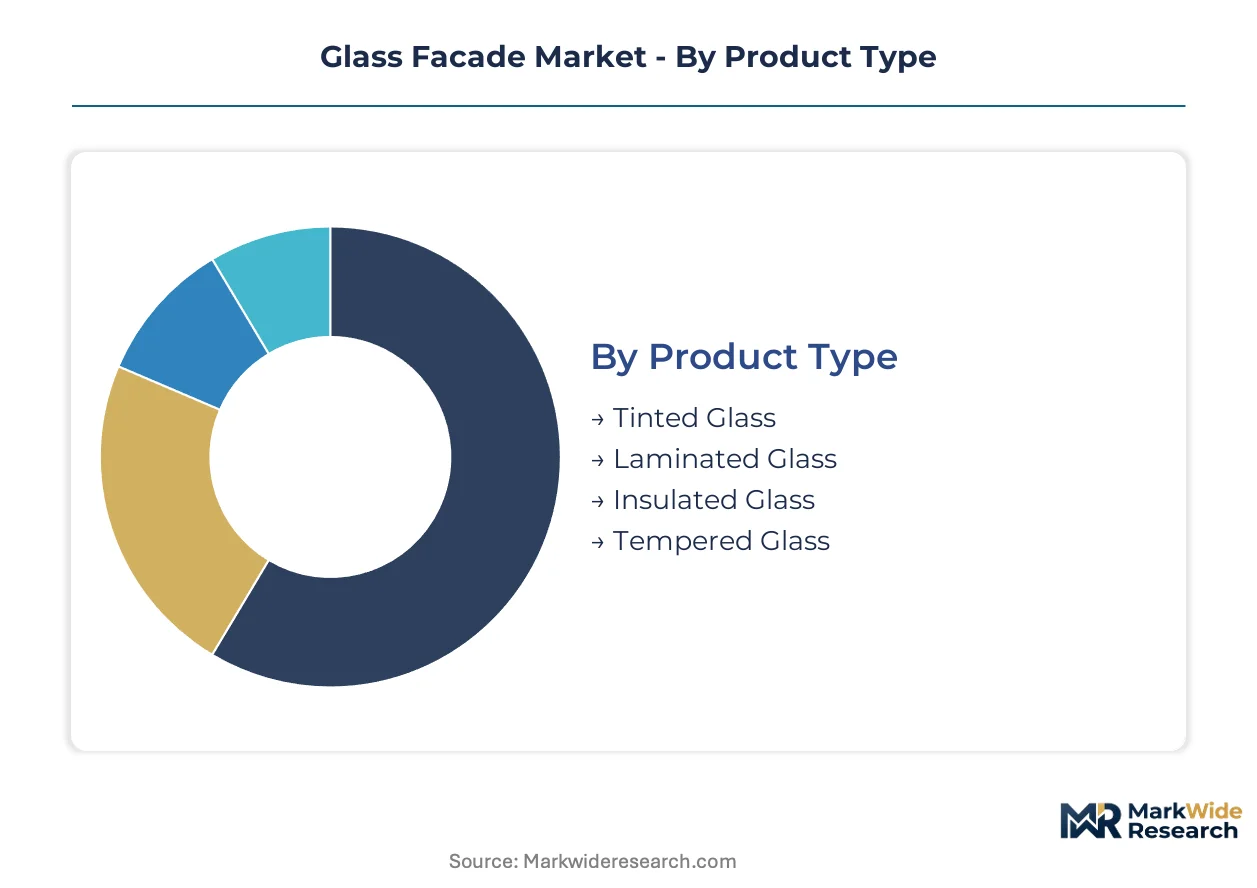
The glass facade market's segmentation reveals the diverse product technologies and application contexts driving its expansion. Understanding these distinct segments helps suppliers align product development with specific end-user demands and regulatory requirements. This granular view clarifies where value accumulates across the value chain, from material specification to final installation.
Product Type:
The supply of specialized glass products is concentrating among a few large manufacturers capable of meeting stringent performance specifications.
- Laminated Glass:This product consists of multiple glass plies bonded together with an interlayer, typically PVB or SGP, enhancing safety and acoustic performance. Demand for laminated glass is rising in institutional structures like schools and hospitals due to its superior safety properties and sound dampening.
- Insulated Glass:Comprising two or more glass panes separated by a sealed air or gas-filled space, insulated glass units (IGUs) provide superior thermal insulation. Energy performance mandates, such as those from the EU Green Deal, drive high demand for IGUs in commercial buildings.
- Tinted Glass:Tinted glass incorporates colorants to reduce solar glare and heat gain, offering basic solar control and aesthetic variation.
- Tempered Glass:Tempered glass undergoes a heat treatment process, significantly increasing its strength and causing it to break into small, blunt fragments for safety.
Insulated Glass absorbs the bulk of installed capacity; Laminated Glass is expanding most quickly.
Installation Type:
Application complexity and project scale differentiate the various installation types in the glass facade sector.
- New Construction:These projects involve installing facade systems in entirely new buildings, often large-scale commercial towers or high-rise residential complexes. Rapid urbanization in India and Southeast Asia creates consistent, large-scale demand for new construction facades.
- Retrofit:Retrofit projects replace existing facade systems in older buildings, primarily to improve energy efficiency or update aesthetics. Mandates to upgrade energy performance in North America and Europe represent a vast, underpenetrated market for facade replacement.
- Renovation:Renovation involves significant upgrades or alterations to existing building facades, often without full replacement, to enhance appearance or functionality.
- Expansion:Expansion projects add new sections or wings to existing structures, requiring facade integration with the current building design.
New Construction projects continue to drive significant volume, while Retrofit initiatives show considerable growth potential.
Building Type:
The specific requirements of customer types dictate the performance and aesthetic choices for different building facade applications.
- Commercial Buildings:This segment includes office towers, retail centers, and hospitality venues, which prioritize aesthetic appeal, energy performance, and occupant comfort. Demand concentrates in rapidly urbanizing centers for high-rise office towers and mixed-use developments.
- Institutional Structures:These encompass schools, hospitals, and government buildings, where safety, security, and acoustic insulation are paramount. Laminated glass products are gaining share in institutional structures due to superior safety and acoustic insulation properties.
- Residential Complexes:Multi-unit dwellings and high-rise apartments form this segment, focusing on aesthetics, thermal comfort, and sound attenuation for residents.
- Industrial Facilities:This segment includes factories, warehouses, and manufacturing plants, which often require durable, functional, and cost-effective facade solutions.
Commercial Buildings generate the largest revenue, and Institutional Structures are experiencing accelerated specification of advanced systems.
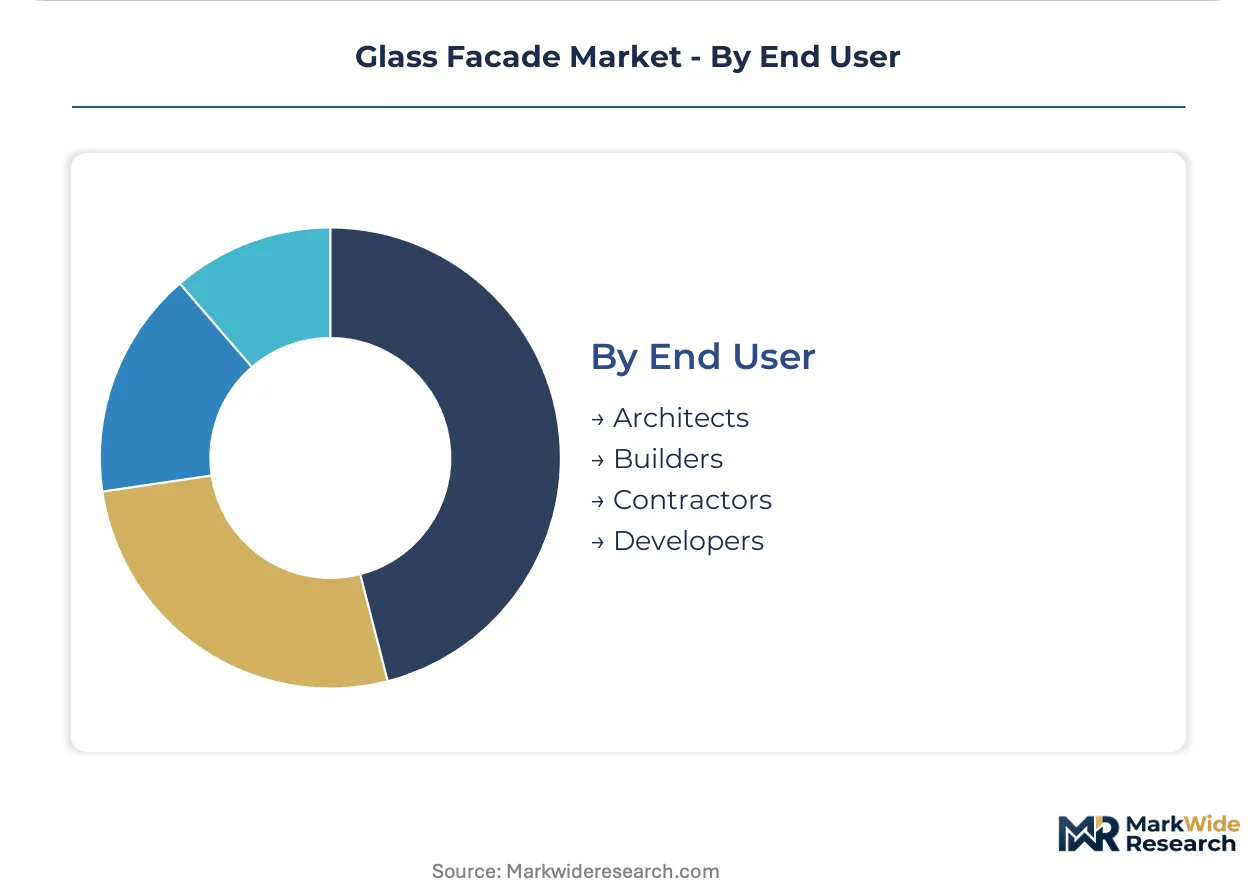
End User:
Margin capture varies significantly across the end-user segments, influenced by project involvement and specification power.
- Developers:These entities initiate and manage large-scale construction projects, making critical decisions on facade system specification and supplier selection. The consolidation of large-scale developers in major metropolitan markets recalibrates procurement criteria for suppliers.
- Contractors:General contractors and facade specialists are responsible for the procurement, installation, and project management of facade systems. A shortage of trained professionals capable of installing complex unitized curtain wall systems creates project delays and quality control risks.
- Architects:Architects design building envelopes, specify material performance, and influence aesthetic choices for glass facade systems.
- Builders:Builders execute the construction plans, often working directly with contractors to install facade components according to specifications.
Developers hold significant influence over product selection, while Contractors manage the critical installation phase.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for glass facade systems concentrates in rapidly urbanizing centers across Asia and established metropolitan markets in Europe and North America. This concentration drives specific regional requirements for energy performance and structural integrity. Project scale and regulatory frameworks significantly influence material specification and procurement patterns across different geographies.
China
China's dual carbon goals intensely drive demand for high-performance glass facades in new construction. More stringent GB standards for building energy performance compel developers to specify systems with lower thermal U-values. Major Tier 1 cities like Shanghai and Beijing are rapidly adopting advanced insulated glass units for high-rise developments.
India
Rapid urbanization across India fuels substantial demand for new glass facade installations, particularly in commercial and high-rise residential projects. Government initiatives promoting smart city development encourage modern, energy-efficient building envelopes. Metropolitan centers such as Mumbai, Bengaluru, and Delhi-NCR are experiencing significant construction booms.
United States
The United States market sees increasing demand for facade retrofitting to improve energy efficiency in existing commercial buildings. EPA building energy codes and incentives from the US Inflation Reduction Act (IRA) stimulate upgrades. Major urban cores like New York City and Chicago represent significant markets for facade replacement projects.
Germany
Germany's market for glass facades is strongly influenced by the EU Green Deal's stringent requirements for building energy performance. This directive mandates higher thermal performance for both new construction and deep energy retrofits. Urban centers such as Frankfurt and Berlin lead in the adoption of advanced facade systems.
United Arab Emirates
The United Arab Emirates exhibits consistent demand for glass facades due to its ambitious architectural projects and rapid infrastructure expansion. Local green building codes, including Estidama, set high standards for energy efficiency and material performance. Dubai and Abu Dhabi continue to launch large-scale developments requiring sophisticated facade solutions.
Glass Facade Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue premium, performance-differentiated systems and integrated solutions. The supply of specialized glass products is concentrating among a few large manufacturers capable of meeting stringent performance specifications. Strategic archetypes include global integrated glass manufacturers, specialized high-performance coating providers, and regional fabrication and installation specialists. Portfolio diversification and strategic partnerships represent dominant competitive moves.
Among global manufacturers, Compagnie de Saint-Gobain S.A. exemplifies an integrated player leveraging an extensive product portfolio to serve large, complex projects. AGC Inc., a Japanese-based corporation, occupies a position specializing in high-performance coated glass for premium architectural applications, often targeting bespoke architectural designs. Nippon Sheet Glass Co., Ltd., another Japanese entity, sustains its market standing through strong distribution networks across key Asian and European markets, anchoring regional supply and ensuring widespread product availability.
| Leading Market Players |
|---|
| Nippon Sheet Glass Co., Ltd. |
| Xinyi Glass Holdings Limited |
| AGC Inc. |
| China Glass Holdings Limited |
| Fuyao Glass Industry Group Co., Ltd. |
| Compagnie de Saint-Gobain S.A. |
| SCHOTT AG |
| Vitro S.A.B. de C.V. |
| Guardian Industries Corporation |
| Others |
Cost & Logistics Intelligence
Specialized glass product costs, driven by energy-intensive manufacturing processes, translate directly into higher downstream pricing for advanced facade systems. This cost structure influences procurement decisions for developers in rapidly urbanizing centers.
Pricing Analysis
Volume-based contracts typically define pricing for standard glass facade systems, while premium, performance-differentiated systems command higher margins. Project-based pricing dominates for complex, bespoke architectural applications, reflecting significant customization and engineering input. Price differentiation stems from the specific U-value achieved and the inclusion of advanced coatings. Pricing pressure stems from intense competition in the standard insulated glass unit segment. Institutional structures demonstrate lower price sensitivity due to stringent safety and acoustic requirements, prioritizing performance over upfront cost.
Supply Chain Analysis
Direct-to-developer channels handle large-scale commercial project demand, ensuring integrated design and logistics support. Geographic supply concentration for high-performance coatings and inert gases like argon centers in specialized manufacturing hubs across Europe and East Asia. The supply chain draws heavily from silica sand for glass production and specialized polymers for interlayers. Single-source vulnerability for advanced coating technologies represents a structural supply chain risk. Regional fabrication and installation specialists then integrate these components for final project delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play, where the imperative for manufacturing next-generation products requiring substantial capital investment is forcing smaller, less capitalized players out.
For Market Incumbents: Acquire specialized coating technologies and advanced manufacturing capabilities. This move mitigates the threat from emerging niche players and secures intellectual property critical for high-performance systems. Deepen vertical integration into specialized interlayer production to control quality and supply. Invest in installer training programs to bridge the skill gap and maintain project quality standards.
For New Entrants and Emerging Players: Capture market share in building stock retrofitting, focusing on energy efficiency upgrades in North America and Europe. This segment represents a vast, underpenetrated market with clear regulatory tailwinds. Target institutional structures with superior laminated glass offerings, emphasizing safety and acoustic performance. A go-to-market angle focusing on integrated BIPV solutions provides a strong differentiation point for sustainable projects.
For Investors and Strategic Acquirers: Increased government incentives for energy-efficient building upgrades is the leading indicator that signals sustained long-term growth for advanced facade systems. The long-term viability of the market is anchored by global decarbonization goals and urbanization trends. Target vertically integrated mid-cap specialists with strong R&D in dynamic glass or BIPV technologies. Watch for shifts in regional building code stringency, as this directly drives demand for premium products.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand advanced coating production capacity | Secures critical supply for high-performance glass and enables product differentiation. |
| Invest in BIPV R&D and integration | Unlocks new revenue streams through energy-generating building envelopes for commercial clients. |
| Develop certified installer networks | Mitigates project delays and quality risks, enhancing client confidence in complex systems. |
| Target deep energy retrofit projects | Captures growth in established markets driven by stringent energy performance mandates. |
| Form strategic partnerships with developers | Ensures early-stage project involvement and influences specification for large-scale urban developments. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, providing a comprehensive baseline for market sizing. The analysis combined these datasets with primary interviews involving architects, developers, contractors, and specialized glass manufacturers. Bottom-up and top-down triangulation validated volume and value estimates across key segments.
Granular segmentation across product type, installation type, building type, and end-user informed the analytical framework, modeling market dynamics over the projection horizon. CAGRs were derived from historical growth trends and anticipated shifts in regulatory environments and technological adoption. Industry-specific forecast inputs included projected new construction starts in Tier 1 cities and estimated retrofit project volumes in established markets.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to evolving building energy codes and raw material price volatility. The forecasts reflect assumptions regarding technological advancements and sustained urbanization rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Building Asphalt Market
Building Materials
Construction Repair Composites Market
Building Materials
ASEAN Dry Mix Mortar Market
Building Materials
Global Lightweight Aggregate Concrete Market
Building Materials
India Cement Market
Building Materials
Europe Aluminum Door and Window Market
Building Materials
Bio-Based Structural Wood Adhesives for Modular Construction Market
Building Materials
North America Building and Construction Sheets Market
Building Materials
Europe Cement Market
Building Materials
Stone Coated Steel Roofing Market
Building Materials
Long Steel Market
Building Materials
Stone Adhesive Market
Building Materials
North America Spray Polyurethane Foam for Building and Construction Market
Building Materials
Steel Sleepers Market
Building Materials
Cement Tiles Market
Building Materials
Roofing and Tile Underlayment Market