
 Shotcrete Market | 2026-2036
Shotcrete Market Size, Share, and Industry Trends Forecast 2026-2036
Shotcrete Market Intelligence
Fiber-reinforced admixture technology is reshaping shotcrete performance standards for high-stress underground applications. Sika AG leverages its polymer chemistry portfolio to dominate specialty additive supply for wet-mix formulations. BASF SE anchors its position through R&D intensity in alkali-free accelerators that reduce rebound rates. Putzmeister competes on mechanized spraying system integration, extending its reach from equipment into application training services.
Shotcrete refers to concrete or mortar pneumatically projected at high velocity onto a surface, typically employing accelerators to achieve rapid early strength within minutes and final compressive strengths exceeding 30 MPa depending on mix design. Its primary purpose lies in providing immediate structural support, waterproofing linings, and slope stabilization in geometries where conventional formwork proves impractical. Wet-mix shotcrete leads volume in tunneling applications where dust suppression and consistent hydration control matter most, while fiber-reinforced variants represent the fastest-growing category as steel and synthetic macro-fibers replace welded wire mesh for crack control. Dry-mix persists in mining contractors' portfolios where remote site logistics favor bagged material handling over ready-mix supply chains.
OSHA enforces permissible exposure limits on respirable crystalline silica during shotcrete application, directly shaping dust collection investments and wet-process preference in US infrastructure construction. The EU Green Deal's embodied carbon benchmarks are forcing reformulation of Portland cement binders, with REACH compliance adding scrutiny on accelerator chemistries. Stakeholders must monitor how robotic application systems alter labor economics and quality certification requirements across project types.
Market Dynamics
Fiber-reinforced admixture technology is compressing specification cycles in underground construction, forcing reformulation of traditional Portland cement binders and accelerating displacement of welded wire mesh reinforcement systems across tunneling and mining operations.
Growth Catalysts
- EU Green Deal embodied carbon benchmarks:Construction material procurement in European infrastructure projects now prioritizes low-carbon shotcrete formulations, creating pull-through demand for alkali-free accelerator chemistries and supplementary cementitious materials.
- Underground mining expansion in Australia:Ground support specifications in hard-rock mining operations are mandating wet-mix shotcrete with steel macro-fiber reinforcement for immediate structural integrity in high-stress geologies.
- Synthetic fiber technology maturation:Polypropylene and PVA macro-fibers are achieving performance parity with steel at reduced weight, enabling mechanized spraying in remote logistics-constrained sites where bagged dry-mix previously dominated.
Market Restraints
- Portland cement input cost volatility:Energy-intensive clinker production exposes shotcrete margins to natural gas and electricity price swings, particularly acute in European manufacturing where carbon border adjustments compound cost pressure.
- Respirable crystalline silica exposure limits:OSHA enforcement of permissible exposure limits during pneumatic application mandates capital-intensive dust collection infrastructure, elevating wet-process equipment costs for US contractors.
- Spray-applied membrane substitution:Polyurea and bituminous waterproofing systems are capturing specification share in secondary lining applications where shotcrete previously served dual structural-waterproofing functions.
Strategic Opportunities
- Brazil hydroelectric tunneling pipeline:Transport and power generation projects in the southeastern states are concentrating demand for high-performance wet-mix shotcrete with rapid-set accelerators for water-bearing ground conditions.
- Robotic application system convergence:Integration of automated spraying platforms with real-time thickness monitoring is creating service-revenue streams beyond material supply, capturing value from quality certification and labor productivity gains.
- REACH compliance accelerator reformulation:Alkali-free and low-alkali accelerator chemistries are opening specification access in EU public procurement where traditional sodium aluminate formulations face substance restriction scrutiny.
Industry Challenges
- Nozzleman skill scarcity:Pneumatic shotcrete application demands specialized craftsmanship for rebound control and compaction density, with training pipelines failing to match retirement rates in mature mining regions.
- Accelerated strength certification timelines:Project specifications requiring 1-hour and 24-hour compressive strength verification compress quality control laboratory capacity, creating bottlenecks in high-volume tunneling schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shotcrete Market |
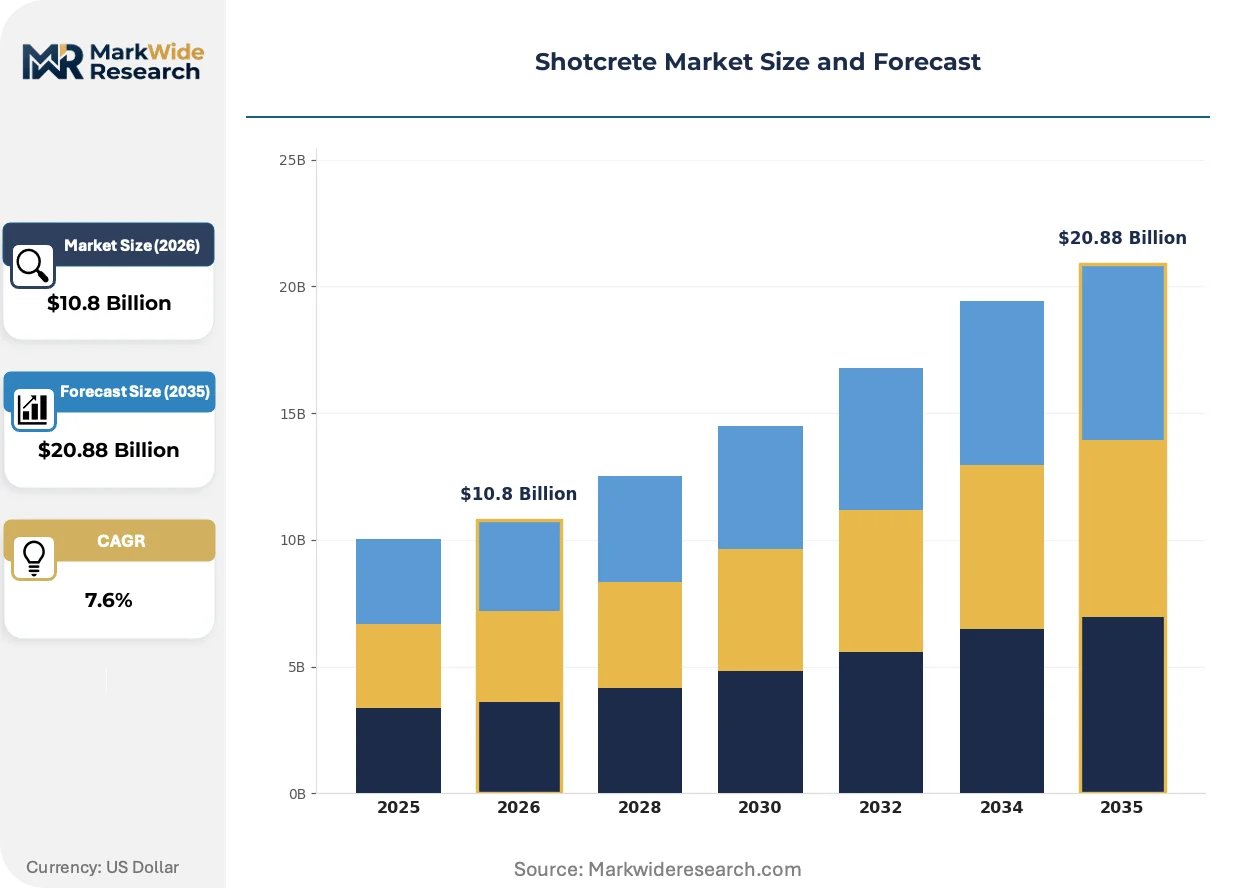
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $20.88 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry-Mix, Wet-Mix, Fiber-Reinforced, Polymer-Modified Application: Tunneling, Mining, Slope Stabilization, Structural Repair, Hydraulic Engineering End User Industry: Infrastructure Construction, Mining Contractors, Civil Engineering Firms, Hydro Power Projects Deployment Method: Manual Spraying, Mechanized Spraying, Robotic Application, Dry Nozzle Technology |
| Companies Covered | Mapei Group, Master Builders Solutions, Sika AG, Heidelberg Cement, GCP Applied Technologies, BASF SE, Putzmeister, Cemex, Normet Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shotcrete Market Strategic Shifts & Innovations
Shotcrete formulation and application methodology are undergoing simultaneous transformation as fiber reinforcement chemistry advances, environmental compliance tightens binder specifications, and mechanization reshapes labor economics in underground construction.
Synthetic macro-fiber reinforcement is hybridizing with steel fiber and welded mesh systems in high-stress ground support applications. Mining contractors in Australia's Western Underground operations are specifying hybrid designs that combine steel fibers for initial crack control with synthetic additions for long-term durability in corrosive groundwater environments. This hybridization is compressing the traditional specification hierarchy that segregated fiber types by application severity, enabling single-source supply consolidation.
REACH substance restrictions are forcing accelerator chemistry transitions across European shotcrete supply chains. The European Chemicals Agency's scrutiny of sodium aluminate and sodium silicate-based formulations is elevating alkali-free alternatives that reduce alkali-silica reaction risk in aggregate-sensitive concrete. German and Austrian tunneling projects are now mandating ECHA-registered accelerator portfolios, displacing legacy formulations in cross-border infrastructure procurement.
Equipment-led service bundling is restructuring contractor-supplier relationships in mechanized shotcrete application. Putzmeister and other spraying system manufacturers are capturing recurring revenue through application training certification and maintenance contracts that lock in consumable supply. This model is most visible in Scandinavian infrastructure markets where robotic spraying platform penetration exceeds conventional manual nozzle operations on major rail and road tunnel projects.
Shotcrete Market Segmentation
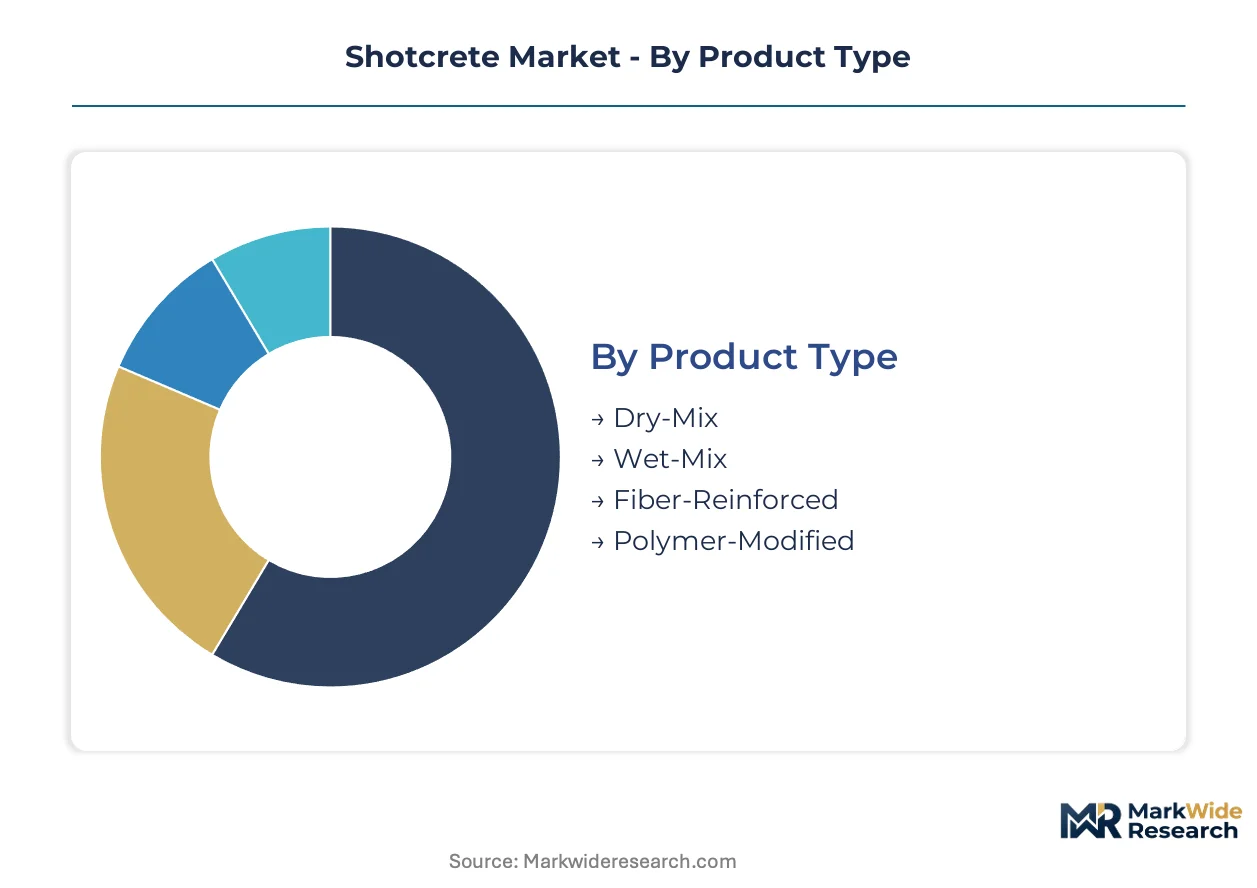
Shotcrete procurement decisions cascade across four distinct segmentation axes. Product formulation determines performance envelopes for ground support. Application context dictates accelerator chemistry and fiber reinforcement specifications. Deployment method selection shapes labor economics and quality certification requirements.
Product Type:
Cost tier stratification separates commodity formulations from specialty admixtures engineered for extreme service conditions.
- Dry-Mix:Bagged cement-aggregate blends premixed at batch plants, activated with water at the nozzle. Mining contractors in Australia's Pilbara region specify dry-mix for remote site logistics where ready-mix supply chains prove uneconomical.
- Wet-Mix:Fully hydrated concrete delivered via ready-mix trucks, demanding precision accelerator dosing at the pump. Tunneling projects across Scandinavia mandate wet-mix for dust suppression compliance and consistent hydration control in water-bearing ground.
- Fiber-Reinforced:Steel or synthetic macro-fibers dosed at 25-60 kg/m³ replacing welded wire mesh. Infrastructure specifications in Brazil's hydroelectric sector are rotating toward hybrid steel-synthetic designs for crack control in aggressive groundwater environments.
- Polymer-Modified:Latex or epoxy emulsions enhancing bond strength and chemical resistance for structural repair applications. Bridge deck rehabilitation contracts in Germany specify polymer-modified shotcrete for chloride-exposed concrete substrates.
Wet-Mix holds installed capacity in European tunneling. Fiber-Reinforced is rotating up the share rankings in high-stress mining ground support.
Application:
Application context determines accelerator chemistry selection, thickness specifications, and quality certification protocols.
- Tunneling:Primary lining applications requiring 30-50 MPa final compressive strength with rapid early strength development. Swiss and Austrian alpine rail tunnels specify alkali-free accelerators to satisfy ECHA-registered substance portfolios under REACH scrutiny.
- Mining:Hard-rock ground support demanding immediate structural integrity in high-stress geologies. Western Australian underground operations mandate steel macro-fiber reinforcement for seismic loading resistance in deep-level extraction.
- Slope Stabilization:Surface protection on cuttings and embankments where conventional formwork access proves impractical. Norwegian road infrastructure employs shotcrete for rockfall mitigation on fjord-side highway corridors.
- Structural Repair:Bridge soffit and column jacketing applications prioritizing bond strength and low rebound. German federal transport authority specifications require polymer modification for chloride-contaminated concrete rehabilitation.
- Hydraulic Engineering:Dam face repairs and canal linings exposed to flowing water and freeze-thaw cycling. Brazilian hydroelectric projects in Minas Gerais specify rapid-set formulations for water-bearing ground conditions.
Tunneling commands specification authority in European public procurement. Mining is gaining share fastest in Australia's resource extraction expansion.
End User Industry:
Customer type segmentation reveals divergent procurement sophistication and supply chain integration patterns.
- Infrastructure Construction:Public sector tunneling and bridge contracts with stringent embodied carbon benchmarks. EU Green Deal compliance is forcing Portland cement binder reformulation in French and Italian transport infrastructure.
- Mining Contractors:Hard-rock extraction operators prioritizing immediate ground support and logistics flexibility. Australian contractors balance wet-mix quality advantages against dry-mix portability in remote Western Underground operations.
- Civil Engineering Firms:Slope stabilization and structural repair specialists with application methodology expertise. Scandinavian firms lead robotic spraying platform adoption on rail and road tunnel projects.
- Hydro Power Projects:Dam and tunnel specifications for water-bearing ground with aggressive chemical exposure. Brazilian southeastern states concentrate demand for rapid-set accelerator chemistries in transport and power generation tunnels.
Infrastructure Construction holds specification authority through public procurement. Mining Contractors are rotating up the share rankings in commodity price recovery cycles.
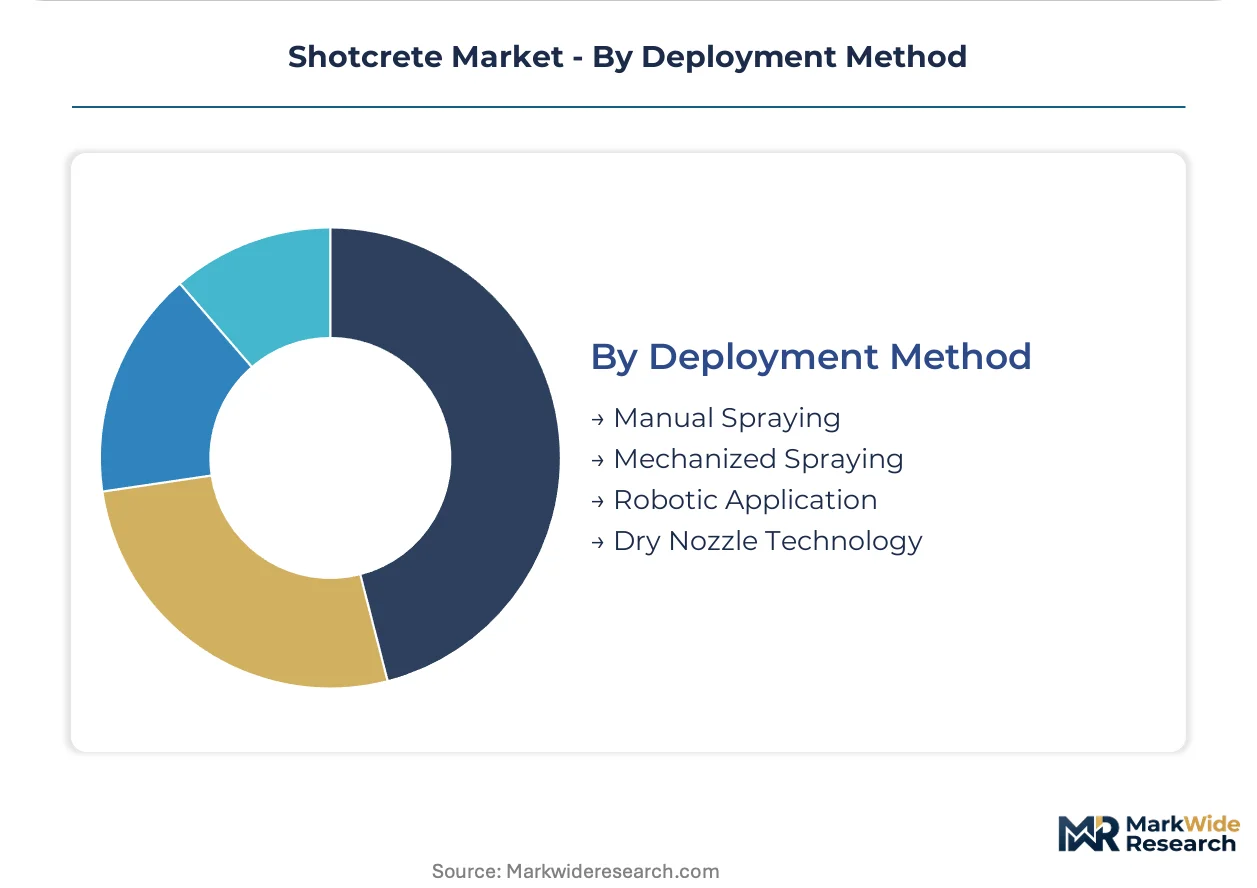
Deployment Method:
Volume and labor economics separate manual craftsmanship from mechanized productivity platforms.
- Manual Spraying:Nozzleman-operated hoses requiring specialized skill for rebound control and compaction density. OSHA respirable crystalline silica enforcement in US construction is elevating wet-process preference for dust exposure mitigation.
- Mechanized Spraying:Pump and boom systems integrating accelerator dosing with continuous material supply. Putzmeister and other equipment manufacturers capture recurring revenue through maintenance contracts and application training certification.
- Robotic Application:Automated spraying platforms with real-time thickness monitoring and quality documentation. Scandinavian infrastructure markets exceed conventional manual nozzle penetration on major rail tunnel projects.
- Dry Nozzle Technology:Water injection at the nozzle point for dry-mix hydration control in remote logistics-constrained sites. Synthetic fiber maturation is enabling mechanized spraying in locations previously reserved for bagged material handling.
Mechanized Spraying holds installed capacity in mature European markets. Robotic Application is climbing the fastest in labor-cost-sensitive Scandinavian procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German specialty chemical exports supply alkali-free accelerator formulations to tunneling contractors across Scandinavia and the Alpine corridor. Australian mining operations import wet-mix application equipment from European manufacturers to support Western Underground expansion.
Germany
Alpine rail tunneling and bridge rehabilitation contracts drive specialty admixture consumption. ECHA registration requirements under REACH restrict sodium aluminate accelerator formulations, elevating alkali-free alternatives. Bavarian chemical clusters supply reformulated binders for cross-border infrastructure procurement.
Australia
Hard-rock mining ground support specifications mandate steel macro-fiber reinforced wet-mix shotcrete for seismic loading resistance. Safe Work Australia enforces respirable crystalline silica exposure limits during pneumatic application. Western Australia's Pilbara region concentrates dry-mix demand for remote site logistics where ready-mix supply chains prove uneconomical.
Brazil
Hydroelectric and transport tunneling projects in southeastern states concentrate demand for rapid-set accelerator chemistries. ANVISA registration requirements govern construction chemical imports for public infrastructure. Minas Gerais dam face repairs specify shotcrete formulations for water-bearing ground conditions.
United States
OSHA enforcement of permissible exposure limits on respirable crystalline silica elevates wet-process equipment investments for dust exposure mitigation. Federal infrastructure spending directs shotcrete specification toward tunneling and slope stabilization contracts. Pacific Northwest rockfall mitigation projects on highway corridors employ mechanized spraying systems.
Switzerland
Alpine base tunnel rail projects specify alkali-free accelerators to satisfy ECHA-registered substance portfolios. Swissmedic oversight extends to construction chemical safety documentation for transnational procurement. Gotthard corridor contractors integrate robotic spraying platforms with real-time thickness monitoring systems.
Shotcrete Market Key Industry Players
Channel-controlling players compete with product-specialist players across formulation chemistry, application equipment, and integrated service bundling. The vendor base organizes around three strategic archetypes: multinational chemical conglomerates with polymer chemistry portfolios, specialized spraying equipment manufacturers extending into training services, and regional construction material suppliers with captive distribution networks. Dominant competitive moves include equipment-led service bundling that locks in consumable supply, and REACH-compliant accelerator reformulation that secures EU public procurement access.
Among European-based chemical specialists, Sika AG, BASF SE, and Mapei Group exemplify the formulation-centric archetype, anchoring competitive positioning through polymer chemistry and admixture R&D capabilities. Putzmeister represents the equipment-led service model, while Heidelberg Cement and Cemex illustrate construction material conglomerates with integrated shotcrete supply chains.
| Leading Market Players |
|---|
| Mapei Group |
| Master Builders Solutions |
| Sika AG |
| Heidelberg Cement |
| GCP Applied Technologies |
| BASF SE |
| Putzmeister |
| Cemex |
| Normet Group |
| Others |
Cost & Logistics Intelligence
Portland cement clinker price volatility determines both pricing tier spreads and supply chain shape in shotcrete markets. Energy-intensive clinker production exposes margins to natural gas and electricity swings, compressing standard-grade formulations while premium alkali-free accelerator blends capture value through regulatory compliance premiums.
Pricing Analysis
Conventional wet-mix formulations trade at substantial discounts to next-generation fiber-reinforced and polymer-modified grades. Project-based contract pricing dominates infrastructure procurement, with differentiation driven by ECHA-registered accelerator certification and steel macro-fiber dosing rates. Cost compression in commodity dry-mix tiers intensifies as Brazilian and Australian mining contractors squeeze bagged material suppliers. Small-scale rehabilitation contractors exhibit highest price sensitivity, while alpine rail tunneling authorities prioritize performance over unit economics.
Supply Chain Analysis
Clinker and supplementary cementitious materials feed from Germany, China, and India into regional admixture blending operations. Specialty alkali-free accelerators and synthetic macro-fibers draw from German and Austrian chemical clusters. Single-source vulnerability concentrates in steel fiber supply from Chinese metallurgical producers. Distribution runs through construction chemical distributors with captive applicator training networks, particularly in Scandinavian mechanized spraying markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shotcrete markets exhibit defensive moat characteristics rooted in regulatory entrenchment. REACH compliance and ECHA registration requirements create substantial barriers to accelerator chemistry substitution, locking incumbent positions.
For Market Incumbents: Build certification moats through ECHA-registered alkali-free accelerator portfolios that preempt regulatory displacement of sodium aluminate formulations. Deepen backward integration into clinker grinding capacity in Germany and Austria to secure binder supply against energy cost volatility. Capture channel control by bundling robotic spraying platform leases with mandatory maintenance contracts that lock consumable supply.
For New Entrants and Emerging Players: Mid-market dry-mix conversion opportunities in Australia's Pilbara region represent the most penetrable entry point, where synthetic fiber maturation enables mechanized spraying in logistics-constrained sites previously reserved for bagged handling. Target Brazilian hydroelectric contractors with rapid-set accelerator formulations for water-bearing ground conditions. Pursue joint development agreements with European equipment manufacturers to secure application training certification access.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialty chemical players with polymer chemistry R&D depth over commodity construction material conglomerates. Long-term viability hinges on accelerator reformulation capabilities and robotic application system integration. Watch for inflection signals in EU carbon border adjustment implementation timelines that would accelerate Portland cement binder cost pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Clinker Production | Captive supply of energy-intensive binder inputs insulates margins from natural gas volatility in European manufacturing. |
| ECHA-Registered Accelerator Portfolio Expansion | REACH-compliant chemistry access secures specification authority in EU public infrastructure procurement. |
| Robotic Spraying Platform Deployment | Automated application with real-time thickness monitoring captures service revenue beyond material supply in Scandinavian tunneling. |
| Hybrid Fiber Formulation Development | Steel-synthetic combinations enable single-source supply consolidation in Australian mining ground support. |
| Application Training Certification Programs | Nozzleman skill scarcity creates recurring revenue streams through mandatory competency validation for mechanized equipment operation. |
Research Approach
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from construction material conglomerates, and ECHA substance registration databases. Interviews with shotcrete plant managers, mining contractor procurement leads, tunneling project engineers, and admixture R&D directors informed demand-side validation. Bottom-up volume estimates triangulated against top-down infrastructure spending allocations across modeled geographies.
Forecast inputs include wet-mix versus dry-mix process adoption, fiber reinforcement penetration by application severity, and robotic spraying platform deployment rates. Segmentation dimensions span product formulation grade, end-use context, deployment method sophistication, and regional regulatory cluster. CAGRs derive from elasticity modeling against construction output indices and mining capital expenditure cycles.
Practitioners should monitor EU carbon border adjustment implementation, ANVISA registration pathway changes in Brazil, and OSHA silica enforcement intensity for early signals of forecast revision. Cross-checking against national infrastructure procurement databases and mining industry association expenditure surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Middle East and Africa Concrete Admixtures Market
Building Materials
Latin America Facade Market
Building Materials
Fly Ash Bricks Market
Building Materials
Construction Coatings Market
Building Materials
United States Architectural Coatings Market
Building Materials
Construction Materials Market
Building Materials
Foam Concrete Market
Building Materials
North America Dry-Mix Mortar Market
Building Materials
India Dry Mix Mortar Market
Building Materials
United Kingdom Architectural Coatings Market
Building Materials
Mexico Architectural Coatings Market
Building Materials
Fiber Reinforced Concrete Market
Building Materials
Asia-Pacific Dry-Mix Mortar Market
Building Materials
East Africa Cement Market
Building Materials
Cement Market
Building Materials
Geocells Market