
 Wave and Tidal Energy Market | 2026-2036
Wave and Tidal Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Wave and Tidal Energy Market Intelligence
The European Green Deal's ambitious renewable energy targets is expanding the commercial viability for large-scale marine energy projects. This policy framework creates new opportunities for technology developers. Orbital Marine Power specializes in floating tidal turbine technology for high-flow sites. Meanwhile, CorPower Ocean focuses on point absorber wave energy converters, and Voith Hydro leverages its extensive hydropower experience for tidal applications.
Wave and tidal energy systems convert the kinetic and potential energy of ocean movements into electricity. These technologies utilize devices like tidal stream generators, which function akin to underwater wind turbines with rotor diameters often exceeding 20 meters, or oscillating water columns that use wave action to compress air. Tidal stream generators represent the most technologically mature and commercially deployed energy generation method. Fixed platforms are common for nearshore projects, but floating structures are gaining traction for deeper water deployments targeting coastal community electrification.
International Electrotechnical Commission (IEC) standards provide the technical specifications for marine energy converters, ensuring safety and interoperability. In parallel, national bodies like the US Federal Energy Regulatory Commission (FERC) and Canadian government incentives shape market access and project permitting. Future investment decisions hinge on achieving cost-reductions through standardized manufacturing and streamlined permitting processes.
Market Dynamics
The primary structural force shaping the market is the global policy mandate for energy decarbonization. This pressure elevates marine renewables from experimental technologies to essential components of national energy transition strategies, particularly within the EU and Canada.
Growth Catalysts
- Policy Frameworks:The European Green Deal provides a strong regulatory tailwind and specific targets for ocean energy development.
- Technology Maturation:Floating platforms are enabling deployment in deeper waters, expanding the range of viable project sites beyond nearshore locations.
- Electrification Demand:The expansion of electrification projects for remote and coastal communities creates a direct application for localized marine energy systems.
Market Restraints
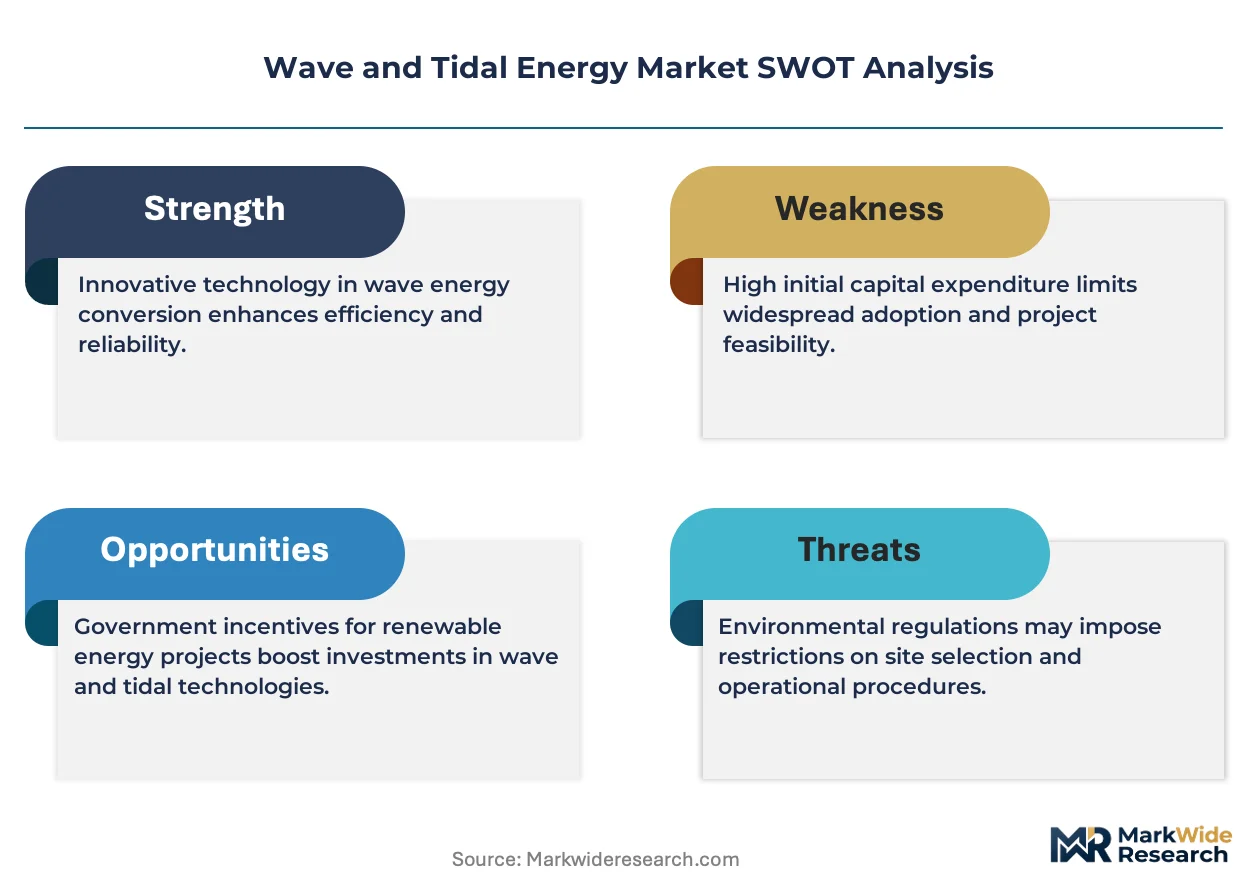
- High Capital Costs:The initial investment for manufacturing and deploying robust devices capable of surviving harsh marine environments remains a significant barrier.
- Grid Integration:Intermittent power generation from wave and tidal sources presents challenges for grid stability without complementary energy storage solutions.
- Permitting Complexity:Lengthy and complex permitting processes, such as those overseen by the US FERC, can delay projects and increase development costs.
Strategic Opportunities
- Hybrid Projects:Co-locating wave or tidal energy systems with offshore wind farms or aquaculture operations creates synergistic value streams.
- Geographic Expansion:Nations in Southeast Asia with extensive coastlines and strong tidal resources represent a significant, underpenetrated market for project development.
- Data as a Service:Integrating environmental sensors into energy devices allows operators to sell valuable oceanographic data to research institutions and government agencies.
Industry Challenges
- Component Standardization:A lack of standardized designs for major components like turbine blades and foundations hinders the development of a cost-effective supply chain.
- Specialized Talent Scarcity:A shortage of marine engineers and technicians with experience in subsea installation, operations, and maintenance limits project execution capacity.
- Certification Timelines:Achieving compliance with IEC technical specifications for marine energy converters is a time-consuming and expensive process for technology developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wave and Tidal Energy Market |
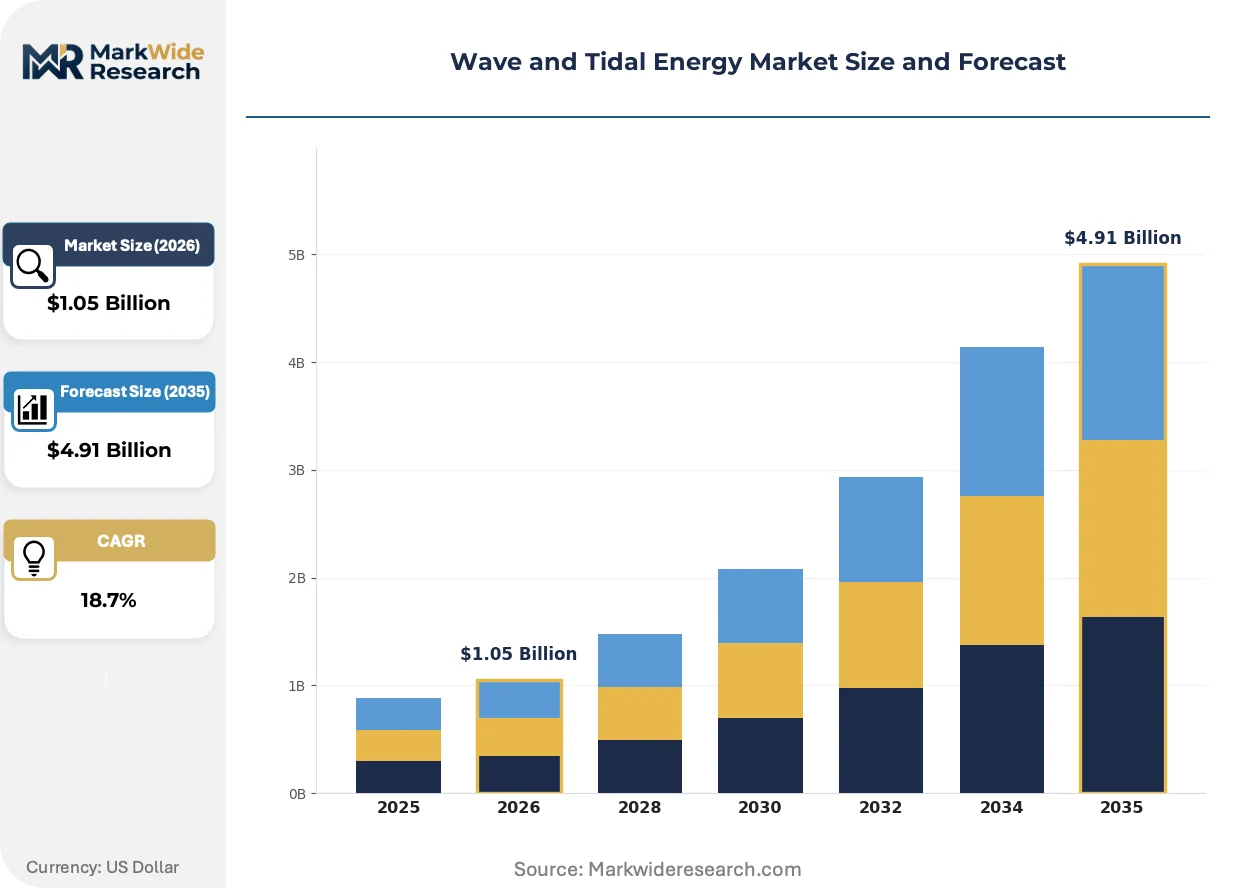
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $4.91 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Energy Generation Method: Oscillating Water Columns, Point Absorbers, Overtopping Devices, Tidal Stream Generators, Underwater Kites Deployment Type: Fixed Platforms, Floating Structures, Subsea Installations, Shoreline Systems, Multi-device Arrays Application Sector: Offshore Power Supply, Coastal Community Electrification, Desalination Plants, Marine Research Facilities, Island Electrification End User Type: Renewable Energy Utilities, Marine Infrastructure Operators, Research Institutions, Island Administrations, Independent Power Producers |
| Companies Covered | Voith Hydro, Nova Innovation, Orbital Marine Power, Eco Wave Power, Minesto, SIMEC Atlantis Energy, EDF Renewables, CorPower Ocean, Ocean Renewable Power Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wave and Tidal Energy Market Strategic Shifts & Innovations
The market's evolution hinges on transitioning from bespoke, high-cost engineering to scalable, standardized systems. This shift is critical for achieving the cost-reductions necessary for commercial competition with other renewable sources like offshore wind.
Digital twin technology creates virtual replicas of physical tidal turbines and their operating environment. Project operators are adopting this for predictive maintenance and performance optimization on commercial-scale arrays. This simulation capability is unifying previously separate domains of fluid dynamics, material science, and power electronics into a single operational model.
Government incentives in Canada, particularly within Nova Scotia for the Bay of Fundy, are creating favorable investment conditions. These policies de-risk early-stage projects through funding and streamlined environmental assessments. Consequently, tidal stream technology developers are increasingly targeting Canadian waters for deploying and validating their systems.
A shift toward hybrid offtake agreements is altering how projects generate revenue. Simple power purchase agreements are being augmented by contracts that value ancillary grid services, such as frequency regulation. This model is most advanced in the United Kingdom, where grid operators compensate predictable power sources for enhancing system stability.
Wave and Tidal Energy Market Segmentation
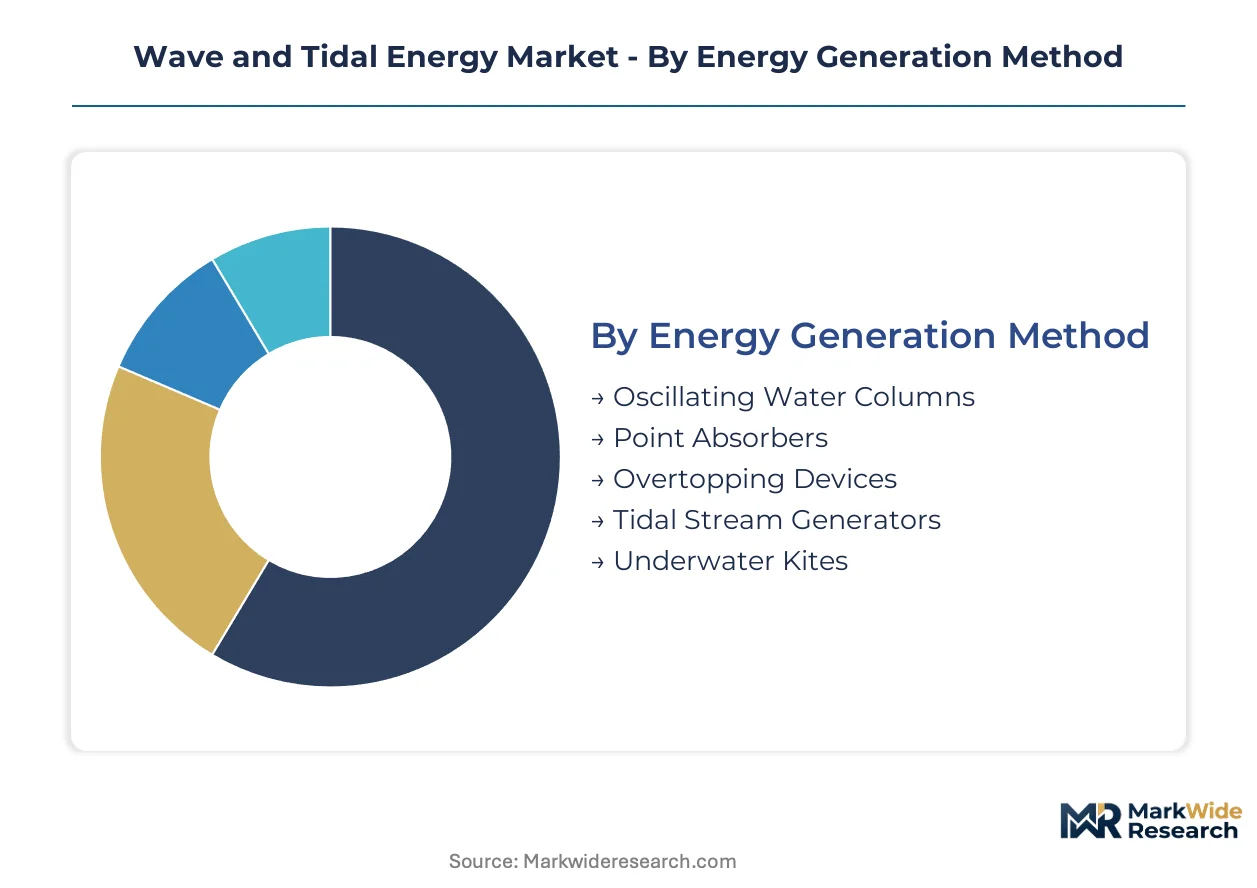
Market segmentation for wave and tidal energy systems clarifies the distinct technological approaches and end-use applications driving industry expansion. Understanding these segments is critical for technology developers to target specific regulatory pathways and for investors to evaluate commercial viability across the value chain.
Energy Generation Method:
The market for wave and tidal energy requires adherence to stringent technical specifications, with International Electrotechnical Commission (IEC) standards guiding certification for specific energy generation methods.
- Tidal Stream Generators:These devices function like underwater wind turbines, converting kinetic energy from tidal currents into electricity through rotating blades often exceeding 20 meters in diameter. Their technological maturity and predictable energy output make them commercially significant for grid-scale projects in high-flow regions like Scotland and Canada's Bay of Fundy.
- Point Absorbers:These wave energy converters utilize buoyant structures that oscillate with wave motion, converting vertical movement into electrical power. Significant research and development efforts focus on improving their efficiency and survivability in harsh marine environments, making them a focus for innovation in wave energy.
- Oscillating Water Columns:Wave action compresses air within a partially submerged chamber, driving a bidirectional turbine to generate electricity.
- Overtopping Devices:Waves flow over a ramp into an elevated reservoir, creating a hydrostatic head that drives conventional low-head turbines.
- Underwater Kites:These tethered devices harness strong subsea currents, moving in a figure-eight pattern to maximize energy capture and generate power through onboard turbines.
Leading the category by volume: Tidal Stream Generators. Growing fastest: Point Absorbers.
Deployment Type:
Deployment types exhibit varied capital expenditure profiles, influenced by platform complexity and installation depth.
- Fixed Platforms:These structures are anchored directly to the seabed, typically used for nearshore projects in shallower waters where foundations are less complex. Fixed platforms offer stability for tidal stream generators and shoreline wave energy converters, reducing operational movement.
- Floating Structures:These platforms are moored to the seabed, allowing deployment in deeper waters and expanding the viable geographic range for wave and tidal energy projects. Floating structures are gaining traction for coastal community electrification, offering flexibility in site selection and installation.
- Subsea Installations:Entire energy conversion systems are placed on the seabed, minimizing visual impact and protecting equipment from surface weather conditions.
- Shoreline Systems:Devices integrated directly into coastal infrastructure or positioned very close to the shore, often utilizing breakwaters or natural formations.
- Multi-device Arrays:Multiple energy converters are deployed together in a single project, creating a larger power output and optimizing resource capture across a given site.
The segment with the highest operational complexity is Subsea Installations, while Floating Structures demonstrate the steepest expansion trajectory.
Application Sector:
Application sectors are defined by distinct demand characteristics, ranging from localized community power needs to industrial offshore requirements.
- Coastal Community Electrification:This sector involves providing reliable, renewable electricity to remote coastal populations, often in island nations or isolated regions. Marine energy systems offer a stable, localized power source, reducing reliance on fossil fuel imports and supporting energy independence.
- Offshore Power Supply:This application focuses on providing electricity to offshore industrial facilities such as oil and gas platforms, aquaculture operations, or data centers. Co-locating marine energy with these operations creates synergistic value streams and reduces the need for long subsea power cables.
- Desalination Plants:Wave and tidal energy can power the energy-intensive processes of converting seawater into fresh water, providing a sustainable solution for water scarcity.
- Marine Research Facilities:These facilities utilize marine energy to power sensors, monitoring equipment, and underwater observatories, supporting oceanographic and environmental studies.
- Island Electrification:Similar to coastal communities, this involves providing sustainable power to island grids, often replacing diesel generators and enhancing energy security.
Demand for Coastal Community Electrification applications presently drives the largest portion of market revenue, with Island Electrification gaining share fastest.
End User Type:
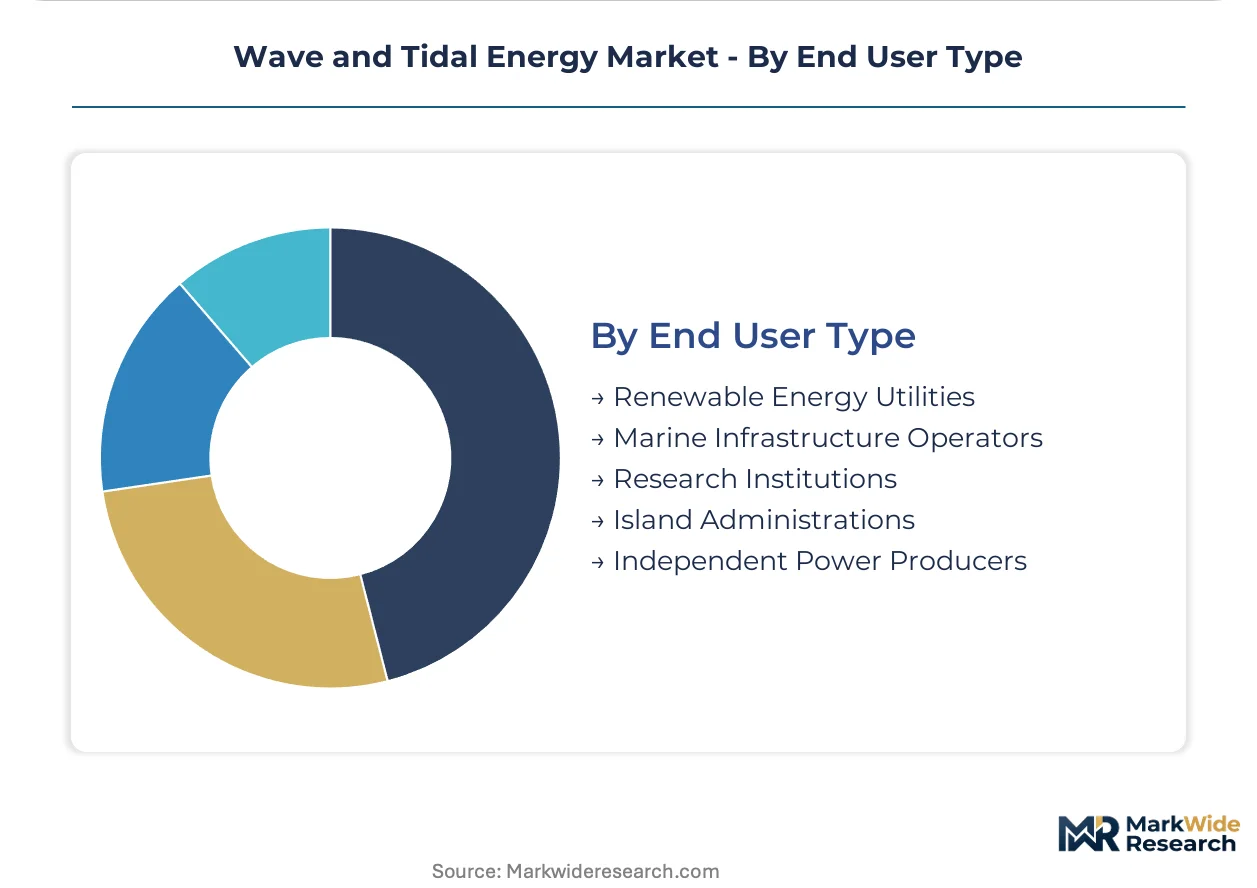
End user types demonstrate diverse procurement patterns, reflecting their operational scales and strategic energy objectives.
- Renewable Energy Utilities:These large entities focus on developing, owning, and operating utility-scale renewable energy projects, integrating wave and tidal power into national grids. Their long-term investment horizons and grid integration expertise are crucial for large-scale marine energy deployment.
- Independent Power Producers:These companies specialize in developing and operating power generation facilities, often selling electricity directly to utilities or large industrial consumers. They seek competitive and reliable energy sources, including emerging marine technologies, to diversify their portfolios.
- Marine Infrastructure Operators:Entities managing ports, harbors, or offshore platforms that require self-sufficient power solutions for their operations.
- Research Institutions:Universities and government laboratories that develop, test, and validate marine energy technologies, often in collaboration with industry partners.
- Island Administrations:Local governments or public bodies responsible for energy supply in island territories, prioritizing energy independence and cost reduction.
Procurement volume is highest among Renewable Energy Utilities entities, while Independent Power Producers entities exhibit the most rapid growth in project initiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global demand for marine energy systems concentrates in coastal regions with strong tidal resources and electrification needs. These areas benefit from predictable energy output and reduced reliance on fossil fuels. Policy support, such as the EU Green Deal, further accelerates project development in these strategic locations.
United Kingdom
United Kingdom's energy transition drives significant demand for predictable marine energy, enhancing grid stability and meeting decarbonization targets. Grid operators in the UK compensate predictable power sources for enhancing system stability. Scotland's waters, particularly around the Orkney Islands, host significant tidal stream generator deployments validating commercial-scale arrays and grid integration solutions.
Canada
Canada's vast coastline and remote communities create substantial demand for localized energy solutions, particularly for electrification projects. Canadian government incentives de-risk early-stage projects through funding and streamlined environmental assessments. Nova Scotia, specifically the Bay of Fundy, attracts tidal stream technology developers for system deployment and validation in high-flow environments.
France
France, driven by EU Green Deal targets, seeks to enhance its energy independence through diverse renewable sources. The EU Green Deal provides a strong regulatory tailwind for marine renewable energy development across member states, including France. Coastal regions like Brittany and Normandy are actively exploring tidal and wave energy projects to diversify their national energy mix.
South Korea
South Korea's extensive coastline and numerous islands generate demand for stable, localized power solutions. National energy policies in South Korea support renewable energy expansion and technology development, including marine energy. The southwestern coast and various island territories are key targets for deploying marine energy systems to power remote grids and aquaculture operations.
Wave and Tidal Energy Market Key Industry Players
European producers anchor one tier of the Wave and Tidal Energy market, while Canadian and Asian specialists hold significant positions. The market structure exhibits a tiered consolidation, with established hydropower firms and specialized marine energy developers. Strategic archetypes include technology innovators focused on device efficiency and project developers emphasizing grid integration. Dominant competitive moves involve strategic partnerships for large-scale deployments and continuous technology maturation to reduce levelized cost of energy.
Within the technology developer archetype, Orbital Marine Power exemplifies innovation in floating tidal turbine technology for high-flow sites, showcasing advanced engineering for robust marine environments. Meanwhile, CorPower Ocean represents a specialized focus on point absorber wave energy converters, pushing boundaries in wave energy efficiency and survivability. Voith Hydro, leveraging its extensive hydropower experience, occupies a position among established players adapting proven engineering for tidal applications, particularly in large-scale projects. These entities collectively drive advancements in marine energy conversion systems and project scalability.
| Leading Market Players |
|---|
| Voith Hydro |
| Nova Innovation |
| Orbital Marine Power |
| Eco Wave Power |
| Minesto |
| SIMEC Atlantis Energy |
| EDF Renewables |
| CorPower Ocean |
| Ocean Renewable Power Company |
| Others |
Cost & Logistics Intelligence
Wave and tidal energy technologies have a clear performance gap between mature tidal stream generators and nascent wave energy converters. This divergence shapes pricing models and influences component sourcing strategies across the value chain.
Pricing Analysis
Volume-based pricing dominates for established tidal stream generator projects, driven by economies of scale in manufacturing and deployment. Price differentiation stems from project-specific IEC certification levels and the level of grid integration services offered. Pricing pressure stems from the need to achieve cost-reductions to compete with other renewables. Renewable Energy Utilities are less price-sensitive for proven technologies, while Independent Power Producers seek more competitive solutions.
Supply Chain Analysis
Dual-sourcing requirements are emerging for critical components like large-diameter turbine blades and power electronics to mitigate supply risks. Geographic supply concentrates in European countries like Germany and the UK for specialized marine components, alongside Asian manufacturers for standard electrical systems. Raw material dependencies include high-strength alloys for turbine structures and rare earth magnets for generators. Single-source vulnerability for specialized subsea connectors presents a structural risk. Distribution runs through specialized marine logistics providers and EPC contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Wave and Tidal Energy market is poised for consolidation, driven by the intense capital costs required for device development and large-scale project deployment. This financial pressure is forcing smaller, undercapitalized technology developers to seek strategic partnerships or exit the market.
For Market Incumbents:
Lock in long-term power purchase agreements with Renewable Energy Utilities to secure predictable revenue streams against emerging hybrid energy solutions. Expand manufacturing capacity for standardized components, reducing the levelized cost of energy and countering margin pressure from offshore wind. Invest in R&D for advanced grid integration solutions to mitigate intermittency challenges. Pursue strategic partnerships with established offshore infrastructure operators to leverage existing expertise.
For New Entrants and Emerging Players:
Local energy cooperatives offer a viable channel for new entrants to deploy smaller-scale, localized marine energy systems in remote coastal communities. Target underpenetrated island electrification projects in Southeast Asia with modular, easily deployable wave energy converters. Focus on developing robust, low-maintenance designs to address high capital cost barriers. Emphasize value proposition around energy independence and reduced fossil fuel reliance for remote grids.
For Investors and Strategic Acquirers:
Re-rating potential sits with technology developers specializing in floating structures given their expanded deployment flexibility for coastal community electrification. Acquisition targets should prioritize firms with proven IEC certification pathways and a strong project pipeline in favorable regulatory environments like the EU. Long-term viability hinges on achieving standardized manufacturing processes and significant cost reductions for wave energy converters. Watch for increasing adoption of digital twin technology as an inflection indicator for operational efficiency gains.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Expanding manufacturing for standardized tidal stream generators reduces unit costs for project developers. |
| Power Purchase Agreement | Securing long-term PPAs with Renewable Energy Utilities ensures predictable revenue for large-scale projects. |
| Technology Licensing | Licensing wave energy converter designs accelerates market entry for regional project developers in new geographies. |
| Vertical Integration into Storage | Integrating battery storage solutions enhances grid stability for intermittent wave and tidal power output. |
| Green Certification Program | Achieving IEC certification for new marine energy devices validates performance and builds investor confidence. |
Research Approach
Document review covered academic papers, industry reports, and government policy documents, complemented by interviews with industry stakeholders. Primary interviews included marine engineers, project developers, utility planning officers, and regulatory affairs specialists. Secondary validation drew from IEC standards, national energy agency data, and corporate financial filings. This approach ensured robust bottom-up and top-down triangulation of insights.
Cross-referencing historical data with expert panel input shaped the analytical framework across the analysis window. Segmentation dimensions modeled included energy generation method, deployment type, application sector, end user type, and regional policy frameworks. Compound annual growth rates were derived from projected technology maturation and policy-driven investment. Key forecast inputs included LCoE reductions and global decarbonization targets.
Caveats apply where rapid technological breakthroughs or significant policy reversals could materially shift the outlook. Forecasts reflect assumptions regarding regulatory stability and continued investment in marine energy. Deviation in project permitting timelines or funding availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydropower Systems
Hydropower Turbine Market
Hydropower Systems
Asia-Pacific Pumped Hydro Storage Market
Hydropower Systems
United States Hydro Turbine Market
Hydropower Systems
Europe Small Hydropower Market
Hydropower Systems
Small Hydropower Market
Hydropower Systems
Asia-Pacific Hydropower Market
Hydropower Systems
Offshore Hydropower Market
Hydropower Systems
Underground Hydro Power Plant Market
Hydropower Systems
North America Pumped Hydro Storage Market
Hydropower Systems
Pumped Hydro Storage Market
Hydropower Systems
Global Hydro Turbine Generator Unit Market
Hydropower Systems
Hydropower Generation Market
Hydropower Systems
Southeast Asia Hydropower Market
Hydropower Systems
Asia-Pacific Small Hydropower Market
Hydropower Systems
South America Hydropower Market
Hydropower Systems
Europe Hydro Turbine Market