
 Tidal Energy Generation Systems Market | 2026-2036
Tidal Energy Generation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Tidal Energy Generation Systems Market Insights
The gap between premium offshore installations and commodity near-shore systems is expanding as water depth, grid connection cost, and turbine reliability requirements split project economics. Andritz Hydro Hammerfest anchors Nordic deployment through its deep-water turbine expertise. Nova Innovation competes in shallow-channel arrays with modular designs. Orbital Marine Power leads on floating platform technology for high-velocity sites.
Tidal energy generation systems harness kinetic and potential energy from lunar gravitational cycles through submerged turbines, barrages, or dynamic fences, typically operating at 20-40% capacity factor in prime locations to feed baseload-compatible power into regional grids. Tidal Stream technology dominates active deployment, while Tidal Range retains mature project pipelines where estuary geography permits. Small Scale capacity attracts island and coastal community buyers, whereas Utility Scale installations command long-term offtake contracts from national transmission operators.
EU Green Deal marine energy directives, UK Crown Estate seabed leasing frameworks, and Scotland's Saltire Tidal Energy Challenge Fund collectively shape project bankability and equipment certification requirements. These mechanisms reduce developer risk but impose lengthy environmental impact protocols that extend commissioning timelines. Stakeholders must monitor evolving consenting rules and grid interconnection standards to time capital deployment effectively.
Market Dynamics
Grid interconnection bottlenecks and seabed leasing queue congestion are compressing project timelines more than turbine technology readiness, forcing developers to front-load consenting risk before final investment decisions.
Growth Catalysts
- EU Green Deal marine renewable targets:The directive accelerates national permitting timelines for ocean energy projects, reducing regulatory uncertainty for array developers.
- Scotland's Pentland Firth corridor:Multiple demonstration sites now operate at commercial scale, validating bankability models for utility-scale deployments.
- Dynamic tidal fence arrays:Modular fence configurations reduce foundation costs in shallow-channel environments, opening near-shore sites previously deemed uneconomic.
Market Restraints
- Grid connection cost volatility:Subsea cable procurement and onshore substation upgrades absorb disproportionate capital in deep-water arrays.
- Environmental impact protocol duration:EU Habitats Directive assessments and UK Marine Management Organisation licensing extend commissioning timelines.
- Intermittency of competing offshore wind:Floating offshore wind captures similar seabed leases with lower LCOE, constraining tidal site availability.
Strategic Opportunities
- Island and coastal community microgrids:Small-scale tidal installations offer baseload-compatible power where diesel generation currently dominates.
- Technology convergence with floating solar:Hybrid platforms combining tidal turbines with photovoltaic arrays maximize energy density per seabed lease.
- Scotland's Saltire Tidal Energy Challenge Fund:The grant mechanism de-risks early-stage demonstration projects, lowering developer equity requirements.
Industry Challenges
- Marine engineering talent scarcity:Subsea installation crews and corrosion specialists command premium wages, inflating OPEX forecasts.
- IEC 62600 certification timelines:Type testing for tidal energy converters requires multi-year tank and sea trials, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tidal Energy Generation Systems Market |
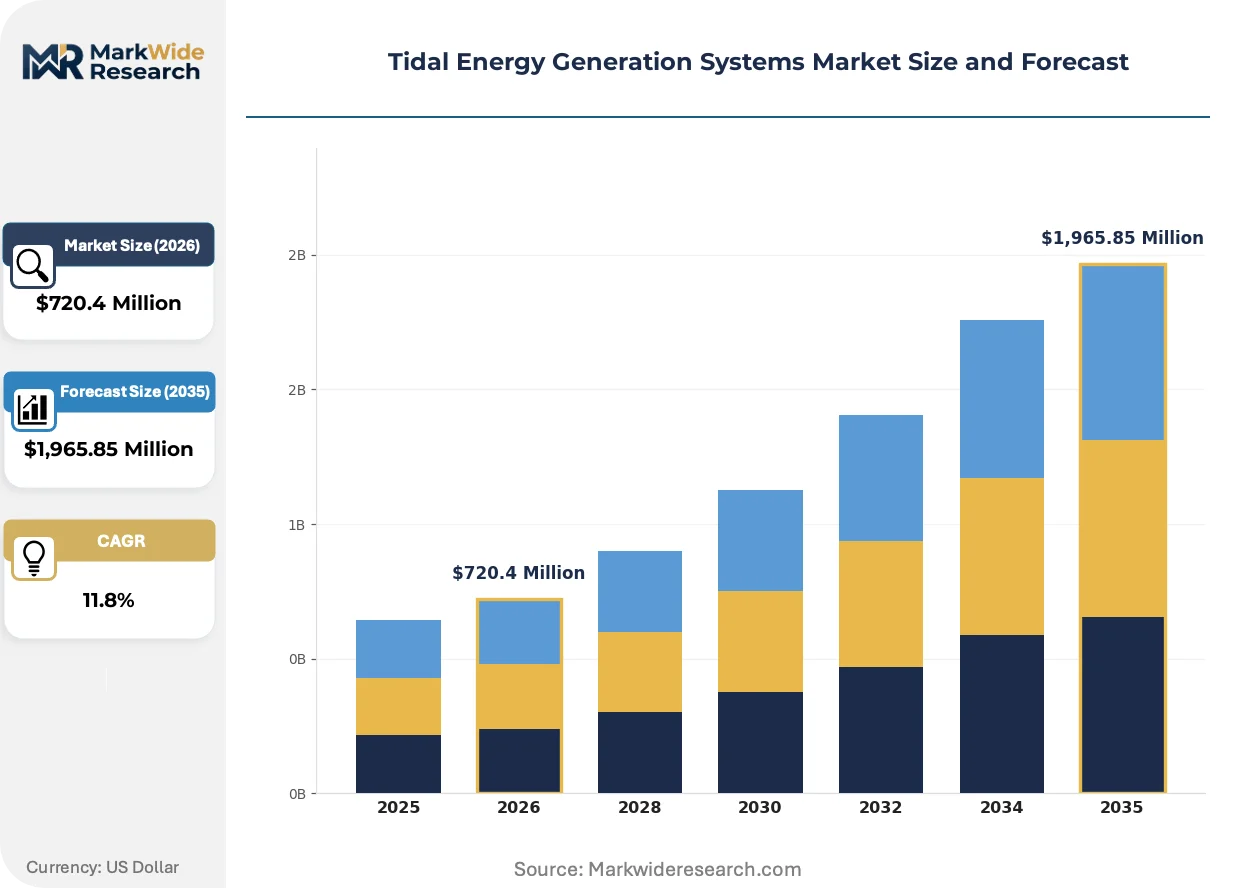
| Market Size in 2026 | $720.4 Million |
| Market Size in 2035 | $1,965.85 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Tidal Stream, Tidal Range, Dynamic Tidal Power, Hybrid Systems Installation Type: Onshore, Offshore, In-Stream, Integrated End User: Utilities, Government, Private Sector, Research Institutions Capacity: Small Scale, Medium Scale, Large Scale, Utility Scale |
| Companies Covered | Andritz Hydro Hammerfest, Sustainable Marine Energy, Nova Innovation, Orbital Marine Power, Verdant Power, SIMEC Atlantis Energy, Magallanes Renovables, HydroQuest SAS, Minesto, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tidal Energy Generation Systems Market Trends and Innovations
Floating platform architectures and predictive maintenance systems are compressing the cost gap between tidal stream and mature offshore wind, while consenting digitization accelerates project origination velocity.
Direct-drive permanent magnet generators are electrifying drivetrain reliability in harsh marine environments. Developers deploying high-velocity sites in the Pentland Firth corridor specify these units to eliminate gearbox maintenance windows. The technology is electrifying project finance terms by reducing operational risk premiums in long-term offtake negotiations.
UK Crown Estate seabed leasing frameworks now mandate biodiversity net gain commitments for new array awards. The requirement forces developers to integrate artificial reef structures into turbine foundations. Floating platform specialists face the steepest compliance costs, as their minimal seabed footprint offers fewer habitat offset opportunities.
Utility buyers now unbundle installation risk from equipment supply through separate EPC and turbine procurement contracts. National transmission operators in Scotland and Wales insist on this structure, shifting construction performance guarantees onto marine contractors. Channel array developers in shallow sites have adapted fastest, as their lower foundation complexity attracts competitive EPC bidding.
Tidal Energy Generation Systems Market Segmentation
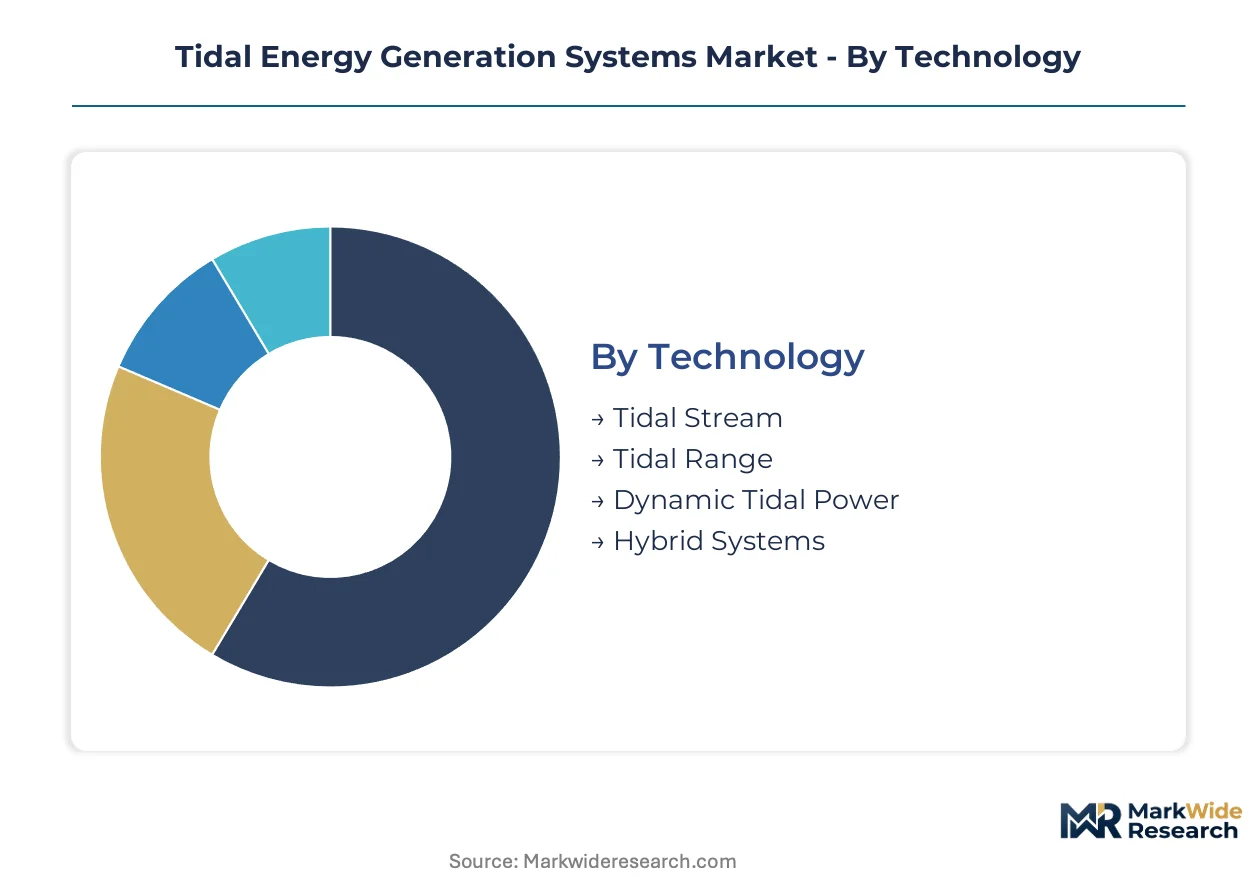
Technology choice dictates foundation complexity and permitting pathways across tidal energy projects. Installation type and capacity tier further stratify capital requirements, while end-user identity shapes offtake contract structures and revenue stability.
Technology:
Capital intensity peaks with barrage infrastructure and falls toward modular stream arrays, creating divergent financing ecosystems for each pathway.
- Tidal Stream:Horizontal-axis turbines extract kinetic energy from tidal currents at 20-40% capacity factor. Scotland's Pentland Firth corridor concentrates demand as developers validate commercial-scale arrays here.
- Tidal Range:Barrage and lagoon structures harness potential energy through tidal head differentials. Estuary geography constraints limit deployable sites to the Severn Estuary and comparable locations with sufficient tidal amplitude.
- Dynamic Tidal Power:Long dams perpendicular to coastlines create artificial head differences without enclosed basins. Netherlands and South Korean feasibility studies dominate project pipelines.
- Hybrid Systems:Combined tidal-stream and energy-storage configurations optimize dispatchability. Island microgrid operators in Orkney and Shetland specify these units to displace diesel generation.
Tidal Stream absorbs the bulk of installed capacity; Hybrid Systems are expanding most quickly.
Installation Type:
Water depth and seabed geology determine whether gravity-base, piled, or floating foundations prove economically viable at specific sites.
- Offshore:Deep-water arrays beyond 40 meters depth access stronger, more consistent currents. UK Crown Estate leasing rounds in Scottish waters concentrate procurement activity here.
- In-Stream:Shallow-channel turbines mounted directly on riverbed or seabed minimize foundation costs. Welsh tidal estuaries and Nova Scotian passages attract developers with simplified consenting pathways.
- Onshore:Land-based power conversion and control equipment supports submarine cable termination. Grid interconnection bottlenecks in rural Scotland inflate substation upgrade requirements.
- Integrated:Co-located tidal and offshore wind infrastructure shares export cables and maintenance vessels. Multi-use leasing frameworks in French waters enable these configurations.
Offshore installations dominate capital deployment; In-Stream configurations are climbing the fastest as near-shore permitting accelerates.
End User:
Contract duration and creditworthiness vary sharply across public and private offtake counterparts, reshaping project finance terms.
- Utilities:National transmission operators in Scotland, Wales, and Brittany sign 20-25 year power purchase agreements. These contracts provide the revenue certainty required for utility-scale project sanctioning.
- Government:Defense installations and coastal infrastructure authorities procure baseload power for remote facilities. UK Ministry of Defence specifications for Scapa Flow drive demand in this segment.
- Private Sector:Industrial clusters and data center operators seek 24/7 renewable supply. Subsea cable manufacturers in Norway and aluminum smelters in Iceland evaluate tidal contracts.
- Research Institutions:Universities and national laboratories fund demonstration arrays to validate environmental monitoring protocols. European Marine Energy Centre installations in Orkney exemplify this demand category.
Utilities command the largest share of committed capacity; Private Sector buyers are gaining share fastest as corporate renewable procurement expands.
Capacity:
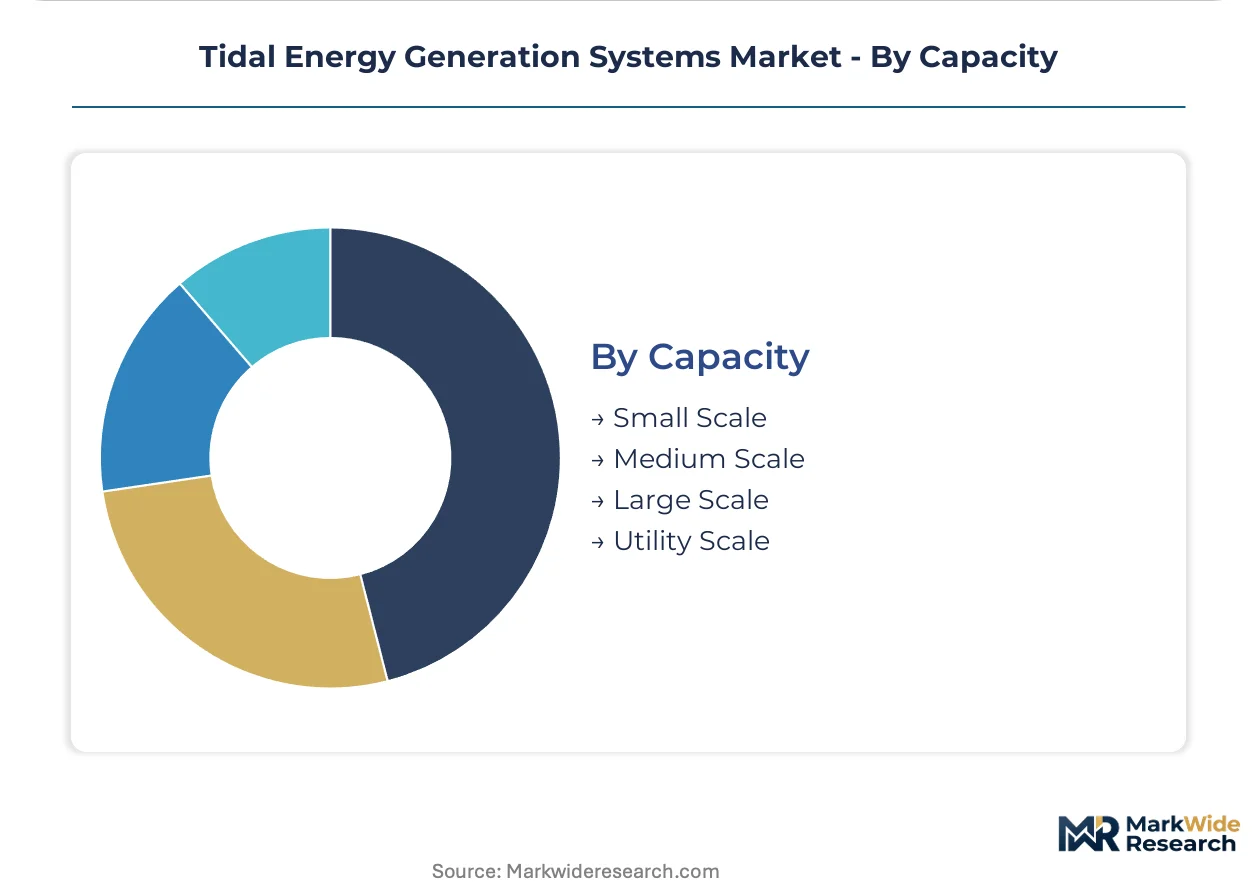
Scale thresholds determine whether projects qualify for national subsidy mechanisms or must rely on niche revenue streams.
- Utility Scale:Arrays exceeding 10 MW capacity feed directly into transmission networks. Scotland's Saltire Tidal Energy Challenge Fund targets these deployments with capital grants.
- Small Scale:Sub-100 kW installations serve single facilities or isolated communities. Scottish island councils and Canadian First Nations territories specify these units.
- Large Scale:1-10 MW projects bridge demonstration and commercial phases. Welsh tidal lagoon proposals and Korean demonstration zones concentrate activity here.
- Medium Scale:100 kW-1 MW systems support industrial microgrids and coastal processing facilities. Aquaculture operations in Norway and desalination plants in the Middle East evaluate this tier.
Utility Scale projects absorb dominant capital flows; Small Scale deployments are expanding most rapidly as distributed energy regulations mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scotland's Pentland Firth corridor anchors commercial deployment activity, with multiple demonstration sites now operating at utility scale and validating bankability models for tidal stream arrays.
United Kingdom
The UK Crown Estate seabed leasing framework accelerates project origination through streamlined consenting pathways. EU Green Deal marine renewable targets complement domestic policy, reducing regulatory uncertainty for array developers. Wales hosts active tidal lagoon proposals in the Severn Estuary corridor.
France
Brittany's national transmission operator signs long-term power purchase agreements that provide revenue certainty for utility-scale project sanctioning. Multi-use leasing frameworks enable integrated tidal and offshore wind configurations in French waters. The Raz Blanchard site concentrates demonstration activity.
Netherlands
Feasibility studies for dynamic tidal power dominate project pipelines where long dams perpendicular to coastlines create artificial head differences. The country's national energy regulator evaluates estuary geography constraints for deployable sites. Rotterdam's marine engineering cluster supports foundation design innovation.
South Korea
Demonstration zones in the 1-10 MW range bridge commercial phases for tidal range technology. The country's national renewable energy agency channels capital grants toward utility-scale deployments. Coastal provinces evaluate dynamic tidal power configurations.
Canada
Nova Scotian passages attract developers with simplified consenting pathways for in-stream shallow-channel turbines. First Nations territories specify small-scale installations to displace diesel generation. The Bay of Fundy's tidal amplitude supports range technology feasibility.
Tidal Energy Generation Systems Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the tidal energy generation systems market, creating a tiered structure where integrated technology developers face modular equipment specialists. The vendor base splits between deep-water turbine fabricators and shallow-channel array assemblers. Strategic archetypes include full-stack platform developers, component subsystem suppliers, and project development consortia. Capacity expansion and technology licensing dominate competitive moves as players seek to compress LCOE gaps with offshore wind.
Among Nordic-anchored full-stack developers, Andritz Hydro Hammerfest occupies a position representing deep-water turbine expertise, while Nova Innovation exemplifies the modular design archetype for shallow-channel environments. Orbital Marine Power sits within the floating platform specialization tier, anchoring technology convergence for high-velocity sites.
| Leading Market Players |
|---|
| Andritz Hydro Hammerfest |
| Sustainable Marine Energy |
| Nova Innovation |
| Orbital Marine Power |
| Verdant Power |
| SIMEC Atlantis Energy |
| Magallanes Renovables |
| HydroQuest SAS |
| Minesto |
| Others |
Pricing and Supply Chain Analysis
Direct-drive permanent magnet generator adoption in the Pentland Firth corridor is compressing lifecycle cost economics while concentrating procurement leverage among Nordic drivetrain specialists. This technology transition simultaneously elevates upfront capital requirements and reduces long-term maintenance exposure, reshaping how developers structure equipment supply agreements.
Pricing Analysis
Capacity-factor guarantees anchor value-based pricing for tidal stream arrays, with developers contracting uptime commitments rather than equipment-only supply. Price differentiation rests on IEC 62600 certification tier and foundation complexity grade, with floating platforms commanding premiums over gravity-base alternatives. Cost compression in shallow-channel configurations is intensifying because Nova Innovation's modular designs reduce installation vessel days. Island microgrid buyers exhibit highest price sensitivity due to limited concession financing access, while UK Crown Estate leaseholders show lowest sensitivity given long-term offtake security.
Supply Chain Analysis
Marine engineering talent scarcity in Scottish fabrication yards and Norwegian subsea installation ports is extending equipment delivery timelines. Supply concentration centers on the United Kingdom, France, and South Korea for turbine assembly, with rare-earth magnet sourcing drawing from Chinese processors. Single-source vulnerability runs through permanent magnet supply chains. Distribution runs through EPC-led project delivery where marine contractors assume installation risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained turbine fabrication capacity props pricing power for certified equipment suppliers, as IEC 62600 type-testing queues extend commissioning timelines beyond developer patience thresholds.
For Market Incumbents: Deploy predictive maintenance system licensing to capture recurring revenue streams and defend against floating offshore wind substitution. Anchor capacity addition in Scottish waters where Crown Estate leasing rounds concentrate demand. Deepen backward integration into permanent magnet supply to offset Chinese processor concentration risk. For New Entrants and Emerging Players: Capture Welsh tidal estuary in-stream opportunities where simplified consenting pathways lower regulatory capital barriers. Target Canadian First Nations territories specifying small-scale diesel displacement units. Pursue technology convergence partnerships with floating solar developers to maximize seabed lease energy density. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by offshore wind developers seeking tidal diversification. Long-term viability frames around technology convergence with hybrid storage configurations and marine engineering talent access. Watch Scotland's Saltire Tidal Energy Challenge Fund allocation velocity as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Scottish Pentland Firth deployments validate commercial-scale bankability models for utility-scale arrays. |
| Power Purchase Agreement | Brittany's national transmission operator contracts provide revenue certainty for project sanctioning decisions. |
| Technology Licensing | Direct-drive generator IP transfers compress LCOE gaps with mature offshore wind technologies. |
| Vertical Integration into Storage | Hybrid tidal-battery configurations optimize dispatchability for island microgrid displacement applications. |
| Green Certification Program | UK Crown Estate biodiversity net gain mandates force artificial reef integration into foundation design. |
Research Methodology
Independent corroboration across utility planning officers, IPP project developers, EPC contractors, and grid operators underwrites the qualitative findings. Primary field engagement with marine engineering specialists and tidal array developers combined with secondary validation from EIA data, IEA ocean energy reports, UK Crown Estate leasing registers, and FERC interconnection filings. Bottom-up project pipeline enumeration triangulates against top-down national renewable target allocations.
Rate-of-change decomposition separates technology cost trajectories from regulatory velocity and grid interconnection expansion schedules across the analysis window. Segmentation dimensions span technology type, installation depth, capacity tier, end-user contract structure, and regional regulatory framework. CAGRs derive from installed capacity build-up curves and unit cost learning rates, with specific inputs including EU Green Deal marine renewable target trajectories and Scotland's Saltire Tidal Energy Challenge Fund disbursement schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to floating offshore wind LCOE convergence and seabed leasing queue clearance rates. Forecasts reflect documented assumptions around IEC 62600 certification timeline stability and subsea cable procurement cost trajectories. A small set of triggers warrants ongoing watch: EU Habitats Directive assessment protocol revisions, UK Marine Management Organisation staffing levels, and rare-earth magnet export restriction developments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Offshore Wind Energy Infrastructure Market
Renewable Energy
Solar Floating Pool Lights Market
Renewable Energy
Solar Oven Market
Renewable Energy
Drone Inspection Service for Renewable Energy Market
Renewable Energy
LAMEA Wave and Tidal Energy Market
Renewable Energy
Wave Energy Market
Renewable Energy
Hybrid Solar Wind System Market
Renewable Energy
North America IoT in Renewable Energy Market
Renewable Energy
Solar Watch Market
Renewable Energy
Renewable Heating Market
Renewable Energy
Biogas Upgrading Technology Market
Renewable Energy
Italy Renewable Energy Market
Renewable Energy
Europe Ocean Power Market
Renewable Energy
New Zealand Renewable Energy Market
Renewable Energy
Canada Renewable Energy Market
Renewable Energy
Global Green Energy Market