
 Asia-Pacific Small Hydropower Market | 2026-2036
Asia-Pacific Small Hydropower Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Small Hydropower Market Outlook
China's dual carbon goals is decoupling project economics from fossil-fuel baselines across the Asia-Pacific small hydropower sector. ANDRITZ leverages its Austrian engineering heritage to dominate turbine supply chains across Himalayan projects. Bharat Heavy Electricals Limited anchors India's public-sector procurement pipeline with in-house manufacturing of electromechanical packages. Voith GmbH & Co. KGaA differentiates through digital automation layers that optimize plant efficiency in variable-flow river systems.
Asia-Pacific small hydropower encompasses run-of-river, reservoir, and pumped storage installations typically below 20 MW capacity, utilizing impulse turbines, reaction turbines, or Archimedes screw technologies to convert hydraulic head into rotational mechanical energy for electricity generation. Run-of-river configurations occupy the largest installed base due to lower civil works requirements and reduced environmental permitting complexity compared with impoundment alternatives. The 1-5 MW capacity band captures the fastest expansion as rural electrification agencies in Indonesia, Nepal, and Vietnam prioritize distributed generation over grid extension.
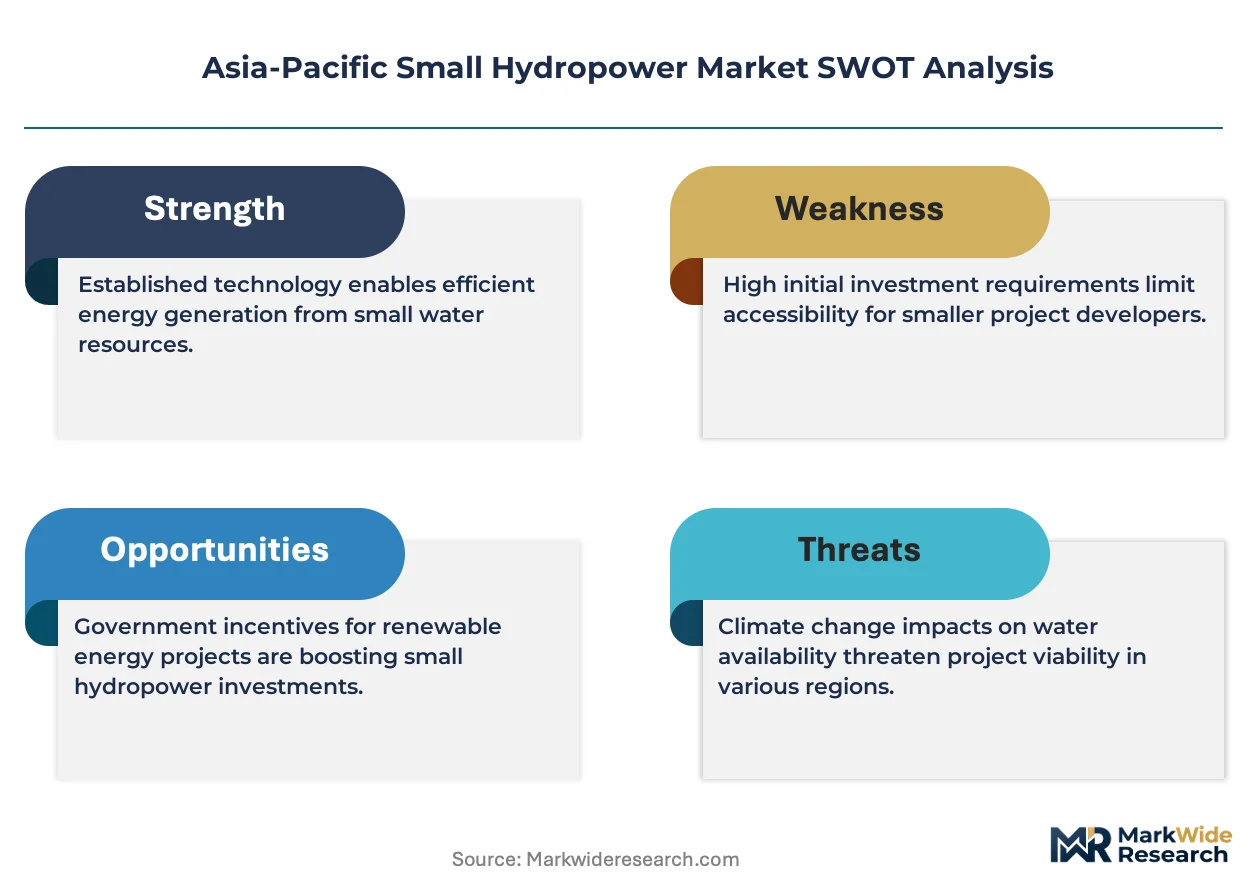
India's Central Electricity Authority enforces mandatory hydrological risk assessments that filter out speculative developers and concentrate project pipelines among engineering-capable firms. China's Ministry of Ecology and Environment (MEE) mandates fish-passage provisions and minimum ecological flow releases that raise civil works costs but bar low-compliance entrants. Japan's METI maintains feed-in tariff schedules that sustain retrofits of aging prefectural installations. Stakeholders must track how evolving river-basin authority permits in the Mekong region reshape cross-border equipment procurement and EPC contracting terms.
Market Dynamics
China's dual carbon goals are compressing fossil-fuel baselines across the Asia-Pacific small hydropower sector, forcing developers to recalibrate project economics against stricter emissions accounting. This structural pressure cascades through equipment procurement, EPC contracting, and cross-border financing arrangements.
Growth Catalysts
- India's PLI scheme for clean energy:Production-linked incentives for domestic manufacturing of electromechanical components are shortening import dependency for Himalayan state projects.
- Rural electrification agencies:Indonesia's village-level programs are accelerating run-of-river deployment over costly grid extension into remote archipelago communities.
- Variable-flow optimization:Digital turbine control systems are capturing seasonal flow fluctuations that previously rendered sites economically marginal.
Market Restraints
- Steel and cement input volatility:Civil works for intake structures and penstocks face cost pressure from commodity price swings, squeezing fixed-price EPC margins.
- Equipment supply concentration:Austrian and German turbine specialists dominate high-head Himalayan projects, creating procurement bottlenecks during peak construction windows.
- China's MEE ecological flow mandates:Minimum downstream release requirements raise civil works costs and reduce firm capacity factors at reservoir-dependent sites.
Strategic Opportunities
- Vietnam's central highlands:Underpenetrated river basins in Kon Tum and Gia Lai provinces offer untapped 1-10 MW sites with existing road access.
- Pumped storage retrofits:Converting aging Japanese prefectural installations to dual-mode operation captures ancillary services revenue under METI feed-in tariff adjustments.
- Direct power purchase agreements:Industrial offtakers in Thailand's Eastern Economic Corridor are bypassing utility intermediaries for dedicated renewable supply contracts.
Industry Challenges
- Hydrological risk assessment capacity:India's CEA mandatory studies filter speculative developers, but qualified assessor scarcity delays project pipelines.
- Fish-passage engineering integration:MEE compliance requires specialized biological and hydraulic design capabilities that standard EPC firms lack in-house.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Small Hydropower Market |
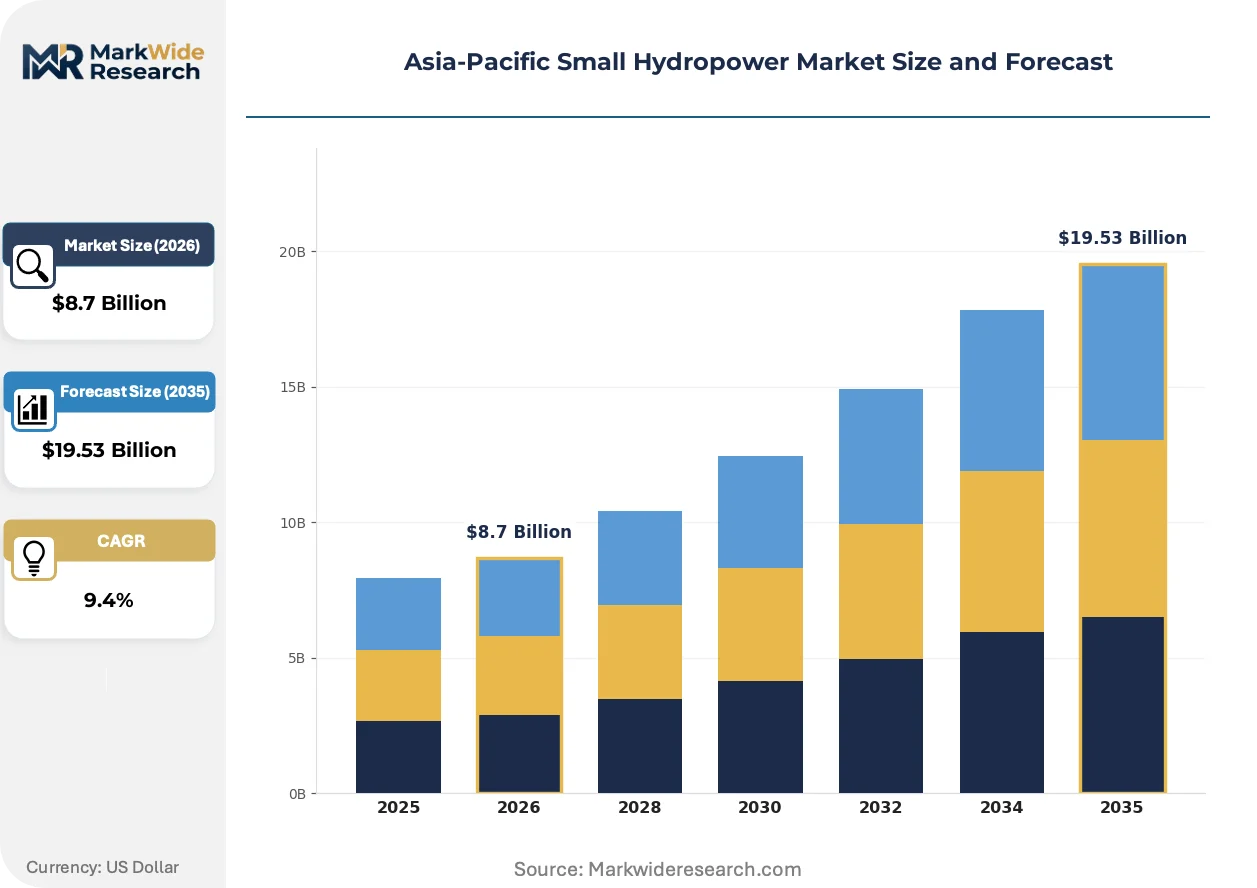
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Installation Type: Run-of-River, Reservoir, Pumped Storage, Off-Grid End User: Agriculture, Industrial, Municipal, Remote Communities Technology: Impulse Turbines, Reaction Turbines, Archimedes Screw, Turbine Generators Capacity: Up to 1 MW, 1-5 MW, 5-10 MW, 10-20 MW |
| Companies Covered | ANDRITZ, FLOVEL Energy Private Limited, General Electric, SNC Lavalin Group, Bharat Heavy Electricals Limited, Siemens Energy, Voith GmbH & Co. KGaA, Natel Energy, Toshiba Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Small Hydropower Market Strategic Shifts
Digital layer integration is reshaping how Asia-Pacific small hydropower assets are operated, financed, and maintained. Automation, ecological compliance technology, and procurement model evolution are compressing traditional engineering timelines.
Digital twin platforms are automating predictive maintenance scheduling across aging Japanese prefectural installations. METI-subsidized retrofits deploy sensor arrays that feed machine-learning models for turbine blade wear forecasting. This capability is automating outage planning that previously relied on fixed-interval inspections, extending operational life at sub-5 MW sites.
China's MEE river-basin authority permits now mandate real-time ecological flow monitoring with satellite telemetry backup. This regulatory layer forces developers to embed SCADA systems with redundant data transmission from project inception. Himalayan projects in Sichuan and Yunnan provinces are absorbing these civil-electrical integration costs as a condition of construction approval.
Vietnamese industrial buyers are consolidating procurement through engineering-procurement-construction-management contracts that unbundle turbine supply from civil works. This model transfers hydrological risk to EPCMs while retaining equipment specification control. The shift is most visible in Quang Nam province, where textile manufacturers aggregate demand for captive renewable supply.
Asia-Pacific Small Hydropower Market Segmentation
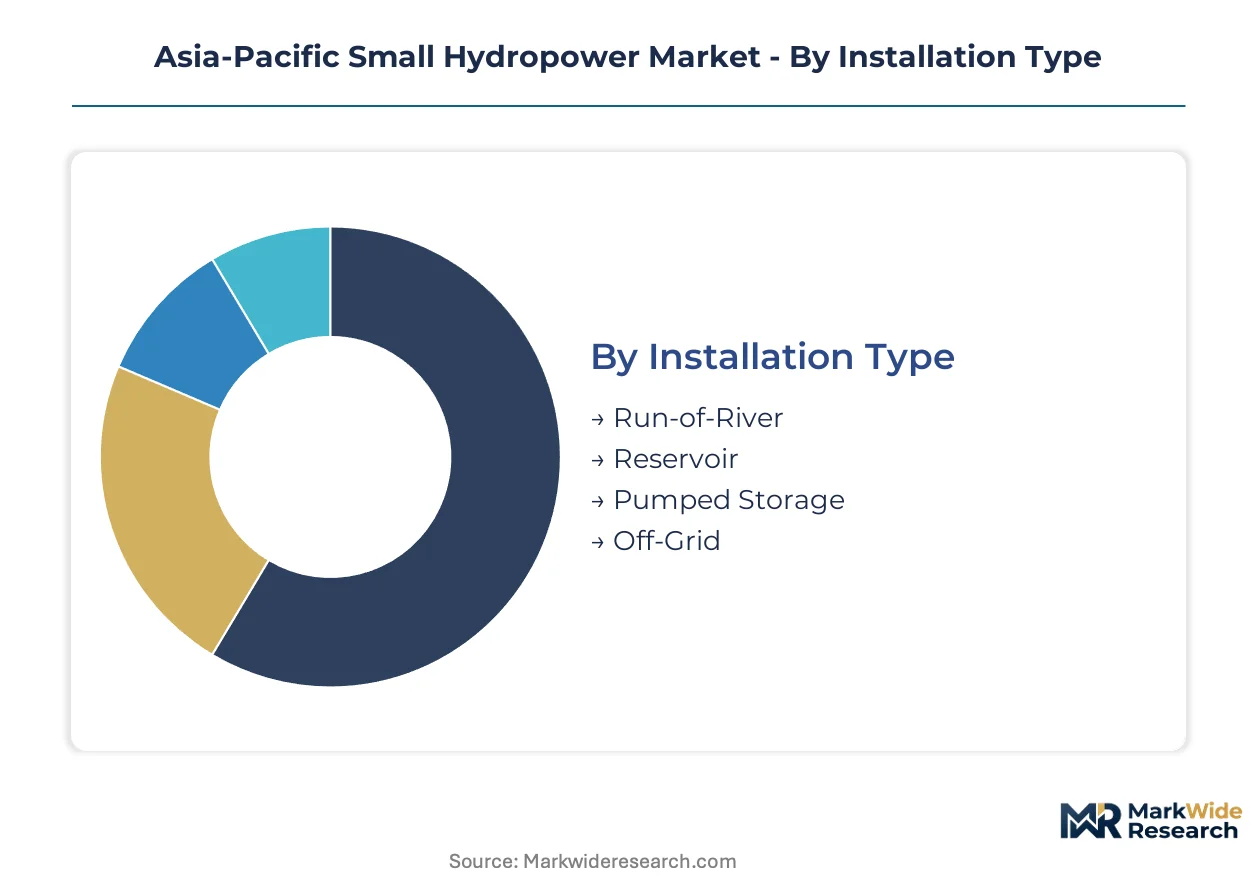
Segmentation in Asia-Pacific small hydropower reveals how capital allocation, regulatory exposure, and technology choices diverge across project archetypes. Developers, financiers, and equipment suppliers calibrate strategies against these fault lines.
Installation Type:
Capital intensity varies sharply across installation configurations, with civil works requirements driving the widest spreads in upfront investment.
- Run-of-River:Divert flow through intake weirs and penstocks without large impoundment, minimizing concrete and land acquisition costs. Demand concentrates in Indonesia's outer islands and Vietnam's central highlands where grid extension proves uneconomical and environmental permitting favors minimal footprint.
- Reservoir:Require dam construction, sediment management infrastructure, and extended geological surveys that multiply civil works budgets. China's southwestern provinces absorb these costs under MEE ecological flow mandates that downstream release obligations impose.
- Pumped Storage:Dual-reservoir configurations with reversible turbine-generators command the highest capital outlays per megawatt. Japan's aging prefectural installations drive retrofit demand under METI feed-in tariff adjustments.
- Off-Grid:Standalone micro-installations below 1 MW serve isolated loads without transmission interconnect. Nepal's mountain districts and Philippine archipelago communities anchor procurement.
Most installed capacity flows through Run-of-River configurations. Expansion is steepest in Pumped Storage retrofits.
End User:
Customer type dictates dispatch priority, tariff structures, and offtake risk profiles across the project pipeline.
- Agriculture:Irrigation districts and rural cooperatives purchase power for pumping and processing. India's Himalayan states channel subsidies toward farm electrification.
- Industrial:Textile mills, cement plants, and food processors seek captive supply to hedge grid volatility. Thailand's Eastern Economic Corridor bypasses utility intermediaries through direct power purchase agreements.
- Municipal:City governments procure for street lighting, water treatment, and public buildings. Vietnamese provincial authorities aggregate demand across urban clusters.
- Remote Communities:Village-level programs in Indonesia and Papua New Guinea prioritize distributed generation over transmission investment. Rural electrification agencies fund these deployments through concessional finance windows.
Industrial offtakers command the highest tariff tolerance. Remote Communities absorb the fastest capacity additions.
Technology:
Head and flow characteristics at specific sites determine turbine technology selection, with manufacturing complexity driving cost differentiation.
- Impulse Turbines:Pelton and Turgo designs convert high-head, low-flow conditions through jet impingement on bucket-shaped runners. Himalayan projects in Sikkim and Himachal Pradesh deploy these for heads exceeding 100 meters.
- Reaction Turbines:Francis and Kaplan variants operate fully submerged, capturing energy from pressure and kinetic components across moderate head ranges. China's Yangtze tributaries and Mekong basin sites favor these configurations.
- Archimedes Screw:Low-head, high-flow applications with minimal fish mortality risk. MEE compliance requirements in riverine ecosystems accelerate adoption.
- Turbine Generators:Integrated electromechanical packages combining runner, generator, and control systems. India's PLI scheme for clean energy incentivizes domestic assembly.
Reaction Turbines dominate cumulative installations. Archimedes Screw configurations are climbing the fastest.
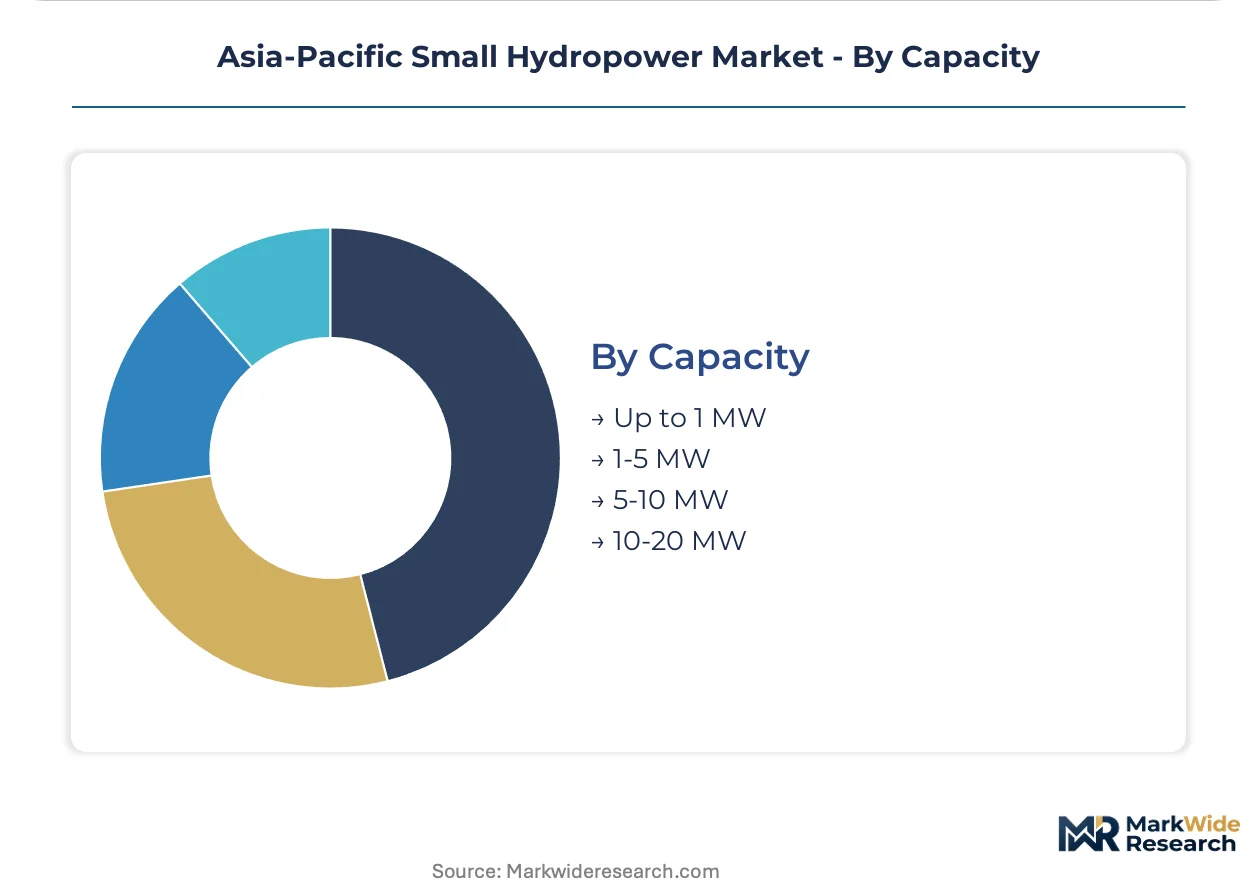
Capacity:
Scale thresholds trigger distinct regulatory regimes, financing mechanisms, and equipment procurement patterns.
- Up to 1 MW:Micro-hydro installations serving single villages or small industrial loads. Nepal's micro-hydro development program and Indonesia's village-level initiatives channel public finance here.
- 1-5 MW:Mini-hydro scale capturing the steepest expansion trajectory as rural electrification agencies prioritize distributed generation. Vietnam's Quang Nam province and India's Uttarakhand state concentrate deployment.
- 5-10 MW:Small-hydro threshold where grid interconnect requirements intensify and environmental impact assessments deepen. Chinese provincial SOEs dominate this band.
- 10-20 MW:Upper small-hydro limit approaching utility-scale classification, attracting independent power producers and infrastructure funds. Japan's retrofit pipeline and Thailand's captive industrial supply segment anchor demand.
The 1-5 MW band carries the majority of new project announcements. The 10-20 MW segment posts the highest revenue per installation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in Sichuan, Himachal Pradesh, and Kyushu anchor project execution capacity across the Asia-Pacific small hydropower sector. These workforce concentrations support specialized civil works, turbine manufacturing, and digital automation deployment.
China
Southwestern provinces including Sichuan and Yunnan concentrate run-of-river and reservoir development under MEE ecological flow mandates. The Ministry of Ecology and Environment requires real-time monitoring systems with satellite telemetry backup, embedding SCADA infrastructure from project inception. Developers in these river basins absorb elevated civil-electrical integration costs as a condition of construction approval.
India
Himalayan states of Uttarakhand, Himachal Pradesh, and Sikkim drive procurement of high-head impulse turbines for sites exceeding 100 meters. The Central Electricity Authority enforces mandatory hydrological risk assessments that filter speculative developers and concentrate pipelines among engineering-capable firms. Bharat Heavy Electricals Limited anchors public-sector procurement with in-house electromechanical package manufacturing.
Japan
Prefectural installations across Kyushu and Tohoku regions sustain retrofit demand under METI feed-in tariff schedules. The Ministry of Economy, Trade and Industry subsidizes digital twin deployments for predictive maintenance at aging sub-5 MW sites. Machine-learning models now automate outage planning that previously relied on fixed-interval inspections.
Vietnam
Central highlands provinces of Kon Tum and Gia Lai offer underpenetrated 1-10 MW sites with existing road access. Provincial authorities aggregate municipal demand across urban clusters while textile manufacturers in Quang Nam province consolidate procurement through engineering-procurement-construction-management contracts. This model transfers hydrological risk to EPCMs while retaining equipment specification control.
Indonesia
Outer island archipelago communities accelerate village-level run-of-river deployment over costly grid extension. Rural electrification agencies channel concessional finance toward micro-hydro installations below 1 MW serving isolated loads. These programs prioritize distributed generation where transmission interconnect proves economically unviable.
Asia-Pacific Small Hydropower Market Competitive Environment
The competitive structure tilts toward European engineering specialists with Austrian and German heritage dominating high-head turbine supply. Equipment procurement concentrates among firms with decades of hydraulic engineering lineage, creating tiered access based on technical certification depth. Two strategic archetypes prevail: integrated electromechanical packagers and precision turbine specialists. Competitive moves center on digital automation layer integration and backward integration into casting and forging capabilities.
Among European engineering houses, ANDRITZ and Voith GmbH & Co. KGaA occupy positions reflecting Austrian and German hydraulic heritage respectively. Bharat Heavy Electricals Limited sits within the public-sector integrated packager archetype, leveraging in-house manufacturing for India's Himalayan state pipelines. These three entities exemplify how engineering lineage and domestic policy alignment shape competitive positioning without requiring equivalent scale or geographic scope.
| Leading Market Players |
|---|
| ANDRITZ |
| FLOVEL Energy Private Limited |
| General Electric |
| SNC Lavalin Group |
| Bharat Heavy Electricals Limited |
| Siemens Energy |
| Voith GmbH & Co. KGaA |
| Natel Energy |
| Toshiba Corporation |
| Others |
Value Chain & Pricing Dynamics
Digital twin deployments for predictive maintenance are compressing lifecycle service costs while concentrating procurement leverage among turbine manufacturers with automation capabilities. This technology shift simultaneously lowers operational expenditure thresholds for asset owners and rewards suppliers with integrated SCADA offerings.
Pricing Analysis
The bundled-vs-unbundled service split defines pricing architecture across Asia-Pacific small hydropower. Engineering-procurement-construction contracts dominate Himalayan projects, embedding electromechanical packages within fixed civil works pricing. Price differentiation hinges on automation tier and after-sales service depth. Cost compression in standard turbine supply is intensifying because Vietnamese textile manufacturers consolidate demand through EPCM contracts. Remote community offtakers exhibit highest price sensitivity; Japanese industrial retrofits show lowest.
Supply Chain Analysis
Specialty steel forging capacity rests on Austrian and German engineering houses for high-head Pelton runners. China's southwestern provinces and India's Himalayan states draw from these European specialists for turbine supply, while domestic casting feeds lower-head Francis applications. Single-source vulnerability concentrates in precision-machined impulse turbine components. Distribution runs through EPC contractors with river-basin authority relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific small hydropower offers margin expansion through digital service layers and ecological compliance technology premiums. Cost-down drivers include modular turbine-generator standardization reducing custom engineering overhead.
For Market Incumbents: Anticipate procurement consolidation by Vietnamese industrial buyers and Indonesian rural electrification agencies compressing equipment margins. Deepen backward integration into precision casting to defend against Austrian and German turbine specialists. Prioritize SCADA platform certification under China's MEE real-time monitoring mandates.
For New Entrants and Emerging Players: Begin with Archimedes screw technology for low-head, high-flow sites where MEE fish-passage requirements disadvantage traditional turbine configurations. Vietnam's central highlands offer most penetrable geography with existing road access and underdeveloped river basin authority permitting. Pursue direct power purchase agreement origination with Thai Eastern Economic Corridor manufacturers seeking captive renewable supply.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap EPC contractors with hydrological assessment capabilities but limited equipment manufacturing. Long-term viability frames around 5-10 year regulatory enforcement windows for ecological flow compliance. Watch China's MEE permit processing velocity as inflection indicator for construction approval timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Deployment | METI subsidies accelerate predictive maintenance adoption across Japan's aging prefectural installations. |
| Ecological Flow Monitoring Integration | MEE mandates embed SCADA infrastructure from project inception in Sichuan and Yunnan. |
| Backward Integration into Casting | Bharat Heavy Electricals Limited anchors India's PLI scheme with in-house electromechanical manufacturing. |
| EPCM Contract Consolidation | Vietnamese textile manufacturers aggregate demand while transferring hydrological risk to contractors. |
| Pumped Storage Retrofit Conversion | Japan's METI feed-in tariff adjustments sustain dual-mode operation revenue capture. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged IPP project developers, EPC contractors, utility planning officers, and grid operators across China, India, Japan, Vietnam, and Indonesia. Secondary validation drew from EIA data, IEA hydropower databases, FERC filings, and river-basin authority permit records. Bottom-up project pipeline aggregation triangulated against top-down national renewable energy targets.
Comparable-period anchoring calibrated the forecast window against historical capacity addition trajectories across the projection horizon. Segmentation dimensions modeled include installation type, capacity tier, turbine technology, and regional regulatory framework. CAGRs derived from slope-log regression on normalized deployment curves. Industry-specific inputs incorporated MEE ecological flow compliance cost curves and PLI scheme domestic content thresholds.
Several conditions sit outside the modeled scope, including cross-border transmission interconnect timelines and Mekong river-basin authority jurisdictional disputes. Forecasts reflect documented assumptions on hydrological risk assessment completion rates and steel-cement input price stability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydropower Systems
United States Hydro Turbine Market
Hydropower Systems
Standard Modular Hydropower Market
Hydropower Systems
Asia-Pacific Pumped Hydro Storage Market
Hydropower Systems
Global Hydro Turbine Generator Unit Market
Hydropower Systems
Hydroelectricity Market
Hydropower Systems
Small Hydropower Market
Hydropower Systems
Whirlpool Turbine Market
Hydropower Systems
Floating Power Plant Market
Hydropower Systems
Pumped Hydro Storage Market
Hydropower Systems
North America Pumped Hydro Storage Market
Hydropower Systems
Hydropower Market
Hydropower Systems
Hydropower Turbine Market
Hydropower Systems
Offshore Hydropower Market
Hydropower Systems
Tidal Power Market
Hydropower Systems
Southeast Asia Hydropower Market
Hydropower Systems
Hydropower Generation Market