
 Europe Small Hydropower Market | 2026-2036
Europe Small Hydropower Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Small Hydropower Market Foresight
Long-term operations and maintenance contracts is expanding as a revenue layer, shifting vendor economics from equipment sales to lifecycle service agreements. Voith GmbH & Co. KGaA leverages its turbine refurbishment expertise to lock in recurring revenue streams. Siemens Energy AG anchors its position through digital hydropower monitoring platforms. Statkraft competes by bundling small hydro assets with Nordic grid-balancing services.
Small hydropower denotes electricity generation facilities typically below 10 MW capacity utilizing diverted river flows, penstock channels, and reaction or impulse turbines to convert hydraulic head into rotational mechanical energy. These installations serve baseload renewable supply, grid stabilization, and remote community electrification across Europe's river networks. Run-of-river systems dominate installed capacity due to lower environmental disruption and reduced reservoir requirements. Municipal utilities represent the fastest-growing end user segment as cities pursue direct renewable procurement under climate action mandates. Retrofit projects command premium margins where aging infrastructure requires turbine modernization without civil works reconstruction.
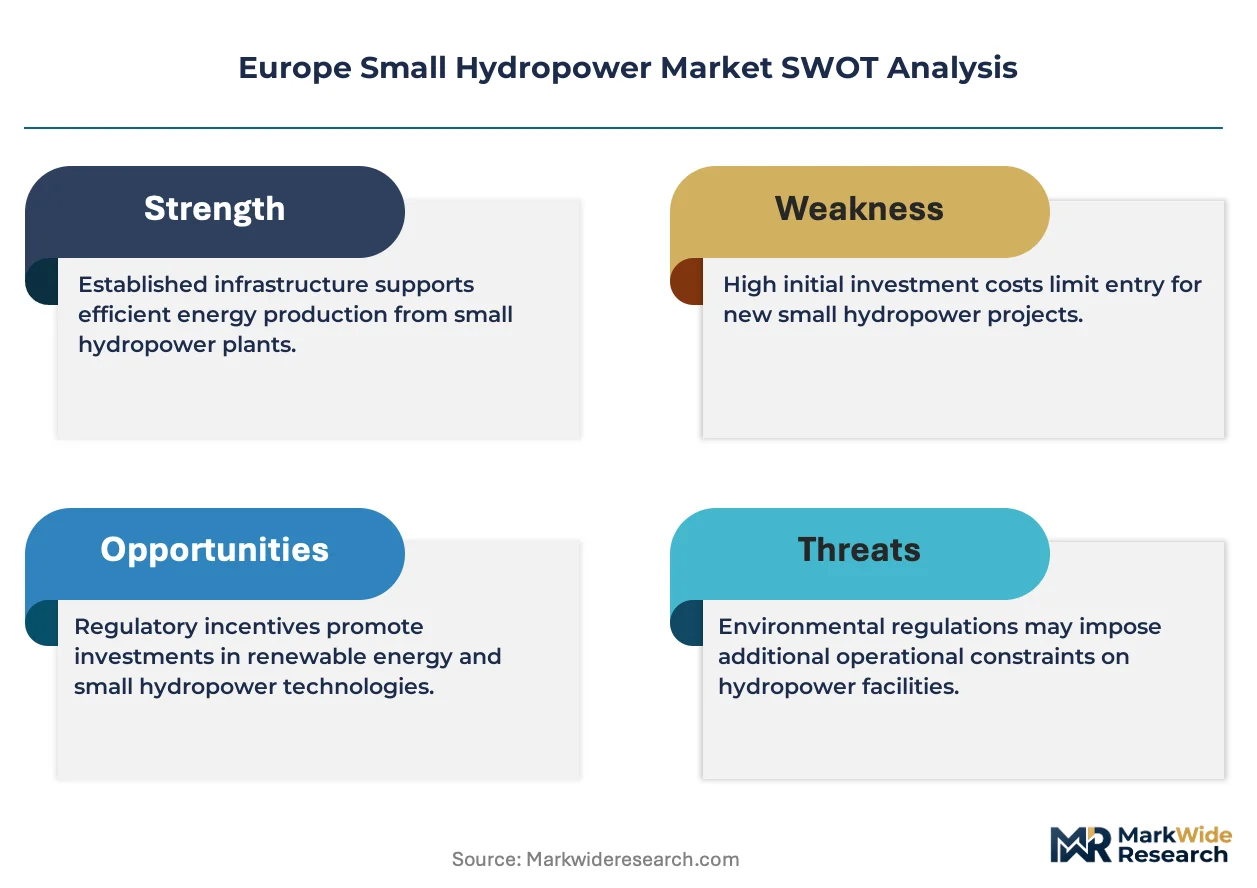
EU Green Deal targets, the revised Renewable Energy Directive, and national transpositions under EMAS frameworks are tightening environmental flow requirements and streamlining cross-border permitting. ECHA chemical restrictions and CE marking obligations for electromechanical equipment further shape component sourcing and market access protocols. Stakeholders must monitor evolving subsidy phase-out schedules and grid connection priority rules to align capital deployment with policy trajectories.
Market Dynamics
Run-of-river turbine refurbishment cycles are compressing as Alpine municipal utilities accelerate asset renewal under EU Green Deal deadlines. This equipment refresh dynamic is redrawing vendor-customer relationships toward multi-decade service partnerships.
Growth Catalysts
- EU Green Deal implementation:National transpositions of renewable targets are unlocking permitting fast-tracks for sub-10 MW installations in Norway, Italy, and Austria.
- Grid decentralization mandates:Distribution system operators across Alpine regions now prioritize distributed generation assets for frequency regulation services.
- Penstock composite materials:Fiber-reinforced polymer piping is reducing civil works costs by half in mountainous terrain applications.
Market Restraints
- Steel and copper input volatility:Electromechanical component fabrication faces margin pressure from base metal price swings affecting turbine housing and generator winding costs.
- Environmental flow requirements:Revised national implementations of the Water Framework Directive are restricting viable site availability in ecologically sensitive catchments.
- Solar-plus-storage substitution:Modular photovoltaic-battery configurations are capturing rural electrification budgets previously allocated to micro-hydro.
Strategic Opportunities
- Retrofit turbine modernization:Aging Francis and Pelton installations across the Alps require electromechanical replacement without dam reconstruction.
- CE marking harmonization:Streamlined conformity assessment procedures under the revised Machinery Directive are reducing time-to-market for equipment vendors.
- Digital twin convergence:IoT sensor networks combined with predictive analytics are enabling remote asset management contracts.
Industry Challenges
- Specialized hydromechanical engineering talent:Turbine blade design and cavitation analysis expertise concentrates among retiring workforce cohorts in Alpine engineering clusters.
- Cross-border permitting complexity:Transboundary river basin authorities require synchronized approvals for installations affecting multiple jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Small Hydropower Market |
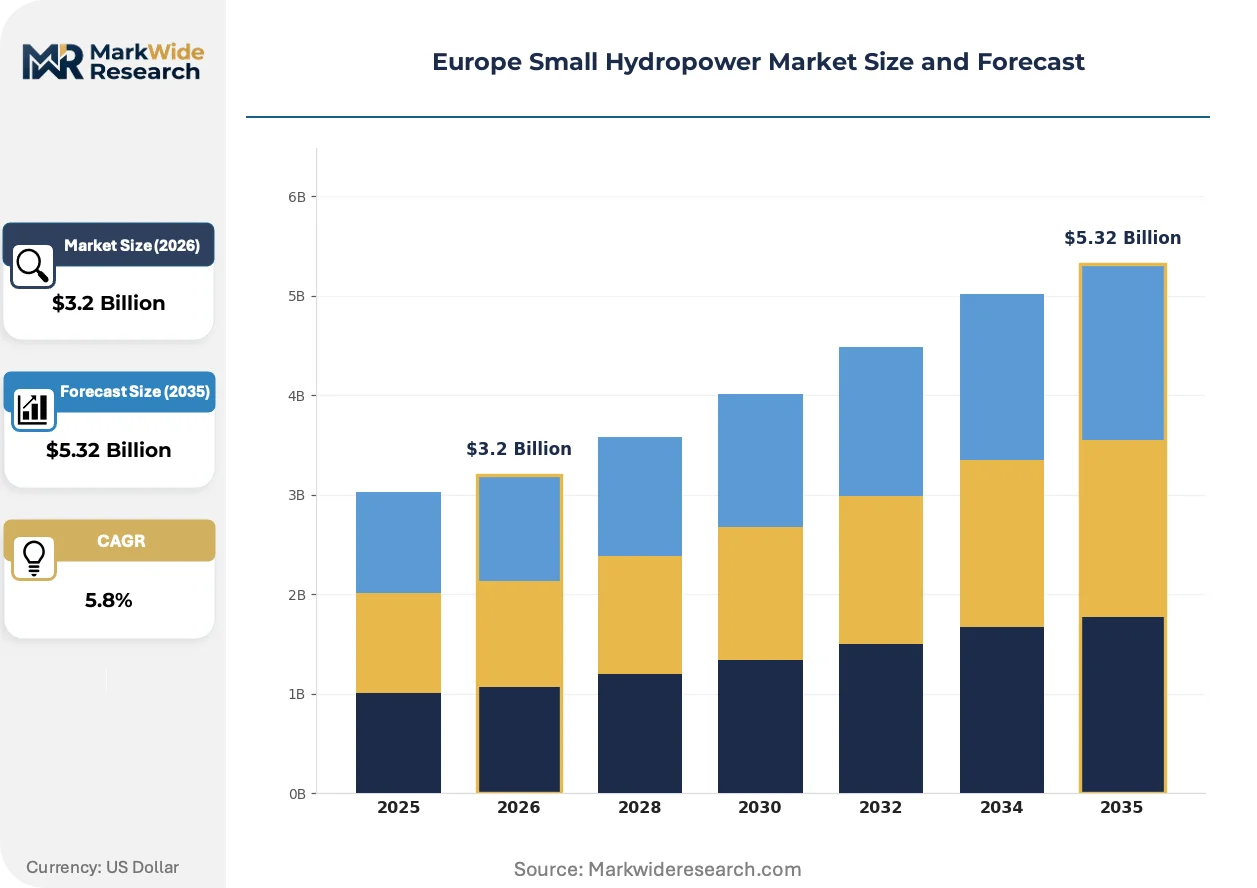
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $5.32 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Turbinated Systems, Diversion Systems, Pondage Systems, Run-of-River Systems End User: Municipal Utilities, Industrial Users, Private Developers, Agricultural Users Installation Type: Onshore Installations, Standalone Units, Hybrid Systems, Retrofit Projects Power Output: Up to 1 MW, 1-5 MW, Over 5 MW, Below 100 kW |
| Companies Covered | GE Renewable Energy, Iberdrola SA, Voith GmbH & Co. KGaA, Kolektor Group, Gilbert Gilkes & Gordon Ltd., Siemens Energy AG, Electricite de France SA, Statkraft, Andritz AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Small Hydropower Market Shifts & Advancements
Digital monitoring platforms are penetrating small hydropower operations as utilities prioritize uptime guarantees over capital expenditure efficiency. This shift is rewiring competitive advantage toward software-enabled service capabilities.
Variable-speed generator technology is overtaking fixed-speed synchronous machines in run-of-river applications. Norwegian and Austrian municipal utilities are retrofitting existing penstocks with doubly-fed induction generators to capture partial-load efficiency gains. This electromechanical upgrade path is compressing simple payback periods for aging assets.
The EU Green Deal's revised Renewable Energy Directive is tightening environmental flow requirements across member states. Hydropower developers must now integrate fish-friendly turbine designs and real-time ecological monitoring systems. Alpine project pipelines are restructuring around these biological passage mandates.
Municipal utilities are consolidating equipment procurement through framework agreements spanning multiple installations. Voith and Siemens Energy are responding with lifecycle service bundles that transfer operational risk from plant operators to OEM balance sheets. This preference shift is most visible in Austria's provincial utility sector.
Europe Small Hydropower Market Segmentation
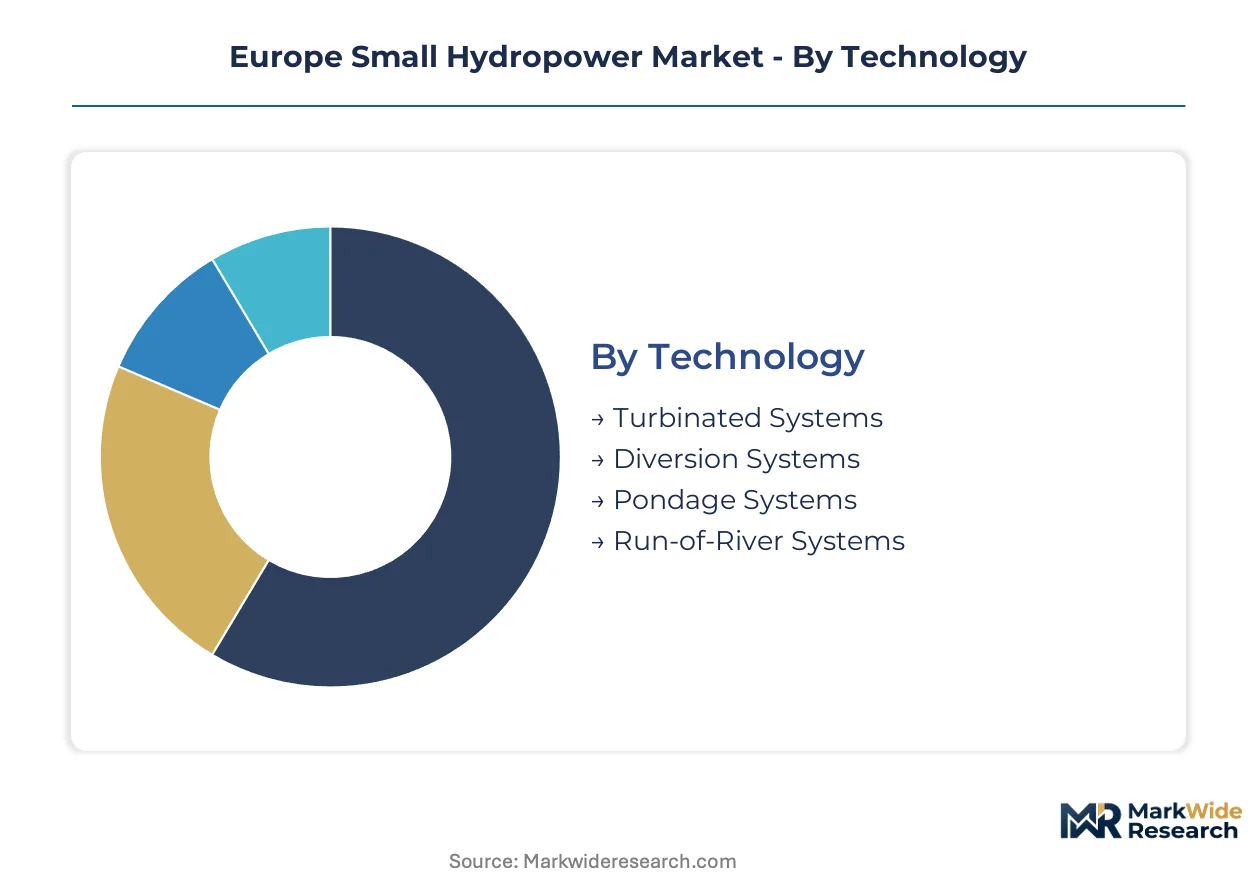
Segmentation reveals how capital deployment, regulatory exposure, and operational complexity vary across technology choices and customer profiles. Alpine utilities prioritize different configurations than industrial off-takers, reshaping vendor go-to-market strategies.
Technology:
Capital intensity diverges sharply across these four approaches, with civil works requirements driving the largest upfront differentials.
- Run-of-River Systems:Channel diverted river flow through penstocks without reservoir impoundment, minimizing civil infrastructure. Norwegian and Austrian municipal utilities concentrate procurement here under EU Green Deal fast-track permitting for low-environmental-impact designs.
- Turbinated Systems:Encompass reaction and impulse turbine configurations optimized for specific head and flow conditions. Italian alpine provinces favor Francis turbine retrofits where existing civil structures limit modernization options.
- Diversion Systems:Partial flow abstraction through weirs and canals serving remote agricultural communities. Lower capital barriers attract private developers in Spain's Pyrenean valleys.
- Pondage Systems:Small reservoir storage enabling limited dispatchability. Regulatory complexity under the Water Framework Directive restricts new permits in ecologically sensitive catchments.
Most installed capacity flows through Run-of-River Systems. Expansion is steepest in Turbinated Systems as refurbishment cycles accelerate.
End User:
Customer type determines contract structure, with municipal procurement favoring long-term service agreements over equipment-only transactions.
- Municipal Utilities:Provincial and city-owned operators across Austria, Italy, and Norway bundle small hydro with grid-balancing service contracts. Climate action mandates drive direct renewable procurement outside national tariff schemes.
- Industrial Users:Pulp, paper, and aluminum producers in Norway and Sweden seek captive baseload supply. Power purchase agreements typically span 15-20 years with take-or-pay structures.
- Private Developers:Independent power producers targeting feed-in tariff regimes in France and Switzerland.
- Agricultural Users:Irrigation districts and cooperatives installing sub-1 MW units for self-consumption and surplus sales to distribution networks.
Municipal Utilities command the largest project pipelines. Private Developers are gaining share fastest as subsidy frameworks shift toward competitive auctions.
Installation Type:
Project archetype shapes margin structure, with retrofits commanding premium pricing where civil works avoidance accelerates payback periods.
- Retrofit Projects:Electromechanical replacement within existing dam and penstock infrastructure. Austrian provincial utilities prioritize Francis turbine upgrades without reservoir reconstruction.
- Onshore Installations:Greenfield run-of-river construction in mountainous terrain. Fiber-reinforced polymer penstock materials are compressing civil works costs by half in Alpine applications.
- Hybrid Systems:Small hydro paired with battery storage or solar photovoltaic for enhanced dispatchability.
- Standalone Units:Isolated micro-grids serving remote communities in Norway's fjord regions.
Retrofit Projects absorb the majority of maintenance and upgrade expenditure. Onshore Installations are climbing the fastest as new permitting fast-tracks unlock greenfield development.
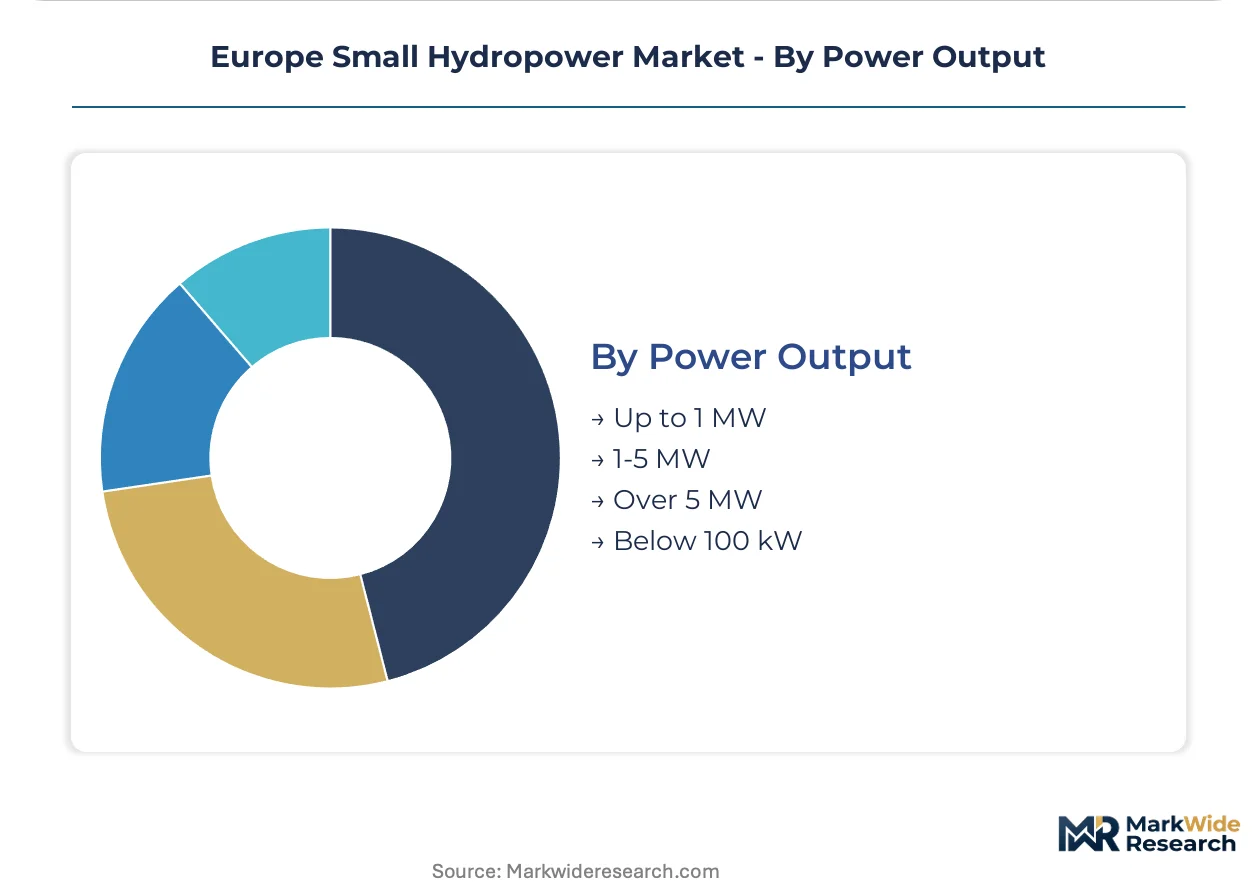
Power Output:
Scale tier determines grid connection protocol, with sub-1 MW installations benefiting from simplified distribution network access rules.
- 1-5 MW:Mid-scale installations optimizing turbine efficiency through variable-speed generator technology. Norwegian municipal utilities retrofit existing penstocks with doubly-fed induction generators to capture partial-load gains.
- Up to 1 MW:Micro-hydro configurations serving single industrial sites or agricultural cooperatives. Standardized equipment packages reduce engineering costs and accelerate deployment timelines.
- Over 5 MW:Approaching the 10 MW small hydro threshold with more complex environmental permitting under national Water Framework Directive implementations.
- Below 100 kW:Pico-hydro units for isolated rural electrification, increasingly displaced by solar-plus-storage alternatives.
The 1-5 MW band contains the greatest installed base. Up to 1 MW installations are expanding most quickly as modular procurement frameworks proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norway's municipal utilities deploy more run-of-river capacity per capita than Italian provincial operators, yet both markets accelerate refurbishment cycles under EU Green Deal deadlines. Alpine topography and grid decentralization policies converge across Austria, Italy, and Norway, concentrating procurement in mountainous catchments.
Norway
Statkraft and municipal utilities expand run-of-river portfolios for Nordic grid-balancing services. The Norwegian Water Resources and Energy Directorate streamlines sub-10 MW permitting under EU Green Deal transpositions. Hardangerfjord and Sognefjord regions host dense clusters of 1-5 MW retrofits with variable-speed generator upgrades.
Italy
Alpine provincial utilities in Lombardy and Trentino-Alto Adige prioritize Francis turbine electromechanical replacement. National transpositions of the revised Renewable Energy Directive harmonize environmental flow assessments across Po and Adige river basins. Aosta Valley engineering clusters specialize in fish-friendly turbine retrofits meeting Water Framework Directive standards.
Austria
Tyrol and Salzburg municipal utilities bundle small hydro assets with frequency regulation contracts. The country's EMAS framework implementation tightens ecological monitoring for pondage system permits. Vorarlberg's provincial energy cooperatives consolidate procurement through multi-installation framework agreements.
France
EDF and regional operators target Pyrenean and Alpine catchments for diversion system deployments. The national renewable energy regulator accelerates simplified grid connection protocols for sub-1 MW agricultural installations. Auvergne-Rhône-Alpes clusters focus on hybrid hydro-solar configurations for enhanced dispatchability.
Switzerland
Canton-owned utilities retrofit aging penstocks with fiber-reinforced polymer piping to compress civil works costs. Swiss Federal Office for the Environment enforces stringent ecological flow requirements under revised water protection ordinances. Graubünden and Valais engineering networks specialize in high-head Pelton modernizations.
Europe Small Hydropower Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-service OEMs dominating municipal utility procurement while component fabricators serve agricultural and industrial niches. The vendor base concentrates among German, Austrian, and Norwegian engineering groups with deep Alpine installation experience. Three archetypes define competitive positioning: turbine refurbishment specialists capturing lifecycle service contracts, digital platform providers enabling remote asset management, and integrated utilities bundelling generation with grid services. Geographic expansion through framework agreements and technology licensing for variable-speed generator retrofits represent the dominant competitive moves.
Among German-headquartered engineering groups, Voith GmbH & Co. KGaA and Siemens Energy AG exemplify divergent strategic archetypes. Voith occupies a position as a refurbishment specialist leveraging turbine modernization expertise for recurring revenue streams. Siemens Energy represents the digital platform vector through hydropower monitoring capabilities. Norwegian state-owned Statkraft anchors the integrated utility model, bundling small hydro assets with Nordic balancing services. These three players illustrate how vendor economics shift from equipment sales toward multi-decade operational partnerships.
| Leading Market Players |
|---|
| GE Renewable Energy |
| Iberdrola SA |
| Voith GmbH & Co. KGaA |
| Kolektor Group |
| Gilbert Gilkes & Gordon Ltd. |
| Siemens Energy AG |
| Electricite de France SA |
| Statkraft |
| Andritz AG |
| Others |
Supply & Pricing Matrix
EU Green Deal environmental flow requirements gate both qualified turbine suppliers and premium-tier pricing access for municipal utilities seeking fast-track permitting compliance. Alpine project developers face bifurcated procurement economics where fish-friendly electromechanical packages command substantial premiums over standard configurations, compressing margins for vendors unable to demonstrate ecological certification.
Pricing Analysis
Capacity additions in Norway are reshaping price floors for variable-speed generator retrofits as Statkraft's framework agreements compress competitor margins. Project-based contracting dominates, with price differentiation resting on CE marking tier and after-sales service bundling. Cost compression in sub-1 MW standardized equipment is intensifying because solar-plus-storage alternatives capture rural electrification budgets. Agricultural cooperatives exhibit highest price sensitivity; municipal utilities absorbing lifecycle service premiums show least.
Supply Chain Analysis
Single-source vulnerability sits with German and Austrian precision turbine casting foundries supplying Francis and Pelton runner components. The supply chain draws from Norway, Italy, and Switzerland for penstock civil works, with fiber-reinforced polymer piping emerging as a substitute input. Steel and copper price volatility represents the dominant structural risk. Distribution runs through municipal utility framework agreements and EPC contractor consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Small Hydropower Market functions as a geographic-arbitrage play where Austrian permitting fast-tracks under EMAS frameworks reduce development timelines versus Swiss ecological review processes, lowering effective cost of capital for comparable Alpine catchment projects.
For Market Incumbents: Deepen backward integration into precision casting capabilities to offset steel input volatility threatening turbine housing margins. Lock municipal utility relationships through digital twin service contracts that transfer operational risk to OEM balance sheets, defending against emerging solar-plus-storage substitution in sub-1 MW rural electrification segments. For New Entrants and Emerging Players: Launch via agricultural cooperative consortia in France's Auvergne-Rhône-Alpes region where simplified grid connection protocols for sub-1 MW installations reduce regulatory barriers. Target hybrid hydro-solar configurations as the most penetrable white-space, leveraging standardized equipment packages to compress deployment timelines versus greenfield run-of-river construction. For Investors and Strategic Acquirers: Roll-up economics work for regional turbine refurbishment specialists because Alpine asset renewal cycles concentrate electromechanical replacement demand across fragmented provincial utility portfolios. Long-term viability hinges on lifecycle service contract monetization; watch for EU Green Deal subsidy phase-out schedules as the critical inflection signal for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Retrofit Turbine Modernization | Francis and Pelton electromechanical replacement captures premium margins without dam reconstruction in Austrian and Italian Alpine provinces. |
| Digital Twin Service Contracts | IoT-enabled predictive maintenance transfers operational risk from municipal utilities to Voith and Siemens Energy balance sheets. |
| Variable-Speed Generator Retrofit | Doubly-fed induction generator installation in Norwegian penstocks compresses payback periods through partial-load efficiency capture. |
| Fish-Friendly Turbine Certification | Water Framework Directive compliance unlocks fast-track permitting for run-of-river installations across EU member state transpositions. |
| Framework Agreement Consolidation | Multi-installation procurement bundling by Tyrol and Salzburg utilities reduces vendor customer acquisition costs and pricing volatility. |
Research Methodology
Bottom-up municipal utility procurement modeling reconciled against top-down turbine manufacturer order tracking forms the analytical core of this study. Primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators combined with secondary validation from EIA data, IEA hydropower reports, FERC filings, and EU project development databases. Triangulation across these sources ensures segmentation integrity.
Input-output matrices map electromechanical component demand to installed capacity additions across the projection horizon. Segmentation dimensions include technology type, end-user archetype, installation configuration, and power output tier. CAGRs derive from regression analysis of historical deployment patterns against policy trajectory assumptions. Forecast inputs incorporate EU Green Deal transposition timelines and steel price volatility indices.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated solar-plus-storage substitution or Water Framework Directive enforcement tightening. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydropower Systems
Africa Small Hydropower Market
Hydropower Systems
United States Hydropower Market
Hydropower Systems
North America Pumped Hydro Storage Market
Hydropower Systems
Offshore Hydropower Market
Hydropower Systems
Run of River Power Market
Hydropower Systems
Europe Hydro Turbine Market
Hydropower Systems
Hydropower Turbine Market
Hydropower Systems
Whirlpool Turbine Market
Hydropower Systems
Standard Modular Hydropower Market
Hydropower Systems
Hydropower Generation Market
Hydropower Systems
North America Hydropower Market
Hydropower Systems
Tidal Power Market
Hydropower Systems
Europe Hydropower Market
Hydropower Systems
Small Hydropower Market
Hydropower Systems
Asia-Pacific Hydropower Market
Hydropower Systems
South America Hydropower Market