
 Southeast Asia Hydropower Market | 2026-2036
Southeast Asia Hydropower Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Hydropower Market Analytics
Laos is narrowing its hydropower development focus on the Lower Mekong corridor to serve Thai and Vietnamese offtake agreements. Vietnam Electricity (EVN) leverages its integrated grid monopoly to anchor large-scale reservoir projects in Son La and Lai Chau provinces. EGAT sustains its procurement dominance through long-term power purchase agreements with neighboring Lao developers. Sarawak Energy differentiates through Borneo-based pumped storage geology that supports peak-load balancing for Malaysian industrial buyers.
Southeast Asia hydropower encompasses turbine-generator systems converting kinetic water energy into grid-synchronized electricity, typically employing Francis, Kaplan, or Pelton turbines rated between 1 MW and 1,000 MW depending on head and flow conditions. Its primary purpose is dispatchable baseload and peak-shaving supply for electrification of industry and rural households. Run-of-river installations lead capacity additions due to lower resettlement burdens and faster permitting cycles than large reservoirs. Pumped storage represents the fastest-growing technology segment as Thailand and Vietnam integrate variable solar and wind assets requiring diurnal storage. Micro hydropower occupies niche margin pools in remote Indonesian archipelago communities where transmission extension remains uneconomical.
Vietnam's Ministry of Industry and Trade implements Power Development Plan VIII licensing requirements that mandate environmental flow provisions for Mekong tributary projects. Thailand's Energy Regulatory Commission and EGAT jointly enforce grid code compliance standards for cross-border imports from Lao hydropower stations. Indonesia's PLN coordinates with the Ministry of Energy and Mineral Resources on feed-in tariff structures that determine project bankability for private developers. Stakeholders must monitor how evolving transboundary water governance frameworks between Mekong riparian states reshape site accessibility and investment security for new developments.
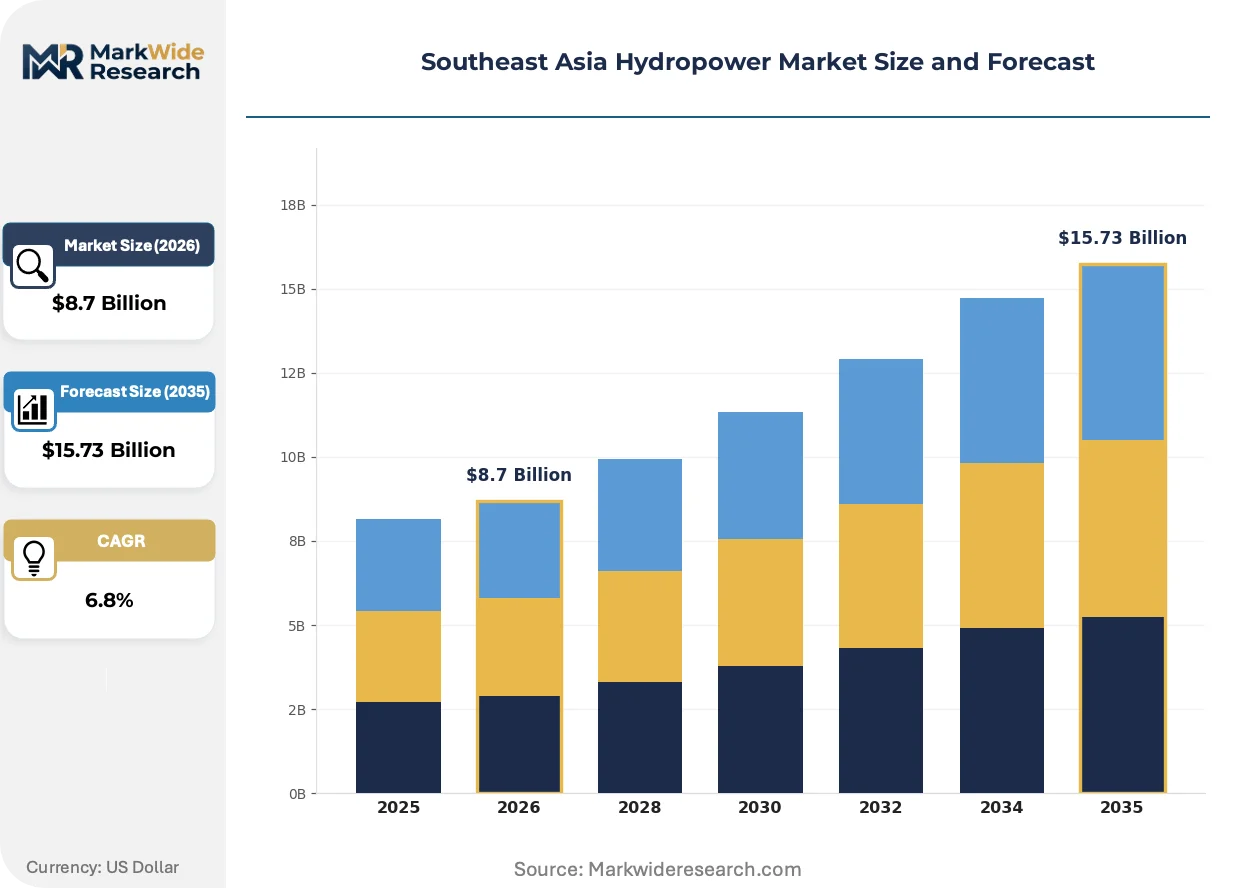
Market Dynamics
Cross-border power purchase agreements between Lao developers and Thai offtakers are restructuring investment flows across the Lower Mekong corridor, concentrating capital in transboundary transmission infrastructure over domestic distribution networks.
Growth Catalysts
- Power Development Plan VIII:Vietnam's Ministry of Industry and Trade licensing mandates accelerate reservoir project approvals in Son La and Lai Chau provinces while embedding environmental flow safeguards.
- Run-of-river technology:Indonesian utilities favor these installations for faster permitting cycles and reduced resettlement burdens compared to large reservoir schemes.
- Pumped storage geology:Sarawak's karst formations enable peak-load balancing capacity that attracts Malaysian industrial buyers seeking grid stability.
Market Restraints
- Transboundary water governance:Evolving Mekong River Commission frameworks between riparian states create site accessibility uncertainty and extended due diligence timelines.
- Silica sand supply:Concrete dam construction faces input cost volatility from concentrated Vietnamese and Cambodian aggregate suppliers.
- Grid code compliance:Thailand's Energy Regulatory Commission enforces technical standards that disqualify older Lao turbine designs from new offtake contracts.
Strategic Opportunities
- Micro hydropower:Remote Indonesian archipelago communities present white space where transmission extension remains uneconomical and diesel substitution creates tariff arbitrage.
- Solar-wind convergence:Diurnal storage pairing with Vietnam's accelerating renewable buildout positions pumped storage as critical balancing infrastructure.
- Feed-in tariff restructuring:Indonesia's Ministry of Energy and Mineral Resources revisions to PLN procurement terms improve private developer bankability for run-of-river schemes.
Industry Challenges
- Turbine engineering specialization:Francis and Kaplan unit refurbishment requires scarce high-head hydromechanical expertise concentrated in European and Chinese supplier networks.
- Resettlement negotiation:Large reservoir projects face protracted community consultation timelines that compress construction windows and escalate carrying costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Hydropower Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Run-of-River, Pumped Storage, Reservoir, Micro Hydropower End User: Utilities, Industrial Sector, Agriculture, Residential Customers Installation Type: Onshore, Offshore, Hybrid Systems, Greenfield Projects Power Capacity: Small Scale, Medium Scale, Large Scale, Others |
| Companies Covered | Vietnam Electricity (EVN), Electricity Generating Authority of Thailand (EGAT), PT Perusahaan Listrik Negara (PLN), Vietnam Electricity Construction JSC, Tenaga Nasional Berhad, Andritz AG, Sarawak Energy, ACEN Corp, B.Grimm Power PCL, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Hydropower Market Evolving Landscape
Digitalization of hydropower asset management is compressing maintenance cycles and enabling predictive interventions that reshape operator economics across the Mekong basin and Indonesian archipelago.
Variable-speed pumped storage technology is hybridizing fixed-speed turbine-generator sets with power electronics that enable rapid frequency response. Thai grid operators deploy these units to balance evening ramp-downs from solar arrays. The technology is hybridizing traditional hydropower's role from baseload provider to grid stabilization service.
Vietnam's environmental flow mandates under Power Development Plan VIII require real-time discharge monitoring systems at all new Mekong tributary installations. Developers must integrate automated gauging stations that transmit data to provincial water resource departments. Run-of-river projects in the Central Highlands face the steepest compliance cost escalation.
Industrial buyers in Thailand and Malaysia now unbundle long-term power purchase agreements into separate energy and capacity contracts. This fragmentation exposes Lao developers to merchant price risk while enabling Thai manufacturers to optimize load profiles against spot market fluctuations. EGAT's procurement team has pioneered this contract restructuring.
Southeast Asia Hydropower Market Segmentation
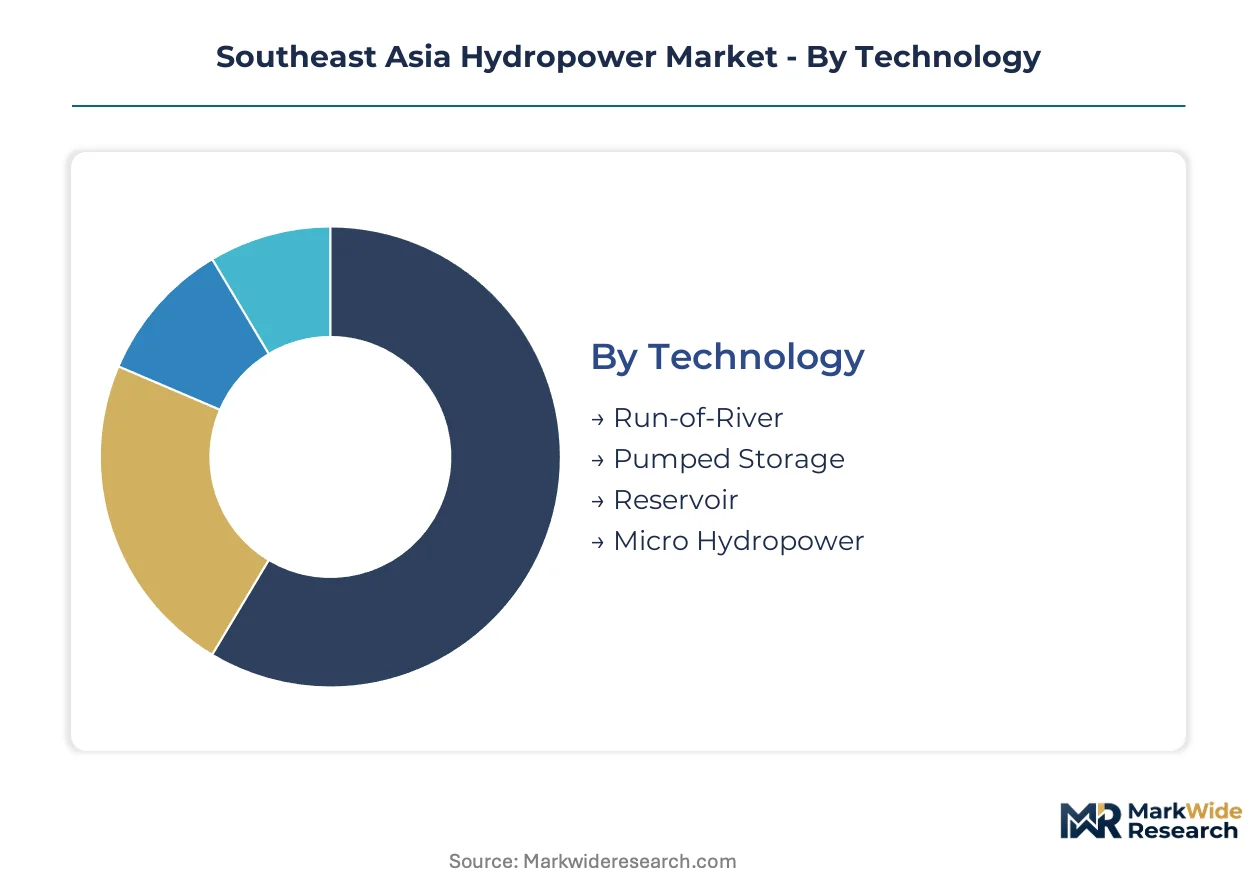
Segmentation reveals how technology choices, customer archetypes, and project scale reshape procurement economics across the Mekong basin and Indonesian archipelago. Distinct operational requirements for run-of-river versus pumped storage installations create divergent vendor qualification criteria and maintenance contract structures.
Technology:
After-sales service intensity varies sharply across technology types, with pumped storage requiring specialized turbine-generator refurbishment networks that concentrate expertise in European and Chinese supplier bases.
- Run-of-River:These installations capture kinetic energy from flowing water without large impoundment structures, utilizing compact Francis or Kaplan turbines suited to moderate head conditions. Indonesian utilities favor these schemes in Sumatra and Sulawesi where resettlement burdens delay reservoir permitting. Demand concentrates among PLN procurement teams seeking faster licensing cycles for rural electrification targets.
- Pumped Storage:Reversible turbine-generator sets shift water between upper and lower reservoirs to provide diurnal storage and frequency regulation. Sarawak's karst geology enables cost-effective cavern construction that attracts Malaysian industrial buyers requiring peak-load balancing. The technology hybridizes traditional hydropower's role from baseload provision to grid stabilization service as Thailand and Vietnam integrate variable solar assets.
- Reservoir:Large-scale impoundment projects store seasonal water flows behind concrete or embankment dams, typically deploying high-head Francis turbines rated above 100 MW.
- Micro Hydropower:Sub-1 MW installations serve remote Indonesian archipelago communities where transmission extension remains uneconomical and diesel substitution creates tariff arbitrage opportunities.
Reservoir installations hold the largest share; momentum sits with pumped storage as grid operators prioritize balancing infrastructure.
End User:
Customer type determines contract duration, tariff structure, and environmental compliance burden across the region's divergent regulatory environments.
- Utilities:State-owned grid operators including Vietnam Electricity, EGAT, and PLN anchor procurement through long-term power purchase agreements that structure project finance. These buyers prioritize dispatchable capacity and cross-border transmission compatibility for Lao import contracts.
- Industrial Sector:Energy-intensive manufacturers in Thailand and Malaysia unbundle contracts into separate energy and capacity components, exposing developers to merchant price risk while optimizing load profiles against spot fluctuations.
- Agriculture:Irrigation districts and agro-processing cooperatives purchase smaller blocks of firm power for pumping and milling operations, typically through distribution utility intermediaries.
- Residential Customers:Rural electrification programs and urban grid extension projects drive demand for micro and small-scale installations in Indonesian outer islands and Vietnamese Central Highlands provinces.
Utilities dominate procurement volume; industrial buyers are expanding most quickly as contract unbundling spreads.
Installation Type:
Project delivery model shapes capital structure, risk allocation, and equipment sourcing strategy for developers navigating transboundary water governance.
- Onshore:Conventional land-based civil works including dam structures, powerhouses, and switchyards constitute the overwhelming majority of installed capacity across the Mekong basin.
- Offshore:Floating solar-hydropower hybrid platforms and tidal barrage concepts remain experimental in Southeast Asian waters, constrained by typhoon exposure and limited site surveys.
- Hybrid Systems:Co-located solar PV and hydropower installations share transmission infrastructure and dispatch coordination, particularly in Vietnam's reservoir provinces where daytime solar generation complements evening hydro ramping.
- Greenfield Projects:New developments on previously unexploited sites face extended due diligence timelines under evolving Mekong River Commission frameworks and national environmental flow mandates.
Onshore installations retain the largest share; hybrid systems are climbing the fastest as Vietnam integrates variable renewable buildout.
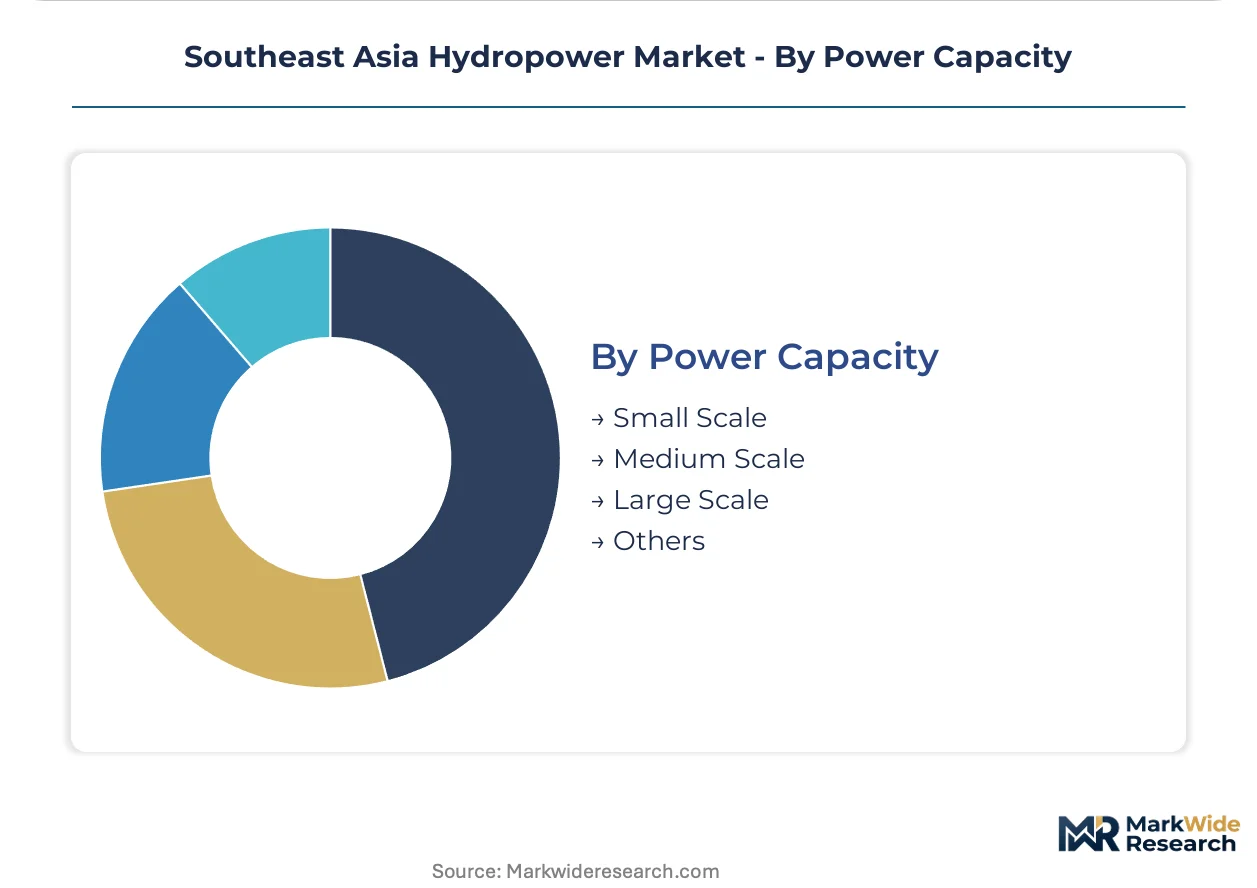
Power Capacity:
Scale tier determines equipment supplier qualification, grid connection voltage level, and regulatory oversight intensity from national energy ministries.
- Small Scale:Sub-10 MW installations serve isolated grids and industrial captive demand, frequently employing standardized turbine packages that reduce engineering costs.
- Medium Scale:10-100 MW projects balance economies of scale against resettlement complexity, dominating private developer portfolios in Laos and Cambodia.
- Large Scale:Reservoir projects exceeding 100 MW require multi-year construction programs and multilateral financing, with Son La and Lai Chau provinces in Vietnam anchoring regional capacity concentration.
- Others:Experimental and demonstration installations including variable-speed pumped storage pilots and modular turbine designs occupy niche procurement channels.
Large scale projects hold the largest share; small scale installations are gaining share fastest as remote electrification programs accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam's Ministry of Industry and Trade anchors regional policy through Power Development Plan VIII licensing mandates that cascade across the Lower Mekong corridor. National energy ministries in Thailand, Indonesia, and Laos coordinate cross-border procurement frameworks that reshape investment geography.
Vietnam
Reservoir development in Son La and Lai Chau provinces drives procurement volume for Vietnam Electricity. Power Development Plan VIII mandates real-time environmental flow monitoring at all Mekong tributary installations. The Central Highlands cluster faces steepest compliance cost escalation as developers integrate automated gauging stations.
Thailand
EGAT sustains procurement dominance through long-term power purchase agreements with Lao developers. The Energy Regulatory Commission enforces grid code compliance standards that disqualify older turbine designs from new cross-border contracts. Industrial buyers in Bangkok and Eastern Economic Corridor unbundle contracts into separate energy and capacity components.
Indonesia
PLN coordinates with the Ministry of Energy and Mineral Resources on feed-in tariff structures determining private developer bankability. Run-of-river installations lead capacity additions in Sumatra and Sulawesi where resettlement burdens delay reservoir permitting. Remote archipelago communities in Maluku and Papua present micro hydropower deployment opportunities.
Laos
Cross-border electricity export infrastructure concentrates development in the Lower Mekong corridor serving Thai and Vietnamese offtake agreements. Medium-scale projects between 10-100 MW dominate private developer portfolios. The Xayaburi and Don Sahong corridors anchor transboundary transmission investment flows.
Malaysia
Sarawak Energy leverages Borneo-based pumped storage geology to attract industrial buyers requiring peak-load balancing. Karst formations enable cost-effective cavern construction supporting grid stabilization services. Peninsular Malaysia integrates hybrid solar-hydropower coordination at reservoir sites.
Southeast Asia Hydropower Market Competitive Landscape
Capability concentration sits with European and Chinese turbine-generator specialists; scale advantage sits with state-owned utilities commanding integrated grid monopolies. The market structures around three tiers: national champions with transmission dominance, international equipment suppliers with refurbishment networks, and private developers securing cross-border offtake contracts. Strategic moves center on portfolio diversification into pumped storage and backward integration into civil construction capabilities.
Within the state utility tier, Vietnam Electricity (EVN) and Electricity Generating Authority of Thailand (EGAT) exemplify procurement dominance through long-term power purchase agreement structures. Among equipment specialists, Andritz AG occupies a position representing European turbine-engineering expertise. These three entities anchor competitive dynamics: EVN and EGAT through grid control and import contracting, Andritz through specialized hydromechanical refurbishment capability.
| Leading Market Players |
|---|
| Vietnam Electricity (EVN) |
| Electricity Generating Authority of Thailand (EGAT) |
| PT Perusahaan Listrik Negara (PLN) |
| Vietnam Electricity Construction JSC |
| Tenaga Nasional Berhad |
| Andritz AG |
| Sarawak Energy |
| ACEN Corp |
| B.Grimm Power PCL |
| Others |
Value Network & Pricing Analysis
Silica sand supply volatility from concentrated Vietnamese and Cambodian aggregate producers compresses margin spreads across reservoir project tiers while forcing developers toward run-of-river configurations with lower concrete intensity. This input cost risk stratifies pricing between premium reservoir schemes with long-term offtake security and economy-tier run-of-river installations competing on speed-to-market.
Pricing Analysis
Cross-border power purchase agreements between Lao developers and Thai offtakers exhibit the widest price spreads in the regional market. Contract unbundling into separate energy and capacity components exposes developers to merchant price risk while enabling industrial buyers to optimize against spot fluctuations. Cost compression in economy-tier run-of-river projects intensifies as Indonesian PLN procurement teams prioritize faster permitting over performance guarantees. State-owned utilities demonstrate the lowest price sensitivity due to integrated grid monopolies and sovereign-backed financing.
Supply Chain Analysis
Tariff exposure between European turbine-engineering specialists and Southeast Asian EPC contractors dominates supply chain risk architecture for high-head Francis and Kaplan unit procurement. Manufacturing concentration in China, Germany, and Austria feeds into hydromechanical refurbishment networks that service the Mekong basin. Steel forgings, generator windings, and control systems draw from these concentrated supplier bases. Single-source vulnerability for specialized turbine castings shapes developer sourcing strategies. Distribution runs through state utility procurement departments that anchor long-term equipment supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Southeast Asia hydropower market sits at a platform-economics inflection where cross-border transmission infrastructure and standardized grid codes are reshaping competitive access. Interoperability between Lao generation assets and Thai-Vietnamese offtake systems creates winner-take-most dynamics for developers securing early corridor positioning.
For Market Incumbents: Entrench procurement dominance through backward integration into civil construction capabilities and exclusive turbine refurbishment partnerships with European specialists. Vietnam Electricity and EGAT should lock in long-term power purchase agreement structures before feed-in tariff restructuring spreads across Indonesia. Priority lever: captive control over transboundary transmission rights.
For New Entrants and Emerging Players: Establish a beachhead in Indonesian micro hydropower deployments across Maluku and Papua where transmission extension economics favor sub-1 MW installations. Remote archipelago communities present the most penetrable segment due to diesel substitution arbitrage and minimal incumbent presence. Go-to-market angle: standardized turbine packages with integrated mini-grid control systems.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors developers with secured cross-border offtake contracts and environmental flow compliance infrastructure. Long-term viability hinges on portfolio diversification into pumped storage balancing assets. Signal to watch: Mekong River Commission framework finalization as inflection indicator for site accessibility risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Pumped Storage Capacity Buildout | Sarawak Energy leverages karst geology to attract Malaysian industrial buyers requiring peak-load balancing. |
| Cross-Border Power Purchase Agreement | Lao developers anchor financing through EGAT and Vietnam Electricity long-term offtake structures. |
| Run-of-River Technology Licensing | Indonesian IPPs accelerate permitting cycles by adopting compact Francis turbine configurations. |
| Backward Integration into Civil Construction | Developers control silica sand input costs and resettlement timeline risks through captive EPC capabilities. |
| Environmental Flow Certification Program | Real-time discharge monitoring systems satisfy Vietnam Power Development Plan VIII mandates. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators across Vietnam, Thailand, Indonesia, and Laos. Secondary validation drew from Mekong River Commission technical reports, national energy ministry licensing databases, FERC-style regulatory filings, and project finance disclosure records. Bottom-up installation capacity tallies were triangulated against top-down macroeconomic demand projections.
Calibration against historical capacity commissioning timelines and tariff restructuring announcements anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include technology type, project scale tier, end-user archetype, and regulatory framework cluster. CAGRs were derived from slope analysis of capacity addition trajectories and investment flow patterns. Industry-specific forecast inputs incorporated environmental flow compliance cost curves and cross-border transmission infrastructure buildout schedules.
Sensitivities concentrate around Mekong River Commission governance evolution, silica sand supply disruption events, and feed-in tariff restructuring timing in Indonesia. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydropower Systems
United States Hydro Turbine Market
Hydropower Systems
Europe Hydro Turbine Market
Hydropower Systems
Hydro Turbines Market
Hydropower Systems
Run of River Power Market
Hydropower Systems
Pumped Hydro Storage Market
Hydropower Systems
Tidal Power Market
Hydropower Systems
North America Hydropower Market
Hydropower Systems
Whirlpool Turbine Market
Hydropower Systems
North America Pumped Hydro Storage Market
Hydropower Systems
Asia-Pacific Hydropower Market
Hydropower Systems
Hydroelectricity Market
Hydropower Systems
United States Hydropower Market
Hydropower Systems
Asia-Pacific Pumped Hydro Storage Market
Hydropower Systems
France Tidal Power Market
Hydropower Systems
South America Hydropower Market
Hydropower Systems
Offshore Hydropower Market