
 LAMEA Wave and Tidal Energy Market | 2026-2036
LAMEA Wave and Tidal Energy Market Size, Share, and Industry Trends Forecast 2026-2036
LAMEA Wave and Tidal Energy Market Analytics
Offshore utilities is decoupling from onshore independent power producers as the dominant procurement channel in the LAMEA wave and tidal energy landscape. Orbital Marine Power leverages its horizontal axis turbine expertise to anchor project pipelines along Scotland-to-export corridors serving Latin American markets. SIMEC Atlantis Energy sustains technology leadership through sustained R&D intensity in tidal stream generator architectures. Carnegie Clean Energy specializes in buoy system integration for distributed coastal grids across the LAMEA zone.
Wave and tidal energy systems harness kinetic energy from ocean currents and surface oscillations through submerged turbines, pressure differential chambers, or floating absorber arrays, typically operating at 20-50 meter depths with rated capacities from 100 kW to 2 MW per unit, converting mechanical rotation into grid-synchronous electricity for baseload or peaking power supply. Tidal stream generators capture the most mature margin pool given established operational track records at MeyGen and comparable sites, while point absorbers represent the fastest-growing product category as modular deployment reduces capex risk for utilities. Horizontal axis turbines dominate current installed capacity, though hybrid systems are gaining traction where wave and tidal resources co-locate.
Brazil's ANEEL, South Africa's NERSA, and Mexico's CRE collectively shape market access through renewable auction design, grid connection standards, and environmental licensing timelines that determine project viability across the LAMEA region. The EU Green Deal's extraterritorial supply chain requirements for equipment imports, coupled with ISO 14001 environmental management certifications, filter participant eligibility in tender processes. Stakeholders must monitor how regulatory harmonization between national energy regulators and maritime authorities resolves overlapping jurisdictional claims in exclusive economic zones.
Market Dynamics
Grid decarbonization mandates across Latin America and South Africa are forcing utilities to procure baseload renewable capacity, with tidal stream generators emerging as the preferred technology for coastal load centers requiring predictable output profiles.
Growth Catalysts
- ANEEL Renewable Auctions:Brazil's regulator structures long-term power purchase agreements that de-risk capital deployment for tidal projects along the southern coastline.
- Agulhas Current Density:South Africa's western seaboard hosts current velocities exceeding three meters per second, enabling capacity factors above forty percent for horizontal axis turbines.
- Hybrid System Architectures:Convergent wave-tidal platforms reduce levelized cost by sharing mooring infrastructure and grid connection assets at co-located resource sites.
Market Restraints
- Subsea Cable Concentration:Specialized dynamic cable suppliers cluster in European manufacturing hubs, exposing LAMEA projects to currency volatility and extended lead times.
- Foundation Material Costs:Gravity-base and piled foundations require high-grade marine concrete and corrosion-resistant steel alloys subject to commodity price swings.
- Grid Interconnection Queues:Mexico's CRE licensing timelines for offshore substations extend project development cycles by eighteen to thirty-six months beyond equipment fabrication.
Strategic Opportunities
- Argentina's Patagonian Coast:Untapped wave energy potential along Chubut and Santa Cruz provinces offers first-mover advantages before regulatory frameworks mature.
- Island Microgrids:Caribbean utilities seek distributed buoy systems to displace diesel generation at isolated coastal communities.
- Green Hydrogen Co-location:Electrolyzer integration with tidal baseload enables ammonia export projects at Chilean and Brazilian deepwater ports.
Industry Challenges
- Marine Operations Expertise:Specialized vessel crews for turbine installation and maintenance remain concentrated in North Sea markets, requiring training programs in LAMEA coastal cities.
- Type Certification Delays:IEC 62600-2 conformity assessment timelines for novel tidal stream architectures extend commercialization schedules by two to four years.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LAMEA Wave and Tidal Energy Market |
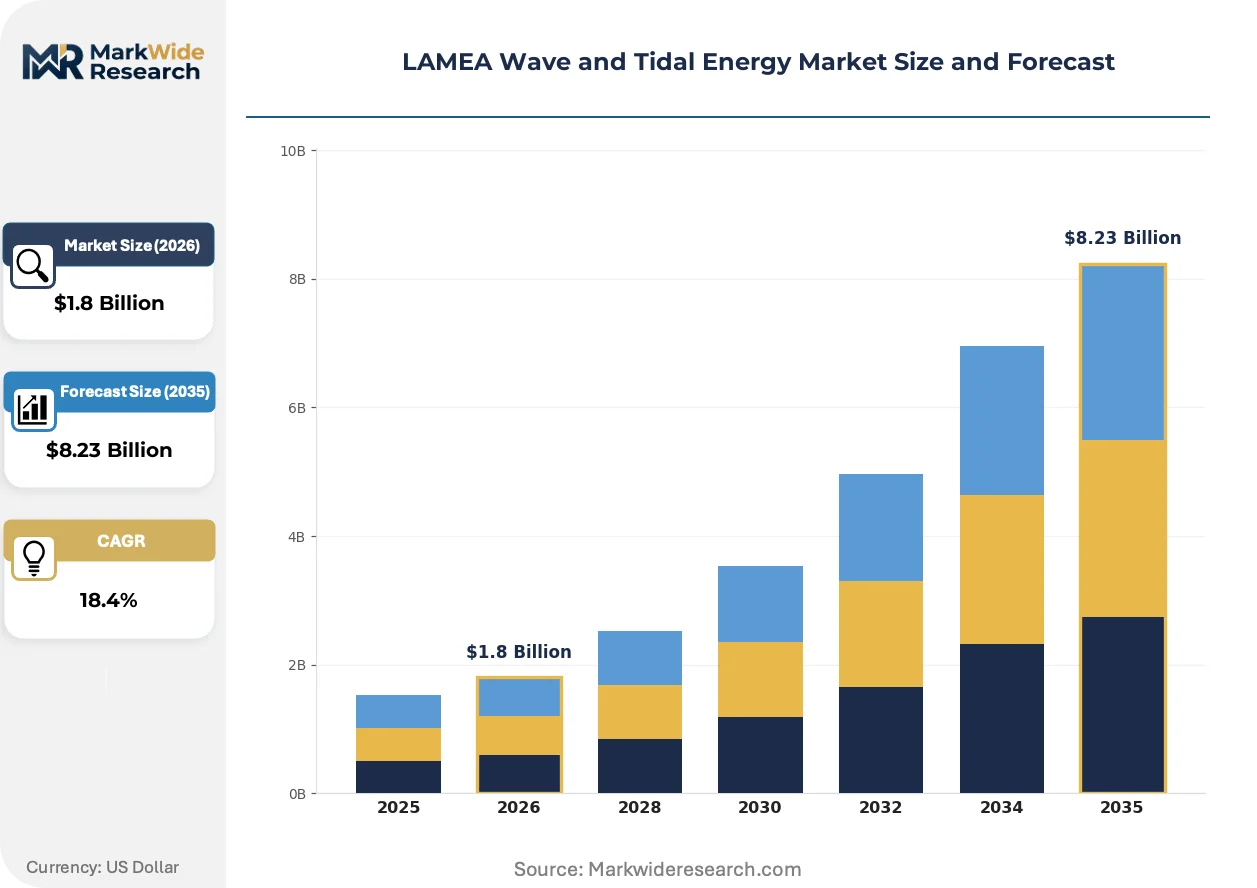
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.23 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tidal Stream Generators, Oscillating Water Columns, Point Absorbers, Tidal Barrages End User: Utilities, Independent Power Producers, Government Agencies, Research Institutions Technology: Horizontal Axis Turbines, Vertical Axis Turbines, Buoy Systems, Hybrid Systems Installation: Onshore, Offshore, Floating Platforms, Integrated Systems |
| Companies Covered | Orbital Marine Power, SIMEC Atlantis Energy, Carnegie Clean Energy, BioPower Systems, AW Energy, CorPower Ocean, Eco Wave Power, Ocean Power Technologies, ORPC, Others |
| Regions Covered | LAMEA: Brazil, Mexico, Argentina, Saudi Arabia, UAE, South Africa, Nigeria, Egypt, Rest of LAMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LAMEA Wave and Tidal Energy Market Evolving Landscape
Tidal stream technology is modularizing rapidly as manufacturers pursue factory fabrication and rapid offshore assembly, while regulatory frameworks and utility procurement models adapt to accommodate standardized unit deployment.
Horizontal axis turbine platforms are modularizing through segmented nacelle designs and bolted-blade assemblies that enable road transport to remote port facilities. Brazilian developers are adopting these configurations to bypass heavy-lift vessel bottlenecks at southern Atlantic ports. This structural shift is compressing installation windows from seasonal campaigns to continuous deployment schedules.
South Africa's NERSA has embedded local content thresholds into renewable procurement rounds, requiring tidal developers to source thirty percent of capital expenditure from domestic manufacturing and services. This industrial policy is redirecting supply chain planning toward Port Elizabeth fabrication yards. Horizontal axis turbine suppliers are responding by licensing blade molding techniques to composite manufacturers in the Eastern Cape.
Utility offtake agreements are migrating from single-project structures to portfolio procurement covering multiple tidal sites, enabling developers to diversify resource risk across Brazil's southern coastline and South Africa's Agulhas corridor. Aggregated procurement is displacing bilateral negotiations as the dominant contracting mode. This concentration is most visible in ANEEL auction participation, where consortia now bid five to seven site clusters rather than individual installations.
LAMEA Wave and Tidal Energy Market Segmentation
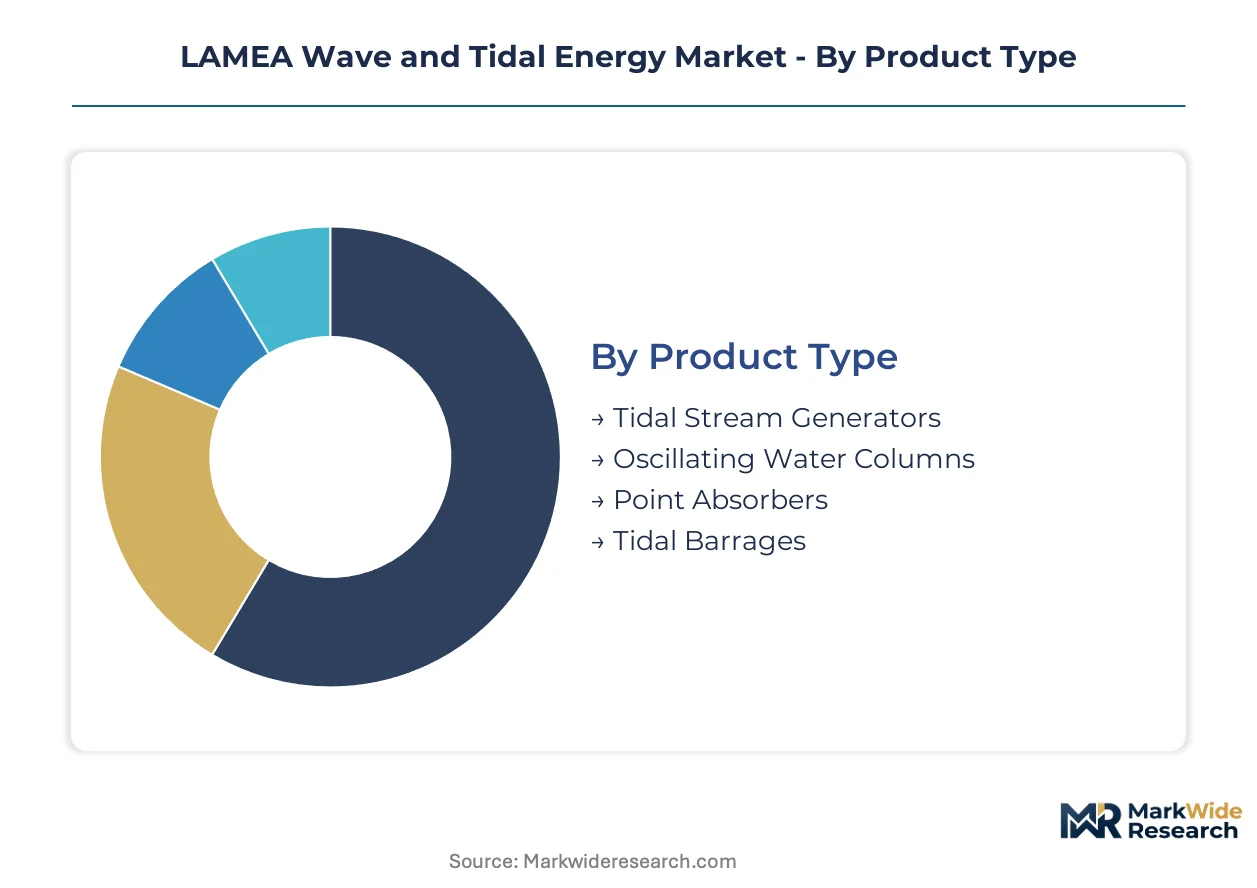
Segmentation reveals how capital deployment and operational risk distribute across the LAMEA wave and tidal energy value chain. Technology choices, installation depth, and offtaker creditworthiness determine project bankability and procurement timelines.
Product Type:
Capital intensity varies sharply across marine energy architectures, with foundation and subsea cable requirements driving upfront expenditure differentials.
- Tidal Stream Generators:Horizontal axis turbines mounted on seabed frames convert kinetic current energy at velocities above two meters per second. Brazilian utilities concentrate procurement along the Santa Catarina coastline where ANEEL auction structures de-risk twenty-year revenue streams.
- Point Absorbers:Floating buoy systems capture surface oscillation energy through heave-responsive hydraulic pistons. Caribbean island microgrids drive demand as diesel displacement economics improve at isolated coastal communities.
- Oscillating Water Columns:Shore-mounted chambers compress air through wave-driven water pistons to drive bidirectional turbines. Retrofit applications at existing breakwaters reduce civil engineering costs.
- Tidal Barrages:Coastal embankment structures impound water for hydroelectric generation during tidal cycles. High concrete volumes and environmental licensing complexity limit newbuild activity.
Tidal stream generators absorb the bulk of installed capacity; point absorbers are expanding most quickly.
End User:
Procurement scale and contract duration separate institutional buyers, with credit ratings determining access to non-recourse project finance.
- Utilities:State-backed power distributors anchor long-term offtake through regulated renewable procurement mechanisms. South Africa's Eskom and Brazil's distribution concessionaires dominate tender participation.
- Independent Power Producers:Merchant developers assume wholesale price exposure in exchange for construction flexibility. Chilean and Mexican IPPs pursue bilateral corporate power purchase agreements.
- Government Agencies:Direct state investment supports pre-commercial demonstration arrays and research infrastructure. Argentina's Ministry of Energy funds Patagonian pilot sites.
- Research Institutions:Universities and national laboratories validate device performance and environmental impact. University of Cape Town and COPPE/UFRJ operate test berths.
Utilities command the dominant share of committed capacity; independent power producers are gaining share fastest.
Technology:
Technology selection trades rotational efficiency against installation logistics, with water depth and current velocity dictating optimal configurations.
- Horizontal Axis Turbines:Propeller-style rotors on directional yaw mechanisms maximize energy capture in unidirectional flows. Agulhas Current velocities exceeding three meters per second enable capacity factors above forty percent.
- Hybrid Systems:Convergent platforms combine tidal turbines with wave energy absorbers on shared mooring infrastructure. Co-located resource sites in Brazil's southern Atlantic reduce levelized cost through asset sharing.
- Vertical Axis Turbines:Omnidirectional Darrieus or Savonius rotors eliminate yaw mechanism complexity. Bidirectional tidal flows in estuarine applications favor simplified mechanical architectures.
- Buoy Systems:Surface-following floats drive internal power take-off mechanisms through relative motion against submerged reaction plates. Distributed coastal grids favor modular deployment.
Horizontal axis turbines dominate current deployment; hybrid systems show the steepest expansion trajectory.
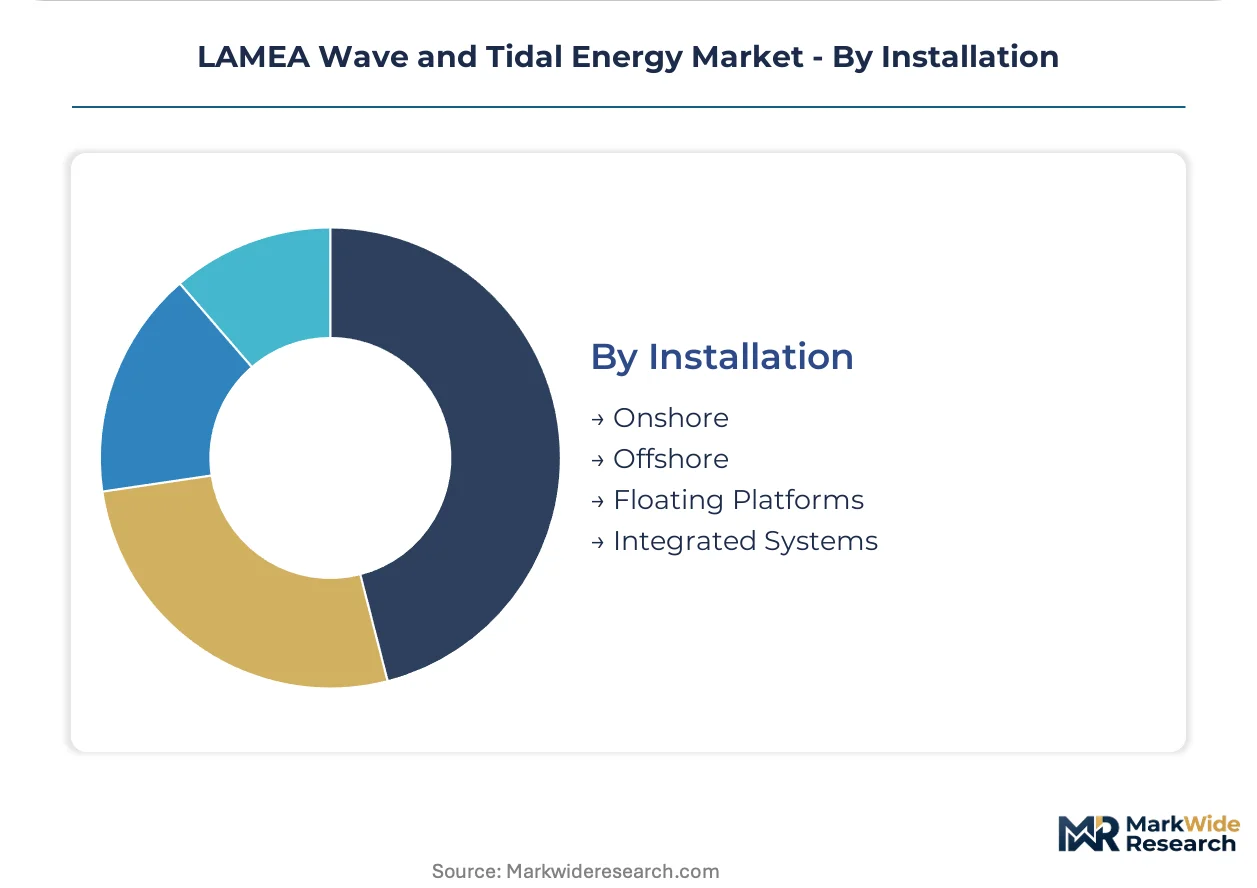
Installation:
Installation mode determines vessel requirements, seasonal weather windows, and grid connection topology.
- Offshore:Seabed-mounted systems in twenty to fifty meter depths access highest resource densities. Dynamic cable runs to offshore substations add fifteen to twenty percent to capital cost.
- Floating Platforms:Tension-leg or semi-submersible moored structures enable deepwater deployment beyond continental shelf limits. Reduced foundation costs offset dynamic cable complexity.
- Onshore:Oscillating water columns and shoreline-mounted systems minimize marine operations. Limited to wave-exposed coastal geologies with suitable bathymetry.
- Integrated Systems:Combined wave-tidal platforms with shared electrical infrastructure reduce unit development cost. Port of Acu and Port Elizabeth fabrication yards support integrated assembly.
Offshore installation accounts for the majority of committed megawatts; floating platforms are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's special economic zones for renewable manufacturing concentrate project development activity across the LAMEA wave and tidal energy corridor. ANEEL auction mechanisms and South Africa's industrial development zones anchor capital deployment patterns.
Brazil
ANEEL renewable auctions structure twenty-year power purchase agreements that de-risk tidal stream investments along Santa Catarina's coastline. The regulator's local content requirements redirect supply chain planning toward southern Atlantic port facilities. Port of Acu fabrication yards support integrated turbine assembly for utility-scale deployment.
South Africa
Agulhas Current velocities exceeding three meters per second enable capacity factors above forty percent for horizontal axis turbines. NERSA procurement rounds embed thirty percent domestic sourcing thresholds into renewable tenders. Port Elizabeth composite manufacturers license blade molding techniques under technology transfer agreements with European suppliers.
Mexico
CRE licensing timelines for offshore substations extend project development cycles by eighteen to thirty-six months beyond equipment fabrication. The regulator's grid interconnection queues create bottlenecks for Pacific coast wave energy arrays. Baja California fabrication clusters specialize in tension-leg platform components for floating installations.
Chile
Deepwater ports at Antofagasta and Valparaíso enable green hydrogen co-location with tidal baseload for ammonia export projects. The national energy commission structures maritime concession frameworks for exclusive economic zone development. Magallanes Region wave energy pilots test buoy system resilience in extreme Southern Ocean conditions.
Argentina
Patagonian coastlines along Chubut and Santa Cruz provinces host untapped wave energy potential ahead of regulatory framework maturation. The Ministry of Energy funds demonstration arrays through direct state investment mechanisms. Mar del Plata research infrastructure validates device performance for subsequent commercial scaling.
LAMEA Wave and Tidal Energy Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with technology licensors and fabrication subcontractors occupying distinct competitive tiers. Horizontal axis turbine developers concentrate project pipelines through Scotland-to-export corridors serving Latin American markets. Two strategic archetypes dominate: integrated technology owners with proprietary generator architectures, and regional deployment specialists with maritime operations expertise. Competitive moves center on technology licensing agreements and local content partnerships with domestic fabrication yards.
Within the integrated technology tier, Orbital Marine Power and SIMEC Atlantis Energy represent horizontal axis turbine expertise anchored to European supply chains. Carnegie Clean Energy exemplifies buoy system specialists targeting distributed coastal grids. These three companies occupy positions across the technology spectrum from seabed-mounted tidal stream generators to surface-following wave absorbers, with each archetype responding to distinct procurement channels—utility auctions versus island microgrid tenders.
| Leading Market Players |
|---|
| Orbital Marine Power |
| SIMEC Atlantis Energy |
| Carnegie Clean Energy |
| BioPower Systems |
| AW Energy |
| CorPower Ocean |
| Eco Wave Power |
| Ocean Power Technologies |
| ORPC |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between IEC 62600-2 type-certified tidal stream generators and pre-certified prototypes manifests in both pricing premiums and supply chain sourcing patterns across LAMEA markets. ANEEL auction eligibility rules tether premium pricing tiers to verified conformity assessments, while uncertified developers face compressed margins and restricted supplier access.
Pricing Analysis
Short lead-time premiums for dynamic subsea cable procurement command fifteen to twenty percent markups over standard delivery schedules at Brazilian southern Atlantic ports. Project-based long-term offtake contracts dominate utility procurement, with price differentiation resting on IEC certification tier and domestic content ratio rather than brand positioning. Pricing pressure stems from gravity-base foundation material cost volatility, with high-grade marine concrete and corrosion-resistant steel alloys subject to commodity swings. State-backed utilities exhibit lowest price sensitivity given sovereign credit backing, while merchant IPPs in Chile and Mexico face acute margin compression from wholesale market exposure.
Supply Chain Analysis
Specialized turbine installation vessel crews concentrate in Scottish and Norwegian maritime hubs, creating workforce bottlenecks that extend project timelines at LAMEA deployment sites. Manufacturing gravity draws from Germany for precision gearbox components, South Korea for composite blade molding, and Brazil's Port of Acu for integrated nacelle assembly. Raw material dependencies center on rare-earth magnets for generator rotors, high-tensile mooring chain alloys, and subsea cable copper conductors. Single-source vulnerability pervades dynamic cable suppliers clustered in European manufacturing zones. Distribution runs through EPC contractors with established maritime operations expertise rather than direct OEM-to-developer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine energy fabrication yard capacity constraints prop pricing power for incumbent turbine suppliers with secured port access across Brazil and South Africa.
For Market Incumbents: Cement technology licensing partnerships with Port Elizabeth and Port of Acu fabrication yards to preempt emerging European-Asian hybrid competitors from securing local content thresholds. Anchor supply chain control through backward integration into composite blade manufacturing, as NERSA and ANEEL procurement rules harden domestic sourcing requirements. Defend against modular point absorber entrants by accelerating horizontal axis turbine certification timelines. For New Entrants and Emerging Players: Island microgrid developers in the Caribbean represent the most penetrable channel partner type for buoy system specialists seeking utility-scale credibility. Target diesel displacement economics at isolated coastal communities where distributed generation bypasses grid interconnection queues. Pursue technology demonstration partnerships with University of Cape Town and COPPE/UFRJ test berths to validate performance claims ahead of commercial tender participation. For Investors and Strategic Acquirers: Re-rating potential sits with hybrid system architects given Agulhas Current and southern Atlantic wave-tidal co-location economics. Long-term viability hinges on electrolyzer integration capabilities for green hydrogen export projects at Chilean and Brazilian deepwater ports. Watch for ANEEL auction participation thresholds tightening toward forty percent local content as the inflection signal for supply chain reconfiguration.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing Agreement | European turbine developers transfer blade molding techniques to Port Elizabeth composite manufacturers under NERSA local content rules. |
| Power Purchase Agreement Portfolio | Aggregated procurement across five to seven site clusters displaces bilateral negotiations in ANEEL auction participation. |
| Backward Integration into Foundations | Captive marine concrete production at Port of Acu reduces exposure to commodity price swings in gravity-base structures. |
| Green Certification Program | ISO 14001 environmental management certification filters eligibility for EU Green Deal extraterritorial supply chain requirements. |
| Joint Venture for Hybrid Platforms | Convergent wave-tidal architectures share mooring infrastructure at Brazil's southern Atlantic co-located resource sites. |
Research Methodology
ANEEL auction documentation, NERSA procurement round filings, and IEC 62600 conformity assessment records formed the secondary backbone for market sizing and technology deployment tracking. Primary interviews with utility planning officers at Eskom and Brazilian distribution concessionaires, IPP project developers along Chile's Magallanes coast, EPC contractors with North Sea marine operations expertise, and grid operators managing interconnection queues supplemented secondary validation. Bottom-up project pipeline aggregation and top-down regulatory framework analysis enabled triangulation across data sources.
Historical trendline analysis of auction participation volumes, capacity factor realizations at MeyGen reference sites, and local content threshold evolution informed projection modeling across the analysis window. Segmentation dimensions covered technology architecture, installation depth tier, end-user credit profile, and regulatory framework cluster. CAGRs derived from fitted growth curves adjusted for equipment fabrication lead times and licensing timeline variability. Forecast inputs incorporated Agulhas Current velocity measurements and ANEEL auction schedule announcements.
Caveats apply where CRE grid interconnection queue reforms, ANEEL local content threshold adjustments, or IEC 62600-2 certification timeline compressions could materially shift the outlook. Forecasts embed assumptions regarding maritime vessel crew availability and dynamic cable supplier capacity expansion. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Renewable Energy Monitoring and Control System Market
Renewable Energy
Offshore Wind Energy Infrastructure Market
Renewable Energy
United Arab Emirates Renewable Energy Market
Renewable Energy
LAMEA Ocean Power Market
Renewable Energy
Egypt Renewable Energy Market
Renewable Energy
West Europe Renewable Energy Market
Renewable Energy
Southern Africa Renewable Energy Market
Renewable Energy
Solar Thermal Water Heater Market
Renewable Energy
Wind Turbine Crane Market
Renewable Energy
Nigeria Renewable Energy Market
Renewable Energy
Solar Navigation Light Market
Renewable Energy
Zimbabwe Renewable Energy Market
Renewable Energy
Global Organic Rankine Cycle Market
Renewable Energy
Singapore Renewable Energy Market
Renewable Energy
Australia Renewable Energy Market
Renewable Energy
North Africa Renewable Energy Market