
 Asia-Pacific Pumped Hydro Storage Market | 2026-2036
Asia-Pacific Pumped Hydro Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Pumped Hydro Storage Market Outlook
Composite turbine runners are restructuring capital-cost economics for pumped hydro equipment across Asia-Pacific. Andritz AG leverages its Francis turbine expertise to anchor European-origin technology in Australian and Southeast Asian projects. Voith GmbH & Co. KGaA sustains manufacturing scale through its Környe facility, competing on delivery timelines for above-500 MW installations. Dongfang Electric Corporation dominates domestic procurement in China, where state-backed developers prioritize locally sourced electromechanical packages.
Pumped hydro storage uses reversible pump-turbine units to transfer water between upper and lower reservoirs, achieving round-trip efficiencies of 75–85 percent while providing grid inertia and frequency response. Closed-loop systems eliminate dependence on continuous river flow, expanding siting flexibility in water-scarce regions such as Australia's Snowy Mountains. The 500–1000 MW capacity bracket carries the deepest margin pools, as these projects balance economies of scale against manageable geological risk and permitting complexity. New build installations lead volume, though retrofit and upgrade segments accelerate as aging Japanese and Korean facilities approach design-life thresholds.
China's National Energy Administration sets annual pumped hydro construction targets through its 14th Five-Year Plan framework, directly shaping provincial investment pipelines. Australia's Clean Energy Regulator integrates pumped hydro into the Renewable Energy Target certificate scheme, altering project revenue stacking for developers. Japan's METI reviews grid codes to recognize pumped hydro's fast-frequency response capabilities, potentially expanding ancillary service remuneration. Stakeholders must monitor how India's CEA storage mandates translate into executable procurement schedules across state transmission utilities.
Market Dynamics
China's 14th Five-Year Plan construction targets are compressing project development cycles across the Asia-Pacific pumped hydro sector, forcing developers to accelerate reservoir engineering and turbine procurement simultaneously.
Growth Catalysts
- Renewable Purchase Obligations:India's Central Electricity Authority mandates storage obligations that accelerate project approvals for grid-scale utilities balancing intermittent solar generation.
- Closed-loop Configurations:Water-scarce regions in Australia's Snowy Mountains adopt river-independent reservoir designs that expand siting flexibility beyond traditional hydroelectric corridors.
- Frequency Response Recognition:Japan's METI reviews grid codes to remunerate fast-frequency ancillary services, expanding revenue streams for existing and new pumped hydro assets.
Market Restraints
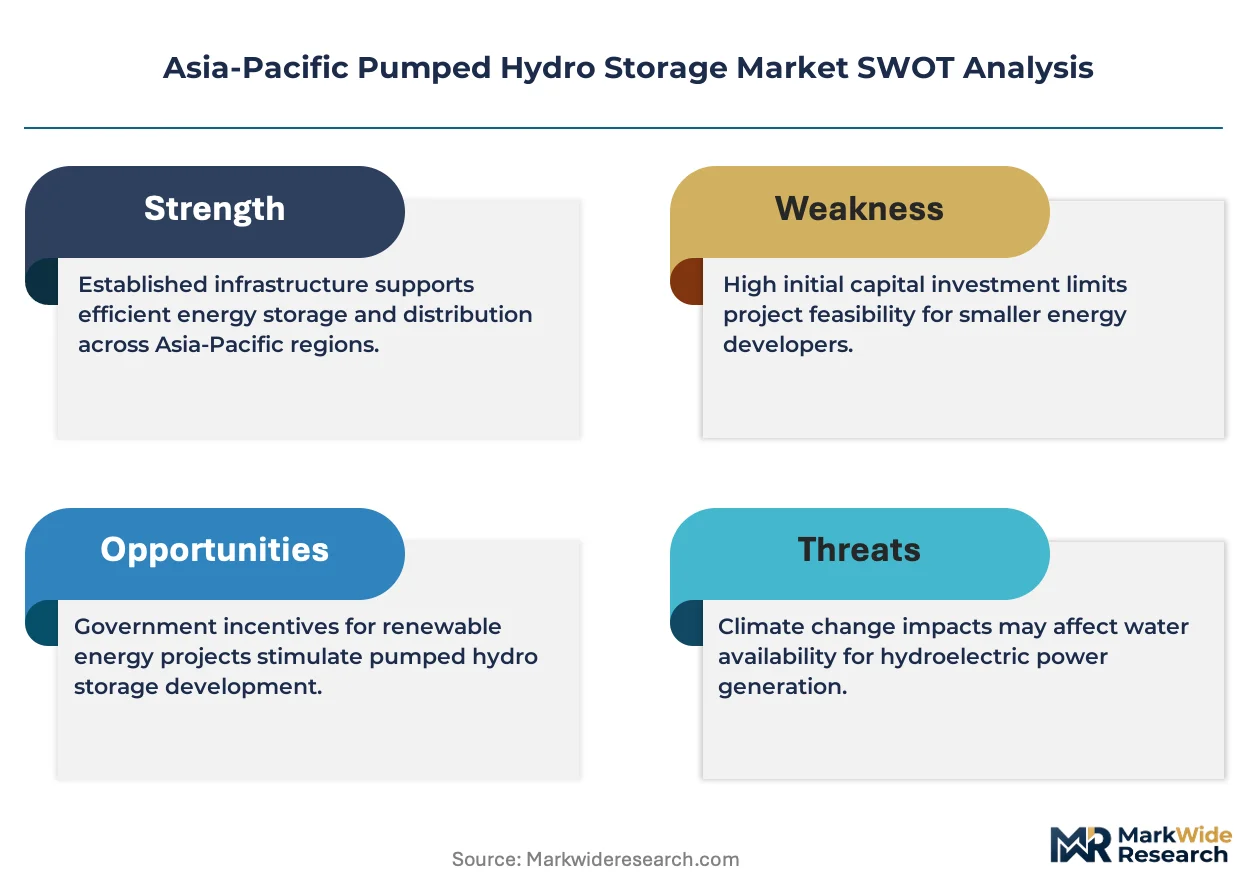
- Geological Risk Concentration:Above-500 MW installations in China's southwestern provinces face extended permitting timelines due to seismic zone assessments and reservoir stability studies.
- Electromechanical Supply Concentration:State-backed Chinese developers prioritize domestically sourced turbine packages, limiting market access for European and Australian equipment suppliers.
- Capital Intensity Thresholds:Front-loaded reservoir construction and tunneling costs require long-dated power purchase agreements that few offtakers outside state utilities can underwrite.
Strategic Opportunities
- Retrofit Segment Expansion:Aging Japanese and Korean facilities approaching design-life thresholds create demand for runner replacements and digital control system upgrades.
- Composite Material Adoption:Carbon-fiber-reinforced turbine runners reduce cavitation damage and maintenance intervals, opening margin pools in the 500–1000 MW capacity bracket.
- Certificate Scheme Integration:Australia's Clean Energy Regulator incorporates pumped hydro into Renewable Energy Target frameworks, altering revenue stacking for merchant developers.
Industry Challenges
- Specialized Tunneling Expertise Scarcity:Underground reservoir construction requires geotechnical engineers familiar with high-head pressure conditions, a skill set concentrated among state-owned construction consortia.
- Grid Code Harmonization Delays:Disconnected provincial transmission utilities across India and China maintain incompatible frequency response standards, complicating inter-regional project development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Pumped Hydro Storage Market |
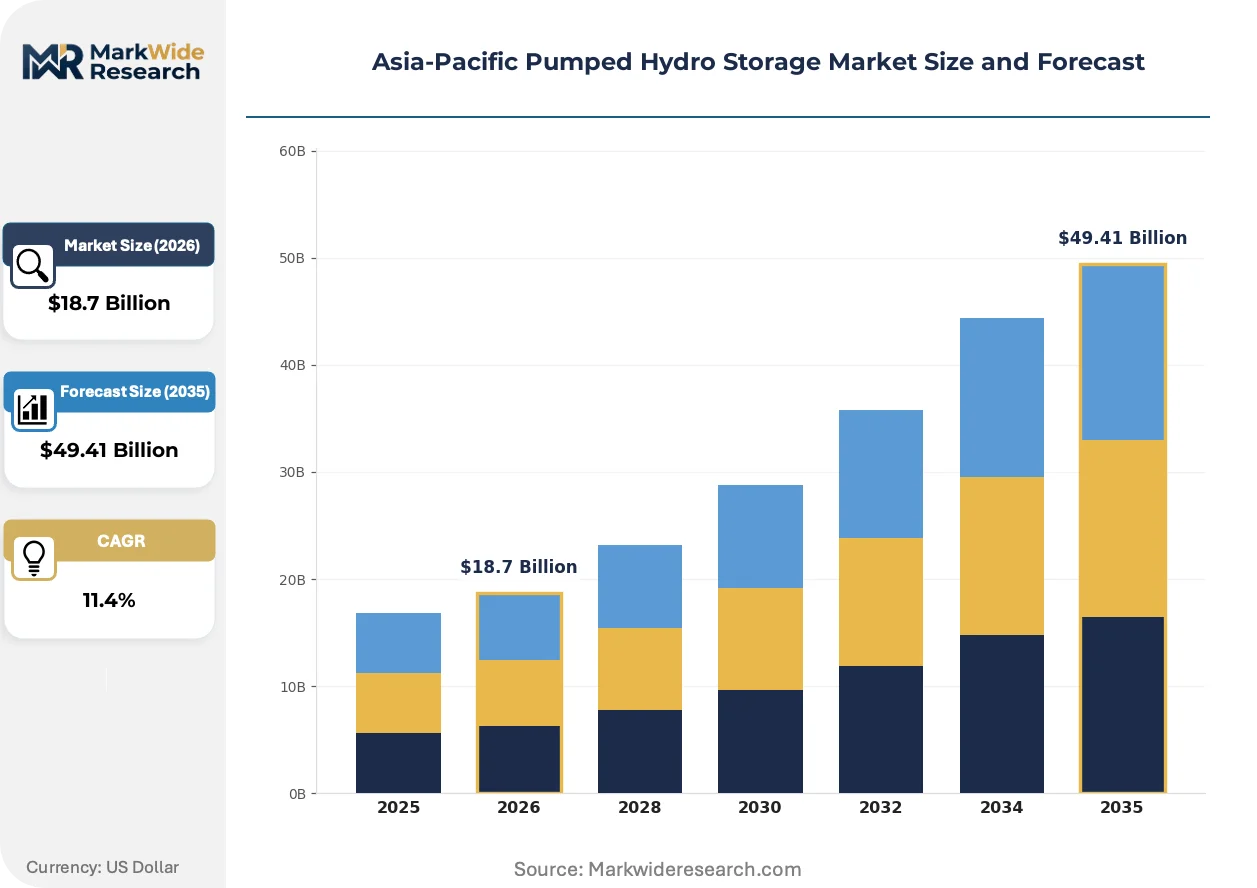
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Closed Loop, Open Loop, Pumped Storage, Hybrid System End User: Utilities, Industrial, Commercial, Renewable Energy Providers Installation Type: New Build, Retrofit, Expansion, Upgrade Capacity: Less than 100 MW, 100–500 MW, 500–1000 MW, Above 1000 MW |
| Companies Covered | Enel SpA, Andritz AG, Voith GmbH & Co. KGaA, Black & Veatch Holding Company, Stantec, Siemens AG, Tokyo Electric Power Company, Dongfang Electric Corporation, General Electric Company, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Pumped Hydro Storage Market Strategic Shifts
Digital twin modeling and advanced geotechnical surveying are compressing feasibility study timelines for pumped hydro developers across Asia-Pacific, reducing upfront capital at risk before final investment decisions.
Variable-speed pump-turbine technology is modularizing project design across China's Yunnan and Sichuan provinces. State Grid Corporation deploys these units to stabilize frequency fluctuations from adjacent solar farms. The technology enables smaller upper reservoir footprints while maintaining grid inertia services, reducing land acquisition conflicts in mountainous terrain.
Australia's Clean Energy Regulator has integrated pumped hydro into certificate eligibility rules under the Renewable Energy Target scheme. This policy shift alters developer revenue stacking calculations, particularly for Snowy Mountains projects seeking merchant exposure. The regulatory change most affects mid-scale developers previously excluded from capacity market participation.
State transmission utilities in India are consolidating procurement authority under the Central Electricity Authority's storage mandate framework. This centralization displaces fragmented state-level tendering processes that previously delayed project execution. The behavioral shift concentrates buyer power among five regional transmission utilities, compressing vendor negotiation cycles for electromechanical packages.
Asia-Pacific Pumped Hydro Storage Market Segmentation
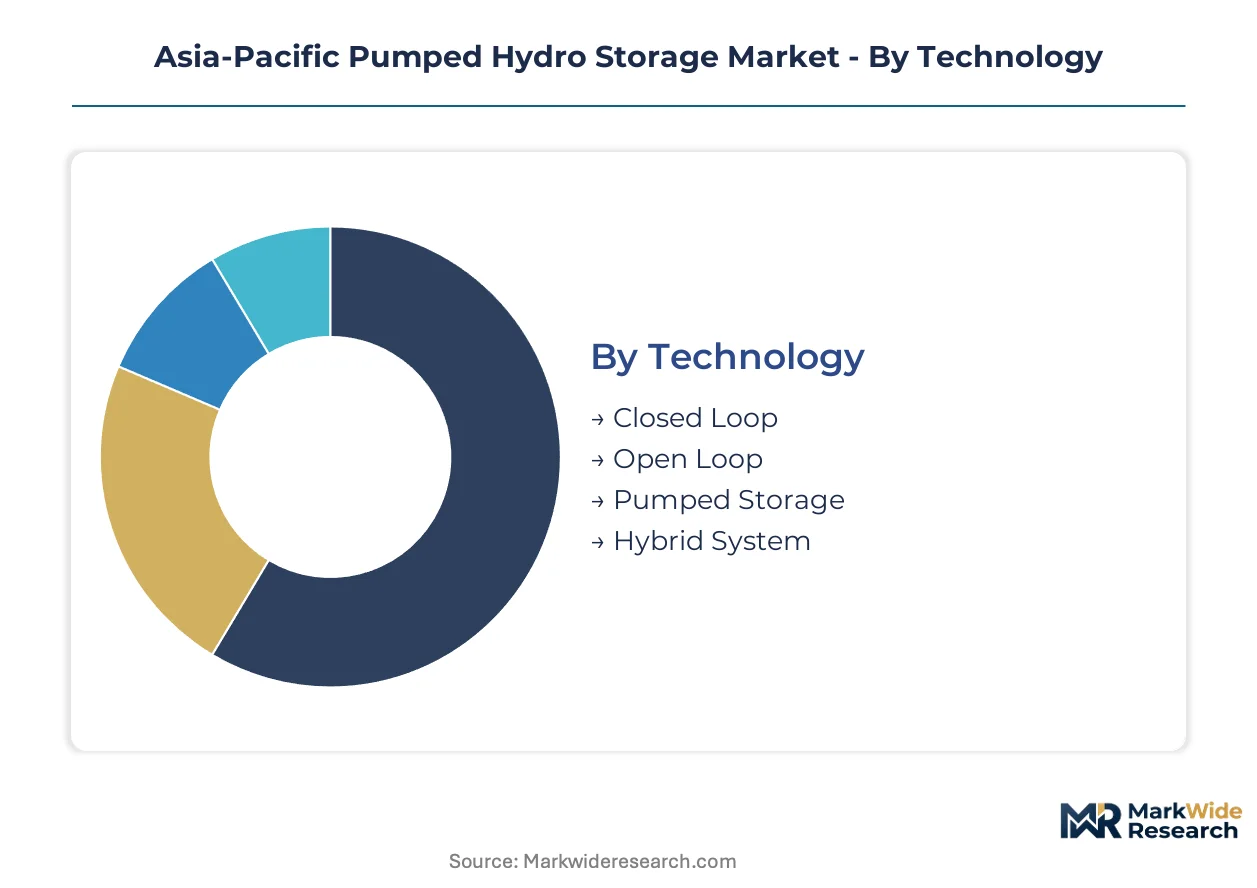
Pumped hydro storage economics vary dramatically across technology configurations and capacity brackets. Segment-level capital requirements, permitting timelines, and revenue stacking opportunities determine developer prioritization across Asia-Pacific markets.
Technology:
Capital intensity peaks with closed-loop systems requiring dual reservoir construction without natural waterway integration.
- Closed Loop:Self-contained upper and lower reservoirs eliminate river flow dependency. Australia's Snowy Mountains developers favor this configuration to bypass water rights disputes and seasonal flow variability.
- Open Loop:Continuous river-fed designs leverage existing topography for reduced civil works. China's southwestern provinces exploit steep river valleys to minimize tunneling costs for state-backed utilities.
- Pumped Storage:Conventional reversible turbine installations dominate procurement pipelines across established Asian grids.
- Hybrid System:Battery-pumped hydro combinations address ramp-rate limitations in frequency response applications.
Most installed capacity flows through Pumped Storage. Expansion is steepest in Closed Loop.
End User:
Procurement authority concentrates among entities capable of underwriting multi-decade power purchase agreements.
- Utilities:State transmission companies and grid-scale operators command project pipelines through integrated resource planning mandates. India's Central Electricity Authority storage obligations channel investment toward state utilities with renewable purchase obligation compliance requirements.
- Renewable Energy Providers:Solar and wind developers co-locate storage to firm output profiles and capture premium tariff structures. China's State Grid Corporation procures dedicated pumped hydro to balance Yunnan and Sichuan photovoltaic clusters.
- Industrial:Aluminum smelters and data centers seek behind-the-meter arbitrage capacity where retail tariff spreads justify captive investment.
- Commercial:Campus-scale microgrids in Australian mining operations deploy modular configurations for remote supply security.
Utilities anchor current deployment volumes. Renewable Energy Providers are climbing the fastest.
Installation Type:
Greenfield construction absorbs the majority of capital deployment, though aging infrastructure creates aftermarket opportunities.
- New Build:Fresh civil works and electromechanical packages characterize China's 14th Five-Year Plan construction targets. Provincial energy bureaus compress development cycles through streamlined environmental reviews for strategic projects.
- Retrofit:Runner replacements and digital control upgrades extend asset life for Japanese facilities approaching design-life thresholds. METI grid code revisions incentivize frequency response capability investments.
- Expansion:Additional generating units at existing sites exploit permitted reservoir footprints and transmission interconnections.
- Upgrade:Efficiency improvements through turbine runner material advances reduce maintenance intervals for mid-life assets.
New Build captures the dominant share of capital formation. Retrofit is gaining share fastest.
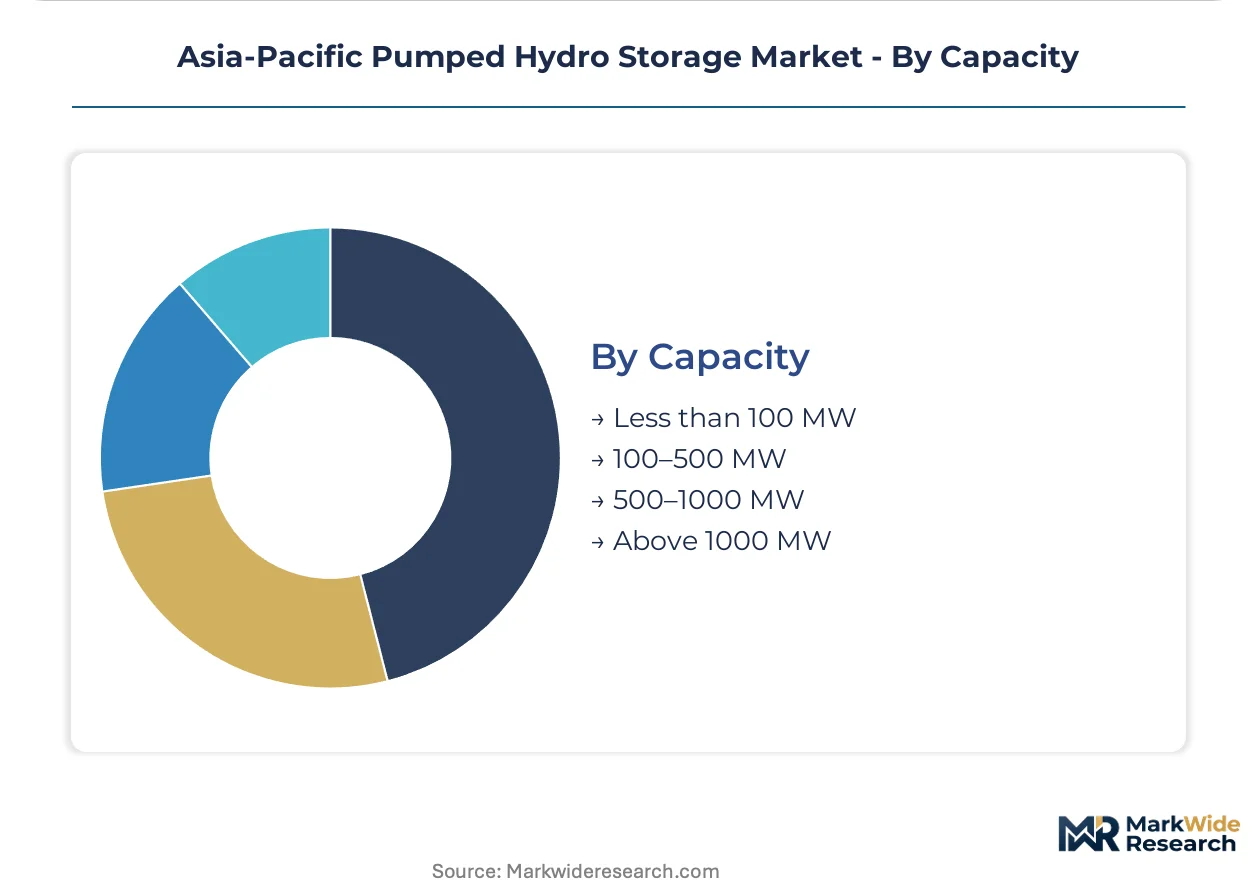
Capacity:
Project scale determines geological risk exposure, equipment supplier access, and offtaker eligibility for procurement programs.
- 500–1000 MW:This bracket balances economies of scale against manageable permitting complexity. China's southwestern provinces concentrate development here, with mountainous terrain supporting large reservoir configurations and state-backed developers prioritizing domestically sourced electromechanical packages.
- Above 1000 MW:Mega-projects face extended seismic assessments and reservoir stability studies. India's Central Electricity Authority identifies this scale for strategic grid balancing, though few offtakers outside state utilities can underwrite front-loaded construction costs.
- 100–500 MW:Mid-scale developments suit merchant exposure and Australia's Renewable Energy Target certificate stacking.
- Less than 100 MW:Modular configurations serve island grids and industrial microgrids across Southeast Asian archipelagos.
500–1000 MW represents the deepest margin pool. Above 1000 MW shows the steepest expansion trajectory where permitting allows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yunnan and Sichuan provinces anchor Asia-Pacific pumped hydro deployment through steep river valleys and concentrated solar-wind hybrid zones. State Grid Corporation channels investment toward southwestern reservoir configurations that balance intermittent generation. Provincial energy bureaus compress development timelines through streamlined environmental reviews.
China
State-backed developers in Yunnan and Sichuan provinces exploit mountainous terrain for large reservoir configurations. The National Energy Administration sets annual construction targets through the 14th Five-Year Plan framework. Provincial procurement prioritizes domestically sourced electromechanical packages from Dongfang Electric Corporation.
India
State transmission utilities consolidate procurement authority under Central Electricity Authority storage mandates. Renewable purchase obligations accelerate project approvals for grid-scale solar balancing. The Western Ghats and Himalayan foothills concentrate geological assessments for above-500 MW installations.
Japan
Aging facilities in Kanto and Kansai regions approach design-life thresholds, creating retrofit demand for runner replacements. METI reviews grid codes to recognize fast-frequency response capabilities. Tokyo Electric Power Company operates legacy assets requiring digital control system upgrades.
Australia
Snowy Mountains developers favor closed-loop configurations to bypass water rights disputes. The Clean Energy Regulator integrates pumped hydro into Renewable Energy Target certificate eligibility rules. New South Wales and Victoria concentrate mid-scale merchant projects seeking revenue stacking opportunities.
South Korea
Korea Hydro & Nuclear Power maintains existing pumped hydro capacity for grid frequency stabilization. Aging installations in Gangwon and Gyeongsang provinces drive aftermarket demand for efficiency improvements. The Ministry of Trade, Industry and Energy evaluates grid code revisions for ancillary service remuneration.
Asia-Pacific Pumped Hydro Storage Market Competitive Environment
Global majors compete with regional champions across electromechanical supply chains and engineering procurement construction contracting. The vendor base stratifies into three tiers: integrated turbine-generator manufacturers, specialized civil works contractors, and hybrid engineering consultancies. European-origin technology suppliers anchor premium-tier positioning through Francis turbine expertise. Competitive moves center on manufacturing scale defense and local content compliance for state-backed procurement programs.
Among European-heritage equipment suppliers, Andritz AG and Voith GmbH & Co. KGaA represent the integrated manufacturing archetype, while Dongfang Electric Corporation occupies the dominant domestic champion position in China. These three entities exemplify the competitive tension between imported technology packages and locally sourced procurement mandates across Asia-Pacific project pipelines.
| Leading Market Players |
|---|
| Enel SpA |
| Andritz AG |
| Voith GmbH & Co. KGaA |
| Black & Veatch Holding Company |
| Stantec |
| Siemens AG |
| Tokyo Electric Power Company |
| Dongfang Electric Corporation |
| General Electric Company |
| Others |
Value Chain & Pricing Dynamics
Geotechnical engineers specializing in high-head pressure tunneling concentrate among state-owned construction consortia in China's southwestern provinces, with labor-cost differentials between Sichuan-based crews and Australian contractors driving spreads between economy-tier civil works and premium European-sourced electromechanical packages.
Pricing Analysis
Input-cost pass-through from carbon-fiber-reinforced turbine runner materials and specialized tunneling labor flows directly into project bids, with pricing stratifying across premium, standard, and economy tiers based on equipment origin certification and reservoir complexity. European-origin Francis turbine packages command brand premiums against domestically sourced Dongfang Electric alternatives. Cost compression in the standard tier intensifies as Indian state utilities consolidate procurement authority under CEA storage mandates. Merchant developers in Australia's Renewable Energy Target scheme exhibit highest price sensitivity, while China's State Grid Corporation demonstrates lowest sensitivity due to integrated resource planning budgets.
Supply Chain Analysis
Dual-sourcing requirements for critical electromechanical components compel developers to qualify both European-origin suppliers and domestic champions across procurement pipelines. Manufacturing concentration centers on China, Austria, and Germany for turbine-generator packages, with raw material dependencies spanning high-grade steel forgings, copper windings, and carbon-fiber composites. Single-source vulnerability persists for variable-speed drive systems where Voith and Andritz hold specialized expertise. Distribution runs through engineering-procurement-construction contractors who bundle civil works with equipment packages for state-backed utilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with developer procurement shifting toward premium specifications for composite turbine runners and digital control systems as aging Japanese and Korean assets approach design-life thresholds.
For Market Incumbents: Deepen backward integration into carbon-fiber runner manufacturing to defend margin position against emerging Chinese suppliers capturing domestic procurement share. Prioritize certification investment for frequency-response grid codes under Japan's METI review to lock in ancillary service revenue streams before regulatory windows close. For New Entrants and Emerging Players: State transmission utilities in India's Western Ghats represent the most penetrable buyer segment, with fragmented state-level tendering displacement creating entry paths for mid-scale EPC contractors. Pursue joint-venture structures with established tunneling specialists to overcome geotechnical capability barriers in above-500 MW reservoir configurations. For Investors and Strategic Acquirers: State-backed infrastructure funds are the most active acquirer in this space, consolidating operational assets for yield-focused portfolios. Target retrofit-ready facilities in Japan's Kanto region with unexploited frequency-response capability upgrades. Watch India's CEA procurement schedule execution as the signal for demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | State Grid Corporation's Yunnan deployments balance adjacent photovoltaic clusters. |
| Backward Integration | Dongfang Electric's captive forging capacity secures supply for 14th Five-Year Plan targets. |
| Technology Licensing | Voith's variable-speed drive patents anchor premium positioning in Australian projects. |
| Power Purchase Agreement | Long-dated offtake contracts with India's regional transmission utilities underwrite construction finance. |
| Green Certification Program | Australia's Clean Energy Regulator integration alters revenue stacking for Snowy Mountains developers. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with utility planning officers, EPC project developers, turbine procurement leads at state transmission utilities, and geotechnical engineering directors with secondary validation against IEA hydropower databases, FERC pumped hydro filings, China National Energy Administration construction target disclosures, and India CEA storage mandate circulars. Bottom-up project pipeline aggregation and top-down regulatory target reconciliation provided cross-verification.
Segment-weighting across the projection horizon applied capacity-tier brackets, technology configuration categories, end-user procurement authority levels, and regional regulatory framework clusters as analytical dimensions. CAGRs derived from installed capacity buildout trajectories, with input variables spanning construction timeline compression rates under China's 14th Five-Year Plan, India's RPO compliance acceleration curves, and Japan's METI grid code revision implementation schedules.
Revisions become necessary when permitting timeline extensions in Chinese seismic zones, India's state-level tendering fragmentation resurgence, or Australia's RET certificate price volatility materialize. Deviation in any trigger would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydropower Systems
Standard Modular Hydropower Market
Hydropower Systems
Offshore Hydropower Market
Hydropower Systems
Hydroelectricity Market
Hydropower Systems
South America Hydropower Market
Hydropower Systems
Europe Small Hydropower Market
Hydropower Systems
Tidal Power Market
Hydropower Systems
Global Hydro Turbine Generator Unit Market
Hydropower Systems
Africa Small Hydropower Market
Hydropower Systems
Pumped Hydro Storage Market
Hydropower Systems
South America Pumped Hydro Storage Market
Hydropower Systems
Floating Power Plant Market
Hydropower Systems
France Tidal Power Market
Hydropower Systems
Hydropower Market
Hydropower Systems
Whirlpool Turbine Market
Hydropower Systems
Run of River Power Market
Hydropower Systems
Wave and Tidal Energy Market