
 United States Hydro Turbine Market | 2026-2036
United States Hydro Turbine Market Size, Share, and Industry Trends Forecast 2026-2036
United States Hydro Turbine Market Analytics
Buyer concentration among public utilities is restructuring procurement patterns across the United States hydro turbine landscape. Duke Energy Corporation leverages its regulated utility footprint to secure long-term turbine supply agreements for pumped storage expansion. Voith Hydro anchors its position through vertical integration into turbine runner casting and precision machining. GE Vernova competes on technology leadership in variable-speed generation systems for grid stabilization services.
A hydro turbine converts hydraulic energy into rotational mechanical energy through precision-engineered runners, wicket gates, and draft tubes designed for specific head and flow conditions. Francis turbines dominate the United States installed base due to their operational flexibility across medium-head installations from 50 to 500 meters. Kaplan turbines capture growing share in run-of-river applications where adjustable blade pitch maximizes efficiency at variable seasonal flows. Pelton turbines occupy niche high-head positions in mountainous western terrain where jet-impulse designs extract maximum energy from steep hydraulic gradients.
FERC licensing requirements shape project timelines and environmental compliance costs for new and refurbished installations. EPA water quality standards under the Clean Water Act influence turbine design to minimize dissolved oxygen depletion and fish passage mortality. NERC reliability standards mandate grid-code compliance for frequency response and reactive power capability. Stakeholders must monitor evolving FERC rulemakings on pumped storage market participation and state renewable portfolio standards that increasingly count existing hydroelectric capacity toward clean energy mandates.
Market Dynamics
FERC licensing timelines and EPA environmental compliance are compressing project development windows, forcing utilities to front-load engineering and pre-certification work before construction financing closes.
Growth Catalysts
- IRA Production Tax Credits:Federal incentives for existing hydroelectric upgrades and new pumped storage installations are accelerating capital deployment timelines for public utilities.
- Intermittent Renewable Integration:Grid operators in California and Texas require fast-ramping capacity, expanding procurement of adjustable-speed turbine-generator sets for frequency regulation services.
- Columbia River Basin Replacement Cycle:Aging infrastructure across Washington and Oregon is driving systematic runner and wicket gate refurbishment programs.
Market Restraints
- Specialized Forging Capacity Concentration:Domestic production of large stainless steel turbine runners depends on a limited number of heavy foundries, creating procurement bottlenecks for projects over 100 MW.
- FERC Licensing Duration:New project authorizations routinely exceed five years, inflating development carry costs and deterring private capital participation.
- Environmental Litigation Risk:Endangered Species Act consultations for fish passage modifications add contingent liability exposure that constrains project financing terms.
Strategic Opportunities
- Closed-Loop Pumped Storage:Off-stream reservoir configurations bypass traditional streamflow dependencies, opening development in Arizona and Nevada transmission corridors.
- Small Modular Hydropower:Standardized turbine-generator packages below 10 MW are penetrating agricultural irrigation districts and municipal water systems.
- Grid-Scale Battery Hybridization:Co-located lithium-ion storage with existing hydro facilities enables stacked revenue streams from capacity and ancillary services markets.
Industry Challenges
- Turbomachinery Engineering Talent Pipeline:Universities have reduced hydraulic engineering program enrollment, narrowing the specialist workforce for computational fluid dynamics and cavitation analysis.
- Legacy Control System Integration:Digital governor retrofits on pre-1990s installations require protocol translation layers that extend commissioning schedules.
Report Scope
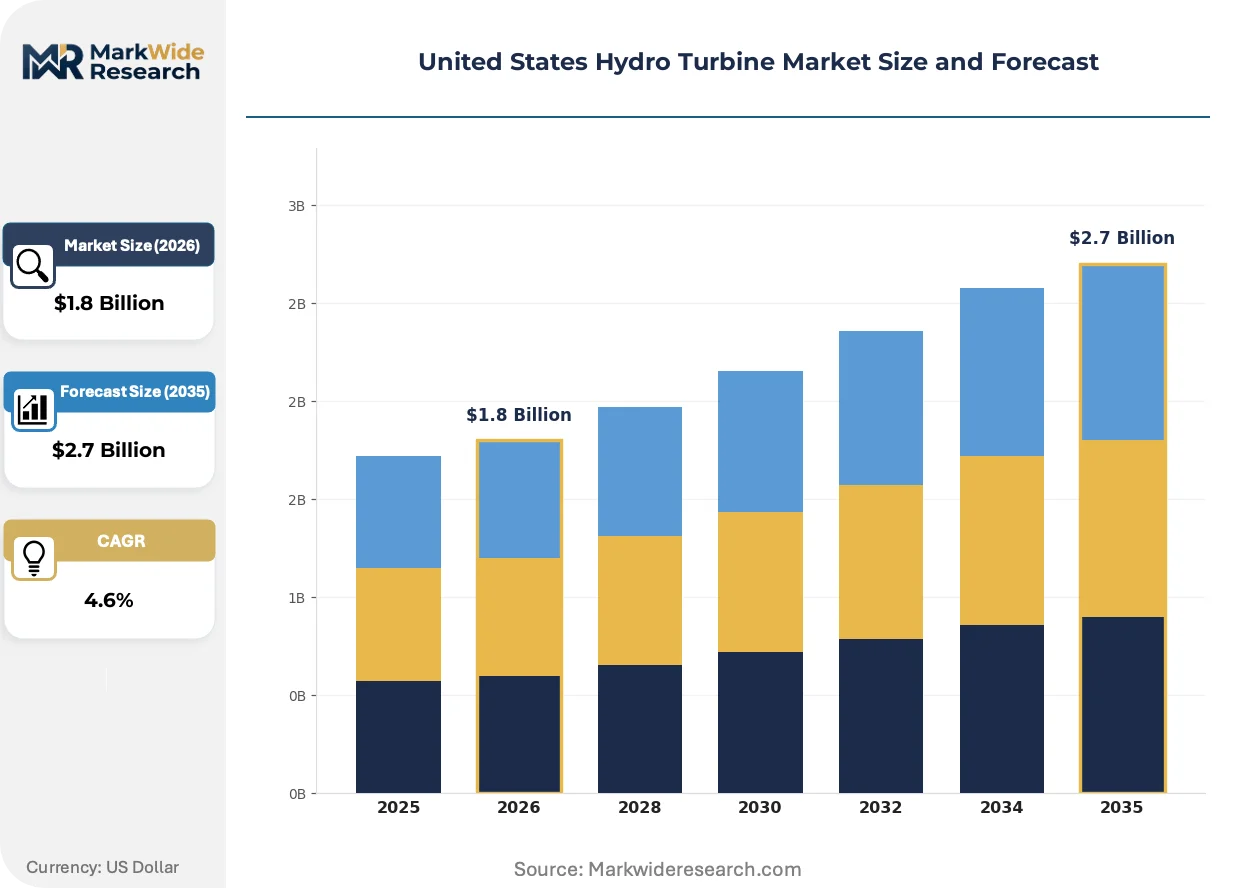
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Hydro Turbine Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bulb Turbines, Francis Turbines, Pelton Turbines, Kaplan Turbines Application: Utility Scale Generation, Mini Hydropower, Pumped Storage, Run-of-River End User: Public Utilities, Private Sector, Industrial Clients, Renewable Energy Providers Installation: Onshore, Offshore, Distributed Grid, Centralized Systems |
| Companies Covered | Voith Hydro, American Hydro, GE Vernova, Brookfield Renewable US, Canyon Hydro, Siemens Energy AG, Duke Energy Corporation, NextEra Energy Resources, Andritz AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Hydro Turbine Market Evolving Landscape
Digital twin modeling and additive manufacturing are compressing design-to-deployment cycles while enabling performance optimization across variable operating regimes previously considered uneconomic.
Variable-speed doubly-fed induction generators are absorbing grid stabilization responsibilities that once required separate synchronous condenser installations. Mid-size utilities in the Pacific Northwest are retrofitting Francis units with full-converter interfaces to capture frequency regulation revenue streams. This technology is absorbing capital that previously flowed to standalone battery storage for grid services.
EPA Section 316(b) regulations on cooling water intake structures are mandating fish-friendly turbine designs with reduced rotational speeds and modified blade geometries. Manufacturers must now certify passage survival rates exceeding ninety percent for target species. The rule is compressing procurement timelines for municipal utilities in the Northeast that must comply with compliance deadlines.
Long-term service agreements are displacing transactional spare parts purchasing among investor-owned utilities. Duke Energy and Berkshire Hathaway Energy subsidiaries are bundling twenty-year maintenance contracts with initial equipment supply, transferring operational risk to OEMs. This pattern is most visible in the Southeast, where vertically integrated utilities face rate-base pressure to minimize unplanned outage costs.
United States Hydro Turbine Market Segmentation
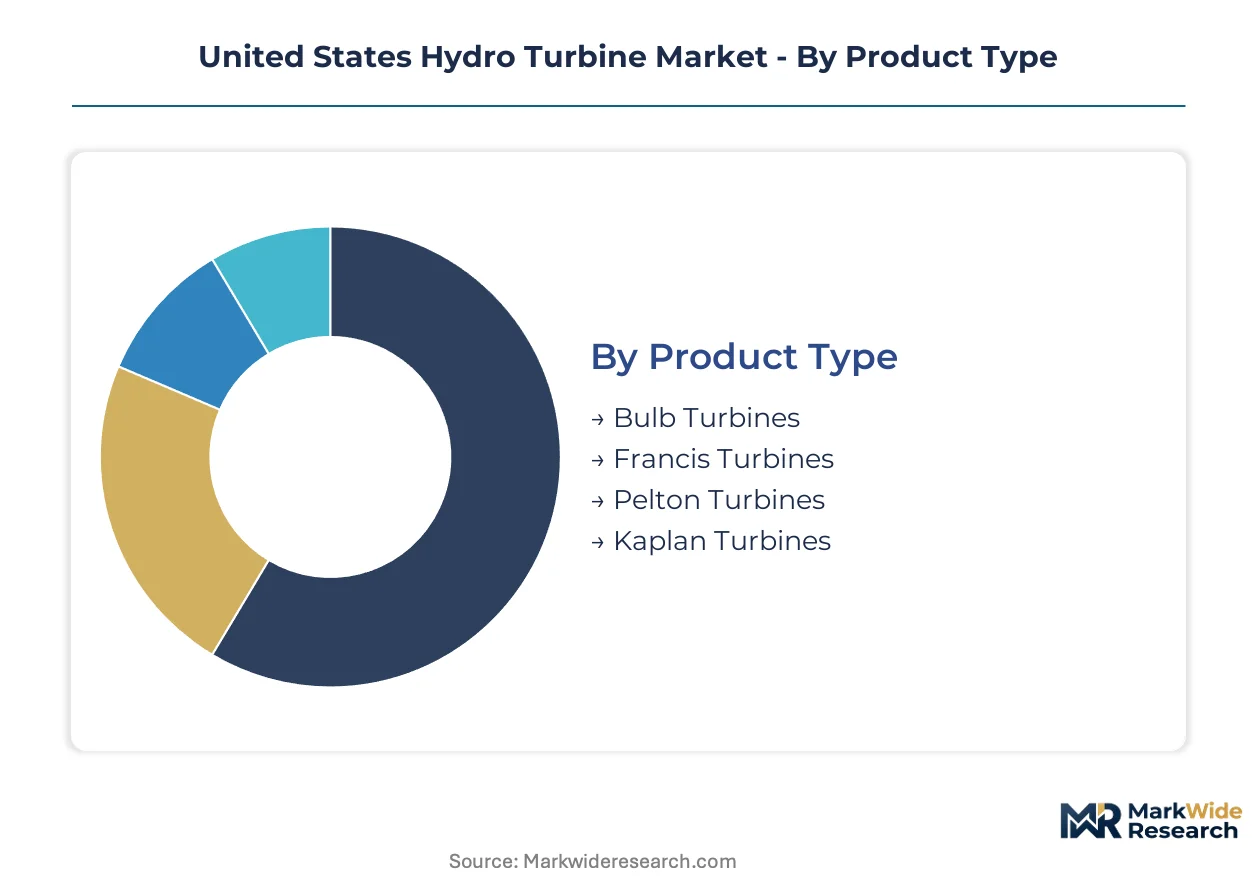
Segmentation of the United States hydro turbine market reveals how technology specifications, application contexts, and customer procurement patterns create distinct competitive arenas. Understanding these divisions allows manufacturers to align R&D investments with specific performance requirements and regulatory constraints.
Product Type:
Runner geometry and hydraulic head range define the fundamental technology axis for turbine selection across American installations.
- Francis Turbines:Spiral-cased reaction turbines with fixed or adjustable wicket gates dominate the Columbia River Basin refurbishment cycle. Public utilities in Washington and Oregon specify these units for their operational flexibility across 50-to-500-meter head ranges and proven grid stabilization capability.
- Kaplan Turbines:Axial-flow designs with adjustable blade pitch capture run-of-river deployments where seasonal flow variation demands efficiency optimization. Municipal utilities in the Northeast favor these units for low-head installations subject to EPA fish passage mandates.
- Bulb Turbines:Horizontal-axis units with generator housed within the flow stream suit tidally influenced estuaries and navigation locks. The compact footprint appeals to constrained civil works sites.
- Pelton Turbines:Impulse-type wheels with bucket-shaped runners extract energy from high-head jet streams in Rocky Mountain terrain. Steep hydraulic gradients in Colorado and Utah favor this configuration.
Mature deployment sits with Francis Turbines. Newer deployment is concentrated in Kaplan Turbines.
Application:
Project scale and grid function determine capital intensity, licensing complexity, and revenue model structure for turbine procurement.
- Utility Scale Generation:Centralized installations exceeding 100 MW require custom-engineered runners and multi-year FERC licensing timelines. Duke Energy and Berkshire Hathaway Energy subsidiaries drive demand through systematic replacement of pre-1980s infrastructure.
- Pumped Storage:Reversible turbine-pump units provide frequency regulation and renewable integration services. IRA production tax credits are accelerating closed-loop reservoir configurations in Arizona and Nevada transmission corridors.
- Run-of-River:Minimal reservoir designs with continuous flow dependency suit environmental constraints in the Pacific Northwest. Smaller civil works reduce upfront capital exposure.
- Mini Hydropower:Standardized packages below 10 MW penetrate agricultural irrigation districts and municipal water systems. Modular designs compress procurement cycles.
Capital deployment concentrates in Utility Scale Generation. Regulatory tailwinds favor Pumped Storage for fastest expansion.
End User:
Ownership structure shapes risk tolerance, financing mechanisms, and maintenance contracting preferences across the customer base.
- Public Utilities:Rate-regulated entities with cost-recovery mechanisms favor twenty-year service agreements bundling equipment and maintenance. Long-term procurement horizons align with FERC licensing timelines.
- Private Sector:Independent power developers and investor-owned utilities prioritize merchant revenue exposure and shorter payback periods. These customers drive demand for grid-scale battery hybridization.
- Industrial Clients:Self-generation users at pulp mills, aluminum smelters, and data centers seek behind-the-meter reliability. Cogeneration configurations with process heat integration dominate.
- Renewable Energy Providers:Wind and solar developers adding hydro assets for portfolio diversification require fast-ramping turbine sets. Frequency regulation revenue streams justify premium equipment specifications.
Procurement volume concentrates with Public Utilities. Private Sector participation is expanding most quickly under IRA incentive structures.
Installation:
Physical siting and electrical interconnection architecture determine civil engineering requirements and grid code compliance obligations.
- Onshore:Conventional dam and powerhouse configurations on navigable rivers constitute the vast majority of installed capacity. FERC jurisdiction applies uniformly.
- Distributed Grid:Small-scale installations at multiple points on distribution networks reduce transmission congestion. These projects face streamlined interconnection queues.
- Centralized Systems:Single-point transmission interconnections at high voltage require NERC reliability standard compliance. Synchronous condenser capabilities feature in specifications.
- Offshore:Submerged turbine configurations for tidal and ocean current energy remain pre-commercial in United States waters. Demonstration projects operate under experimental permits.
Asset base concentrates in Onshore installations. Distributed Grid configurations are gaining share fastest among new project development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Public utilities concentrate procurement authority across distinct hydrological zones, with each region presenting unique siting constraints and regulatory compliance burdens. The Pacific Northwest dominates installed capacity, while the Southwest and Southeast emerge as growth corridors for pumped storage development.
Pacific Northwest
The Columbia River Basin drives systematic refurbishment of pre-1980s Francis turbine installations across Washington and Oregon. FERC relicensing requirements for federal hydroelectric projects mandate fish passage upgrades and dissolved oxygen mitigation. Voith Hydro maintains manufacturing presence in York, Pennsylvania to serve runner replacement cycles at Bonneville Power Administration facilities.
Southwest
Arizona and Nevada transmission corridors attract closed-loop pumped storage proposals bypassing traditional streamflow dependencies. IRA production tax credits accelerate capital deployment for reversible turbine-pump units serving California grid balancing needs. Developers concentrate preliminary engineering in Phoenix and Las Vegas metropolitan zones to exploit existing high-voltage interconnection capacity.
Southeast
Duke Energy subsidiaries drive demand for twenty-year bundled service agreements covering turbine supply and predictive maintenance. The Infrastructure Investment and Jobs Act directs federal funding toward modernizing aging hydropower assets across Tennessee Valley Authority watersheds. Equipment suppliers cluster manufacturing support in Charlotte and Atlanta to serve regulated utility procurement timelines.
Mountain West
High-head Pelton turbine applications dominate Colorado and Utah installations exploiting steep hydraulic gradients in Rocky Mountain terrain. EPA Section 316(b) regulations mandate fish-friendly designs with reduced rotational speeds for municipal utilities in the Upper Colorado River Basin. Canyon Hydro anchors specialized fabrication capacity for impulse-type wheels serving niche elevation-differential projects.
Northeast
Run-of-river Kaplan turbines capture municipal utility preference for low-head installations subject to stringent EPA water quality standards. Compliance deadlines for cooling water intake structure modifications compress procurement timelines across New York and New England. Equipment vendors maintain technical service operations in Boston and Albany to support seasonal flow optimization requirements.
United States Hydro Turbine Market Competitive Landscape
German and Austrian producers anchor one tier of precision turbine manufacturing; American specialists hold project execution and long-term service contracting positions. The vendor structure concentrates around vertically integrated foundry operations and digital control system providers. Three archetypes dominate: full-line OEMs with captive casting capacity, regional fabricators focused on refurbishment cycles, and utility-affiliated developers securing equipment through affiliate relationships. Competitive moves center on backward integration into stainless steel runner production and strategic partnerships for grid-scale battery hybridization.
Among European-headquartered full-line suppliers, Voith Hydro and Andritz AG exemplify the integrated manufacturing archetype with in-house precision machining capabilities. GE Vernova occupies a position bridging turbine hardware and variable-speed generator control systems. These three entities represent distinct strategic postures: Voith Hydro emphasizes vertical control over casting and machining operations; Andritz AG concentrates on computational fluid dynamics optimization for fish-passage-compliant designs; GE Vernova competes through full-converter interfaces enabling frequency regulation revenue capture. American Hydro and Canyon Hydro sit within the specialized fabricator tier, focusing on runner replacement and high-head impulse applications respectively. Utility-affiliated developers including Duke Energy Corporation and Brookfield Renewable US leverage regulated rate-base mechanisms or independent power portfolios to secure equipment supply through long-term offtake structures rather than merchant procurement.
| Leading Market Players |
|---|
| Voith Hydro |
| American Hydro |
| GE Vernova |
| Brookfield Renewable US |
| Canyon Hydro |
| Siemens Energy AG |
| Duke Energy Corporation |
| NextEra Energy Resources |
| Andritz AG |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap fabricators anchor runner production capacity across Pennsylvania and Ohio, translating concentrated forging expertise into pricing discipline that resists commoditization despite utility procurement consolidation.
Pricing Analysis
High-volume replacement cycles for Columbia River Basin Francis units trade margin for throughput, while custom-engineered Pelton installations for Rocky Mountain terrain command premium positioning. Price differentiation rests on FERC certification tier and bundled twenty-year service agreements. Cost compression in standardized Kaplan packages intensifies as municipal utilities consolidate procurement through joint powers authorities. Investor-owned utilities exhibit lowest price sensitivity given rate-base recovery mechanisms, whereas independent power developers face acute capital constraint pressure.
Supply Chain Analysis
Stainless steel runner casting rests on domestic heavy foundries concentrated in Pennsylvania, Ohio, and Indiana, with precision machining capacity clustering in York and Charlotte. Raw material feeds from specialty alloy producers and precision bearing manufacturers face single-source vulnerability for forgings exceeding fifty-ton unit weight. Tariff exposure on European control system imports compounds lead time uncertainty. Distribution runs through EPC contractor networks with utility-direct procurement gaining share for refurbishment cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
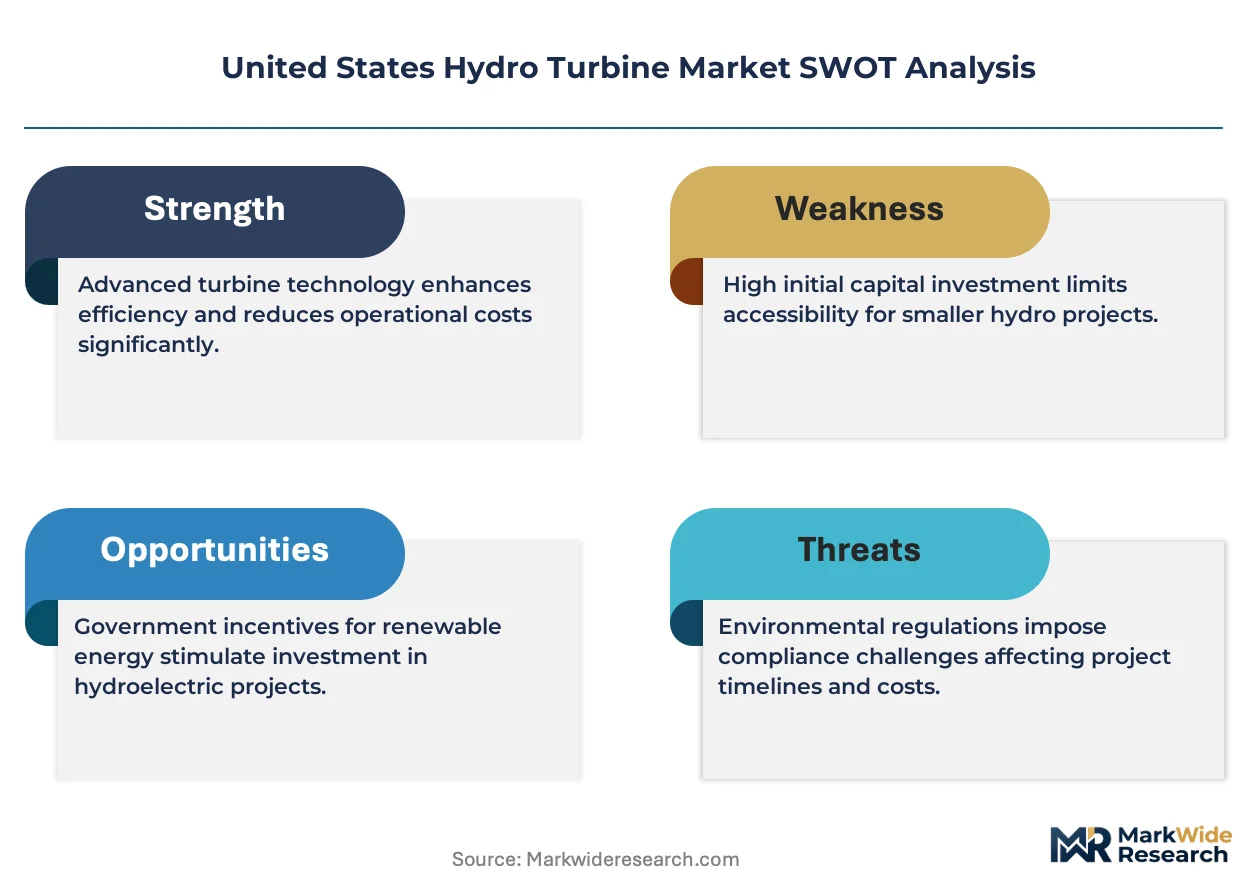
This market consolidates around foundry-backed OEMs as FERC licensing duration filters out capital-light developers unable to carry five-year pre-construction development costs.
For Market Incumbents: Lock in captive forging capacity through exclusive supply agreements with Ohio and Pennsylvania foundries before alloy price volatility escalates. Secure long-term service contracts with Duke Energy and Berkshire Hathaway Energy subsidiaries to entrench replacement part revenue streams against emerging digital twin competitors. For New Entrants and Emerging Players: IRA production tax credits in the United States open a window for closed-loop pumped storage development in Arizona and Nevada transmission corridors. Target agricultural irrigation districts for standardized sub-10 MW modular packages where procurement cycles compress and incumbent service networks remain thin. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized Pelton fabricators in Colorado and Utah as high-head project development stalls under environmental litigation risk. Watch FERC rulemakings on pumped storage market participation as the inflection signal for capital redeployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Runner Casting | Captive forging capacity insulates Voith Hydro and Andritz AG from specialty alloy supply shocks. |
| Digital Twin Service Platform | Predictive maintenance contracts with Duke Energy transfer operational risk and lock in twenty-year revenue. |
| Closed-Loop Pumped Storage Development | Off-stream reservoir configurations in Arizona bypass EPA Section 316(b) fish passage mandates. |
| Grid-Scale Battery Hybridization | Co-located lithium-ion storage with Columbia River facilities captures stacked capacity and ancillary services revenue. |
| Fish-Friendly Turbine Certification | EPA compliance designs with ninety percent passage survival rates open municipal utility procurement in the Northeast. |
Research Methodology
Document review covered FERC licensing databases, EIA generation statistics, and EPA compliance filings, complemented by interviews with utility planning officers, EPC contractors, turbine OEM technical directors, and grid operators across the Pacific Northwest and Southwest corridors. Secondary validation drew from Infrastructure Investment and Jobs Act disbursement records, state renewable portfolio standard filings, and foundry capacity utilization surveys. Bottom-up project pipeline analysis triangulated against top-down utility capital expenditure disclosures.
Installed capacity and revenue outputs reflect segmentation across turbine technology type, application scale, and regional hydrological zone, with growth trajectories modeled across the projection horizon. CAGRs derived from utility procurement timeline analysis, FERC relicensing queue projections, and IRA incentive uptake curves. Variable-speed generator penetration rates and closed-loop pumped storage permitting velocity served as key forecast inputs.
The model assumes a particular technology adoption path for full-converter interfaces; alternative pathways for synchronous condenser retrofits would alter the outlook. Forecasts reflect assumptions on FERC rulemaking timelines and EPA compliance deadline extensions. A small set of triggers—environmental litigation outcomes, alloy price spikes, and grid interconnection queue reform—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydropower Systems
Pumped Hydro Storage Market
Hydropower Systems
Global Hydro Turbine Generator Unit Market
Hydropower Systems
South America Pumped Hydro Storage Market
Hydropower Systems
Japan Hydropower Market
Hydropower Systems
Europe Small Hydropower Market
Hydropower Systems
Southeast Asia Hydropower Market
Hydropower Systems
Asia-Pacific Hydropower Market
Hydropower Systems
Hydropower Turbine Market
Hydropower Systems
Tidal Power Market
Hydropower Systems
Asia-Pacific Small Hydropower Market
Hydropower Systems
North America Pumped Hydro Storage Market
Hydropower Systems
Offshore Hydropower Market
Hydropower Systems
United States Hydropower Market
Hydropower Systems
France Tidal Power Market
Hydropower Systems
North America Hydropower Market
Hydropower Systems
South America Hydropower Market