
 Asia-Pacific Hydropower Market | 2026-2036
Asia-Pacific Hydropower Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Hydropower Market Outlook
State-owned utilities across Southeast Asia are rotating procurement toward flexible pumped storage assets as grid operators absorb surging solar and wind capacity. China Yangtze Power Co. Ltd leverages its cascade control over the Yangtze River basin to dominate seasonal dispatch optimization. NTPC Ltd anchors India's expanding pumped storage pipeline with integrated project development across the Himalayan foothills. Tokyo Electric Power Company Holdings, Inc. competes through advanced variable-speed turbine technology exported to ASEAN grid operators.
Hydropower harnesses gravitational energy from flowing or stored water to drive turbine-generator sets, with modern installations exceeding 90% mechanical-to-electrical conversion efficiency at heads above 100 meters. The technology provides baseload power, grid inertia, and black-start capability that battery storage cannot replicate at multi-gigawatt scale. Pumped storage leads technology type deployment as utilities seek daily cycling capacity to absorb midday solar oversupply. Run-of-river occupies stable but lower-margin terrain where environmental licensing constrains greenfield development. Small hydropower differentiates through distributed rural electrification programs that bypass centralized transmission investment.
China's MEE enforces escalating environmental flow requirements under GB standards that reshape dam design and operating protocols across the Mekong tributaries. India's CEA mandates frequency response capabilities that filter out older turbine designs from new procurement tenders. METI in Japan certifies pumped storage efficiency tiers that determine grid access tariffs for private developers. Stakeholders must monitor how evolving water allocation compacts between downstream riparian states constrain project siting across transboundary river systems.
Market Dynamics
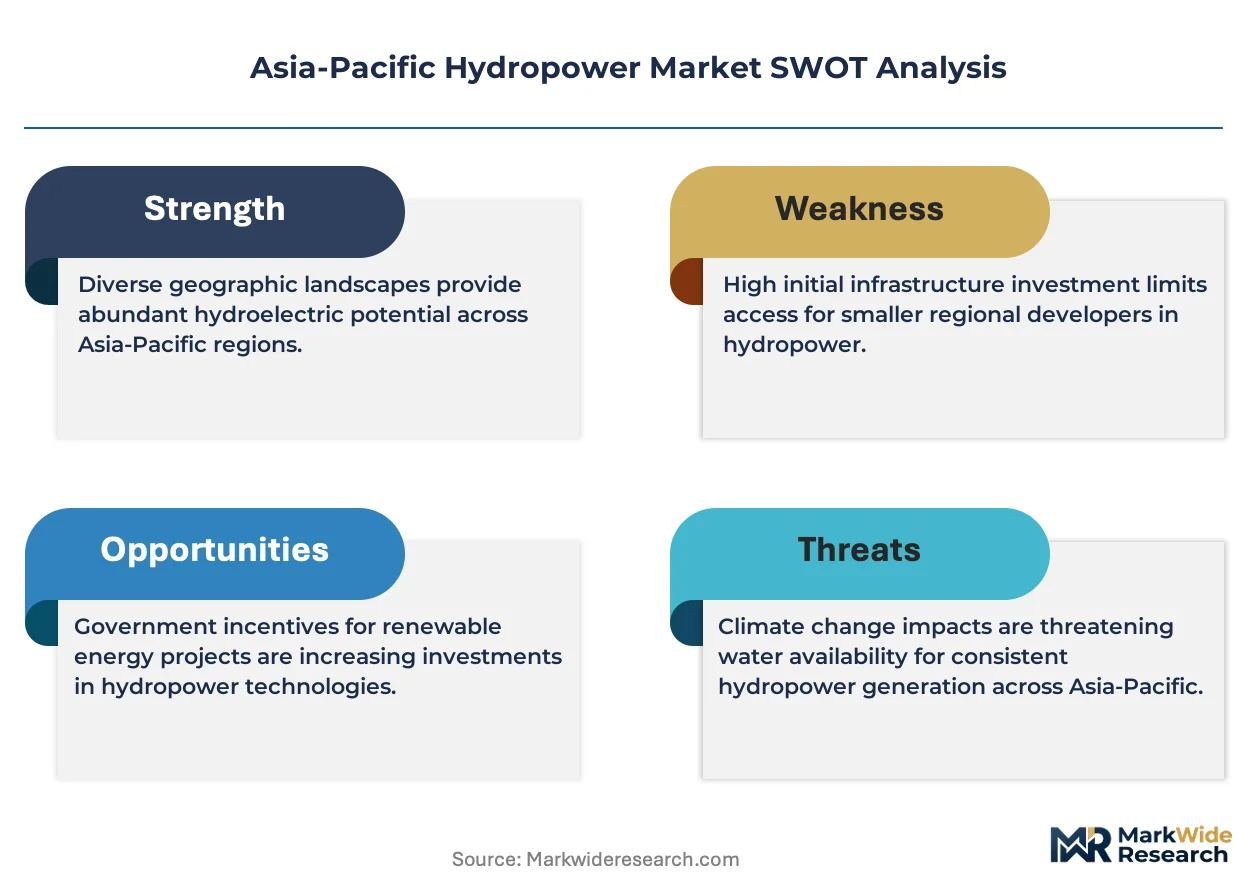
State-owned utilities across Southeast Asia are accelerating pumped storage procurement to balance grid volatility from solar and wind integration. China's MEE environmental flow mandates and India's CEA frequency response requirements are reshaping equipment specifications and project economics simultaneously.
Growth Catalysts
- CEA Frequency Mandates:India's Central Electricity Authority requires modern turbine governors capable of primary frequency response, filtering obsolete designs from new procurement tenders and creating replacement demand across existing fleets.
- Archipelago Electrification:Indonesia's state utility PLN targets distributed small hydropower installations across 17,000 islands to bypass transmission infrastructure gaps and reach remote load centers.
- Variable-Speed Turbines:Advanced pump-turbine designs with doubly-fed induction generators enable 30% faster ramp rates than fixed-speed units, matching ASEAN grid operator requirements for solar balancing services.
Market Restraints
- Environmental Licensing Friction:China's GB 3838 surface water quality standards and MEE fish passage mandates extend permitting timelines for greenfield projects on Yangtze tributaries by 18-36 months.
- Steel and Cement Input Volatility:Dam construction faces concentrated exposure to Chinese steel rebar and Portland cement prices, with hydropower civil works representing 60-70% of total project capex.
- Transboundary Water Allocation:Mekong River Commission coordination gaps between Laos, Cambodia, and Vietnam constrain cascade development on shared tributaries where downstream riparian rights remain unresolved.
Strategic Opportunities
- Philippines Off-Grid Islands:The archipelago's 7,000+ unelectrified islands present distributed run-of-river deployment potential where diesel replacement economics favor small-scale hydro despite higher unit costs.
- Japan METI Efficiency Tiers:Japan's Agency for Natural Resources and Energy certifies pumped storage round-trip efficiency bands that determine grid access tariffs, creating premium positioning for technology leaders.
- Digital Twin Convergence:Integration of computational fluid dynamics with real-time sensor arrays enables predictive maintenance contracts that extend turbine runner life and capture aftermarket revenue streams.
Industry Challenges
- Geotechnical Specialist Scarcity:Tunnel boring machine operators and underground cavern engineers command 40% wage premiums across Himalayan and Southeast Asian project sites where complex geology dominates.
- Legacy SCADA Integration:Grid operators in Vietnam and Indonesia struggle to synchronize new variable-speed pumped storage units with 1980s-era control systems that lack IEC 61850 communication protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Hydropower Market |
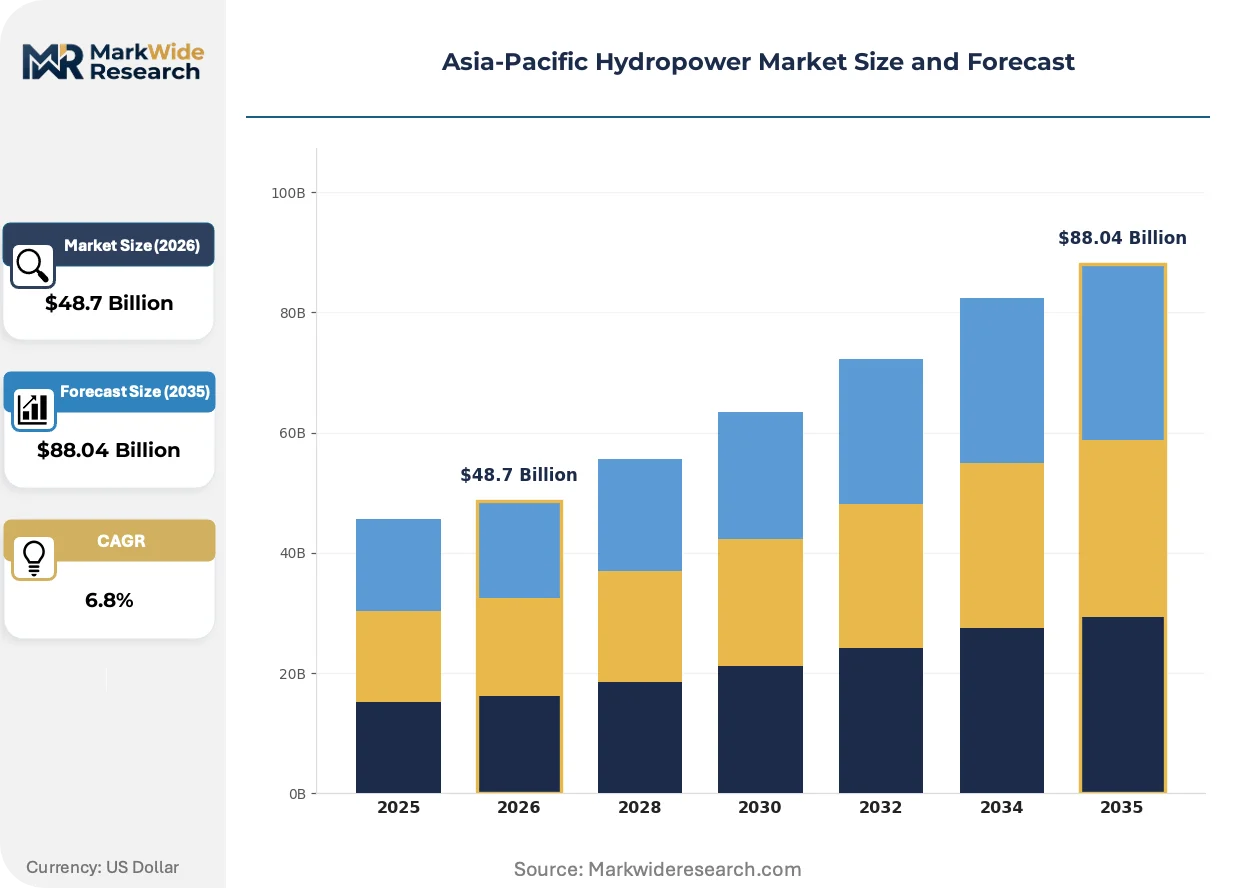
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology Type: Run-of-River, Pumped Storage, Small Hydropower, Conventional Hydropower Application Area: Electricity Generation, Agricultural Irrigation, Water Supply, Flood Control End User: Utilities, Government Agencies, Industrial Sector, Residential Users Installation Type: Greenfield, Brownfield, Retrofitting, Rehabilitation |
| Companies Covered | China Yangtze Power Co. Ltd, PowerChina, NTPC Ltd, NHPC Ltd, Tokyo Electric Power Company Holdings, Inc., Electricity Generating Authority of Thailand, PT Perusahaan Listrik Negara, Tenaga Nasional Berhad, Sinohydro Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Hydropower Market Strategic Shifts
Digitalization and modularization are compressing project development cycles while environmental compliance technologies reshape civil engineering specifications across the Asia-Pacific basin.
Modular compact turbine-generator packages are miniaturizing. These containerized units integrate Francis or Pelton runners with permanent magnet generators for sub-10 MW deployments. Remote utilities in Papua New Guinea and the Solomon Islands are adopting skid-mounted systems that reduce installation time from 18 months to 8 weeks. The technology is miniaturizing capital barriers for distributed rural electrification programs that previously required centralized procurement.
China's MEE is enforcing escalating environmental flow requirements under GB standards that reshape dam design and operating protocols across the Mekong tributaries. Fish-friendly turbine runners and aerating weir structures are becoming mandatory for new concessions. Developers in Yunnan and Sichuan provinces are responding with computational fluid dynamics-optimized blade profiles that maintain efficiency above 88% while reducing fish mortality.
Utility procurement departments are consolidating vendor relationships around integrated EPC contractors capable of delivering civil works, electromechanical equipment, and digital control systems under single accountability. State-owned operators in Thailand and Malaysia are displacing fragmented multi-contractor models that created interface risk and schedule overruns. This concentration is most visible in Vietnam's EVN tendering, where integrated bids now capture 80% of awarded capacity.
Asia-Pacific Hydropower Market Segmentation
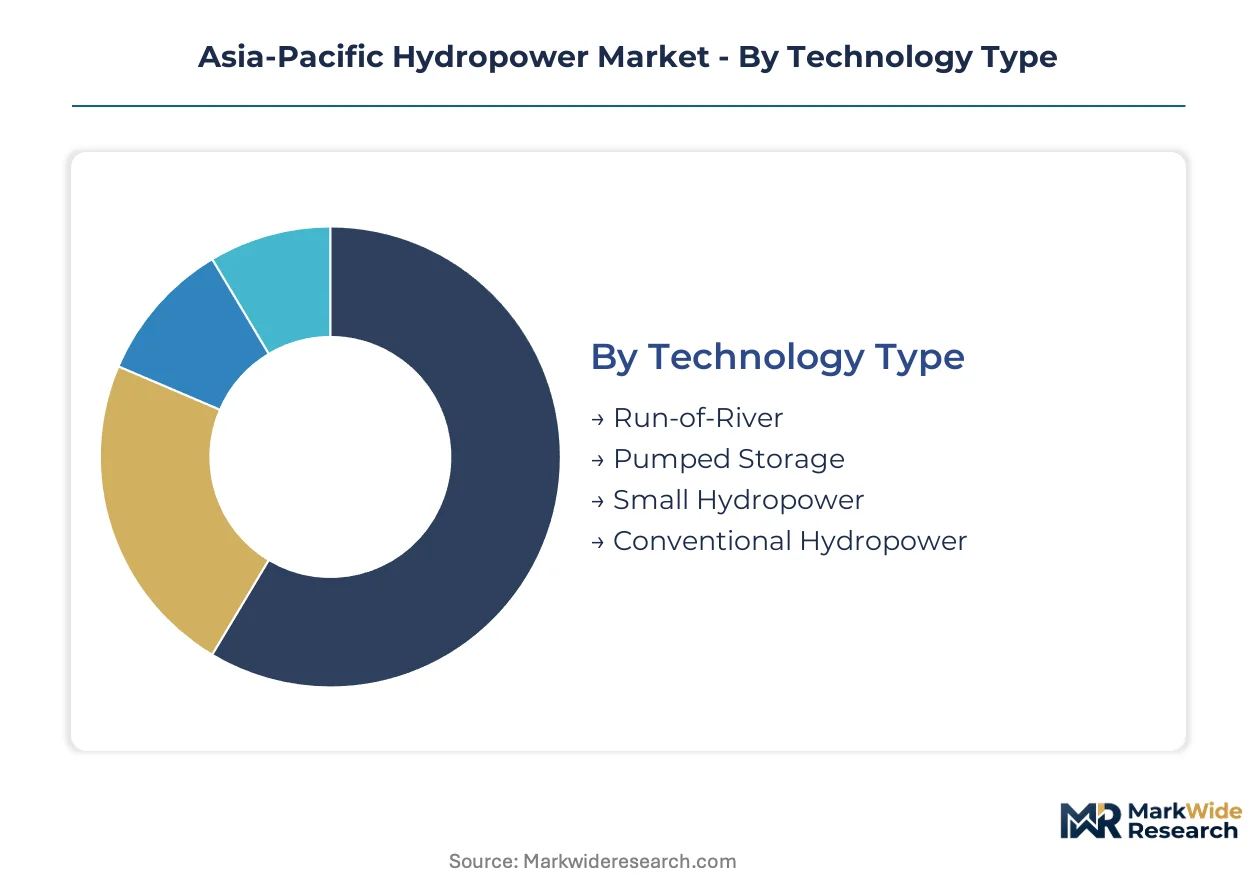
Technology choices in Asia-Pacific hydropower are hardening around grid services rather than raw generation capacity. Regulatory mandates on frequency response and environmental flow are filtering which segments can access state procurement budgets across China, India, and Southeast Asian markets.
Technology Type:
China's MEE environmental flow standards and India's CEA frequency mandates are segmenting equipment eligibility by technical capability rather than cost alone.
- Pumped Storage:Reversible pump-turbine systems with variable-speed doubly-fed induction generators enable rapid ramping to absorb solar oversupply. State utilities in Thailand, Vietnam, and Indonesia are concentrating procurement here as grid balancing requirements tighten under renewable integration targets.
- Run-of-River:Diversion structures without large impoundments operate on natural flow regimes, making them eligible for streamlined permitting under China's GB standards where environmental licensing constrains reservoir projects. Development clusters along the Mekong tributaries in Laos and Yunnan province are driving deployment.
- Small Hydropower:Distributed sub-10 MW installations bypass transmission infrastructure gaps across Indonesia's 17,000 islands and the Philippines' unelectrified archipelago clusters.
- Conventional Hydropower:Large reservoir projects face extended permitting timelines under MEE fish passage mandates and transboundary water allocation disputes on the Mekong.
Pumped Storage handles the majority of throughput; Small Hydropower is expanding most quickly on share.
Application Area:
Revenue concentration follows power market liberalization progress, with electricity generation commanding premium equipment specifications while non-power applications absorb lower-margin civil works capacity.
- Electricity Generation:Grid-connected turbine-generator sets exceeding 90% mechanical-to-electrical conversion efficiency at heads above 100 meters. China's Yangtze cascade and India's Himalayan foothills projects anchor demand as CEA mandates filter obsolete turbine designs from new tenders.
- Flood Control:Multi-purpose dams with gated spillways manage monsoon variability across Vietnam's Mekong Delta and Bangladesh's Brahmaputra basin. Seasonal storage operations prioritize water retention over energy revenue during peak flood risk windows.
- Agricultural Irrigation:Diversion weirs and canal systems in India's Punjab and Haryana states integrate small hydro units where water delivery obligations constrain power market participation.
- Water Supply:Urban water security projects in Australia's Snowy Mountains and Japan's Kanto region leverage existing dam infrastructure for dual-use energy recovery.
Electricity Generation captures the dominant revenue position; Flood Control is climbing the fastest on policy-driven infrastructure allocation.
End User:
Procurement authority determines technology access, with state-backed utilities capturing integrated EPC contracts while fragmented industrial users face equipment standardization barriers.
- Utilities:State-owned operators in China, India, Thailand, and Vietnam consolidate vendor relationships around single-accountability contractors capable of delivering civil works, electromechanical equipment, and digital control systems.
- Industrial Sector:Captive power consumers in Vietnam's northern manufacturing zones and Indonesia's smelter islands deploy small hydro where grid extension costs exceed distributed generation premiums.
- Government Agencies:Irrigation departments and water resource bureaus in India and China control multi-purpose project concessions that subordinate power revenue to water allocation priorities.
- Residential Users:Micro-hydro cooperatives in Nepal's hill districts and Papua New Guinea's highlands operate outside formal procurement frameworks with limited equipment standardization.
Utilities dominate installed capacity; Industrial Sector is gaining share fastest on captive power economics.
Installation Type:
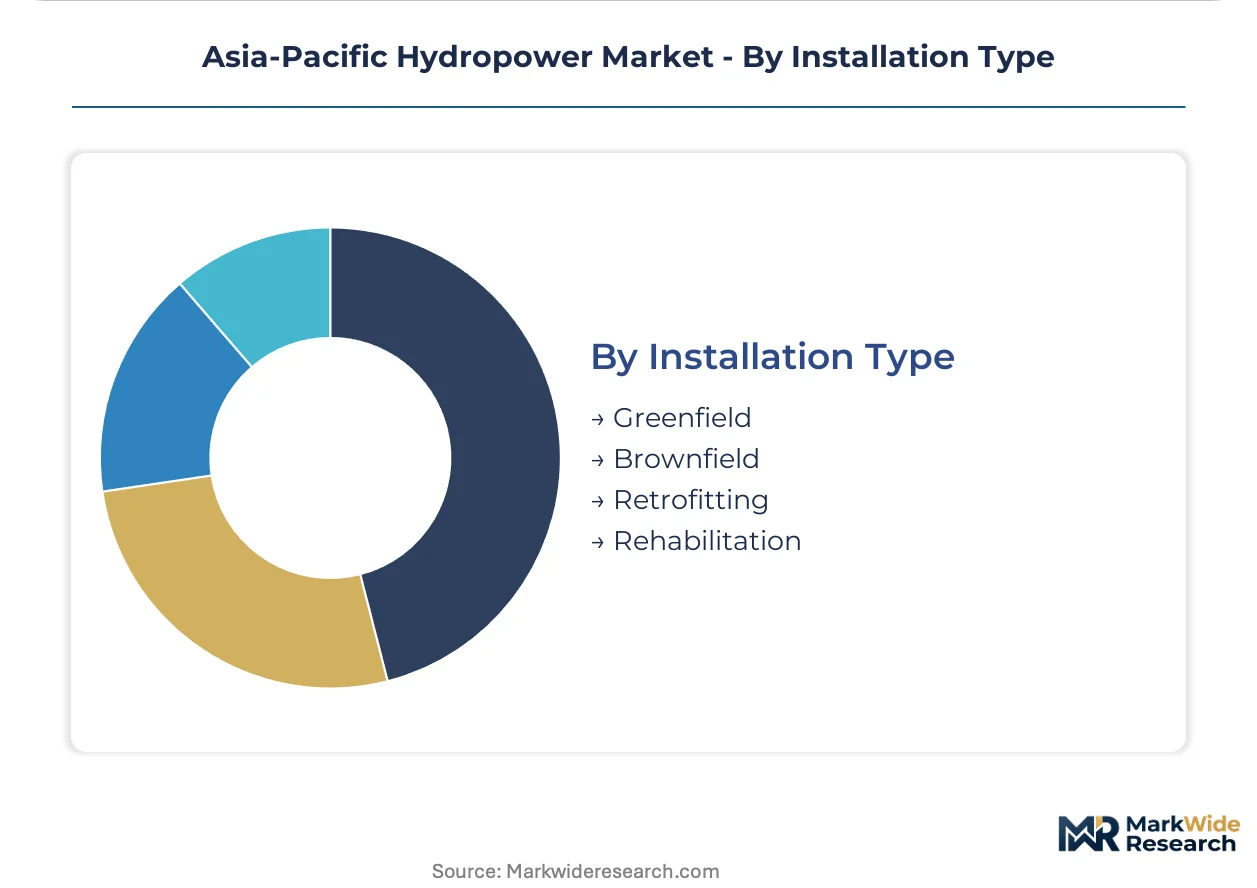
Site availability and grid connection infrastructure are shifting developer preference toward existing asset modification rather than greenfield construction.
- Retrofitting:Turbine runner replacements and generator upgrades on 1980s-era installations in Japan and South Korea restore efficiency to CEA-compliant levels without new civil works.
- Brownfield:Capacity additions at existing dam sites in China's Sichuan and Yunnan provinces exploit permitted impoundments while MEE environmental reviews constrain new reservoir approvals.
- Greenfield:New developments concentrate in Indonesia's outer islands and the Philippines where transmission infrastructure gaps justify distributed run-of-river construction despite higher unit costs.
- Rehabilitation:Structural repairs and spillway modifications on aging concrete dams across Australia's Murray-Darling basin extend asset life under revised safety standards.
Retrofitting handles the majority of current activity; Brownfield is expanding most quickly on permitting risk mitigation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The China-Laos Railway corridor underwrites mainland Southeast Asia's integration into Yunnan province's power trading architecture. This infrastructure asset channels equipment flows and technical standards across the Mekong basin.
China
Yunnan and Sichuan provinces host cascade developments on the Jinsha and Yalong rivers where MEE environmental flow mandates under GB standards reshape dam operating protocols. The dual carbon goals accelerate pumped storage procurement to absorb solar oversupply from the western deserts. Chengdu and Kunming anchor manufacturing clusters for turbine runners and digital control systems serving domestic and export markets.
India
Himalayan foothill states of Himachal Pradesh and Uttarakhand concentrate run-of-river and pumped storage pipelines where CEA frequency response requirements filter obsolete turbine designs. The PLI scheme for clean energy manufacturing redirects domestic supply chains toward higher-efficiency equipment. NTPC Ltd anchors integrated project development across these sub-Himalayan corridors.
Japan
The Kanto and Kansai regions maintain legacy pumped storage assets where METI efficiency tier certifications determine grid access tariffs for private developers. Variable-speed turbine technology from domestic suppliers exports to ASEAN grid operators seeking solar balancing capability. Tokyo Electric Power Company Holdings, Inc. competes through advanced governor systems.
Vietnam
The Mekong Delta water management projects concentrate state utility procurement where EVN tendering now favors integrated EPC contractors over fragmented multi-contractor models. Transboundary water allocation disputes with downstream riparian states constrain cascade development on shared tributaries. Ho Chi Minh City anchors electromechanical equipment import and distribution.
Indonesia
PLN targets distributed small hydropower installations across 17,000 islands to bypass transmission infrastructure gaps and reach remote load centers. Archipelago electrification programs favor containerized turbine-generator packages that reduce installation timelines. Java and Sumatra anchor manufacturing and technical service capabilities for outer island deployment.
Asia-Pacific Hydropower Market Competitive Environment
Concentration sits with state-backed utilities and integrated EPC contractors that control civil works, electromechanical equipment, and digital systems under single accountability. The vendor base organizes around three archetypes: river basin operators with cascade control advantages, national construction conglomerates with civil engineering scale, and technology specialists with variable-speed turbine capabilities. Competitive moves center on integrated EPC contract consolidation and efficiency certification positioning under national regulator tier systems.
Among Chinese state-owned enterprises, China Yangtze Power Co. Ltd and Sinohydro Corporation exemplify the integrated basin-operator archetype, while PowerChina occupies a position spanning construction and equipment manufacturing. India's NTPC Ltd and NHPC Ltd represent the utility-led development model with captive project pipelines. Tokyo Electric Power Company Holdings, Inc. anchors the technology-export tier serving ASEAN grid modernization requirements.
| Leading Market Players |
|---|
| China Yangtze Power Co. Ltd |
| PowerChina |
| NTPC Ltd |
| NHPC Ltd |
| Tokyo Electric Power Company Holdings, Inc. |
| Electricity Generating Authority of Thailand |
| PT Perusahaan Listrik Negara |
| Tenaga Nasional Berhad |
| Sinohydro Corporation |
| Others |
Value Chain & Pricing Dynamics
China's MEE environmental flow certifications under GB standards gate both equipment supplier qualification and project bid price tiers simultaneously, compressing margins for uncertified turbine runners while awarding premium positioning to CFD-optimized designs that meet fish-passage mandates. State utilities in Thailand and Vietnam translate these technical thresholds into three-band procurement scoring where compliance weighting overrides pure cost competition.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs electromechanical equipment procurement, with variable-speed pump-turbine units commanding spreads over fixed-speed alternatives based on METI efficiency certification tiers and CEA frequency response compliance. Price differentiation hinges on turbine runner efficiency grades above 88% and bundled digital control system integration. Cost compression in the standard tier is intensifying because integrated EPC contractors consolidate vendor relationships and squeeze fragmented equipment-only suppliers. Captive power consumers in Vietnam's manufacturing zones exhibit highest price sensitivity, while Japan's METI-certified developers demonstrate lowest sensitivity due to grid access tariff premiums.
Supply Chain Analysis
Extended lead times for tunnel boring machine components and Francis runner castings stretch project schedules across Himalayan and Southeast Asian sites where geotechnical complexity dominates. Manufacturing concentration rests on China for steel rebar and Portland cement, Japan for variable-speed turbine technology, and India for generator windings under PLI scheme incentives. Raw material dependencies draw from Chinese steel rebar, specialized turbine blade alloys, and high-grade concrete aggregates. Single-source vulnerability concentrates in TBMs and underground cavern engineering expertise commanding wage premiums. Distribution runs through state utility procurement departments consolidating integrated EPC contracts under single accountability frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery storage cost curves and grid-scale lithium deployment threaten hydropower's historical dominance in frequency response and black-start services, forcing incumbents to defend through operational flexibility advantages that electrochemical alternatives cannot replicate at multi-gigawatt scale.
For Market Incumbents: Fortify cascade control advantages across river basin systems by digitizing seasonal dispatch optimization and securing environmental flow certification ahead of MEE enforcement escalations. Deepen backward integration into computational fluid dynamics-optimized runner manufacturing to capture efficiency tier premiums. Defend against battery storage substitution by emphasizing pumped storage's multi-hour duration capability and grid inertia services. For New Entrants and Emerging Players: Aftermarket digital twin services for predictive turbine maintenance represent the most penetrable service-layer gap where incumbent OEMs under-serve aging installations in Japan and South Korea. Target rehabilitation and retrofitting segments in Australia's Murray-Darling basin where dam safety standards drive structural upgrade demand. Enter through IEC 61850 protocol integration contracts that synchronize new variable-speed units with legacy SCADA systems in Vietnam and Indonesia. For Investors and Strategic Acquirers: India's CEA frequency mandate reshapes the acquisition landscape toward turbine governor technology specialists capable of primary response compliance. Long-term viability centers on assets with permitted impoundments and existing environmental clearances that bypass MEE review timelines. Monitor transboundary water allocation compact negotiations between Mekong riparian states as the critical inflection signal for cascade development risk repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated EPC Contract Consolidation | State utilities in Thailand and Vietnam displace fragmented multi-contractor models that created interface risk. |
| Variable-Speed Turbine Technology Licensing | Tokyo Electric Power Company Holdings exports advanced governor systems to ASEAN grid operators seeking solar balancing. |
| Digital Twin Predictive Maintenance Platform | CFD-sensor array integration extends turbine runner life and captures recurring aftermarket revenue streams. |
| Environmental Flow Certification Program | China's MEE GB standards compliance gates project eligibility and price tier positioning across Mekong tributaries. |
| Pumped Storage Capacity Buildout | NTPC Ltd anchors India's Himalayan pipeline as CEA mandates filter obsolete designs from new procurement tenders. |
Study Parameters
Initial hypotheses were tested against primary input from utility planning officers, EPC project directors, turbine OEM technical leads, and grid operator dispatch managers and refined through secondary validation against FERC filings, IEA hydropower databases, MEE environmental compliance registries, and project development tracking systems. Bottom-up installation data triangulated with top-down regulatory flow analysis to reconcile capacity announcements with permitting timelines.
Variance decomposition across technology type, project scale tier, and regulatory framework clusters shaped the projection horizon. CAGRs derived from segmented growth rate reconciliation between equipment shipment data and utility procurement budget trajectories. Forecast inputs incorporated MEE environmental flow mandate enforcement schedules, CEA frequency response compliance deadlines, and METI efficiency tier certification adoption curves.
Underlying assumptions cover continued state utility procurement centralization, steel and cement price stabilization, and transboundary water compact status quo, with deviation risk concentrated in environmental licensing timeline extensions and geotechnical complexity cost overruns. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydropower Systems
Underground Hydro Power Plant Market
Hydropower Systems
Europe Small Hydropower Market
Hydropower Systems
North America Hydropower Market
Hydropower Systems
Whirlpool Turbine Market
Hydropower Systems
Hydropower Generation Market
Hydropower Systems
Hydropower Market
Hydropower Systems
Southeast Asia Hydropower Market
Hydropower Systems
United States Hydro Turbine Market
Hydropower Systems
Europe Hydropower Market
Hydropower Systems
Floating Power Plant Market
Hydropower Systems
Asia-Pacific Small Hydropower Market
Hydropower Systems
United States Hydropower Market
Hydropower Systems
South America Hydropower Market
Hydropower Systems
Pumped Hydro Storage Market
Hydropower Systems
South America Pumped Hydro Storage Market
Hydropower Systems
North America Pumped Hydro Storage Market