
 Underground Hydro Power Plant Market | 2026-2036
Underground Hydro Power Plant Market Size, Share, and Industry Trends Forecast 2026-2036
Underground Hydro Power Plant Market Analytics
IEC 61850 certification for substation automation and communication is redrawing competitive boundaries in underground hydro deployment. Andritz Hydro GmbH leverages its Austrian manufacturing heritage to dominate high-head Francis turbine supply. Voith Hydro GmbH & Co. KG anchors German engineering standards across European cavern power station projects. General Electric Company competes through integrated digital controls that bridge underground generation with grid synchronization.
An underground hydro power plant situates turbines, generators, and auxiliary systems within excavated caverns or tunnels beneath mountainous terrain, typically achieving hydraulic heads exceeding 200 meters through penstock configurations that surface plants cannot replicate. The primary purpose centers on harnessing gravitational water pressure for baseload electricity while minimizing surface land use and environmental visibility. Pumped storage installations command the fastest expansion trajectory as grid operators seek multi-gigawatt-hour storage reservoirs. Francis turbine technology leads installed capacity due to its operational flexibility across variable head conditions. Small and medium scale projects attract development capital where transmission infrastructure remains limited and community-scale generation satisfies localized demand.
The European Union's F-Gas Regulation and Water Framework Directive constrain coolant selections and aquatic ecosystem impacts, pushing developers toward closed-loop underground designs that eliminate surface reservoir requirements. China's MEE enforces environmental impact assessments that favor subterranean construction in protected watershed regions. Switzerland's Federal Office of Energy maintains stringent geological stability protocols that shape cavern engineering specifications. Stakeholders must monitor evolving carbon border adjustment mechanisms and their interaction with embedded concrete emissions from tunnel construction.
Market Dynamics
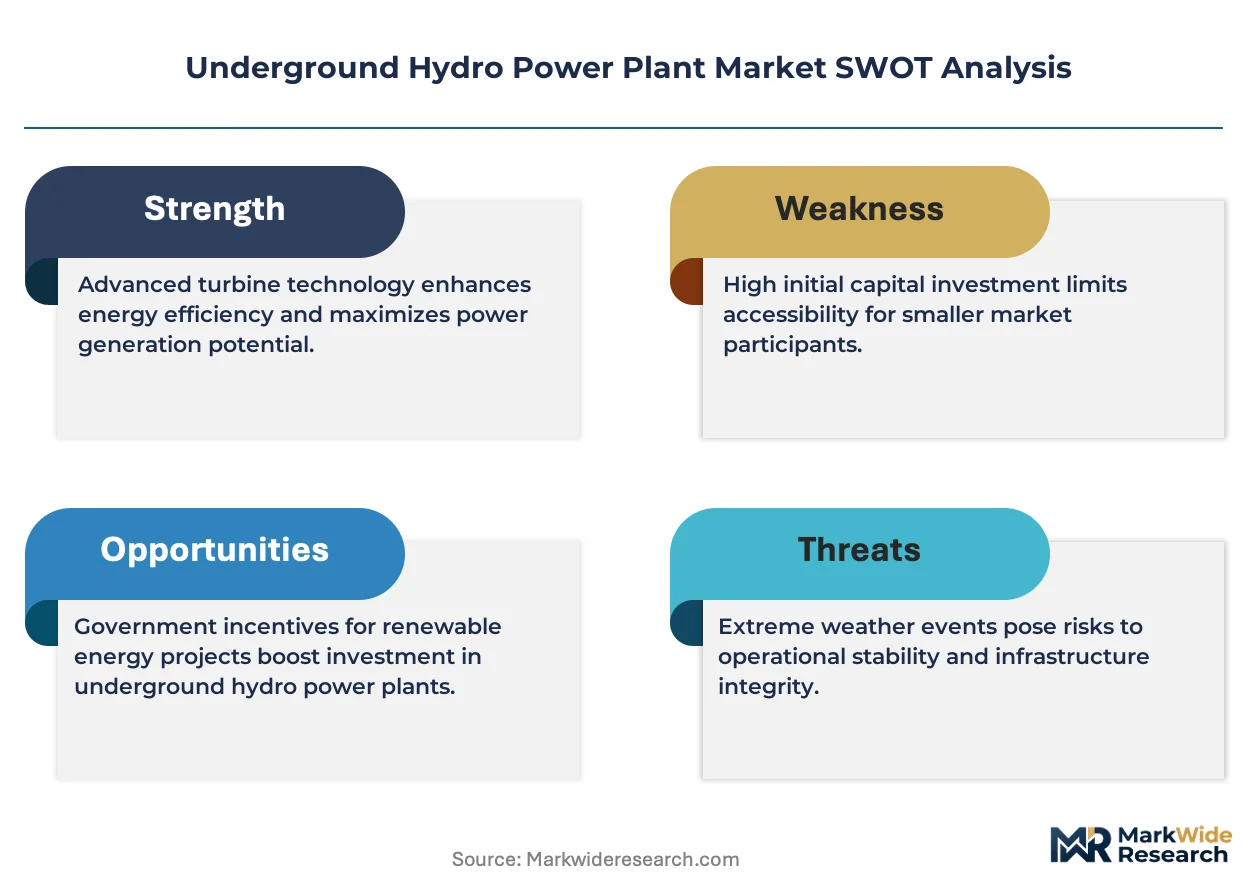
Grid balancing mandates from transmission operators are compressing project development timelines for pumped storage caverns, forcing developers to front-load geological risk assessments before regulatory filing.
Growth Catalysts
- Pumped Storage Expansion:Utility companies in Switzerland, Austria, and Norway are advancing multi-gigawatt-hour reservoir projects to stabilize intermittent renewable generation.
- F-Gas Regulation:The European Union's phase-down of fluorinated greenhouse gases eliminates conventional surface cooling systems, accelerating approvals for closed-loop underground designs.
- Dual Carbon Goals:China's MEE enforcement of environmental impact assessments in protected watersheds favors subterranean construction methods that minimize surface ecological disruption.
Market Restraints
- Specialized Tunneling Equipment:Concentration of hard-rock boring machine suppliers in Germany and Japan creates procurement bottlenecks for projects in remote mountain corridors.
- Geological Uncertainty:Unmapped fault lines and variable rock mechanics in Alpine terrain generate cost overruns exceeding 30 percent on cavern excavation contracts.
- Long-Duration Lithium-Ion:Battery storage systems with four-hour discharge capability are capturing frequency regulation contracts that underground pumped storage previously dominated.
Strategic Opportunities
- Small-Scale Deployment:Community-scale projects between 5 and 50 megawatts in Peru, Colombia, and Ecuador address transmission gaps in the Andean spine.
- IEC 61850 Integration:Substation automation standards enable digital twin monitoring of underground cavern conditions, reducing unplanned maintenance intervals.
- Carbon Border Adjustment:Embedded emissions accounting for tunnel concrete and steel creates competitive advantage for developers with verified low-carbon supply chains.
Industry Challenges
- Geotechnical Expertise Scarcity:Engineering firms with cavern stability modeling capability number fewer than twelve worldwide, stretching project staffing timelines.
- IEC Certification Delays:Substation communication protocol validation requires 14-18 months of interoperability testing before grid connection approval.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Underground Hydro Power Plant Market |
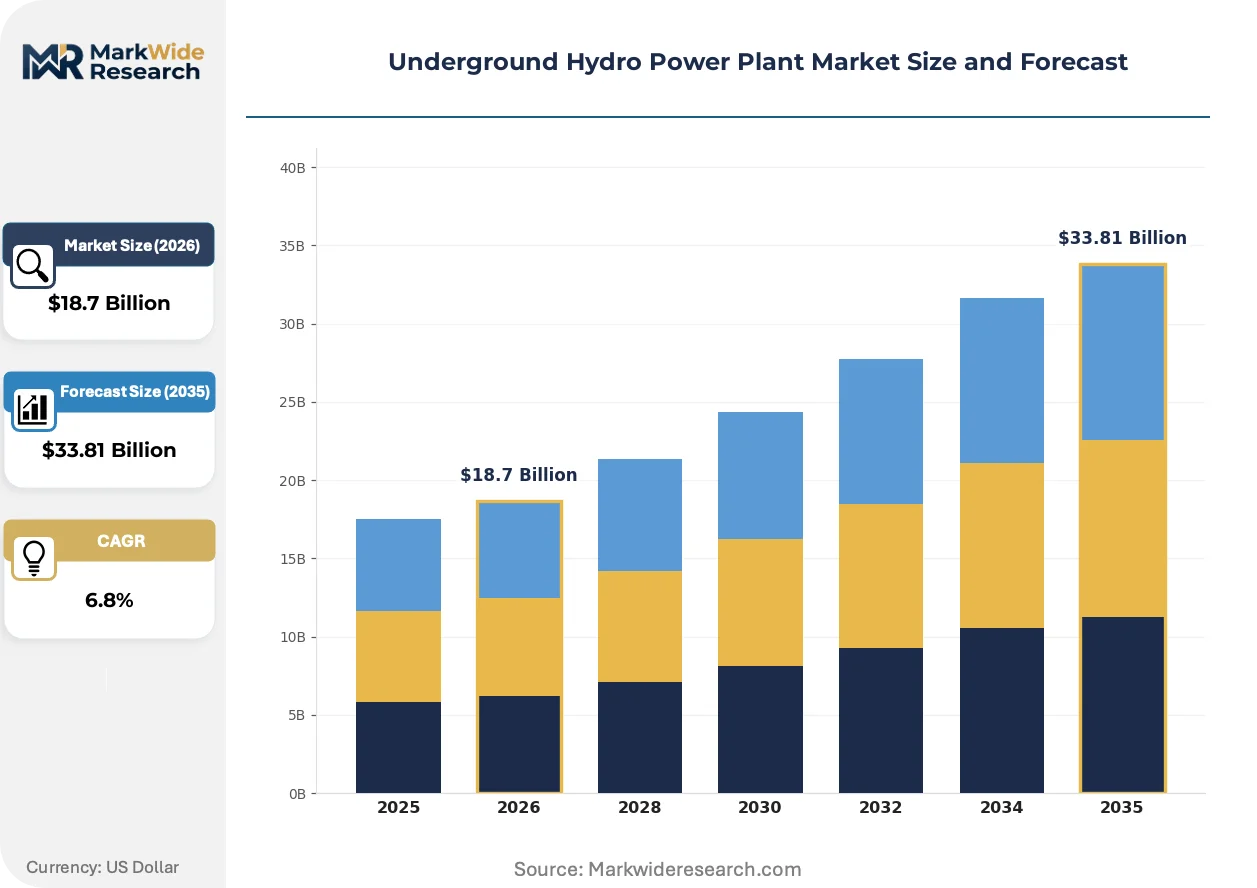
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Francis Turbine, Pelton Turbine, Turbine Generator, Pumped Storage Capacity: Small Scale, Medium Scale, Large Scale, Extra Large Scale Installation Type: Greenfield, Brownfield, Retrofit, Modular End User: Utility Companies, Industrial Users, Government, Renewable Energy Firms |
| Companies Covered | AECOM, Nalcor Energy, The Churchill Falls (Labrador) Corporation, Tokyo Electric and Power Company (TEPCO), Meridian Energy Limited, Andritz Hydro GmbH, General Electric Company, Voith Hydro GmbH & Co. KG, Siemens Energy AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Underground Hydro Power Plant Market Evolving Landscape
Digitalization of underground asset monitoring is compressing maintenance windows while enabling predictive interventions in inaccessible cavern environments.
Variable-speed Francis turbine technology is miniaturizing generator-motor units for medium-head applications previously served by fixed-speed configurations. Alpine utilities in Switzerland and Austria are retrofitting existing caverns with these compact units to extend operational range across 150-400 meter head variations. Equipment footprint reduction is miniaturizing auxiliary system layouts, freeing cavern volume for expanded transformer housing or control room automation.
The European Union's F-Gas Regulation imposes strict phase-down schedules on hydrofluorocarbon coolants used in underground transformer and generator systems. Developers are retrofitting existing facilities with natural ester fluids and sealed gas-insulated switchgear to maintain operating permits. Swiss and Norwegian projects face the steepest compliance curves due to earlier regulatory adoption timelines and existing facility density.
After-sales service unbundling is fragmenting long-term maintenance contracts that previously bundled turbine overhaul, generator rewinding, and control system updates. Alpine utility operators are negotiating discrete service modules with specialized regional contractors, particularly for penstock integrity inspection and wicket gate refurbishment. This disaggregation is most pronounced in Switzerland, where cantonal power authorities maintain in-house electrical expertise but outsource mechanical rehabilitation to Bavarian and Lombard specialists.
Underground Hydro Power Plant Market Segmentation
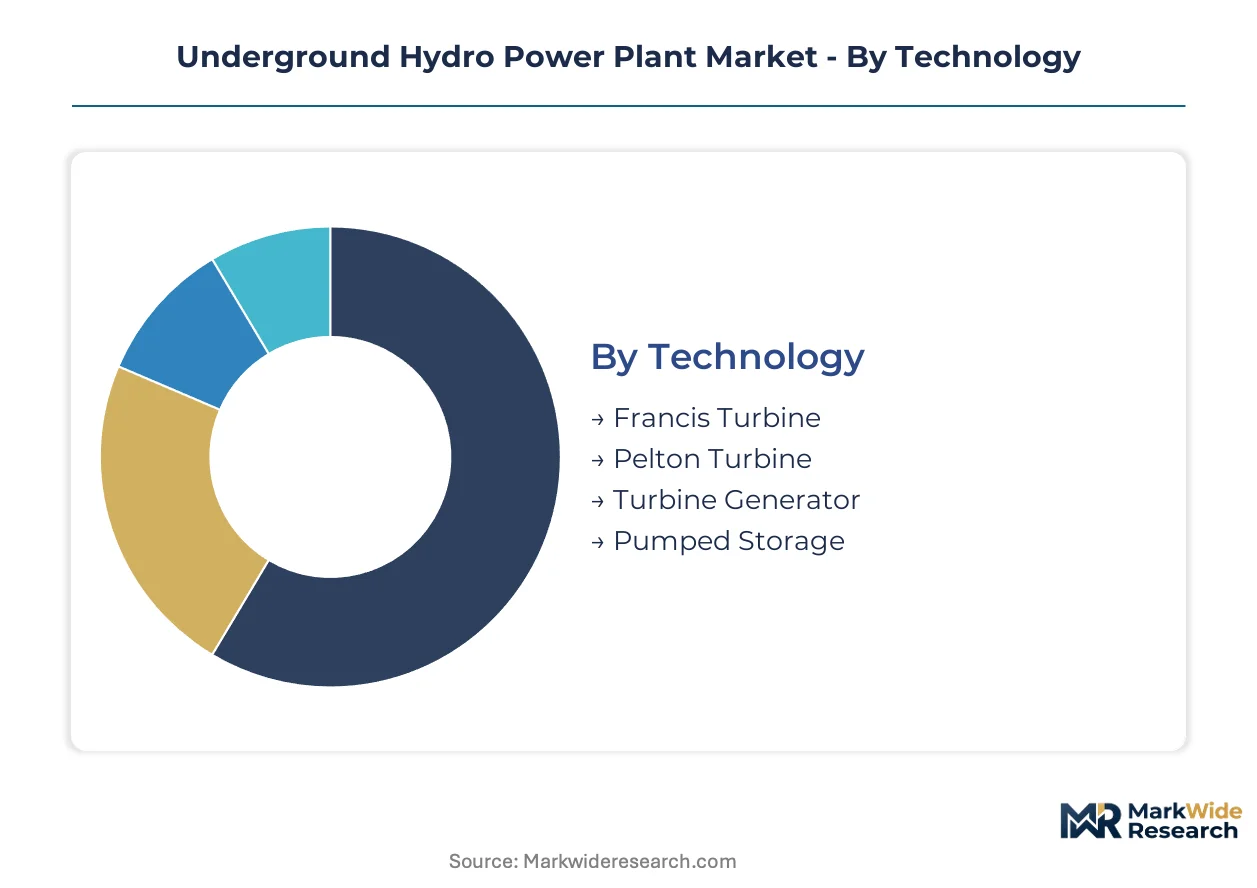
Underground hydro power plant segmentation reveals distinct procurement patterns across technology maturity and project scale. Developers align turbine selection with hydraulic head profiles while capacity tiers determine financing structures and regulatory pathways.
Technology:
Francis and Pelton turbine deployments concentrate in domestic Alpine markets where established supply chains serve regional utilities. Pumped storage installations increasingly target export-led configurations for grid operators balancing intermittent renewables across European transmission networks.
- Francis Turbine:Variable-speed generator-motor units now dominate medium-head applications between 150 and 400 meters. Swiss and Austrian utilities retrofit existing caverns with compact Francis configurations to extend operational range across fluctuating reservoir levels.
- Pumped Storage:Multi-gigawatt-hour reservoir projects command the steepest expansion trajectory as transmission operators mandate grid balancing capacity. China's MEE environmental assessments favor subterranean pumped storage in protected watersheds to minimize surface ecological disruption.
- Pelton Turbine:High-head impulse designs exceeding 500 meters suit Alpine corridor geology with steep penstock gradients.
- Turbine Generator:Integrated units reduce cavern footprint requirements for constrained excavation volumes.
Francis turbine technology commands the established base. The steepest expansion runs through pumped storage installations.
Capacity:
Cost tier stratification separates community-scale projects with simplified permitting from capital-intensive extra-large developments requiring decade-long construction timelines.
- Large Scale:Projects above 100 megawatts anchor baseload generation for national grids. Norwegian and Swiss utilities concentrate development in geological corridors with proven rock stability and existing transmission infrastructure.
- Small Scale:Five to fifty megawatt installations address transmission gaps in Andean regions. Peruvian and Colombian developers leverage modular tunneling approaches to reduce upfront capital exposure in remote terrain.
- Medium Scale:Fifty to one hundred megawatt configurations balance economies of scale with manageable geological risk profiles.
- Extra Large Scale:Multi-hundred megawatt complexes require dedicated hard-rock boring machine procurement from German and Japanese suppliers.
Large scale projects command the established base. The steepest expansion runs through small scale deployments.
Installation Type:
Application maturity varies sharply between proven brownfield approaches in Alpine corridors and experimental modular systems targeting standardized deployment.
- Greenfield:New cavern excavation in virgin geological formations carries 30 percent cost overrun risk from unmapped fault lines. Swiss Federal Office of Energy protocols mandate extensive pre-construction stability modeling.
- Retrofit:Existing cavern refurbishment extends asset life without new tunneling exposure. Alpine utilities unbundle maintenance contracts, sourcing mechanical rehabilitation from Bavarian and Lombard specialists while retaining in-house electrical expertise.
- Brownfield:Expansion of previously excavated sites reduces geological uncertainty through documented rock mechanics.
- Modular:Factory-assembled components compress on-site construction windows for remote mountain corridors.
Greenfield installations command the established base. The steepest expansion runs through retrofit configurations.
End User:
Customer type determines risk tolerance and financing structure, with utility companies absorbing long construction timelines that industrial users reject.
- Utility Companies:Grid operators in Switzerland, Austria, and Norway advance multi-gigawatt-hour pumped storage to stabilize renewable intermittency. These entities accept 10-15 year development horizons for strategic storage assets.
- Renewable Energy Firms:Wind and solar developers procure co-located underground storage to firm dispatch profiles. European F-Gas Regulation compliance requirements accelerate closed-loop underground designs over conventional surface cooling.
- Industrial Users:Mining and metallurgical operations seek captive generation for energy-intensive processes in remote locations.
- Government:Public infrastructure agencies fund strategic storage for national energy security objectives.
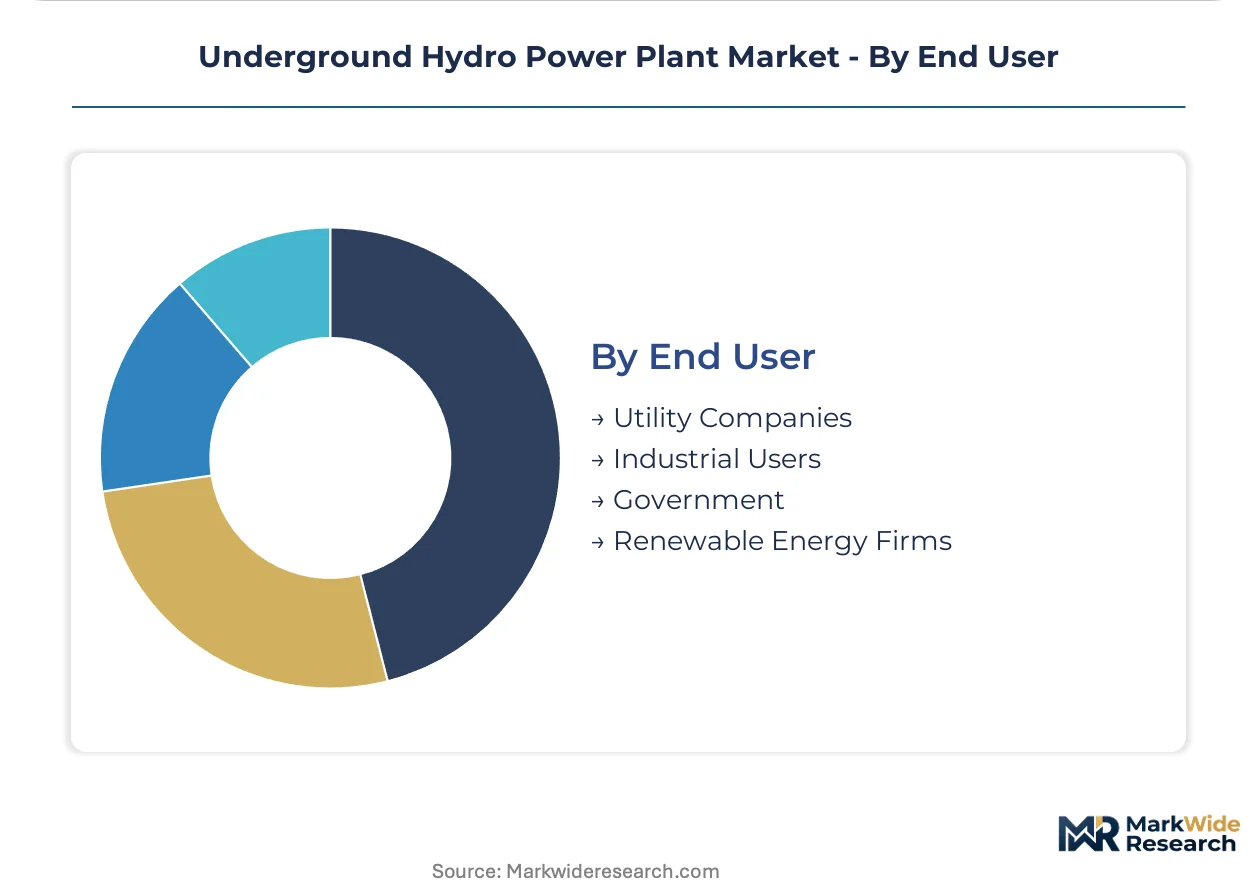
Utility companies command the established base. The steepest expansion runs through renewable energy firms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility companies in mountainous corridors drive procurement concentration, with grid operators in Switzerland, Austria, Norway, and China absorbing decade-long development timelines for strategic storage assets.
Switzerland
Cantonal power authorities advance multi-gigawatt-hour pumped storage reservoirs to stabilize intermittent renewable generation across European transmission networks. The Swiss Federal Office of Energy enforces stringent geological stability protocols that shape cavern engineering specifications. The Alpine corridor concentrates tunneling expertise and water head availability, with Uri and Valais cantons hosting active brownfield expansion projects.
China
State-owned grid operators deploy subterranean pumped storage to meet dual carbon goals while minimizing surface ecological disruption in protected watershed regions. The Ministry of Ecology and Environment enforces environmental impact assessments that favor underground construction methods. Sichuan and Yunnan provinces anchor development, where steep terrain and existing transmission infrastructure support cavern excavation programs.
Norway
Statkraft and regional utilities concentrate large-scale baseload generation in geological corridors with proven rock stability. Norwegian Water Resources and Energy Directorate licensing requirements prioritize closed-loop designs that eliminate surface reservoir impacts. Hardangerfjord and Sognefjord regions host established clusters, with modular tunneling approaches reducing upfront capital exposure in remote terrain.
Austria
Verbund AG and provincial utilities retrofit existing caverns with variable-speed Francis turbine configurations to extend operational range across fluctuating reservoir levels. Austrian federal environmental regulations align with EU F-Gas Regulation phase-down schedules on hydrofluorocarbon coolants. Tyrol and Salzburg regions concentrate manufacturing heritage and high-head turbine supply chains.
Japan
Tokyo Electric Power Company and regional operators maintain pumped storage assets for grid frequency regulation amid renewable integration pressures. METI safety standards govern cavern stability and seismic resilience in tectonically active terrain. Nagano and Gunma prefectures host established installations, where hard-rock boring machine procurement from domestic and German suppliers sustains maintenance programs.
Underground Hydro Power Plant Market Competitive Landscape
Player mix skews toward European engineering conglomerates with Austrian and German manufacturing heritage dominating high-head turbine supply. The vendor base concentrates around integrated equipment suppliers and specialized civil contractors with Alpine tunneling expertise. Two strategic archetypes define positioning: full-system integrators bundling turbine, generator, and digital controls; and component specialists unbundling long-term maintenance contracts into discrete service modules. Competitive moves center on IEC 61850 certification races for substation automation and strategic partnerships with regional civil engineering firms for cavern excavation risk-sharing.
Among Austrian and German fabricators, Andritz Hydro GmbH, Voith Hydro GmbH & Co. KG, and Siemens Energy AG occupy positions representing the integrated-system archetype. Andritz Hydro exemplifies the high-head Francis turbine specialist with manufacturing heritage embedded in Alpine supply chains. Voith Hydro anchors German engineering standards across European cavern power station projects. Siemens Energy sits within the digital controls tier, bridging underground generation with grid synchronization protocols. General Electric Company represents the North American-integrated alternative competing through automation platforms. AECOM and Tokyo Electric Power Company exemplify the civil-contractor and utility-operator archetypes respectively, with the former representing engineering-procurement-construction capability and the latter anchoring long-duration asset ownership models in seismically active terrain.
| Leading Market Players |
|---|
| AECOM |
| Nalcor Energy |
| The Churchill Falls (Labrador) Corporation |
| Tokyo Electric and Power Company (TEPCO) |
| Meridian Energy Limited |
| Andritz Hydro GmbH |
| General Electric Company |
| Voith Hydro GmbH & Co. KG |
| Siemens Energy AG |
| Others |
Value Network & Pricing Analysis
Natural ester fluid substitution for hydrofluorocarbon coolants under the EU F-Gas Regulation simultaneously shifts procurement geography toward Swiss and Norwegian chemical suppliers and compresses transformer maintenance pricing through consolidated fluid sourcing contracts. Equipment vendors now bundle sealed gas-insulated switchgear with long-term service agreements, embedding compliance costs into upfront capital expenditure rather than exposing operators to spot-market coolant volatility.
Pricing Analysis
Cost-plus contracts with steel and cement indexation dominate cavern excavation agreements, protecting German and Japanese tunneling specialists from raw material volatility while transferring commodity risk to utility developers. Price differentiation separates premium-tier projects with full IEC 61850 certification and digital twin integration from standard configurations with fixed-speed Francis turbines. Pricing pressure stems from lithium-ion battery systems capturing frequency regulation contracts that pumped storage previously dominated, forcing underground developers to emphasize multi-gigawatt-hour duration advantages. Small-scale Andean projects exhibit highest price sensitivity due to limited transmission revenue streams, while Swiss cantonal utilities absorb premium pricing for geological stability guarantees.
Supply Chain Analysis
Alpine tunneling equipment chokepoint concentration in Germany and Japan underwrites procurement timelines stretching 18-24 months for hard-rock boring machines serving remote mountain corridors. Component sourcing draws from Austrian Francis turbine foundries, Swiss high-voltage switchgear manufacturers, and Chinese steel suppliers for penstock fabrication. Single-source vulnerability concentrates in specialized civil contractors with cavern stability modeling capability numbering fewer than twelve worldwide. Distribution runs through engineering-procurement-construction consortia bundling equipment procurement with geological risk-sharing arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Underground hydro power plant developers face a substitution defense against long-duration battery storage systems that now capture grid balancing contracts through faster deployment timelines and modular scalability.
For Market Incumbents: Shield installed asset value by retrofitting existing caverns with variable-speed Francis turbine configurations that extend operational flexibility across 150-400 meter head variations, outpacing battery duration limitations. Deepen geological risk-sharing partnerships with Bavarian and Lombard civil contractors to compress pre-construction stability modeling timelines and defend against lithium-ion encroachment on frequency regulation markets. For New Entrants and Emerging Players: Anchor in Peru, Colombia, and Ecuador community-scale deployments between 5 and 50 megawatts where transmission infrastructure gaps create captive demand for localized generation. Target modular tunneling approaches that reduce upfront capital exposure in remote Andean terrain, leveraging standardized factory-assembled components to compress on-site construction windows against established Alpine competitors. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors engineering-procurement-construction platforms with integrated cavern stability modeling and equipment supply capabilities. Long-term viability hinges on developers with verified low-carbon concrete and steel supply chains positioned for carbon border adjustment compliance. Watch IEC 61850 certification completion rates as the inflection indicator for grid connection approval velocity and revenue recognition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Variable-Speed Turbine Retrofit | Extends operational range across fluctuating reservoir levels for Swiss and Austrian utilities. |
| Natural Ester Fluid Transition | Ensures EU F-Gas Regulation compliance for sealed transformer systems in Norwegian facilities. |
| Modular Tunneling Deployment | Compresses construction timelines for remote Andean projects in Peru and Colombia. |
| IEC 61850 Certification Investment | Enables digital twin monitoring of underground cavern conditions for predictive maintenance. |
| Carbon Border Adjustment Preparation | Creates competitive advantage through verified low-carbon concrete supply chains. |
Research Methodology
Desk research of FERC filings, IEA hydroelectric databases, and EU ETS carbon accounting frameworks preceded structured interviews with utility planning officers, EPC contractors, hard-rock boring machine procurement specialists, and Alpine tunneling geologists. Secondary validation drew from project development databases, national grid operator capex disclosures, and environmental impact assessment records. Bottom-up project pipeline aggregation triangulated against top-down national renewable integration targets.
Variance decomposition across technology segments, capacity tiers, and installation types informed the analytical framework over the projection horizon. Segmentation dimensions modeled include turbine technology, project scale classification, greenfield versus brownfield development status, and end-user archetype. CAGRs were derived from capacity-weighted project commissioning schedules and equipment procurement lead times. Forecast inputs incorporated grid balancing mandate intensity from transmission operators and F-Gas Regulation compliance timeline enforcement.
Material uncertainties — unmapped geological fault lines, hard-rock boring machine procurement bottlenecks, and lithium-ion battery cost trajectories — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory stability for underground construction approvals and carbon border adjustment implementation scope. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydropower Systems
Floating Power Plant Market
Hydropower Systems
Global Hydro Turbine Generator Unit Market
Hydropower Systems
Offshore Hydropower Market
Hydropower Systems
United States Hydro Turbine Market
Hydropower Systems
Asia-Pacific Small Hydropower Market
Hydropower Systems
North America Pumped Hydro Storage Market
Hydropower Systems
North America Hydropower Market
Hydropower Systems
Europe Hydropower Market
Hydropower Systems
Hydropower Turbine Market
Hydropower Systems
Southeast Asia Hydropower Market
Hydropower Systems
Pumped Hydro Storage Market
Hydropower Systems
Europe Hydro Turbine Market
Hydropower Systems
Tidal Power Market
Hydropower Systems
South America Pumped Hydro Storage Market
Hydropower Systems
Hydropower Market
Hydropower Systems
Asia-Pacific Hydropower Market