
 North America Pumped Hydro Storage Market | 2026-2036
North America Pumped Hydro Storage Market Size, Share, and Industry Trends Forecast 2026-2036
North America Pumped Hydro Storage Market Analytics
Advanced turbine efficiency specifications above ninety percent hydraulic performance is rotating procurement standards across the North America pumped hydro storage landscape. General Electric Company leverages its turbine manufacturing scale to dominate equipment supply for greenfield projects. Voith GmbH & Co. KGaA sustains technology leadership in variable-speed pump-turbine designs that optimize grid frequency response. Duke Energy Corporation anchors demand growth through its regulated utility footprint across the Carolinas and Midwest.
Pumped hydro storage uses gravitational potential energy from water elevation differentials, typically requiring upper and lower reservoirs separated by five hundred to one thousand vertical feet, with reversible pump-turbine units converting electrical energy to stored hydraulic head during off-peak periods. Its primary purpose is bulk energy shifting and grid inertia provision for electric power systems with high renewable penetration. Closed-loop configurations command structural attention because they eliminate riverine dependency and streamline FERC licensing. Large-scale and gigawatt-scale capacity segments concentrate margin pools where engineering complexity creates barriers to new entrants. Utility companies occupy the dominant end-user position due to their balance-sheet capacity for billion-dollar civil works.
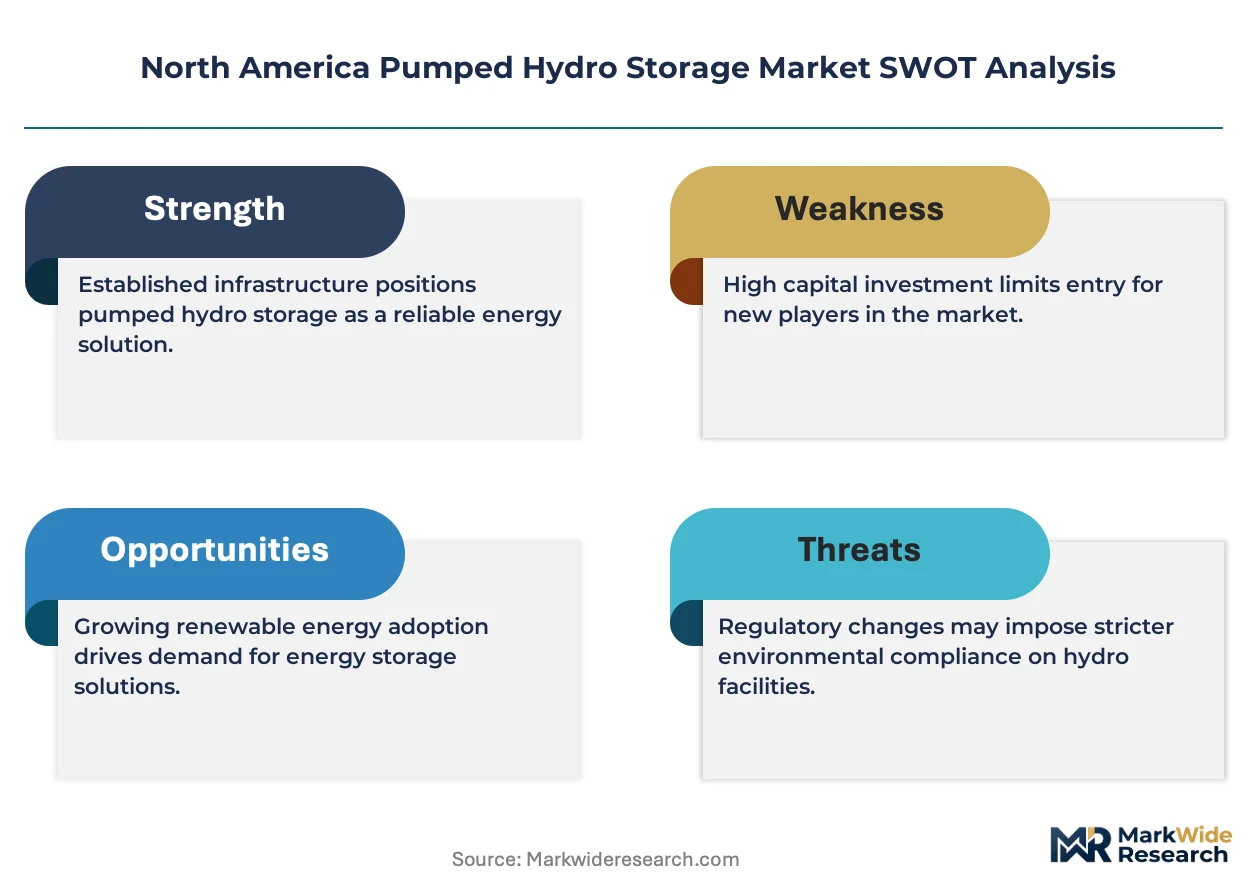
FERC, EPA, and state public utility commissions shape project economics through licensing duration, environmental review stringency, and rate-base treatment of storage assets. The IRA production tax credits and modified investment tax credit provisions directly reduce capital recovery periods for qualifying pumped storage installations. Stakeholders must monitor interconnection queue reform and regional transmission organization market rule changes that determine whether storage capacity captures full capacity value streams.
Market Dynamics
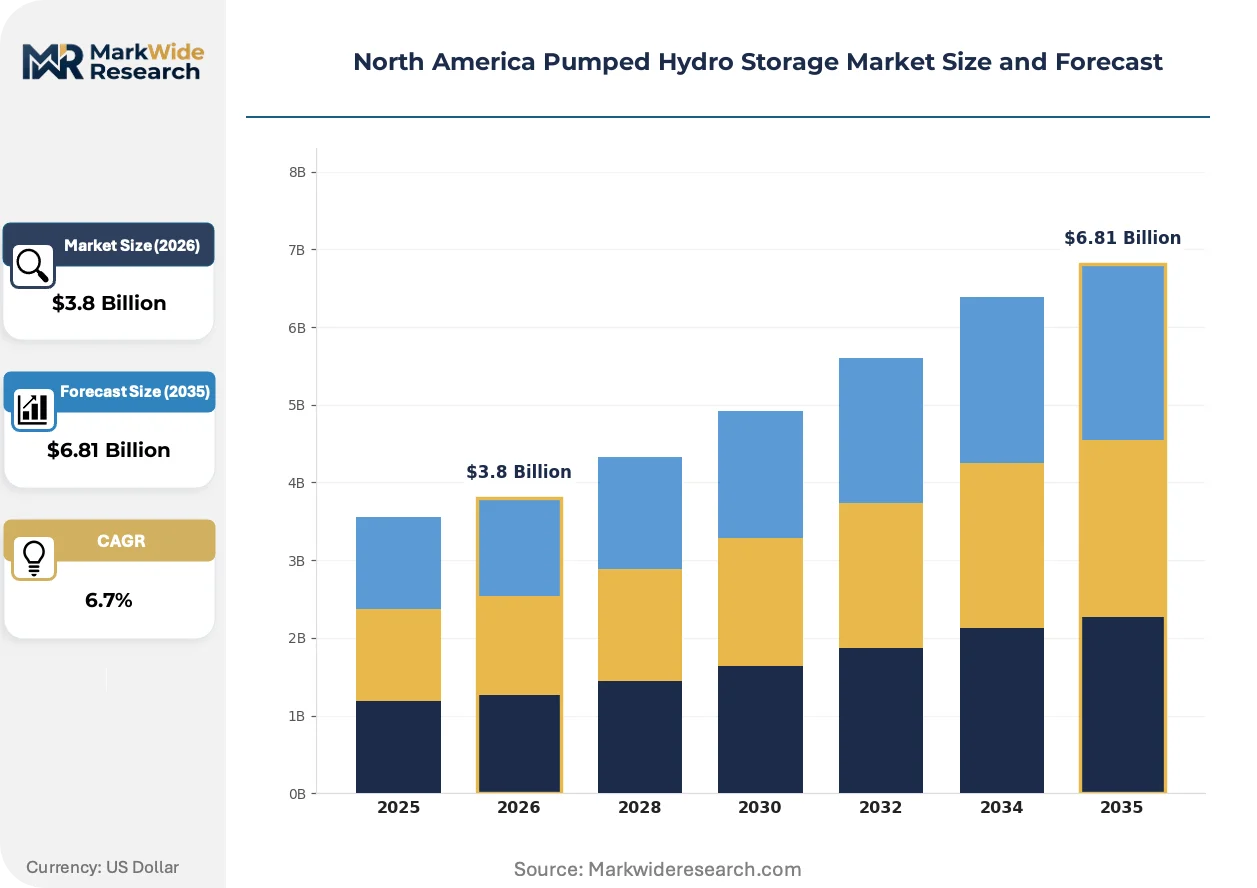
FERC licensing reforms and IRA investment tax credits are compressing project development timelines from permit to operation, fundamentally altering how utilities finance billion-dollar civil works across the United States and Canada.
Growth Catalysts
- IRA Investment Tax Credits:Federal tax provisions directly reduce capital recovery periods for qualifying closed-loop installations, improving project IRRs for utility sponsors.
- State Clean Energy Mandates:Procurement requirements in California, New York, and Colorado are forcing utilities to contract long-duration storage capacity.
- Variable-Speed Pump-Turbines:Advanced hydraulic designs enable rapid grid frequency response, unlocking ancillary service revenue streams previously unavailable to fixed-speed units.
Market Restraints
- Steel and Concrete Input Volatility:Reservoir construction requires massive civil works where commodity price swings directly threaten fixed-price EPC contracts.
- Environmental Review Stringency:EPA wetland assessments and state-level endangered species consultations extend permitting timelines unpredictably.
- Lithium-Ion Battery Substitution:Four-hour battery storage is capturing shorter-duration shifting applications that pumped hydro once dominated.
Strategic Opportunities
- Appalachian Brownfield Sites:Abandoned coal mines in West Virginia and Pennsylvania offer pre-excavated lower reservoirs with minimal new environmental disturbance.
- Canada Provincial Procurement:Ontario and British Columbia utilities lack binding storage mandates, creating first-mover advantages for early project developers.
- Hybrid Solar-Pumped Configurations:Co-located photovoltaic generation reduces transmission interconnection costs while optimizing reservoir fill cycles.
Industry Challenges
- Geotechnical Engineering Talent Scarcity:Dam safety certification requires specialized expertise that utilities and EPC firms struggle to staff for multi-year project horizons.
- FERC License Transfer Complexity:Secondary market transactions for existing pumped storage assets trigger extensive environmental re-evaluations that deter financial buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Pumped Hydro Storage Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Energy Management, Grid Stability, Renewable Integration, Peak Shaving Technology: Closed Loop, Open Loop, Underground, Pumped Storage End User: Utility Companies, Independent Power Producers, Industrial Users, Government Agencies Capacity: Small Scale, Medium Scale, Large Scale, Gigawatt Scale |
| Companies Covered | General Electric Company, Voith GmbH & Co. KGaA, Duke Energy Corporation, Siemens AG, Enel SpA, Andritz Hydro, Absaroka Energy, Nevada Hydro Corporation, Brookfield Renewable, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Pumped Hydro Storage Market Evolving Landscape
Equipment manufacturers and project developers are racing to reduce civil works intensity while extracting more grid services from each installed megawatt. Three concurrent shifts are redefining competitive positioning.
Variable-speed pump-turbine technology is displacing fixed-speed units in new procurement specifications. Pacific Northwest utilities now require frequency regulation capability as standard equipment. The technology is displacing mechanical governors and synchronous condensers as the primary source of grid inertia in high-renewable balancing areas.
FERC's 2023 interconnection queue reform is compressing study timelines for storage assets. The policy eliminates serial dependency on transmission upgrades that previously stalled pumped hydro projects. Developers in the Carolinas and Midwest are restructuring project phasing to align with expedited cluster study schedules.
Utility procurement departments are unbundling EPC contracts into separate civil, electro-mechanical, and commissioning packages. This fragmentation transfers geological risk to specialized contractors while allowing equipment vendors to compete on turbine efficiency guarantees. The shift is most visible in Duke Energy's recent solicitation for Appalachian greenfield capacity.
North America Pumped Hydro Storage Market Segmentation
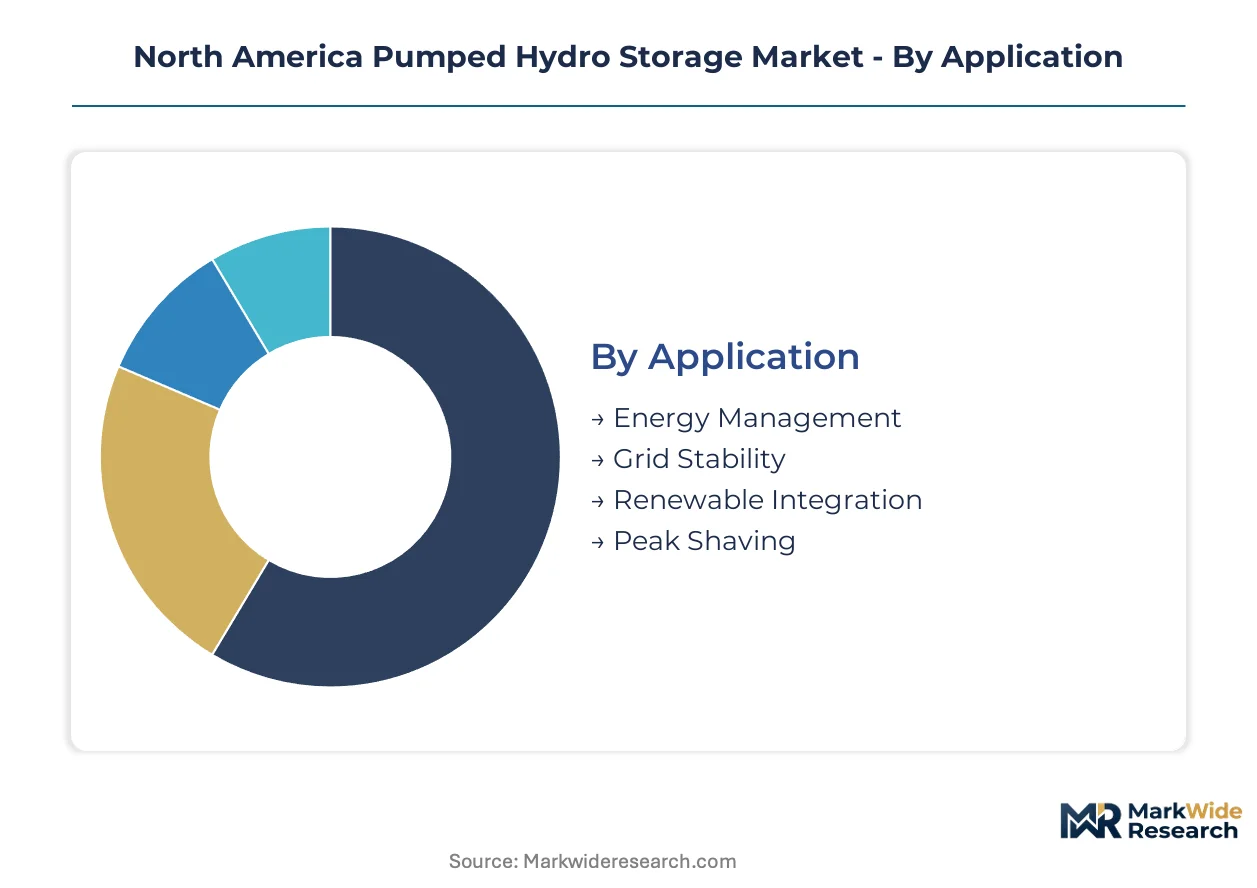
Pumped hydro storage procurement patterns diverge sharply across application types, technology configurations, and end-user balance sheets. FERC licensing pathways and IRA tax credit eligibility create structural incentives that reshape segment economics. Understanding these fault lines reveals where capital deployment concentrates and where new entrants face barriers.
Application:
FERC Order 841 implementation and state-level clean energy mandates have reordered which grid services command premium valuation across the United States and Canada.
- Energy Management:Bulk energy shifting from off-peak to peak periods constitutes the foundational service model. Pacific Northwest utilities with high hydroelectric surplus contract this capacity to manage seasonal runoff variability.
- Grid Stability:Ancillary frequency regulation and voltage support services now dominate procurement specifications in California and Texas ERCOT territories where renewable penetration exceeds forty percent. Variable-speed pump-turbines unlock this revenue stream.
- Renewable Integration:Co-located storage mitigates wind and solar curtailment in Colorado and New York markets with aggressive decarbonization timelines.
- Peak Shaving:Four-to-eight-hour discharge capacity reduces utility peak demand charges in Appalachian regions with summer cooling load spikes.
Energy Management handles the majority of throughput; Grid Stability is the fastest mover on share.
Technology:
Capital intensity and environmental review duration separate winners from stranded assets in technology selection.
- Closed Loop:Self-contained reservoir systems eliminate riverine dependency and compress FERC licensing timelines. Appalachian greenfield projects in West Virginia and Pennsylvania now specify this configuration exclusively.
- Open Loop:River-connected installations leverage existing water bodies but trigger extended EPA Clean Water Act consultations. Legacy facilities in the Pacific Northwest retain this structure.
- Underground:Subsurface lower reservoirs using abandoned mines or caverns minimize surface footprint. Kentucky and Ohio coal regions host pilot developments.
- Pumped Storage:Conventional reversible pump-turbine installations remain the baseline technology for large-scale deployments.
Closed Loop attracts the dominant share of new capital commitment; Underground configurations are expanding most quickly off a small base.
End User:
Balance sheet capacity and rate-base treatment determine which customer classes can absorb billion-dollar civil works.
- Utility Companies:Regulated investor-owned utilities in the Carolinas and Midwest deploy ratepayer-backed financing for multi-decade asset lives. Duke Energy and Dominion Energy anchor regional procurement.
- Independent Power Producers:Merchant developers rely on power purchase agreements and tax equity partnerships. IRA investment tax credits improve project IRRs sufficiently to attract private capital.
- Industrial Users:Aluminum smelters and data center operators in Quebec and Washington State evaluate behind-the-meter storage for power quality assurance.
- Government Agencies:Federal power marketing administrations and provincial Crown corporations in Canada pursue non-commercial reliability objectives.
Utility Companies command the largest committed capacity; Independent Power Producers are gaining share fastest as offtake contracting structures mature.
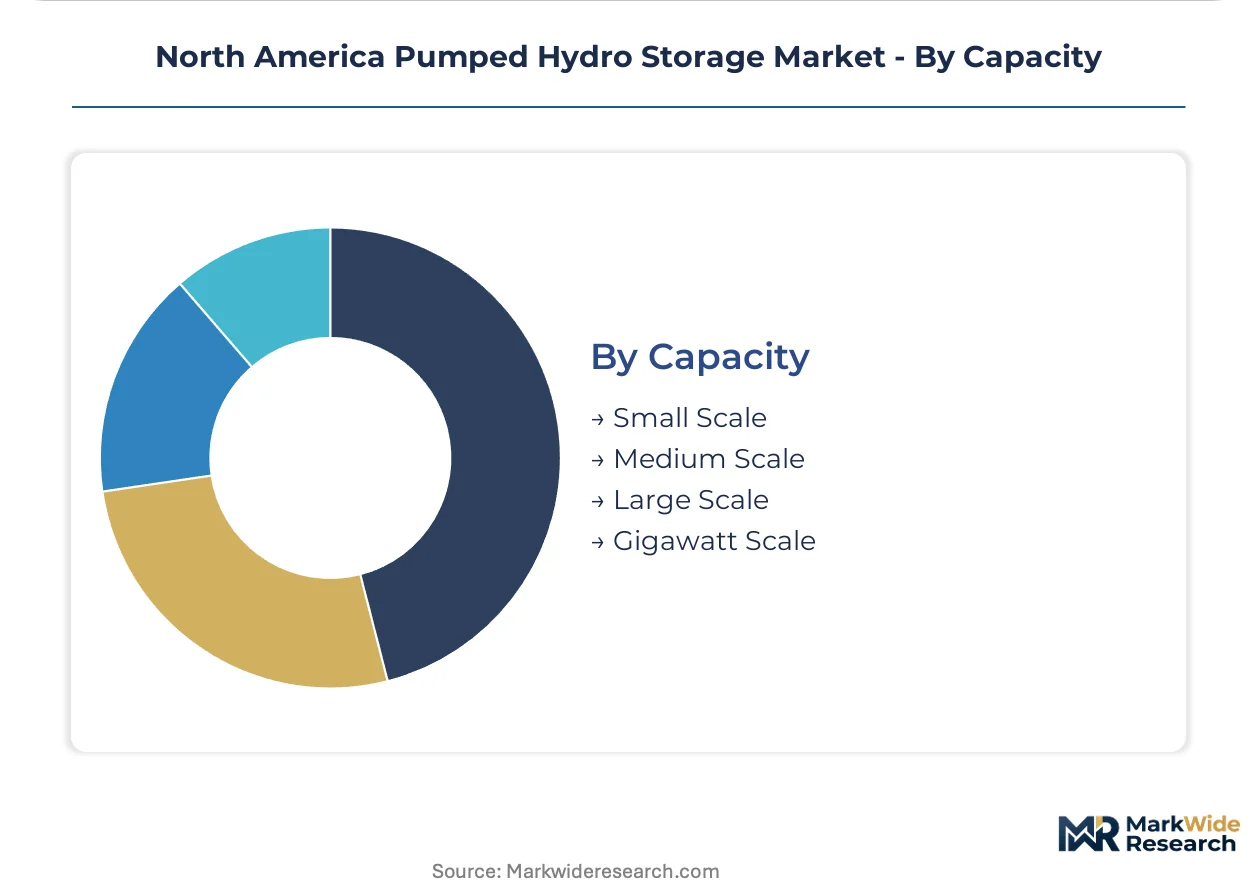
Capacity:
Economies of scale in civil works and turbine manufacturing reshape competitive dynamics across size tiers.
- Large Scale:Facilities between five hundred megawatts and two gigawatts dominate the development pipeline. Engineering standardization and repeat contractor relationships reduce execution risk.
- Gigawatt Scale:Multi-reservoir complexes serve as regional backbone infrastructure. Only federal power marketing administrations and the largest integrated utilities possess development bandwidth.
- Medium Scale:One hundred to five hundred megawatt projects target congested transmission corridors where smaller footprints ease interconnection.
- Small Scale:Sub-hundred-megawatt installations face diseconomies in civil works intensity. Niche applications include island grids and remote industrial loads.
Large Scale captures the bulk of engineering resources; Gigawatt Scale projects are climbing the fastest as interregional transmission planning accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Capital flows into North American pumped hydro storage track regional transmission constraints and state-level procurement mandates rather than import-export dynamics. Project developers concentrate engineering resources where FERC licensing pathways and IRA tax credit eligibility align with favorable topography.
United States
Utility-scale procurement concentrates in the Pacific Northwest and Appalachian regions where five-hundred-to-one-thousand-foot elevation differentials support reservoir construction. FERC's 2023 interconnection queue reform compresses study timelines for storage assets in the Carolinas and Midwest. Duke Energy Corporation anchors demand growth through regulated utility expansion across southeastern states.
Canada
Ontario and British Columbia utilities evaluate long-duration storage additions to manage hydroelectric surplus variability and grid inertia requirements. Provincial Crown corporations pursue non-commercial reliability objectives without binding federal storage mandates. Quebec's aluminum smelter corridor generates behind-the-meter demand for power quality assurance applications.
Mexico
Federal power sector restructuring under CFE creates procurement uncertainty for independent storage developers. The country's national electricity regulator evaluates interconnection standards for utility-scale renewable pairing projects. Northern border states concentrate pilot interest where cross-border transmission planning intersects with solar generation expansion.
North America Pumped Hydro Storage Market Competitive Landscape
Listed leaders compete with private specialists across equipment supply and project development segments, creating a tiered structure where turbine manufacturers and utility sponsors occupy distinct competitive spaces. General Electric Company and Siemens AG leverage manufacturing scale against specialized hydraulic engineering firms. Three archetypes dominate: integrated equipment conglomerates, regulated utility developers, and independent renewable power producers. Competitive moves center on EPC contract unbundling and brownfield site acquisition for reservoir construction.
Within the integrated equipment tier, General Electric Company and Voith GmbH & Co. KGaA represent contrasting approaches to turbine technology positioning, while Duke Energy Corporation exemplifies the regulated utility developer archetype with rate-base-backed project finance capacity. These three entities anchor the competitive landscape across equipment supply and utility sponsorship vectors.
| Leading Market Players |
|---|
| General Electric Company |
| Voith GmbH & Co. KGaA |
| Duke Energy Corporation |
| Siemens AG |
| Enel SpA |
| Andritz Hydro |
| Absaroka Energy |
| Nevada Hydro Corporation |
| Brookfield Renewable |
| Others |
Value Network & Pricing Analysis
FERC licensing requirements and IRA tax credit eligibility gates simultaneously determine supplier qualification tiers and price differentiation between project developers. Equipment vendors and EPC contractors face divergent margin structures depending on which regulatory pathway their customers pursue.
Pricing Analysis
Utility companies anchor pricing structures through billion-dollar rate-base commitments that span multi-decade asset lives. Project-based contract pricing dominates, with differentiation driven by turbine efficiency guarantees and FERC licensing risk allocation. Cost compression in electro-mechanical packages is intensifying as GE and Voith compete on hydraulic performance specifications. Independent power producers exhibit highest price sensitivity due to merchant revenue exposure, while regulated utilities absorb premium pricing for execution certainty.
Supply Chain Analysis
Specialized turbine manufacturing capacity concentrates in Germany, Austria, and the United States, creating chokepoint vulnerability for North American project timelines. Reversible pump-turbine units and penstock steel draw from precision-forging capabilities in Austria and Japan. Single-source dependency on Voith and Andritz Hydro for variable-speed designs exposes developers to eighteen-month order backlogs. Distribution runs through utility procurement departments that unbundle EPC contracts into discrete civil, electro-mechanical, and commissioning packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as Duke Energy and Dominion Energy consolidate regional procurement through multi-gigawatt master service agreements, fragmenting smaller developers into price-taker positions.
For Market Incumbents: Consolidate equipment supply relationships through exclusive turbine efficiency guarantee frameworks that lock out emerging hydraulic engineering specialists. Deepen backward integration into penstock manufacturing to capture margin pools currently flowing to Japanese steel fabricators. Anchor rate-base treatment advantages by accelerating FERC license applications before interconnection queue reforms sunset. For New Entrants and Emerging Players: Anchor in Appalachian brownfield sites where abandoned coal mines offer pre-excavated lower reservoirs with minimal EPA wetland exposure. Target Ontario and British Columbia procurement offices that lack binding storage mandates and exhibit limited vendor familiarity. Pursue hybrid solar-pumped configurations as the go-to-market angle, leveraging co-located photovoltaic generation to reduce transmission interconnection costs and accelerate project finance. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across closed-loop configurations as standardized turbine designs reduce engineering customization. Long-term viability favors developers with secured interconnection agreements and FERC licenses rather than speculative greenfield positions. Acquisition targets should display completed environmental review and active utility offtake negotiations. The signal to watch is FERC license transfer velocity, which indicates secondary market liquidity and exit pathway clarity.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Multi-gigawatt Appalachian developments anchor Duke Energy's rate-base expansion across Carolinas and Midwest. |
| Power Purchase Agreement | Long-term utility offtake contracts unlock project finance for independent power producers seeking tax equity partnerships. |
| Technology Licensing | Variable-speed pump-turbine patents from Voith enable frequency regulation revenue streams in high-renewable balancing areas. |
| Vertical Integration into Storage | Backward control over penstock fabrication reduces exposure to Japanese steel price volatility and delivery delays. |
| Green Certification Program | IRA investment tax credit qualification compresses capital recovery periods and improves project IRRs for qualifying installations. |
Research Methodology
A standing panel of utility planning officers, IPP project developers, EPC contractors, and FERC licensing specialists provided ongoing calibration throughout the research process. Primary interviews with grid operators and equipment procurement managers were cross-validated against EIA generation data, FERC project filings, IEA renewable integration reports, and utility integrated resource plans. Bottom-up project pipeline aggregation was triangulated against top-down capacity expansion forecasts from regional transmission organizations.
Consistency checks validated volume and value outputs against external benchmarks including interconnection queue data and announced utility procurement targets. The analytical framework modeled capacity tiers, technology configurations, application types, and end-user balance sheet categories across the projection horizon. CAGRs were derived from project-level development timelines and assumed construction cost trajectories. Key inputs included assumed FERC licensing duration improvements and IRA tax credit utilization rates by developer type.
Underlying assumptions cover construction cost stability and commodity price normalization, with deviation risk concentrated in steel and concrete input volatility and EPA environmental review stringency. Forecasts reflect these assumptions with explicit scenario boundaries around permitting acceleration and interconnection reform implementation. Practitioners should keep alternative scenarios live as FERC rulemaking and state-level mandate expansion evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydropower Systems
France Tidal Power Market
Hydropower Systems
Hydropower Turbine Market
Hydropower Systems
Offshore Hydropower Market
Hydropower Systems
Europe Small Hydropower Market
Hydropower Systems
Global Hydro Turbine Generator Unit Market
Hydropower Systems
United States Hydropower Market
Hydropower Systems
United States Hydro Turbine Market
Hydropower Systems
Japan Hydropower Market
Hydropower Systems
Hydroelectricity Market
Hydropower Systems
Underground Hydro Power Plant Market
Hydropower Systems
Southeast Asia Hydropower Market
Hydropower Systems
Whirlpool Turbine Market
Hydropower Systems
Asia-Pacific Pumped Hydro Storage Market
Hydropower Systems
Europe Hydropower Market
Hydropower Systems
Asia-Pacific Small Hydropower Market
Hydropower Systems
South America Hydropower Market