
 Wave Energy Market | 2026-2036
Wave Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Wave Energy Market Analysis
The capital-intensity divergence between wave energy developers is bifurcating competitive tiers. CorPower Ocean leverages advanced control systems and phased array architectures to sustain high R&D burn rates. Eco Wave Power anchors its position through nearshore installations that reduce mooring complexity and installation costs.
Wave energy captures kinetic and potential energy from ocean surface waves through mechanical or pneumatic conversion systems, typically operating at 20-80 kW per meter of wave front depending on converter topology. Its primary purpose is grid-connected renewable electricity generation in coastal and offshore environments. Point absorbers occupy the dominant technology position due to modularity and lower material intensity, while attenuator designs are gaining traction in utility-scale arrays where wave climate consistency supports higher capacity factors. Power generation applications command the largest value share, though desalination paired with wave energy is emerging as a margin pool in water-stressed island economies.
Scotland's Marine Scotland licensing framework, Portugal's AICEP ocean energy concessions, and Australia's NOPSEA offshore infrastructure approvals collectively shape project timelines and equipment certification requirements. The EU's Renewable Energy Directive and associated member-state marine spatial plans mandate streamlined consenting for ocean energy demonstration zones. Stakeholders must monitor which regulatory jurisdictions resolve grid interconnection liability allocation first, as this determines viable project finance structures.
Market Dynamics
The wave energy sector faces a structural tension between offshore scale economics and nearshore deployment speed, with converter topology choices now determining competitive viability more than raw resource access.
Growth Catalysts
- EU Green Deal marine spatial planning:Portugal's AICEP ocean energy concessions and Scotland's Marine Scotland licensing framework compress consenting timelines for demonstration arrays.
- Point absorber modularity:Lower material intensity and standardized subcomponents enable rapid replication across Atlantic test sites without custom engineering.
- Baseload procurement mandates:European offshore utilities now contract wave energy as firm renewable capacity to balance intermittent wind and solar portfolios.
Market Restraints
- Mooring system cost volatility:Synthetic rope and anchor chain prices fluctuate with offshore oil rig demand, squeezing project IRRs.
- Grid interconnection liability ambiguity:Unclear allocation between developers and transmission operators in EU member states stalls financial close.
- Tidal range competition:Barrage and lagoon projects in France and South Korea capture similar marine energy investment flows with lower technology risk.
Strategic Opportunities
- Australia's NOPSEA streamlined approvals:The regulator's risk-based assessment framework for offshore infrastructure reduces certification cycles relative to European counterparts.
- Wave-powered desalination bundling:Island economies in the Caribbean and Pacific combine electricity and freshwater output to improve project economics.
- Digital twin convergence:Real-time hydrodynamic modeling fused with predictive maintenance software cuts operational expenditure for remote offshore assets.
Industry Challenges
- Marine engineering talent scarcity:Deepwater mooring design and biofouling management expertise concentrates in offshore oil services, creating recruitment bottlenecks.
- Certification timeline compression:IEC 62600-1 type certification for wave energy converters requires multi-year sea trials, delaying revenue recognition.
- Supply chain reconfiguration friction:Heavy fabrication capacity for steel hulls and power take-off systems must shift from oil platform construction to renewable specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wave Energy Market |
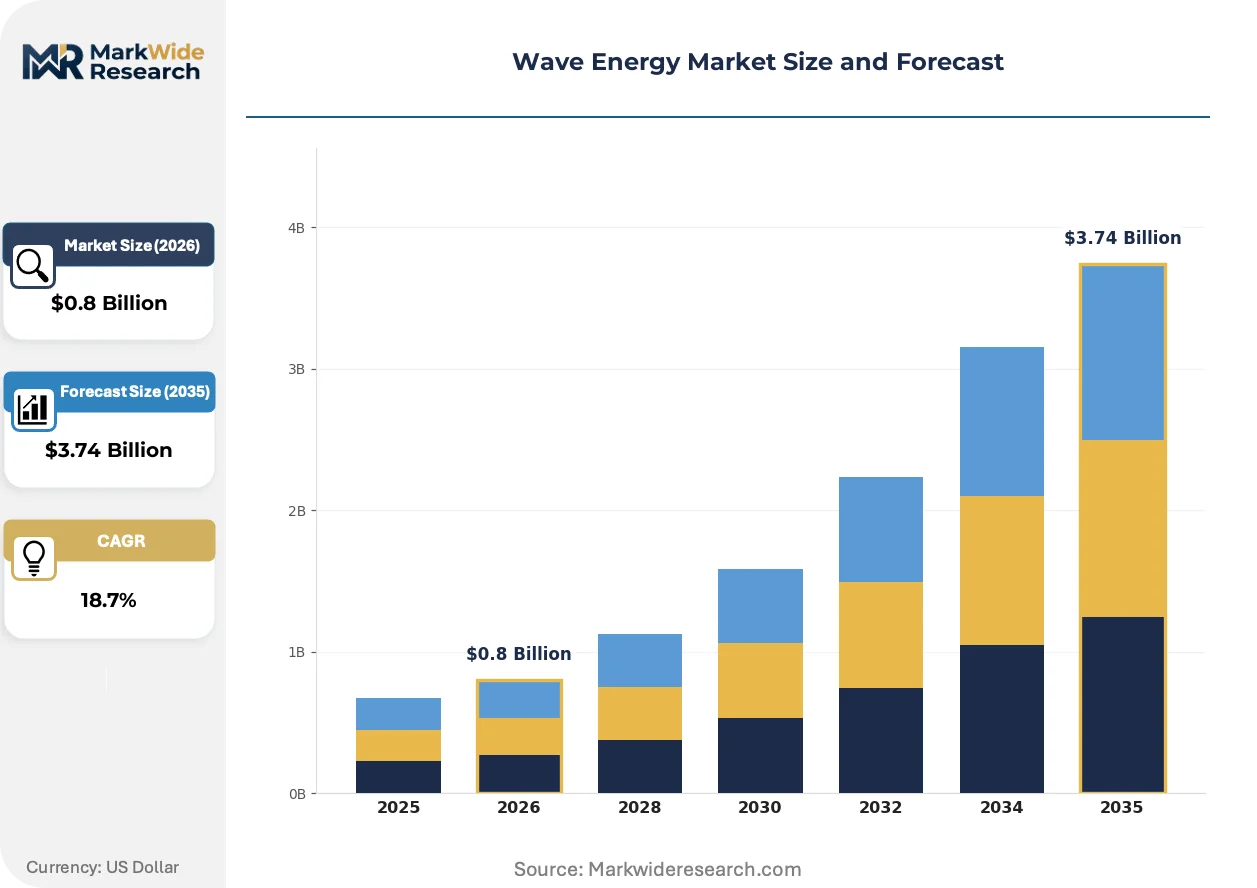
| Market Size in 2026 | $0.8 Billion |
| Market Size in 2035 | $3.74 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Point Absorbers, Oscillating Water Columns, Attenuators, Terminators Application: Power Generation, Coastal Protection, Aquaculture, Desalination End User: Utilities, Government Agencies, Research Institutions, Industrial Users Deployment: Onshore, Offshore, Nearshore, Hybrid |
| Companies Covered | CorPower Ocean, Ocean Power Technologies, Eco Wave Power, Carnegie Clean Energy, Seabased, AW-Energy, Mocean Energy, Bombora Wave Power, Wave Swell Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wave Energy Market Emerging Trajectories
Converter control architectures and array configuration strategies are diverging rapidly, with developers betting on opposing pathways to cost reduction. These technology choices are reshaping vendor partnerships and project finance structures.
Advanced control systems for point absorbers is fragmenting the competitive landscape between high-complexity offshore platforms and simplified nearshore units. Developers deploying phased array architectures with real-time wave-by-wave tuning capture higher capacity factors in Atlantic swell climates. The technology is fragmenting procurement patterns, with utilities now segmenting tenders by water depth and sea state rather than treating wave energy as a uniform category.
Scotland's Marine Scotland licensing framework and Portugal's AICEP concessions are creating regulatory arbitrage opportunities across European Atlantic coastlines. The industrial consequence is a clustering of demonstration projects in jurisdictions with pre-approved marine spatial zones and clarified grid liability rules. Offshore utility procurement teams are responding by prioritizing project pipelines in Orkney and Agucadoura over jurisdictions with unresolved consenting pathways.
Integrated service contracts now bundle equipment supply with long-term availability guarantees, displacing traditional EPC-only procurement. Offshore utilities in Europe are contracting wave energy developers as independent power producers rather than equipment vendors, shifting performance risk onto technology providers. This pattern is most visible in the UK and French markets, where power purchase agreement structures now dominate early commercial deployments.
Wave Energy Market Segmentation
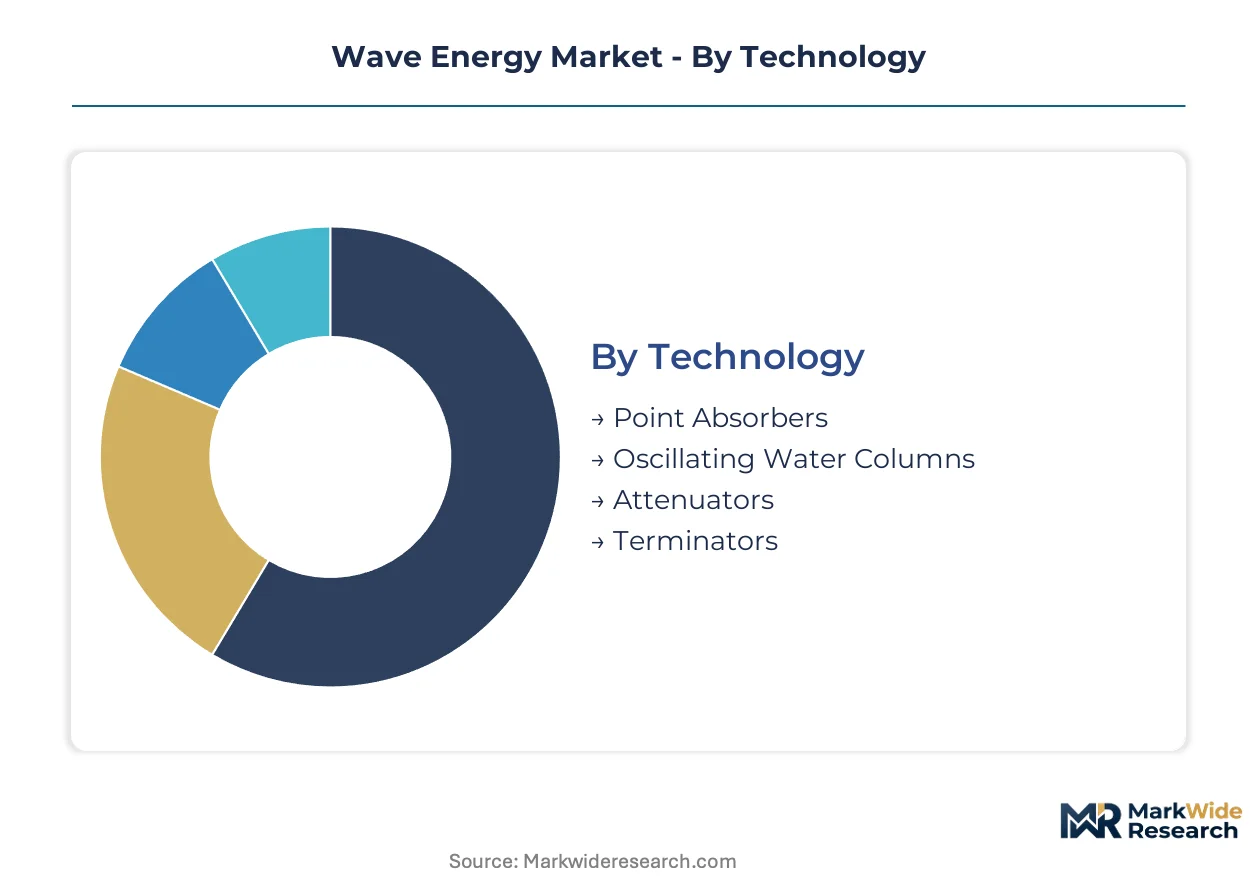
Wave energy converter topology, application pairing, and deployment depth collectively determine project economics and regulatory pathways. Segmentation choices directly shape equipment certification requirements, mooring system specifications, and power purchase agreement structures across Atlantic and Pacific demonstration zones.
Technology:
Substitution pressure from tidal range and offshore wind installations is forcing technology developers to differentiate on capacity factor and grid stability rather than resource capture alone.
- Point Absorbers:Compact floating units with heave-motion power take-off systems achieve 25-40% capacity factors in moderate swell climates. Demand concentrates in Scotland's Orkney waters and Portugal's Agucadoura test zone, driven by modular installation logistics and reduced steel tonnage per megawatt.
- Attenuators:Multi-segment floating structures aligned parallel to wave fronts extract energy through relative hinge motion. Atlantic utility procurement in the UK and France favors these designs for utility-scale arrays where wave climate consistency supports 35-50% capacity factors and firm renewable contracting.
- Oscillating Water Columns:Shore-mounted or floating chambers compress air through wave-driven water piston action, driving bidirectional turbines. Retrofit applications at existing breakwaters in Spain and Australia leverage civil infrastructure to cut capital intensity.
- Terminators:Shore-perpendicular structures that capture wave energy at coastline termination points. Coastal protection bundling in Japan and South Korea creates dual-revenue streams for seawall-integrated installations.
Point absorbers retain volume leadership; attenuators hold the steepest expansion curve as utility-scale procurement accelerates.
Application:
Cost tier stratification separates grid-connected bulk power from premium-priced bundled services in water-stressed island economies.
- Power Generation:Grid-connected electricity supply dominates commercial deployment, with European offshore utilities contracting wave energy as baseload renewable capacity. The EU Green Deal marine spatial planning directives in Portugal and Scotland compress consenting timelines for utility-scale arrays.
- Desalination:Wave-driven reverse osmosis systems pair electricity and freshwater output in Caribbean and Pacific island territories. High diesel displacement values and water security premiums improve project IRRs where grid extension is uneconomic.
- Coastal Protection:Breakwater-integrated converters reduce wave energy at harbor entrances while generating electricity. Spanish and Italian port authorities pilot these configurations to share civil works costs across stakeholders.
- Aquaculture:Nearshore installations power offshore fish farm operations and monitoring systems. Norway and Scotland's aquaculture operators test wave-powered autonomous feeding and environmental sensing platforms.
Power generation commands revenue concentration; desalination is climbing fastest on island economy procurement.
End User:
Customer type determines risk allocation structures, with performance guarantees and availability contracts varying sharply across procurement categories.
- Utilities:Offshore power producers in the UK, France, and Portugal contract wave energy developers as independent power producers under long-term power purchase agreements. These offtakers demand IEC 62600-1 type certification and 90%+ availability guarantees.
- Government Agencies:National energy authorities and marine research bodies fund demonstration arrays to de-risk technology for commercial scale-up. Australia's NOPSEA and Scotland's Marine Scotland provide streamlined permitting pathways for publicly supported projects.
- Research Institutions:Universities and national laboratories operate test berths to validate converter control algorithms and array interaction models. The European Marine Energy Centre in Orkney and Portugal's WavEC anchor collaborative R&D programs.
- Industrial Users:Offshore oil platform operators and remote mining sites evaluate wave energy for diesel displacement. North Sea decommissioning timelines and supply vessel electrification create niche demand for autonomous power systems.
Utilities dominate procurement volume; government agencies are expanding fastest on Green Deal demonstration funding.
Deployment:
Geography and water depth segmentation shapes mooring complexity, installation vessel requirements, and grid interconnection liability allocation.
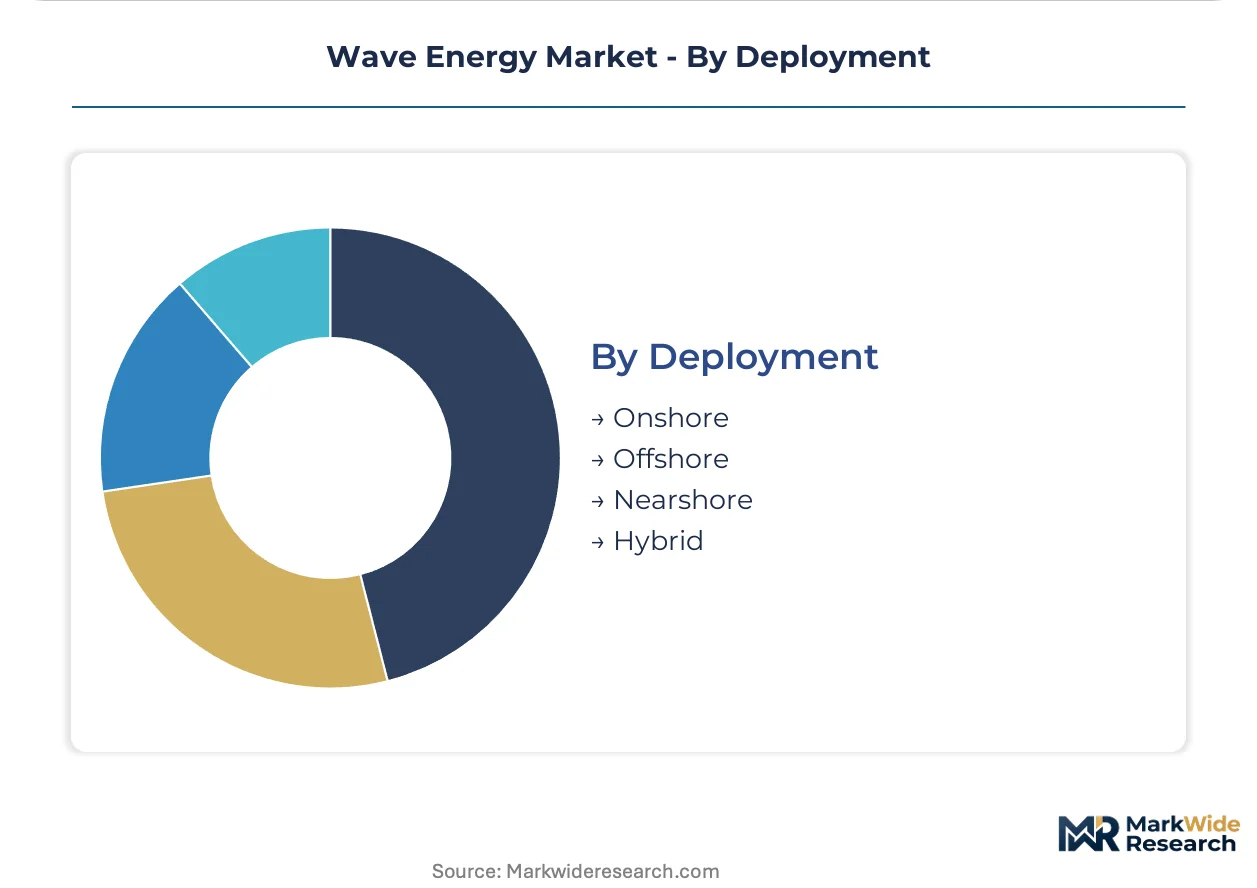
- Offshore:Deepwater installations beyond 50 meters depth access higher wave energy densities but require dynamic positioning vessels and synthetic mooring systems. The UK and Portugal lead procurement of floating arrays for utility-scale generation.
- Nearshore:Intermediate depth deployments between 10-50 meters balance resource access with installation logistics. Eco Wave Power and similar developers target this band to reduce capital intensity and accelerate project timelines.
- Onshore:Cliff-mounted or shoreline-integrated systems eliminate mooring costs entirely. Oscillating water column retrofits at existing breakwaters in Spain and Australia concentrate in this category.
- Hybrid:Configurations combining wave energy with offshore wind platforms or aquaculture infrastructure share foundation and cable costs. The EU's multi-use platform initiatives in the North Sea and Atlantic coast pilot these integrated designs.
Offshore retains capacity leadership; nearshore is gaining share fastest on deployment speed advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scotland deploys wave energy primarily for utility-scale baseload procurement, while Australia and Japan favor island desalination bundles and coastal protection integration respectively. This consumption-mix differential shapes converter topology preferences and regulatory urgency across Atlantic and Pacific markets.
United Kingdom
Scottish offshore utilities contract wave energy as firm renewable capacity to balance intermittent wind portfolios. Marine Scotland's licensing framework compresses consenting timelines for demonstration arrays in Orkney waters. The European Marine Energy Centre anchors collaborative R&D programs validating converter control algorithms.
Portugal
Utility-scale procurement favors attenuator designs for Atlantic swell climates supporting higher capacity factors. AICEP ocean energy concessions streamline permitting pathways at the Agucadoura test zone. WavEC collaborative programs cluster demonstration projects along the northern coastline.
Australia
Island economies in the Pacific territory combine wave-powered desalination with electricity generation to displace diesel. NOPSEA's risk-based assessment framework for offshore infrastructure reduces certification cycles relative to European counterparts. Western Australian breakwaters host oscillating water column retrofits leveraging existing civil infrastructure.
Japan
Coastal protection bundling creates dual-revenue streams for seawall-integrated terminator installations. METI marine energy programs fund demonstration arrays to de-risk technology for commercial scale-up. Northern prefectures pilot breakwater-integrated configurations sharing civil works costs across port authorities.
Spain
Retrofit applications at existing breakwaters concentrate oscillating water column deployments to cut capital intensity. The EU Green Deal marine spatial planning directives mandate streamlined consenting for ocean energy demonstration zones. Basque Country port authorities test coastal protection configurations reducing wave energy at harbor entrances.
Wave Energy Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in wave energy converter development. The capital-intensity divergence between offshore scale players and nearshore deployment specialists is bifurcating competitive tiers. Three archetypes dominate: advanced control system developers, simplified nearshore installers, and hybrid multi-use platform integrators. Strategic moves concentrate on phased array architecture licensing and integrated service contracts bundling equipment with long-term availability guarantees.
Among the integrated offshore tier, CorPower Ocean and Ocean Power Technologies represent high-complexity developers leveraging sophisticated control architectures. Eco Wave Power occupies a distinct position within the nearshore specialist tier, anchoring deployment strategies that reduce mooring complexity. Carnegie Clean Energy exemplifies the hybrid archetype, sitting within configurations that bundle wave energy with coastal infrastructure and aquaculture applications.
| Leading Market Players |
|---|
| CorPower Ocean |
| Ocean Power Technologies |
| Eco Wave Power |
| Carnegie Clean Energy |
| Seabased |
| AW-Energy |
| Mocean Energy |
| Bombora Wave Power |
| Wave Swell Energy |
| Others |
Supply Flow & Price Mechanics
IEC 62600-1 type certification gates both supplier qualification and price differentiation in wave energy converter procurement, with certified developers commanding premium contract terms while uncertified vendors compete on installation speed alone. This regulatory threshold simultaneously constrains the supplier base and stratifies buyer willingness-to-pay across utility and demonstration project categories.
Pricing Analysis
Long-term power purchase agreements dominate commercial procurement, with European offshore utilities contracting wave energy developers as independent power producers rather than equipment vendors. Price differentiation rests on IEC certification tier and array availability guarantees, with 90%+ uptime commitments separating premium from standard tiers. Cost compression in nearshore installations is intensifying because Eco Wave Power and similar specialists reduce mooring complexity. Government-funded demonstration projects exhibit lowest price sensitivity; utility offtakers face highest procurement scrutiny.
Supply Chain Analysis
Synthetic rope and anchor chain supply from Norway, South Korea, and the Netherlands creates a chokepoint for floating array deployment, with offshore oil rig demand fluctuations feeding through to wave energy project IRRs. Steel hull fabrication draws from legacy oil platform construction yards in Scotland and Portugal, while power take-off systems rest on precision manufacturing concentrated in Germany and Denmark. Single-source vulnerability in dynamic positioning vessel availability poses structural risk. Distribution runs through integrated service contracts bundling equipment with long-term availability guarantees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among European offshore utilities contracting wave energy as firm renewable capacity, with procurement consolidation favoring developers who can deliver integrated IPP structures over pure equipment vendors.
For Market Incumbents: Secure phased array architecture licensing agreements to defend against attenuator specialists capturing utility-scale procurement in the UK and France. Lock in synthetic mooring supply contracts before offshore oil demand recovery tightens availability. Deepen backward integration into power take-off system manufacturing to protect margins from precision component price volatility. For New Entrants and Emerging Players: Differentiate on nearshore deployment velocity to capture island economy desalination bundling opportunities in Caribbean and Pacific territories. Target Australia's NOPSEA streamlined approval pathway for faster revenue recognition than European counterparts. Lead with wave-powered reverse osmosis integrated proposals rather than electricity-only offerings. For Investors and Strategic Acquirers: EU Green Deal marine spatial planning implementation reshapes the acquisition landscape by clarifying grid interconnection liability allocation in Portugal and Scotland. Five-to-ten year viability hinges on which developers achieve commercial-scale deployment before demonstration funding exhausts. Target acquisition archetype: nearshore specialists with proven installation track records and existing utility relationships. Watch for IEC 62600-1 certification completion as inflection indicator for revenue-ready assets.| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Structuring | Shifts performance risk onto developers under long-term utility contracts in the UK and France. |
| Backward Integration into Mooring Systems | Captures synthetic rope and anchor chain margin currently exposed to offshore oil demand cycles. |
| Technology Licensing to Array Developers | Monetizes control system IP through phased architecture royalties without capital-intensive manufacturing. |
| Desalination Bundling Partnerships | Opens Caribbean and Pacific island procurement with dual-revenue electricity and freshwater contracts. |
| Certification Fast-Track Investment | Accelerates IEC 62600-1 type approval to meet utility procurement mandates requiring certified equipment. |
Methodological Framework
Operator-level perspectives from utility procurement officers, wave energy converter developers, marine EPC contractors, and grid interconnection specialists anchored the qualitative base. Primary interviews triangulated against secondary sources including FERC filings, IEA ocean energy reports, Marine Scotland licensing databases, and project development registries. Bottom-up installation forecasts across converter topologies reconciled with top-down renewable procurement targets.
Sensitivity analysis tested capacity factor assumptions and capital cost trajectories across the projection horizon. Segmentation dimensions modeled include converter technology, deployment depth, application pairing, and end-user procurement type. CAGRs derived from installed capacity buildout curves and unit cost experience effects. Forecast inputs incorporated marine spatial planning implementation timelines and synthetic mooring cost indices.
Material uncertainties — regulatory consenting delays, grid liability allocation reversals, and offshore oil sector demand shocks — sit outside the modeled envelope. Forecasts reflect assumptions about certification timeline compression and utility procurement appetite for unproven baseload capacity. Revision becomes warranted when synthetic rope supply constraints or marine engineering labor scarcity cross thresholds that stall project financial close.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Romania Solar Energy Market
Renewable Energy
Europe Ocean Power Market
Renewable Energy
Republic of Ireland Renewable Energy Market
Renewable Energy
Canada Renewable Energy Market
Renewable Energy
Renewable Energy Inverters Market
Renewable Energy
South Africa Renewable Energy Market
Renewable Energy
Renewable Energy Consulting Market
Renewable Energy
Spain Renewable Energy Market
Renewable Energy
Singapore Renewable Energy Market
Renewable Energy
Europe Solar Tracker Market
Renewable Energy
Israel Renewable Energy Market
Renewable Energy
South Europe Renewable Energy Market
Renewable Energy
Italy Renewable Energy Market
Renewable Energy
Romania Power Market
Renewable Energy
Solar Navigation Light Market
Renewable Energy
West Europe Renewable Energy Market