
 South America Hydropower Market | 2026-2036
South America Hydropower Market Size, Share, and Industry Trends Forecast 2026-2036
South America Hydropower Market Analytics
Modular turbine-generator packages are decoupling equipment procurement from full EPC contracts, letting buyers source Francis and Kaplan units separately from civil works. Centrais Elétricas Brasileiras S.A. leverages its federal scale to dominate refurbishment cycles across legacy reservoirs. Itaipu Binacional anchors binational coordination protocols between Brazil and Paraguay. ENGIE Brasil Energia SA differentiates through run-of-river portfolios that minimize resettlement exposure.
South America hydropower harnesses gravitational energy from river flow through concrete dam structures, penstock systems, and electromechanical turbine-generator assemblies rated from micro-scale sub-100 kW units to multi-gigawatt reservoir complexes. Its primary purpose is dispatchable baseload generation for national grids and energy-intensive industrial offtakers. Large reservoir projects still occupy the dominant share of installed capacity, yet small hydropower and pumped storage segments attract faster permitting timelines and private capital inflows. Turbine-generator technology choices increasingly split by head height: Francis units lead in medium-head Brazilian installations, while Pelton configurations sustain niche positions in Andean terrain.
Brazil's national electric energy regulator and the country's environmental licensing framework shape project timelines through reservoir impact assessments and indigenous consultation mandates. ANA water-use permits and grid-connection standards from ONS dictate operational parameters for new entrants. Paraguay's binational treaty obligations with Itaipu constrain unilateral capacity reallocations. Stakeholders must monitor how drought-frequency modeling reshapes reservoir dispatch strategies and long-term power purchase agreement pricing.
Market Dynamics
Digital turbine control systems are compressing refurbishment timelines across Brazil's aging reservoir fleet, forcing asset owners to choose between full electromechanical replacement and modular retrofit packages that preserve existing civil structures.
Growth Catalysts
- Industrial offtake commitments:Brazilian aluminum smelters and iron ore miners anchor long-term power purchase agreements that underwrite greenfield reservoir financing. Mining operations in Minas Gerais and Pará states contract directly with generators for firm baseload supply.
- ANA water-use permitting:Brazil's National Water Agency streamlined concession timelines for run-of-river projects under 30 MW, accelerating private capital deployment in small hydropower segments. These permits bypass reservoir impact assessment requirements that stall large dam approvals.
- Binational treaty frameworks:Itaipu Binacional's governance structure between Brazil and Paraguay creates replicable templates for cross-border generation assets. Treaty protocols standardize revenue allocation and operational coordination across shared watersheds.
Market Restraints
- Steel and copper input volatility:Turbine-generator fabrication depends on specialty alloys and winding copper whose prices fluctuate with commodity cycles. Equipment suppliers in São Paulo and Curitiba states face margin compression when raw material costs spike without indexed contract clauses.
- Transmission corridor saturation:Southeastern Brazil's existing 500 kV and 800 kV DC lines approach thermal limits, constraining evacuation from new generation sites. Grid congestion forces developers to fund dedicated transmission spurs that erode project returns.
- Reservoir sedimentation rates:Andean tributaries carry high particulate loads that accelerate turbine abrasion and reduce active storage capacity. Operators in Bolivia and Ecuador absorb unplanned maintenance cycles that disrupt dispatch schedules.
Strategic Opportunities
- Pumped storage development:Closed-loop configurations in Chile's Atacama Desert and Argentina's Patagonia offer grid stabilization services without the resettlement conflicts that plague conventional reservoirs. These projects pair with expanding solar portfolios to provide diurnal storage.
- Indigenous consultation protocols:Brazil's FUNAI engagement mandates, while extending timelines, create first-mover advantages for developers who establish sustained community benefit structures. Early movers secure exclusive access to watersheds in Amapá and Roraima states.
- Digital twin integration:Convergence of computational fluid dynamics with SCADA telemetry enables predictive maintenance that extends turbine runner life. Asset managers in Paraguay deploy these systems to optimize gate scheduling and minimize cavitation damage.
Industry Challenges
- Electromechanical specialist scarcity:Francis turbine blade welding and Kaplan runner machining require craft skills that Brazilian technical institutes no longer emphasize. Equipment OEMs compete for aging field technicians who can execute precision alignments on 50-year-old shaft assemblies.
- ONS grid-code compliance:Brazil's national system operator mandates frequency response and reactive power capabilities that legacy governors cannot satisfy without complete excitation system replacement. Retrofit projects stall when owners underestimate control system integration complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Hydropower Market |
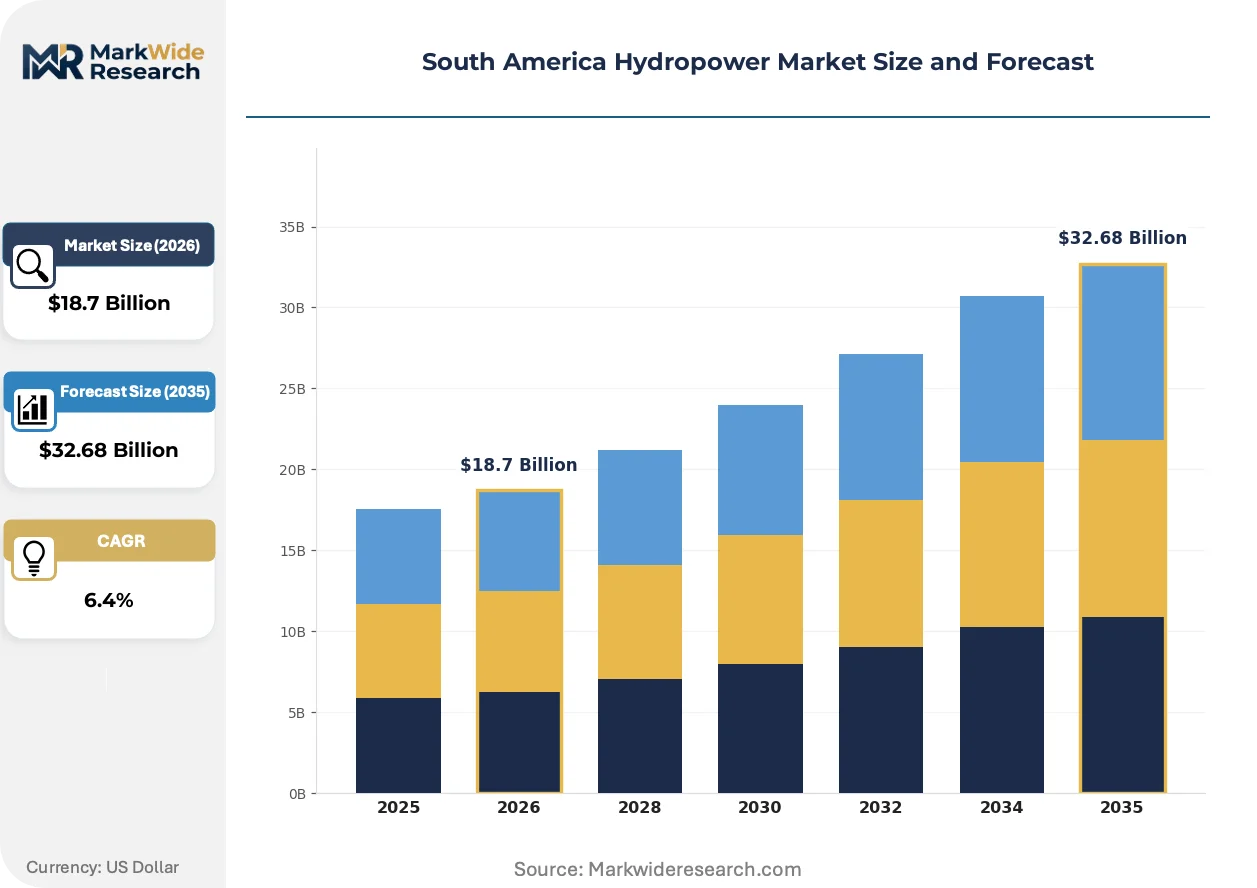
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Run-of-River, Reservoir, Pumped Storage, Small Hydropower Plant Capacity: Micro, Mini, Small, Large Technology: Francis, Kaplan, Pelton, Turbine-Generator End User: Utility Companies, Industrial Users, Residential, Government |
| Companies Covered | Centrais Elétricas Brasileiras S.A., Itaipu Binacional, ENGIE Brasil Energia SA, China Three Gorges Brasil Energia S.A., Enel Américas, AES Brasil Energia S.A., Companhia Paranaense de Energia, Companhia Energética de Minas Gerais, EDP Energias do Brasil S.A., Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Hydropower Market Evolving Landscape
Modular turbine-generator procurement is fragmenting the traditional EPC bundle, letting developers source electromechanical packages separately from civil contractors and compress overall project schedules.
Variable-speed Francis units with full converter coupling are overtaking synchronous generator configurations in medium-head Brazilian installations. Mining and pulp-sector offtakers in São Paulo state specify these systems for their enhanced frequency regulation capabilities. The technology is overtaking fixed-speed alternatives by enabling grid-forming inverters that stabilize weak network nodes without synchronous condenser support.
Brazil's environmental licensing framework under IBAMA now mandates cumulative impact assessment for sequential reservoir development in shared watersheds. Developers in the Tocantins and São Francisco basins must model ecosystem effects across multiple projects rather than evaluating sites in isolation. This regulatory tightening most affects sequential developers in Pará and Minas Gerais states, who now front-load biological baseline studies to secure competitive advantage in permitting queues.
Power purchase agreement structures are unbundling energy and capacity components, letting industrial buyers optimize exposure to spot price volatility. Aluminum smelters in Maranhão state now contract for firm capacity rights while sourcing variable energy volumes through short-term markets. This behavioral shift is most visible among electro-intensive industries in northern Brazil, where transmission constraints create persistent price differentials that sophisticated buyers exploit through locational scheduling.
South America Hydropower Market Segmentation
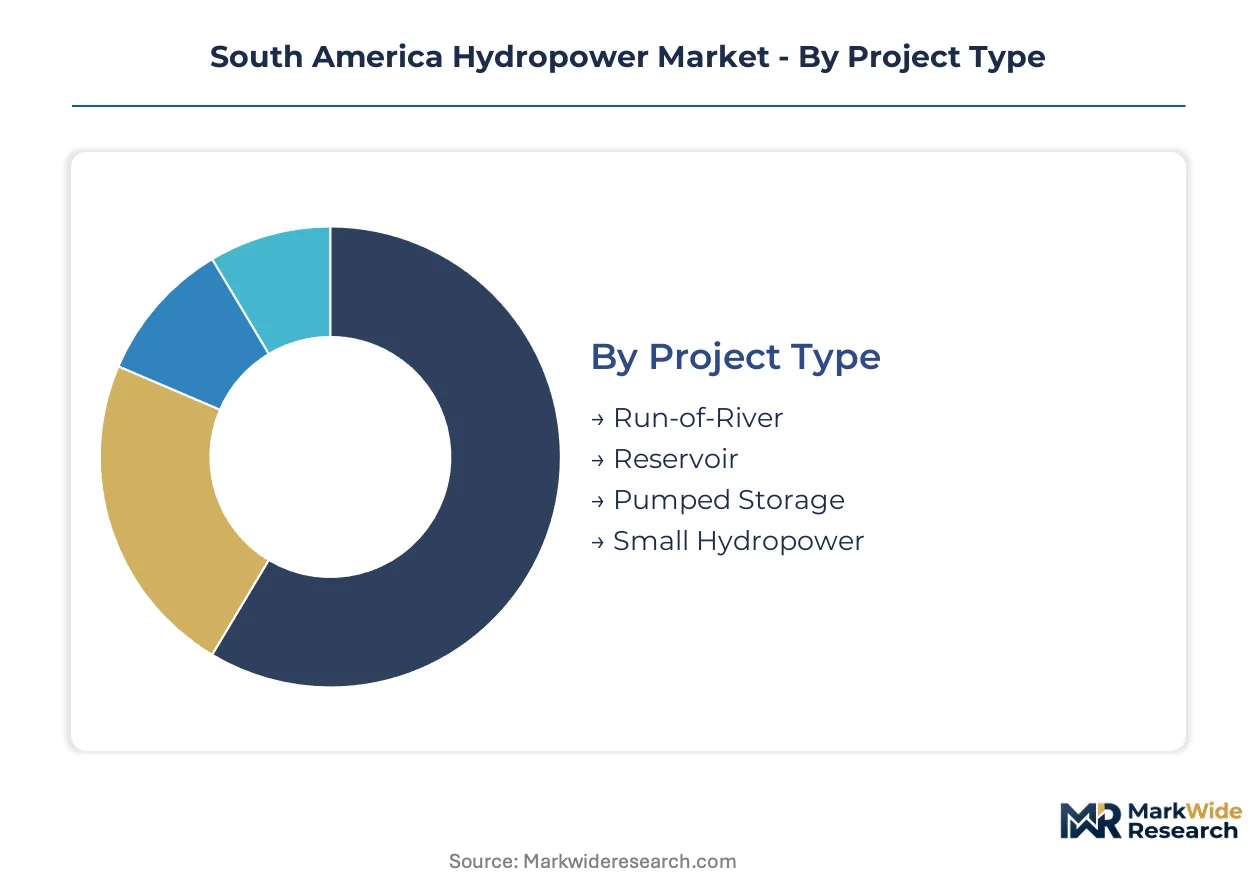
Hydropower project economics diverge sharply across configuration types and scale thresholds in South America. Segmentation reveals how civil works intensity, permitting timelines, and offtake contract structures reshape competitive positioning for developers and equipment suppliers.
Project Type:
Buyers in this category separate by resettlement exposure and water storage rights rather than generation technology alone.
- Run-of-River:These facilities divert river flow through intake weirs and penstocks without significant impoundment, eliminating reservoir communities. ENGIE Brasil Energia SA and private developers in São Paulo state favor this configuration to bypass IBAMA's cumulative impact assessments and accelerate ANA water-use permitting.
- Reservoir:Large dam structures with active storage capacity dominate Brazilian installed base and anchor long-term power purchase agreements with Minas Gerais aluminum smelters. Centrais Elétricas Brasileiras S.A. controls refurbishment cycles across these legacy assets where sedimentation and drought-frequency modeling now reshape dispatch strategies.
- Pumped Storage:Closed-loop configurations in Chile's Atacama Desert and Argentina's Patagonia provide grid stabilization services paired with expanding solar portfolios.
- Small Hydropower:Projects under 30 MW exploit streamlined ANA concession timelines that bypass reservoir impact assessments, concentrating private capital inflows.
Volume sits with Reservoir; growth tilts toward Run-of-River.
Plant Capacity:
Scale thresholds determine regulatory jurisdiction and financing source availability across South American markets.
- Large:Multi-gigawatt complexes like Itaipu Binacional operate under binational treaty frameworks with standardized revenue allocation protocols. These assets anchor national grid stability and absorb the bulk of electromechanical specialist labor pools in Brazil's southeastern states.
- Small:Installations between 1 MW and 30 MW attract faster permitting timelines and private capital inflows through ANA's streamlined water-use concessions. Developers in Pará and Tocantins basins front-load biological baseline studies to secure competitive advantage in these queues.
- Mini:Systems between 100 kW and 1 MW serve isolated industrial loads and rural electrification programs.
- Micro:Sub-100 kW units address remote residential demand in Amapá and Roraima watersheds.
Large-scale assets command capital deployment; Small-scale projects are expanding most quickly.
Technology:
Turbine-generator selection hinges on head height, flow variability, and grid-code compliance requirements rather than unit cost alone.
- Francis:Variable-speed configurations with full converter coupling are overtaking synchronous generator alternatives in medium-head Brazilian installations. Mining and pulp-sector offtakers in São Paulo specify these systems for enhanced frequency regulation and grid-forming inverter capabilities that stabilize weak network nodes.
- Turbine-Generator:Modular procurement packages are decoupling electromechanical sourcing from full EPC contracts, letting buyers compress project schedules. Digital twin integration with SCADA telemetry enables predictive maintenance that extends runner life across Paraguayan and Brazilian asset portfolios.
- Kaplan:Adjustable-blade designs sustain niche positions in low-head, high-flow river sections.
- Pelton:Impulse turbine configurations maintain limited deployment in Andean high-head terrain.
Francis units dominate procurement volume; Turbine-Generator modularization is gaining share fastest.
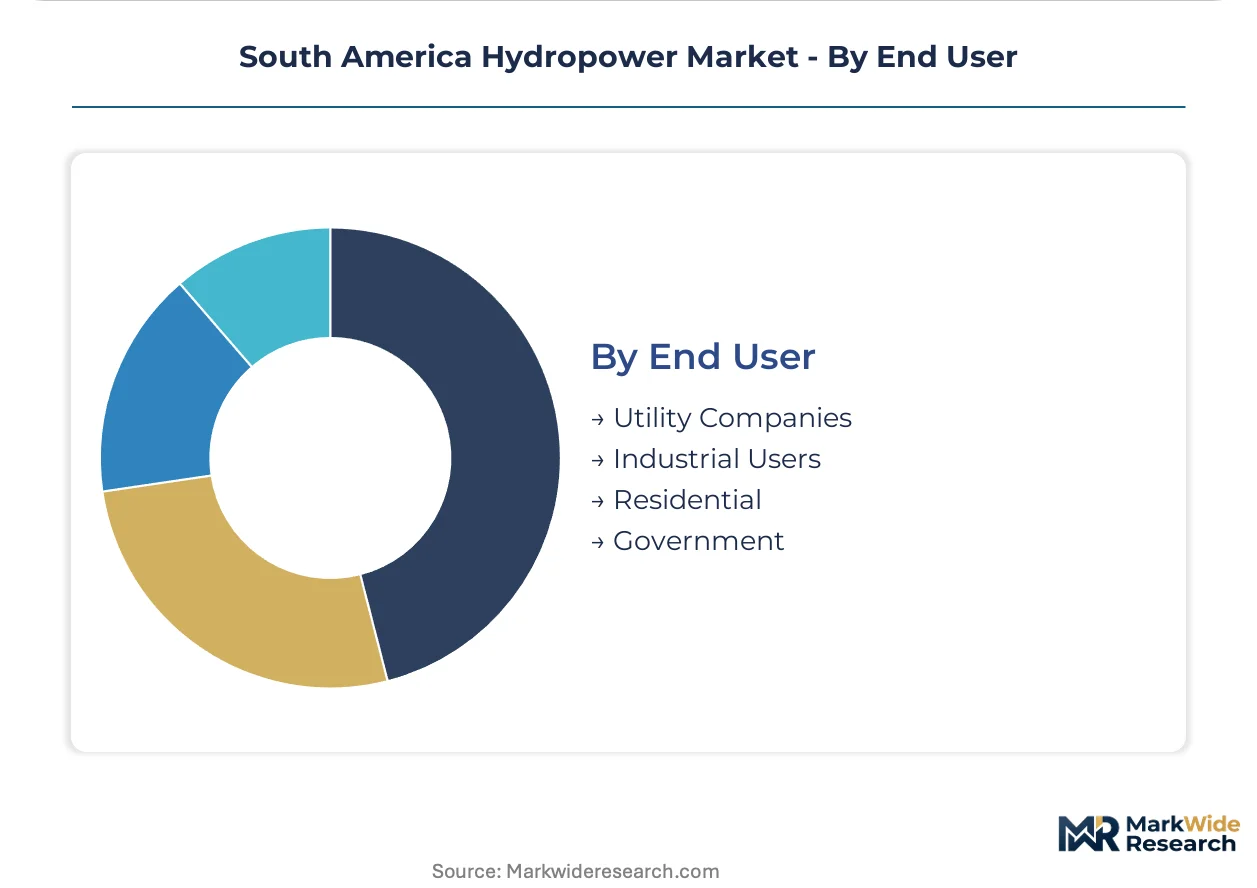
End User:
Contract structures and price risk allocation distinguish offtake categories in South America's power markets.
- Industrial Users:Aluminum smelters and iron ore miners in Maranhão and Pará states now unbundle energy and capacity components in power purchase agreements. These electro-intensive buyers contract for firm capacity rights while sourcing variable energy volumes through short-term markets, exploiting locational price differentials created by transmission constraints.
- Utility Companies:Grid operators and distribution utilities procure dispatchable baseload under ONS grid-code mandates that legacy governors cannot satisfy without excitation system replacement. Compliance investments concentrate in southeastern Brazil's aging reservoir fleet.
- Government:Public sector offtakers support rural electrification and indigenous community benefit structures in Amapá and Roraima.
- Residential:Distributed micro-hydropower serves isolated settlements beyond centralized grid reach.
Utility procurement anchors installed capacity; Industrial offtake shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil generates surplus hydropower capacity while neighboring markets absorb cross-border flows. Argentina and Chile import firm baseload during drought cycles. Transmission interconnection projects reshape regional power trade economics.
Brazil
Southeastern reservoir complexes anchor continental supply as Minas Gerais aluminum smelters contract for firm dispatch. ANA water-use permits and ONS grid-code compliance dictate project timelines across the Tocantins and São Francisco basins. São Paulo state concentrates run-of-river development where ENGIE Brasil Energia SA minimizes resettlement exposure through diversion-weir configurations.
Paraguay
Itaipu Binacional's binational treaty framework constrains unilateral capacity reallocations while standardizing revenue protocols with Brazil. The country's national electric regulator oversees dispatch coordination across shared 50 Hz and 60 Hz systems. Ciudad del Este industrial parks absorb surplus generation through dedicated high-voltage corridors.
Argentina
Patagonian pumped storage projects pair with expanding solar portfolios to provide diurnal grid stabilization without reservoir conflicts. The country's federal energy secretariat licenses closed-loop configurations under streamlined environmental protocols. Neuquén basin developers front-load geological assessments to secure competitive advantage in concession queues.
Chile
Atacama Desert closed-loop pumped storage attracts private capital for grid services supporting mining sector electrification. The national energy commission's transmission expansion plans reduce evacuation constraints from remote generation sites. Antofagasta region concentrates developer activity where copper producers seek firm renewable supply.
Colombia
Andean high-head terrain sustains Pelton turbine deployments where sediment-laden tributaries challenge runner durability. The country's environmental licensing authority mandates cumulative impact assessment for sequential reservoir development. Cauca Valley operators absorb unplanned maintenance cycles from accelerated turbine abrasion.
South America Hydropower Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across equipment procurement and asset operation. Market structure tilts toward consolidation among federal-scale operators with legacy reservoir control, while private developers fragment across run-of-river niches. Three archetypes dominate: state-linked federal utilities, European-headquartered energy majors with regional subsidiaries, and Chinese state-owned enterprises deploying capital through acquisition. Competitive moves center on modular turbine-generator procurement decoupled from EPC contracts, and digital control system retrofits that compress refurbishment timelines.
Among Brazil-domiciled operators, Centrais Elétricas Brasileiras S.A. occupies a position exemplifying federal-scale consolidation across legacy reservoir refurbishment cycles. Itaipu Binacional represents binational governance architecture that anchors cross-border coordination protocols. ENGIE Brasil Energia SA sits within the European-major archetype, differentiating through run-of-river portfolios that minimize resettlement exposure in São Paulo state permitting queues.
| Leading Market Players |
|---|
| Centrais Elétricas Brasileiras S.A. |
| Itaipu Binacional |
| ENGIE Brasil Energia SA |
| China Three Gorges Brasil Energia S.A. |
| Enel Américas |
| AES Brasil Energia S.A. |
| Companhia Paranaense de Energia |
| Companhia Energética de Minas Gerais |
| EDP Energias do Brasil S.A. |
| Others |
Value Network & Pricing Analysis
Francis turbine blade welders concentrated in São Paulo and Curitiba states command wage premiums that widen pricing spreads between premium electromechanical packages and economy retrofit tiers. Labor-cost differentials across Brazilian technical institutes reshape how equipment OEMs tier their turbine-generator offerings.
Pricing Analysis
Margin tightening in standard turbine-generator tiers traces to steel and copper alloy volatility that equipment suppliers cannot fully pass through without indexed contract clauses. Three-tier pricing structure across premium, standard, and economy levels separates digital twin-enabled predictive maintenance bundles from basic governor retrofits. Price differentiation hinges on ANA water-use permit expediting services and ONS grid-code compliance certification. Aluminum smelters in Maranhão state exhibit highest price sensitivity, while federal utilities absorb premium tiers for legacy reservoir refurbishment cycles.
Supply Chain Analysis
Brazil's local-content mandates under BNDES financing rules reshape sourcing patterns, compelling foreign OEMs to establish machining partnerships in Minas Gerais and Pará states. Turbine-generator fabrication draws from specialty alloy foundries in Germany, precision winding suppliers in China, and control system integrators in South Korea. Single-source vulnerability concentrates in Francis runner casting capacity. Distribution runs through EPC contractors who bundle civil works with electromechanical procurement, though modular sourcing is fragmenting this structure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IBAMA's cumulative impact assessment mandates for sequential reservoir development create a cost-of-compliance moat that rewards developers who front-loaded biological baseline studies in Tocantins and São Francisco basins.
For Market Incumbents: Acquire distressed small hydropower portfolios in Pará state where ANA's streamlined concessions attracted overleveraged private developers. Consolidation captures run-of-river assets with intact water-use rights while distressed sellers face refinancing cliffs. Backward integration into Francis runner machining capabilities in Curitiba defends against electromechanical specialist scarcity threatening refurbishment timelines. For New Entrants and Emerging Players: The price-point gap between premium digital-twin-enabled turbine packages and economy synchronous-generator retrofits opens entry space for mid-tier variable-speed Francis configurations. White-space concentrates in São Paulo state run-of-river development where ENGIE Brasil Energia SA's permitting advantages have not fully saturated viable watersheds. Go-to-market leverage rests on pre-negotiated indigenous consultation protocols with FUNAI that compress IBAMA licensing timelines. For Investors and Strategic Acquirers: Re-rating potential sits with federally-scaled utilities possessing legacy reservoir control and established ONS grid-code compliance infrastructure given ANA's tightening water-use permit scarcity. Long-term viability favors operators with contracted industrial offtake from Minas Gerais aluminum smelters and iron ore miners. The signal to watch is drought-frequency model revisions that reshape power purchase agreement pricing and reservoir dispatch valuation.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Integration | Predictive maintenance extends turbine runner life across Paraguayan and Brazilian asset portfolios. |
| Modular Procurement Decoupling | Electromechanical sourcing separate from EPC contracts compresses project schedules for run-of-river developers. |
| Pumped Storage Development | Closed-loop configurations in Chile's Atacama Desert provide grid stabilization without resettlement conflicts. |
| Indigenous Consultation Protocols | Early FUNAI engagement secures exclusive watershed access in Amapá and Roraima states. |
| Variable-Speed Francis Deployment | Full converter coupling enables grid-forming inverters that stabilize weak network nodes in São Paulo. |
Research Methodology
Multi-period observation of ANA water-use permit issuance rates, IBAMA licensing timelines, and ONS grid interconnection queues anchored the trend analysis, supplemented by interviews with utility planning officers, IPP project developers, EPC contractors, and electromechanical equipment OEMs. Secondary validation drew from EIA hydropower capacity data, IEA renewable energy outlooks, FERC comparable market filings, and Brazilian national system operator dispatch records. Bottom-up project pipeline aggregation triangulated against top-down macroeconomic demand modeling.
Segment-weighting across project type, plant capacity, technology configuration, and end-user contract structure informed the analytical framework over the projection horizon. CAGRs derived from capacity addition trajectories, refurbishment cycle intensity, and industrial offtake growth patterns. Forecast inputs incorporated drought-frequency modeling revisions and transmission corridor expansion timelines.
Underlying measurement precision varies by segment; small hydropower and run-of-river categories carry tighter precision than large reservoir developments subject to binational treaty renegotiation risks. Forecasts reflect assumptions around ANA regulatory continuity, IBAMA environmental licensing stringency, and commodity input cost trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydropower Systems
North America Hydropower Market
Hydropower Systems
Europe Hydropower Market
Hydropower Systems
South America Pumped Hydro Storage Market
Hydropower Systems
Europe Small Hydropower Market
Hydropower Systems
France Tidal Power Market
Hydropower Systems
Hydroelectricity Market
Hydropower Systems
Underground Hydro Power Plant Market
Hydropower Systems
Floating Power Plant Market
Hydropower Systems
Hydro Turbines Market
Hydropower Systems
Asia-Pacific Small Hydropower Market
Hydropower Systems
Hydropower Generation Market
Hydropower Systems
Asia-Pacific Hydropower Market
Hydropower Systems
Pumped Hydro Storage Market
Hydropower Systems
Wave and Tidal Energy Market
Hydropower Systems
Southeast Asia Hydropower Market
Hydropower Systems
Asia-Pacific Pumped Hydro Storage Market