
 Pumped Hydro Storage Market | 2026-2036
Pumped Hydro Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Pumped Hydro Storage Market Analysis
The EU Green Deal is decoupling pumped hydro investment from purely commercial returns by embedding storage mandates into national climate plans. Voith Hydro Holding GmbH & Co. KG leverages its turbine manufacturing heritage to dominate European refurbishment cycles. General Electric Company anchors North American project development through integrated power systems expertise. Toshiba Energy Systems & Solutions Corporation competes aggressively on Asian grid stabilization contracts with advanced variable-speed technology.
Pumped hydro storage uses gravitational potential energy by pumping water to an upper reservoir during low demand and releasing it through turbines to generate electricity during peak periods, with typical round-trip efficiencies of 70–85 percent and plant lifespans exceeding fifty years. Conventional surface reservoirs remain the dominant installation type, though underground configurations are gaining traction where topography restricts surface development. The utilities end-user segment commands the largest share of deployed capacity, while renewable integration applications are expanding fastest as wind and solar penetration rises across transmission networks.
The European Union's F-Gas Regulation and CE marking requirements shape equipment standards for turbine and generator imports, while China's MEE enforces environmental impact assessments for reservoir construction. The US FERC streamlines licensing for closed-loop pumped hydro projects exempt from traditional hydropower constraints. Stakeholders must monitor evolving grid codes that redefine frequency response obligations and determine which storage technologies qualify for capacity payments.
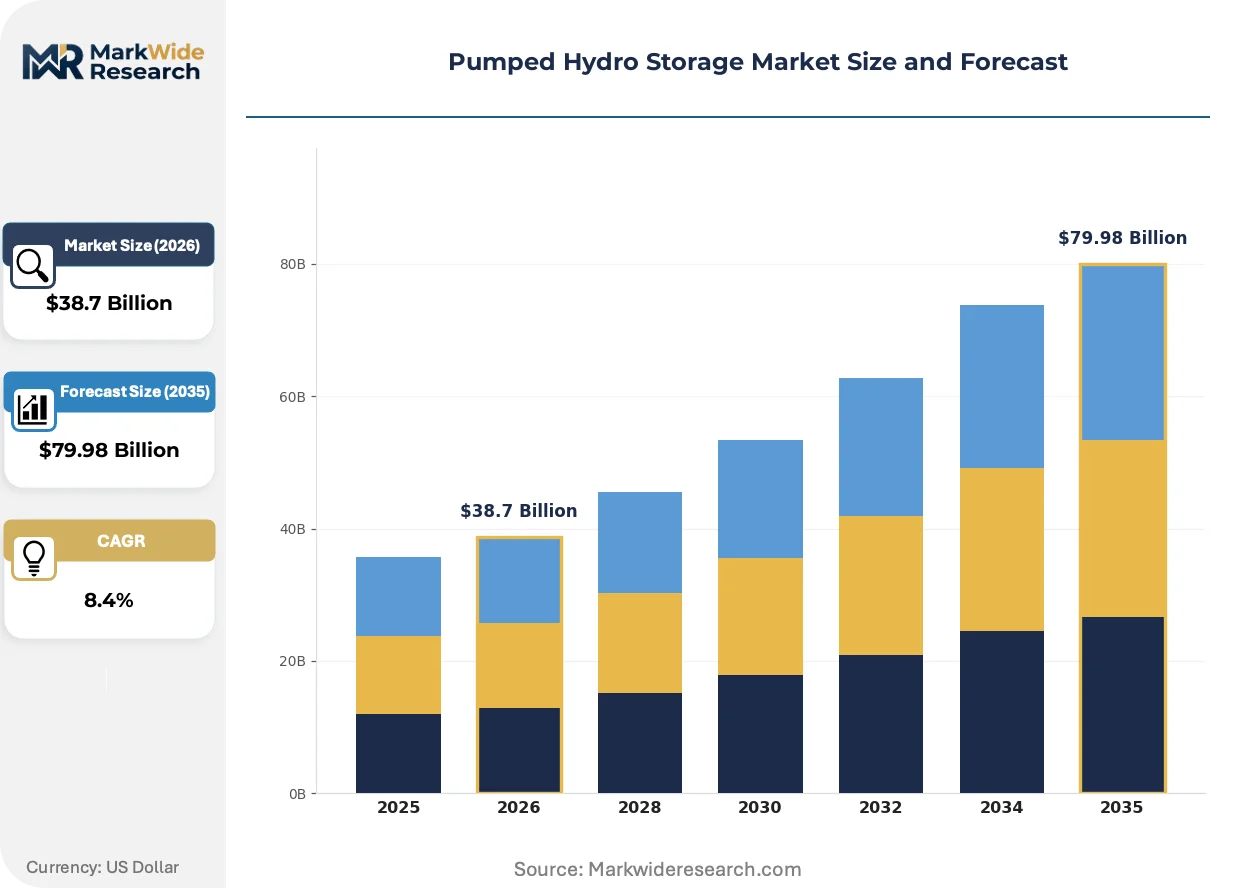
Market Dynamics
Variable-speed pump-turbine technology is compressing plant response times from minutes to seconds, forcing grid operators to rewrite frequency regulation contracts and disqualify fixed-speed assets from new ancillary service markets.
Growth Catalysts
- EU Green Deal storage mandates:National climate plans in Germany and Spain now embed long-duration storage obligations into renewable auction criteria, guaranteeing offtake for new pumped hydro capacity.
- Intermittency management:Grid operators across Vietnam and the Philippines are procuring pumped hydro specifically to absorb midday solar oversupply and discharge during evening demand peaks.
- China's dual carbon goals:The MEE has streamlined environmental impact assessments for reservoir construction in Yunnan and Sichuan provinces, cutting permitting timelines for mountainous developments.
Market Restraints
- Geologic site scarcity:Suitable elevation differentials with adequate water availability concentrate in Norway, Switzerland, and Vietnam, leaving most markets dependent on underground cavern configurations with 40-60% higher civil engineering costs.
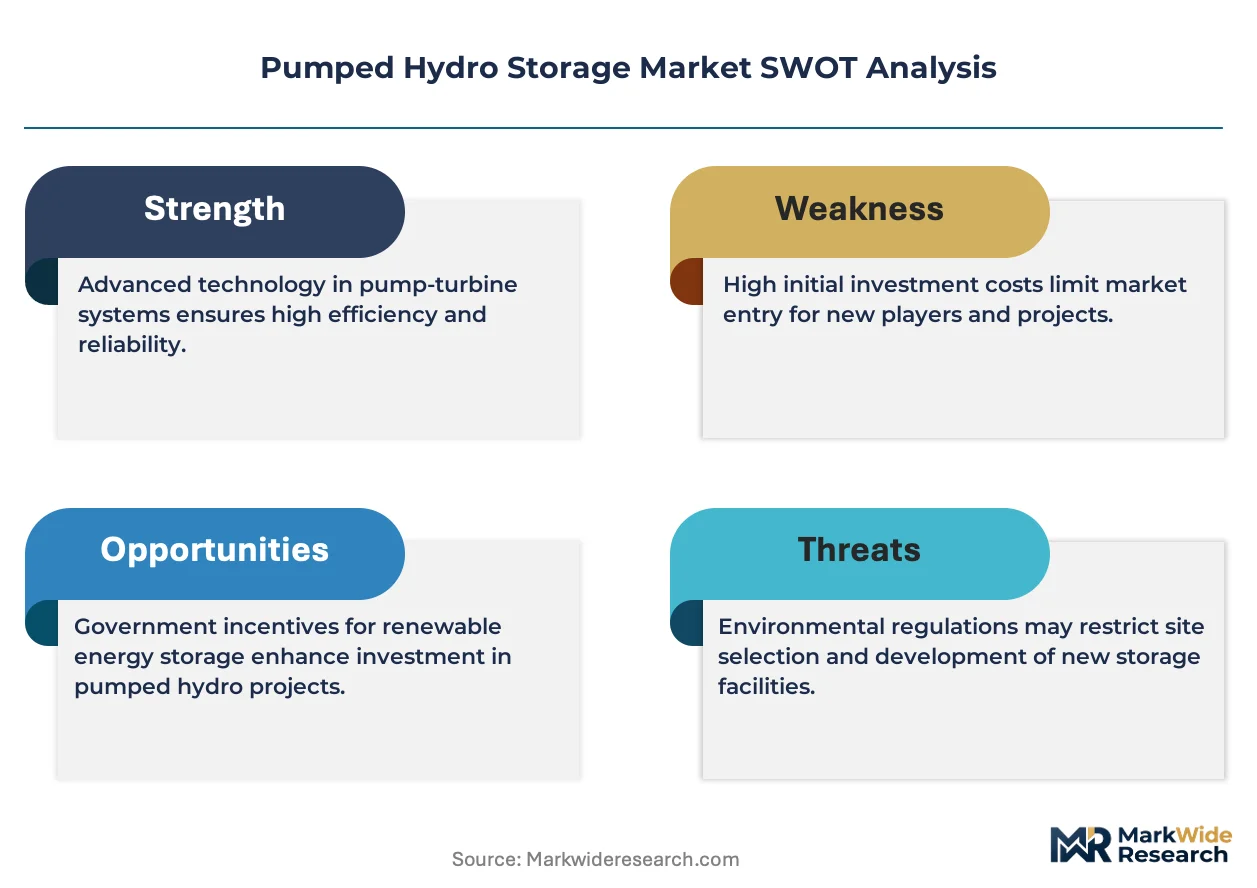
- Lithium-ion substitution:Battery energy storage systems are capturing frequency regulation and short-duration peak shaving contracts that historically anchored pumped hydro economics.
- F-Gas Regulation compliance:The EU's phasedown of sulfur hexafluoride for switchgear insulation is forcing turbine manufacturers to redesign generator cooling systems, extending equipment qualification cycles.
Strategic Opportunities
- Closed-loop development:The US FERC's 2023 licensing exemption for off-river pumped hydro eliminates traditional hydropower constraints, opening development in flat terrain states like Texas and Oklahoma.
- Seawater configurations:Coastal installations in Japan and Chile are eliminating upper reservoir construction costs by using the ocean as the lower reservoir, halving civil works expenditure.
- Hybrid solar-pumped hydro:Floating photovoltaic arrays on upper reservoirs in Vietnam and India are reducing evaporation losses while adding daytime generation capacity to the same land footprint.
Industry Challenges
- Turbine engineering specialization:Variable-speed reversible pump-turbine design requires rare expertise in hydraulic machinery and power electronics integration, with fewer than twelve qualified engineering firms globally.
- Transmission interconnection queues:Grid connection studies for remote mountainous sites in Norway and Switzerland are extending project timelines by three to five years as transmission operators prioritize renewable generation interconnection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pumped Hydro Storage Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Conventional, Underground, Above-ground, Modular End User: Utilities, Industrial, Commercial, Residential Application: Grid Stabilization, Renewable Integration, Load Shifting, Frequency Regulation Installation: New Installations, Retrofits, Upgrades, Hybrid Systems |
| Companies Covered | General Electric Company, Toshiba Energy Systems & Solutions Corporation, Voith Hydro Holding GmbH & Co. KG, Mitsubishi Power Ltd., Hitachi Energy Ltd., ANDRITZ Hydro GmbH, Siemens Energy AG, Harbin Electric Machinery Company Limited, Dongfang Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pumped Hydro Storage Market Emerging Trajectories
Digital twin modeling and modular turbine designs are collapsing the traditional decade-long development cycle for pumped hydro projects, while regulatory frameworks scramble to accommodate technologies that did not exist when most licensing statutes were written.
Ternary pump-turbine configurations with three hydraulic runners are decentralizing the tradeoff between pumping efficiency and generation efficiency that has constrained conventional reversible units for decades. Swiss and Austrian utilities are retrofitting existing plants with ternary sets to capture intraday price arbitrage that was previously uneconomical. This technology is decentralizing the operational flexibility premium away from battery storage and back toward mechanical storage assets with fifty-year lifespans.
The EU F-Gas Regulation's 2036 phaseout deadline for SF6-insulated switchgear is forcing a wholesale redesign of generator step-up transformer and circuit breaker packages. Equipment manufacturers are accelerating development of fluoronitrile-based insulation systems and vacuum interrupter technologies. European turbine OEMs are most exposed, as their installed base relies heavily on SF6-dependent switchgear configurations that cannot be retrofitted economically.
Utility procurement departments are unbundling engineering-procurement-construction contracts into separate design, equipment supply, and civil works packages to attract non-traditional developers. This disaggregation is displacing the integrated consortia that have dominated pumped hydro construction since the 1970s. The shift is most visible in Southeast Asia, where Vietnamese and Indonesian state utilities are solicating competitive bids for turbine-generator packages separately from dam and tunnel construction.
Pumped Hydro Storage Market Segmentation
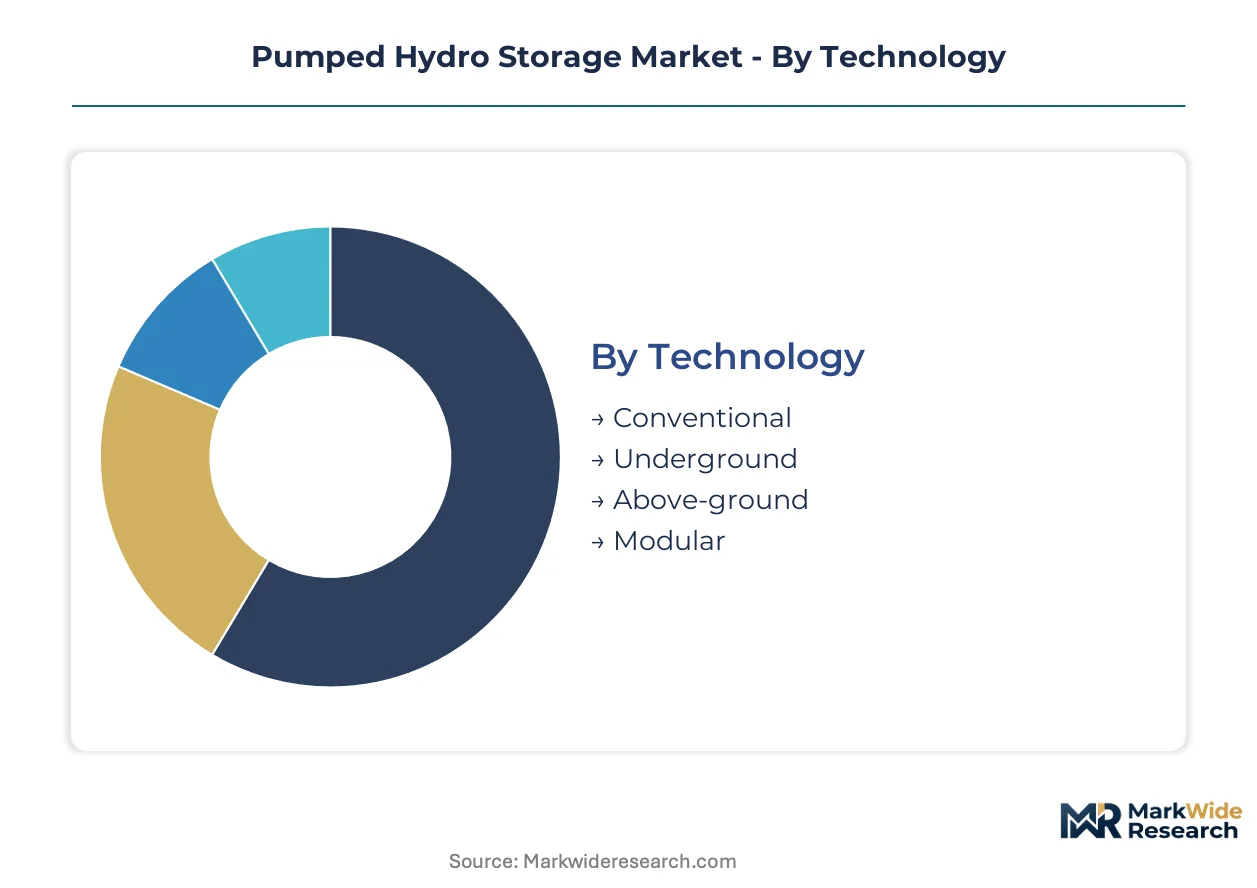
Pumped hydro storage deployment patterns diverge sharply between established utility-scale installations and emerging distributed configurations. Technology selection and end-user priorities determine project economics, civil engineering requirements, and regulatory pathways across distinct market strata.
Technology:
Volume deployment concentrates in surface reservoir configurations with proven cost structures, while premium pricing attaches to specialized underground and modular systems that circumvent topographic constraints.
- Conventional:Surface reservoirs with upper and lower water bodies connected by penstocks and powerhouse facilities. Utilities in Vietnam and Switzerland dominate procurement, driven by established elevation differentials and streamlined permitting for proven designs.
- Underground:Subsurface lower reservoirs excavated in stable rock formations, eliminating surface land use conflicts. Germany and Austria are expanding deployment where surface topography restricts conventional development, though civil works costs escalate substantially.
- Above-ground:Elevated steel or concrete tanks replacing natural upper reservoirs. Industrial micro-grids in Japan favor this configuration for modular scalability without geologic site requirements.
- Modular:Containerized pump-turbine units with standardized civil foundations. Remote mining operations in Chile and Australia represent emerging demand for rapid-deployment mechanical storage without transmission interconnection delays.
Mature deployment sits with Conventional installations. Newer deployment is concentrated in Modular configurations.
End User:
Customer type determines project scale, financing structure, and operational control requirements across fundamentally different procurement workflows.
- Utilities:Transmission-connected grid operators procuring multi-gigawatt-hour systems under regulated cost recovery frameworks. State-owned entities in China and Vietnam anchor global capacity additions through integrated resource planning mandates.
- Industrial:Energy-intensive manufacturers seeking behind-the-meter load management and power quality assurance. Aluminum smelters in Norway and data center operators in Switzerland represent high-priority demand segments.
- Commercial:Distributed energy users with peak demand charge exposure. Large retail and logistics facilities in Germany are piloting small-scale pumped hydro where grid tariffs create favorable arbitrage economics.
- Residential:Individual property-level systems, currently negligible in scale. Alpine property owners in Austria represent a nascent niche for micro-hydro configurations with seasonal storage functionality.
Capacity ownership clusters with Utilities. Fastest expansion is occurring in Industrial procurement.
Application:
Service type dictates response time requirements, cycling frequency, and revenue stacking potential across distinct grid service markets.
- Grid Stabilization:Black-start capability and spinning reserve provision for system reliability. Grid operators in Japan and Switzerland maintain strategic reserves for earthquake and alpine weather resilience.
- Renewable Integration:Absorption of variable solar and wind generation through multi-hour discharge cycles. Vietnam's midday solar oversupply and evening demand peaks create the most pressing deployment imperative globally.
- Load Shifting:Arbitrage between low-cost overnight and high-cost peak electricity periods. Norwegian utilities exploit Nordic price differentials through established pumped hydro fleets.
- Frequency Regulation:Rapid response to grid frequency deviations through automatic generation control. Variable-speed turbine retrofits in Austria and Germany are reclaiming market share from lithium-ion batteries in this service category.
Historical deployment centers on Load Shifting. Steepest expansion trajectory belongs to Renewable Integration.
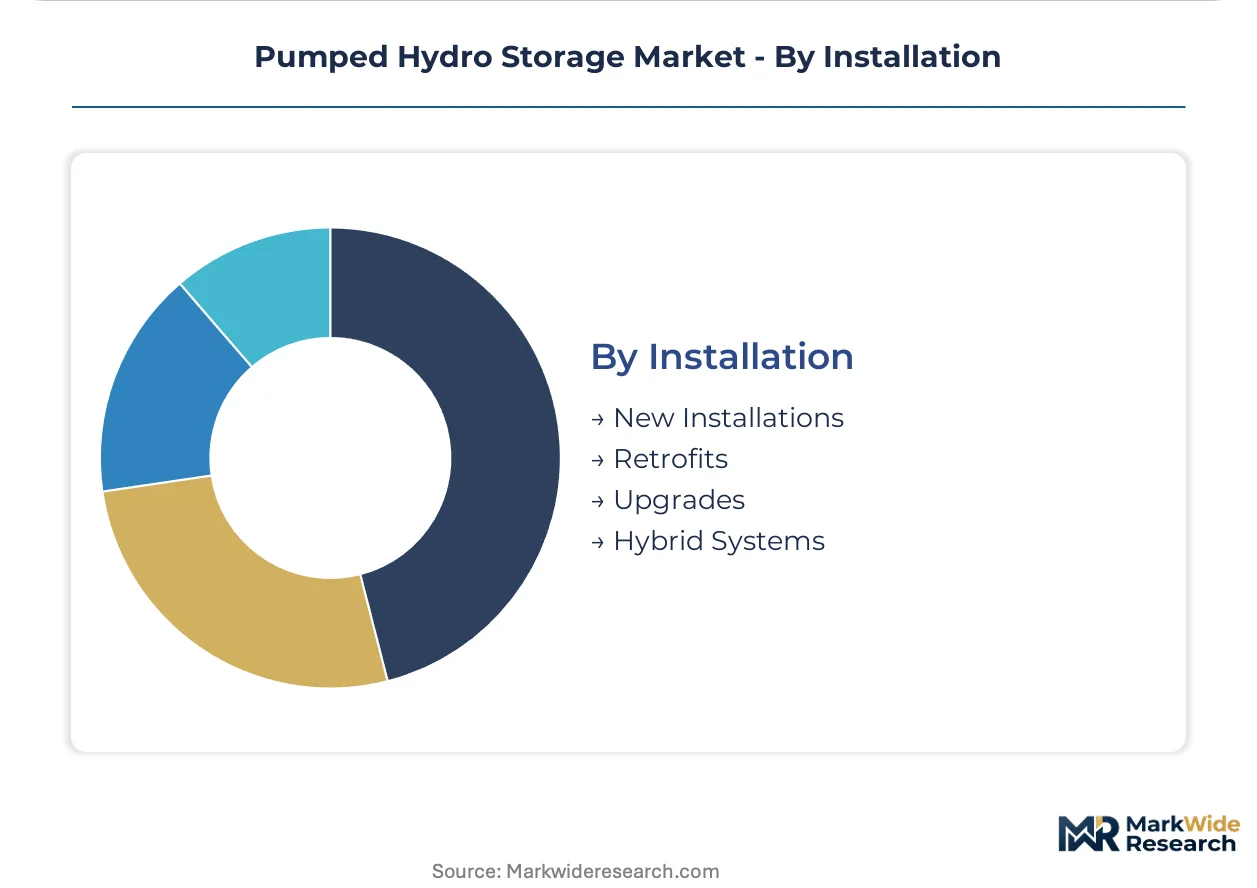
Installation:
Project delivery mode determines development timelines, equipment sourcing strategies, and regulatory pathway complexity.
- New Installations:Greenfield developments on previously undeveloped sites. China's Yunnan and Sichuan provinces dominate through streamlined MEE environmental assessments for mountainous terrain.
- Retrofits:Replacement of aging turbine-generator sets in existing facilities. European refurbishment cycles concentrate in Switzerland and Austria where plant lifespans exceed fifty years.
- Upgrades:Conversion from fixed-speed to variable-speed operation. German and Spanish utilities are prioritizing frequency regulation market access through power electronics integration.
- Hybrid Systems:Co-location with solar photovoltaic or battery storage assets. Floating solar arrays on upper reservoirs in Vietnam and India reduce evaporation while adding generation capacity.
Investment flow currently favors New Installations. Technology innovation is concentrating in Hybrid Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China produces the majority of new pumped hydro capacity while European utilities drive refurbishment demand. Vietnam and Switzerland concentrate development in mountainous terrain with natural elevation advantages. The United States opens flat-terrain opportunities through regulatory exemptions for closed-loop configurations.
China
Yunnan and Sichuan provinces host the fastest greenfield development as grid operators absorb intermittent solar and wind generation. The MEE has streamlined environmental impact assessments for reservoir construction in mountainous terrain, cutting permitting timelines substantially. State-owned utilities in these southwestern provinces anchor multi-gigawatt-hour deployments under integrated resource planning mandates tied to dual carbon goals.
Switzerland
Alpine utilities prioritize turbine retrofits and variable-speed upgrades to capture intraday price arbitrage. The EU Green Deal embeds long-duration storage obligations into national climate plans, guaranteeing offtake for capacity expansions. Engineering clusters around Zurich and Lucerne concentrate ternary pump-turbine retrofits that compress response times from minutes to seconds.
Vietnam
Grid operators procure pumped hydro specifically to manage midday solar oversupply and evening demand peaks in the northern highlands. The country's mountainous topography supports cost-effective surface reservoir development where elevation differentials exceed 500 meters. State utility procurement in Lao Cai and Son La provinces is unbundling engineering-procurement-construction contracts to attract non-traditional developers.
United States
Texas and Oklahoma developers exploit FERC's 2023 licensing exemption for off-river pumped hydro, eliminating traditional hydropower constraints in flat terrain. The exemption opens markets previously inaccessible due to surface water rights and environmental review requirements. Independent power producers in these states are advancing closed-loop projects with 8-12 hour discharge durations for renewable integration.
Germany
Underground configurations expand where surface topography restricts conventional development, particularly in the Black Forest and Bavarian Alps. The EU F-Gas Regulation forces redesign of generator cooling systems to phase out sulfur hexafluoride insulation, extending equipment qualification cycles. Industrial micro-grids in Baden-Württemberg pilot above-ground steel tank configurations for modular scalability without geologic site requirements.
Pumped Hydro Storage Market Vendor Landscape
The competitive structure tilts toward integrated turbine-generator OEMs with century-long hydraulic machinery heritage. European and Japanese engineering conglomerates dominate refurbishment cycles through proprietary variable-speed technology and aftermarket service networks. Three archetypes define positioning: full-system integrators with power electronics expertise, specialized hydraulic turbine fabricators, and state-backed Chinese equipment suppliers. Competitive moves concentrate on technology licensing for variable-speed retrofits and strategic partnerships to unbundle engineering-procurement-construction contracts.
Among European full-system integrators, Voith Hydro Holding GmbH & Co. KG and ANDRITZ Hydro GmbH exemplify the hydraulic machinery heritage archetype, anchoring refurbishment demand in Alpine markets. Siemens Energy AG occupies a position spanning turbine manufacturing and grid infrastructure integration. These three represent distinct approaches to the F-Gas Regulation compliance challenge, with equipment redesign cycles determining qualification timelines for EU market access.
| Leading Market Players |
|---|
| General Electric Company |
| Toshiba Energy Systems & Solutions Corporation |
| Voith Hydro Holding GmbH & Co. KG |
| Mitsubishi Power Ltd. |
| Hitachi Energy Ltd. |
| ANDRITZ Hydro GmbH |
| Siemens Energy AG |
| Harbin Electric Machinery Company Limited |
| Dongfang Electric Corporation |
| Others |
Supply Flow & Price Mechanics
State-owned utilities in China and Vietnam anchor project financing through sovereign-backed procurement frameworks, compressing equipment margins while concentrating supply relationships around turbine OEMs with proven variable-speed technology. This ownership pattern enforces rigid cost discipline on civil works contractors and electromechanical suppliers alike, with price benchmarks set by integrated resource planning mandates rather than competitive auction dynamics.
Pricing Analysis
Margin tightening in variable-speed turbine-generator packages reflects the scarcity of qualified engineering firms with hydraulic machinery and power electronics integration expertise. Project-based long-term offtake contracts dominate, with price differentiation resting on round-trip efficiency guarantees and aftermarket service bundling. Cost-down pressure accelerates as lithium-ion batteries capture frequency regulation contracts that historically anchored pumped hydro returns. Industrial micro-grids in Japan exhibit highest price sensitivity due to modular scalability requirements, while Alpine utilities in Switzerland demonstrate lowest sensitivity given fifty-year asset lifespans and regulated cost recovery frameworks.
Supply Chain Analysis
Dual-sourcing requirements from European utilities mandate qualification of at least two turbine OEMs per project, fragmenting order books across Voith Hydro, ANDRITZ Hydro, and Siemens Energy. Manufacturing concentrates in Germany, Austria, and Japan for precision hydraulic components, with generator step-up transformers sourced from China and South Korea. Raw material dependencies span high-grade stainless steel forgings, copper windings, and sulfur hexafluoride alternatives for switchgear insulation. Single-source vulnerability sits with the twelve qualified engineering firms globally capable of variable-speed reversible pump-turbine design. Distribution runs through engineering-procurement-construction consortia that are disaggregating into separate equipment supply and civil works packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pumped hydro storage market operates under acute supply constraint, with fewer than twelve engineering firms globally qualified for variable-speed reversible pump-turbine design propping equipment pricing and extending lead times.
For Market Incumbents: Deepen aftermarket service networks in Alpine refurbishment markets to capture recurring revenue from fifty-year asset lifespans. Secure backward integration into power electronics manufacturing to reduce dependency on external variable-speed drive suppliers. Lock in long-term civil works partnerships as Vietnamese and Indonesian utilities unbundle EPC contracts and solicit competitive turbine-generator bids separately from dam construction. For New Entrants and Emerging Players: Launch via modular containerized configurations targeting remote mining operations in Chile and Australia where transmission interconnection delays exclude grid-connected alternatives. Target above-ground steel tank installations for Japanese industrial micro-grids seeking rapid-deployment mechanical storage without geologic site requirements. Prioritize technology licensing partnerships with established hydraulic turbine fabricators to circumvent the decade-long qualification cycles that protect incumbent positions. For Investors and Strategic Acquirers: Distressed-cycle entries favor European turbine OEMs with stranded SF6-dependent switchgear inventories facing EU F-Gas Regulation compliance deadlines. Long-term viability hinges on exposure to renewable integration applications rather than frequency regulation markets where lithium-ion substitution accelerates. Watch for inflection in Chinese MEE permitting timelines for Yunnan and Sichuan reservoir construction as signal of capacity expansion velocity. Deviation in grid code definitions of long-duration storage eligibility would shift project finance availability materially.| Strategic Initiative | Industry Significance |
|---|---|
| Variable-Speed Technology Licensing | Power electronics integration expertise from Voith Hydro and Siemens Energy unlocks frequency regulation market access. |
| Closed-Loop Project Development | FERC licensing exemptions enable Texas and Oklahoma developers to bypass traditional hydropower constraints in flat terrain. |
| Ternary Pump-Turbine Retrofits | Swiss and Austrian utilities capture intraday price arbitrage through three-runner configurations that compress response times. |
| Hybrid Solar-Pumped Hydro Deployment | Floating photovoltaic arrays on Vietnamese upper reservoirs reduce evaporation while adding daytime generation capacity. |
| SF6-Free Switchgear Transition | Fluoronitrile-based insulation systems from European OEMs satisfy EU F-Gas Regulation phaseout deadlines. |
Methodological Framework
Independent corroboration across FERC licensing databases, IEA storage technology reports, and MEE environmental assessment filings underwrites the qualitative findings in this study. Primary interviews with utility planning officers, EPC contractors, and turbine OEM technical directors combined with secondary validation from grid operator procurement documents and equipment qualification records. Bottom-up project pipeline aggregation across China, Vietnam, Switzerland, and the United States triangulates against top-down capacity forecasts from integrated resource planning mandates.
Rate-of-change decomposition separates capacity additions by technology configuration, installation mode, and application service type across the projection horizon. Segmentation dimensions span conventional versus underground reservoir types, utility versus industrial end-user categories, and renewable integration versus frequency regulation applications. CAGRs derive from project development timeline assumptions and equipment delivery schedules, with specific inputs including transmission interconnection queue durations and environmental permitting cycle lengths.
The model assumes a particular technology adoption path; alternative pathways for battery energy storage substitution would alter the outlook for frequency regulation service revenues. Forecasts reflect assumptions regarding EU Green Deal storage mandate implementation velocity and Chinese dual carbon goal enforcement intensity. Deviation in F-Gas Regulation compliance timelines or lithium-ion cost curves would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydropower Systems
Tidal Power Market
Hydropower Systems
South America Pumped Hydro Storage Market
Hydropower Systems
Hydro Turbines Market
Hydropower Systems
Whirlpool Turbine Market
Hydropower Systems
Hydropower Turbine Market
Hydropower Systems
United States Hydropower Market
Hydropower Systems
Asia-Pacific Small Hydropower Market
Hydropower Systems
Underground Hydro Power Plant Market
Hydropower Systems
Japan Hydropower Market
Hydropower Systems
North America Hydropower Market
Hydropower Systems
Hydropower Generation Market
Hydropower Systems
France Tidal Power Market
Hydropower Systems
Asia-Pacific Hydropower Market
Hydropower Systems
Wave and Tidal Energy Market
Hydropower Systems
Offshore Hydropower Market
Hydropower Systems
Europe Hydropower Market