
 Europe Hydro Turbine Market | 2026-2036
Europe Hydro Turbine Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Hydro Turbine Market Foresight
Norway's capacity build-out is tilting the competitive landscape toward suppliers with strong Nordic project execution. Andritz AG leverages its deep vertical integration in electromechanical packages to sustain repeat orders across Scandinavian utilities. Voith Hydro GmbH & Co. KG anchors its position through specialized Francis turbine refurbishment contracts on aging Alpine plants.
A hydro turbine converts hydraulic energy into rotational mechanical energy through precisely machined runner blades, typically forged from stainless steel alloys with cavitation-resistant coatings, operating across head ranges from 2 meters to over 2,000 meters to drive synchronous generators. The product type dimension shows Francis turbines occupying the dominant share due to their operational flexibility across medium-head sites, while bulb turbines represent the fastest-growing category as low-head run-of-river projects multiply on European rivers. Installation type segmentation reveals pumped storage commanding the highest capital intensity per megawatt as grid stabilization services attract premium tariff structures.
The EU Green Deal and revised Renewable Energy Directive shape equipment replacement cycles, while EMAS and national water framework directives enforce strict ecological flow requirements that modify turbine design specifications. CE marking under the Machinery Directive governs market access for new installations across member states. Stakeholders must monitor how the EU taxonomy for sustainable finance reclassifies existing hydropower assets and redirects capital toward modernization versus greenfield development.
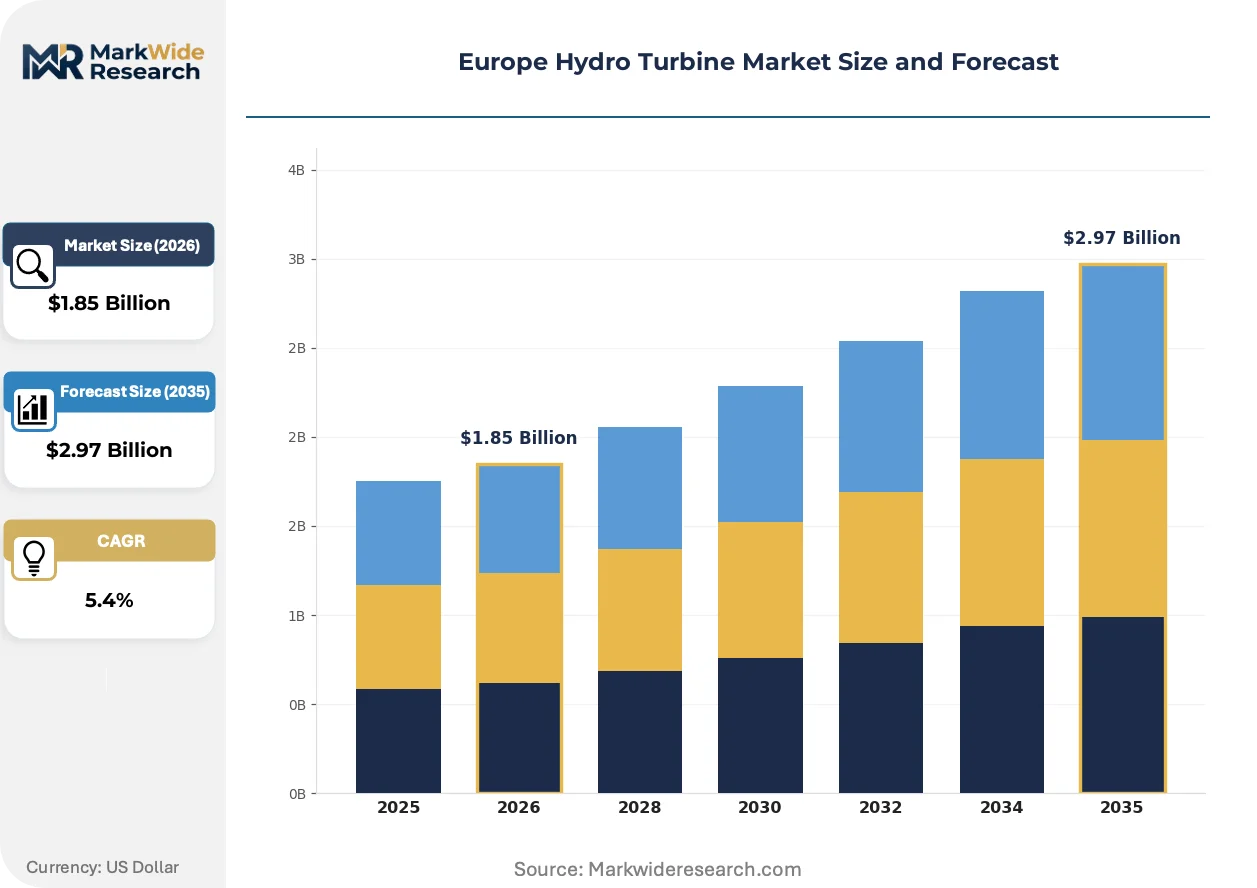
Market Dynamics
The EU Green Deal is forcing a wholesale replacement cycle across aging Alpine hydropower fleets, with refurbishment mandates compressing equipment procurement timelines and favoring suppliers with proven electromechanical integration capabilities.
Growth Catalysts
- EU Green Deal refurbishment mandates:The revised Renewable Energy Directive accelerates turbine replacement schedules at plants exceeding 40 years of operational life. Alpine utilities in Switzerland and Austria face binding compliance deadlines.
- Pumped storage tariff premiums:Grid stabilization services now attract premium tariff structures under national capacity mechanisms. Norwegian and Spanish utilities are expanding reversible pump-turbine installations.
- Run-of-river expansion:Low-head bulb turbine demand multiplies on European rivers as environmental permitting eases for small-scale projects. The Water Framework Directive's ecological flow requirements favor pass-through designs.
Market Restraints
- Stainless steel alloy volatility:Runner blade forgings depend on nickel and chromium supply chains concentrated in Russian and Indonesian mining operations. Input cost swings compress fabrication margins.
- Alpine supplier concentration:Electromechanical package integration capabilities cluster among Austrian and German engineering groups. Limited qualified bidders extend procurement cycles.
- Ecological flow retrofit complexity:The EU Water Framework Directive mandates fish-passage-compatible runner designs that reduce hydraulic efficiency at legacy medium-head installations.
Strategic Opportunities
- Spanish pumped storage greenfield:The country's 2021 National Integrated Energy and Climate Plan targets 2.5 GW of new reversible hydro capacity. Vacuum-sintered runner coatings from emerging Portuguese suppliers offer localized sourcing.
- Digital twin convergence:Real-time cavitation monitoring fused with predictive maintenance algorithms creates aftermarket service revenue streams. Alpine operators in Norway pilot subscription-based turbine health platforms.
- EMAS ecological certification:The EU Eco-Management and Audit Scheme awards preferential treatment in public procurement. Turbine manufacturers with verified lifecycle assessments capture utility tender advantages.
Industry Challenges
- Cavitation repair technician scarcity:Precision welding of stainless steel runner blades requires certified specialists. Alpine training programs graduate fewer than 50 qualified technicians annually.
- CE marking timeline compression:The Machinery Directive's conformity assessment procedures extend 14-18 months for novel bulb turbine geometries. Design-to-commission cycles strain project finance structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Hydro Turbine Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Francis Turbine, Pelton Turbine, Kaplan Turbine, Bulb Turbine Installation Type: Run-of-River, Reservoir, Pumped Storage, Tidal End User: Utility Companies, Industrial Plants, Agriculture, Government Agencies Capacity: Small Scale, Medium Scale, Large Scale, Extra Large Scale |
| Companies Covered | Andritz AG, Voith Hydro GmbH & Co. KG, General Electric Company, Siemens AG, Litostroj Power, Toshiba Energy Systems & Solutions Corporation, IMPSA Europe, Kirloskar Brothers Ltd, Canadian Hydro Components Ltd, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Hydro Turbine Market Shifts & Advancements
Additive manufacturing of titanium-aluminide runner blade inserts is collapsing traditional forging lead times. Digital workflow integration now spans computational fluid dynamics optimization through to field telemetry.
Computational fluid dynamics-optimized runner geometries with variable-pitch blade mechanisms are rendering obsolete fixed-blade Francis designs at medium-head refurbishment sites. Austrian and Swiss utilities now specify adjustable runner configurations as standard. The technology is compressing efficiency upgrade timelines from 36 months to 18 months.
REACH restrictions on hexavalent chromium coatings are accelerating plasma-transferred arc welding adoption for cavitation-resistant surfaces. The European Chemicals Agency's 2024 sunset date for chromate conversion coatings forces coating line requalification. Turbine OEMs with qualified tungsten-carbide overlay processes capture refurbishment contracts ahead of compliance deadlines.
Performance-based service agreements now displace traditional time-and-materials maintenance contracts at Nordic pumped storage facilities. Norwegian utility Statkraft unbundles turbine availability guarantees from capital equipment supply. The model concentrates risk with OEMs while transferring operational expertise to Alpine service hubs.
Europe Hydro Turbine Market Segmentation
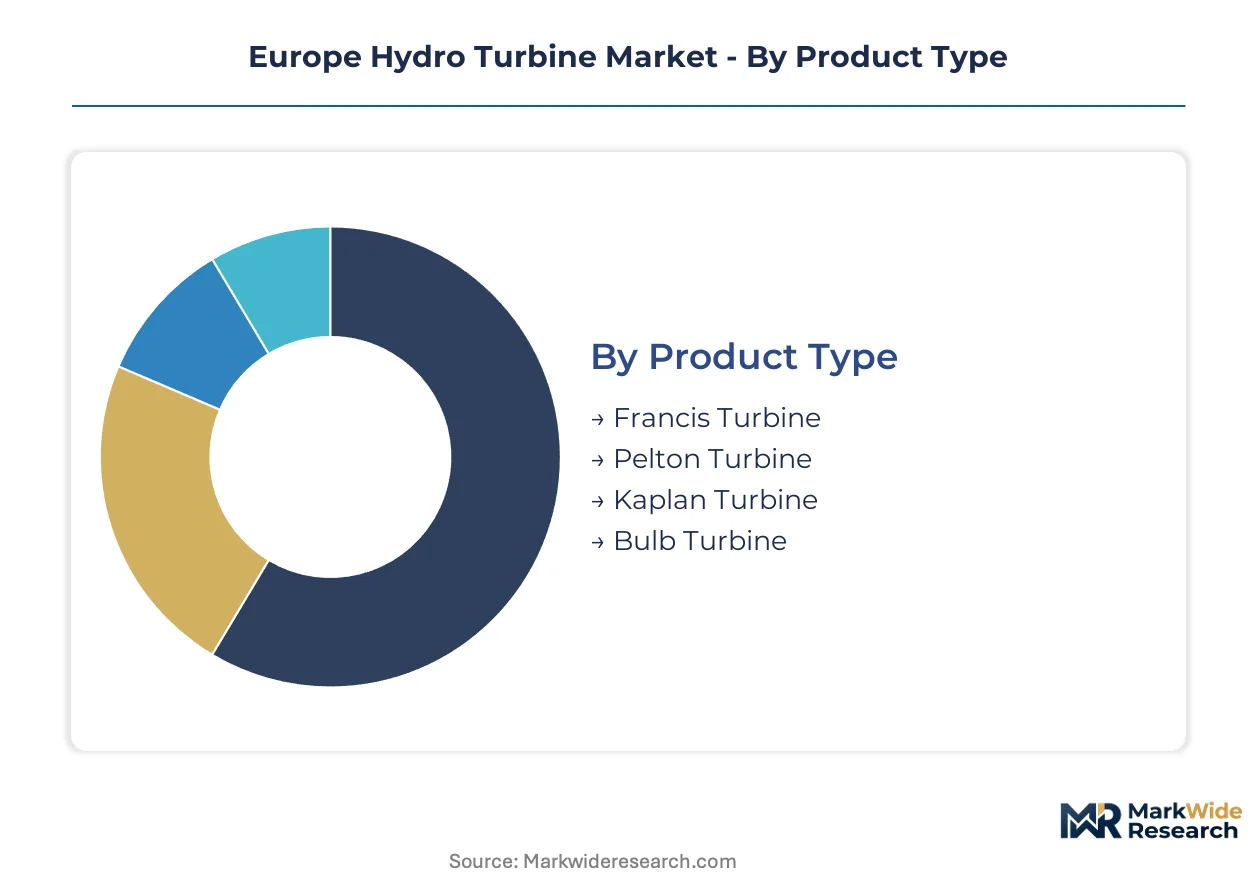
Equipment replacement cycles and capital intensity vary dramatically across turbine configurations and installation architectures. Procurement timelines compress or extend based on head conditions, grid integration requirements, and regulatory compliance burdens specific to each segment.
Product Type:
Francis and Pelton designs turn over slowest due to decades-long asset lives, while bulb turbines refresh fastest as run-of-river permitting accelerates.
- Francis Turbine:Spiral-cased reaction turbines with adjustable wicket gates optimize efficiency across 20-700 meter head ranges. Swiss and Austrian Alpine utilities specify these for medium-head refurbishment contracts under EU Green Deal mandates.
- Bulb Turbine:Horizontal-axis units with directly coupled generators suit low-head river sites with minimal civil works. Norwegian and Spanish developers deploy these for ecological flow-compliant run-of-river expansion on the Nidelva and Ebro basins.
- Pelton Turbine:Impulse-type units with double-bucket runners extract energy from high-pressure jets at heads exceeding 500 meters.
- Kaplan Turbine:Axial-flow reaction designs with adjustable blades operate efficiently at heads below 30 meters.
Francis turbines dominate installed base across Alpine Europe. Bulb turbines are where expansion concentrates most quickly.
Installation Type:
Pumped storage commands premium capital intensity per megawatt, while run-of-river offers the leanest project finance structures.
- Pumped Storage:Reversible pump-turbine installations enable grid stabilization services through 6-12 hour daily cycling. Norwegian Statkraft and Spanish Iberdrola expand capacity under national capacity mechanisms with premium tariff structures.
- Run-of-River:Pass-through designs without significant impoundment minimize ecological disruption and permitting timelines. German and Austrian developers favor these for Water Framework Directive compliance on the Rhine and Danube tributaries.
- Reservoir:Conventional impoundment facilities with seasonal storage regulate multi-year water availability.
- Tidal:Bidirectional turbine arrays harness estuarine flow reversals with predictable generation profiles.
Reservoir installations anchor legacy capacity across Alpine Europe. Pumped storage is where capital deployment concentrates.
End User:
Utility procurement cycles stretch 24-36 months for integrated electromechanical packages, while agricultural installations complete in under 12 months.
- Utility Companies:Vertically integrated European generators like Statkraft and Verbund execute multi-turbine fleet refurbishments with performance-based service agreements. Their specifications drive standardization across Francis turbine adjustable runner configurations.
- Industrial Plants:Captive hydropower for aluminum smelters and chemical processors demands high availability guarantees.
- Agriculture:Small-scale irrigation district cooperatives procure standardized bulb turbine packages.
- Government Agencies:Public water management authorities in France and Italy oversee multipurpose reservoir operations.
Utility companies dominate procurement volume. Industrial plants are where captive generation investment concentrates.
Capacity:
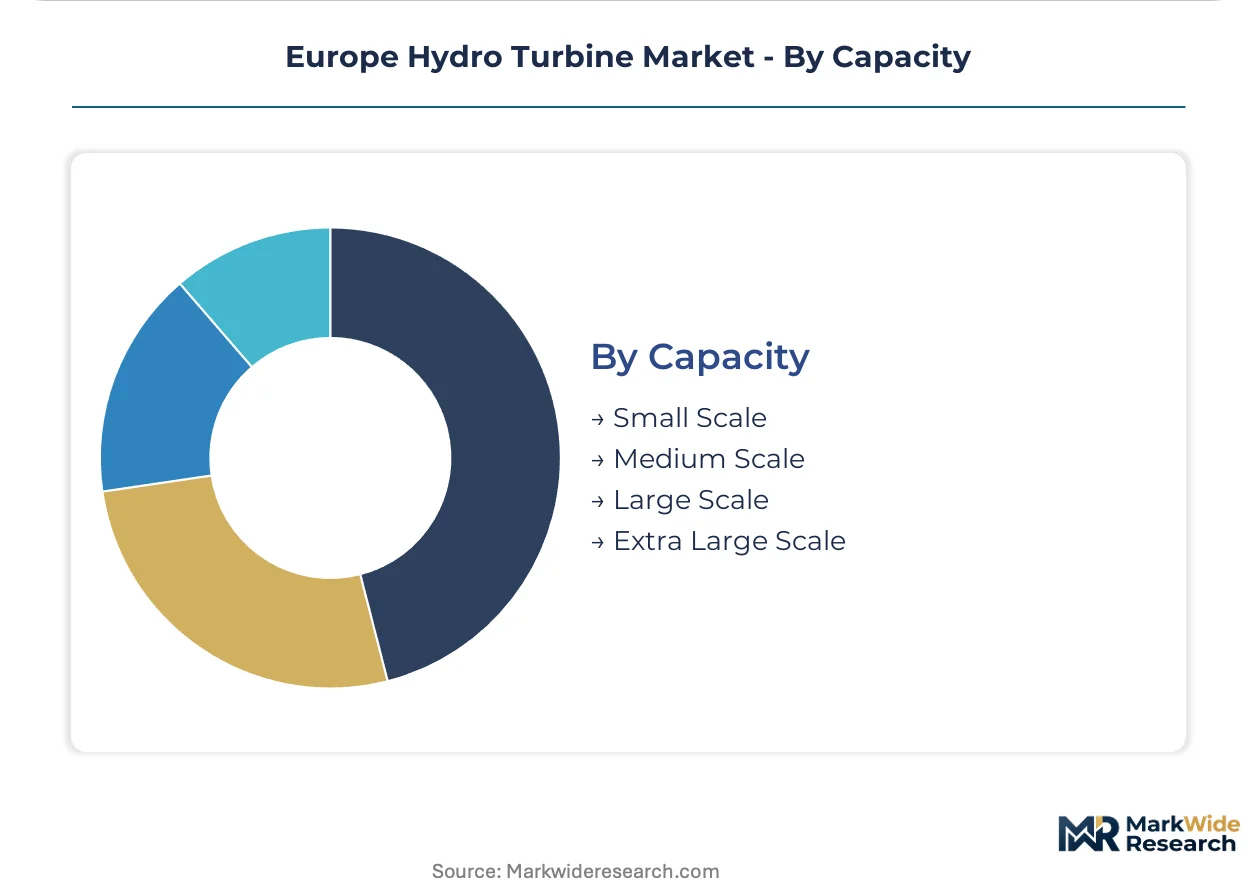
Small-scale projects achieve fastest commissioning timelines, while extra-large installations require decade-long development horizons.
- Large Scale:Units exceeding 100 MW capacity anchor Alpine pumped storage and reservoir installations. Austrian and Swiss utilities deploy these for seasonal storage and grid frequency regulation under ENTSO-E balancing requirements.
- Small Scale:Sub-10 MW run-of-river units streamline permitting under simplified environmental assessments. Portuguese and Italian developers exploit these for distributed generation on smaller tributaries.
- Medium Scale:10-100 MW installations serve regional utility portfolios and industrial microgrids.
- Extra Large Scale:Units exceeding 300 MW require dedicated transmission infrastructure and cross-border coordination.
Large-scale capacity anchors baseload generation across Nordic and Alpine Europe. Small-scale installations are where project proliferation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Austrian and German engineering groups dominate electromechanical package supply, concentrating fabrication capabilities around Alpine industrial corridors. Nordic utilities drive procurement volume through pumped storage expansion. Southern European markets accelerate run-of-river permitting on major river basins.
Norway
Statkraft's reversible pump-turbine program and grid balancing services anchor demand for large-scale electromechanical packages. The country's capacity mechanism regulations under national energy market reforms attract premium tariff structures for storage assets. Industrial clusters around Trondheim and Bergen concentrate runner blade refurbishment capabilities.
Switzerland
Alpine utilities face binding EU Green Deal compliance deadlines for plants exceeding 40 years of operational life. The revised Renewable Energy Directive accelerates Francis turbine replacement schedules at medium-head installations. The Aare and Rhine basins host concentrated refurbishment activity around electromechanical integration specialists.
Austria
Verbund AG executes multi-turbine fleet modernizations with performance-based service agreements standardizing adjustable runner configurations. EMAS ecological certification requirements shape public procurement preferences for verified lifecycle assessments. The Inn and Danube tributaries support active run-of-river bulb turbine deployment.
Spain
The 2021 National Integrated Energy and Climate Plan targets 2.5 GW of new reversible hydro capacity, driving vacuum-sintered runner coating demand. National capacity mechanisms under EU electricity market regulations stabilize revenue streams for grid stabilization services. The Ebro and Duero basins concentrate low-head project development.
Germany
Rhine and Danube tributary operators favor pass-through run-of-river designs for Water Framework Directive ecological flow compliance. CE marking under the Machinery Directive governs conformity assessment for novel bulb turbine geometries entering the market. Bavarian and Baden-Württemberg industrial zones host precision welding specialists for cavitation-resistant surface treatments.
Europe Hydro Turbine Market Competitive Landscape
Vertically integrated electromechanical specialists and regional refurbishment contractors split the market between new installation supply and aftermarket service capture. The vendor base clusters along Alpine industrial corridors where precision machining capabilities and certified welding technician programs concentrate. Two archetypes dominate: full-package OEMs controlling runner forging through generator integration, and niche service providers capturing ecological retrofit mandates. Competitive moves center on strategic partnerships for digital twin platform development and geographic expansion into Iberian pumped storage greenfield sites.
Among Austrian-headquartered full-package suppliers, Andritz AG exemplifies the vertically integrated archetype with captive electromechanical capabilities spanning runner forging through generator integration. Voith Hydro GmbH & Co. KG occupies a parallel position representing German engineering heritage in specialized refurbishment contracting. General Electric Company anchors the diversified industrial conglomerate tier, bringing scale-driven manufacturing resources to large-scale Alpine installations.
| Leading Market Players |
|---|
| Andritz AG |
| Voith Hydro GmbH & Co. KG |
| General Electric Company |
| Siemens AG |
| Litostroj Power |
| Toshiba Energy Systems & Solutions Corporation |
| IMPSA Europe |
| Kirloskar Brothers Ltd |
| Canadian Hydro Components Ltd |
| Others |
Supply & Pricing Matrix
Runner blade forging capabilities cluster in Austrian and German industrial corridors, anchoring margin capture with electromechanical package integrators while compressing fabrication economics for non-vertically aligned suppliers. Stainless steel alloy volatility feeds directly into procurement cycle negotiations, with nickel and chromium cost swings reshaping contract structures across Alpine utility tenders.
Pricing Analysis
CE marking under the Machinery Directive dictates the pricing tier structure across European installations, separating premium-certified adjustable runner configurations from standard fixed-blade refurbishments. Price differentiation rests on EMAS ecological certification status and after-sales service bundling, with verified lifecycle assessments commanding tender advantages. Cost compression in standard-tier equipment is intensifying because REACH-mandated coating line requalification concentrates qualified supplier pools. Small-scale agricultural cooperatives exhibit highest price sensitivity, while Nordic utilities with performance-based service agreements demonstrate lowest sensitivity due to unbundled availability guarantees.
Supply Chain Analysis
Tariff exposure between Indonesian nickel mining operations and European fabrication hubs dominates supply chain risk assessment for runner blade forgings. Geographic supply concentration centers on Austria, Germany, and Norway for precision machining and electromechanical integration. Raw material dependencies draw from Russian chromium, Indonesian nickel, and domestic stainless steel alloy stockpiles. Single-source vulnerability persists in certified cavitation welding technician programs graduating fewer than fifty specialists annually across Alpine training institutes. Distribution runs through utility-direct procurement channels for large-scale installations, with regional refurbishment contractors capturing aftermarket service flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Hydro Turbine Market operates as a regulatory entrenchment story, where CE marking compliance and EMAS certification create switching costs that lock utility procurement relationships with established electromechanical integrators.
For Market Incumbents: Insulate core margins by deepening captive forging capabilities and securing exclusive technician training partnerships with Alpine vocational institutes. Emerging Portuguese vacuum-sintered coating suppliers threaten localized sourcing advantages in Iberian greenfield developments. Backward integration into titanium-aluminide additive manufacturing preserves refurbishment contract capture against novel geometry specialists. For New Entrants and Emerging Players: Spanish pumped storage greenfield capacity represents the most penetrable geographic underpenetration, with 2.5 GW of reversible hydro targets creating procurement volume for non-incumbent coating and blade suppliers. Digital twin platform development offers a service-layer entry point without capital-intensive forging investments. Target Norwegian Statkraft's unbundled availability guarantee model as the anchor utility relationship for aftermarket subscription revenue. For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-cap regional refurbishment contractors holding EMAS certification and Alpine utility relationships but lacking captive runner forging. Long-term viability hinges on regulatory compliance service capture rather than equipment manufacturing scale. Watch for EU Taxonomy reclassification signals redirecting capital flows from greenfield development toward modernization mandates as the inflection indicator for refurbishment demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EMAS Certification Investment | Verified lifecycle assessments unlock preferential treatment in Swiss and Austrian utility tenders. |
| Digital Twin Platform Development | Real-time cavitation monitoring creates recurring revenue streams with Statkraft and Verbund. |
| Additive Manufacturing Capability | Titanium-aluminide runner inserts collapse lead times for Francis turbine refurbishment contracts. |
| Technician Training Partnership | Exclusive welding certification programs address scarcity constraining Alpine aftermarket capacity. |
| Iberian Greenfield Expansion | Spanish capacity mechanism tariffs stabilize revenue for reversible pump-turbine installations. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EU Green Deal implementation documents, ECHA REACH restriction notices, and ENTSO-E grid balancing requirement filings. Primary interviews engaged utility planning officers at Nordic and Alpine generators, EPC contractors specializing in pumped storage civil works, and aftermarket service heads at electromechanical package suppliers. Secondary validation drew from national energy regulator filings, EMAS certification databases, and Machinery Directive conformity assessment records. Bottom-up project pipeline enumeration triangulates against top-down regulatory mandate quantification.
Forecast inputs span turbine replacement schedules under EU Green Deal mandates, pumped storage capacity mechanism tariff structures, and run-of-river permitting velocity under Water Framework Directive ecological flow requirements. Segmentation dimensions include product type, installation architecture, end-user procurement scale, and capacity tier across the analysis window. CAGRs derive from equipment procurement timeline compression observed in Alpine refurbishment cycles and Iberian greenfield development trajectories. Industry-specific inputs incorporate stainless steel alloy price volatility indices and certified welding technician graduation rates.
Practitioners should monitor EU Taxonomy sustainable finance reclassification and ECHA coating restriction enforcement dates for early signals of capital reallocation. Forecasts reflect assumptions regarding regulatory compliance timeline adherence and utility procurement cycle stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydropower Systems
Hydropower Market
Hydropower Systems
Run of River Power Market
Hydropower Systems
Europe Hydropower Market
Hydropower Systems
Small Hydropower Market
Hydropower Systems
Wave and Tidal Energy Market
Hydropower Systems
Whirlpool Turbine Market
Hydropower Systems
United States Hydro Turbine Market
Hydropower Systems
South America Hydropower Market
Hydropower Systems
United States Hydropower Market
Hydropower Systems
South America Pumped Hydro Storage Market
Hydropower Systems
Japan Hydropower Market
Hydropower Systems
Hydro Turbines Market
Hydropower Systems
Floating Power Plant Market
Hydropower Systems
Africa Small Hydropower Market
Hydropower Systems
Asia-Pacific Small Hydropower Market
Hydropower Systems
Tidal Power Market