
 Hydropower Turbine Market | 2026-2036
Hydropower Turbine Market Size, Share, and Industry Trends Forecast 2026-2036
Hydropower Turbine Market Analysis
Long-term service agreements and digital monitoring subscriptions is broadening what turbine OEMs sell beyond hardware. ANDRITZ leverages its digital hydropower platform to secure recurring revenue across installed European bases. Voith sustains competitive positioning through deep specialization in Francis turbine refurbishment and efficiency upgrades. GE Vernova anchors its presence in North America through integrated software-defined control systems that optimize generator output in real time.
A hydropower turbine converts the kinetic and potential energy of flowing or falling water into rotational mechanical energy to drive an electric generator, with modern units operating at head ranges from two meters to over two thousand meters and rotational speeds precisely matched to grid frequency requirements. Francis turbines occupy the largest installed base due to their operational flexibility across medium-head sites, while Pelton turbines command premium positioning in high-head alpine and Andean installations where efficiency thresholds exceed ninety percent. Kaplan variants are displacing older fixed-blade propeller units in low-head run-of-river applications as adjustable wicket gate and runner blade geometries improve part-load performance curves.
The International Electrotechnical Commission sets turbine efficiency measurement and cavitation testing protocols that govern cross-border equipment certification, while China's National Energy Administration enforces domestic content requirements for critical components on projects exceeding defined capacity thresholds. Brazil's national electric energy agency mandates environmental flow compliance that shapes runner design specifications for Amazon basin installations. Stakeholders must monitor evolving grid codes for frequency response and inertia provision as variable renewable penetration alters the ancillary service value of hydroelectric assets.
Market Dynamics
Computational fluid dynamics and additive manufacturing are compressing turbine development cycles while IEC efficiency certification requirements harden technical barriers to market entry.
Growth Catalysts
- Grid inertia mandates:Brazil's ANEEL and European grid codes now require synchronous generation capability that only hydroelectric assets can provide cost-effectively, expanding turbine orders for frequency response services.
- Superalloy blade casting:Directionally solidified nickel-based alloys extend runner lifespans in abrasive silt-laden rivers, reducing lifecycle costs for Himalayan and Andean installations.
- Pumped storage revival:China's dual carbon targets and India's CEA storage mandates are accelerating orders for reversible pump-turbine units in 300-800 MW ranges.
Market Restraints
- Copper and rare earth volatility:Generator winding and permanent magnet supply chains concentrate in Chinese processing facilities, exposing OEMs to SAMR export licensing delays.
- Reservoir sedimentation:Technical limitations in sediment flushing systems reduce effective head at aging Himalayan and Alpine installations, degrading unit economics.
- Environmental flow compliance:Brazil's ANEEL minimum downstream discharge rules constrain operational flexibility at run-of-river sites, limiting capacity factors.
Strategic Opportunities
- Small hydro digitization:Nepal and Vietnam's sub-25 MW installations lack SCADA integration, creating white space for cloud-based predictive maintenance platforms.
- Green hydrogen coupling:Norwegian and Austrian alpine plants are retrofitting turbine-generator sets for direct electrolyzer feed, bypassing grid interconnection queues.
- EU Green Deal taxonomy alignment:Projects certified under the EU's sustainable finance framework access preferential EIB lending rates, accelerating refurbishment pipelines.
Industry Challenges
- Cavitation erosion modeling:CFD validation against physical prototype testing requires specialized hydraulics engineers whose training pipelines lag retirement rates.
- IEC 60193 test rig access:Certification timelines stretch 18-24 months due to limited laboratory capacity at accredited facilities in Prague and Shanghai.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydropower Turbine Market |
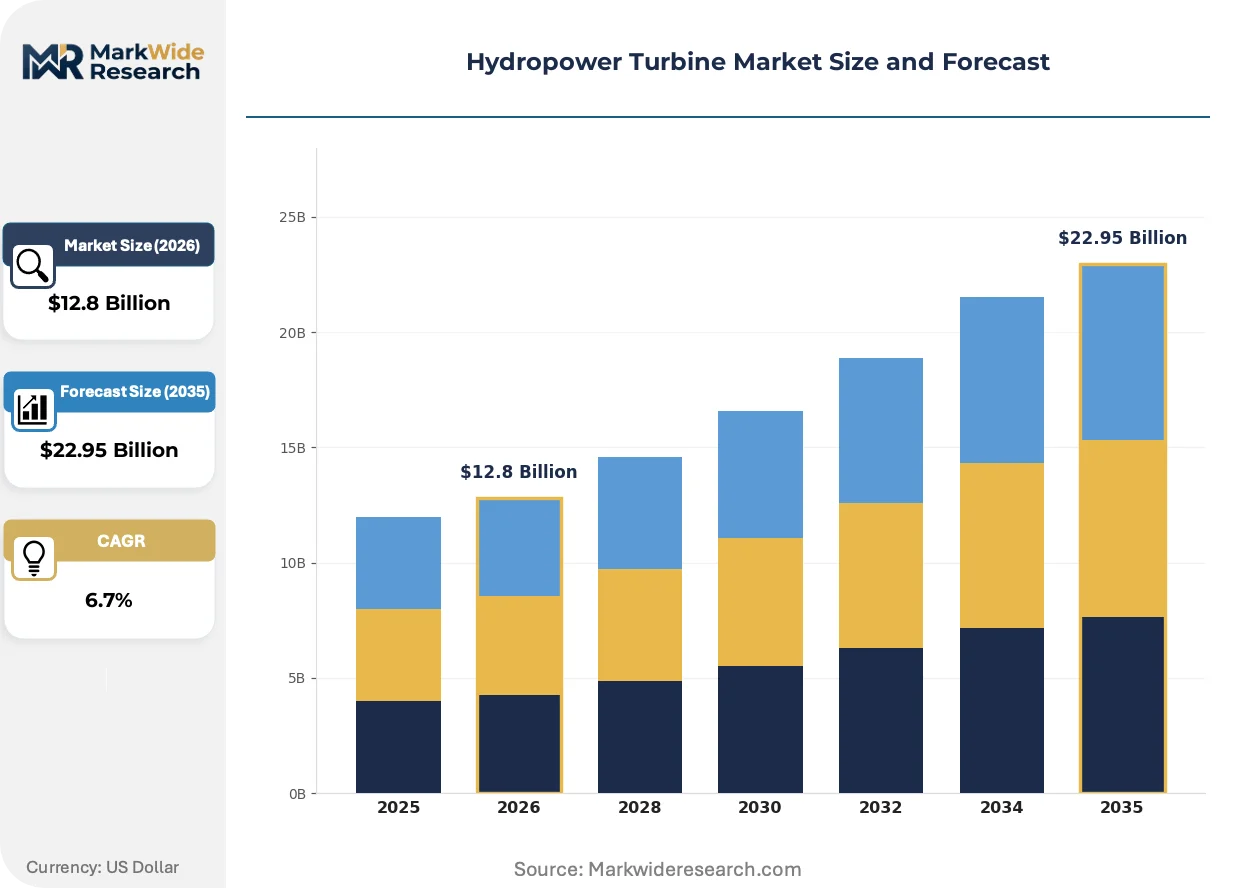
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pelton Turbines, Francis Turbines, Kaplan Turbines, Archimedes Screw End User: Utility Companies, Industrial Plants, Independent Power Producers, Government Agencies Installation Type: Onshore, Offshore, Small-Scale, Large-Scale Application: Electricity Generation, Pumped Storage, Water Supply, Flood Control |
| Companies Covered | ANDRITZ, GE Vernova, Voith, Siemens Energy, Mitsubishi Heavy Industries, Toshiba, Dongfang Electric Corporation, Harbin Electric, BHEL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydropower Turbine Market Emerging Trajectories
Digital twin deployment and modular runner designs are compressing commissioning schedules while environmental certification requirements harden material specifications across supply chains.
Additive manufacturing of stainless steel runner blades is converging with topology optimization algorithms to produce cavitation-resistant geometries impossible with conventional five-axis machining. Voith and ANDRITZ are qualifying laser powder bed fusion for Francis runner crowns at 15-50 MW scales. This convergence is collapsing prototype-to-production timelines from 36 months to 14 months for custom head-flow combinations.
China's MEE enforcement of GB 35574-2017 efficiency standards is disqualifying fixed-blade propeller turbines from new installations, forcing OEMs to accelerate Kaplan retrofit kits. Provincial energy bureaus in Sichuan and Yunnan now withhold grid connection permits for units below 92% peak efficiency. Domestic manufacturers are responding by licensing adjustable runner hub technology from European specialists.
Utility procurement committees now unbundle long-term service agreements from initial equipment supply, selecting predictive analytics providers through separate RFP processes. Statkraft and EDF are piloting this model at Norwegian and French alpine sites, displacing traditional OEM captive service contracts. This pattern is most visible in Alpine and Nordic markets where digital infrastructure maturity supports API-based performance monitoring.
Hydropower Turbine Market Segmentation
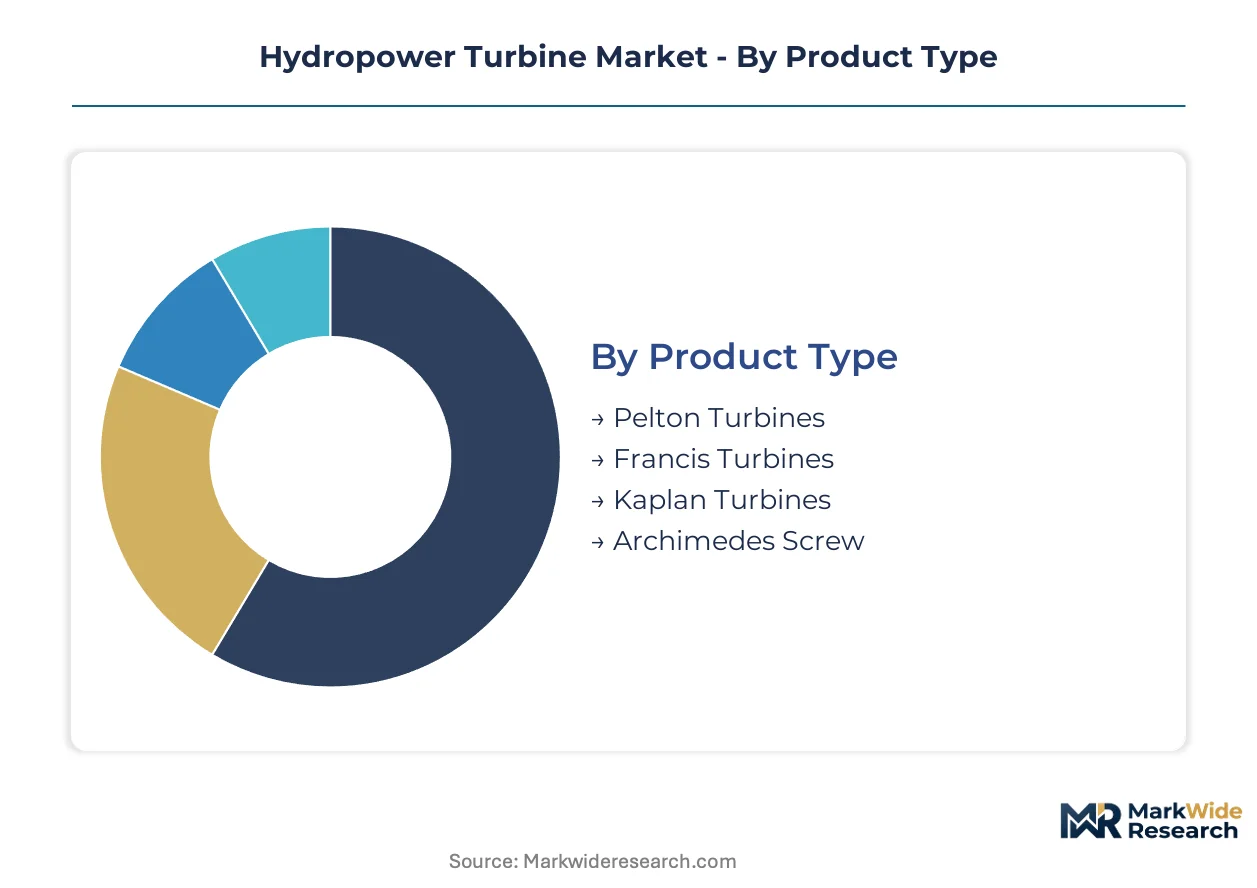
Hydropower turbine procurement patterns diverge sharply across deployment scales and operational mandates. Product selection ties directly to site-specific head and flow parameters, while ownership structures determine financing mechanisms and regulatory exposure.
Product Type:
Pelton and Francis turbines anchor standalone utility-scale installations, while Kaplan variants and Archimedes screws embed into distributed run-of-river systems.
- Francis Turbines:These reaction turbines operate across medium-head ranges from 20 to 700 meters through a spiral case and adjustable wicket gate assembly. Demand concentrates in China's Sichuan and Yunnan provinces where provincial energy bureaus enforce 92% peak efficiency minimums under GB 35574-2017 standards.
- Kaplan Turbines:Axial-flow designs with adjustable runner blades optimize performance across variable low-head conditions from 2 to 40 meters. Norwegian and Austrian alpine plants are retrofitting these units for direct electrolyzer feed in green hydrogen coupling configurations.
- Pelton Turbines:Impulse turbines with double or multiple jet configurations dominate high-head applications exceeding 300 meters in the Andes and Himalayas.
- Archimedes Screw:Low-speed positive displacement systems serve micro-hydro installations under 500 kW with minimal environmental impact and fish-friendly passage.
Francis turbines lead volumes today; Kaplan variants are gaining share fastest.
End User:
Ownership structure determines capital access, regulatory compliance burden, and service contract sophistication.
- Utility Companies:Vertically integrated grid operators procure multi-unit installations with 30-year service agreements. Brazil's ANEEL mandates synchronous generation capability for frequency response services, expanding orders from Eletrobras and Engie.
- Independent Power Producers:Project developers rely on non-recourse financing and equipment leasing structures. These operators prioritize modular runner designs that compress commissioning schedules.
- Industrial Plants:Captive generators at aluminum smelters and chemical complexes seek islanding capability and grid-independent operation.
- Government Agencies:Public irrigation and water resource departments procure multi-purpose infrastructure bundling electricity generation with flood control.
Utility companies dominate installed capacity; independent power producers are expanding most quickly.
Installation Type:
Scale thresholds determine equipment sourcing channels and OEM engagement models.
- Large-Scale:Installations exceeding 100 MW require custom engineering and IEC 60193 certification at accredited test facilities in Prague or Shanghai.
- Small-Scale:Sub-25 MW systems in Nepal and Vietnam lack SCADA integration, creating white space for cloud-based predictive maintenance platforms.
- Onshore:Conventional dam and run-of-river configurations represent the dominant deployment mode across all geographies.
- Offshore:Tidal and marine current turbine installations remain pre-commercial with limited orders outside demonstration projects.
Large-scale projects anchor revenue; small-scale installations show the steepest expansion trajectory.
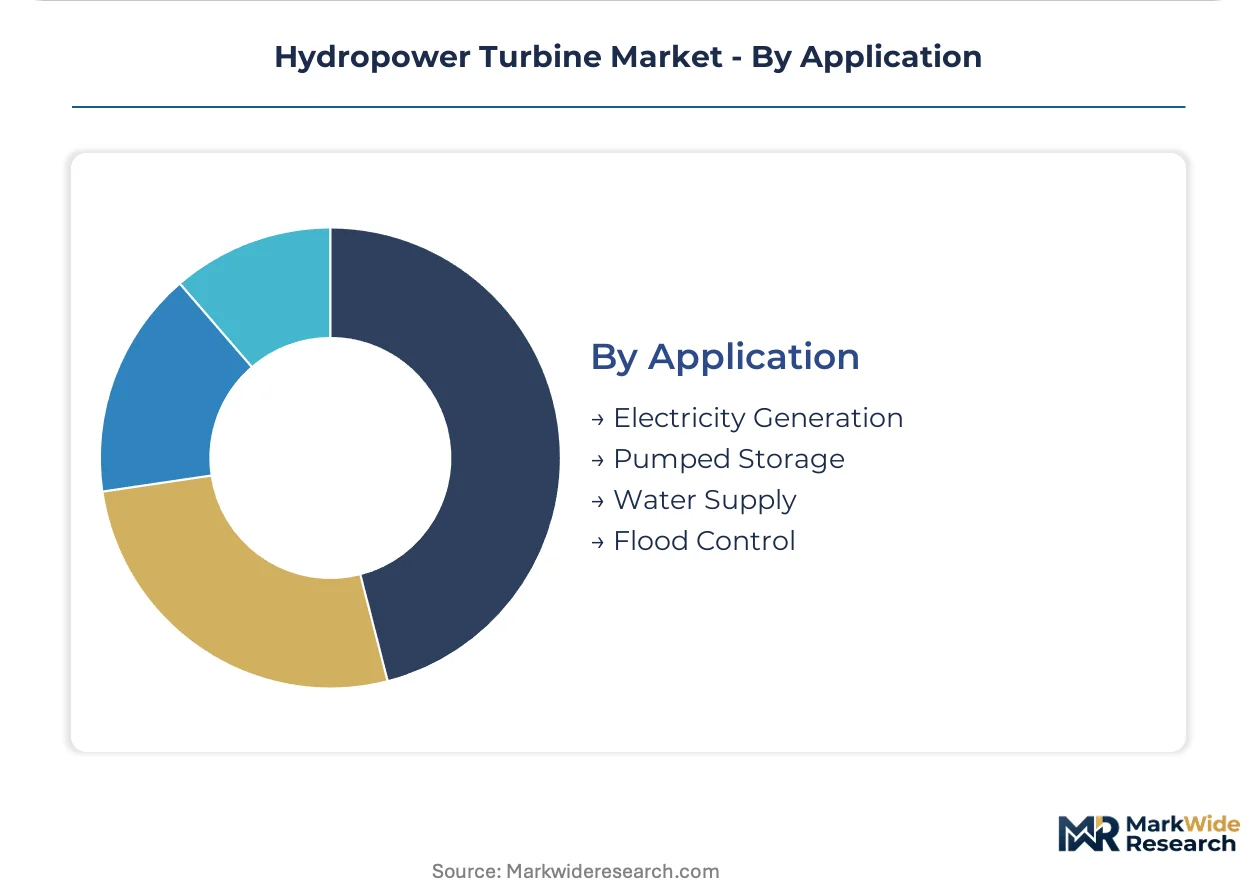
Application:
Revenue model stability varies by application, with electricity generation offering predictable cash flows against pumped storage's merchant exposure.
- Electricity Generation:Baseload and peaking power contracts provide the primary revenue foundation for turbine deployments.
- Pumped Storage:Reversible pump-turbine units in 300-800 MW ranges are accelerating under China's dual carbon targets and India's CEA storage mandates.
- Water Supply:Raw water pumping for municipal distribution and agricultural irrigation creates steady demand for low-head propeller units.
- Flood Control:Multi-purpose dams integrate turbine capacity with spillway infrastructure, though environmental flow compliance constrains operational flexibility.
Electricity generation commands the largest installed base; pumped storage is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's provincial energy bureaus enforce stricter efficiency mandates than Brazil's ANEEL, yet both markets drive substantial turbine refurbishment cycles through divergent regulatory mechanisms.
China
Sichuan and Yunnan provinces anchor domestic demand through GB 35574-2017 efficiency standards that disqualify fixed-blade propeller turbines from new installations. The Ministry of Ecology and Environment enforces these thresholds while withholding grid connection permits for units below 92% peak efficiency. Chengdu and Kunming host manufacturing clusters where domestic producers license adjustable runner hub technology from European specialists.
Brazil
Eletrobras and Engie expand orders under ANEEL mandates requiring synchronous generation capability for frequency response services. The national electric energy agency enforces environmental flow compliance rules that constrain operational flexibility at Amazon basin run-of-river sites. Belo Horizonte and São Paulo concentrate engineering procurement for large-scale dam rehabilitation and greenfield pumped storage projects.
Norway
Statkraft pilots unbundled procurement models separating long-term service agreements from initial equipment supply. The Norwegian Water Resources and Energy Directorate oversees licensing for alpine installations retrofitting turbine-generator sets for direct electrolyzer feed in green hydrogen configurations. Trøndelag and Vestland counties host clusters where digital infrastructure maturity supports API-based performance monitoring.
India
The Central Electricity Authority storage mandates accelerate orders for reversible pump-turbine units in 300-800 MW ranges. BHEL and independent power producers prioritize modular runner designs that compress commissioning schedules for Himalayan installations. Himachal Pradesh and Uttarakhand concentrate project development where sediment-laden rivers demand directionally solidified nickel-based alloy runners.
United States
FERC licensing frameworks shape refurbishment economics for aging federal and privately owned hydroelectric assets. GE Vernova anchors presence through integrated software-defined control systems optimizing generator output in real time. The Pacific Northwest and Tennessee Valley concentrate operational bases where grid inertia provision requirements expand turbine orders for ancillary service contracts.
Hydropower Turbine Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with European incumbents commanding premium positioning in high-efficiency refurbishment while Chinese state-owned enterprises capture volume in domestic greenfield development. The vendor base organizes into three strategic archetypes: integrated digital platform providers, deep specialization shops focused on single turbine categories, and scale-driven full-line manufacturers. Competitive moves concentrate on technology licensing agreements for adjustable runner geometries and backward integration into superalloy casting capabilities.
Among the integrated platform tier, ANDRITZ leverages its digital hydropower platform to secure recurring revenue across installed European bases. Voith occupies a position exemplifying deep specialization in Francis turbine refurbishment and efficiency upgrades. GE Vernova represents the control systems integration archetype, anchoring North American presence through real-time generator optimization software.
| Leading Market Players |
|---|
| ANDRITZ |
| GE Vernova |
| Voith |
| Siemens Energy |
| Mitsubishi Heavy Industries |
| Toshiba |
| Dongfang Electric Corporation |
| Harbin Electric |
| BHEL |
| Others |
Supply Flow & Price Mechanics
Utility procurement committees in China and Brazil anchor pricing power through unbundled RFP processes that separate long-term service agreements from initial equipment supply. This buyer concentration forces OEMs toward project-based pricing with performance guarantees tied to IEC 60193 efficiency certification.
Pricing Analysis
Capacity additions in Sichuan and Yunnan provinces are reshaping price floors for Francis turbine runners as domestic manufacturers license European adjustable hub technology. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by peak efficiency thresholds and after-sales bundling. Cost compression in mid-scale units is intensifying because provincial energy bureaus withhold grid connection permits below 92% efficiency. Independent power producers exhibit highest price sensitivity; utility companies with 30-year service agreements show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Chinese rare earth processing facilities that feed permanent magnet generator windings. Manufacturing concentrates in China, Germany, and Austria for precision casting; superalloy blade supply draws from directionally solidified nickel-based specialists. Tariff exposure runs through SAMR export licensing delays for critical magnet materials. Distribution runs through EPC contractors with captive installation crews for large-scale dam projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Additive manufacturing adoption compresses prototype-to-production timelines from 36 months to 14 months, expanding margin capture for OEMs mastering laser powder bed fusion qualification.
For Market Incumbents: Lock in recurring revenue through digital hydropower platforms that secure predictive analytics subscriptions across installed European bases. Deepen backward integration into superalloy casting capabilities to reduce exposure to SAMR export licensing volatility. Threat substitution from reversible pump-turbine specialists in China's 300-800 MW pumped storage segment demands rapid certification investment at IEC 60193 test facilities. For New Entrants and Emerging Players: Enter via cloud-based predictive maintenance platforms targeting Nepal and Vietnam's sub-25 MW installations lacking SCADA integration. White space concentrates in small hydro digitization where API-based performance monitoring displaces traditional OEM captive service contracts. Go-to-market angle: modular runner designs compressing commissioning schedules for Himalayan IPPs prioritizing non-recourse financing. For Investors and Strategic Acquirers: European utility infrastructure funds are the most active acquirer in this space, consolidating refurbishment specialists with IEC efficiency certification capabilities. Long-term viability hinges on grid inertia provision mandates expanding ancillary service revenue streams. Target acquisition archetype: deep specialization shops with Francis turbine refurbishment expertise and established ANEEL or GB 35574-2017 compliance track records. Signal to watch: frequency response service procurement volumes under Brazil's ANEEL and European grid codes.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Deployment | ANDRITZ and Voith compress commissioning schedules through virtual prototyping before physical installation. |
| Backward Integration into Superalloy Casting | OEMs secure captive supply of directionally solidified nickel-based alloys for Himalayan silt-laden rivers. |
| Green Hydrogen Coupling Retrofit | Norwegian alpine plants bypass grid interconnection queues through direct electrolyzer feed configurations. |
| Modular Runner Design Standardization | IPPs in India and Nepal reduce commissioning risk for Himalayan projects with sediment erosion challenges. |
| API-Based Performance Monitoring | Statkraft and EDF pilot unbundled procurement separating predictive analytics from equipment supply contracts. |
Methodological Framework
Multiple input streams — primary interviews with utility planning officers, IPP project developers, and EPC contractors; secondary validation through EIA data, IEA reports, FERC filings, and project development databases; plus customs records on superalloy trade flows — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include turbine product type, installation scale tier, end-user ownership structure, and regional regulatory framework. CAGRs were derived through growth driver quantification against baseline capacity installations. Industry-specific forecast inputs incorporated GB 35574-2017 efficiency mandate enforcement timelines and ANEEL environmental flow compliance rule evolution.
Inputs from utility procurement committees and provincial energy bureau officials were available through the study window; gaps in real-time SAMR export licensing data introduce uncertainty bands around permanent magnet supply assumptions. Forecasts reflect documented assumptions on grid inertia mandate adoption rates and sediment flushing technology advancement. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydropower Systems
United States Hydropower Market
Hydropower Systems
Underground Hydro Power Plant Market
Hydropower Systems
Hydroelectricity Market
Hydropower Systems
Asia-Pacific Pumped Hydro Storage Market
Hydropower Systems
Europe Small Hydropower Market
Hydropower Systems
South America Hydropower Market
Hydropower Systems
Floating Power Plant Market
Hydropower Systems
Whirlpool Turbine Market
Hydropower Systems
Tidal Power Market
Hydropower Systems
Asia-Pacific Hydropower Market
Hydropower Systems
North America Hydropower Market
Hydropower Systems
France Tidal Power Market
Hydropower Systems
Hydropower Generation Market
Hydropower Systems
Hydro Turbines Market
Hydropower Systems
Europe Hydro Turbine Market
Hydropower Systems
Wave and Tidal Energy Market