
 Offshore Hydropower Market | 2026-2036
Offshore Hydropower Market Size, Share, and Industry Trends Forecast 2026-2036
Offshore Hydropower Market Outlook
Utility-grade reliability specifications are reorganizing procurement criteria for offshore hydropower installations, pushing developers toward integrated platform-turbine systems that withstand saline corrosion and extreme wave loading. Iberdrola leverages its North Atlantic project pipeline to anchor floating platform expertise across multiple jurisdictions. Vattenfall sustains competitive pressure through deep specialization in tidal stream arrays with high-capacity factor ratings. Siemens dominates electrical systems integration, supplying converter stations that bridge subsea generation grids to onshore transmission networks.
Offshore hydropower encompasses electricity generation systems deployed in marine or large freshwater environments, utilizing submerged or surface-mounted turbines, pumped storage caverns, and kinetic energy harvesters that convert water pressure differentials and tidal currents into grid-ready power, typically operating at depths exceeding 50 meters where conventional onshore infrastructure proves impractical. Hydraulic turbines occupy the dominant technology position due to proven engineering margins and established maintenance protocols, while tidal energy captures the fastest expansion trajectory as rotor efficiency improvements reduce levelized cost thresholds. Floating structures command disproportionate capital allocation among installation categories, reflecting the shift toward deeper-water sites where fixed platforms face prohibitive foundation costs.
The EU Green Deal and F-Gas Regulation shape equipment standards for offshore electrical infrastructure, restricting synthetic insulating fluids and mandating biodegradable lubricants in subsea machinery. China's MEE enforces marine ecological red lines that constrain project siting along the Yangtze estuary and Bohai Bay. Stakeholders must weigh jurisdictional permitting complexity against resource quality when sequencing international project portfolios, particularly where overlapping national claims to continental shelf rights introduce legal uncertainty.
Market Dynamics
Utility procurement of floating turbine arrays is reorganizing capital allocation across the offshore hydropower value chain, compressing development timelines as developers compete for seabed leases in high-velocity corridors. This demand pull is accelerating platform standardization and forcing electrical system integrators to co-locate converter stations with installation ports.
Growth Catalysts
- EU Green Deal offshore targets:Binding capacity mandates for marine renewables are streamlining environmental permitting timelines in Norwegian and Scottish waters, reducing project development risk.
- Baseload substitution demand:Grid operators facing renewable intermittency are procuring tidal stream arrays with capacity factors exceeding conventional offshore wind.
- Rotor efficiency improvements:Advanced blade geometries and variable-pitch systems are lowering levelized cost thresholds for commercial-scale tidal deployment.
Market Restraints
- Foundation cost escalation:Fixed-bottom structures face prohibitive capital requirements at depths exceeding 60 meters, constraining site selection to shallower continental shelves.
- Subsea cable manufacturing concentration:Specialized high-voltage DC cable supply concentrates among a limited European supplier base, creating bottleneck risk for array-to-shore transmission.
- Saline corrosion protocols:Extended protective coating lifecycles and cathodic protection systems add recurring OPEX burdens not present in onshore hydropower.
Strategic Opportunities
- Untapped Pacific coastlines:Chile and Peru offer unexploited tidal velocity resources with limited competing marine use, presenting first-mover lease advantages.
- Pumped storage cavern integration:Subsurface rock formations in Scotland and Norway enable hybrid generation-storage configurations that arbitrage intraday price spreads.
- Biodegradable lubricant mandates:F-Gas Regulation compliance requirements are creating premium market segments for environmentally certified turbine drivetrains.
Industry Challenges
- Marine engineering talent scarcity:Deep-water mooring design and dynamic cable routing expertise concentrates among North Sea oil-and-gas veterans approaching retirement.
- Certification timeline compression:IEC 62600-1 marine energy converter standards require multi-year tank testing and sea trials, delaying revenue recognition.
- Legacy grid integration:Onshore substations in remote coastal regions lack capacity headroom for multi-hundred-megawatt array connections.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Offshore Hydropower Market |
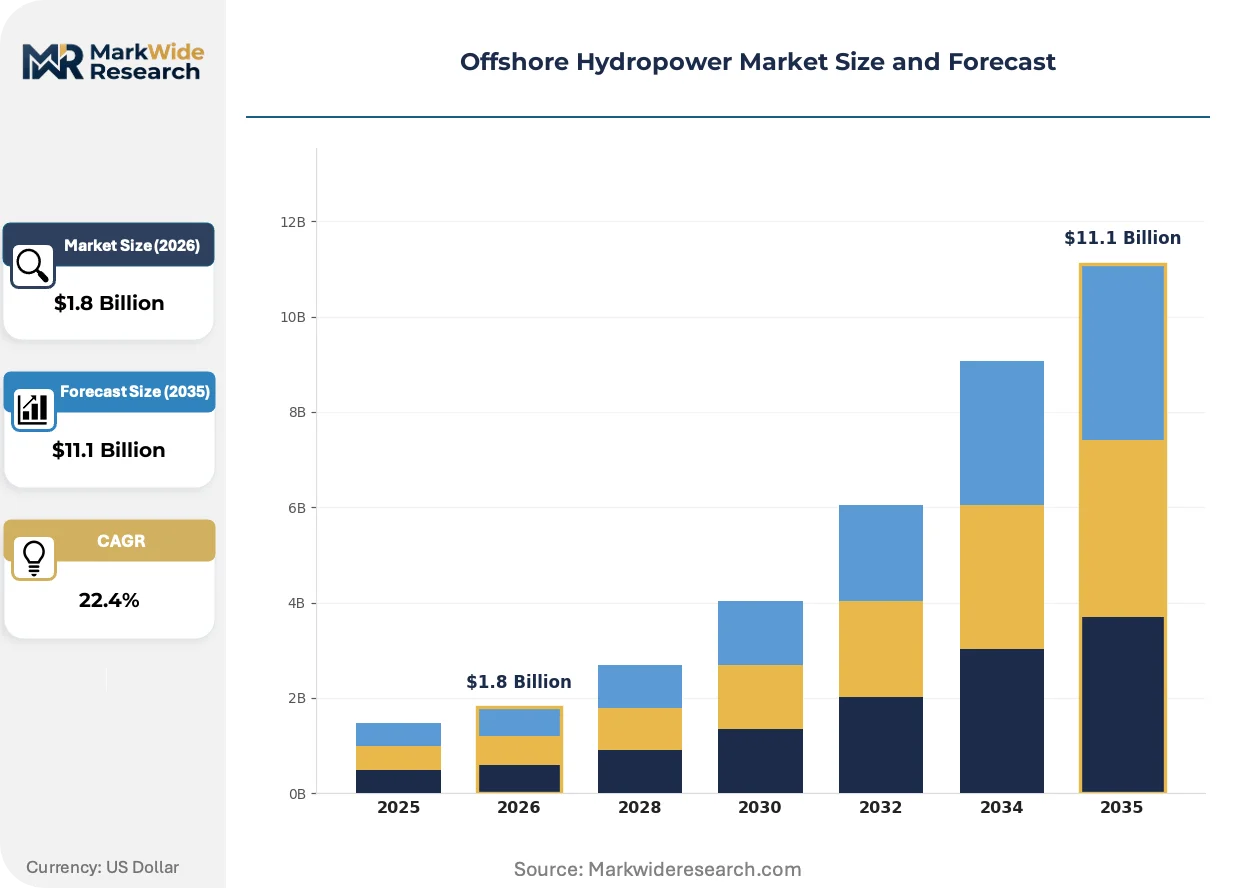
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $11.1 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Hydraulic Turbines, Pumped Storage, Tidal Energy, Wave Energy Application: Electricity Generation, Water Management, Environmental Protection, Fisheries Management End User: Utilities, Government Agencies, Industrial Users, Developers Installation: Fixed Platforms, Floating Structures, Subsea Installations, Modular Systems |
| Companies Covered | Iberdrola, Vattenfall, Calpine Corp, Siemens, Alstom, China Yangtze Power, Hydrochina International Engineering, Minesto AB, Verdant Power, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Offshore Hydropower Market Strategic Shifts
Floating platform architectures are displacing fixed-bottom foundations as the default engineering choice, triggering cascading changes in mooring systems, dynamic cables, and installation vessel specifications. This shift is compressing supply chains around deeper-water competencies and away from jack-up barge-dependent construction methods.
Composite blade materials are displacing traditional steel and aluminum rotor constructions in tidal stream turbines. Developers in the Pentland Firth and Orkney waters are deploying these lighter, fatigue-resistant blades to extend maintenance intervals in high-shear current environments. The structural consequence is displacing heavy-lift vessel requirements from installation campaigns, reducing day-rate exposure and weather window constraints.
The EU F-Gas Regulation and China's MEE marine ecological red lines are tightening equipment specifications for subsea electrical infrastructure. Synthetic insulating fluids face phase-out timelines, compelling converter station suppliers to qualify biodegradable alternatives. Offshore array projects in the Yangtze estuary and Bohai Bay are experiencing siting constraints that favor floating platforms over seabed-anchored alternatives.
Long-term power purchase agreements with industrial offtakers are displacing merchant-exposed development finance in the North Sea corridor. Aluminum smelters and data center operators in Norway and the Netherlands are contracting directly for baseload tidal output, bypassing utility intermediaries. This bilateral contracting pattern is most visible in Scotland, where vertically integrated energy consumers are securing 15-20 year offtake commitments to underwrite project debt.
Offshore Hydropower Market Segmentation
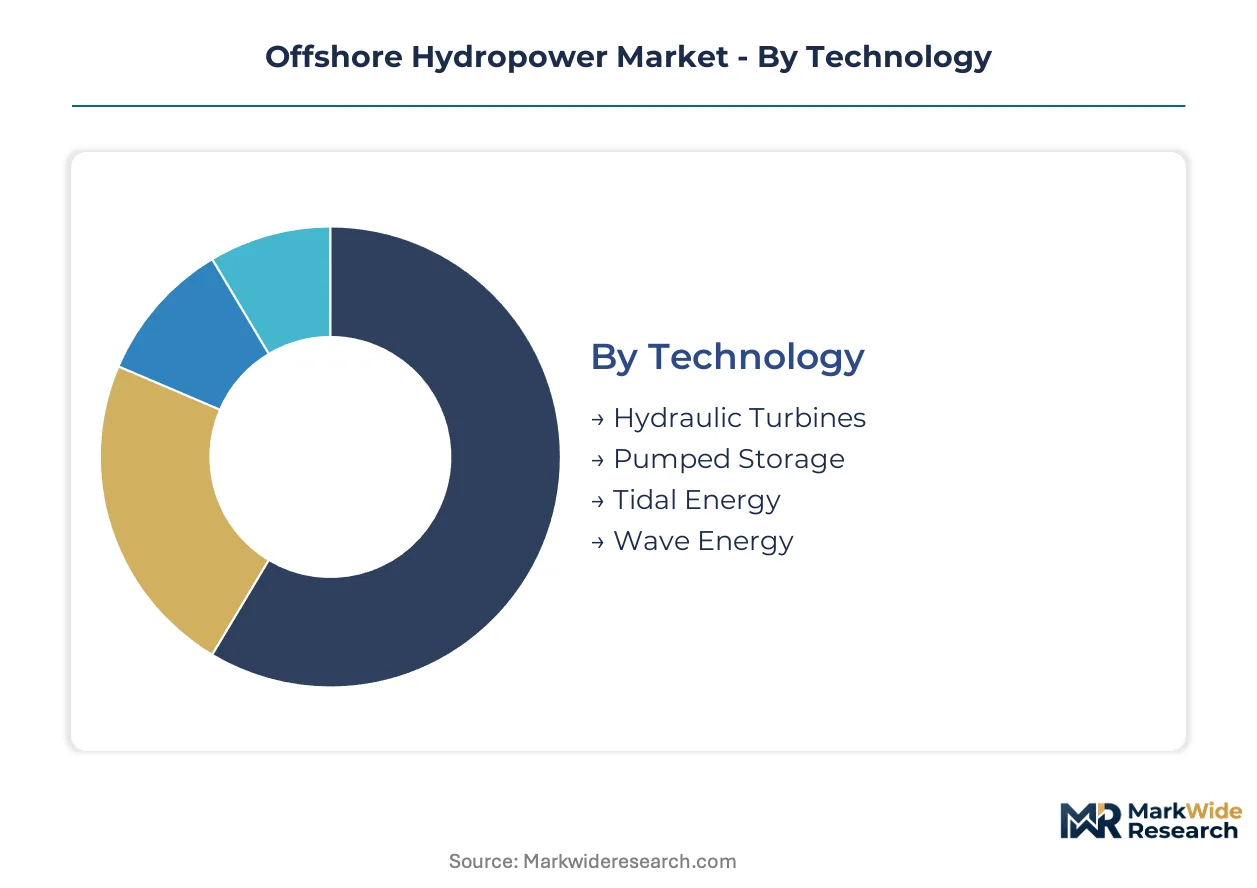
Segmentation reveals how regulatory frameworks, water depth constraints, and offtake contract structures reshape procurement priorities across the offshore hydropower value chain. Technology and installation categories dominate capital allocation decisions, while end-user concentration determines project financing structures.
Technology:
The EU F-Gas Regulation and China's MEE marine ecological red lines impose divergent equipment specifications across technology categories, with biodegradable lubricant mandates favoring certain drivetrain architectures over others.
- Hydraulic Turbines:Submerged or surface-mounted axial and Kaplan turbine configurations dominate commercial deployments due to proven engineering margins and established maintenance protocols. Demand concentrates in Norwegian and Scottish waters where utilities procure these systems for baseload grid integration, constrained by IEC 62600-1 certification timelines that delay revenue recognition.
- Tidal Energy:Horizontal-axis and vertical-axis rotor systems capture kinetic energy from predictable current flows, with advanced blade geometries improving capacity factors above conventional offshore wind. Developers in the Pentland Firth and Orkney waters deploy composite blade materials to extend maintenance intervals in high-shear environments, accelerating adoption as rotor efficiency gains compress levelized cost thresholds.
- Pumped Storage:Subsurface cavern configurations enable hybrid generation-storage arbitrage.
- Wave Energy:Point absorbers and oscillating water column systems remain pre-commercial.
Established volume favors hydraulic turbines; emerging adoption favors tidal energy.
Application:
Cost tier differentiation separates utility-scale generation projects from ancillary service contracts, with environmental protection applications commanding premium pricing for certified equipment.
- Electricity Generation:Grid-connected arrays producing baseload or dispatchable power dominate capital deployment, with long-term power purchase agreements from aluminum smelters and data center operators in the Netherlands and Norway displacing merchant-exposed finance. EU Green Deal binding capacity mandates streamline permitting for these projects in high-velocity corridors.
- Water Management:Pumped storage and flow regulation systems address seasonal variability and flood control requirements. Scottish and Norwegian subsurface rock formations enable hybrid configurations that arbitrage intraday price spreads, attracting integrated utility investment.
- Environmental Protection:Habitat restoration and flow augmentation systems require specialized ecological certification.
- Fisheries Management:Selective water withdrawal and temperature control applications serve aquaculture operations.
Revenue concentration clusters in electricity generation; regulatory tailwinds strengthen water management.
End User:
Customer type determines contracting structure, with bilateral industrial offtake agreements reshaping traditional utility intermediation patterns in the North Sea corridor.
- Utilities:Vertically integrated grid operators and independent power producers procure floating turbine arrays as baseload alternatives to intermittent renewables, driving platform standardization and forcing electrical system integrators to co-locate converter stations with installation ports. Norwegian and Dutch utilities anchor demand through 15-20 year offtake commitments.
- Developers:Independent project sponsors compete for seabed leases in high-velocity corridors, compressing development timelines. These firms concentrate in Scotland and the Pentland Firth, where limited competing marine use enables first-mover lease advantages.
- Government Agencies:Public procurement supports demonstration projects and strategic reserve capacity.
- Industrial Users:Direct corporate renewable energy procurement bypasses utility intermediaries.
Contracting volume tilts toward utilities; project origination concentrates with developers.
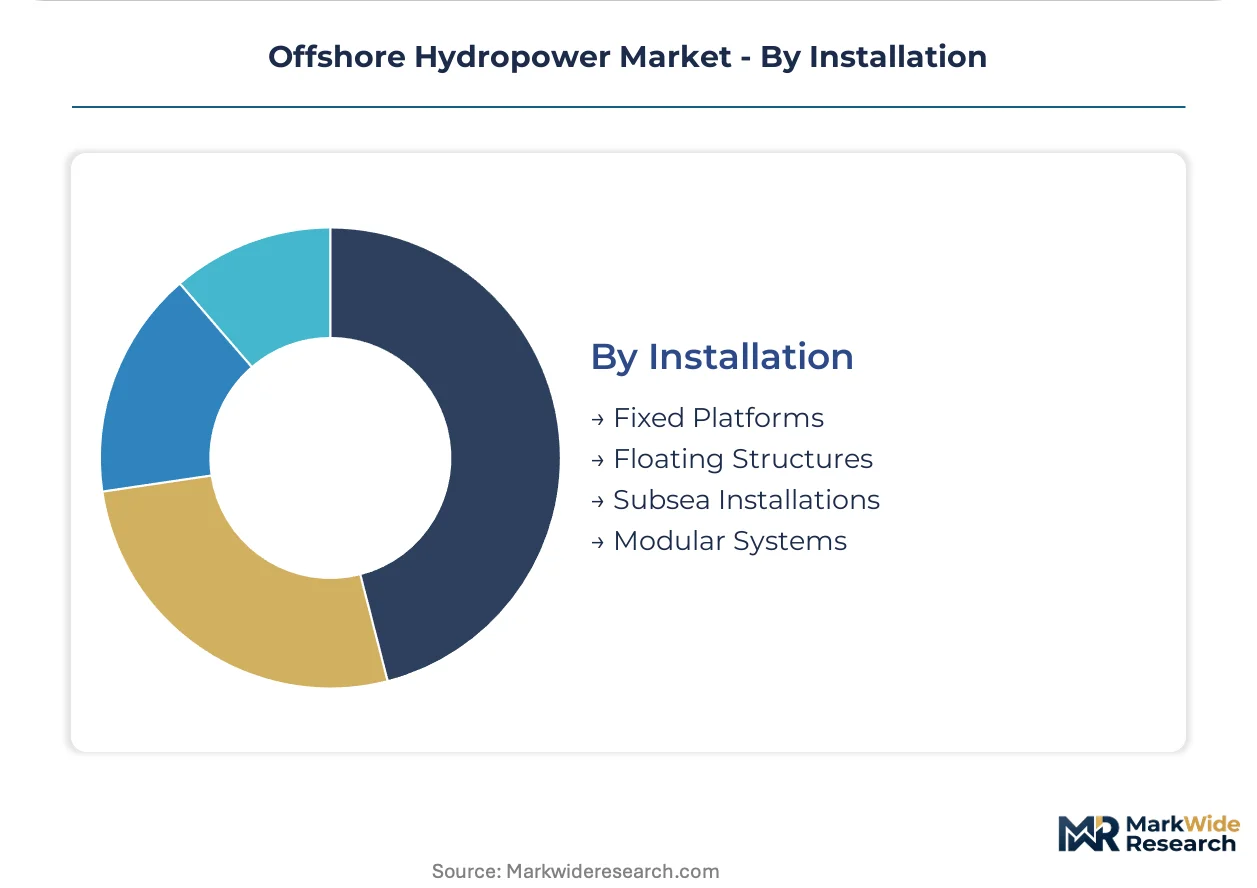
Installation:
Water depth economics drive structural shift away from jack-up barge-dependent methods toward deeper-water competencies that reshape supply chain geography.
- Floating Structures:Platform-turbine integrated systems with dynamic mooring and cable configurations command disproportionate capital allocation, reflecting the shift toward sites exceeding 50-60 meter depths where fixed platforms face prohibitive foundation costs. North Sea oil-and-gas engineering expertise concentrates among Norwegian and Scottish contractors approaching retirement, creating talent scarcity.
- Fixed Platforms:Gravity-base and monopile structures retain viability in shallower continental shelves. These installations face capital escalation at depths exceeding 60 meters, constraining site selection and compressing addressable market share.
- Subsea Installations:Fully submerged systems minimize surface exposure and visual impact.
- Modular Systems:Standardized, scalable configurations reduce deployment lead times.
Capital deployment favors floating structures; residual demand anchors fixed platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentration clusters among North Sea jurisdictions where tidal velocities and water depths favor commercial deployment. Project pipelines concentrate in corridors linking Norwegian fjords, Scottish archipelagos, and Dutch coastal zones.
Norway
Utility procurement of floating turbine arrays drives capital allocation toward deep-water sites in the Norwegian Sea. The EU Green Deal's binding offshore capacity mandates streamline environmental permitting for projects in Rogaland and Hordaland counties. Bergen anchors engineering expertise for dynamic mooring systems and converter station integration.
United Kingdom
Scottish waters host the densest concentration of tidal stream demonstration projects, with the Pentland Firth recording sustained current velocities above three meters per second. The Crown Estate's seabed leasing rounds compress development timelines for independent project sponsors. Orkney Islands serve as the primary testbed for composite blade materials in high-shear environments.
Netherlands
Industrial offtake agreements from aluminum smelters and data center operators reshape contracting structures for North Sea array output. National offshore wind targets create regulatory tailwinds for hybrid marine renewable configurations. Rotterdam port infrastructure supports co-located converter station fabrication and installation vessel mobilization.
China
The MEE's marine ecological red lines constrain project siting along the Yangtze estuary and Bohai Bay, favoring floating platforms over fixed-bottom alternatives. Dual carbon goals accelerate procurement of submerged turbine systems for baseload grid integration. Shanghai-based engineering consortia dominate electrical systems integration for domestic array projects.
Chile
Unexploited tidal velocity resources along the Pacific coastline attract first-mover lease competition with limited competing marine use. National renewable energy auctions create offtake price certainty for pre-commercial deployments. Magallanes Region hosts the most advanced pilot projects targeting the Strait of Magellan's current flows.
Offshore Hydropower Market Competitive Environment
Concentration sits with integrated utilities and electrical engineering conglomerates that control platform-turbine integration and grid connection infrastructure. The competitive structure tiers across three archetypes: North Atlantic utility developers with multi-jurisdiction project pipelines, specialized tidal stream technology firms with proprietary rotor designs, and electrical systems integrators supplying converter stations and subsea transmission hardware. Dominant competitive moves include strategic partnerships between platform engineers and installation vessel operators, plus portfolio diversification into hybrid generation-storage configurations.
Within the utility-developer tier, Iberdrola and Vattenfall exemplify contrasting geographic strategies, with the former anchoring floating platform expertise across multiple North Atlantic jurisdictions and the latter concentrating deep specialization in high-capacity-factor tidal stream arrays. Siemens occupies a distinct position as the dominant electrical systems integrator, supplying converter stations that bridge subsea generation grids to onshore transmission networks. Minesto AB represents the technology-specialist archetype, developing proprietary kinetic energy harvesters for low-velocity current environments.
| Leading Market Players |
|---|
| Iberdrola |
| Vattenfall |
| Calpine Corp |
| Siemens |
| Alstom |
| China Yangtze Power |
| Hydrochina International Engineering |
| Minesto AB |
| Verdant Power |
| Others |
Value Chain & Pricing Dynamics
Floating platform substitution for fixed-bottom foundations simultaneously redistributes supply chain geography toward North Sea engineering hubs and compresses pricing economics for installation services. This displacement concentrates procurement leverage among Norwegian and Scottish contractors while elevating capital costs for deeper-water mooring systems.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure across equipment categories, separating biodegradable-lubricant-certified drivetrains from conventional alternatives. Project-based long-term offtake contracts dominate utility-scale deployments, with price differentiation anchored in IEC 62600-1 certification status and converter station integration depth. Cost compression in fixed-bottom installations intensifies because depth constraints limit addressable site inventory. Industrial offtakers in the Netherlands exhibit lowest price sensitivity due to baseload substitution premiums, while independent developers in Chile face acute capital discipline.
Supply Chain Analysis
Strategic stockpiling of high-voltage DC cable inventory characterizes developer procurement behavior given European supplier concentration and multi-year manufacturing lead times. Supply concentrates in Norway, Germany, and the United Kingdom for dynamic mooring systems, converter stations, and composite blade fabrication. Raw material dependencies span rare-earth magnets for generator assemblies, specialized marine-grade steel for platform structures, and bio-based lubricant formulations. Single-source vulnerability concentrates in subsea cable manufacturing. Distribution runs through EPC contractors with integrated installation vessel fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as baseload substitution demand splinters procurement authority from traditional utilities toward industrial offtakers, creating niche entry points for specialized platform engineers and certified component suppliers.
For Market Incumbents: Secure exclusive converter station co-location agreements at Rotterdam and Bergen port facilities to preempt competitor access to installation mobilization infrastructure. Anchor floating platform expertise through captive engineering talent acquisition from retiring North Sea oil-and-gas specialists, countering workforce scarcity that threatens project execution timelines.
For New Entrants and Emerging Players: Lead with proprietary composite blade designs targeting high-shear current environments in the Pentland Firth and Orkney waters, where extended maintenance intervals command equipment premiums. Direct sales to vertically integrated aluminum smelters and data center operators bypass utility intermediation and accelerate revenue recognition.
For Investors and Strategic Acquirers: The EU Green Deal's binding offshore capacity mandates reshape the acquisition landscape toward platform-turbine integrators with multi-jurisdiction permitting track records. Long-term viability hinges on hybrid generation-storage configuration capabilities that arbitrage intraday price spreads. Acquisition target archetype: tidal stream technology firms with proprietary rotor geometries and Scottish demonstration project operational history. Signal to watch: industrial offtake contract tenor extension beyond fifteen years.
| Strategic Initiative | Industry Significance |
|---|---|
| Floating Platform Standardization | Reduces engineering redundancy across Norwegian and Scottish project portfolios. |
| Biodegradable Lubricant Certification | Unlocks premium pricing tiers under F-Gas Regulation compliance requirements. |
| Converter Station Co-location | Compresses installation timelines by integrating fabrication with port infrastructure. |
| Composite Blade Deployment | Extends maintenance intervals in high-shear environments like Pentland Firth. |
| Pumped Storage Cavern Integration | Enables hybrid arbitrage configurations in Scottish and Norwegian subsurface formations. |
Study Parameters
Operator-level perspectives from utility planning officers, independent project developers, EPC contractors, and grid operators anchored the qualitative base. Primary interviews combined with secondary validation from FERC filings, IEA marine energy reports, Crown Estate seabed leasing records, and project development databases. Bottom-up installation cost modeling and top-down regulatory scenario analysis provided triangulation.
Sensitivity analysis tested forecast outputs against variable regulatory enforcement timelines and raw material cost trajectories across the projection horizon. Segmentation dimensions modeled include technology category, installation depth tier, project scale, end-user contracting structure, and regional regulatory framework. CAGRs derived from unit economics build-ups incorporating named capacity factor improvements and platform cost learning curves. Industry-specific inputs span tidal velocity resource assessments and marine construction labor availability.
Underlying assumptions cover EU Green Deal implementation continuity and F-Gas Regulation phase-out adherence, with deviation risk concentrated in seabed leasing timeline compression and subsea cable manufacturing capacity constraints. Revision becomes warranted when industrial offtake contract penetration crosses utility-scale procurement thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydropower Systems
Hydropower Generation Market
Hydropower Systems
United States Hydropower Market
Hydropower Systems
Europe Small Hydropower Market
Hydropower Systems
Hydropower Turbine Market
Hydropower Systems
France Tidal Power Market
Hydropower Systems
Hydro Turbines Market
Hydropower Systems
Southeast Asia Hydropower Market
Hydropower Systems
Underground Hydro Power Plant Market
Hydropower Systems
Japan Hydropower Market
Hydropower Systems
North America Pumped Hydro Storage Market
Hydropower Systems
Small Hydropower Market
Hydropower Systems
Asia-Pacific Small Hydropower Market
Hydropower Systems
North America Hydropower Market
Hydropower Systems
Floating Power Plant Market
Hydropower Systems
Asia-Pacific Pumped Hydro Storage Market
Hydropower Systems
Run of River Power Market