
 Energy Transition Market | 2026-2036
Energy Transition Market Size, Share, and Industry Trends Forecast 2026-2036
Energy Transition Market Analysis
Aftermarket service revenue is narrowing as original equipment manufacturers capture lifecycle value through long-term service contracts. NextEra Energy anchors its position through integrated renewable development and utility-scale storage deployment. LONGi Green Energy Technology dominates wafer and module manufacturing through aggressive capacity expansion and cost curve positioning.
Energy transition encompasses the structural shift from fossil fuel-based systems to low-carbon alternatives through electrification, renewable generation, and grid modernization, requiring power electronics with switching frequencies above 20 kHz and battery systems achieving 6,000+ cycle life. Renewable energy and energy storage command the dominant margin pools as capital formation shifts toward dispatchable clean power, while smart grids represent the fastest-growing service type as distribution operators modernize for bidirectional power flows. Solar technology leads deployment volumes through crystalline silicon cost reductions, though wind technology sustains higher capacity factors in offshore basins.
The EPA enforces power plant emissions standards under the Clean Air Act that mandate carbon capture or fuel switching, while FERC Order 2222 enables distributed energy resource aggregation in wholesale markets. China's MIIT sets dual carbon goals through GB standards for energy efficiency and renewable manufacturing quotas. Stakeholders must monitor regulatory fragmentation between jurisdictions as compliance costs diverge and supply chain localization requirements multiply.
Market Dynamics
Capital formation is rotating toward dispatchable clean power as grid operators face simultaneous pressures from electrification loads and renewable intermittency, forcing synchronous procurement of battery storage and flexible generation assets.
Growth Catalysts
- EU Green Deal carbon border adjustments:Industrial importers into the European Union face embedded emissions tariffs, redirecting capital toward low-carbon domestic production and clean power offtake agreements.
- Power generation utilities:Battery storage procurement is accelerating as grid modernization timelines converge with renewable penetration targets, creating bundled development opportunities.
- FERC Order 2222:Distributed energy resource aggregation in US wholesale markets unlocks revenue streams for behind-the-meter assets, expanding addressable market for storage and solar developers.
Market Restraints
- Lithium carbonate price volatility:Battery cell input costs swing with South American brine and Australian spodumene concentrate supply disruptions, compressing project returns.
- Polysilicon supply concentration:Xinjiang-based producers control crystalline silicon refining capacity, exposing module manufacturers to forced labor due diligence risks and trade barrier exposure.
- Grid interconnection queues:Transmission upgrade backlogs in Texas, California, and Germany delay project energization by 3-5 years, trapping capital in development limbo.
Strategic Opportunities
- India's PLI scheme for solar manufacturing:Production-linked incentives for polysilicon-to-module domestic value chains attract capital seeking supply chain localization outside China.
- Green hydrogen offtake:Electrolyzer deployment for ammonia and steel decarbonization creates new demand sink for curtailed renewable generation in Spain and Australia.
- Vehicle-to-grid integration:Bidirectional charging standards enable electric vehicle fleets as distributed storage resources, opening revenue stacking for fleet operators in California and Germany.
Industry Challenges
- Power electronics engineering scarcity:Design talent for 20+ kHz switching frequency inverters and grid-forming converters concentrates at a handful of semiconductor firms and research institutes.
- CE marking timeline compression:EU machinery and electromagnetic compatibility certification for novel storage systems extends commercialization schedules by 12-18 months.
- Legacy SCADA integration:Distribution operators struggle to overlay bidirectional power flow management onto decades-old control systems without full infrastructure replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Energy Transition Market |
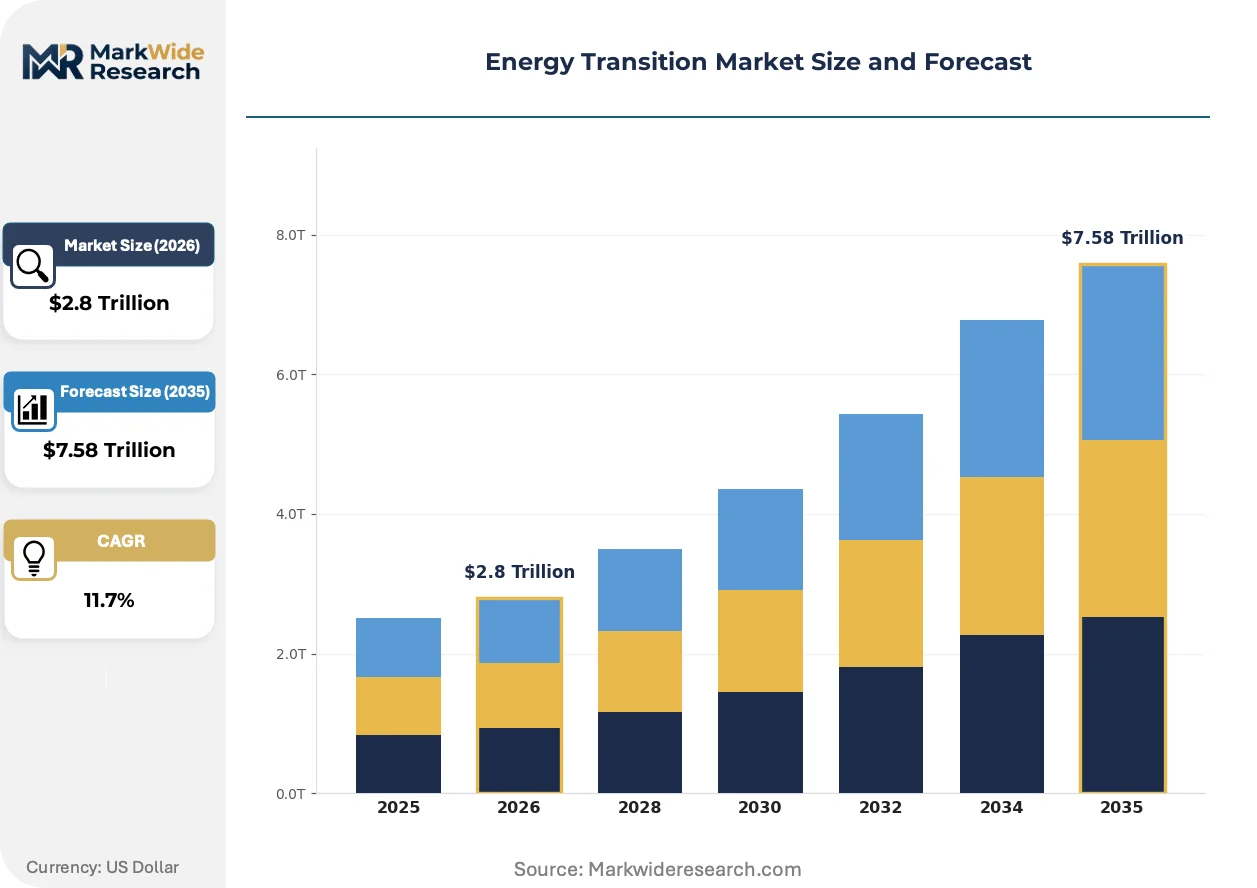
| Market Size in 2026 | $2.8 Trillion |
| Market Size in 2035 | $7.58 Trillion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Renewable Energy, Energy Storage, Smart Grids, Carbon Capture Application: Power Generation, Transportation, Industrial, Residential Technology: Solar, Wind, Hydroelectric, Biogas End User: Utilities, Corporations, Government, Consumers |
| Companies Covered | Sungrow Power Supply, Invenergy, NextEra Energy, Adani Green Energy, Apex Clean Energy, Brookfield Renewable Partners, Clearway Energy Group, LONGi Green Energy Technology, First Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Energy Transition Market Emerging Trajectories
Silicon carbide semiconductors and solid-state battery chemistries are compressing cost-performance curves faster than incumbent technologies can adapt, reshaping competitive moats around manufacturing scale and materials science.
Silicon carbide MOSFETs replace silicon IGBTs in high-frequency power conversion. Offshore wind developers and EV drivetrain manufacturers are adopting them for efficiency gains. This is collapsing thermal management system costs and enabling higher power density inverters.
China's MIIT dual carbon goals mandate GB standards for energy efficiency and renewable manufacturing quotas. Domestic module and cell producers must meet carbon intensity benchmarks for export eligibility. European importers now require supply chain documentation proving compliance.
Corporate renewable energy buyers are consolidating procurement through virtual power purchase agreements rather than onsite generation. Data center operators and semiconductor fabs in Taiwan and Arizona lead this shift. Financial intermediaries in London and Singapore now structure and syndicate these contracts.
Energy Transition Market Segmentation
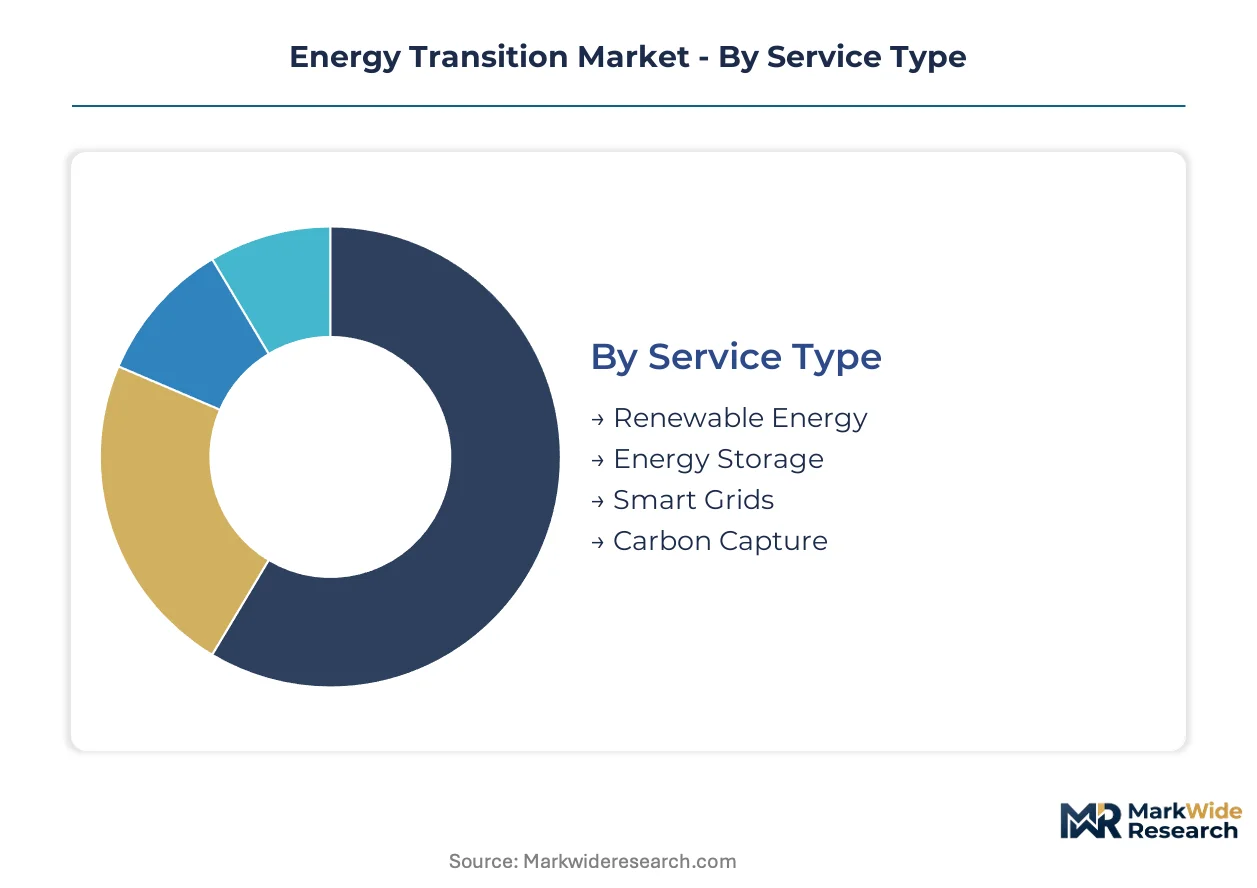
Segmentation in energy transition markets separates capital deployment cycles from technology maturation curves. Procurement timelines for grid infrastructure stretch across decades while battery storage contracts turn over in 3-5 year windows.
Service Type:
Replacement cycles vary from 15-year smart grid hardware refreshes to 5-year energy storage performance warranties, creating divergent vendor cash flow profiles.
- Renewable Energy:Crystalline silicon solar and onshore wind dominate capacity additions through standardized equipment procurement. Utility-scale solar in the United States and offshore wind in Germany absorb the majority of institutional capital as power purchase agreement tenors extend to 20-25 years.
- Energy Storage:Lithium-ion battery systems with 6,000+ cycle life specifications anchor grid stabilization services. Procurement in Texas and California accelerates as renewable penetration exceeds 40% of generation mix, forcing synchronous deployment with solar and wind assets.
- Smart Grids:Distribution automation and advanced metering infrastructure enable bidirectional power flow management.
- Carbon Capture:Post-combustion amine scrubbing and direct air capture systems serve cement and steel decarbonization.
Renewable energy anchors the volume base while energy storage gains share at the steepest rate.
Application:
Cost tiers separate billion-dollar utility infrastructure from residential solar leases under $20,000.
- Power Generation:Utility-scale solar, wind, and combined-cycle gas with carbon capture supply bulk electricity. Developers in India and Spain prioritize projects with offtake contracts from data center operators and semiconductor fabs.
- Transportation:Electric vehicle charging infrastructure and fleet electrification programs absorb storage and power electronics. California's vehicle-to-grid pilots and Germany's highway fast-charging corridors concentrate deployment.
- Industrial:Green hydrogen electrolyzers and process heat electrification serve ammonia and steel production.
- Residential:Rooftop solar plus battery systems target net metering and backup power applications.
Power generation commands the capital base while transportation applications expand most quickly.
Technology:
Technology maturity curves separate decades-proven hydroelectric from solid-state battery chemistries still in pilot phase.
- Solar:Crystalline silicon modules with passivated emitter rear contact architecture achieve 22%+ conversion efficiency. Manufacturing concentration in China and capacity expansion under India's PLI scheme reshape supply geography.
- Wind:Offshore turbines exceeding 15 MW capacity factor sustain 50%+ in North Sea basins. Developers in the United Kingdom and Taiwan advance floating foundation designs for deeper water access.
- Hydroelectric:Pumped storage and run-of-river installations provide baseload and frequency regulation.
- Biogas:Anaerobic digestion of agricultural waste produces biomethane for grid injection and transport fuel.
Solar technology anchors the volume base while wind technology climbs the fastest in average project scale.
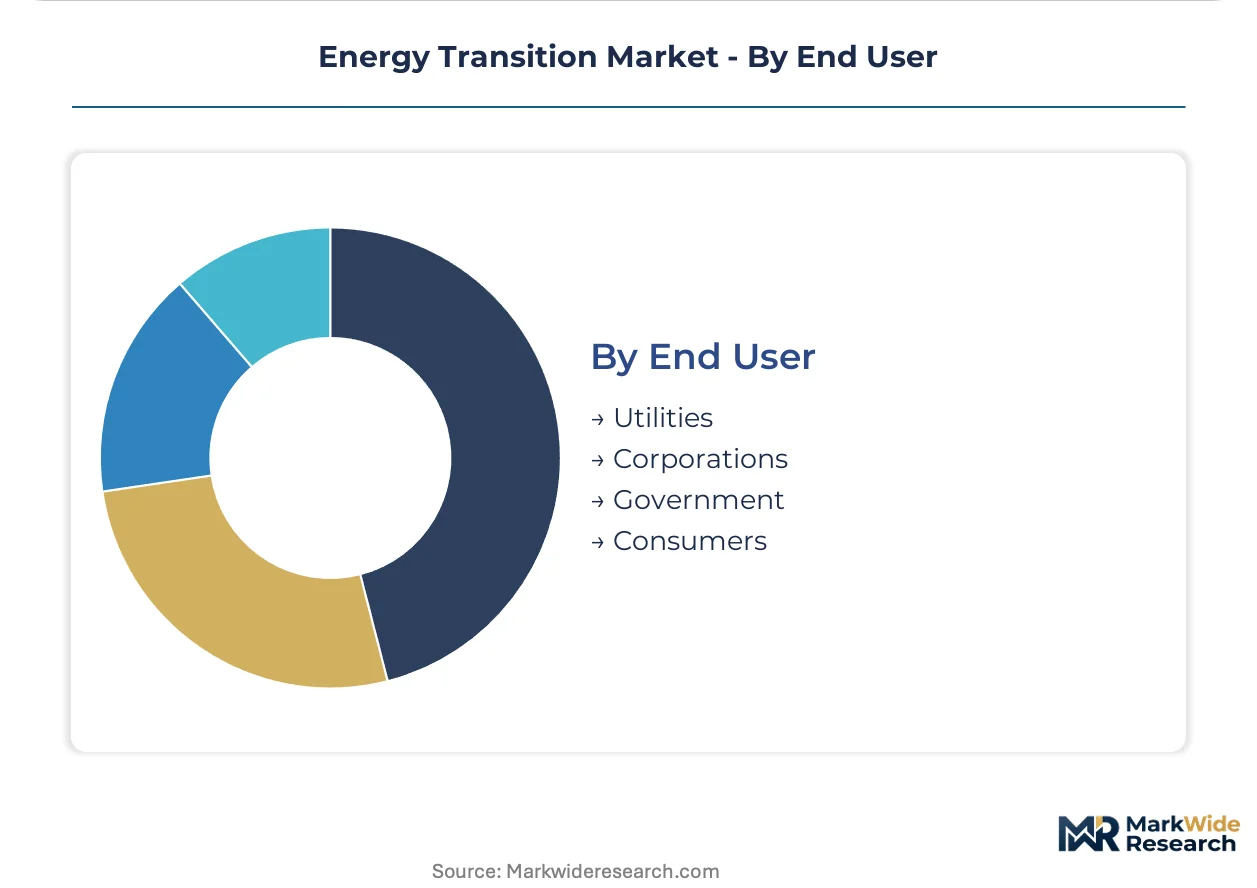
End User:
Customer sophistication tiers separate integrated utilities with in-house procurement teams from residential consumers relying on installer networks.
- Utilities:Vertically integrated power generation companies and distribution operators procure at gigawatt scale. NextEra Energy and national champions in Germany and China bundle renewable development with storage and grid services.
- Corporations:Data center operators and semiconductor manufacturers source renewable energy through virtual power purchase agreements. Financial intermediaries in London and Singapore structure and syndicate these contracts.
- Government:Municipal and national entities fund grid modernization and rural electrification programs.
- Consumers:Residential and small commercial buyers adopt rooftop solar and battery storage through lease and loan products.
Utilities anchor the volume base while corporations gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Southeast Asia exhibit acute price sensitivity to module and cell costs, while German and US utilities absorb premium pricing for dispatchable clean power as grid stability premiums override capital efficiency concerns.
Germany
Offshore wind developers in the North Sea basin drive demand for 15+ MW turbines and grid-forming converters. The EU Green Deal carbon border adjustments force industrial importers to secure low-carbon power purchase agreements. The Port of Hamburg anchors electrolyzer manufacturing clusters for green hydrogen export to steel and ammonia producers.
United States
Texas and California utilities procure battery storage at gigawatt scale as renewable penetration exceeds grid stability thresholds. FERC Order 2222 enables distributed energy resource aggregation in wholesale markets, unlocking revenue streams for behind-the-meter assets. The ERCOT interconnection queue in Texas traps solar and wind projects in 3-5 year development delays.
China
MIIT dual carbon goals mandate GB standards for energy efficiency and renewable manufacturing quotas. Domestic module producers must meet carbon intensity benchmarks for export eligibility. Xinjiang-based polysilicon refining concentration exposes supply chains to forced labor due diligence risks and trade barrier exposure.
India
The PLI scheme for solar manufacturing attracts capital seeking polysilicon-to-module domestic value chains outside China. State-owned power generation utilities bundle renewable development with utility-scale storage procurement. Gujarat and Rajasthan host gigawatt-scale solar parks with dedicated manufacturing zones for cells and modules.
Australia
Green hydrogen offtake agreements from Japanese and Korean industrial buyers drive electrolyzer deployment in Queensland and Western Australia. Curtailed renewable generation from remote solar and wind assets feeds ammonia and steel decarbonization projects. The Pilbara region concentrates iron ore producers seeking clean process heat and hydrogen reduction.
Energy Transition Market Vendor Landscape
Capability concentration sits with power electronics and semiconductor specialists; scale advantage sits with integrated project developers and module manufacturers. The vendor base separates into three tiers: vertically integrated renewable developers owning generation and grid assets, pure-play manufacturers dominating crystalline silicon cost curves, and financial sponsors syndicating virtual power purchase agreements. Competitive moves center on backward integration into polysilicon refining and captive battery cell production.
Among Chinese module and inverter specialists, Sungrow Power Supply and LONGi Green Energy Technology exemplify the manufacturing-scale archetype through aggressive capacity expansion and cost curve positioning. NextEra Energy anchors the integrated developer tier through bundled renewable and storage procurement in US wholesale markets. These three occupy positions at the intersection of manufacturing scale and project development integration.
| Leading Market Players |
|---|
| Sungrow Power Supply |
| Invenergy |
| NextEra Energy |
| Adani Green Energy |
| Apex Clean Energy |
| Brookfield Renewable Partners |
| Clearway Energy Group |
| LONGi Green Energy Technology |
| First Solar |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese crystalline silicon wafer production is compressing module pricing globally and forcing suppliers toward long-term offtake contracts to lock in utilization rates and defend margin structures.
Pricing Analysis
Long-term power purchase agreements dominate utility-scale transactions, with virtual PPAs syndicated by London and Singapore financial intermediaries commanding premiums over spot-market exposure. Price differentiation rests on certification tier — UL-listed versus CE-marked systems — and volume scale, with gigawatt-scale procurement securing double-digit discounts. Cost compression in residential solar leases is intensifying because installer networks compete for customer acquisition. Data center operators and semiconductor fabs show least price sensitivity, absorbing premiums for dispatchable clean power with grid stability guarantees.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for module and inverter procurement. Manufacturing concentrates in China, Vietnam, and India as India's PLI scheme attracts polysilicon-to-module domestic value chains. Raw material dependencies center on lithium carbonate from South American brine, Australian spodumene concentrate, and Xinjiang-based polysilicon refining. Single-source vulnerability in semiconductor-grade silicon carbide substrates constrains power electronics scaling. Distribution runs through vertically integrated developers, pure-play manufacturers, and financial sponsors syndicating virtual power purchase agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment — through FERC Order 2222 aggregation rights and EU Green Deal carbon border adjustments — creates structural barriers to displacement for established participants.
For Market Incumbents: Entrench position through captive battery cell production and backward integration into polysilicon refining to offset lithium carbonate price volatility and Xinjiang supply concentration risks. Secure long-term service contracts that capture lifecycle value from original equipment, narrowing aftermarket revenue pools for third-party providers. Prioritize certification investment in grid-forming converter capabilities to meet 20+ kHz switching frequency specifications where engineering talent concentrates at semiconductor specialists. For New Entrants and Emerging Players: India's state-owned power generation utilities present the most penetrable entry point, with bundled renewable and storage procurement accelerating under PLI scheme incentives. Target vehicle-to-grid integration pilots in California and Germany where bidirectional charging standards are unlocking revenue stacking for fleet operators. Pursue green hydrogen offtake agreements from Japanese and Korean industrial buyers in Queensland and Western Australia as the go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-compounding play because power generation utilities face irreversible capital rotation toward dispatchable clean power as electrification loads and renewable intermittency force synchronous procurement. Acquisition targets should concentrate on power electronics engineering specialists with grid-forming converter design capabilities. Watch for electrolyzer deployment announcements in Spain and Australia as the signal indicating green hydrogen demand sink maturity.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Gigawatt-scale solar parks in Gujarat and Rajasthan absorb institutional capital seeking manufacturing co-location. |
| Power Purchase Agreement | Virtual PPAs syndicated by London intermediaries enable data center operators to source renewable energy without onsite generation. |
| Technology Licensing | Solid-state battery chemistry pilots compress cost-performance curves faster than incumbent lithium-ion can adapt. |
| Backward Integration into Storage | Captive battery cell production defends margins against South American brine and Australian spodumene supply disruptions. |
| Green Certification Program | MIIT GB standards compliance enables Chinese module producers to maintain European export eligibility under carbon intensity benchmarks. |
Methodological Framework
Desk research of EIA data, IEA reports, FERC filings, and project development databases preceded structured interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators. Primary fieldwork with battery storage procurement specialists and renewable development executives was cross-validated against secondary sources including SEC filings from integrated developers and customs data on module imports. Bottom-up project pipeline aggregation was triangulated against top-down capacity deployment forecasts across the analysis window.
Assumptions held fixed include current tariff structures between the United States and China, existing FERC Order 2222 aggregation frameworks, and EU Green Deal carbon border adjustment implementation timelines; variables tested include lithium carbonate price trajectories, polysilicon supply concentration shifts, and grid interconnection queue clearance rates. Segmentation dimensions modeled encompass fuel source, generation capacity tier, project scale, and regional grid type. CAGRs were derived from regression analysis of historical deployment data against policy incentive schedules and grid modernization timelines, with silicon carbide semiconductor adoption curves and solid-state battery commercialization schedules as industry-specific inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed module manufacturers or unexpected FERC regulatory reversals would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging Energy Technologies
Decarbonization Market
Emerging Energy Technologies
Advanced Energy Market
Emerging Energy Technologies
Multi Energy Systems Market
Emerging Energy Technologies
Methanation Technology Market
Emerging Energy Technologies
Global Power-To-X Market
Emerging Energy Technologies
Clean Technology Market
Emerging Energy Technologies
Nanotechnology in Energy Market
Emerging Energy Technologies
Clean Coal Technologies Sales Market
Emerging Energy Technologies
Cryogenic Technology Market
Emerging Energy Technologies
Europe Clean Coal Technologies Market
Emerging Energy Technologies
United States Clean Coal Technologies Market
Emerging Energy Technologies
Global Microreactor Technology Market