
 Small Hydropower Market | 2026-2036
Small Hydropower Market Size, Share, and Industry Trends Forecast 2026-2036
Small Hydropower Market Intelligence
The European Union's Green Deal, with its emphasis on renewable energy targets, is consolidating demand for distributed power generation. This shift benefits established engineering firms like Voith Group, which leverages its expertise in turbine manufacturing for run-of-river projects. ANDRITZ competes by offering comprehensive "water-to-wire" solutions for small hydro installations across diverse geographies, including mountainous regions in Austria and Switzerland. Siemens Energy positions itself with advanced control and automation systems for these facilities.
Small hydropower refers to hydroelectric power generation facilities with a capacity typically under 10 megawatts. These systems convert the kinetic energy of flowing water into electricity without requiring large dams or reservoirs. Run-of-river installations represent the dominant configuration due to their lower environmental impact and civil works costs. Within technology segments, Kaplan and Pelton turbines are selected based on specific site conditions of water head and flow rate, influencing project economics and efficiency.
Regulatory frameworks like the US Federal Energy Regulatory Commission (FERC) licensing process for small conduits and China's Ministry of Ecology and Environment (MEE) guidelines shape project feasibility. In India, the Central Electricity Authority (CEA) sets technical standards that influence equipment choice and grid integration. Future project viability will hinge on navigating evolving water rights legislation and securing long-term power purchase agreements with local utilities or industrial users.
Market Dynamics
The decentralization of energy infrastructure is the central force defining the small hydropower market. This shift is driven by the need for reliable, off-grid power in remote communities and the integration of distributed renewable sources into national energy strategies.
Growth Catalysts
- Rural Electrification Mandates:Government programs in India, guided by the Central Electricity Authority (CEA), and across sub-Saharan Africa prioritize small hydro for electrifying remote villages, creating sustained demand for sub-1 MW systems.
- Renewable Energy Policies:The European Union's Green Deal provides financial incentives and mandates for distributed renewable generation, directly benefiting run-of-river projects that align with its environmental and energy targets.
- Turbine Technology Advances:Innovations in Kaplan and Pelton turbine designs are improving efficiency and expanding the viability of projects in low-head and variable-flow site conditions, previously considered uneconomical.
Market Restraints
- Complex Permitting:Protracted and complex regulatory approval processes, such as the Federal Energy Regulatory Commission (FERC) licensing in the United States, can significantly delay project timelines and increase development costs.
- High Upfront Capital:The substantial initial investment required for civil engineering works, site access, and electromechanical equipment poses a significant barrier, especially for smaller developers without access to large-scale financing.
- Water Rights Conflicts:Evolving legislation and competing claims for water resources among agriculture, industry, and local communities create legal uncertainty and can jeopardize the long-term viability for hydro projects.
Strategic Opportunities
- Hybrid Energy Systems:Integrating small hydropower installations with battery energy storage systems (BESS) and solar PV offers a path to providing firm, 24/7 power, creating a higher-value energy product for industrial users.
- Green Hydrogen Production:Co-locating small hydro plants with electrolyzers in remote, water-rich regions presents an opportunity to produce green hydrogen for local industrial use, creating a new offtake market.
- Underdeveloped Regions:The mountainous Andean and Himalayan regions contain significant untapped hydro potential, offering long-term growth prospects for developers capable of navigating challenging terrain and local regulatory environments.
Industry Challenges
- Grid Integration Complexity:Interconnecting decentralized small hydro plants with existing, often aging, centralized grid infrastructure presents technical challenges related to voltage stability, frequency control, and bidirectional power flow management.
- PPA Negotiation Hurdles:Securing bankable, long-term power purchase agreements (PPAs) with utilities or corporate offtakers is a critical and often difficult step, with pricing negotiations frequently stalling projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Hydropower Market |
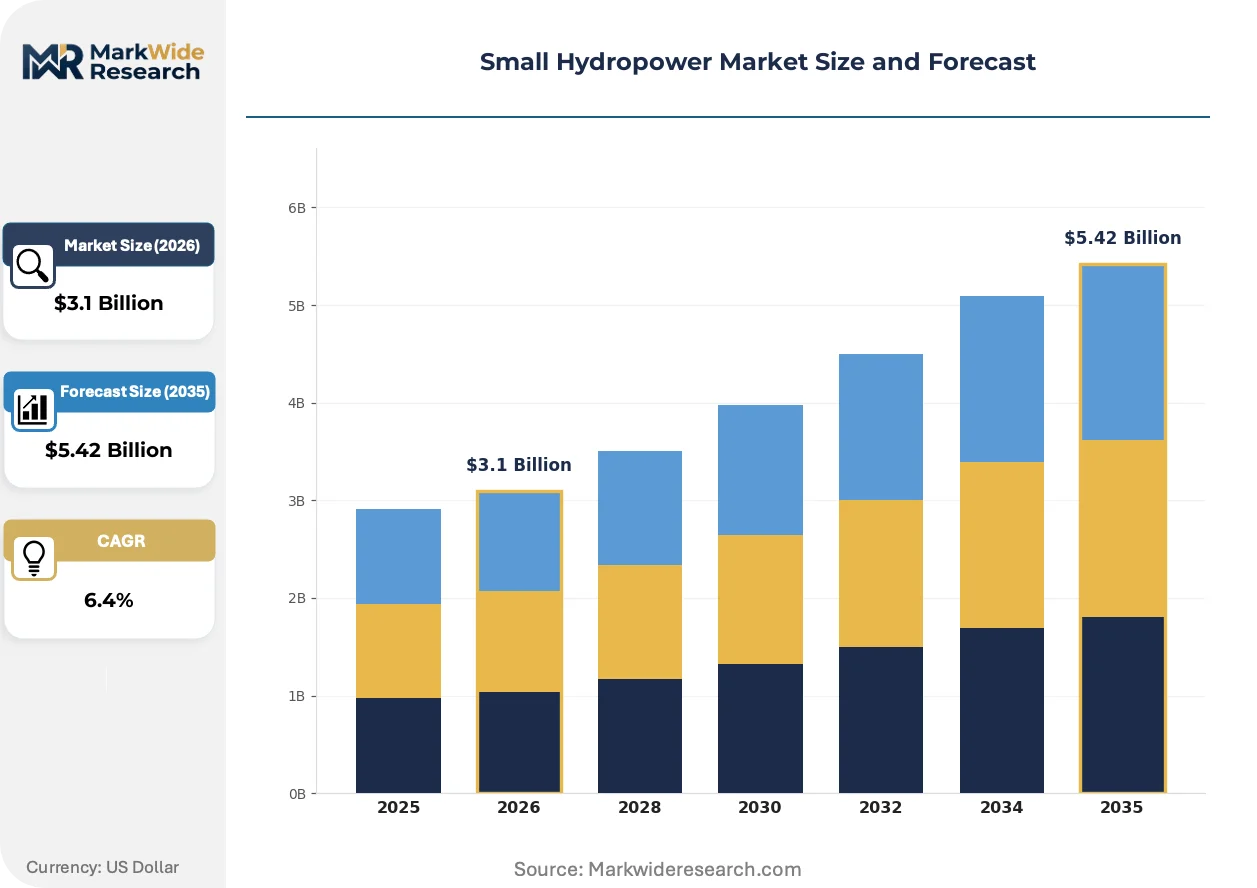
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.42 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Pelton Turbines, Francis Turbines, Kaplan Turbines, Crossflow Turbines, Turgo Turbines Application: Off-Grid Electrification, Rural Power Supply, Industrial Power, Agricultural Irrigation, Remote Community Energy Installation Site: Run-of-River, Impoundment, Canal, Pumped Storage End User: Independent Power Producers, Local Cooperatives, Manufacturing Units, Agricultural Enterprises, Microgrids |
| Companies Covered | Voith Group, ANDRITZ, GE Renewable Energy, Siemens Energy, RusHydro, Statkraft, Innergex, Gilbert Gilkes & Gordon, Flovel Energy Private Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Hydropower Market Strategic Shifts & Innovations
Digitalization and modular design principles are fundamentally changing project economics and operational efficiency. These innovations enable more precise resource assessment, faster deployment, and improved asset management throughout the lifecycle of small hydropower facilities.
Advanced automation platforms provide real-time operational monitoring and predictive maintenance analytics for electromechanical components. Project operators and asset managers are adopting these systems to maximize energy output and reduce unscheduled downtime. This digitalization is unifying disparate functions, from turbine efficiency tracking to grid interaction management, into a single, cohesive control environment.
India's Central Electricity Authority (CEA) is enforcing updated technical standards for grid connectivity of renewable energy sources, including small hydro. This mandate requires new and refurbished plants to incorporate more sophisticated grid support functions, such as frequency response. The sub-5 MW project segment is most affected, facing higher equipment costs for compliant inverters and control systems.
A clear preference is emerging for "water-to-wire" procurement, where a single contractor provides a turnkey solution encompassing all equipment from water intake to grid connection. This model replaces fragmented, multi-vendor procurement, reducing project management complexity and risk for developers. The trend is most prominent in Southeast Asia and Latin America, where developers seek to minimize interface risks.
Small Hydropower Market Segmentation
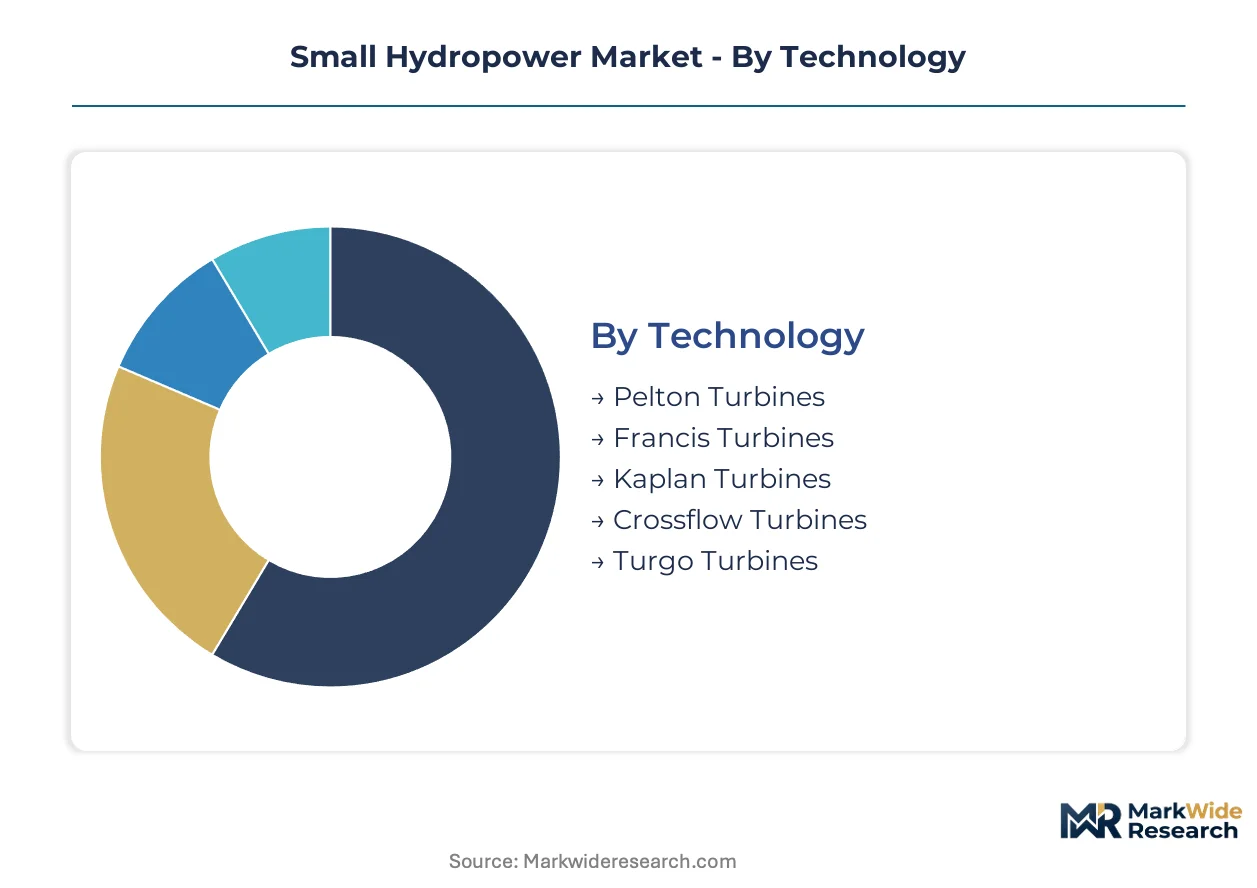
The small hydropower market segments across technology, application, installation site, and end-user categories. Understanding these distinctions is critical for developers and investors to identify viable project opportunities and align solutions with specific energy requirements in diverse geographic contexts.
Technology:
The upgrade and replacement cycle for existing small hydropower plants often dictates turbine selection, balancing efficiency gains against civil works modifications.
- Kaplan Turbines:These propeller-type reaction turbines efficiently operate across a wide range of flow conditions and low to medium water heads, making them suitable for run-of-river projects. Demand for Kaplan turbines is concentrating in Southeast Asia, driven by regional mandates for distributed renewable energy generation.
- Pelton Turbines:Impulse turbines designed for high head and low flow applications, Pelton turbines are highly efficient in mountainous regions with significant elevation drops. European developers utilize Pelton turbines extensively in the Alps for their robust performance and adaptability to variable water resources.
- Francis Turbines:Francis turbines are versatile reaction turbines, commonly employed for medium head and flow rates, representing a significant portion of installed global small hydro capacity.
- Crossflow Turbines:Simple in design and robust, crossflow turbines are suitable for small-scale, remote installations with moderate heads and fluctuating flow rates.
- Turgo Turbines:Similar to Pelton turbines but capable of handling higher flow rates, Turgo turbines offer a cost-effective solution for medium-head sites.
Volume placements concentrate in Francis Turbines; the faster expansion belongs to Kaplan Turbines.
Application:
Different application requirements shape the demand profile for small hydropower systems, influencing project scale and grid integration strategies.
- Rural Power Supply:Small hydro provides essential electricity to remote villages, particularly in India and sub-Saharan Africa, where grid extension is uneconomical. Government mandates for rural electrification significantly drive this segment, fostering demand for sub-1 MW systems.
- Off-Grid Electrification:These applications involve independent power systems serving isolated communities or industrial operations without connection to a national grid. The need for energy independence and reliability in regions like the Andean mountains supports off-grid small hydro development.
- Industrial Power:Manufacturing units and processing plants utilize small hydropower for captive power generation, reducing operational costs and ensuring energy security.
- Agricultural Irrigation:Small hydro systems can power irrigation pumps, particularly in hilly or remote agricultural zones, supporting food security initiatives.
- Remote Community Energy:This application focuses on providing sustainable energy to geographically isolated populations, often integrating with microgrid solutions.
Demand for small hydropower in Rural Power Supply is primarily driven by government programs, while Off-Grid Electrification presents significant growth prospects.
Installation Site:
The physical characteristics of the installation site fundamentally determine project feasibility and environmental impact, influencing regulatory approval processes.
- Run-of-River:These installations divert a portion of a river's flow through a turbine and return it downstream, minimizing environmental disruption without large reservoirs. Run-of-river represents the dominant configuration due to its lower environmental impact and reduced civil works costs.
- Canal:Utilizing existing irrigation or navigation canals for power generation, this segment leverages pre-existing infrastructure to reduce development timelines and costs. India's Central Electricity Authority (CEA) encourages canal-based projects to maximize resource utilization.
- Impoundment:Impoundment projects involve creating a reservoir behind a dam to store water, allowing for controlled release and power generation on demand.
- Pumped Storage:These facilities store energy by pumping water from a lower reservoir to an upper one during periods of low electricity demand and releasing it to generate power during peak demand.
The deployment of small hydropower facilities is most prevalent in Run-of-River, with evolving interest in Canal for specific use cases.
End User:
The type of end-user dictates financing structures, power purchase agreements (PPAs), and the scale of small hydropower projects.
- Local Cooperatives:These community-owned entities develop small hydro projects to provide affordable and reliable electricity to their members, particularly in rural settings. Programs in sub-Saharan Africa support local cooperatives in establishing decentralized energy systems.
- Independent Power Producers:IPPs develop, own, and operate small hydropower plants, selling electricity to utilities or directly to industrial consumers under long-term power purchase agreements. The US Federal Energy Regulatory Commission (FERC) licenses many IPP small hydro projects.
- Manufacturing Units:Industrial facilities install small hydro for self-consumption, reducing reliance on the grid and mitigating energy price volatility.
- Agricultural Enterprises:Large farms or agricultural consortia use small hydro to power operations such as irrigation, processing, or cold storage.
- Microgrids:These localized grids integrate small hydro with other renewable sources and storage, providing resilient power to specific communities or campuses.
Key decision-makers for small hydro projects include Independent Power Producers, while Local Cooperatives increasingly seek decentralized energy solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New Delhi, India, anchors significant policy initiatives for small hydropower development, particularly for rural electrification. This focus on decentralized energy access drives substantial project activity across diverse geographies. Each region presents unique drivers and regulatory landscapes shaping market expansion.
India
India's rural electrification mandates drive significant demand for sub-1 MW small hydro systems. The Central Electricity Authority (CEA) sets technical standards influencing equipment choice and grid integration. Projects in the Himalayan foothills and Northeast India benefit from abundant water resources and government support for remote community power.
China
China's dual carbon goals accelerate investment in small-scale hydro projects across its vast river systems. The Ministry of Ecology and Environment (MEE) guidelines shape project feasibility and environmental compliance. Provinces like Sichuan and Yunnan actively develop small hydro to balance energy demand with environmental sustainability.
Germany
Germany's small hydropower market benefits from the European Union's Green Deal emphasis on renewable energy targets. National incentives support distributed power generation, particularly for run-of-river projects. The Bavarian Alps and Black Forest regions see sustained investment in efficient Pelton turbine installations.
United States
United States demand for small hydropower is driven by renewable energy integration and simplified licensing for small conduits. The US Federal Energy Regulatory Commission (FERC) oversees project approvals, focusing on environmental impact. The Pacific Northwest and Appalachian Mountains offer natural conditions for numerous small-scale hydroelectric developments.
Brazil
Brazil exhibits demand for small hydropower to provide off-grid electrification and industrial power in remote areas. National energy policies prioritize distributed generation to expand energy access. The Amazon Basin and Minas Gerais state present significant untapped hydro potential for sustainable development.
Small Hydropower Market Key Industry Players
The competitive structure tilts toward established engineering firms and specialized equipment manufacturers. These players offer comprehensive solutions, from turbine manufacturing to advanced control systems. A tiered landscape emerges, with global conglomerates alongside regional specialists. Geographic expansion into underdeveloped regions and strategic partnerships for turnkey project delivery are common competitive moves.
Established European engineering firms anchor the premium segment. Voith Group, a German GmbH, represents expertise in turbine manufacturing for run-of-river projects. Austrian-based ANDRITZ AG exemplifies comprehensive "water-to-wire" solutions across diverse geographies. Siemens Energy AG, also a German company, occupies a position in advanced control and automation systems for these facilities, complementing the core equipment providers.
| Leading Market Players |
|---|
| Voith Group |
| ANDRITZ |
| GE Renewable Energy |
| Siemens Energy |
| RusHydro |
| Statkraft |
| Innergex |
| Gilbert Gilkes & Gordon |
| Flovel Energy Private Limited |
| Others |
Cost & Logistics Intelligence
Government programs in India for rural electrification directly influence project-based pricing, often prioritizing cost-effectiveness for sub-1 MW systems. This focus shapes equipment and installation costs across the market.
Pricing Analysis
Uptime and consistent energy output anchor value-based pricing for small hydropower projects, reflecting their long operational lifespans. Project-based contracts dominate, with price differentiation stemming from turbine efficiency and comprehensive "water-to-wire" solutions. Pricing softness reflects intense competition from other distributed renewable sources like solar PV, particularly for smaller systems. Rural power supply initiatives exhibit the highest price sensitivity, while Independent Power Producers prioritize long-term PPA stability.
Supply Chain Analysis
Regional distribution centers support localized project delivery, especially for smaller sub-1 MW systems, leveraging established logistics networks. Global supply for electromechanical equipment concentrates in China, Germany, and Austria, which provide specialized steel alloys, advanced control systems, and generators. Logistics chokepoints for heavy electromechanical components represent a structural risk, particularly for remote installations. Distribution runs through turnkey EPC contractors and specialized engineering firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
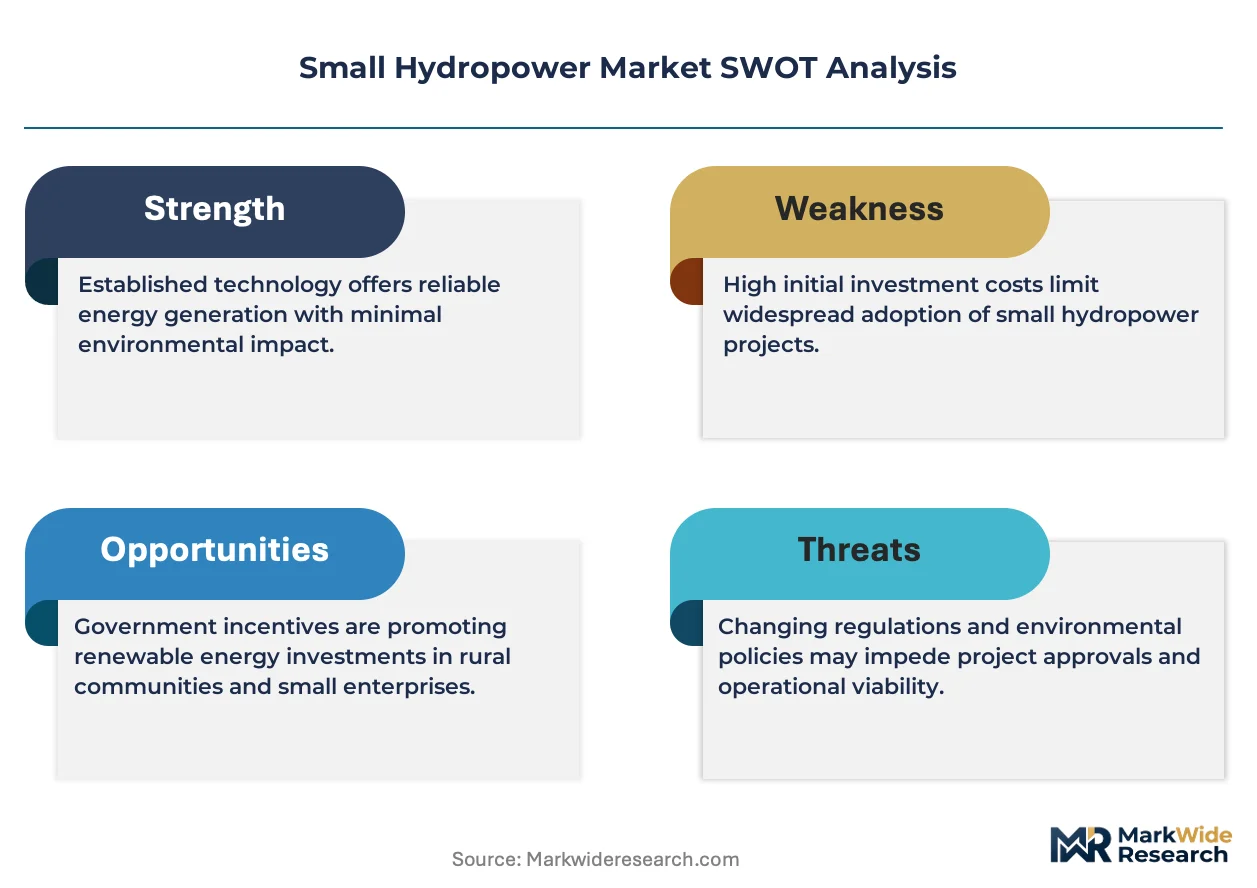
The small hydropower market presents a cost-of-compliance story, where US Federal Energy Regulatory Commission (FERC) licensing creates a barrier-to-entry moat for developers capable of navigating complex environmental and permitting requirements. This regulatory landscape favors established players.
For Market Incumbents: Anchor comprehensive "water-to-wire" solutions by integrating advanced control and automation systems to maintain market leadership. Invest in R&D for modular turbine designs to reduce civil works costs and accelerate deployment, countering grid integration complexity. Leverage existing expertise in turbine manufacturing to secure long-term power purchase agreements (PPAs) in emerging markets, reinforcing market position against new entrants.
For New Entrants and Emerging Players: India's Central Electricity Authority (CEA) technical standards open a window for new entrants focusing on compliant, grid-integrated solutions for sub-5 MW projects. Target underdeveloped regions like the Andean and Himalayan mountains with standardized, rapidly deployable small-scale hydro systems. Offer hybrid energy systems combining small hydro with battery storage to provide firm, 24/7 power, addressing reliability demands in off-grid electrification.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers with patient capital and long-term asset management capabilities. Small hydropower offers a resilient asset class over a 5-10 year horizon, essential for the global energy transition. Target specialized engineering firms or regional turbine manufacturers with strong local regulatory navigation expertise. Watch for successful long-term power purchase agreement (PPA) negotiations as a key inflection indicator for project viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand "Water-to-Wire" Turnkey Offerings | Reduces project management complexity and interface risks for developers, particularly in Southeast Asia. |
| Invest in Modular Turbine Design R&D | Lowers civil works costs and accelerates deployment for small-scale, remote installations. |
| Develop Hybrid Hydro-Storage Solutions | Provides firm, 24/7 power for industrial users, enhancing energy product value. |
| Secure Long-Term Power Purchase Agreements | Ensures project bankability and revenue stability, critical for Independent Power Producer (IPP) financing. |
| Navigate Evolving Water Rights Legislation | Mitigates legal uncertainty and secures long-term resource access for hydro project viability. |
Research Approach
Independent corroboration across project developer insights, turbine manufacturer specifications, and utility planning documents underwrites the qualitative findings. Primary interviews with engineering firms, government officials, and local cooperative leaders provided granular market perspectives. Secondary validation involved analysis of FERC filings, CEA technical standards, and IEA renewable energy statistics. Bottom-up and top-down triangulation ensured data consistency across all segments.
Rate-of-change decomposition formed the basis for projecting market expansion across the analysis window. The analytical framework modeled dimensions including technology segments, application types, installation sites, end-users, and regional policy environments. Compound Annual Growth Rates were derived from historical trends and anticipated policy impacts. Rural electrification targets and global climate goals served as critical forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for advanced battery storage integration would alter the outlook. Forecasts reflect underlying assumptions regarding regulatory stability and project financing availability, with evolving water rights legislation and grid integration challenges posing specific risk factors. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydropower Systems
Underground Hydro Power Plant Market
Hydropower Systems
Asia-Pacific Hydropower Market
Hydropower Systems
Europe Small Hydropower Market
Hydropower Systems
Wave and Tidal Energy Market
Hydropower Systems
Run of River Power Market
Hydropower Systems
United States Hydro Turbine Market
Hydropower Systems
Hydropower Generation Market
Hydropower Systems
Pumped Hydro Storage Market
Hydropower Systems
Hydroelectricity Market
Hydropower Systems
Asia-Pacific Pumped Hydro Storage Market
Hydropower Systems
Europe Hydro Turbine Market
Hydropower Systems
Hydro Turbines Market
Hydropower Systems
Offshore Hydropower Market
Hydropower Systems
South America Pumped Hydro Storage Market
Hydropower Systems
Japan Hydropower Market
Hydropower Systems
Africa Small Hydropower Market