
 Energy Security Market | 2026-2036
Energy Security Market Size, Share, and Industry Trends Forecast 2026-2036
Energy Security Market Analysis
Power generation is repositioning toward hybrid renewable-plus-storage architectures as baseload fossil fuel dependency recedes. Siemens AG leverages its turbine-to-grid software stack to anchor large-scale utility contracts across European and North American markets. Schneider Electric SE specializes in microgrid controls and distributed energy resource management, competing for critical infrastructure resilience projects. Lockheed Martin Corporation dominates defense-sector energy security, where military base microgrids and nuclear-blast-hardened power systems command premium procurement protocols.
Energy security encompasses the uninterrupted availability of energy sources at an affordable price, requiring system redundancy measured in reserve margins typically exceeding fifteen percent above peak demand. Its primary commercial purpose centers on insulating industrial operations, military installations, and healthcare facilities from supply disruptions caused by geopolitical conflict, extreme weather, or cyber intrusion. Smart grids lead technology investment as utilities replace aging SCADA infrastructure with bidirectional communication networks capable of islanding during upstream failures. Energy storage represents the fastest-growing type segment, with lithium-ion and emerging solid-state batteries capturing margin pools from frequency regulation and black-start services. Government end users sustain above-average pricing power due to classified-site requirements and sovereign resilience mandates that override standard cost-benefit thresholds.
FERC Order 2222 in the United States enables distributed energy resource aggregation, reshaping market access for behind-the-meter assets previously excluded from wholesale participation. The EU Green Deal and its embedded Critical Raw Materials Act are forcing European operators to diversify battery supply chains away from single-source mineral dependencies. NERC CIP standards enforce mandatory cybersecurity frameworks for bulk power system operators, elevating compliance spending for utilities and their technology vendors. Stakeholders must monitor how evolving export controls on power electronics and transformer core steel reconfigure equipment procurement timelines and domestic manufacturing incentives.
Market Dynamics
Hybrid renewable-plus-storage architectures are compressing procurement cycles for baseload replacement, forcing utilities to renegotiate interconnection agreements and reserve margin calculations faster than regulatory frameworks can adapt.
Growth Catalysts
- FERC Order 2222:Distributed energy resource aggregation rules unlock wholesale market access for behind-the-meter battery systems and demand response assets, expanding revenue streams for commercial and industrial microgrid operators.
- Defense-sector resilience mandates:Military installation electrification requirements under federal critical infrastructure protection protocols sustain premium procurement for island-capable generation and hardened control systems.
- Lithium-ion cost curves:Cell manufacturing scale economies and cathode chemistry improvements compress levelized storage costs, enabling four-hour duration systems to compete with peaker plants in frequency regulation and black-start services.
Market Restraints
- Transformer core steel concentration:Domestic manufacturing capacity constraints for grain-oriented electrical steel extend lead times for substation upgrades, bottlenecking grid modernization timelines.
- Cybersecurity compliance burdens:NERC CIP standards impose mandatory control system audits and incident reporting protocols that elevate operational technology spending for utilities with limited IT security bench strength.
- Interconnection queue saturation:Regional transmission organization backlogs for generator interconnection studies delay commercial operation dates for distributed solar-plus-storage projects by eighteen to thirty-six months.
Strategic Opportunities
- EU Critical Raw Materials Act:Battery supply chain diversification mandates create procurement openings for non-Chinese lithium, cobalt, and rare earth processing capacity in North American and Australian mining jurisdictions.
- Behind-the-meter aggregation platforms:Virtual power plant software stacks enable residential battery fleet participation in wholesale ancillary services, capturing margin pools previously reserved for utility-scale assets.
- Solid-state battery pilot deployments:Emerging ceramic electrolyte cell architectures promise higher energy density and thermal stability for defense and medical facility microgrids requiring extreme reliability.
Industry Challenges
- SCADA workforce scarcity:Specialized control systems engineering talent pools are thinning as veteran technicians retire faster than universities and trade programs refresh curriculum for modern distributed energy resource management platforms.
- Islanding certification complexity:UL 1741 SA and IEEE 1547-2018 compliance testing for inverter-based resources requires extended laboratory validation cycles that compress project development windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Energy Security Market |
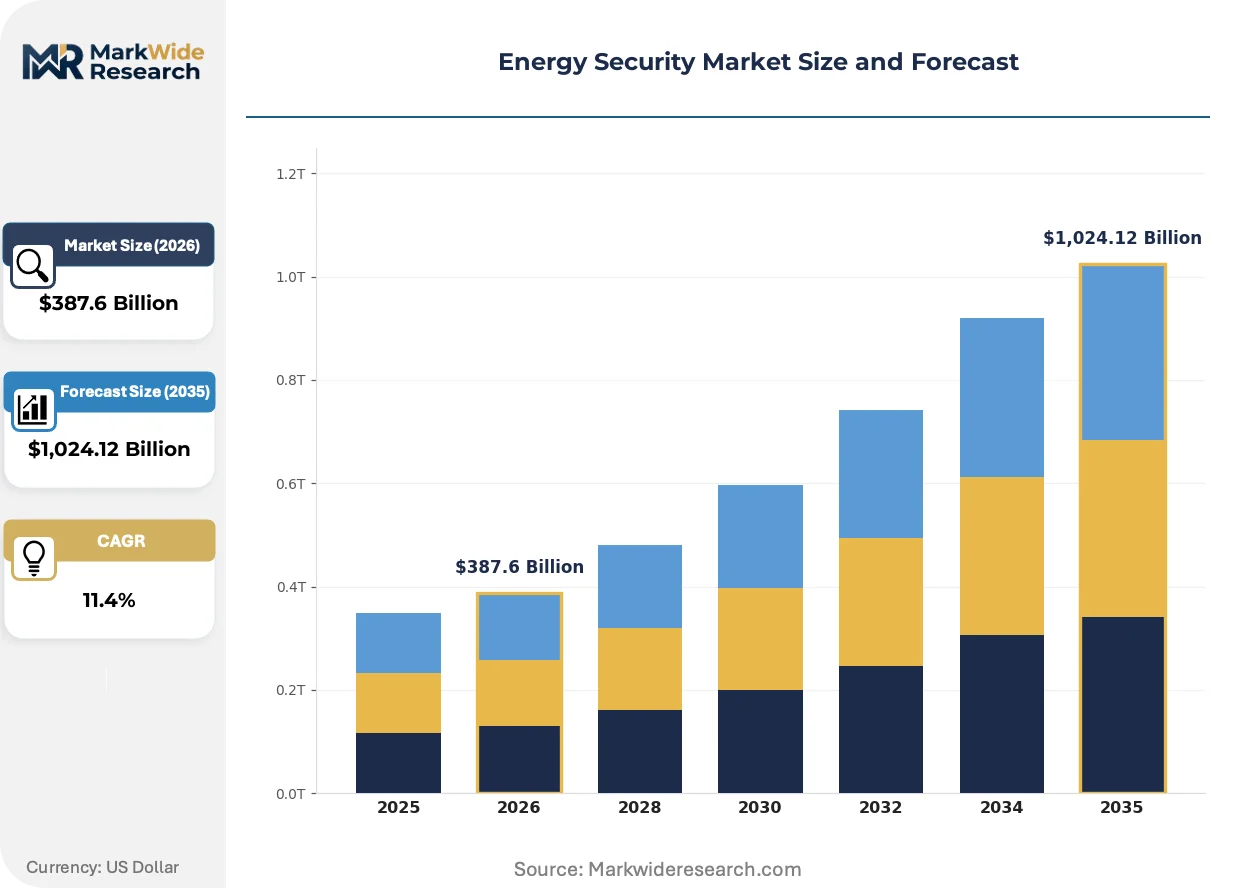
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,024.12 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Renewable Energy, Fossil Fuels, Nuclear Power, Energy Storage Application: Power Generation, Transportation, Heating, Industrial Processes End User: Utilities, Government, Commercial, Residential Technology: Smart Grids, Demand Response, Microgrid, Energy Management |
| Companies Covered | Siemens AG, Honeywell International, Inc., ABB Ltd., Thales Group S.A., BAE Systems PLC, Lockheed Martin Corporation, Schneider Electric SE, General Electric Company, Raytheon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Energy Security Market Emerging Trajectories
Digital twin platforms and predictive analytics are compressing outage response times while artificial intelligence-driven load forecasting reshapes how utilities dimension reserve margins and procurement hedges.
Microgrid control software is unifying previously siloed generation, storage, and load assets into single orchestration layers. Industrial campuses and healthcare complexes are deploying these platforms to achieve sub-cycle islanding detection. This convergence is unifying procurement specifications that previously separated power conditioning, energy management, and cybersecurity into discrete vendor relationships.
The EU Green Deal's embedded F-Gas Regulation is accelerating phase-out schedules for sulfur hexafluoride in switchgear, forcing manufacturers to commercialize fluoronitrile and vacuum interrupter alternatives. Industrial buyers in Germany and France face retrofit timelines that compress capital planning cycles. Grid-scale switchgear procurement is shifting toward dry air and clean air insulation technologies that trade footprint efficiency for regulatory compliance certainty.
Hospital and data center buyers are consolidating vendor relationships around integrated resilience service contracts that bundle equipment, fuel supply, and operational maintenance into single accountability structures. Traditional equipment-only sales channels face margin compression as these end-users demand uptime guarantees and cyber insurance riders. This consolidation is most visible in United States metropolitan markets where critical facility density supports dedicated microgrid-as-a-service providers.
Energy Security Market Segmentation
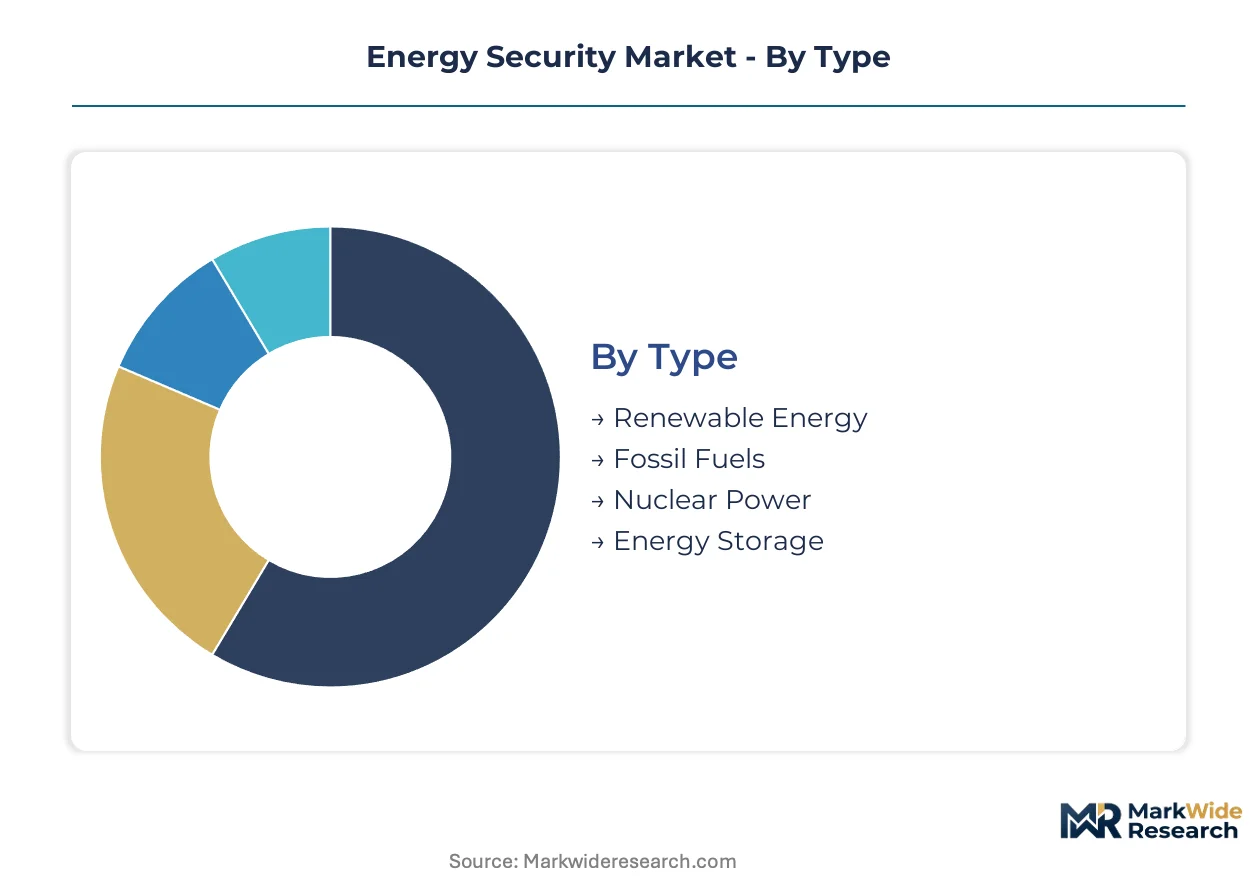
Energy security procurement patterns diverge sharply across technology types, end-use applications, and operational scales. Each segment carries distinct upgrade cycles, regulatory exposure, and margin structures that reshape vendor positioning and capital allocation priorities.
Type:
Replacement cycles for generation assets are compressing as hybrid architectures displace single-source dependencies, forcing utilities to synchronize retirement schedules with storage integration timelines.
- Energy Storage:Lithium-ion and emerging solid-state battery systems provide frequency regulation, black-start capability, and grid-forming inverters for islanding operations. Demand concentrates in United States military installations and German industrial clusters where four-hour duration systems compete directly with gas peakers.
- Renewable Energy:Solar photovoltaic and onshore wind assets with integrated inverters and forecasting software anchor distributed generation portfolios. Procurement accelerates in California and Texas where interconnection reform and renewable portfolio standards mandate accelerated fossil fuel displacement.
- Nuclear Power:Small modular reactor designs and life-extension protocols for existing pressurized water units sustain baseload resilience.
- Fossil Fuels:Natural gas combined-cycle and reciprocating engine sets retain strategic reserve status for black-start and extreme weather recovery.
Energy Storage sits at the top of the volume ranking, with Renewable Energy climbing the fastest.
Application:
Margin structures vary by application based on uptime requirements, fuel flexibility needs, and regulatory scrutiny intensity.
- Power Generation:Centralized and distributed generation assets with cyber-hardened control systems serve grid-forming and grid-following functions. United States utilities and European transmission system operators drive procurement under NERC CIP and EU Cybersecurity Act mandates.
- Industrial Processes:Continuous manufacturing operations require uninterruptible power supplies and on-site generation with sub-cycle transfer switches. Demand clusters in chemical processing corridors along the United States Gulf Coast and Rotterdam-Antwerp industrial zones.
- Transportation:Electrification of fleet operations and charging infrastructure resilience commands dedicated microgrids.
- Heating:District heating networks and industrial thermal processes integrate combined heat and power systems.
Power Generation captures the largest revenue pool, while Industrial Processes expand most quickly as manufacturing reshoring accelerates.
End User:
Customer type determines procurement protocol sophistication, contract structure preferences, and cybersecurity certification requirements.
- Government:Military bases, classified facilities, and critical infrastructure sites mandate island-capable generation with electromagnetic pulse hardening and sovereign supply chain verification. United States Department of Defense procurement sustains premium pricing for defense-grade resilience.
- Utilities:Investor-owned and public power entities deploy grid-scale storage, smart grid infrastructure, and microgrid controls under state renewable mandates and FERC Order 2222 aggregation rules.
- Commercial:Data centers, hospitals, and financial services operations seek integrated resilience-as-a-service contracts with uptime guarantees.
- Residential:Behind-the-meter battery systems and rooftop solar with islanding capability serve outage-prone regions.
Government commands the highest unit economics, with Commercial end users gaining share fastest through service-based procurement models.
Technology:
Technology maturity curves and interoperability standards shape deployment velocity and vendor consolidation patterns.
- Smart Grids:Bidirectional communication networks with advanced metering infrastructure and distribution automation replace aging SCADA systems. United States rural electric cooperatives and French distribution system operators lead deployment under grid modernization mandates.
- Microgrid:Controllers and energy management systems unify generation, storage, and load assets into single orchestration layers with sub-cycle islanding detection. Demand concentrates in United States healthcare complexes and Japanese industrial campuses seeking business continuity assurance.
- Energy Management:Software platforms for predictive analytics, demand forecasting, and automated dispatch optimize asset utilization.
- Demand Response:Aggregated load curtailment and flexible demand resources participate in wholesale ancillary service markets.
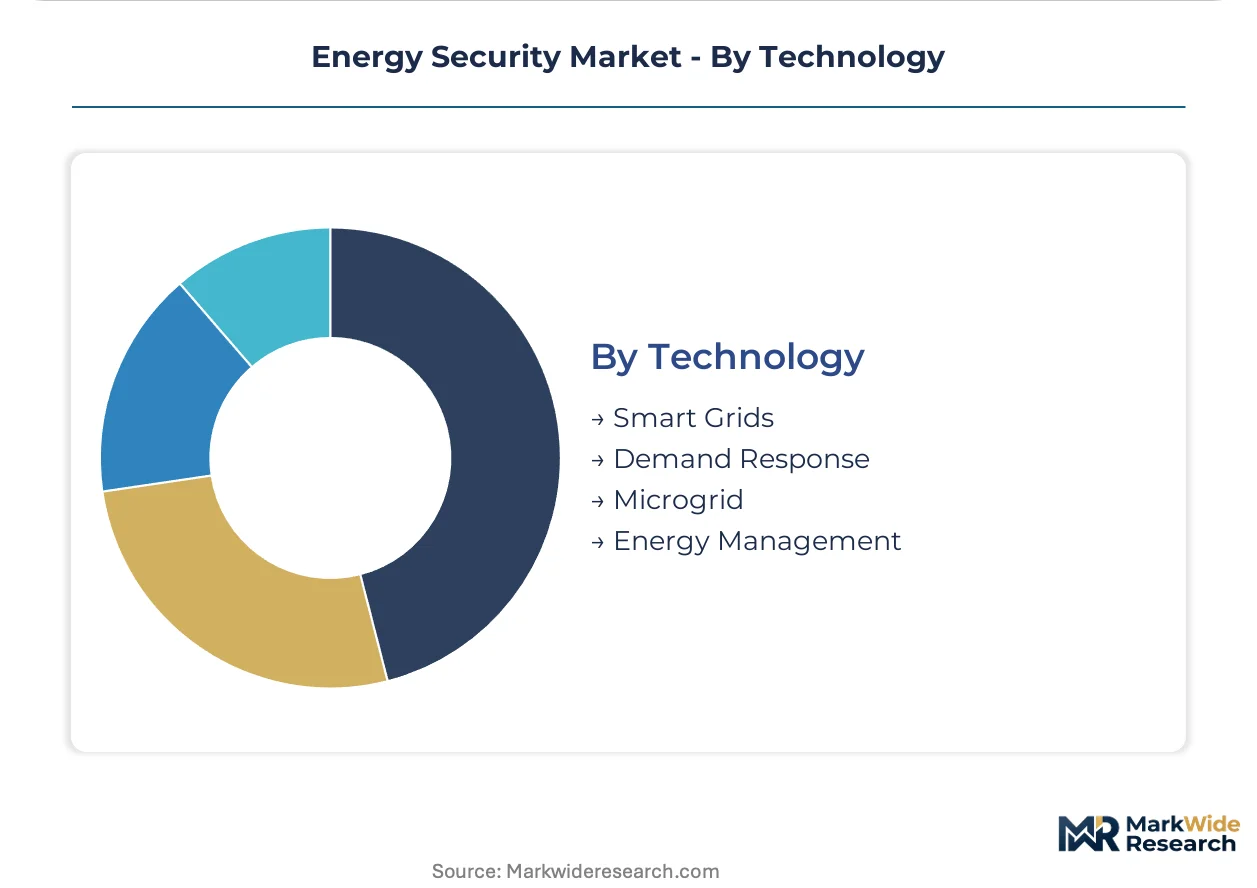
Smart Grids dominate installed base, with Microgrid technology showing the steepest expansion trajectory as control software unifies previously siloed assets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States military installations and data center clusters along the Virginia-Loudoun corridor are accelerating microgrid procurement under federal resilience mandates and state-level renewable portfolio standards.
United States
Defense-sector electrification requirements and FERC Order 2222 aggregation rules are expanding wholesale market access for behind-the-meter battery systems. The Department of Defense sustains premium procurement for island-capable generation at classified facilities. Texas and California utilities lead distributed solar-plus-storage deployment under interconnection reform pressures.
Germany
Industrial corridor demand for uninterruptible power supplies is intensifying along the Rhine-Ruhr and Bavarian manufacturing zones. The EU Green Deal and embedded F-Gas Regulation are forcing switchgear retrofit timelines toward fluoronitrile alternatives. Hamburg and Frankfurt data center operators are consolidating vendor relationships around integrated resilience service contracts.
China
Dual carbon goals and grid modernization investments are compressing procurement cycles for hybrid renewable-plus-storage architectures. The national energy regulator enforces mandatory cybersecurity frameworks for bulk power system operators. Yangtze River Delta industrial campuses are deploying microgrid control software with sub-cycle islanding detection.
Japan
Business continuity assurance requirements are driving microgrid deployment at automotive and electronics manufacturing sites. METI mandates for distributed energy resource management are reshaping utility procurement specifications. Kansai region industrial clusters are unifying generation, storage, and load assets into single orchestration layers.
United Kingdom
Critical infrastructure protection protocols are elevating compliance spending for utilities with limited IT security bench strength. The national cybersecurity center enforces mandatory control system audits for transmission system operators. London financial services operations are seeking uptime guarantees with cyber insurance riders from microgrid-as-a-service providers.
Energy Security Market Vendor Landscape
Strategic partnerships dominate the current landscape as vendors bundle hardware, software, and service components into single accountability structures. The vendor base clusters around three archetypes: diversified industrial conglomerates with turbine-to-grid software stacks, specialized microgrid control firms, and defense-grade resilience contractors. Consolidation pressures are intensifying as end-users demand integrated service contracts rather than equipment-only procurement.
Within the diversified industrial tier, Siemens AG and General Electric Company represent the scale-driven end of the competitive spectrum, anchoring large-scale utility contracts across European and North American markets. Schneider Electric SE occupies a distinct position among specialized control system providers, competing for critical infrastructure resilience projects with distributed energy resource management platforms. Lockheed Martin Corporation exemplifies the defense-sector archetype, where electromagnetic pulse hardening and sovereign supply chain verification command premium procurement protocols.
| Leading Market Players |
|---|
| Siemens AG |
| Honeywell International, Inc. |
| ABB Ltd. |
| Thales Group S.A. |
| BAE Systems PLC |
| Lockheed Martin Corporation |
| Schneider Electric SE |
| General Electric Company |
| Raytheon |
| Others |
Supply Flow & Price Mechanics
Defense-contractor-rolled-up specialists anchor premium pricing tiers through electromagnetic pulse hardening certifications and sovereign supply chain verification protocols that utilities cannot replicate without federal security clearance.
Pricing Analysis
Distributor margins for microgrid control systems compress as direct-to-utility procurement channels expand under FERC Order 2222 aggregation mandates. Project-based pricing dominates utility-scale deployments, while subscription SaaS tiers capture recurring revenue from energy management software. Price differentiation stems from cybersecurity certification grade and after-sales service bundling. Cost compression in lithium-ion storage systems is intensifying because cell manufacturing scale economies erode hardware margins. Commercial data center operators exhibit the highest price sensitivity, whereas Department of Defense installations accept premium pricing for defense-grade resilience specifications.
Supply Chain Analysis
Grain-oriented electrical steel supply rests on Japanese and South Korean specialty metal producers, with domestic North American capacity constraints extending transformer lead times. Lithium carbonate and cobalt sulfate feed from Chilean and Australian mining jurisdictions into Chinese cathode processing facilities. Single-source vulnerability concentrates in rare earth magnet supply for wind turbine generators. Distribution runs through engineering-procurement-construction contractors that bundle equipment, installation, and commissioning services for utility clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FERC Order 2222 aggregation rules continuously expand addressable demand for distributed energy resource participation in wholesale markets.
For Market Incumbents: Lock in long-term service contracts with critical infrastructure operators before microgrid-as-a-service providers consolidate vendor relationships. Deepen backward integration into solid-state battery pilot production to defend against emerging ceramic electrolyte specialists. Capture NERC CIP compliance spending elevation as a recurring revenue stream through managed cybersecurity services. For New Entrants and Emerging Players: Cloud-based virtual power plant platforms offer the lowest customer acquisition cost route into residential battery aggregation markets. White-space concentrates in behind-the-meter fleet orchestration for United States rural electric cooperatives lacking internal IT security bench strength. Pursue partnership-first go-to-market positioning with established inverter manufacturers to bypass UL 1741 SA certification barriers. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized microgrid control software firms lacking utility-scale project track records. Long-term viability hinges on regulatory durability rather than technology differentiation alone. Target acquisition archetypes include distributed energy resource management platforms with FERC-compliant aggregation stacks. Watch solid-state battery defense pilot deployments as the inflection signal for next-generation storage valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Microgrid Control Software Acquisition | Consolidates generation, storage, and load orchestration into single vendor accountability for hospital complexes. |
| Power Purchase Agreement Expansion | Locks in renewable-plus-storage offtake under FERC Order 2222 aggregation rules for commercial and industrial microgrids. |
| Backward Integration into Battery Cell Production | Captures margin pools from frequency regulation services as lithium-ion cost curves compress hardware margins. |
| Cybersecurity Certification Investment | Enables NERC CIP-compliant bidding for United States bulk power system operator contracts. |
| Defense-Grade Resilience Partnership | Accesses electromagnetic pulse hardening protocols and classified-site procurement channels through Lockheed Martin tiering. |
Methodological Framework
Direct dialogue with utility planning officers, independent power producer project developers, EPC contractors, and grid operators grounded demand-side assumptions in procurement pipeline visibility. Secondary validation drew from FERC filings, EIA project databases, IEA grid modernization reports, and NERC CIP compliance expenditure disclosures. Bottom-up project-level capacity additions were triangulated against top-down regulatory mandate trajectories to anchor segmentation splits.
Segmented outputs across generation capacity tier, fuel source architecture, project scale classification, and regional grid type fed into the analytical framework. CAGRs were derived from regression against interconnection queue velocity and storage cost curve trajectories. Forecast inputs incorporated FERC Order 2222 implementation pacing and EU Critical Raw Materials Act supply chain diversification timelines.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery commercialization would alter the outlook for lithium-ion duration market share. Forecasts reflect documented assumptions about regulatory durability and mineral supply chain reconfiguration. A small set of triggers—export control expansion on power electronics, transformer core steel tariff escalation, and SCADA workforce availability—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management
Smart Power Management Market
Energy Management
Energy Management Market
Energy Management
APAC Energy Management Systems (EMS) Market
Energy Management
Heat Meter Market
Energy Management
Middle-East and Africa Demand Response Management Systems Market
Energy Management
Germany Demand Response Management Systems Market
Energy Management
Residential Demand Response Management Systems Market
Energy Management
Australia Energy-As-A-Service Market
Energy Management
Distributed Energy Resource Management System (DERMS) Market
Energy Management
Global Utility Asset Management Market
Energy Management
Connected Energy Market
Energy Management
Demand Response Management System Market
Energy Management
Brazil Energy Sector Market
Energy Management
Testing, Inspection, and Certification (TIC) in the Energy and Power Market
Energy Management
APAC Building Energy Management Systems Market
Energy Management
Global Energy Consumption Market