
 Hydropower Generation Market | 2026-2036
Hydropower Generation Market Size, Share, and Industry Trends Forecast 2026-2036
Hydropower Generation Market Analysis
Utility procurement is reorganizing around industrial offtake agreements as energy-intensive manufacturers seek direct power purchase contracts with hydropower operators. Voith Hydro leverages its turbine manufacturing scale to dominate European refurbishment cycles, while China Three Gorges Corporation anchors multi-gigawatt development corridors across the Yangtze basin. Andritz Hydro specializes in digital governor retrofits that extend asset life for aging North American infrastructure.
Hydropower generation harnesses gravitational energy from flowing or stored water to drive turbine-generator sets, typically operating at head pressures from 2 meters to over 2,000 meters depending on site topology. The technology converts mechanical rotation into grid-synchronous alternating current with round-trip efficiencies exceeding 80% in modern installations, serving as dispatchable baseload and frequency regulation for interconnected power systems. Reservoir and pumped storage technologies command the largest capital deployment pools due to their multi-hour storage duration and grid stabilization value, while run-of-river installations occupy faster-permitting niches in markets with strong environmental review timelines. Small-scale and mini capacity segments attract distributed energy investment where transmission extension costs outweigh centralized development economics.
The International Electrotechnical Commission sets turbine performance and safety standards that shape equipment interoperability across borders, while the EU F-Gas Regulation restricts fluorinated greenhouse gas use in generator cooling systems and pushes OEMs toward alternative insulating mediums. China's MIIT enforces domestic content thresholds for turbine assembly that condition market access for foreign suppliers bidding on state-backed projects. Stakeholders must monitor how evolving grid codes and carbon border adjustments reshape the competitiveness of long-distance hydropower exports against locally sited alternatives.
Market Dynamics
Industrial offtake agreements are restructuring utility procurement as energy-intensive manufacturers bypass traditional grid intermediaries to secure direct baseload power from hydropower operators. This bilateral contracting shift concentrates credit risk with fewer counterparties while accelerating reservoir and pumped storage development timelines.
Growth Catalysts
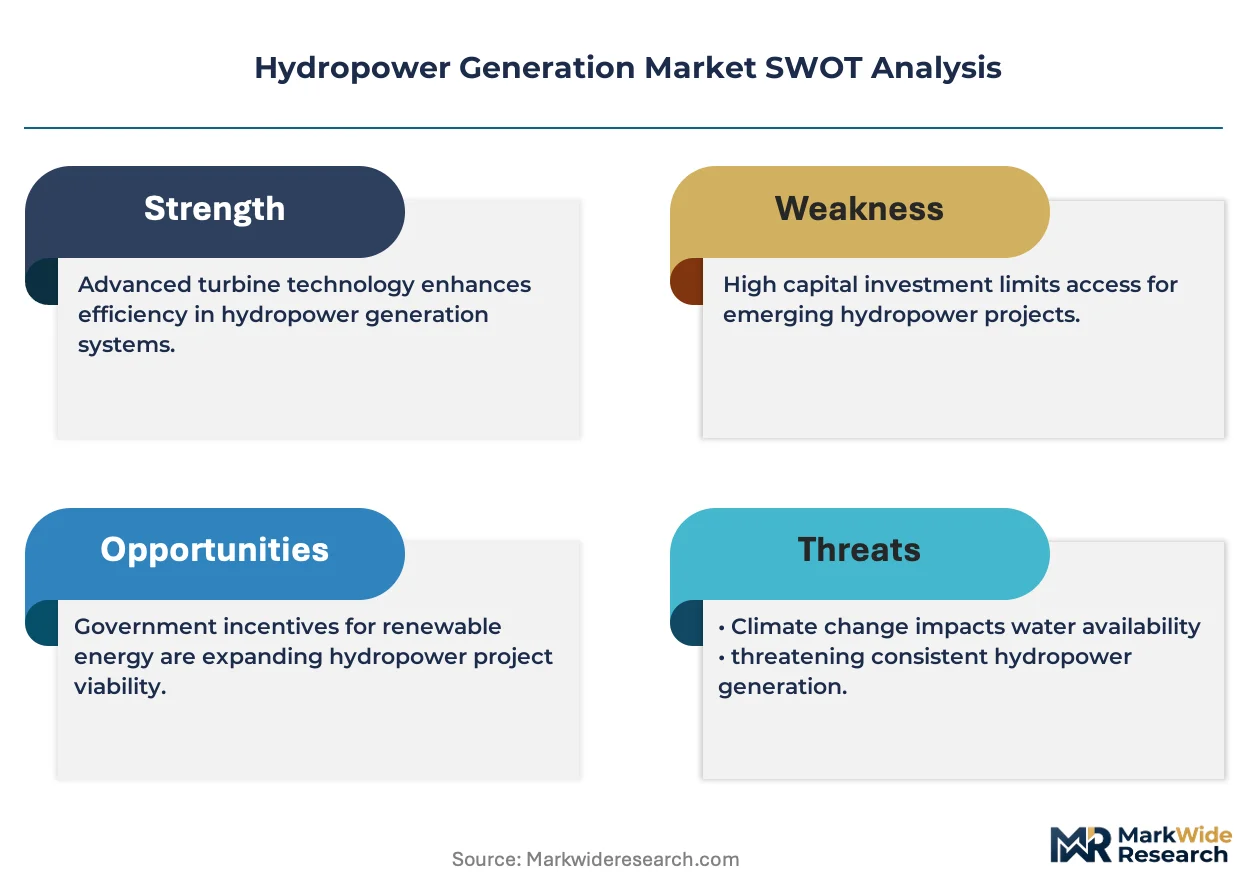
- EU Green Deal Taxonomy Alignment:Reservoir upgrades and pumped storage retrofits now qualify as sustainable investments under EU taxonomy rules, redirecting institutional capital toward qualifying assets.
- Southeast Asian Captive Installations:Energy-intensive manufacturing clusters across Vietnam, Indonesia, and Thailand are building dedicated run-of-river facilities to isolate operations from grid volatility.
- Yangtze Basin Development Corridors:China's MIIT domestic content thresholds for turbine assembly are conditioning state-backed procurement toward integrated multi-gigawatt cascade projects.
Market Restraints
- Extended Environmental Review Timelines:Reservoir projects in OECD markets face decade-plus permitting cycles under evolving aquatic habitat regulations, compressing developer IRRs below hurdle rates.
- Generator Cooling System Retrofit Costs:The EU F-Gas Regulation mandates fluorinated greenhouse gas phaseout, forcing OEMs toward alternative insulating mediums with unproven field durability.
- Silicon Steel Supply Concentration:Electrical steel laminations for turbine-generator cores concentrate among East Asian metallurgical suppliers, exposing project timelines to export quota volatility.
Strategic Opportunities
- Distributed Mini-Hydro Deployment:Sub-10 MW installations in mountainous Balkan territories and Carpathian watersheds exploit transmission extension cost differentials against centralized alternatives.
- Digital Governor Convergence:Integration of AI-driven flow optimization with legacy mechanical governors enables 15-20% efficiency gains at aging North American infrastructure without full replacement.
- Carbon Border Adjustment Positioning:Norway's reservoir operators are structuring long-term export contracts to aluminum and fertilizer producers seeking embedded emissions certification for EU market access.
Industry Challenges
- Grid Code Harmonization Complexity:Synchronous machine inertia requirements vary across interconnected power systems, forcing turbine OEMs to maintain multiple governor firmware configurations.
- Specialized Welding Certification Bottlenecks:Penstock fabrication for high-head installations requires ASME Section IX-qualified pressure vessel welders with limited availability in emerging market construction pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydropower Generation Market |
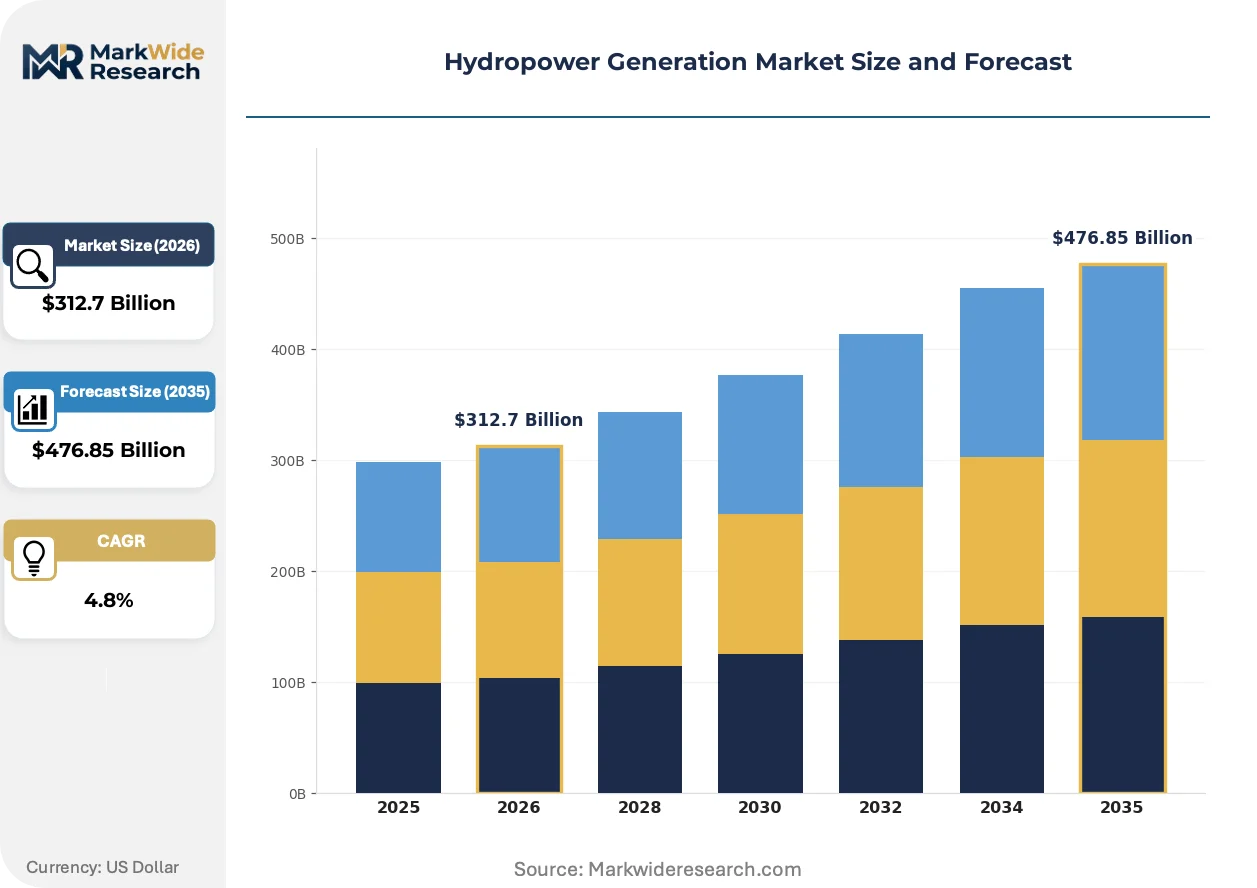
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $476.85 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology Type: Run-of-River, Reservoir, Pumped Storage, Mixed Technology Installation Type: Onshore, Offshore, Small-Scale, Large-Scale End User: Utilities, Independent Power Producers, Government, Industrial Clients Capacity: Micro, Mini, Small, Large |
| Companies Covered | GE Vernova, Siemens Energy AG, Voith Hydro, Andritz Hydro, China Three Gorges Corporation, Duke Energy Corporation, NextEra Energy Resources, Hydro-Quebec, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydropower Generation Market Emerging Trajectories
Additive manufacturing is penetrating turbine component supply chains as powder-bed fusion techniques mature for hydrofoil geometries previously machined from forged billets. This metallurgical shift reduces lead times for replacement runners while enabling topology-optimized cavitation resistance.
Variable-speed doubly-fed induction generator technology is decomposing the traditional fixed-speed turbine-generator marriage that dominated twentieth-century hydropower architecture. European refurbishment specialists are retrofitting aging Francis and Kaplan units with full-converter interfaces, allowing independent optimization of turbine hydraulics and grid frequency response. This flexibility premium commands 12-18% capital cost premiums that Nordic utilities recover through enhanced ancillary service revenue streams.
The EU F-Gas Regulation is accelerating fluorinated gas phaseout timelines for generator cooling and switchgear insulation, compressing OEM R&D cycles toward SF6-free alternatives. Siemens Energy and Hitachi have accelerated dry-air and vacuum interrupter deployments for substation integration with new hydropower interconnects. German TSOs are now mandating F-gas-free specifications for grid connection agreements, extending compliance burdens from equipment supply into project development finance.
Power purchase agreement structures are fragmenting traditional utility offtake monopolies as corporate buyers with 24/7 clean energy commitments negotiate synthetic baseload products combining reservoir output with hourly-matched certificates. Aluminum smelters and data center operators in Nordic and Alpine markets are contracting directly with reservoir owners for shaped delivery profiles that isolate operations from day-ahead price spikes. This bilateral contracting shift concentrates counterparty diligence burdens on developers while compressing traditional utility intermediation margins.
Hydropower Generation Market Segmentation
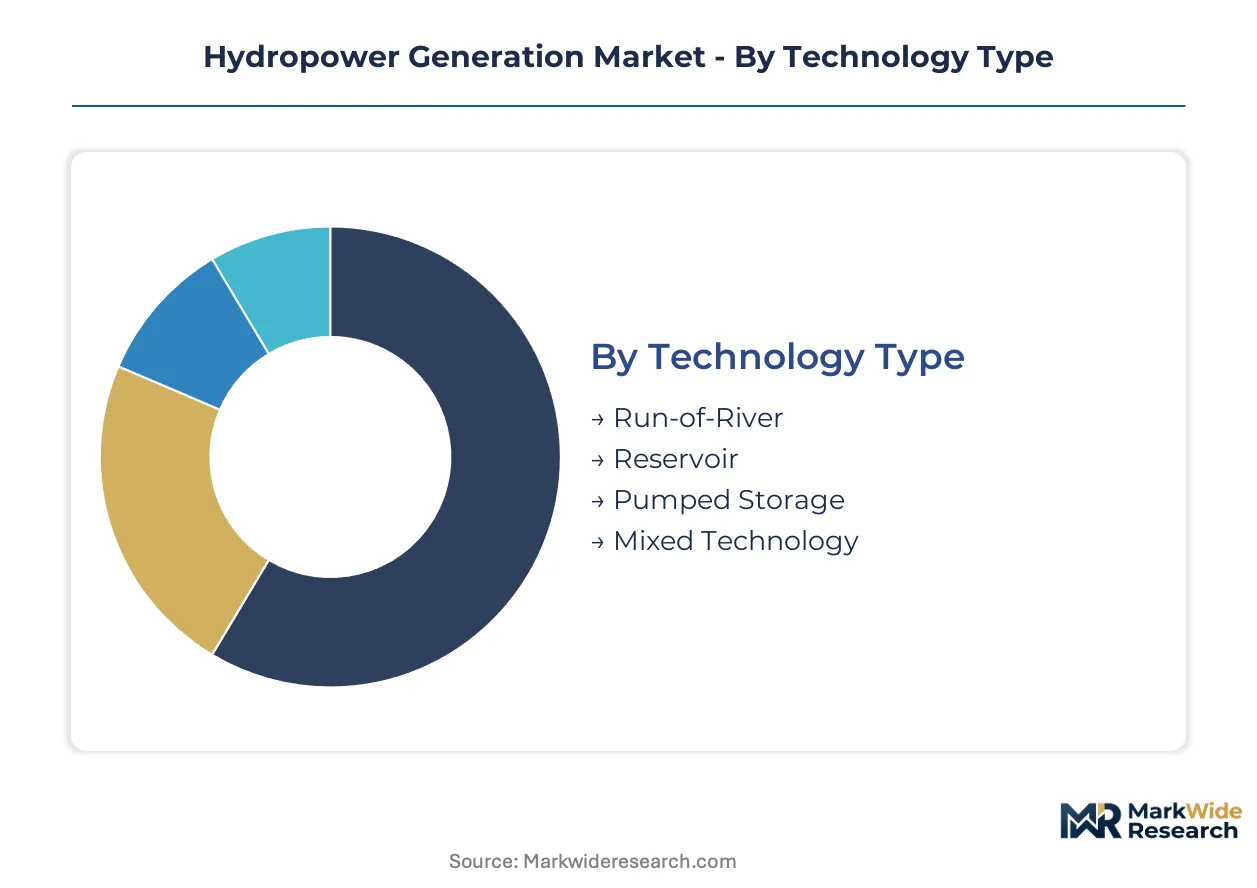
Segmentation in hydropower generation reveals how capital deployment, permitting complexity, and offtake contracting vary across technical configurations. Each dimension shapes project economics differently—reservoir scale drives infrastructure intensity while end-user structure determines revenue stability and counterparty risk.
Technology Type:
Run-of-river installations cluster in domestic supply chains serving localized manufacturing bases, whereas reservoir and pumped storage technologies attract cross-border capital flows from institutional investors seeking grid-scale assets.
- Run-of-River:These facilities divert river flow through penstocks without significant impoundment, operating at head pressures typically below 50 meters. Demand concentrates in Southeast Asian manufacturing corridors where Vietnam, Indonesia, and Thailand deploy captive installations to isolate energy-intensive operations from grid volatility. Extended dry seasons constrain capacity factors and complicate debt structuring.
- Reservoir:Large-scale impoundment creates multi-gigawatt storage buffers with seasonal regulation capability. China anchors global deployment through Yangtze basin cascade development, while Norway structures long-term export contracts to aluminum and fertilizer producers seeking EU carbon border compliance. Aquatic habitat regulations in OECD markets compress developer returns below hurdle rates.
- Pumped Storage:Reversible turbine-generator sets enable grid-scale arbitrage between peak and off-peak pricing. Alpine utilities recover capital premiums through ancillary service revenue streams.
- Mixed Technology:Hybrid configurations integrate run-of-river baseflow with small reservoir peaking capacity. Brazilian developers leverage this architecture to balance environmental review timelines with dispatch flexibility.
Reservoir technology commands the established base. The steepest expansion runs through pumped storage.
Installation Type:
Cost tier differentiation separates centralized billion-dollar reservoirs from distributed sub-10 MW installations where transmission extension economics drive site selection.
- Onshore:Conventional land-based civil works dominate capital deployment, with penstock routing and powerhouse excavation representing 40-60% of project cost. China, Brazil, and Norway concentrate greenfield development leveraging distinct river basin geographies.
- Offshore:Tidal barrage and floating turbine prototypes exploit marine current energy without land acquisition constraints. Early-stage deployment clusters in French and UK coastal zones where tidal range exceeds 8 meters.
- Small-Scale:Sub-10 MW installations in mountainous Balkan territories and Carpathian watersheds exploit transmission extension cost differentials against centralized alternatives.
- Large-Scale:Multi-gigawatt cascades require decade-long construction timelines and sovereign credit backing. China's MIIT domestic content thresholds condition state-backed procurement toward integrated development corridors.
Onshore installations retain the dominant share. Small-scale deployment is climbing the fastest.
End User:
Customer type fragmentation is accelerating as bilateral contracting displaces traditional utility intermediation, concentrating credit risk with fewer offtake counterparties.
- Utilities:Vertically integrated grid operators procure reservoir capacity for baseload and frequency regulation services. Procurement is reorganizing around industrial offtake agreements as manufacturers seek direct power purchase contracts.
- Independent Power Producers:Non-utility developers finance merchant and contracted assets, bearing construction risk and wholesale price exposure. Nordic IPPs capture enhanced ancillary service premiums through variable-speed retrofits.
- Government:State-owned entities anchor multi-gigawatt development in strategic river basins. Brazil's federal power utility Eletrobras structures concession auctions with local content requirements.
- Industrial Clients:Energy-intensive manufacturers bypass traditional grid intermediaries to secure direct baseload power. Aluminum smelters and data center operators in Nordic and Alpine markets contract for shaped delivery profiles isolating operations from day-ahead price spikes.
Utilities command the established base. Industrial clients are gaining share fastest.
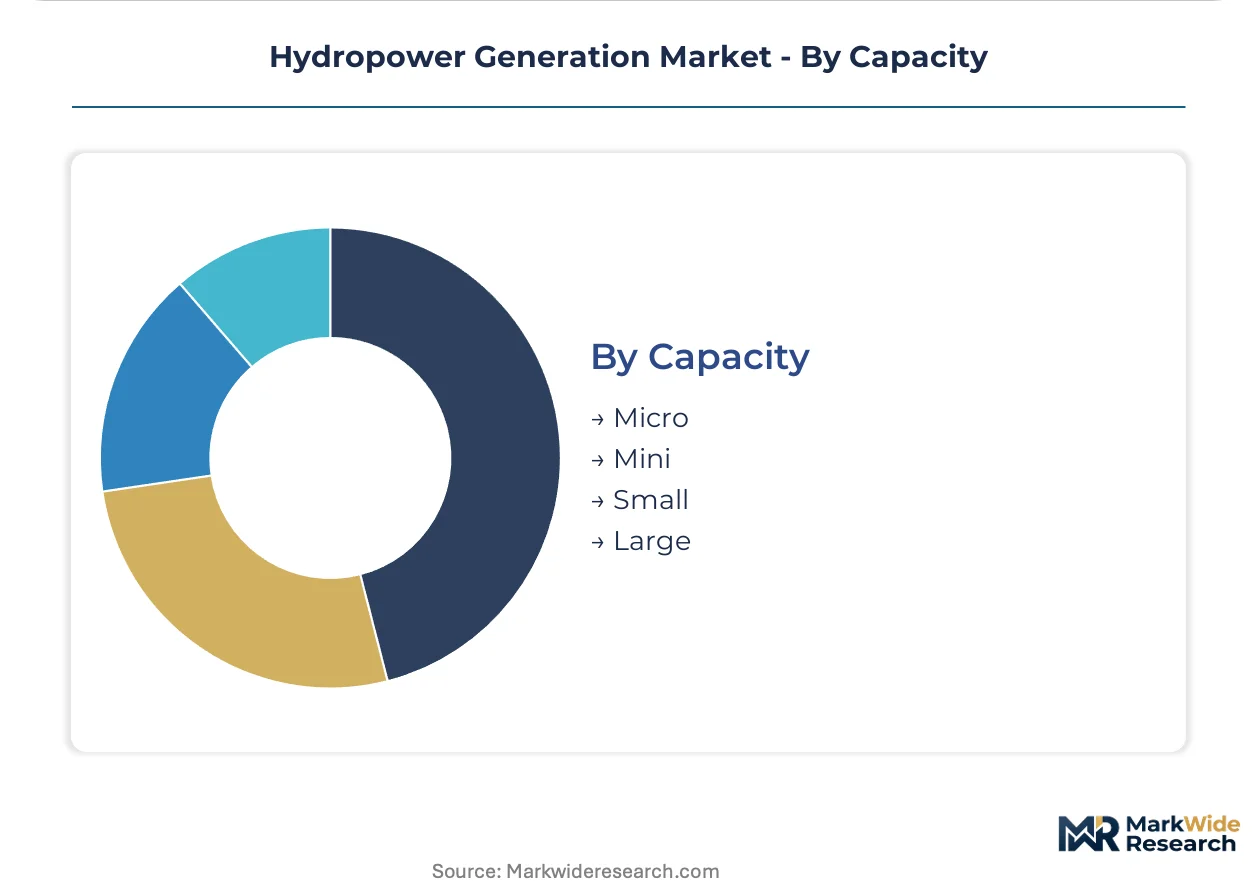
Capacity:
Maturity gradients separate century-old large hydro infrastructure from emerging micro and mini segments where distributed energy investment responds to last-mile electrification gaps.
- Micro:Sub-100 kW installations serve isolated rural loads without grid interconnection. Himalayan communities in Nepal and Bhutan deploy run-of-river micro units where transmission extension costs exceed generation asset value.
- Mini:100 kW to 1 MW capacity bridges individual facility supply and small distribution network injection. Indonesian palm oil processors deploy captive mini-hydro to stabilize operations across archipelago locations.
- Small:1-10 MW facilities qualify for expedited permitting in many jurisdictions while achieving economies of scale in electromechanical equipment procurement. Romanian Carpathian development exploits this threshold to bypass decade-plus environmental reviews faced by larger impoundments.
- Large:Exceeding 10 MW, these installations dominate global generation volume and capital deployment pools. China Three Gorges Corporation anchors multi-gigawatt cascade corridors across the Yangtze basin with state-backed financing.
Large capacity commands the established base. Mini capacity shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment fabrication and turbine assembly concentrate heavily in China, Germany, and Austria, with civil engineering contractors and electromechanical suppliers clustering near major river basin developments. State-backed procurement programs and domestic content mandates in these jurisdictions shape competitive access for foreign OEMs.
China
Yangtze basin cascade developments anchor multi-gigawatt capacity additions through state-backed financing corridors. MIIT domestic content thresholds condition turbine assembly procurement toward integrated projects with local manufacturing requirements. Sichuan and Yunnan provinces host concentrated electromechanical supply chains serving upstream dam construction.
Brazil
Federal concession auctions through Eletrobras structure reservoir development with local content requirements for electromechanical packages. ANEEL regulatory frameworks govern grid interconnection standards for Amazon basin and Paraná river projects. São Paulo and Minas Gerais industrial clusters absorb captive hydropower output for metals processing and manufacturing.
Norway
Reservoir operators structure long-term export contracts to aluminum and fertilizer producers seeking embedded emissions certification for EU carbon border compliance. NVE licensing frameworks govern watercourse concessions with environmental flow requirements. Hardanger and Sognefjord regions concentrate pumped storage development serving Nordic grid balancing.
United States
FERC licensing timelines for reservoir projects extend across decade-plus permitting cycles under evolving aquatic habitat regulations. Independent power producers and utilities deploy digital governor retrofits at aging Bureau of Reclamation and Corps of Engineers infrastructure. Pacific Northwest and Tennessee Valley Authority regions concentrate run-of-river refurbishment activity.
Germany
Alpine pumped storage operators recover capital premiums through ancillary service revenue streams under TSO frequency regulation contracts. EU F-Gas Regulation mandates accelerate SF6-free switchgear adoption for grid interconnection agreements. Bavarian and Black Forest watersheds host concentrated small-scale and mini-hydro distributed deployment.
Hydropower Generation Market Vendor Landscape
Concentration sits with integrated electromechanical OEMs and state-backed utility developers that control turbine manufacturing scale and multi-gigawatt project pipelines. The competitive structure tiers across full-service turbine suppliers, digital retrofit specialists, and sovereign development corporations. Strategic moves center on digital governor convergence for aging infrastructure and bilateral offtake contracting that displaces traditional utility intermediation.
Among European turbine fabricators, Voith Hydro and Andritz Hydro exemplify the integrated electromechanical archetype, while China Three Gorges Corporation anchors the sovereign development corporation tier. These entities represent distinct competitive positions: European OEMs capture refurbishment cycles and digital retrofit premiums, while Chinese state-backed developers control greenfield cascade corridors with domestic supply chain integration.
| Leading Market Players |
|---|
| GE Vernova |
| Siemens Energy AG |
| Voith Hydro |
| Andritz Hydro |
| China Three Gorges Corporation |
| Duke Energy Corporation |
| NextEra Energy Resources |
| Hydro-Quebec |
| ABB |
| Others |
Supply Flow & Price Mechanics
Eighteen-month lead times for Francis turbine runners concentrate pricing power with Austrian and German electromechanical OEMs while compressing developer IRRs on delayed projects. This inventory-to-delivery gap amplifies cost pass-through for electrical steel laminations and penstock-grade carbon steel, embedding supply chain rigidity directly into EPC contract escalation clauses.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure by mandating SF6-free switchgear premiums that stratify across certified-green, transitional, and legacy equipment categories. Project-based long-term offtake contracts dominate, with price differentiation resting on turbine efficiency class and domestic content compliance under China's MIIT thresholds. Pricing pressure stems from silicon steel supply concentration among East Asian metallurgical suppliers, squeezing margins on generator core fabrication. Industrial offtakers exhibit lowest price sensitivity due to carbon border compliance premiums, while distributed mini-hydro developers face acute cost compression.
Supply Chain Analysis
Strategic stockpiling of electrical steel laminations and forged turbine runners prevails over just-in-time approaches given eighteen-to-twenty-four-month procurement cycles for critical electromechanical packages. Supply concentrates in China, Germany, and Austria for turbine assembly, with Brazil and Norway anchoring civil engineering and reservoir construction pools. Raw material dependencies center on grain-oriented electrical steel, high-strength carbon steel for penstocks, and copper windings for generator stators. Single-source vulnerability runs through East Asian silicon steel suppliers subject to export quota volatility. Distribution feeds from OEM fabrication centers through EPC contractors to utility and industrial offtake counterparties.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hydropower generation operates as a regulatory-moat industry where concession licensing and aquatic habitat permitting create decade-plus barriers to greenfield entry. This entrenchment favors incumbents with existing reservoir assets and licensed watercourse access over new market participants.
For Market Incumbents: Shield existing concession portfolios by accelerating digital governor retrofits at aging North American infrastructure before FERC relicensing windows close. Pursue backward integration into electrical steel sourcing through long-term offtake agreements with East Asian metallurgical suppliers to isolate against export quota volatility. Vertical control over turbine manufacturing scale remains essential as China's MIIT thresholds tighten procurement access. For New Entrants and Emerging Players: Anchor in distributed mini-hydro deployment across mountainous Balkan territories and Carpathian watersheds where transmission extension cost differentials outweigh centralized development economics. Target captive industrial installations for energy-intensive manufacturing clusters in Vietnam, Indonesia, and Thailand seeking isolation from grid volatility. A direct bilateral contracting model with aluminum smelters and data center operators bypasses traditional utility intermediation. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pumped storage retrofits as Alpine utilities recover premiums through ancillary service revenue streams under TSO frequency regulation contracts. Acquisition targets should screen for reservoir assets with existing environmental permits and licensed watercourse concessions in OECD markets. The signal to watch is EU carbon border adjustment implementation tightening embedded emissions certification requirements for aluminum and fertilizer producers.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Governor Retrofit Deployment | Andritz Hydro and Voith Hydro capture 15-20% efficiency gains at aging Bureau of Reclamation infrastructure without full replacement. |
| SF6-Free Switchgear Transition | Siemens Energy and Hitachi accelerate dry-air interrupter adoption under EU F-Gas Regulation mandates for grid interconnection agreements. |
| Long-Term Industrial Offtake Contracting | Norwegian reservoir operators structure shaped delivery profiles isolating aluminum smelters from day-ahead Nordic price spikes. |
| Electrical Steel Supply Security | Developers lock in grain-oriented silicon steel laminations through multi-year offtakes with East Asian metallurgical suppliers. |
| Variable-Speed Generator Refurbishment | European IPPs recover 12-18% capital premiums through enhanced ancillary service revenue streams under TSO contracts. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators across China, Brazil, Norway, and the United States. Secondary validation drew from FERC licensing databases, IEA hydropower statistics, EIA generation capacity reports, and ANEEL regulatory filings. Bottom-up project pipeline aggregation was triangulated against top-down macroeconomic capacity forecasts.
Across the analysis window, volume and value outputs reflect segmentation by technology type, installation scale, end-user structure, and capacity tier. CAGRs were derived from project-level IRR sensitivity analysis and institutional capital deployment tracking. Key inputs included turbine manufacturing lead times, environmental review timeline distributions, and bilateral offtake contract pricing benchmarks.
Decision-makers should treat outputs as directional under base assumptions of sustained EU Green Deal taxonomy alignment and stable East Asian electrical steel export quotas; material deviation would warrant model refresh. Revision becomes warranted when FERC or ANEEL regulatory timelines cross threshold extensions compressing developer returns below hurdle rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydropower Systems
Floating Power Plant Market
Hydropower Systems
Hydropower Turbine Market
Hydropower Systems
South America Hydropower Market
Hydropower Systems
Hydropower Market
Hydropower Systems
Africa Small Hydropower Market
Hydropower Systems
Offshore Hydropower Market
Hydropower Systems
France Tidal Power Market
Hydropower Systems
Standard Modular Hydropower Market
Hydropower Systems
Europe Hydropower Market
Hydropower Systems
Run of River Power Market
Hydropower Systems
Europe Small Hydropower Market
Hydropower Systems
Hydroelectricity Market
Hydropower Systems
Whirlpool Turbine Market
Hydropower Systems
Europe Hydro Turbine Market
Hydropower Systems
Global Hydro Turbine Generator Unit Market
Hydropower Systems
Southeast Asia Hydropower Market