
 Global Hydro Turbine Generator Unit Market | 2026-2036
Global Hydro Turbine Generator Unit Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hydro Turbine Generator Unit Market Outlook
Independent power producers are rotating into larger procurement volumes as utilities defer greenfield capital. Toshiba leverages its pumped storage technology leadership across Asia-Pacific baseload projects. Andritz anchors European refurbishment demand with specialized Francis turbine upgrades. Harbin Electric dominates domestic Chinese installations through integrated manufacturing scale.
A hydro turbine generator unit converts hydraulic energy into rotational mechanical energy and then electrical output through a coupled generator, typically operating at head ranges from 2 meters to over 2,000 meters depending on turbine classification. The assembly requires precision-machined runners, wicket gates, and thrust bearings engineered for decades of continuous submersion. Francis Technology retains the largest installed base across medium and high-head applications, while Pumped Storage Technology captures the fastest expansion as grid operators seek multi-gigawatt balancing assets. Horizontal Turbines command premium positioning in low-head run-of-river sites where civil works minimization drives project economics.
FERC licensing requirements in the United States mandate environmental flow compliance and fish passage infrastructure, extending project timelines but embedding long-term service contracts for incumbent suppliers. China's MIIT enforces minimum efficiency thresholds under national GB standards, effectively filtering lower-tier domestic manufacturers from large-scale tenders. The EU Green Deal and associated taxonomy criteria direct capital toward rehabilitated hydro assets with modernized runner hydraulics. Stakeholders must track how carbon border adjustment mechanisms treat imported turbine components against locally manufactured alternatives.
Market Dynamics
Independent power producers are accelerating procurement of pumped storage turbine generator units as grid operators prioritize multi-gigawatt balancing assets to manage renewable intermittency.
Growth Catalysts
- EU Green Deal taxonomy criteria:The framework directs institutional capital toward rehabilitated hydro assets with modernized runner hydraulics, expanding refurbishment demand across European installations.
- Pumped storage technology:Grid operators in Asia-Pacific baseload projects are deploying turbine generator units for frequency regulation and load balancing at unprecedented scale.
- Brazil's hydropower corridor:Run-of-river developments in the Amazon and Paraná basins require horizontal turbine configurations optimized for low-head civil works minimization.
Market Restraints
- Specialized forging capacity:Precision-machined runners and wicket gates depend on concentrated heavy-industrial forging clusters in China and Germany, creating supply bottlenecks for large-diameter components.
- FERC environmental compliance:United States licensing mandates for fish passage infrastructure and environmental flow requirements extend project development timelines by multiple years.
- Lithium-ion battery substitution:Utility-scale battery storage systems compete for grid balancing contracts, displacing some planned pumped storage turbine generator unit installations in deregulated markets.
Strategic Opportunities
- Mekong Basin development:Laos and Cambodia host underexploited low-head sites where horizontal turbine technology enables run-of-river economics without reservoir construction.
- MIIT efficiency mandates:China's GB standards for minimum turbine efficiency are filtering domestic manufacturers, creating procurement openings for certified international suppliers in large-scale tenders.
- Digital twin integration:Convergence of computational fluid dynamics with IoT sensor networks enables predictive maintenance contracts that extend service revenue streams across decades-long asset lifecycles.
Industry Challenges
- Turbine hydraulic engineering expertise:The specialized knowledge required for runner blade design and cavitation mitigation is concentrated among retiring specialists in Europe and Japan, constraining workforce expansion.
- Thrust bearing certification timelines:Type approval for submersion-rated bearings under IEC standards requires multi-year testing protocols that delay commercial deployment of novel bearing materials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hydro Turbine Generator Unit Market |
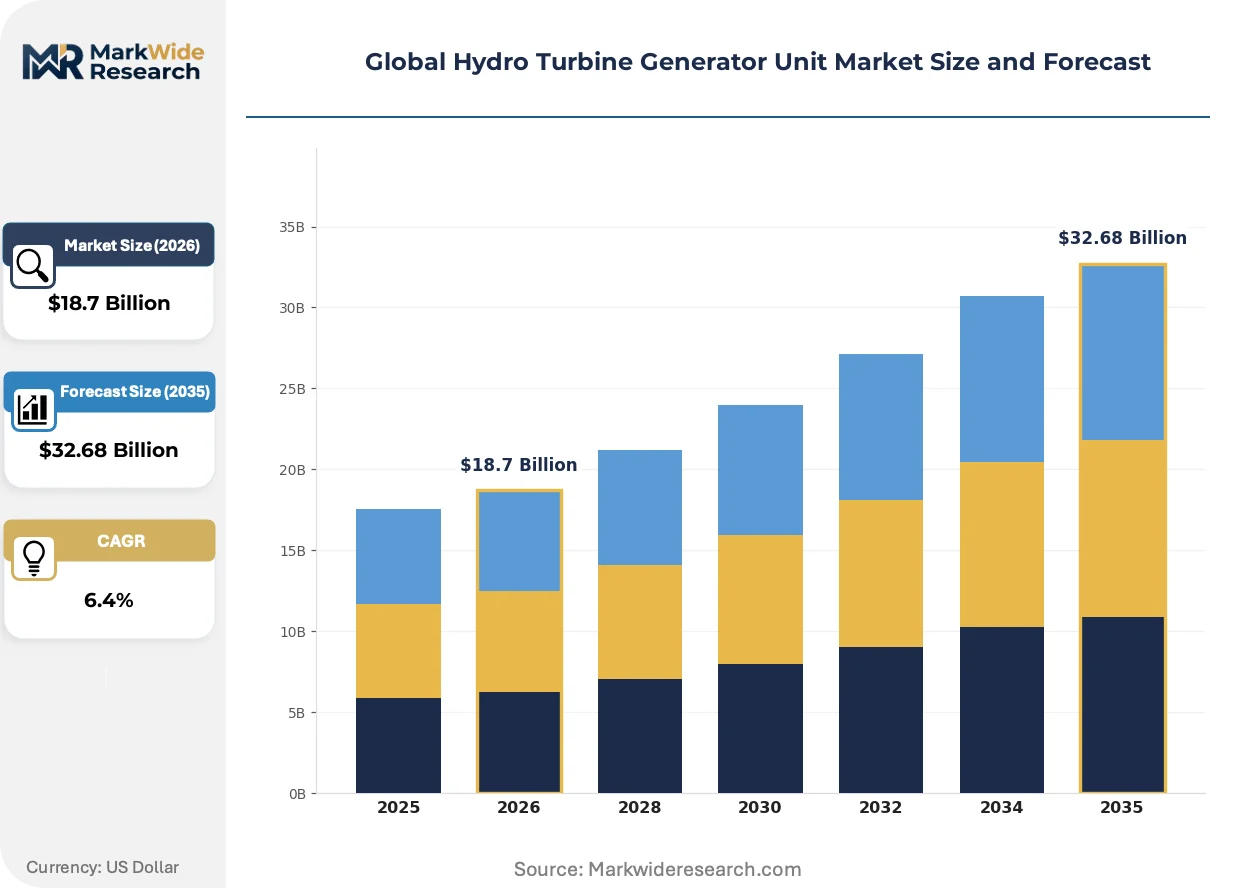
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Turbines, Horizontal Turbines, Bulb Turbines, Kaplan Turbines Technology: Francis Technology, Pelton Technology, Kaplan Technology, Pumped Storage Technology End User: Utilities, Independent Power Producers, Industrial Plants, Government Entities Capacity: Small Scale, Medium Scale, Large Scale, Extra Large Scale |
| Companies Covered | Toshiba, Harbin Electric, Andritz, BHEL, Hitachi Mitsubishi, Voith, Dongfang Electric, Power Machines, General Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hydro Turbine Generator Unit Market Strategic Shifts
Additive manufacturing of turbine runners is fragmenting traditional casting supply chains as precision metal deposition enables complex internal cooling geometries previously impossible with conventional forging methods.
Computational fluid dynamics software is fragmenting the engineering workflow for runner blade optimization, allowing independent power producers to specify site-specific hydraulic profiles rather than accepting standardized catalog designs. European utilities with refurbishment mandates under the EU Green Deal are adopting this approach fastest, compressing lead times for Francis turbine upgrades while reducing prototype testing costs.
China's MIIT has tightened GB standard efficiency thresholds for new hydro turbine generator unit installations, effectively disqualifying lower-tier domestic manufacturers from state-backed tenders. The regulation is compressing supplier margins as certified producers absorb compliance testing costs, with the policy most affecting medium-head Francis turbine procurement in provincial hydropower expansions.
Long-term service contracts are displacing transactional spare parts sales as the dominant commercial model for turbine generator unit suppliers. European independent power producers under EU Green Deal rehabilitation mandates are unbundling maintenance from equipment supply, creating dedicated service subsidiaries. This pattern is most visible in Germany and Austria where aging Alpine installations require continuous wicket gate and thrust bearing replacement programs.
Global Hydro Turbine Generator Unit Market Segmentation
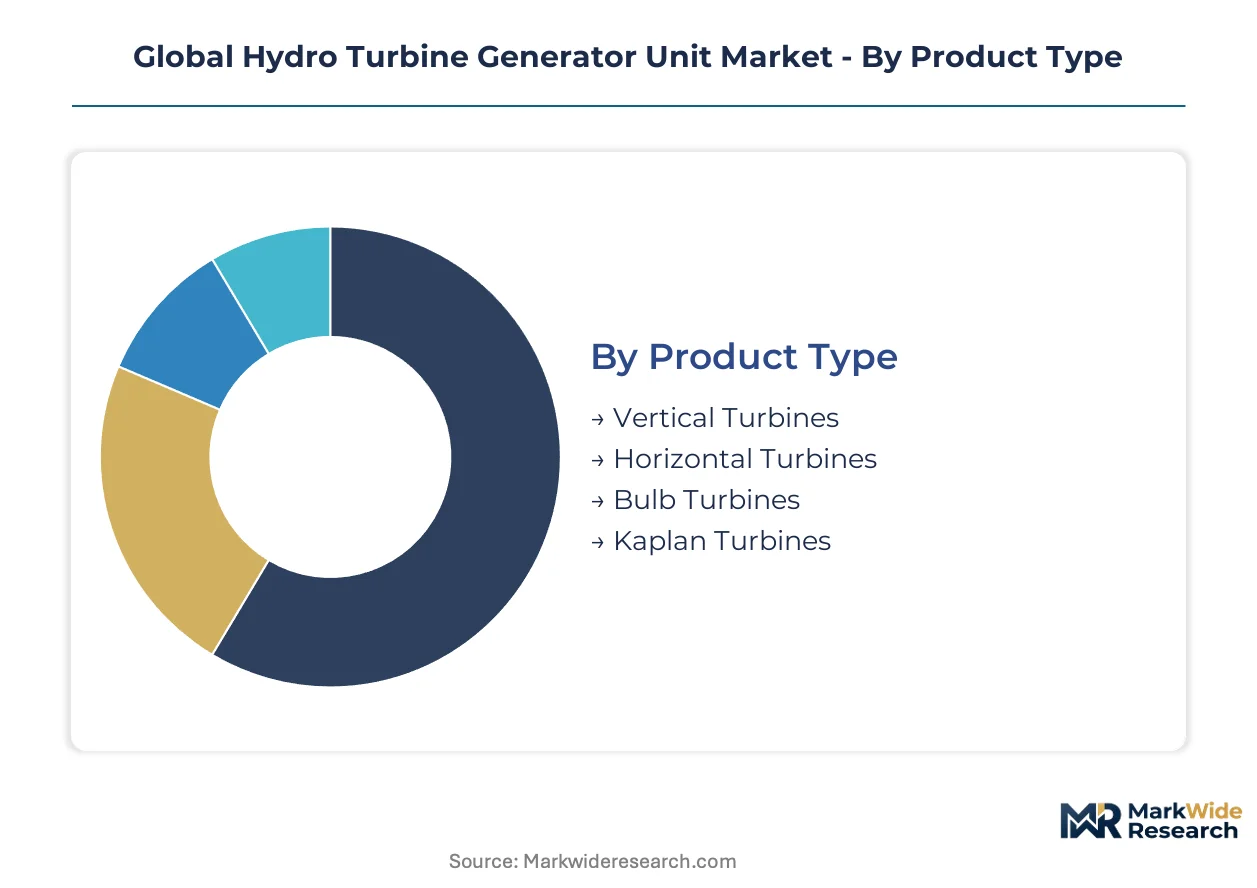
Hydro turbine generator unit procurement patterns diverge sharply across product configurations, technology lineages, and ownership structures. Regulatory frameworks in China, the EU, and the United States create distinct compliance thresholds that reshape segment prioritization for developers and equipment suppliers alike.
Product Type:
China's MIIT efficiency mandates under GB standards and FERC environmental flow requirements in the United States impose divergent civil works and performance specifications on turbine orientation choices.
- Vertical Turbines:Shaft-mounted configurations position the generator above waterline, enabling easier maintenance access in high-head installations. China's provincial hydropower expansions favor vertical arrangements for medium-head Francis applications where MIIT efficiency thresholds filter non-compliant suppliers.
- Horizontal Turbines:Compact shaft alignment minimizes powerhouse excavation depths, reducing civil costs in low-head run-of-river developments. Brazil's Amazon basin projects specify horizontal configurations for sites below 30 meters head where topography constraints dominate project economics.
- Bulb Turbines:Submerged generator housings eliminate vertical shafts entirely, optimizing hydraulic efficiency in tidal and very low-head river applications.
- Kaplan Turbines:Adjustable blade geometry accommodates variable flow regimes in irrigation-fed canals and seasonal rivers.
Established volume favors Vertical Turbines; emerging adoption favors Horizontal Turbines.
Technology:
Technology selection maps directly to head range and grid service requirements, with pumped storage commanding premium positioning for balancing services.
- Francis Technology:Reaction turbine design harnesses both pressure and kinetic energy across medium to high heads. European refurbishment demand under EU Green Deal taxonomy criteria concentrates on modernized Francis runners with computational fluid dynamics-optimized hydraulics.
- Pumped Storage Technology:Reversible turbine-generator assemblies enable bi-directional operation for energy arbitrage and frequency regulation. Grid operators in Japan and South Korea are deploying multi-gigawatt pumped storage assets to manage solar and wind intermittency.
- Pelton Technology:Impulse turbine configuration extracts energy from high-velocity jets, dominating alpine installations above 300 meters head.
- Kaplan Technology:Axial-flow design with adjustable wicket gates and runner blades optimizes part-load efficiency in variable head conditions.
Francis Technology retains the largest installed base; Pumped Storage Technology is climbing the fastest.
End User:
Ownership structure determines procurement scale, financing mechanisms, and service contract duration.
- Utilities:Vertically integrated grid operators prioritize asset longevity and standardized maintenance protocols. State-owned utilities in China dominate domestic tender volumes through consolidated procurement frameworks aligned with MIIT certification requirements.
- Independent Power Producers:Merchant developers seek flexible equipment configurations and performance guarantees to secure project finance. IPPs in Germany and Austria are unbundling maintenance from supply, creating dedicated service subsidiaries for aging Alpine installations.
- Industrial Plants:Captive generation for mining, aluminum smelting, and pulp operations demands high availability turbines with rapid restart capabilities.
- Government Entities:Public works agencies in the Mekong Basin sponsor run-of-river developments where horizontal technology enables reservoir-free economics.
Utilities anchor current procurement volumes; Independent Power Producers are gaining share fastest.
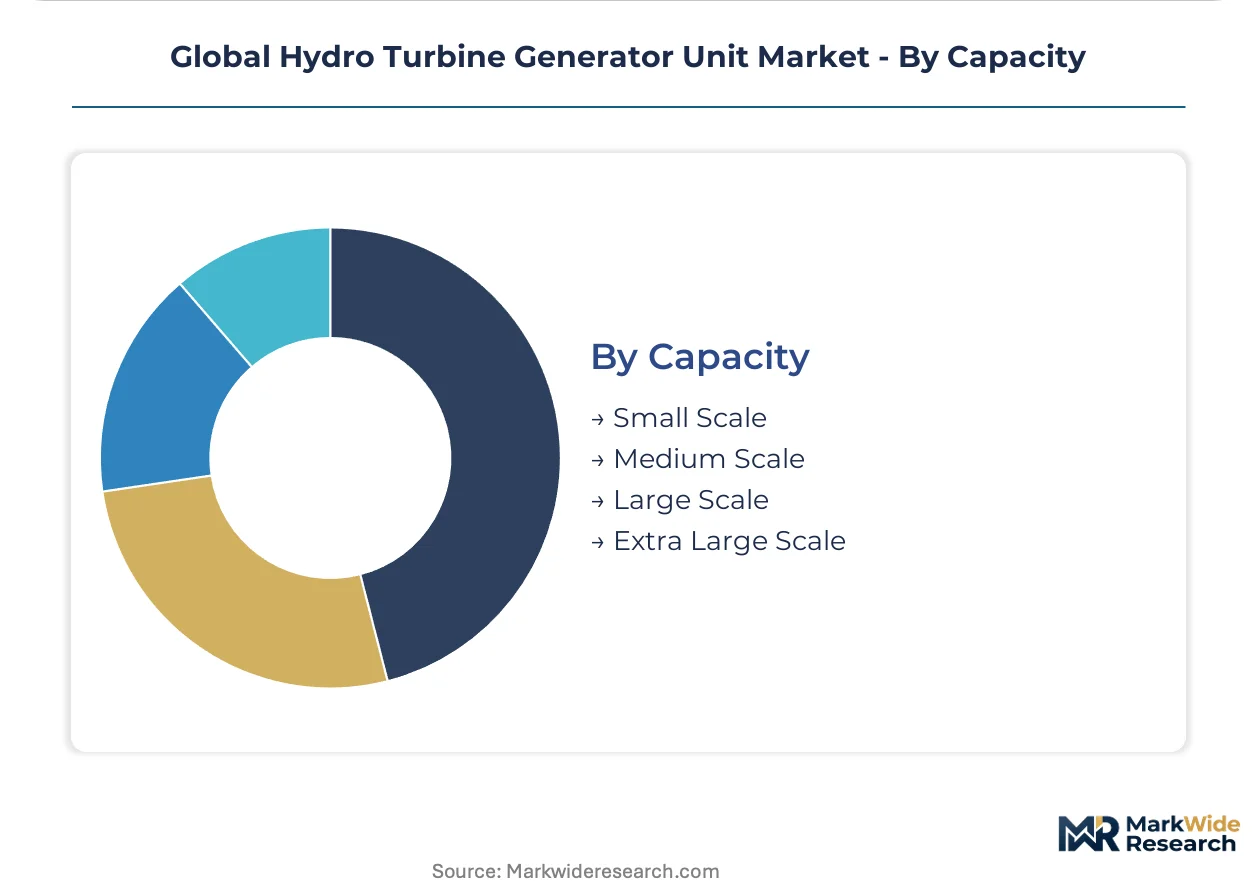
Capacity:
Scale thresholds determine forging supply chain access, transportation logistics, and grid interconnection voltage classes.
- Large Scale:Units above 100 MW require specialized forging clusters in China and Germany for precision-machined runners. Brazil's hydropower corridor developments specify large-scale configurations for transmission-connected projects in the Paraná basin.
- Small Scale:Modular designs below 10 MW enable distributed deployment with standardized civil templates. Laos and Cambodia are procuring small-scale horizontal units for isolated grid extensions without reservoir construction.
- Medium Scale:Mid-range installations balance efficiency optimization with manufacturing standardization.
- Extra Large Scale:Gigawatt-class units demand custom engineering and multi-year manufacturing timelines.
Large Scale commands premium margins; Small Scale is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Three Gorges Dam complex on the Yangtze River anchors China's dominance in installed hydroelectric capacity. Brazil's Itaipu Binacional facility underwrites South American baseload generation. The European Alps host aging infrastructure requiring systematic refurbishment.
China
Provincial hydropower expansions in Sichuan and Yunnan provinces drive procurement of large-scale Francis turbine units. MIIT enforces GB standard efficiency thresholds that filter non-compliant domestic manufacturers from state-backed tenders. The Yangtze River Delta manufacturing cluster concentrates precision forging capacity for precision-machined runners and wicket gates.
Brazil
Run-of-river developments in the Amazon and Paraná basins require horizontal turbine configurations optimized for low-head civil works minimization. ANEEL licensing frameworks mandate environmental flow compliance and fish passage infrastructure. The Belo Monte complex on the Xingu River exemplifies multi-gigawatt horizontal turbine deployment.
Germany
Alpine refurbishment demand under EU Green Deal taxonomy criteria concentrates on modernized Francis runners with computational fluid dynamics-optimized hydraulics. The KBA does not regulate this sector; instead, EU Green Deal directives shape capital allocation. The Bavarian Alps host specialized service subsidiaries performing continuous wicket gate and thrust bearing replacement programs.
United States
FERC licensing requirements mandate environmental flow compliance and fish passage infrastructure, extending project timelines but embedding long-term service contracts. The Pacific Northwest's Columbia River Basin hosts aging installations requiring thrust bearing certification under IEC standards. Tennessee Valley Authority procurement prioritizes asset longevity and standardized maintenance protocols.
Japan
METI directs capital toward rehabilitated hydro assets with modernized runner hydraulics as part of broader decarbonization targets. Pumped storage deployment at the Okutataragi and Kannagawa facilities supports grid balancing for renewable intermittency. The Kansai region concentrates engineering expertise for cavitation mitigation and runner blade design.
Global Hydro Turbine Generator Unit Market Competitive Environment
Listed leaders compete with private specialists across technology licensing and service contract duration. The vendor base organizes around three tiers: integrated conglomerates with captive forging capacity, specialized turbine engineering houses, and regional fabrication specialists serving discrete geographies. Strategic archetypes include efficiency-certified producers qualifying for Chinese state tenders, refurbishment-focused European service providers, and pumped storage technology leaders. Competitive moves concentrate on backward integration into heavy-industrial forging and geographic expansion through joint ventures in emerging basins.
Among Asia-Pacific-based integrated manufacturers, Harbin Electric and Dongfang Electric exemplify scale-driven archetypes with domestic Chinese installation dominance. Voith represents the European specialist tier, anchoring Alpine refurbishment demand through Francis turbine upgrade capabilities. These three occupy positions across distinct competitive vectors: manufacturing scale, service specialization, and technology leadership in reversible pumped storage configurations.
| Leading Market Players |
|---|
| Toshiba |
| Harbin Electric |
| Andritz |
| BHEL |
| Hitachi Mitsubishi |
| Voith |
| Dongfang Electric |
| Power Machines |
| General Electric |
| Others |
Value Chain & Pricing Dynamics
Additive manufacturing of precision-machined runners is displacing traditional forging methods, simultaneously redrawing supply geography away from concentrated heavy-industrial clusters in China and Germany while compressing price premiums for complex blade geometries.
Pricing Analysis
Volume-discount tiering structures dominate procurement, with three-tier pricing separating MIIT-certified premium units from standard efficiency-grade equipment and economy-tier regional fabricators. Price differentiation rests on certification grade under Chinese GB standards and bundled after-sales service duration. Cost compression in the economy tier is intensifying as lower-tier domestic manufacturers absorb compliance testing expenses to qualify for provincial tenders. State-owned utilities demonstrate lowest price sensitivity due to consolidated procurement frameworks, while merchant independent power producers negotiate aggressively on performance guarantees.
Supply Chain Analysis
Strategic stockpiling of specialized forgings prevails over just-in-time approaches given multi-year manufacturing timelines for large-diameter runners and wicket gates. Precision forging capacity concentrates in China, Germany, and Japan, with raw material dependencies spanning high-grade stainless steel, specialized bearing alloys, and copper windings. Single-source vulnerability around submersion-rated thrust bearings under IEC certification protocols creates structural risk. Distribution runs through engineering-procurement-construction contractors with direct OEM relationships for gigawatt-class projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among consolidated state-backed utilities in China and unbundled independent power producers in Europe, squeezing margins for non-certified suppliers.
For Market Incumbents: Secure backward integration into heavy-industrial forging capacity in the Yangtze River Delta to defend against additive manufacturing disruption. Lock in multi-decade service contracts with European independent power producers under EU Green Deal rehabilitation mandates, as lithium-ion battery substitution threatens pumped storage project pipelines. For New Entrants and Emerging Players: Anchor in the Mekong Basin's underexploited low-head sites where horizontal turbine technology enables reservoir-free economics without competing against established European refurbishment specialists. Pursue joint venture structures with provincial Chinese developers to bypass MIIT certification barriers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors service-specialist acquisitions over manufacturing scale plays. Long-term viability hinges on predictive maintenance capabilities and digital twin integration. Monitor carbon border adjustment mechanism rulings on imported turbine components as the critical inflection signal for geographic sourcing strategies.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forging | Captive supply of precision-machined runners insulates margin pressure from concentrated Chinese and German suppliers. |
| Digital Twin Integration | IoT-enabled predictive maintenance contracts extend revenue visibility across decades-long asset lifecycles for European utilities. |
| MIIT Certification Investment | GB standard compliance unlocks access to state-backed tenders in Sichuan and Yunnan provincial expansions. |
| Pumped Storage Technology Licensing | Reversible turbine-generator expertise addresses grid balancing demand from Japan and South Korea renewable intermittency. |
| Mekong Basin Joint Ventures | Local partnerships in Laos and Cambodia bypass civil works minimization constraints for horizontal turbine deployment. |
Study Parameters
Cross-validation between primary fieldwork and secondary regulatory filings anchors the qualitative findings. The research combined interviews with utility planning officers, independent power producer project developers, EPC contractors, and aftermarket service heads with secondary validation through FERC licensing databases, MIIT GB standard publications, EU Green Deal taxonomy documentation, and IEA hydropower tracking reports. Bottom-up project pipeline analysis and top-down installed capacity assessments provided triangulation across the modeling period.
Sensitivity analysis around capacity addition schedules and efficiency mandate enforcement timelines shaped the analytical framework. The forecast segmented by technology lineage, turbine orientation, capacity tier, and regional regulatory cluster. CAGRs were derived from unit shipment trajectories and average selling price evolution across certified and non-certified supplier tiers. Key inputs included provincial Chinese hydropower expansion approvals and European refurbishment mandate compliance deadlines.
Decision-makers should treat outputs as directional under base assumptions of continued MIIT enforcement and EU Green Deal capital allocation; material deviation in regulatory stringency would warrant model refresh. Practitioners should keep alternative scenarios live as carbon border adjustment mechanism treatments and lithium-ion battery cost curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydropower Systems
Tidal Power Market
Hydropower Systems
Africa Small Hydropower Market
Hydropower Systems
France Tidal Power Market
Hydropower Systems
Hydro Turbines Market
Hydropower Systems
Pumped Hydro Storage Market
Hydropower Systems
Asia-Pacific Hydropower Market
Hydropower Systems
South America Pumped Hydro Storage Market
Hydropower Systems
Asia-Pacific Pumped Hydro Storage Market
Hydropower Systems
Offshore Hydropower Market
Hydropower Systems
Europe Hydro Turbine Market
Hydropower Systems
Europe Small Hydropower Market
Hydropower Systems
Whirlpool Turbine Market
Hydropower Systems
Japan Hydropower Market
Hydropower Systems
Small Hydropower Market
Hydropower Systems
Run of River Power Market
Hydropower Systems
Asia-Pacific Small Hydropower Market