
 Ocean Energy Market | 2026-2036
Ocean Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Ocean Energy Market Intelligence
The development of large-scale, grid-connected tidal stream projects is decoupling from the market for smaller, specialized wave energy converters designed for remote power applications. This divergence reflects different technology maturity levels and capital requirements. Orbital Marine Power leads in floating tidal turbine technology for utility-scale generation. In contrast, CorPower Ocean AB specializes in point-absorber wave energy converters, targeting niche offshore and island energy needs, demonstrating a different commercialization pathway.
Ocean energy involves harnessing the kinetic or thermal power of seawater to generate electricity. This process utilizes technologies like turbines to capture energy from tidal currents or wave motion, or employs temperature differentials in Ocean Thermal Energy Conversion systems. The primary commercial purpose is to provide a predictable, renewable power source for coastal communities and industries. Tidal Energy technology currently leads in large-scale deployments, whereas Wave Energy represents a segment with extensive ongoing research for applications like powering marine and offshore platforms.
Regulatory support is a critical enabler of market development. In the United States, the Inflation Reduction Act (IRA) provides investment tax credits for marine energy projects. The EU Green Deal offers a strategic framework and funding mechanisms for member states to pursue renewable targets, benefiting ocean energy developers. These policies, alongside national-level support in countries like Canada, create the financial stability necessary for long-term project planning and securing power purchase agreements with utility companies.
Market Dynamics
The central force shaping the ocean energy market is the global mandate for decarbonized, predictable power generation. This demand, driven by national net-zero commitments, creates a direct pull for grid-scale tidal and wave projects from utility companies seeking to diversify their renewable energy portfolios.
Growth Catalysts
- Favorable Government Policies:The EU Green Deal and similar frameworks provide critical funding mechanisms and revenue support, de-risking large capital investments and enabling long-term power purchase agreements for ocean energy developers.
- Technological Maturation:Advances in floating tidal turbine technology and point-absorber wave energy converters are demonstrating commercial viability and reliability, moving beyond pilot stages to support utility-scale generation.
- Resource-Rich Geographies:Development is concentrating in areas with strong, predictable tidal streams and wave patterns, such as the waters around the United Kingdom and Canada, which attract focused investment and infrastructure development.
Market Restraints
- High Capital Expenditure:The substantial upfront investment required for manufacturing, deploying, and connecting large-scale ocean energy arrays remains a primary barrier to entry and project scalability compared to mature renewables.
- Environmental Permitting Complexity:Securing project approvals involves lengthy and rigorous environmental impact assessments to evaluate potential effects on marine ecosystems, which can introduce significant delays and uncertainty.
- Grid Connection Infrastructure:The logistical and financial challenges of building and maintaining high-voltage subsea cables to connect offshore energy farms to onshore electricity grids can constrain project development.
Strategic Opportunities
- Remote and Offshore Power:Deploying smaller, modular wave and tidal devices presents an opportunity to supply power to off-grid coastal communities, island nations, and offshore industrial platforms like aquaculture and data centers.
- Green Hydrogen Production:Co-locating ocean energy converters with electrolyzers offers a pathway to produce green hydrogen, providing a dedicated offtake market and supporting the broader hydrogen economy.
- Hybrid Energy Projects:Integrating ocean energy systems with offshore wind farms allows for shared grid infrastructure and creates a more consistent, baseload-style renewable power output, enhancing project economics and grid stability.
Industry Challenges
- Device Survivability and Maintenance:Ensuring the long-term operational durability of equipment in corrosive, high-energy marine environments poses a significant engineering challenge, driving up operational and maintenance costs.
- Specialized Workforce Scarcity:A limited pool of engineers and technicians with expertise in marine hydrodynamics, subsea robotics, and power systems for ocean energy creates a bottleneck for project execution and innovation.
- Component Supply Chain Limitations:The supply chain for specialized components, including large composite structures, power take-off systems, and mooring solutions, is not yet scaled for mass production, leading to potential bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ocean Energy Market |
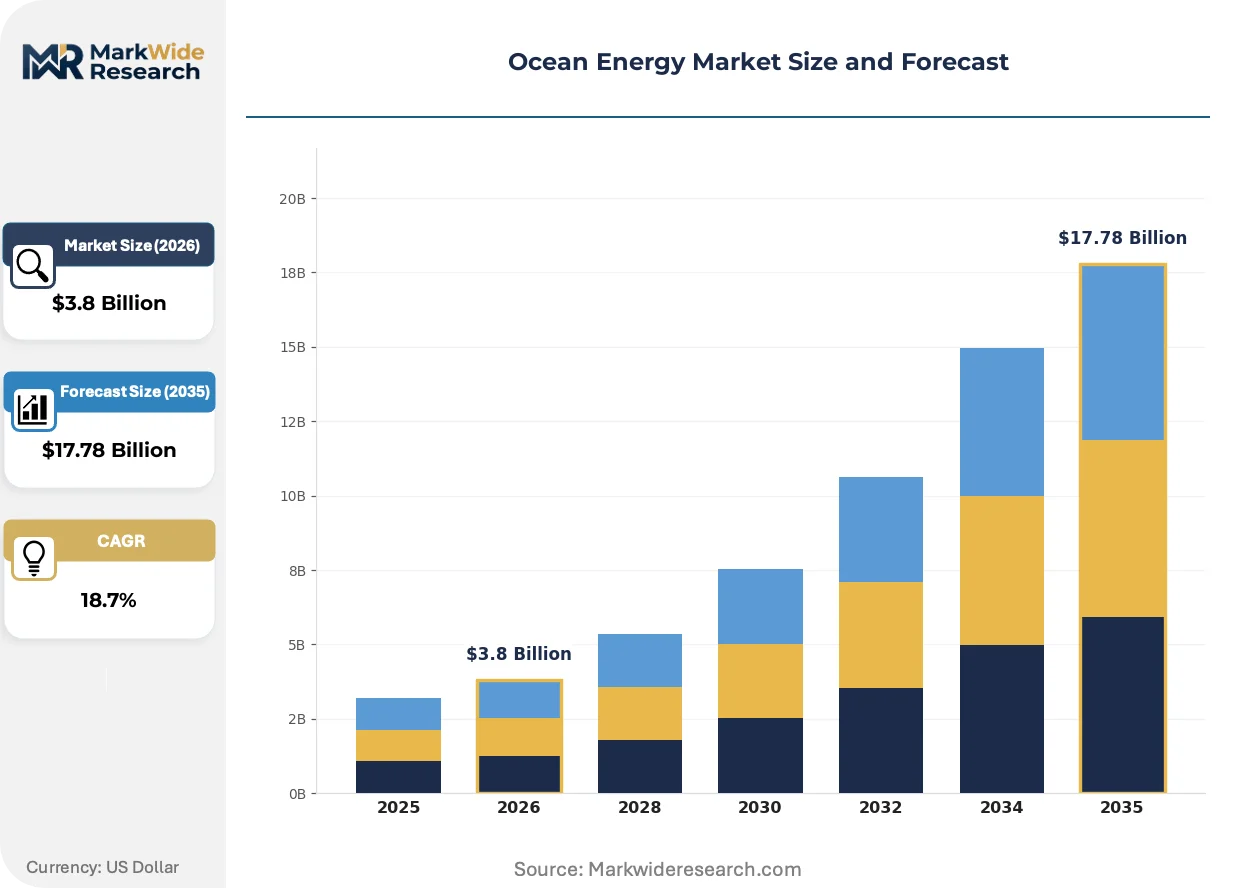
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.78 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Wave Energy, Tidal Energy, Ocean Thermal Energy Conversion, Salinity Gradient Application: Coastal Infrastructure, Marine and Offshore Platforms, Energy Storage, Desalination End User: Utility Companies, Maritime Operators, Research Institutions, Government Agencies Service Type: Consulting, Installation, Maintenance, Financing |
| Companies Covered | Ocean Power Technologies, Eco Wave Power, CorPower Ocean AB, Orbital Marine Power, SIMEC Atlantis Energy, Nova Innovations, Andritz Hydro Hammerfest, Carnegie Clean Energy, Mocean Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ocean Energy Market Strategic Shifts & Innovations
A convergence of policy support and technological validation is accelerating the transition from small pilot projects to commercial-scale deployments. This shift is most evident in the development of grid-connected arrays designed for predictable, utility-grade power delivery.
Floating tidal turbine platforms provide a method for deployment in deeper waters without requiring fixed seabed foundations. Utility companies and project developers are adopting this technology to access more powerful tidal resources farther from shore. This flexible deployment model is overtaking the previous focus on fixed, seabed-mounted systems, which have greater geographical and environmental siting constraints.
The Inflation Reduction Act (IRA) in the United States provides specific investment tax credits for marine and hydrokinetic energy projects. This policy directly de-risks the significant capital investment required for developers to build new capacity. Project financing in US waters is the most affected segment, enabling developers to secure more favorable terms for projects planned in coastal regions.
A focus on grid stability is altering procurement models for utility companies, which are shifting from simply purchasing energy to contracting for predictable capacity. Large grid operators now value the reliable, forecastable output from tidal sources to balance intermittent renewables like wind and solar. This demand is most pronounced in European markets like the United Kingdom, which have high renewable penetration rates.
Ocean Energy Market Segmentation
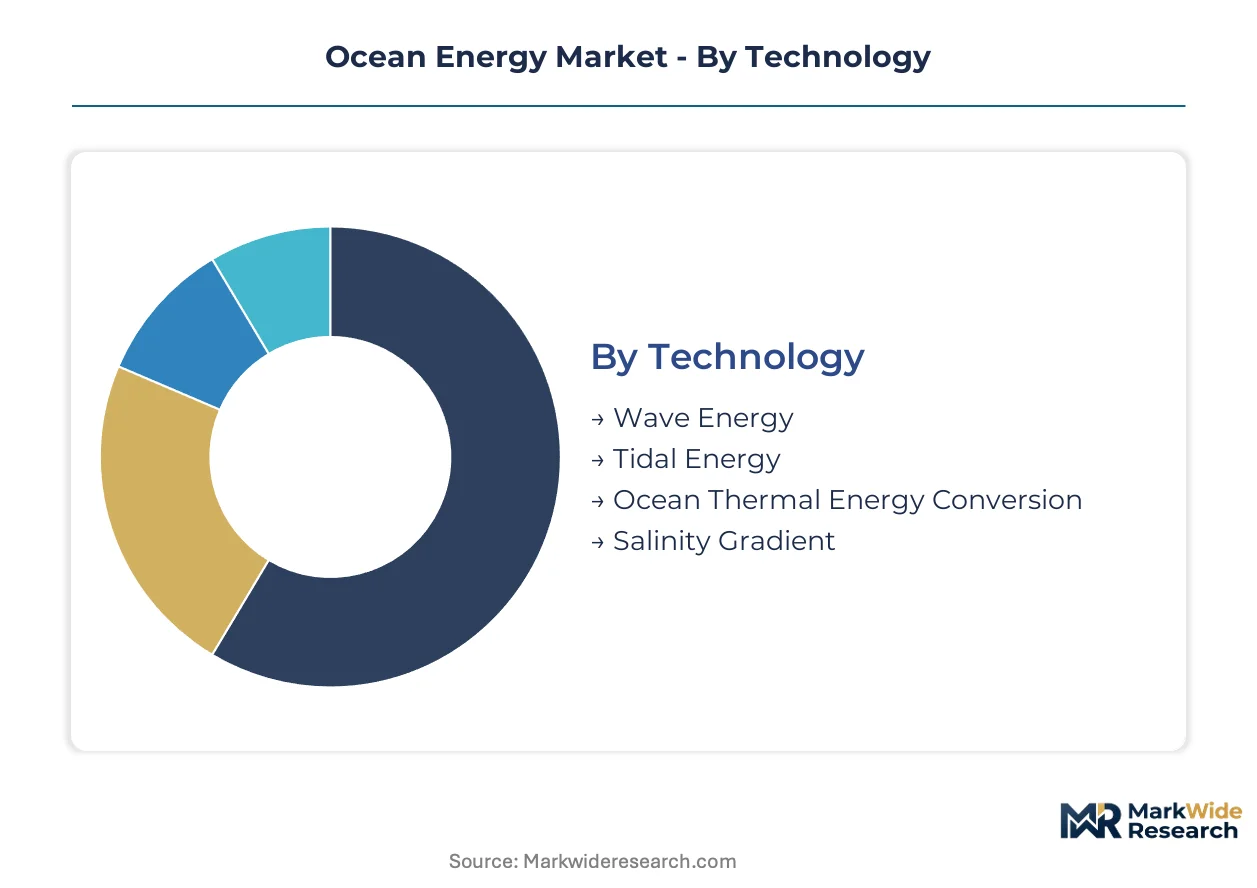
The Ocean Energy Market segments across diverse technologies, applications, end-users, and service types, reflecting the varied approaches to harnessing marine power. Understanding these segments helps developers and investors identify specific opportunities and challenges within the market's evolving landscape.
Technology:
Ocean energy technologies range from mature, grid-integrated systems to nascent solutions for specialized applications, indicating a spectrum of commercial readiness and deployment strategies.
- Tidal Energy:This technology leverages predictable tidal currents through turbines, providing consistent, utility-grade power. Deployment activity is notably concentrated in resource-rich geographies such as the United Kingdom, where grid operators value its reliable output for balancing intermittent renewables.
- Wave Energy:Wave energy converters capture kinetic energy from ocean waves, primarily targeting remote power applications and niche offshore needs. Extensive ongoing research aims to improve device survivability and cost-effectiveness for island nations and marine platforms.
- Ocean Thermal Energy Conversion:OTEC systems generate electricity by exploiting temperature differences between warm surface water and cold deep water. These systems are suitable for tropical regions with consistent thermal gradients and show potential for baseload power.
- Salinity Gradient:Salinity gradient technology harnesses the osmotic pressure difference between fresh and saltwater, offering a clean energy source. This emerging technology is in early research and development phases, with pilot projects exploring its viability for specific coastal sites.
Volume placements concentrate in Tidal Energy; the faster expansion belongs to Wave Energy.
Application:
The deployment of ocean energy systems varies significantly based on the intended use, from large-scale grid contributions to localized power solutions, influencing project scale and required infrastructure.
- Coastal Infrastructure:This segment includes providing power for onshore facilities, ports, and population centers, directly connecting to national grids. Utility companies in countries like Canada are actively pursuing these projects to diversify their renewable energy portfolios.
- Marine and Offshore Platforms:Ocean energy devices supply electricity to remote offshore installations, including aquaculture farms, data centers, and scientific monitoring stations. CorPower Ocean AB specializes in converters for these niche, off-grid applications.
- Energy Storage:Ocean energy can be integrated with energy storage solutions, such as battery banks or pumped hydro, to enhance grid stability and ensure continuous power delivery. This application supports the broader decarbonization goals of national grids.
- Desalination:Utilizing ocean energy to power desalination plants offers a sustainable solution for freshwater scarcity in coastal regions. This application is particularly relevant for island communities and arid coastal areas.
The market for Coastal Infrastructure applications drives immediate revenue, while Marine and Offshore Platforms applications show significant future potential.
End User:
The primary beneficiaries of ocean energy span from large public utilities to specialized maritime operations, each with distinct needs and procurement models driving market development.
- Utility Companies:These entities procure large-scale, grid-connected ocean energy projects to meet renewable portfolio standards and provide predictable baseload power. The EU Green Deal provides critical financial support for these major projects.
- Maritime Operators:This segment includes shipping companies, offshore oil and gas platforms, and aquaculture businesses requiring reliable, localized power. Smaller, modular wave and tidal devices serve these remote power needs effectively.
- Research Institutions:Universities and governmental labs conduct extensive research and development on new ocean energy technologies and environmental impacts. Their work is crucial for advancing the sector's technological maturation.
- Government Agencies:National and regional government bodies support ocean energy through policy frameworks, funding mechanisms, and direct project investments. The US Inflation Reduction Act provides tax credits for marine energy projects.
Demand from Utility Companies underpins significant project development, with Maritime Operators segments seeking tailored solutions.
Service Type:
The array of services supporting the ocean energy market reflects the complex lifecycle of these projects, from initial planning and deployment to long-term operational sustainment.
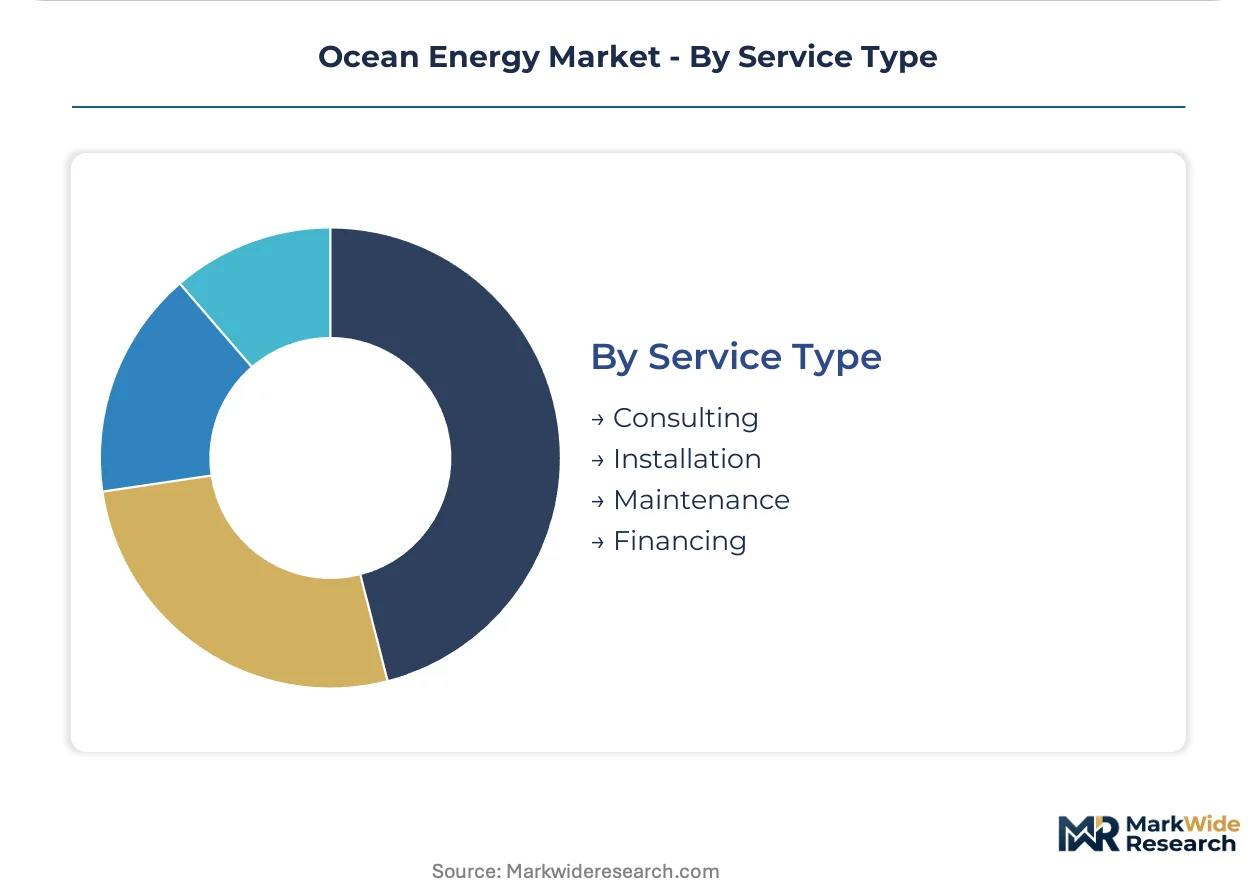
- Installation:This service involves the deployment of ocean energy converters, mooring systems, and subsea cables in challenging marine environments. High capital expenditure for installation remains a primary barrier for new projects.
- Maintenance:Ongoing inspection, repair, and upkeep of ocean energy devices are critical for ensuring long-term operational durability in corrosive conditions. This service addresses the significant engineering challenge of device survivability.
- Consulting:Specialized consulting firms provide expertise in site assessment, environmental impact studies, regulatory compliance, and project feasibility analysis. Their services are crucial for navigating environmental permitting complexity.
- Financing:Financial services include securing capital investment, project funding, and power purchase agreements for ocean energy developments. Favorable government policies like the IRA de-risk these investments.
Installation services are critical for project realization, as Maintenance services address long-term operational needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The waters around the United Kingdom represent a primary hub for ocean energy development, driven by strong tidal and wave resources. This region actively pursues large-scale, grid-connected projects to meet ambitious decarbonization targets. Critical government support underpins significant capital investments in marine energy infrastructure.
United Kingdom
Decarbonization goals and grid stability drive ocean energy projects. UK government support for renewables, aligning with broader European energy transition frameworks, provides critical funding. Scotland's Orkney Islands host significant tidal and wave energy testing, including projects by Orbital Marine Power.
Canada
Coastal communities and utility companies seek predictable renewable power sources. National-level support mechanisms facilitate long-term project planning for marine energy. Nova Scotia's Bay of Fundy is a focal point for tidal stream projects, leveraging its powerful currents.
United States
Renewable portfolio standards and coastal infrastructure needs spur marine energy interest. The Inflation Reduction Act (IRA) provides essential investment tax credits for marine energy projects. The Pacific Northwest, particularly off the Oregon coast, sees concentrated efforts in wave energy research and development.
Australia
Island nations and remote communities require reliable, localized power solutions. National renewable energy targets encourage investment in diverse marine energy technologies. Western Australia's Perth region is active in wave energy converter development, focusing on device survivability and cost-effectiveness.
Ocean Energy Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the ocean energy market, creating a dynamic competitive environment. The industry structure shows a mix of established engineering firms focused on large-scale deployments and specialized technology developers targeting specific applications. Strategic archetypes include integrated project developers, niche solution providers for remote applications, and specialized component manufacturers. Companies primarily pursue strategic partnerships, technology licensing, and capacity expansion to accelerate commercialization and reduce development risks in this capital-intensive sector.
Within the specialized technology developer archetype, CorPower Ocean AB and Orbital Marine Power exemplify focused innovation. These firms occupy positions at the forefront of wave and tidal energy converter development respectively, demonstrating different commercialization pathways. SIMEC Atlantis Energy, a UK-based company, also anchors a significant position in tidal energy projects, particularly with its operational arrays. These players represent the diverse approaches to harnessing marine power, ranging from utility-scale generation to niche offshore applications. Their activities underscore the ongoing maturation of ocean energy technologies towards broader market integration.
| Leading Market Players |
|---|
| Ocean Power Technologies |
| Eco Wave Power |
| CorPower Ocean AB |
| Orbital Marine Power |
| SIMEC Atlantis Energy |
| Nova Innovations |
| Andritz Hydro Hammerfest |
| Carnegie Clean Energy |
| Mocean Energy |
| Others |
Cost & Logistics Intelligence
The EU Green Deal and similar national decarbonization mandates gate access to qualified supply and premium-tier pricing for ocean energy projects. These frameworks prioritize projects demonstrating clear pathways to grid integration and predictable power delivery, influencing the entire value chain.
Pricing Analysis
Contract-based long-term offtake agreements with utility companies anchor pricing in the ocean energy market. Price differentiation stems from the predictability of tidal energy output and the technology readiness level of wave energy converters. Pricing pressure stems from the substantial upfront capital expenditure required for project development. Utility companies exhibit the least price sensitivity due to their demand for stable, baseload renewable power, while remote platform operators prioritize cost-effective modular solutions.
Supply Chain Analysis
Returns, refurbishment, and remanufacturing flows for ocean energy components are nascent, reflecting the early commercial stage of the industry. The supply chain for specialized components concentrates in resource-rich regions like the United Kingdom, Canada, and the United States. Raw material dependencies include advanced composite materials for turbine blades and robust subsea cables for grid connection. Specialized workforce scarcity represents a primary supply chain risk. Distribution runs through direct project sales to utility companies and specialized integrators serving niche offshore applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal frames the ocean energy market as a cost-of-compliance story, establishing a significant barrier-to-entry moat for compliant, large-scale project developers.
For Market Incumbents:Extend existing technology leadership by investing in device survivability research for high-energy marine environments. Form strategic partnerships with grid operators to optimize power dispatch and integrate ocean energy into broader renewable portfolios. This mitigates the threat of intermittent renewable competition. Leverage long-term power purchase agreements as a lever for securing project financing and demonstrating commercial viability.
For New Entrants and Emerging Players:Begin with targeting niche, off-grid applications such as remote island communities and offshore aquaculture platforms. The most penetrable segment lies in modular wave energy converters designed for localized power needs. A go-to-market angle should focus on delivering cost-effective, scalable solutions that reduce reliance on fossil fuels in isolated locations.
For Investors and Strategic Acquirers:Successful large-scale grid-connected project financing rounds and operational uptime are the leading indicators that signal market maturation. The long-term viability of ocean energy centers on its ability to provide predictable baseload power for global decarbonization over the next decade. Acquisition targets should be specialized technology developers with proven prototypes or early commercial deployments in tidal or wave energy.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Expanding large-scale tidal arrays in the United Kingdom increases grid stability and renewable energy contribution. |
| Power Purchase Agreement | Securing long-term PPAs with utility companies in Canada provides financial stability for significant project investments. |
| Technology Licensing | Licensing floating tidal turbine technology accelerates global deployment and reduces development risks for new regions. |
| Vertical Integration into Storage | Combining ocean energy with battery storage enhances grid stability and ensures continuous, reliable power output. |
| Green Certification Program | Achieving recognized certifications for marine energy devices builds trust and facilitates market acceptance among utility buyers. |
Research Approach
Independent corroboration across primary interviews, national energy agency data, and academic research underwrites the qualitative findings of this study. Primary data collection involved conversations with utility planning officers, marine engineers, project developers, and regulatory affairs specialists. Secondary validation drew from IEA reports, company financial filings, and academic literature on marine hydrodynamics, triangulating insights through both bottom-up and top-down approaches.
Rate-of-change decomposition framed the forecast framework, projecting market evolution across the analysis window. The model segmented by technology (tidal, wave, OTEC), application (coastal infrastructure, marine platforms), end-user (utilities, maritime operators), and regional regulatory frameworks. Compound annual growth rates were derived from historical trends and projected market drivers, with government policy changes and technology readiness levels serving as key industry-specific forecast inputs.
Policy shifts, technological breakthroughs, and capital expenditure volatility are the dominant revision risks for market forecasts. Forecasts reflect assumptions regarding regulatory support and commercialization pathways. Practitioners should monitor project financing success rates and operational longevity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Wave Energy Converter Market
Renewable Energy
Hybrid Power System Market
Renewable Energy
North America Renewable Energy Market
Renewable Energy
Solar Highway Market
Renewable Energy
Africa Renewable Energy Market
Renewable Energy
North America Ocean Power Market
Renewable Energy
Green Renewable Energy Market
Renewable Energy
Global Organic Rankine Cycle Market
Renewable Energy
Renewable Energy Consulting Market
Renewable Energy
Nigeria Renewable Energy Market
Renewable Energy
Zimbabwe Renewable Energy Market
Renewable Energy
Indonesia Renewable Energy CAPEX Market
Renewable Energy
Wind and Solar Hybrid Monitoring Systems Market
Renewable Energy
Hydrokinetic Converters Market
Renewable Energy
Solar Ceiling Fans Market
Renewable Energy
Botswana Renewable Energy Market