
 Vitrectomy Devices Market | 2026-2036
Vitrectomy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Vitrectomy Devices Market Intelligence
A shortage of fellowship-trained vitreoretinal surgeons is unwinding access to advanced posterior segment care across multiple healthcare systems. Alcon Inc. leverages its integrated portfolio spanning vitrectomy machines, probes, and disposables to sustain installed-base loyalty in high-volume surgical centers. Bausch + Lomb competes through specialized focus on disposable consumables that reduce cross-contamination risk in busy operating rooms. Carl Zeiss Meditec AG anchors its position with precision optics and intraoperative visualization systems that differentiate complex membrane peeling workflows.
Vitrectomy devices constitute ophthalmic surgical instruments designed to remove vitreous humor from the posterior chamber while maintaining intraocular pressure, typically operating at cut rates exceeding 5,000 cuts per minute with 23-gauge, 25-gauge, or 27-gauge probe diameters. Their primary commercial purpose centers on enabling minimally invasive posterior segment surgery for retinal detachment, diabetic retinopathy, and macular hole repair. The 25-gauge and 27-gauge technology segments lead procedural adoption due to sutureless wound architecture and reduced surgical trauma, while 23-gauge systems retain dominance in complex cases requiring instrument rigidity. Application demand clusters in diabetic retinopathy as population-level metabolic disease burdens expand, with macular hole procedures representing a mature but stable volume pool.
The FDA's 510(k) premarket notification framework governs device clearance timelines in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for Class IIa and IIb ophthalmic surgical instruments entering European markets. ISO 10993 biocompatibility standards and IEC 60601 electrical safety specifications shape material selection and design validation protocols across manufacturing operations. Stakeholders must monitor evolving reimbursement thresholds for office-based versus hospital-based vitrectomy procedures, as site-of-service differentials increasingly determine capital equipment purchasing decisions and disposable utilization rates.
Market Dynamics
The vitrectomy devices market is experiencing structural pressure from the migration of complex retinal procedures into ambulatory surgery centers, a site-of-service shift that compresses capital equipment cycles and elevates disposable utilization rates. This transition demands reconfigured procurement frameworks and tighter integration between machine platforms and single-use consumables.
Growth Catalysts
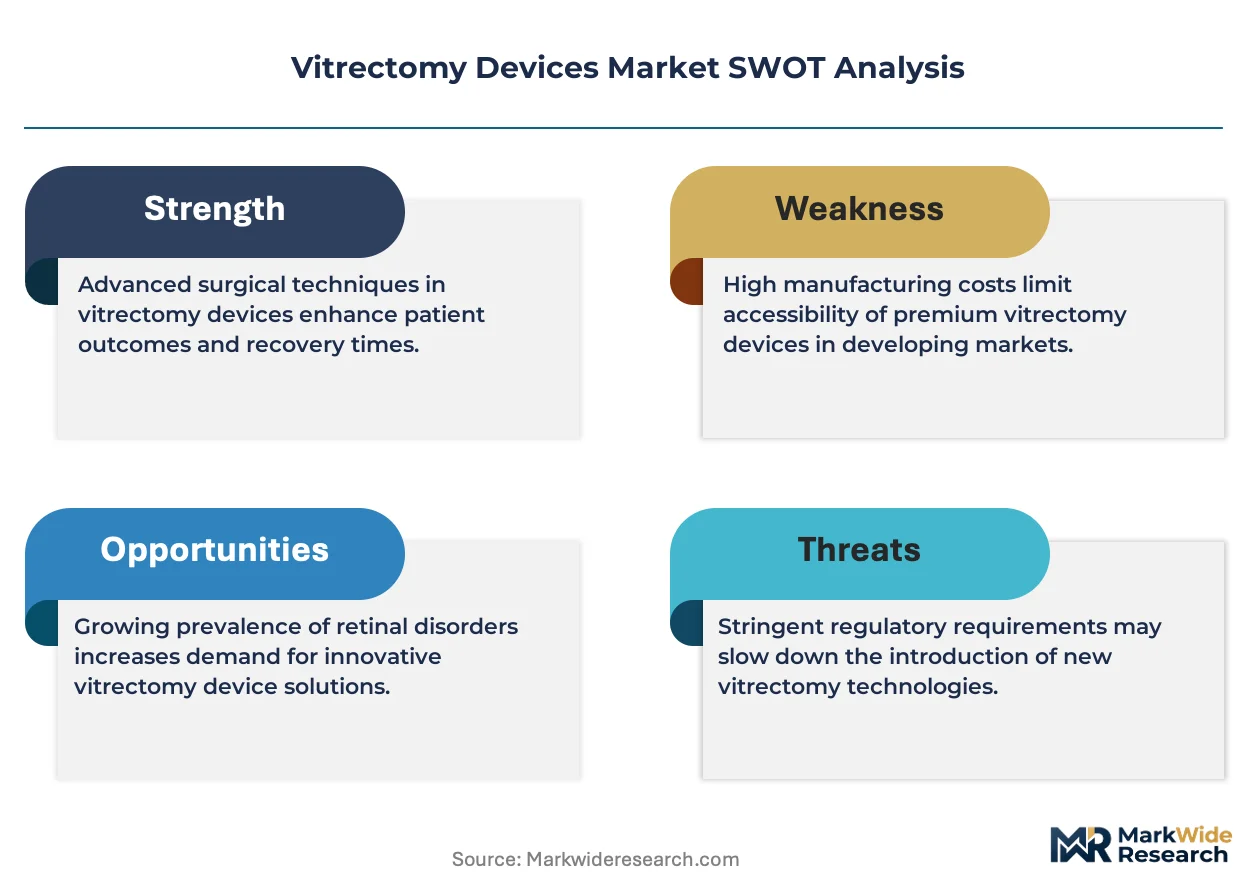
- EU Medical Device Regulation:The MDR's enhanced clinical evidence requirements for Class IIb ophthalmic surgical instruments is accelerating consolidation among manufacturers capable of funding robust post-market surveillance systems.
- Diabetic retinopathy procedural volumes:Expanding metabolic disease burdens across aging populations in the United States and Japan are sustaining demand for posterior segment surgical intervention.
- 27-gauge probe technology:Sutureless wound architecture and reduced surgical trauma are driving adoption in high-volume surgical centers seeking faster patient throughput.
Market Restraints
- Fellowship-trained surgeon scarcity:Limited pipeline of vitreoretinal specialists constrains procedural capacity across multiple healthcare systems regardless of equipment availability.
- Silicone oil and tamponade agent costs:Input price volatility for specialized ocular endotamponades compresses margin structures in complex retinal detachment repair workflows.
- ISO 10993 biocompatibility compliance:Extensive material validation protocols for probe coatings and disposable polymers extend product development timelines.
Strategic Opportunities
- Office-based vitrectomy reimbursement expansion:Shifting payment differentials between hospital outpatient departments and ambulatory surgery centers create procurement advantages for integrated platform vendors.
- Intraoperative OCT convergence:Integration of optical coherence tomography with vitrectomy visualization systems enables real-time membrane characterization during macular hole repair.
- Brazil and Mexico surgical infrastructure:Underpenetrated vitreoretinal service networks in Latin American metropolitan centers present equipment placement opportunities.
Industry Challenges
- 510(k) clearance timeline variability:FDA premarket notification review durations for novel probe designs create revenue recognition uncertainty.
- Installed-base lock-in effects:Surgeon training investments and disposable compatibility requirements complicate competitive displacement of entrenched machine platforms.
- Supply chain reconfiguration:Concentration of precision probe manufacturing in specific industrial clusters exposes distributors to geopolitical disruption risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vitrectomy Devices Market |
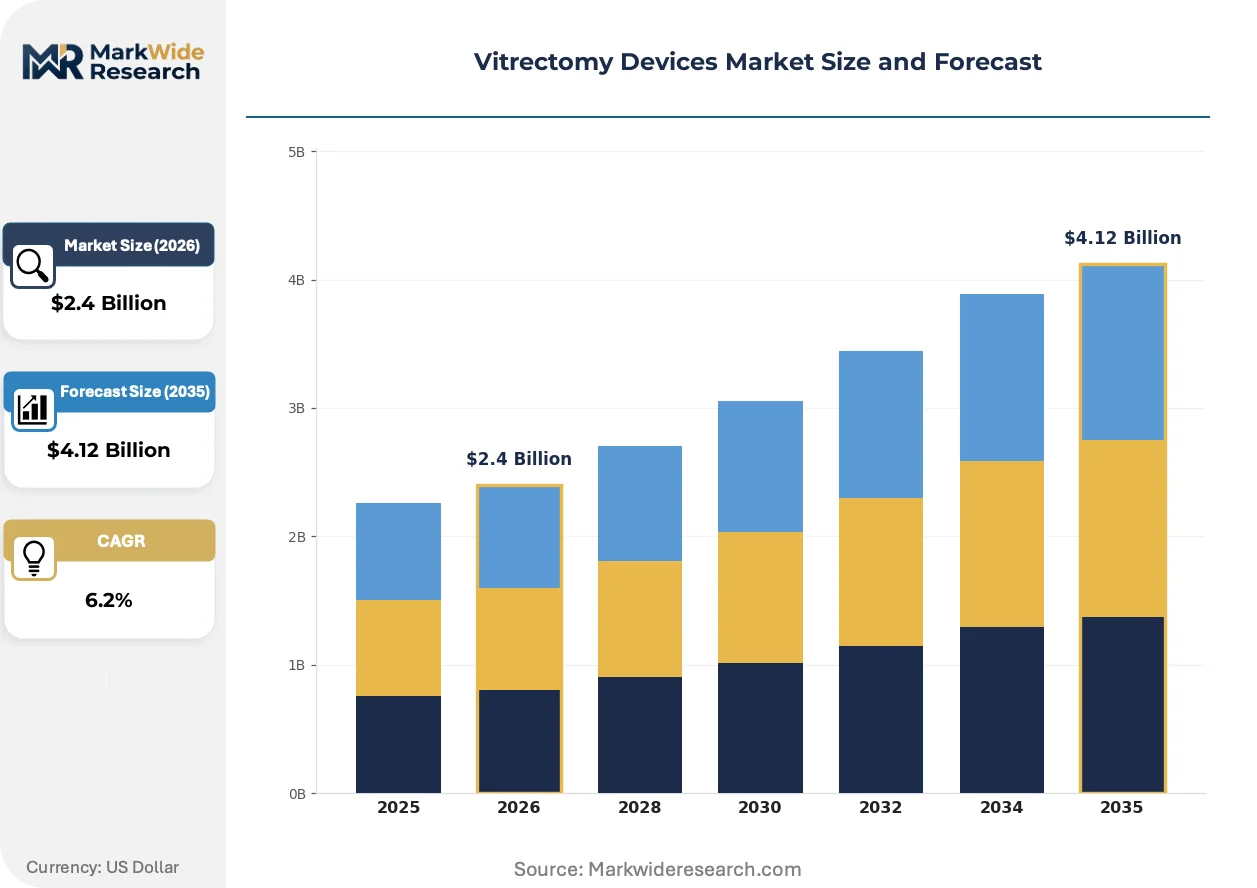
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.12 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
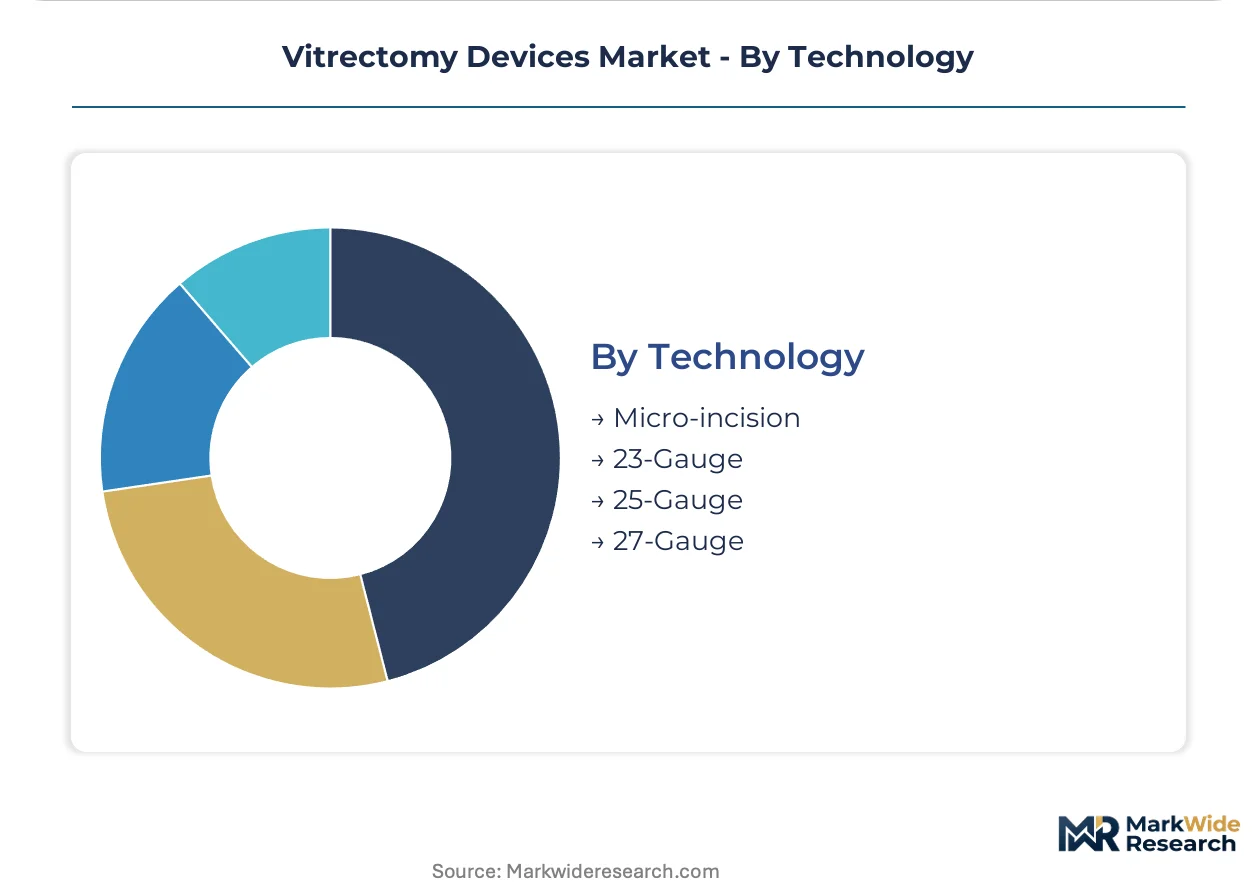
| Segmentation | Device Type: Light Pipe, Infusion Pumps, Vitrectomy Probes, Endolaser Units Application: Retinal Detachment, Diabetic Retinopathy, Macular Hole, Epiretinal Membrane End User: Hospitals, Specialty Clinics, Ambulatory Surgery Centers, Research Institutes Technology: Micro-incision, 23-Gauge, 25-Gauge, 27-Gauge |
| Companies Covered | Alcon Inc., Carl Zeiss Meditec AG, Bausch + Lomb, Johnson & Johnson Vision, BVI, NIDEK Co. Ltd., Geuder AG, HOYA Surgical Optics, D.O.R.C. Holding B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vitrectomy Devices Market Strategic Shifts & Innovations
Technological differentiation in vitrectomy platforms is increasingly anchored to intraoperative visualization capabilities and disposable ecosystem integration rather than cut-rate specifications alone. Device manufacturers are prioritizing software-enabled workflow automation and seamless data capture to secure high-volume surgical center commitments.
High-speed vitrectomy probe technology is bifurcating between ultra-high-cut-rate systems exceeding 10,000 cuts per minute for membrane dissection and specialized lower-cut-rate probes optimized for dense vitreous hemorrhage evacuation. Ambulatory surgery centers in the United States are adopting dual-probe configurations to accommodate diverse case mixes. This technological divergence is compressing single-platform vendor margins while rewarding integrated portfolio suppliers.
The FDA's 510(k) premarket notification framework for ophthalmic surgical devices is tightening evidentiary standards for substantial equivalence claims involving modified probe geometries. Manufacturers must now submit comprehensive bench testing and clinical performance data for gauge transitions. Small-cap entrants lacking regulatory affairs infrastructure are retreating from the United States market, ceding share to established platform holders.
Site-of-service economics are restructuring purchasing authority within integrated delivery networks. Hospital procurement committees are consolidating vitrectomy machine decisions across multiple ambulatory surgery center affiliates, displacing individual surgeon preference. This concentration is most visible in United States metropolitan markets where health system consolidation has created multi-facility retinal service lines with standardized equipment protocols.
Vitrectomy Devices Market Segmentation
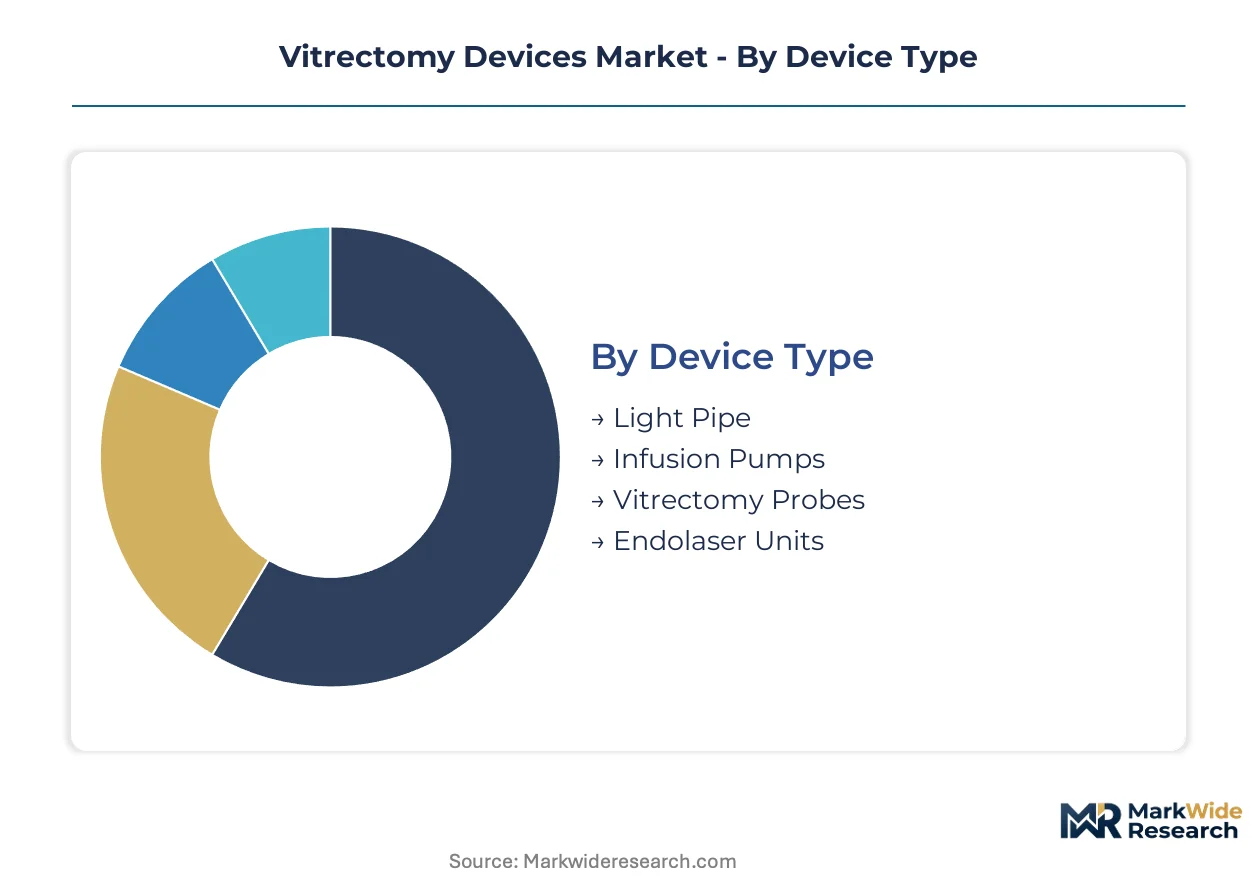
Segmentation in vitrectomy devices reveals how procurement authority, clinical workflow requirements, and reimbursement economics fragment purchasing decisions across healthcare delivery settings. Manufacturers must align platform configurations to distinct capital cycles and disposable utilization patterns.
Device Type:
Margin pools concentrate in integrated probe-pump systems where recurring disposable revenue anchors long-term customer value.
- Vitrectomy Probes:Precision-engineered cutting instruments operating at variable cut rates with gauge-specific port geometries. Demand clusters in high-volume ambulatory surgery centers across the United States where sutureless wound architecture accelerates patient throughput and reduces operating room occupancy costs.
- Infusion Pumps:Pressure-controlled fluid management systems maintaining intraocular stability during vitreous exchange. Japanese and German surgical centers prioritize automated pressure feedback mechanisms that reduce surgeon cognitive load during complex membrane peeling procedures.
- Light Pipe:Fiber-optic illumination instruments enabling posterior segment visualization through pars plana entry.
- Endolaser Units:Photocoagulation delivery systems integrated with vitrectomy platforms for intraoperative retinal treatment.
The dominant share belongs to Vitrectomy Probes, while Infusion Pumps are closing the gap fastest through software-enabled workflow integration.
Application:
Procedure volumes distribute according to disease prevalence demographics and reimbursement favorability for surgical versus pharmacologic intervention.
- Diabetic Retinopathy:Posterior segment surgery addressing proliferative complications and tractional detachments in metabolic disease patients. The United States and Japan sustain elevated procedural volumes through aging population disease burdens and established vitreoretinal specialist networks.
- Macular Hole:Full-thickness foveal defect repair requiring precise membrane manipulation and gas tamponade. European surgical centers in France and Germany emphasize intraoperative OCT guidance that improves anatomical closure rates and reduces reoperation frequency.
- Retinal Detachment:Rhegmatogenous and tractional detachment repair through pars plana vitrectomy with endotamponade.
- Epiretinal Membrane:Idiopathic or secondary membrane peeling to restore foveal contour and visual acuity.
Diabetic Retinopathy commands the largest procedure base, with Macular Hole exhibiting the steepest expansion trajectory as visualization technology improves surgical precision thresholds.
End User:
Site-of-service economics restructure capital equipment procurement authority toward consolidated health system committees and away from individual surgeon preference.
- Ambulatory Surgery Centers:Outpatient facilities optimized for same-day retinal procedures with compressed turnover intervals. United States metropolitan markets concentrate purchasing decisions through multi-facility integrated delivery networks that standardize machine platforms across affiliate locations.
- Hospitals:Inpatient and hospital-based outpatient departments managing complex cases requiring general anesthesia or extended monitoring. Brazilian and Mexican academic medical centers anchor regional training pipelines and sustain demand for 23-gauge systems with instrument rigidity for proliferative disease.
- Specialty Clinics:Dedicated ophthalmic surgical facilities with focused retinal service lines.
- Research Institutes:Academic and clinical research organizations evaluating novel surgical techniques and device iterations.
Ambulatory Surgery Centers have captured procedural volume leadership, while Hospitals defend position through complex case referral networks that require platform versatility.
Technology:
Gauge selection trade-offs between wound architecture, instrument rigidity, and procedural versatility determine technology adoption curves.
- 25-Gauge:Sutureless transconjunctival entry with balanced rigidity for membrane manipulation and fluidics control. United States high-volume centers adopt dual-probe configurations accommodating diverse case mixes without instrument exchange delays.
- 27-Gauge:Ultra-small incision technology minimizing surgical trauma and accelerating visual recovery. Japanese surgical centers lead adoption where patient expectations for rapid return to function drive technology preference.
- 23-Gauge:Larger bore instrumentation retaining dominance in complex proliferative cases requiring instrument stiffness.
- Micro-incision:Platform architectures enabling gauge flexibility through modular probe compatibility.
25-Gauge systems hold installed-base dominance, with 27-Gauge gaining share fastest as sutureless benefits expand addressable case volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds that in Brazil by substantial margins, reflecting divergent reimbursement structures and procurement sophistication. German surgical centers command premium positioning through integrated health system purchasing, while Japanese facilities prioritize technology density over cost minimization.
United States
Diabetic retinopathy procedural volumes and ASC migration sustain equipment demand across metropolitan markets. The FDA's 510(k) clearance pathway shapes product development timelines for domestic manufacturers. Texas and Florida surgical corridors concentrate multi-facility integrated delivery networks standardizing vitrectomy platforms.
Germany
Precision optics requirements and intraoperative OCT integration drive technology preference in academic medical centers. The EU Medical Device Regulation imposes enhanced clinical evidence standards for Class IIb ophthalmic instruments. Bavarian surgical clusters anchor regional training pipelines and sustain demand for visualization-integrated systems.
Japan
Aging demographics and proliferative diabetic retinopathy burdens expand addressable procedure volumes. PMDA regulatory frameworks govern device approval timelines for imported platforms. Tokyo-Osaka metropolitan corridors concentrate high-volume vitreoretinal specialists adopting 27-gauge sutureless technology.
Brazil
Underpenetrated vitreoretinal service networks and expanding private insurance coverage create equipment placement opportunities. ANVISA registration requirements structure market entry timelines for multinational manufacturers. São Paulo academic medical centers anchor regional training capacity and sustain demand for 23-gauge instrument rigidity.
United Kingdom
NHS procurement frameworks centralize purchasing decisions across hospital trusts and affiliated surgical centers. MHRA post-Brexit regulatory autonomy modifies device approval pathways from EU-aligned systems. London-Southeast corridor concentrates private retinal surgery volumes driving premium platform adoption.
Vitrectomy Devices Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure rather than consolidated dominance. The installed-base lock-in effects surrounding vitrectomy machines protect incumbent positions while disposable consumables attract specialized entrants. Three archetypes predominate: integrated platform vendors spanning machines and disposables, precision optics specialists anchoring visualization workflows, and regional disposable manufacturers competing on cross-contamination protocols. M&A activity concentrates among platform vendors seeking visualization technology, while strategic partnerships proliferate between machine manufacturers and intraoperative imaging developers.
Within the integrated platform tier, Alcon Inc. and Bausch + Lomb occupy positions exemplifying machine-disposable ecosystem control, while Carl Zeiss Meditec AG anchors the precision optics archetype through visualization system differentiation. These three entities represent the dominant competitive anchors structuring procurement decisions in high-volume surgical centers.
| Leading Market Players |
|---|
| Alcon Inc. |
| Carl Zeiss Meditec AG |
| Bausch + Lomb |
| Johnson & Johnson Vision |
| BVI |
| NIDEK Co. Ltd. |
| Geuder AG |
| HOYA Surgical Optics |
| D.O.R.C. Holding B.V. |
| Others |
Cost & Logistics Intelligence
Ninety-day probe inventory cycles at United States ambulatory surgery centers compress procurement flexibility while amplifying pricing leverage for integrated platform vendors holding disposable ecosystem control. This lead-time band concentrates purchasing power among health system committees that standardize machine platforms across multi-facility networks, tightening margin structures for standalone probe manufacturers.
Pricing Analysis
United States metropolitan markets command premium positioning over Brazilian surgical centers by substantial margins, reflecting divergent reimbursement structures and procurement sophistication. Three-tier pricing structure across premium visualization-integrated systems, standard machine-disposable bundles, and economy probe-only configurations dominates capital equipment transactions. Price differentiation rests on FDA 510(k) clearance tier and installed-base compatibility guarantees. Pricing pressure stems from site-of-service economics as hospital outpatient departments lose volume to ambulatory surgery centers with compressed capital cycles. High-volume integrated delivery networks exhibit lowest price sensitivity, while independent specialty clinics in Latin America face acute budget constraints.
Supply Chain Analysis
Strategic stockpile preferences dominate Japanese and German surgical centers facing precision probe lead-time volatility, while United States facilities maintain lean just-in-time inventory exposed to disruption. Manufacturing concentration clusters in Germany for precision optics, the United States for vitrectomy machine assembly, and Japan for high-gauge probe fabrication. Raw material dependencies center on medical-grade stainless steel alloys, fiber-optic illumination bundles, and biocompatible polymer coatings. Single-source vulnerability concentrates in precision probe tip grinding equipment. Distribution runs through authorized surgical device distributors with field service engineering capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vitrectomy devices market is accelerating through 27-gauge sutureless technology disruption and EU Medical Device Regulation consolidation, creating asymmetric returns for platform-integrated vendors versus standalone disposable manufacturers.
For Market Incumbents: Fortify installed-base loyalty through backward integration into precision probe manufacturing and captive supply of 27-gauge consumables. Alcon and Bausch + Lomb should deepen software-enabled workflow automation to displace visualization specialists like Carl Zeiss Meditec from high-volume surgical centers. The priority lever centers on multi-facility integrated delivery network contracts that standardize machine platforms across affiliate locations.
For New Entrants and Emerging Players: Lead with disposable probe compatibility for entrenched machine platforms rather than attempting full-system displacement. São Paulo and Mexico City academic medical centers represent the most penetrable geography, with demand for 23-gauge instrument rigidity in proliferative diabetic retinopathy cases. The go-to-market angle should emphasize cross-contamination protocols and single-use sterility guarantees that differentiate from established vendors.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across intraoperative OCT visualization systems as FDA 510(k) evidentiary standards tighten for substantial equivalence claims. Long-term viability favors integrated platform vendors with recurring disposable revenue anchoring customer lifetime value. Acquisition targets should display installed-base scale in United States ambulatory surgery centers or proprietary visualization software. The signal to watch is site-of-service reimbursement differentials between hospital outpatient departments and ambulatory surgery centers.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerated timelines for probe gauge modifications strengthen United States market entry. |
| Intraoperative OCT Integration | Real-time membrane visualization during macular hole repair differentiates premium platforms. |
| Ambulatory Surgery Center Partnership | Multi-facility standardization contracts displace individual surgeon preference in procurement. |
| Disposable Ecosystem Expansion | Recurring probe revenue anchors long-term customer value against capital equipment cyclicality. |
| Brazilian Market Registration | ANVISA compliance opens underpenetrated vitreoretinal service networks in São Paulo corridors. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with vitreoretinal surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation through FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU Medical Device Regulation submission documentation. Bottom-up procedural volume modeling triangulated against top-down equipment shipment estimates.
Across the projection horizon, the analytical framework segmented by device type, application, end user, technology gauge, and geographic regulatory cluster. CAGRs derived from installed-base expansion rates and disposable utilization intensity per procedure. Forecast inputs incorporated diabetic retinopathy prevalence trajectories, fellowship-trained surgeon pipeline constraints, and site-of-service migration patterns.
Underlying assumptions cover reimbursement stability for outpatient retinal procedures, with deviation risk concentrated in FDA 510(k) timeline variability and silicone oil input price volatility. Revision becomes warranted when ambulatory surgery center procedural volume crosses thresholds that restructure capital equipment procurement authority.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Italy Spinal Surgery Devices Market
Medical Devices
IV Fluid Transfer Drugs Devices Market
Medical Devices
Organ on a Chip Kit Market
Medical Devices
Minimally Invasive Neurosurgery Devices Market
Medical Devices
Vein Illumination Devices Market
Medical Devices
Veterinary X-Ray Illuminators Market
Medical Devices
Soft Tissue Markers Market
Medical Devices
Oxygen Therapy Devices Market
Medical Devices
Pressure Ulcer Detection Devices Market
Medical Devices
Operating Room Integration Market
Medical Devices
Ingestible Smart Pills Market
Medical Devices
China Drug Delivery Devices Market
Medical Devices
Urolithiasis Management Devices Market
Medical Devices
Global Anti-Snoring Devices and Snoring Surgery Market
Medical Devices
Australia Ultrasound Devices Market
Medical Devices
Water Flosser Market