
 Italy Spinal Surgery Devices Market | 2026-2036
Italy Spinal Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Spinal Surgery Devices Market Foresight
EU MDR transition deadlines are restructuring how Italian hospitals evaluate spinal implant suppliers, pushing procurement teams toward manufacturers with robust clinical documentation and notified body certifications. Medtronic PLC leverages its extensive European regulatory affairs infrastructure to sustain market presence across Italy's largest university hospitals. Johnson & Johnson competes through its specialized DePuy Synthes division, which anchors its Italian operations with dedicated spine training centers in the north.
Spinal surgery devices comprise implantable hardware and associated instruments designed to stabilize, decompress, or fuse vertebral segments, typically manufactured from titanium alloys or bio-absorbable polymers to achieve osseointegration while minimizing post-operative imaging interference. Pedicle screws and fusion devices dominate procedure volumes in Italy, though minimally invasive surgery instrumentation captures expanding margin pools as surgeons seek reduced tissue disruption and faster recovery protocols. Titanium-based spinal cages lead material selection for lumbar fusions due to favorable strength-to-weight ratios and established biocompatibility profiles.
Italy's national pharmaceutical regulator, AIFA, coordinates with the Ministry of Health to enforce EU MDR requirements for high-risk implantable devices, while regional health authorities in Lombardy and Veneto layer additional tender specifications that favor suppliers with local technical support. BSI Italy and other notified bodies conduct conformity assessments that determine market access timelines for new device introductions. Stakeholders must monitor how regional procurement consortia consolidate purchasing power and whether reimbursement rate adjustments under the national essential levels of care framework alter site-of-service economics for complex spine procedures.
Market Dynamics
EU MDR compliance deadlines are compressing supplier qualification timelines across Italian hospital procurement offices, forcing rapid consolidation of approved vendor lists for implantable spinal hardware.
Growth Catalysts
- Aging demographics:Italy's 65-plus population cohort drives sustained demand for degenerative spine interventions, particularly lumbar fusion procedures concentrated in Lombardy and Emilia-Romagna.
- Minimally invasive surgery instrumentation:Smaller incision platforms reduce hospital length-of-stay metrics, aligning with regional health authority cost-containment targets under the national essential levels of care framework.
- EU MDR Article 117:Streamlined conformity assessment pathways for well-established device categories accelerate market access for titanium alloy spinal cages with existing clinical documentation.
Market Restraints
- Titanium alloy input costs:Price volatility in aerospace-grade titanium sponge concentrates margin pressure on domestic device assemblers lacking long-term supply contracts.
- Notified body capacity constraints:BSI Italy and TÜV SÜD Italia face extended audit queues, delaying CE marking timelines for novel bio-absorbable polymer implants.
- Regional procurement consolidation:Lombardy and Veneto purchasing consortia concentrate buyer power, compressing unit pricing for standard pedicle screw systems.
Strategic Opportunities
- Southern Italy expansion:Campania and Sicily exhibit lower penetration rates for motion-preserving disc replacement technologies relative to northern benchmarks.
- Robotic navigation integration:Convergence of optical tracking systems with pre-operative planning software creates premium positioning for university hospitals in Milan and Bologna.
- Day-surgery spine protocols:AIFA reimbursement adjustments for ambulatory cervical procedures open channel innovation through specialized outpatient surgical centers.
Industry Challenges
- Surgeon training deficits:Limited fellowship positions in minimally invasive techniques constrain adoption velocity outside established orthopedic hubs.
- Legacy ERP integration:Hospital information systems in smaller provincial facilities require costly middleware upgrades to support implantable device traceability mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Spinal Surgery Devices Market |
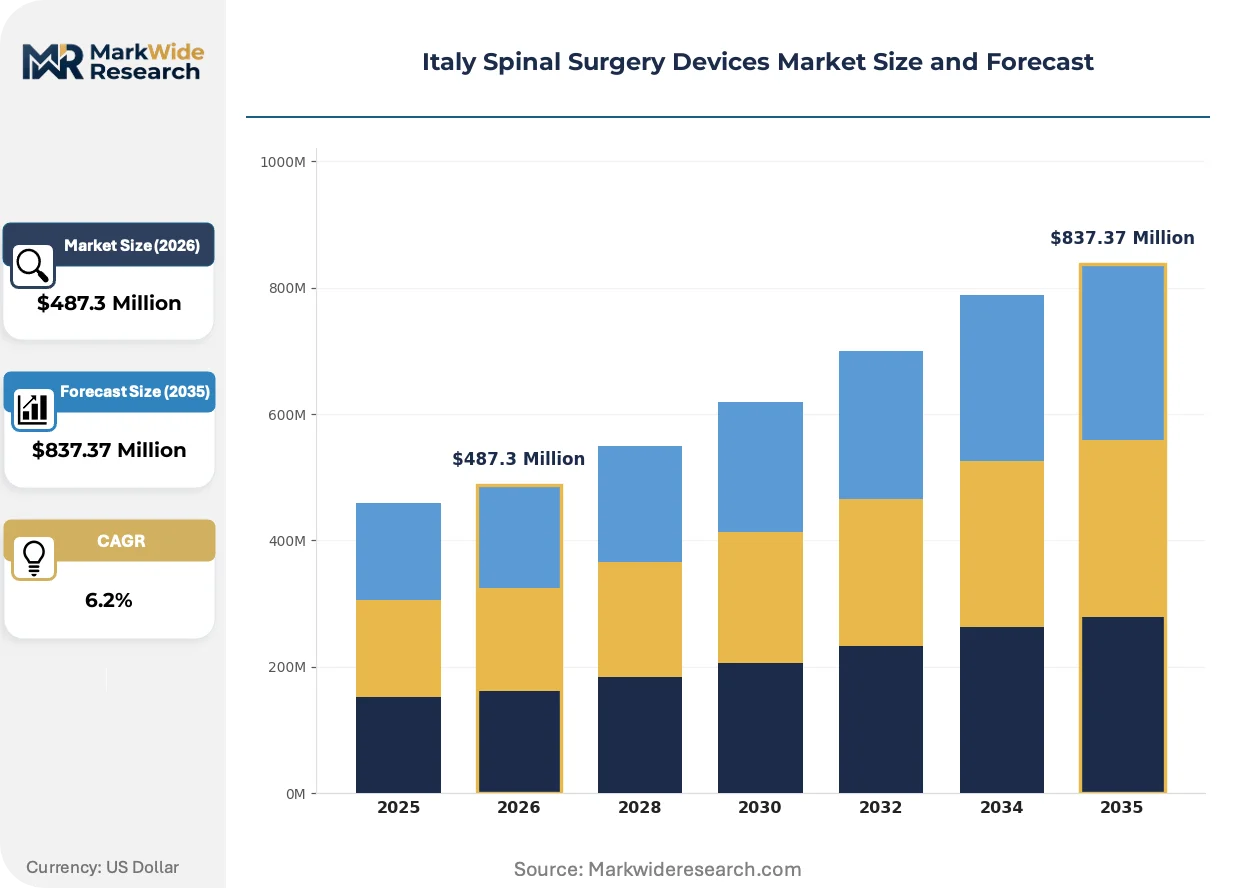
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $837.37 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Pedicle Screws, Spinal Cages, Discectomy Instruments, Fusion Devices End User: Hospitals, Ambulatory Surgery Centers, Orthopedic Clinics, Rehabilitation Centers Procedure Type: Minimally Invasive Surgery, Traditional Open Surgery, Decompressive Surgery, Revision Surgery Material: Stainless Steel, Titanium, Bio-Absorbable Polymers, Composite Materials |
| Companies Covered | Medtronic PLC, Johnson & Johnson, Stryker Corporation, Zimmer Biomet, Globus Medical Inc., NuVasive, Orthofix Holdings Inc., Alphatec Spine Inc., SeaSpine Holdings Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Spinal Surgery Devices Market Shifts & Advancements
Device manufacturers are racing to embed connectivity and advanced materials into spinal hardware while procurement offices rewrite vendor scorecards around clinical evidence depth.
Patient-specific titanium cages derived from pre-operative CT segmentation are integrating into complex deformity correction workflows at Policlinico di Milano and Istituto Ortopedico Rizzoli. These additive-manufactured implants match individual vertebral anatomy, reducing operative time and blood loss in multi-level fusions. The technology is integrating orthopedic biomechanics research with hospital-based 3D printing capabilities, compressing the traditional device supply chain into localized production nodes.
EU MDR Annex XIV post-market clinical follow-up requirements now mandate systematic collection of real-world performance data for Class III implantable devices. Manufacturers must submit periodic safety update reports to notified bodies, driving investment in clinical affairs infrastructure. Spinal fusion systems with legacy predicate approvals face the steepest documentation burdens, advantaging firms with established European regulatory teams.
Regional purchasing consortia in northern Italy now weight technical support proximity heavily in tender evaluations, displacing pure price-based selection. Hospital supply chain managers prioritize vendors with same-day instrument loaner availability and on-site sterilization validation. This behavioral shift concentrates contract awards among suppliers maintaining dedicated logistics operations across the Po Valley industrial corridor.
Italy Spinal Surgery Devices Market Segmentation
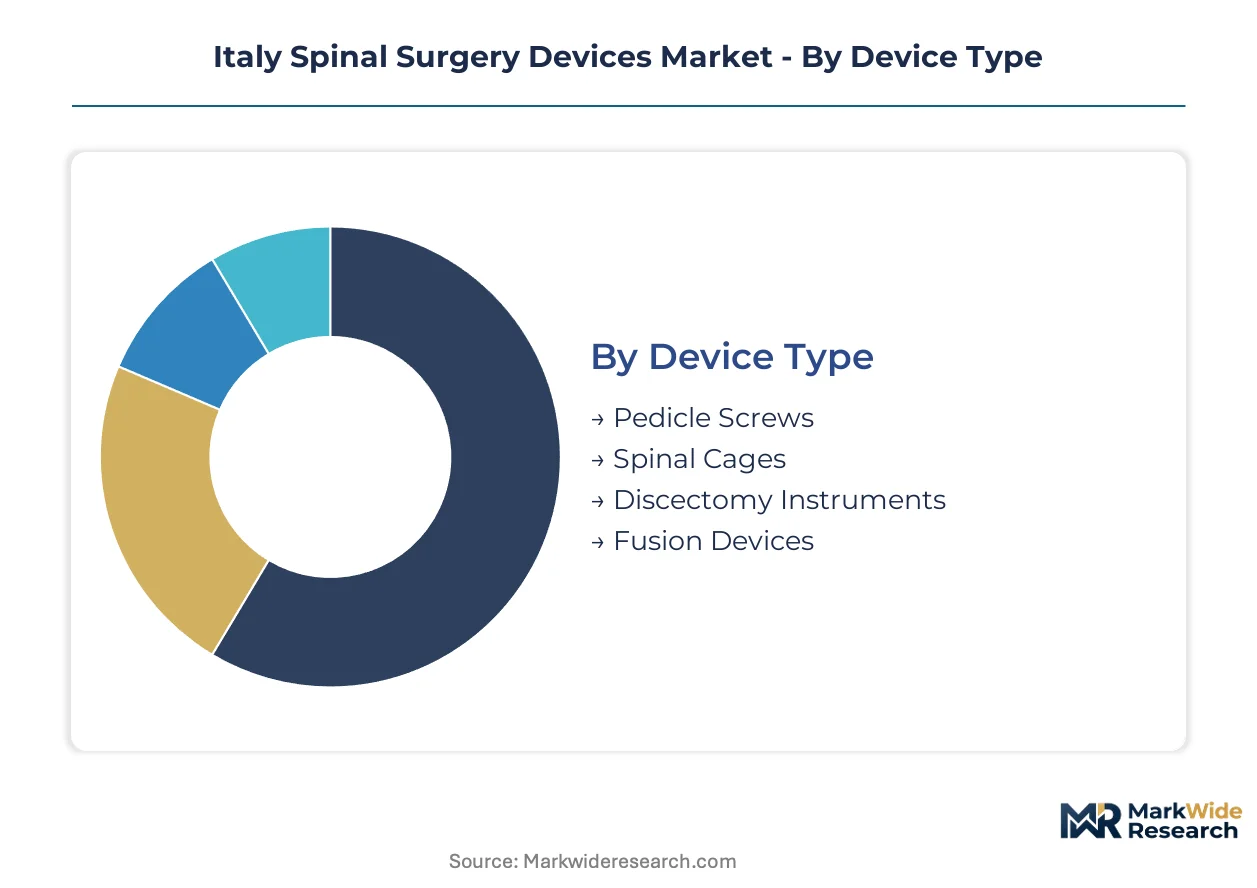
Spinal surgery devices fragment across four intersecting dimensions that determine procurement priorities, reimbursement pathways, and supplier qualification requirements in Italy's regulated healthcare environment. Understanding these segment boundaries clarifies how EU MDR compliance costs concentrate in high-risk implantable categories versus lower-classification instruments.
Device Type:
Pedicle screws and spinal cages absorb disproportionate procurement investment due to their implantable classification and extended liability exposure under EU MDR Annex VIII.
- Pedicle Screws:Titanium alloy constructs with polyaxial heads enable multi-planar rod attachment for deformity correction. Lombardy's university hospitals drive specification standards, demanding extended fatigue testing documentation that smaller notified bodies struggle to validate.
- Spinal Cages:Interbody fusion devices manufactured from porous titanium or PEEK polymer maintain structural integrity under axial loading. Emilia-Romagna's orthopedic hubs favor lordotic-profile designs for anterior lumbar approaches, compressing procurement cycles for geometrically differentiated suppliers.
- Discectomy Instruments:Tubular retractors and Kerrison rongeurs for nerve root decompression.
- Fusion Devices:Rods, plates, and cross-connectors completing construct stability.
Today's leader: Pedicle Screws. Tomorrow's challenger: Spinal Cages.
End User:
Site-of-service economics diverge sharply between capital-intensive hospitals and emerging outpatient channels reshaping cervical procedure volumes.
- Hospitals:Academic medical centers in Milan and Bologna anchor complex deformity and revision case volumes. These institutions maintain dedicated spine units with intraoperative neuromonitoring capabilities that ambulatory settings cannot replicate.
- Ambulatory Surgery Centers:Day-case cervical discectomies and single-level lumbar decompressions migrate to specialized outpatient facilities. Veneto's regional health authority has piloted bundled reimbursement for these procedures, accelerating capital deployment into standalone surgical centers.
- Orthopedic Clinics:Private practice settings for diagnostic workup and post-operative rehabilitation.
- Rehabilitation Centers:Post-surgical physical therapy and pain management services.
Hospitals retain the highest implantable device spend per procedure, though ambulatory centers are climbing the fastest on expanded cervical case eligibility.
Procedure Type:
Surgical approach selection determines instrument complexity, operative duration, and subsequent reimbursement tier under Italy's DRG-based hospital financing.
- Minimally Invasive Surgery:Tubular retractor systems and percutaneous screw placement reduce paraspinal muscle disruption. Surgeon training deficits outside northern hubs constrain penetration in Campania and Sicily.
- Traditional Open Surgery:Midline approaches with bilateral muscle stripping remain standard for multi-level fusions and severe deformity cases. Istituto Ortopedico Rizzoli maintains Europe's largest open surgery fellowship pipeline.
- Decompressive Surgery:Laminectomy and foraminotomy without fusion for stenosis management.
- Revision Surgery:Hardware removal and reconstruction following pseudarthrosis or adjacent segment degeneration.
Minimally invasive platforms command premium pricing, while traditional open procedures retain volume dominance in complex deformity correction.
Material:
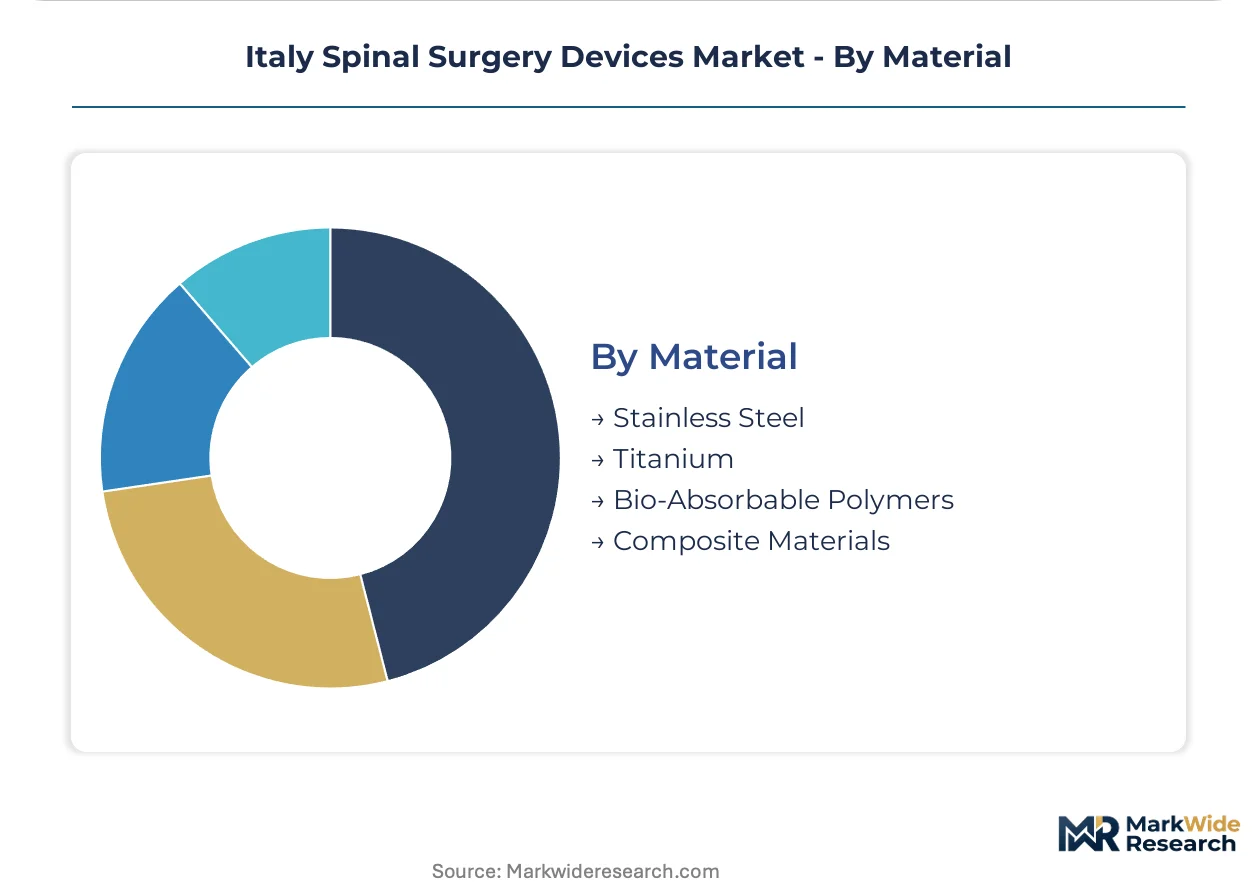
Biocompatibility profiles and imaging compatibility drive material selection, with titanium alloys establishing clinical reference standards for load-bearing applications.
- Titanium:Grade 5 Ti-6Al-4V ELI dominates spinal cage and screw manufacturing due to favorable osseointegration kinetics and MRI artifact reduction. Aerospace-grade sponge supply constraints from Ukrainian and Russian sources have compressed margins for European device assemblers.
- Bio-Absorbable Polymers:PLGA and PCL constructs for temporary fixation eliminate secondary removal surgeries. Extended biodegradation timelines and inflammatory response variability have limited Italian adoption to pediatric scoliosis applications at Policlinico di Milano.
- Stainless Steel:Cost-effective alternative for temporary external fixation and certain rod constructs.
- Composite Materials:Carbon fiber reinforced PEEK for radiolucent instrumentation.
Titanium maintains structural dominance in load-bearing segments, while bio-absorbable polymers represent the steepest expansion trajectory in pediatric and sports medicine niches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized orthopedic surgeons and neurosurgical fellowship programs cluster disproportionately in northern Italy's industrial corridor, anchoring procedure volume concentration and device procurement sophistication.
Lombardy
Milan's Policlinico di Milano and IRCCS Galeazzi Sant'Ambrogio drive demand for patient-specific titanium cages and robotic navigation platforms. AIFA coordinates with Lombardy's regional health authority to enforce EU MDR post-market surveillance for Class III implants. The metropolitan Milan cluster concentrates additive manufacturing partnerships between university hospitals and device suppliers.
Emilia-Romagna
Bologna's Istituto Ortopedico Rizzoli maintains Europe's largest open surgery fellowship pipeline, sustaining demand for complex deformity correction hardware. Regional tender specifications under Emilia-Romagna's purchasing consortia weight technical support proximity heavily in vendor evaluations. The Bologna-Modena corridor anchors specialized spine training centers operated by multinational device manufacturers.
Veneto
Verona and Padua university hospitals pilot bundled reimbursement for ambulatory cervical procedures, accelerating migration to day-surgery protocols. Veneto's regional health authority layers additional procurement requirements favoring suppliers with local sterilization validation capabilities. The Po Valley industrial corridor supports dedicated logistics operations for same-day instrument loaner availability.
Piedmont
Turin's Molinette Hospital and Città della Salute complex sustain volume for revision surgery hardware following adjacent segment degeneration cases. EU MDR notified body audits from BSI Italy concentrate compliance activity in this northern hub. The Turin-Milan axis facilitates cross-border regulatory coordination for titanium alloy supply chain security.
Campania
Naples and surrounding provinces exhibit lower penetration rates for motion-preserving disc replacement technologies relative to northern benchmarks. AIFA reimbursement rate adjustments under the national essential levels of care framework create site-of-service economics challenges for complex procedures. The southern expansion opportunity concentrates training investments from device manufacturers seeking to bridge adoption gaps.
Italy Spinal Surgery Devices Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Italy's regulated procurement environment, where EU MDR compliance infrastructure determines vendor list eligibility. The market structure consolidates around multinational conglomerates with dedicated European regulatory affairs teams, mid-cap specialists with niche material expertise, and regional distributors serving provincial hospital networks. Three strategic archetypes dominate: integrated spine platforms with training academy investments, titanium alloy specialists with aerospace supply contracts, and robotic navigation integrators targeting university hospital capital budgets. Competitive moves concentrate on M&A for clinical data portfolios and strategic partnerships with northern Italian purchasing consortia.
Within the integrated platform tier, Medtronic PLC and Johnson & Johnson exemplify archetypes anchored by extensive notified body certification infrastructure and dedicated Italian training operations. Stryker Corporation occupies a position representing capital equipment convergence with implantable hardware, reflecting scale-driven competitive positioning in university hospital segments.
| Leading Market Players |
|---|
| Medtronic PLC |
| Johnson & Johnson |
| Stryker Corporation |
| Zimmer Biomet |
| Globus Medical Inc. |
| NuVasive |
| Orthofix Holdings Inc. |
| Alphatec Spine Inc. |
| SeaSpine Holdings Corporation |
| Others |
Supply & Pricing Matrix
Regional purchasing consortia in Lombardy and Veneto concentrate procurement volume for implantable spinal hardware, anchoring contract-based long-term offtake arrangements that favor suppliers with notified body certifications and localized technical support infrastructure. This buyer concentration compresses unit economics for standard pedicle screw systems while creating pricing premiums for patient-specific additive-manufactured cages.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates robotic navigation-integrated systems from conventional titanium constructs and basic stainless steel alternatives. Price differentiation rests on CE marking tier under EU MDR Annex VIII and surgeon training academy bundling. Cost compression in the standard tier is intensifying because regional procurement consortia consolidate purchasing power across northern Italy. Ambulatory surgery centers exhibit highest price sensitivity, while university hospitals in Milan and Bologna prioritize clinical documentation depth over unit cost.
Supply Chain Analysis
Notified body certification gating under EU MDR Article 117 concentrates qualified supplier networks among firms with established BSI Italy or TÜV SÜD Italia relationships. Titanium sponge sourcing draws from Ukrainian and Russian aerospace-grade suppliers, with device assembly anchored in Germany, Switzerland, and domestic Italian facilities. Single-source vulnerability in aerospace-grade titanium feedstock creates supply chain risk amid geopolitical disruption. Distribution runs through dedicated logistics operations across the Po Valley industrial corridor, with same-day instrument loaner availability determining hospital contract awards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
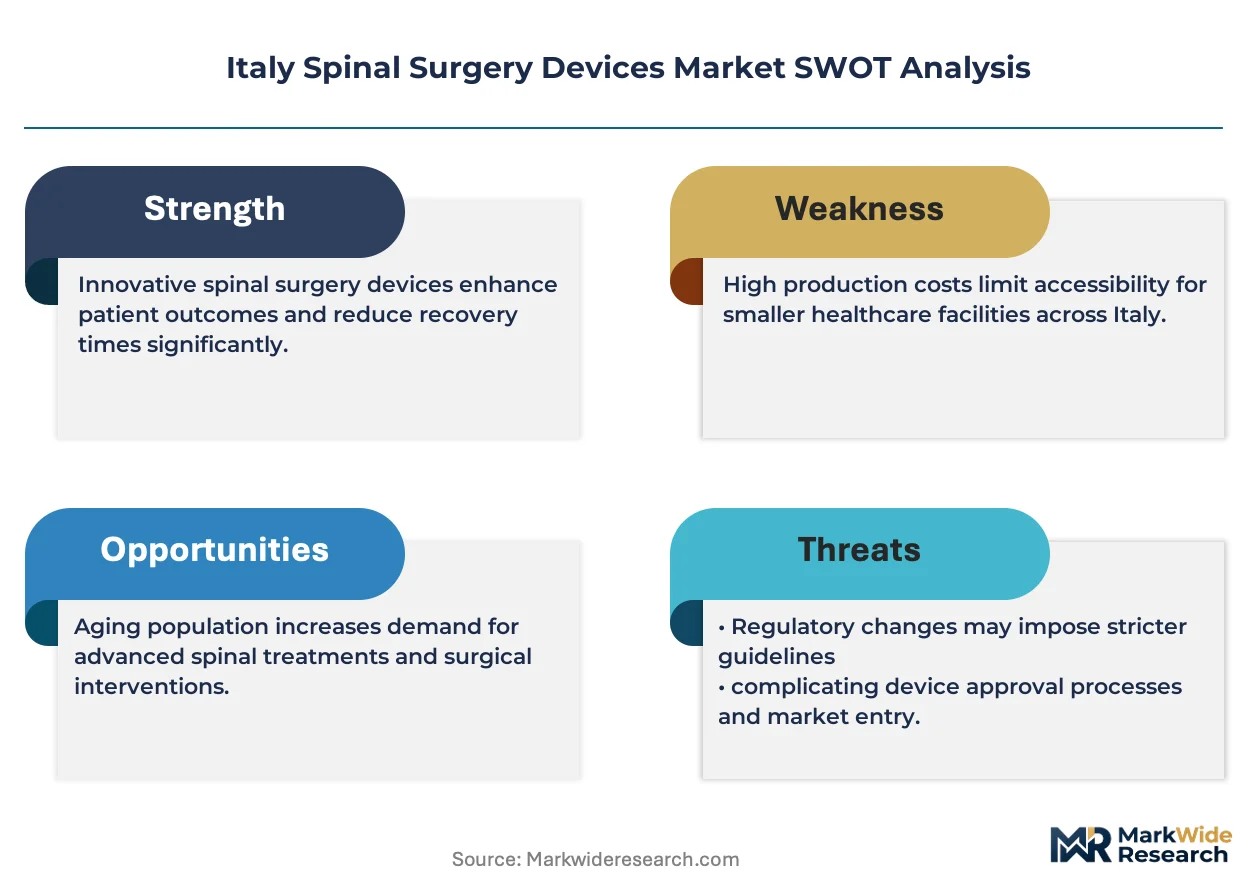
Italy's spinal surgery devices market functions as a stable compounder, with aging demographics and EU MDR compliance barriers protecting incumbent positions while constraining new entrant disruption.
For Market Incumbents: Anchor market position through backward integration into titanium alloy supply contracts and expansion of notified body certification infrastructure. Regional procurement consolidation in Lombardy and Veneto threatens margin compression, making channel control through dedicated Italian training academies the critical defensive lever. For New Entrants and Emerging Players: The price-point gap between premium robotic navigation systems and economy stainless steel constructs creates entry opportunity in mid-tier minimally invasive instrumentation. Southern Italy's Campania and Sicily regions exhibit lowest penetration rates for motion-preserving technologies, with specialized surgeon training partnerships offering the most viable go-to-market angle. For Investors and Strategic Acquirers: Multinational orthopedic conglomerates with established European regulatory affairs teams are the most active acquirers in this space, seeking clinical data portfolios to accelerate EU MDR compliance. Long-term viability favors targets with proprietary additive manufacturing capabilities for patient-specific implants. The signal to watch is AIFA reimbursement rate adjustments for ambulatory cervical procedures, which would accelerate capital deployment into outpatient surgical center channels.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Annex VIII compliance determines vendor list eligibility across Lombardy purchasing consortia. |
| Hospital System Partnership | Technical support proximity weighting in regional tenders favors suppliers with Milan-based operations. |
| Software Companion Development | Robotic navigation integration with pre-operative planning software captures premium positioning in Bologna. |
| Reimbursement Strategy | AIFA ambulatory procedure rate adjustments reshape site-of-service economics for cervical interventions. |
| Backward Integration | Captive titanium alloy supply contracts insulate margins from aerospace-grade sponge price volatility. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with spine surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers with secondary validation against EU MDR filings, AIFA reimbursement databases, hospital procurement records, and notified body audit disclosures. Bottom-up procedure volume estimates triangulated with top-down device shipment data across the analysis window.
Comparable-period anchoring linked projection assumptions to historical reference data spanning pre- and post-EU MDR implementation phases. The analytical framework modeled segmentation across device type, end user, procedure approach, and material composition, with CAGRs derived from trend extrapolation adjusted for regulatory compliance cost absorption and regional procurement consolidation velocity. Forecast inputs incorporated surgeon training pipeline constraints and additive manufacturing adoption curves.
Caveats apply where notified body capacity constraints, titanium supply disruption, or AIFA reimbursement recalibration could materially shift the outlook. Forecasts reflect documented assumptions regarding EU MDR transition timelines and regional health authority procurement behavior. A model refresh is warranted upon material change in southern Italy training investment patterns or ambulatory surgery center reimbursement eligibility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Global Augmentative and Alternative Communication (AAC) Devices Market
Medical Devices
Nephrostomy Devices Market
Medical Devices
Global Prosthetic Heart Valve Market
Medical Devices
Global Handheld Bladder Scanner Market
Medical Devices
Medical Polyimide Tubing Market
Medical Devices
Inferior Vena Cava Filters Market
Medical Devices
Global Image Guided Surgery Devices Market
Medical Devices
Global Artificial Pancreas Device System Market
Medical Devices
Sharps Destruction Device Market
Medical Devices
Support Surfaces Market
Medical Devices
United Arab Emirates Drug Delivery Devices Market
Medical Devices
Cranial Navigation Systems Market
Medical Devices
Hemodialysis Catheters Market
Medical Devices
Digital Blood Pressure Monitors Market
Medical Devices
US C-Arms Market