
 Vitrectomy Machines Market | 2026-2036
Vitrectomy Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Vitrectomy Machines Market Insights
The gap between premium integrated surgical platforms and standalone commodity vitrectomy units is expanding in measurable ways. Alcon Inc. leverages its dominance in digital imaging-integrated consoles to command the high-performance tier, while Bausch + Lomb Incorporated anchors its position through specialized fluidics control systems for complex retinal cases. Carl Zeiss Meditec AG competes on optical coherence tomography compatibility, extending its reach into academic medical centers that demand real-time tissue visualization.
Vitrectomy machines are precision ophthalmic surgical systems that remove vitreous gel from the posterior segment through controlled aspiration and cutting mechanisms, typically operating at cut rates exceeding 5,000 cuts per minute to minimize retinal traction. These devices serve the primary commercial purpose of enabling posterior segment interventions for retinal detachment, macular pathology, and diabetic complications. Tabletop machines retain the largest installed base in hospital operating rooms where space and power stability permit permanent installation, yet portable systems are gaining fastest in outpatient clinics seeking to expand procedural capacity without capital-intensive infrastructure. Digital imaging technology leads margin capture across the technology dimension because proprietary image-processing algorithms lock in consumable revenue streams.
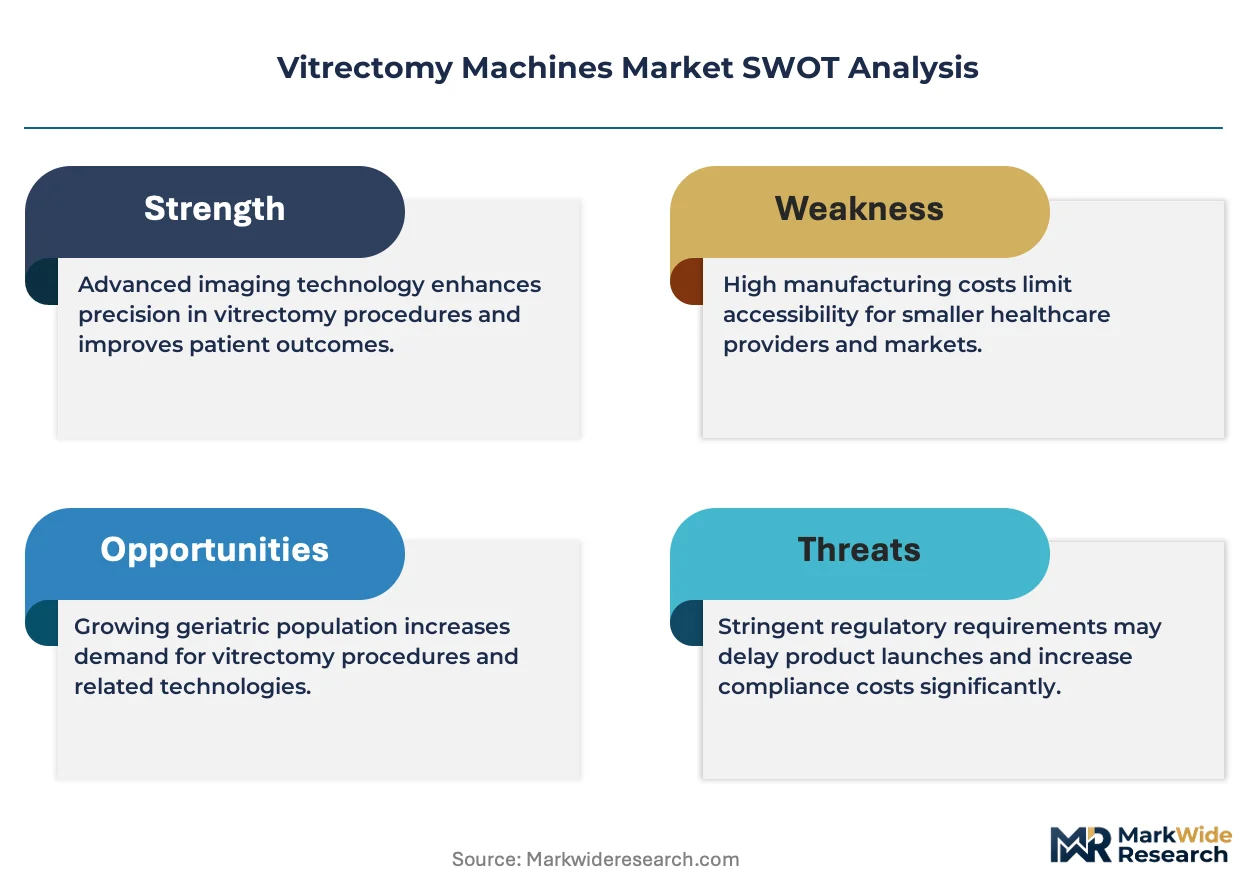
The FDA governs 510(k) clearance pathways for vitrectomy system modifications in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for Class IIb surgical equipment in Europe. Japan's PMDA maintains distinct quality management system inspections that delay market entry for non-Japanese manufacturers. Stakeholders must monitor how evolving software-as-medical-device classifications affect regulatory burden for AI-enhanced imaging modules.
Market Dynamics
The EU Medical Device Regulation is compressing certification timelines for Class IIb surgical equipment, forcing manufacturers to front-load clinical evidence generation and restructure quality management systems before market access.
Growth Catalysts
- Diabetic Retinopathy Prevalence:Rising diabetes incidence across aging populations in the United States, Germany, and Japan generates procedural volume for posterior segment interventions.
- EU MDR Harmonization:Stricter clinical evidence requirements for Class IIb surgical equipment under the EU Medical Device Regulation are consolidating compliant suppliers and accelerating replacement cycles.
- Digital Imaging Integration:Proprietary image-processing algorithms embedded in surgical consoles lock in recurring consumable revenue streams and extend equipment lifecycle value.
Market Restraints
- Precision Component Concentration:High-performance vitrectomy cutters and aspiration pumps depend on specialized suppliers concentrated in Germany and Japan, creating single-source vulnerability.
- Capital Intensity Barrier:Integrated surgical platforms require hospital infrastructure investments exceeding outpatient clinic budgets, limiting addressable market penetration.
- Technical Ceiling:Cut rate optimization above 10,000 cuts per minute encounters diminishing returns in traction reduction, constraining premium tier differentiation.
Strategic Opportunities
- Portable System Expansion:Ambulatory surgical centers in the United States seek tabletop alternatives that bypass permanent operating room infrastructure requirements.
- OCT Convergence:Real-time optical coherence tomography feed integration during vitrectomy procedures creates premium positioning for academic medical centers.
- Software-as-Medical-Device Pathway:FDA 510(k) clearance frameworks for AI-enhanced imaging modules offer faster regulatory routes than full system approvals.
Industry Challenges
- Vitreoretinal Surgeon Scarcity:Fellowship-trained specialists capable of complex posterior segment procedures concentrate in tertiary academic centers, constraining procedural capacity expansion.
- Legacy System Interoperability:Proprietary digital imaging protocols from established manufacturers block seamless third-party module integration, fragmenting installed base upgrade paths.
- Extended Certification Timelines:Japan's PMDA quality management system inspections impose 12-18 month delays for non-Japanese manufacturers seeking market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vitrectomy Machines Market |
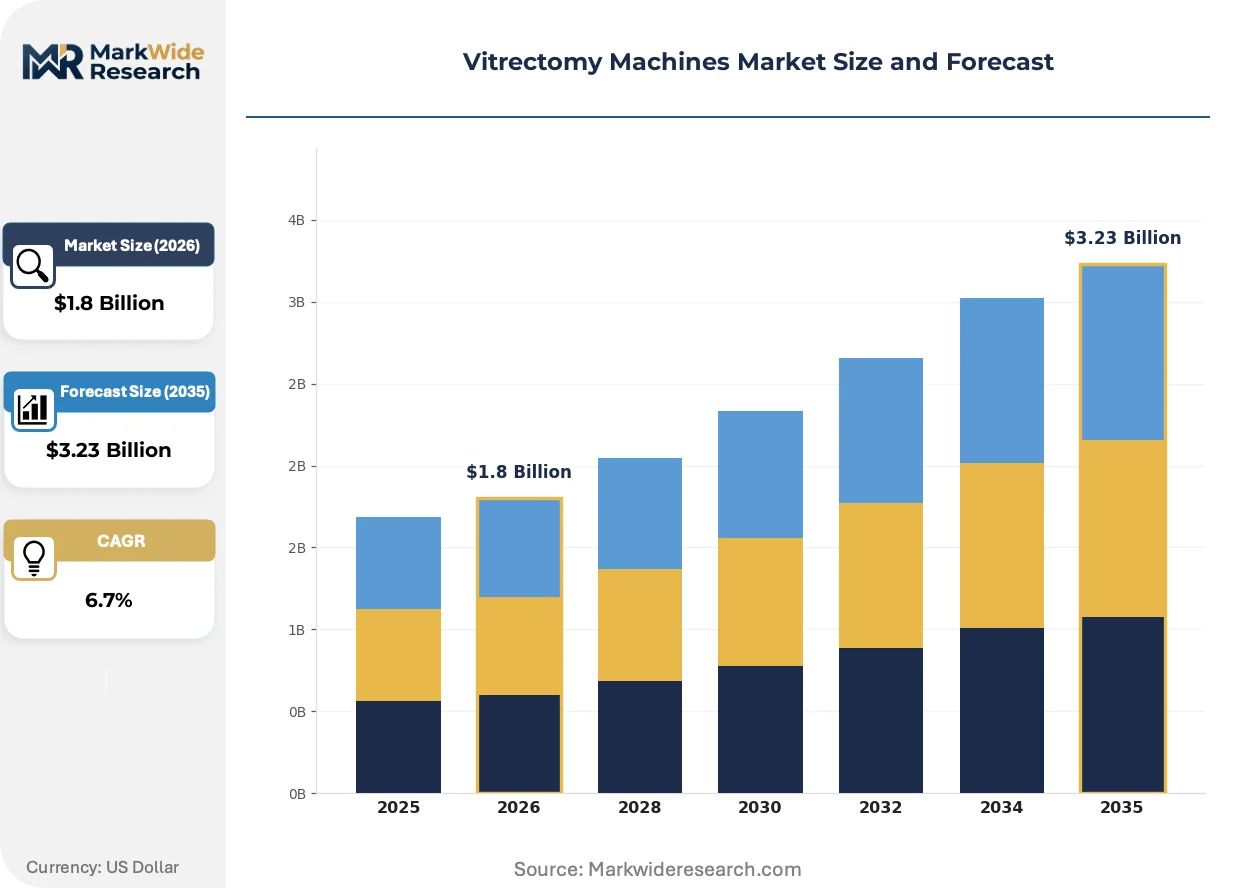
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tabletop Machines, Portable Systems, Robotic Devices, Surgical Units End User: Hospitals, Outpatient Clinics, Specialized Eye Centers, Research Laboratories Technology: Digital Imaging, Laser-Assisted, Optical Coherence Tomography, Stereoscopic Visualization Application: Retinal Detachment Repair, Macular Hole Surgery, Vitreous Hemorrhage Treatment, Diabetic Retinopathy Procedures |
| Companies Covered | Alcon Inc., Bausch + Lomb Incorporated, Carl Zeiss Meditec AG, Topcon Corporation, NIDEK Co., Ltd., Johnson & Johnson Vision, Hoya Corporation, BVI Medical, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vitrectomy Machines Market Trends and Innovations
Digital imaging integration is compressing the competitive gap between standalone vitrectomy units and full surgical platforms, while regulatory burden redistribution is reshaping vendor geographic prioritization.
Ultrahigh-speed vitrectomy cutters operating above 7,500 cuts per minute are expanding into complex retinal detachment procedures previously restricted to lower-speed instrumentation. Academic medical centers in Germany and Japan are adopting these systems for diabetic tractional detachments where membrane segmentation demands minimal retinal traction. The technology is expanding into outpatient clinic settings as portable console designs accommodate power and space constraints without sacrificing cut rate performance.
The EU Medical Device Regulation's Class IIb clinical evidence requirements are extending pre-market validation timelines for vitrectomy system modifications. Manufacturers must now submit prospective clinical data for software updates affecting cutting algorithms or aspiration profiles, not just hardware changes. Smaller vendors without established European notified body relationships are withdrawing from the EU market, concentrating supply among multinational ophthalmic device firms with dedicated regulatory affairs infrastructure.
Hospital procurement departments are unbundling after-sales service contracts from equipment purchases, forcing manufacturers to compete on transparent parts pricing and response time guarantees rather than bundled multi-year agreements. This shift is most visible in the United States, where health system consolidation has centralized purchasing authority and standardized vendor scorecards across integrated delivery networks. Service revenue compression is redirecting manufacturer investment toward consumable attachment lock-in strategies.
Vitrectomy Machines Market Segmentation
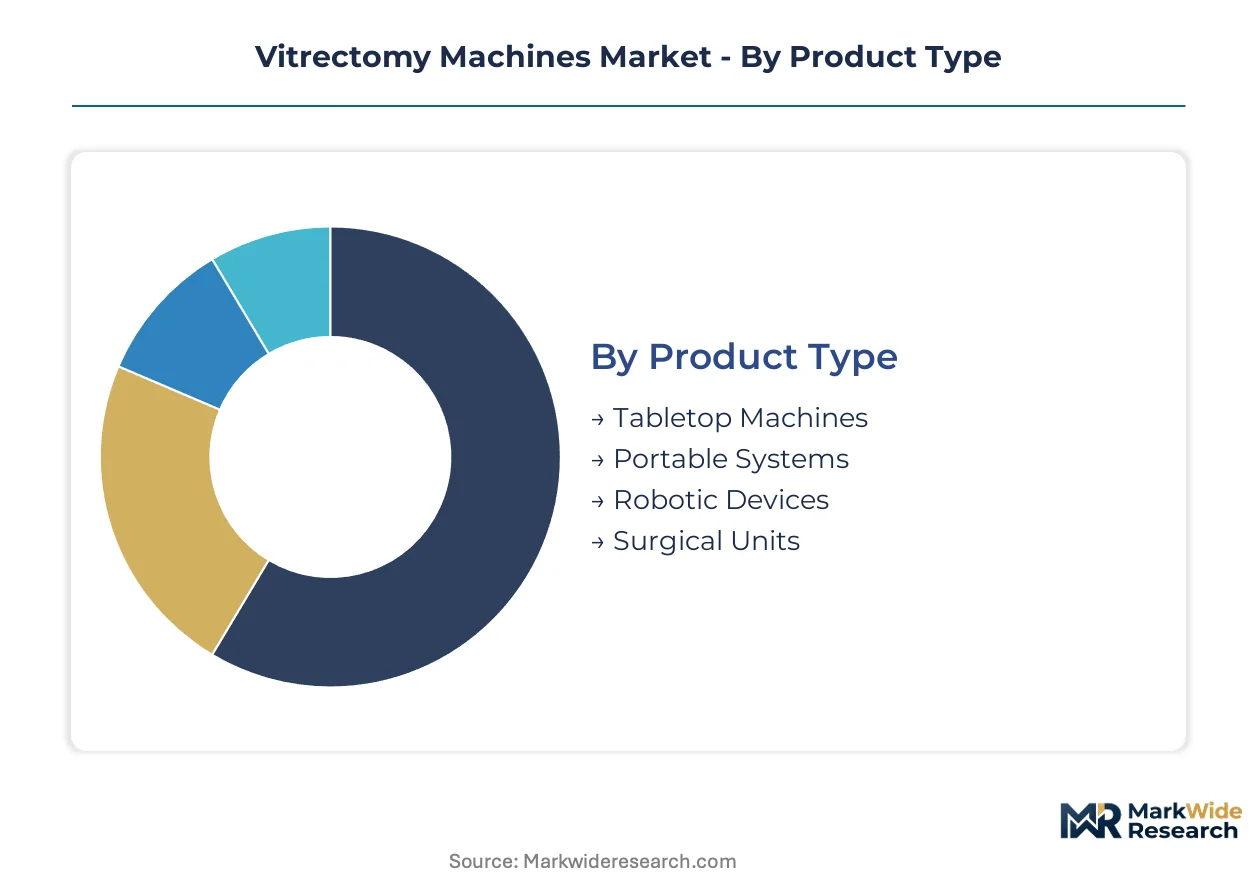
Segmentation in the vitrectomy machines market reveals distinct procurement patterns across facility types and technological sophistication tiers. Equipment specifications diverge sharply between permanent operating room installations and mobile clinical deployments, with regulatory pathways further stratifying vendor access by geography.
Product Type:
Cut rate performance and console footprint define the technology axis across product categories.
- Tabletop Machines:These permanent-installation systems operate at cut rates exceeding 7,500 cuts per minute through integrated aspiration pumps and proprietary cutter mechanisms. Demand concentrates in hospital operating rooms across the United States and Germany where power stability and space allocation support fixed infrastructure.
- Portable Systems:Compact console designs deliver comparable cut rate performance through battery-backed power systems and reduced fluidics complexity. Outpatient clinics in Japan and ambulatory surgical centers in the United States are expanding procurement fastest to bypass capital-intensive infrastructure requirements.
- Robotic Devices:Computer-assisted motion control systems enable sub-millimeter precision in membrane peeling procedures.
- Surgical Units:Modular configurations allow component upgrades without full console replacement.
Mature deployment sits with tabletop machines. Newer deployment is concentrated in portable systems.
End User:
Procedural volume and reimbursement rates determine equipment acquisition capacity across facility tiers.
- Hospitals:Tertiary academic medical centers in Germany and Japan anchor procurement of integrated surgical platforms with real-time OCT compatibility. These facilities generate sufficient procedural volume to justify premium capital expenditure through bundled payment structures.
- Specialized Eye Centers:Dedicated vitreoretinal practices concentrate high-complexity cases requiring ultrahigh-speed cutters above 10,000 cuts per minute. The United States hosts the densest concentration of these standalone facilities.
- Outpatient Clinics:Limited infrastructure budgets favor tabletop alternatives and portable system leasing arrangements.
- Research Laboratories:Preclinical testing demands drive procurement of prototype systems and modified fluidics configurations.
Equipment lifecycle extension dominates hospital procurement. Fastest capacity expansion is occurring in specialized eye centers.
Technology:
Margin capture potential separates proprietary imaging ecosystems from commodity visualization components.
- Digital Imaging:Embedded image-processing algorithms in surgical consoles lock in recurring consumable revenue through proprietary attachment protocols. Academic medical centers demand these systems for intraoperative decision support.
- Optical Coherence Tomography:Real-time tissue visualization during posterior segment procedures commands premium positioning in Germany and Japan where fellowship-trained specialists concentrate.
- Laser-Assisted:Integrated photocoagulation capabilities reduce instrument exchange requirements during complex cases.
- Stereoscopic Visualization:Three-dimensional viewing systems address surgeon ergonomics in extended procedures.
Digital imaging commands the highest attach rates. OCT convergence is gaining share fastest in academic settings.
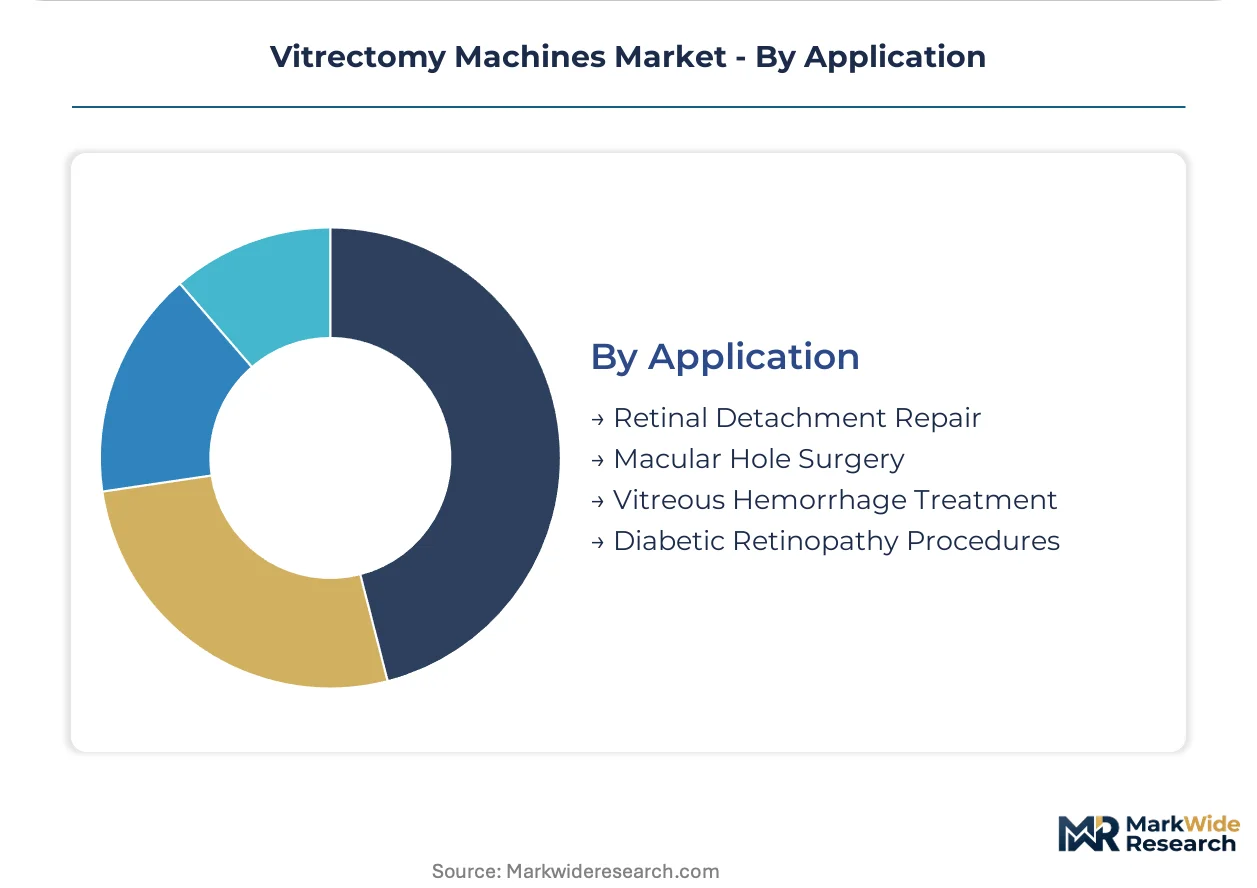
Application:
Disease prevalence and surgical complexity dictate equipment specification requirements across procedure types.
- Diabetic Retinopathy Procedures:Tractional retinal detachments and vitreous hemorrhage interventions demand ultrahigh-speed cutters and advanced fluidics control for membrane segmentation. Procedural volume is expanding across aging populations in the United States, Germany, and Japan.
- Retinal Detachment Repair:Rhegmatogenous cases require precise cutter control near thin peripheral retina, favoring systems with variable cut rate modulation.
- Macular Hole Surgery:Epiretinal membrane peeling and internal limiting membrane removal prioritize minimal retinal traction.
- Vitreous Hemorrhage Treatment:Diagnostic visualization challenges drive demand for integrated illumination systems.
Established procedural protocols govern retinal detachment repair. Steepest expansion trajectory is occurring in diabetic retinopathy procedures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The vitrectomy machines market concentrates in metropolitan medical corridors where tertiary eye care infrastructure and specialized surgical training programs intersect. Boston's Longwood Medical Area anchors North American demand through dense academic medical center clustering. Procurement patterns diverge sharply across national reimbursement frameworks and regulatory validation timelines.
United States
Diabetic retinopathy procedural volume and ambulatory surgical center expansion drive equipment procurement. FDA 510(k) clearance pathways enable faster market entry for system modifications than European counterparts. The Cleveland Clinic and Bascom Palmer Eye Institute in Miami concentrate fellowship-trained vitreoretinal specialists who anchor high-complexity case volumes.
Germany
Academic medical center procurement of integrated OCT-compatible platforms exceeds other European markets. EU Medical Device Regulation Class IIb requirements compress certification timelines and consolidate compliant suppliers. The Heidelberg University Hospital corridor and Munich's Ludwig Maximilian University medical cluster generate concentrated demand for ultrahigh-speed cutter systems.
Japan
Aging demographics and diabetic complication prevalence sustain procedural growth in tertiary eye centers. PMDA quality management system inspections impose 12-18 month delays for non-Japanese manufacturers seeking market entry. Tokyo's Juntendo University Hospital and Osaka University Hospital anchor specialized vitreoretinal surgical capacity in the Kanto and Kansai regions.
United Kingdom
NHS bundled payment structures concentrate premium platform procurement in designated specialist treatment centers. MHRA post-Brexit regulatory divergence from EU MDR creates parallel compliance pathways for market entrants. Moorfields Eye Hospital in London and the Manchester Royal Eye Hospital represent the densest concentrations of complex posterior segment surgical volume.
Switzerland
Private clinic procurement of portable systems outpaces hospital sector growth due to outpatient procedural expansion. Swissmedic maintains alignment with EU MDR clinical evidence standards while offering faster quality system review timelines. The University Hospital of Geneva and Zurich's Klinik Hirslanden anchor German-speaking demand for precision ophthalmic surgical equipment.
Vitrectomy Machines Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a tiered vendor structure where integrated platform manufacturers face specialized component suppliers. The market exhibits moderate consolidation among multinational ophthalmic device firms with dedicated regulatory affairs infrastructure, while smaller vendors withdraw from EU markets under MDR pressure. Three archetypes dominate: full-stack surgical platform builders, precision cutter mechanism specialists, and optical imaging convergence players. Competitive moves center on consumable attachment lock-in strategies and geographic prioritization shifts away from extended European certification timelines.
Among multinational ophthalmic device conglomerates, Alcon Inc., Bausch + Lomb Incorporated, and Carl Zeiss Meditec AG occupy positions that exemplify divergent strategic vectors. Alcon represents the integrated digital imaging platform archetype through its console-centric ecosystem approach. Bausch + Lomb exemplifies fluidics specialization for complex retinal cases. Carl Zeiss Meditec anchors optical coherence tomography convergence positioning in academic medical center procurement. These three firms collectively demonstrate how proprietary technology lock-in and regulatory infrastructure scale separate sustainable competitors from market exiters.
| Leading Market Players |
|---|
| Alcon Inc. |
| Bausch + Lomb Incorporated |
| Carl Zeiss Meditec AG |
| Topcon Corporation |
| NIDEK Co., Ltd. |
| Johnson & Johnson Vision |
| Hoya Corporation |
| BVI Medical |
| Danaher Corporation |
| Others |
Pricing and Supply Chain Analysis
Captive cutter mechanism production in Germany and Japan anchors both supply security and premium pricing power for integrated platform manufacturers, while outsourced console assembly in lower-cost jurisdictions compresses margins for mid-tier competitors lacking proprietary fluidics control.
Pricing Analysis
Value-based pricing anchored to procedural throughput and equipment uptime dominates the vitrectomy machine market. Three-tier pricing structure across premium, standard, and economy levels separates integrated OCT-compatible platforms from standalone cutters and refurbished legacy systems. Price differentiation stems from FDA 510(k) clearance tier and bundled after-sales service coverage. Cost compression in the standard tier is intensifying because hospital procurement departments are unbundling multi-year service contracts. Outpatient clinics exhibit highest price sensitivity, while tertiary academic medical centers prioritize performance specifications over capital expenditure.
Supply Chain Analysis
High-precision aspiration pumps and ultrahigh-speed cutter mechanisms rest on specialized component suppliers concentrated in Germany, Japan, and the United States. Raw material dependencies span surgical-grade stainless steel alloys, piezoelectric ceramics for cutter actuation, and medical-grade silicone tubing for fluidics circuits. Single-source vulnerability in precision cutter manufacturing creates supply chain risk, as dual-qualified suppliers remain scarce for cut rates exceeding 10,000 per minute. Distribution runs through direct hospital sales forces for integrated platforms and specialized ophthalmic device distributors for portable systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vitrectomy machines market functions as a vertical-integration race where control over precision cutter manufacturing and proprietary imaging software determines sustainable margin capture.
For Market Incumbents: Anticipate regulatory burden redistribution by front-loading EU MDR clinical evidence generation for AI-enhanced imaging modules before competitors consolidate notified body relationships. Defend installed base positions through proprietary attachment protocols that block third-party cutter compatibility, while building captive supply of precision fluidics components to offset German and Japanese supplier concentration risk. For New Entrants and Emerging Players: Capture ambulatory surgical center demand in the United States by offering portable system leasing arrangements that bypass capital-intensive infrastructure requirements. The outpatient clinic segment represents the most penetrable white space, as incumbent focus on tertiary hospital procurement leaves price-sensitive mid-tier facilities underserved. Pursue FDA 510(k) clearance for software-as-medical-device imaging modules to accelerate market entry versus full system approvals. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational ophthalmic device conglomerates seeking regulatory affairs infrastructure scale and European market access. Long-term viability favors targets with established notified body relationships under EU MDR and proprietary cutter mechanism IP. Watch for PMDA approval timeline compression in Japan as an inflection signal for geographic prioritization shifts among non-Japanese manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Investment | Accelerates market access consolidation among compliant suppliers under stricter Class IIb clinical evidence requirements. |
| Software-as-Medical-Device Pathway | Unlocks faster FDA 510(k) clearance for AI-enhanced imaging modules versus full surgical platform approvals. |
| Portable System Leasing Programs | Addresses ambulatory surgical center budget constraints while expanding addressable market penetration. |
| OCT Integration Partnership | Commands premium positioning in academic medical centers demanding real-time tissue visualization during procedures. |
| Precision Cutter Vertical Integration | Reduces single-source vulnerability from German and Japanese component suppliers while protecting proprietary technology. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this vitrectomy machines market assessment, supplemented by primary interviews with vitreoretinal surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. FDA 510(k) databases, EU MDR notified body registers, PMDA approval records, and hospital procurement databases provided procedural volume and equipment installation validation. Bottom-up facility-level demand modeling triangulated against top-down manufacturer shipment data.
Data-stream reconciliation across equipment unit shipments, procedural volume estimates, and average selling price bands supported the analytical framework across the analysis window. Segmentation dimensions modeled include product type, end-user facility tier, technology integration level, and application procedure category. CAGRs were derived from weighted regression across historical installation base expansion and replacement cycle timing. Forecast inputs incorporated diabetic retinopathy prevalence trajectories and regulatory pathway timeline assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU MDR implementation pace, PMDA inspection timeline variability, and vitreoretinal surgeon training pipeline expansion. Forecasts reflect documented assumptions regarding reimbursement stability and procedural volume growth. Regulatory pathway disruption, supply chain consolidation among precision component suppliers, and software-as-medical-device classification evolution warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Astigmatism Market
Ophthalmology
Asia-Pacific Glaucoma Treatment Market
Ophthalmology
Retinal Detachment Market
Ophthalmology
South Africa Ophthalmic Devices Market
Ophthalmology
Nystagmus Market
Ophthalmology
Latin America Dry Eye Syndrome Market
Ophthalmology
Ophthalmology Diagnostics and Surgical Devices Market
Ophthalmology
Leber Congenital Amaurosis Market
Ophthalmology
Presbyopia Treatment Market
Ophthalmology
Retinal Disease Therapeutics Market
Ophthalmology
Lubricating Eye Drops Market
Ophthalmology
Sodium Hyaluronate Eye Drops Market
Ophthalmology
Eye Care Surgical Market
Ophthalmology
Ocular Pain Market
Ophthalmology
Thyroid Eye Disease Treatment Market
Ophthalmology
3D Printed Ophthalmic Implants Market