
 Minimally Invasive Neurosurgery Devices Market | 2026-2036
Minimally Invasive Neurosurgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Minimally Invasive Neurosurgery Devices Market Outlook
EU MDR is pivoting the cost-of-entry calculus for neurosurgical device manufacturers, forcing substantial clinical evidence investments that favor well-capitalized incumbents. Medtronic leverages its integrated surgical ecosystems to sustain premium positioning across navigation and visualization platforms. Stryker anchors its portfolio through specialized instruments and capital equipment tailored to cranial access. Karl Storz GmbH & Co. KG differentiates via rigid endoscope optics that dominate European teaching hospitals.
Minimally invasive neurosurgery devices comprise precision-engineered instruments, endoscopes, stents, and navigation systems designed for intracranial and spinal access through small port sites, typically requiring sub-millimeter tolerance in instrument fabrication and real-time imaging integration to preserve eloquent neural tissue. These systems serve the primary commercial purpose of reducing perioperative morbidity, shortening hospitalization, and enabling intervention in surgically fragile patient populations. Neurovascular stents capture concentrated margin pools due to catheter-delivered complexity and prolonged regulatory validation timelines, while endoscopes represent the most mature segment with established replacement cycles across academic medical centers. Biopsy devices are gaining procedural share as frameless stereotaxy and intraoperative MRI expand tissue diagnosis capabilities.
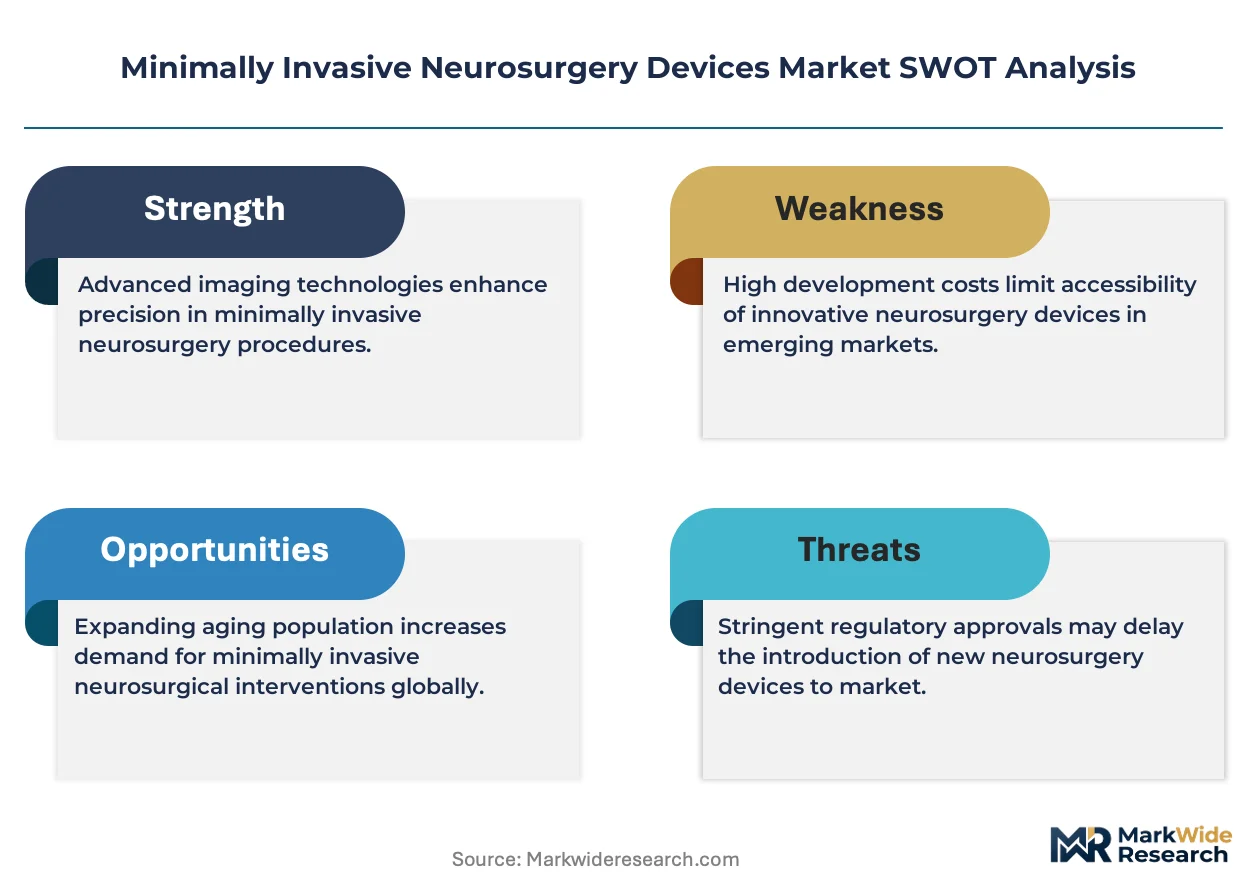
FDA premarket notification pathways, EU MDR clinical evaluation requirements, and Japan's PMDA orphan device frameworks collectively shape product development roadmaps, reimbursement eligibility, and market access timelines for neurosurgical innovators. ISO 13485 quality management standards and IEC 60601 electrical safety protocols further constrain design verification and supply chain qualification processes. Stakeholders must monitor how FDA breakthrough device designations and EU MDR notified body capacity constraints redistribute competitive advantage between established manufacturers and emerging technology developers.
Market Dynamics
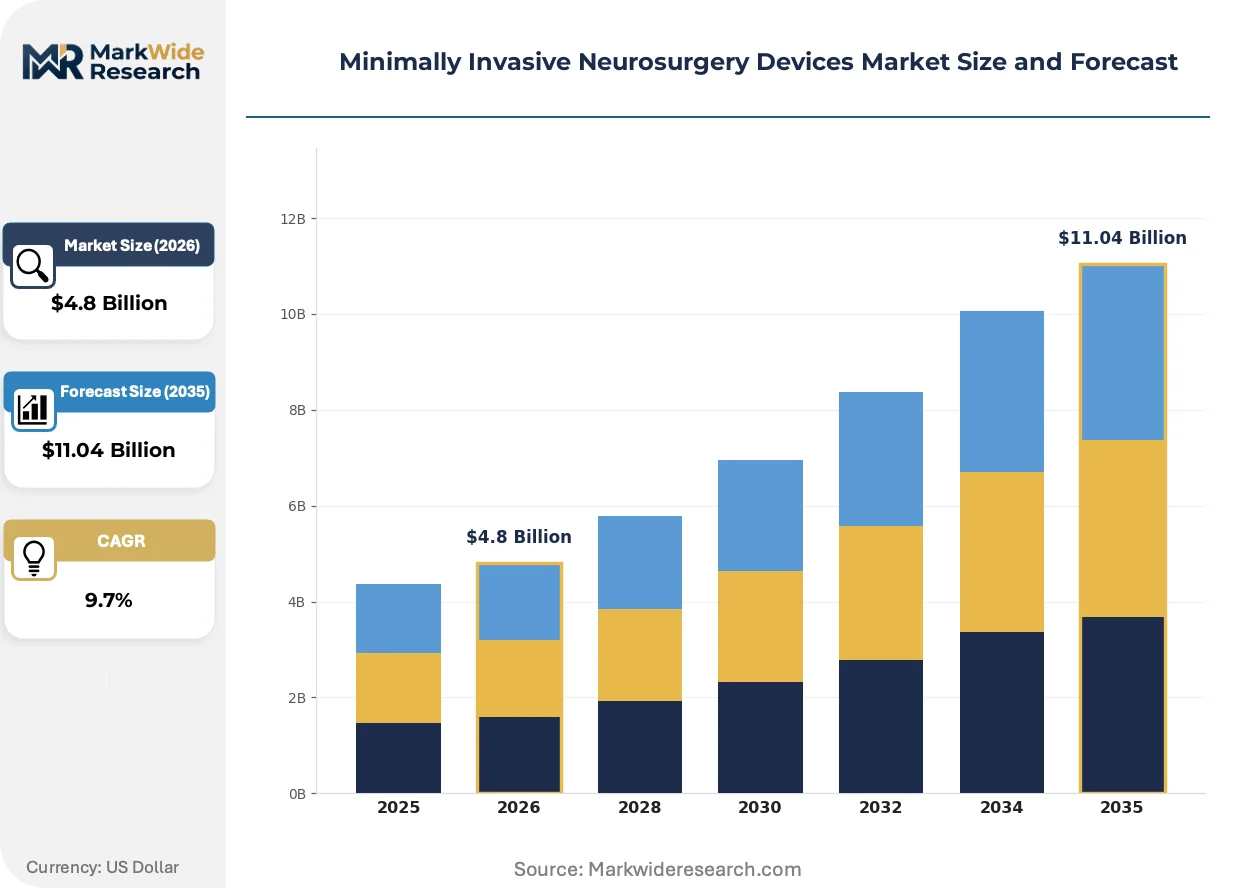
EU MDR clinical evaluation requirements are compressing development timelines for neurosurgical device developers while simultaneously elevating capital requirements, creating asymmetric pressure that favors integrated manufacturers with established notified body relationships over modular suppliers.
Growth Catalysts
- FDA Breakthrough Device Designation:The FDA's expedited premarket review pathway for neurosurgical innovations reduces regulatory friction for intracranial navigation systems and compresses time-to-revenue for eligible developers.
- Frameless Stereotaxy Adoption:Academic medical centers in Germany and Japan are replacing framed biopsy systems with optical tracking platforms, expanding addressable procedure volumes for port-based tissue sampling.
- Spinal Endoscope Replacement Cycles:European teaching hospitals are accelerating capital equipment refresh schedules for rigid endoscope towers, driven by optical resolution improvements and warranty expiration clustering.
Market Restraints
- EU MDR Notified Body Capacity Constraints:Bottlenecks in European conformity assessment are extending certification timelines for Class III neurovascular implants, delaying market entry for emerging manufacturers.
- Precision Manufacturing Input Concentration:Sub-millimeter tolerance instrument fabrication depends on concentrated German and Swiss specialty machining suppliers, creating vulnerability to capacity constraints.
- Catheter-Delivered Stent Complexity:Neurovascular stent production requires braided nitinol expertise that remains captive to a limited supplier base, constraining margin expansion for device assemblers.
Strategic Opportunities
- Ambulatory Surgery Center Penetration:United States outpatient facilities are expanding spinal decompression capabilities, creating demand for compact navigation systems with smaller footprints than hospital-tier platforms.
- Intraoperative MRI Convergence:Integration of real-time magnetic resonance imaging with robotic biopsy trajectories is opening procedure categories previously excluded from minimally invasive approaches due to visualization limitations.
- Japan PMDA Orphan Device Framework:Accelerated review pathways for rare neurological indications offer first-mover advantages for developers targeting pediatric hydrocephalus or craniofacial malformation interventions.
Industry Challenges
- Neurosurgeon Training Pipeline Constraints:Fellowship programs in endoscopic skull base techniques produce insufficient operators to match installed base expansion, limiting utilization rates for capital equipment.
- Legacy Navigation System Integration:Hospital IT infrastructure fragmentation complicates interoperability between new visualization platforms and existing surgical planning software, delaying procurement decisions.
- ISO 13485 Supply Chain Qualification:Component supplier audits for quality management compliance extend vendor onboarding timelines, compressing manufacturing flexibility for device assemblers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Minimally Invasive Neurosurgery Devices Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endoscopes, Neurovascular Stents, Biopsy Devices, Surgical Instruments Application: Brain Tumors, Spine Disorders, Vascular Disorders, Pain Management Delivery Mode: Telemedicine, In-Person Consultations, Hybrid Models, Emergency Services End User: Hospitals, Ambulatory Surgery Centers, Specialty Clinics, Research Institutes |
| Companies Covered | Medtronic, Stryker, Karl Storz GmbH & Co. KG, Olympus Corporation, NICO Corporation, Integra LifeSciences, Penumbra, NuVasive, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Minimally Invasive Neurosurgery Devices Market Strategic Shifts
Digital surgery ecosystems are absorbing standalone instrument categories into integrated platforms, reshaping how hospitals evaluate capital purchases and how manufacturers defend installed base positions.
Robotic trajectory guidance systems are absorbing frameless stereotaxy workflows in cranial biopsy procedures. United States academic medical centers are piloting these platforms for deep-brain electrode placement, with adoption timelines compressing from five-year evaluation cycles to eighteen-month procurement decisions. The technology is absorbing margin from conventional navigation hardware while enabling procedure categories requiring sub-millimeter accuracy.
EU MDR post-market surveillance requirements are mandating systematic clinical follow-up for permanently implanted neurovascular devices. Manufacturers must now maintain registries tracking patient outcomes across extended timelines, elevating operational costs for stent producers. The regulation is concentrating competitive advantage among firms with existing European infrastructure versus entrants dependent on contract research organizations.
Hospital procurement committees are unbundling after-sales service from capital equipment contracts, forcing device manufacturers to compete on discrete maintenance pricing rather than bundled lifecycle agreements. United States health system consolidation is accelerating this shift, with integrated delivery networks standardizing service procurement across multiple facilities. The pattern is most visible in Midwestern hospital clusters where group purchasing organizations have centralized neurosurgical capital allocation.
Minimally Invasive Neurosurgery Devices Market Segmentation
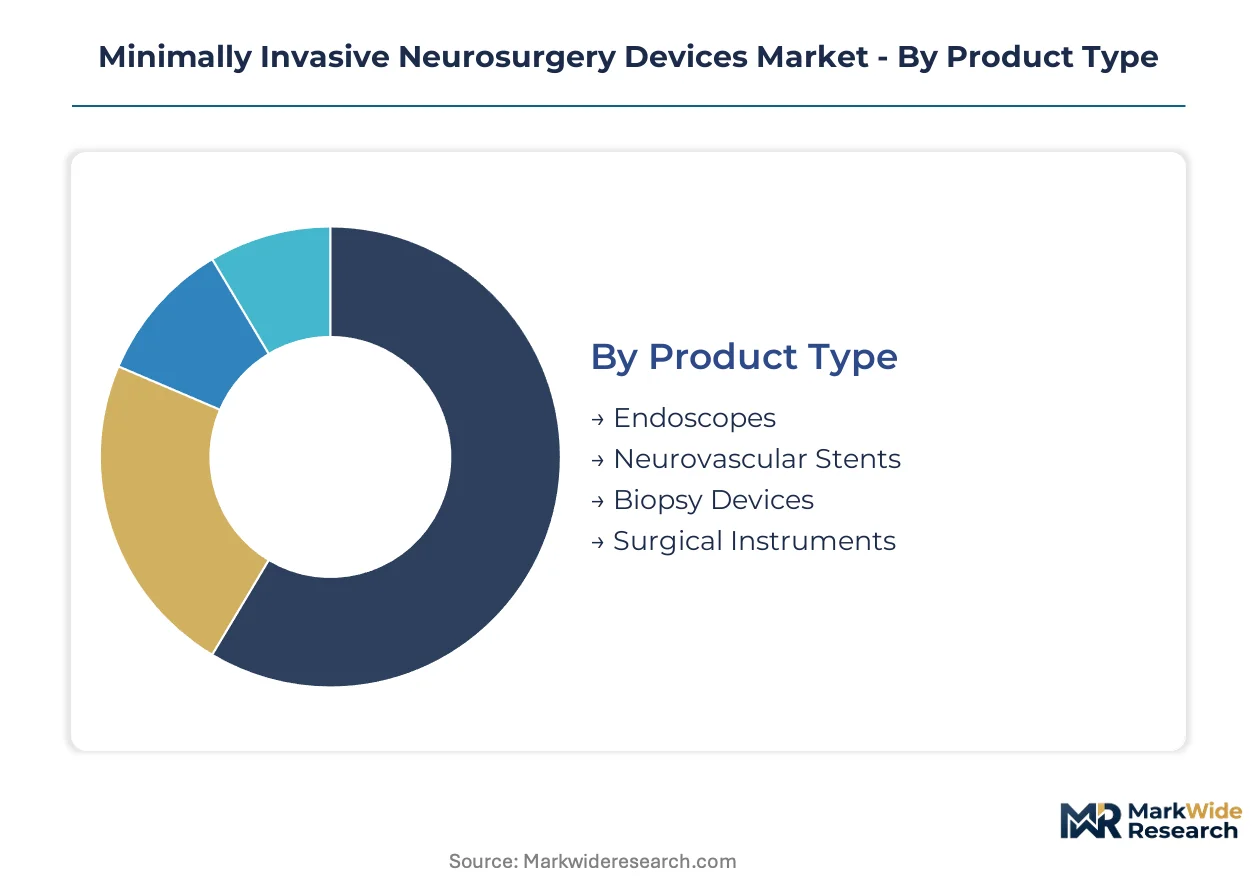
Device taxonomy in minimally invasive neurosurgery determines capital allocation priorities, regulatory pathway selection, and surgeon training requirements. Segment boundaries increasingly blur as integrated platforms absorb standalone instrument categories.
Product Type:
Capital intensity varies dramatically across this category, with neurovascular stents requiring braided nitinol foundries and multi-year clinical validation while surgical instruments demand precision machining at lower absolute investment thresholds.
- Neurovascular Stents:Braided nitinol constructs delivered through microcatheter systems achieve vessel wall apposition in intracranial aneurysm treatment. Demand clusters in United States comprehensive stroke centers and Japanese neurovascular hubs where PMDA orphan device frameworks accelerate pediatric indications. Catheter-delivered complexity and prolonged regulatory timelines sustain concentrated margin pools.
- Endoscopes:Rigid rod-lens optical systems with Hopkins prism technology enable visualization through narrow port sites in skull base and spinal procedures. European teaching hospitals in Germany and Switzerland drive replacement cycles as optical resolution improvements render legacy towers obsolete. Karl Storz GmbH & Co. KG dominates installed base in academic medical centers.
- Biopsy Devices:Frameless stereotactic needle systems extract tissue samples through burr hole access without fixed cranial frames. Optical tracking platforms are displacing framed systems in German and Japanese academic centers.
- Surgical Instruments:Sub-millimeter tolerance graspers, dissectors, and suction devices fabricated from surgical stainless steel or titanium alloys. German and Swiss specialty machining suppliers constrain capacity expansion for precision fabrication.
Most installed capacity flows through endoscopes. Expansion is steepest in biopsy devices as frameless stereotaxy displaces framed systems.
Application:
Procedure volume distribution across this category reflects demographic disease burden and reimbursement generosity, with spine disorders capturing the highest absolute case counts while brain tumor interventions command premium pricing.
- Brain Tumors:Navigation-guided resection and biopsy procedures targeting gliomas, metastases, and pituitary adenomas. United States academic medical centers are piloting robotic trajectory guidance for deep-brain electrode placement alongside tumor interventions.
- Spine Disorders:Decompression and fusion procedures via tubular retractor systems and endoscopic approaches. Ambulatory surgery centers in the United States Midwest are expanding spinal capabilities, creating demand for compact navigation platforms.
- Vascular Disorders:Aneurysm coiling, stent-assisted coiling, and flow diversion for intracranial and spinal vascular pathology. Japanese neurovascular specialists leverage PMDA orphan pathways for rare malformation treatments.
- Pain Management:Percutaneous approaches to trigeminal neuralgia and spinal cord stimulation lead placement. Hybrid delivery models are emerging as United States health systems consolidate pain service lines.
Spine disorders absorb the greatest procedure volume. Brain tumor applications are gaining share fastest as intraoperative MRI integration expands addressable cases.
Delivery Mode:
Care delivery configuration in this category reflects post-pandemic infrastructure investments and regulatory flexibility around remote surgical consultation, with hybrid models capturing investment preference over pure telemedicine plays.
- Hybrid Models:Combined remote consultation with scheduled in-person intervention, enabling preoperative planning and postoperative monitoring without repeated facility visits. United States integrated delivery networks are standardizing hybrid protocols across Midwestern hospital clusters.
- In-Person Consultations:Traditional facility-based evaluation and procedure execution. Remains dominant for initial diagnosis and complex revision surgeries requiring physical examination.
- Telemedicine:Remote preoperative assessment and postoperative follow-up via video consultation. Regulatory frameworks in the United States vary by state, complicating standardized deployment.
- Emergency Services:Time-critical intervention for stroke, hemorrhage, and trauma requiring immediate surgical access. United States comprehensive stroke centers maintain 24/7 neurosurgical coverage with endovascular capabilities.
Hybrid models are capturing capital allocation preference. Emergency services infrastructure is expanding most quickly as stroke network certification requirements tighten.
End User:
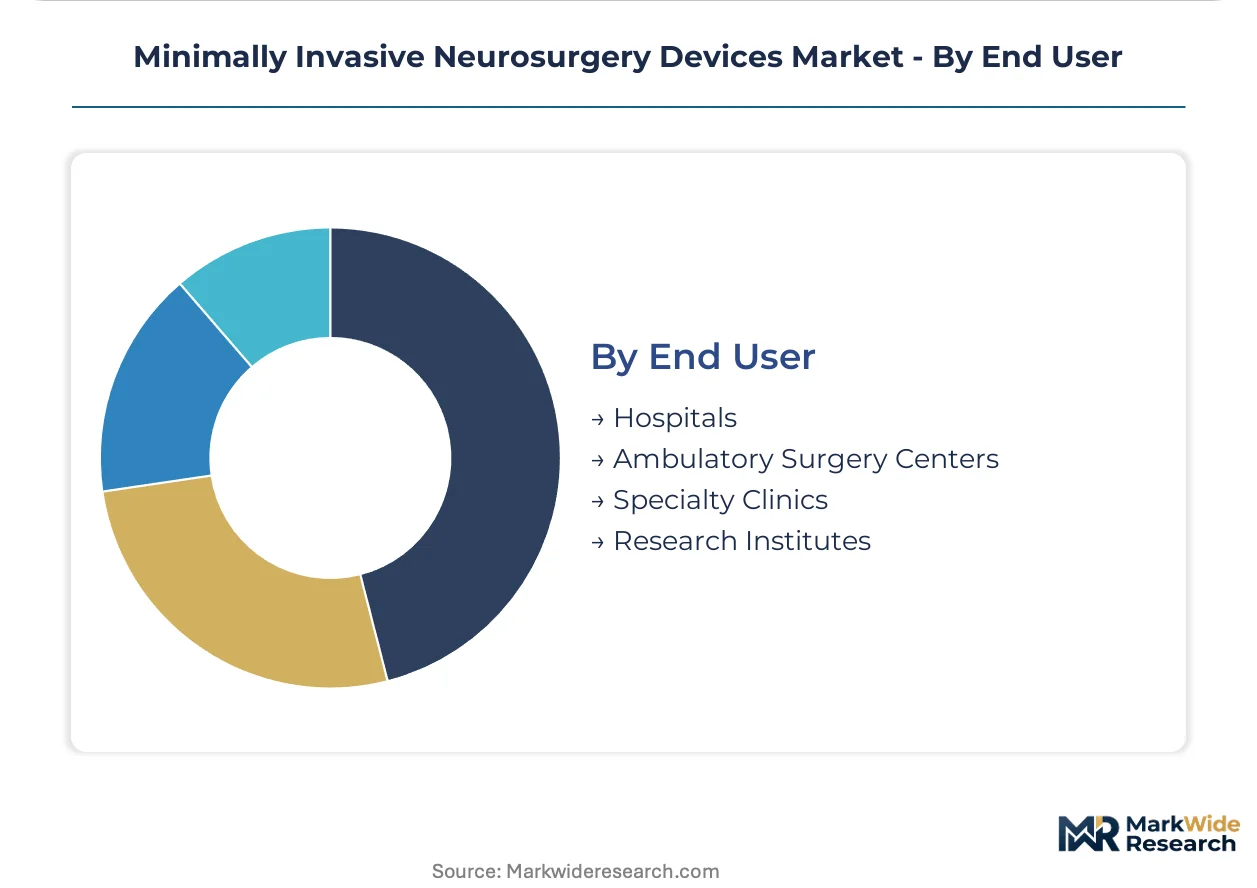
Procurement authority and capital availability diverge sharply across this category, with hospitals maintaining bundled lifecycle contracts while ambulatory surgery centers unbundle service components to drive down per-procedure costs.
- Hospitals:Academic medical centers and community hospitals with neurosurgical suites, navigation platforms, and intensive care capacity. North American facilities are expanding endoscopic and image-guided platform installations.
- Ambulatory Surgery Centers:Outpatient facilities performing spinal decompression and select cranial procedures. United States ASCs are demanding compact navigation systems with smaller footprints than hospital-tier platforms as case complexity rises.
- Specialty Clinics:Focused neurosurgical practices and pain management centers. Concentrated in urban United States markets with direct-to-employer contracting relationships.
- Research Institutes:Preclinical and clinical trial sites evaluating novel device platforms. EU MDR post-market surveillance requirements are elevating registry maintenance costs for permanently implanted devices.
Hospitals retain the dominant installed base. Ambulatory surgery centers are climbing the fastest as United States outpatient procedural volume shifts site of service.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neurosurgical fellowship programs in the United States, Germany, and Japan produce the specialized operators driving procedural demand for minimally invasive platforms. These talent concentrations anchor installed base expansion across academic medical centers and comprehensive stroke networks.
United States
Comprehensive stroke centers in Cleveland Clinic and Mayo Clinic networks are expanding 24/7 endovascular coverage for intracranial aneurysm interventions. FDA breakthrough device designations compress premarket review timelines for intracranial navigation systems. The Midwestern hospital cluster around Chicago and Minneapolis is standardizing hybrid delivery protocols across integrated delivery networks.
Germany
Academic medical centers in Heidelberg and Munich are replacing framed biopsy systems with optical tracking platforms for port-based tissue sampling. EU MDR clinical evaluation requirements are elevating registry maintenance costs for permanently implanted neurovascular devices. The precision machining corridor in Baden-Württemberg supplies sub-millimeter tolerance instruments to device assemblers.
Japan
PMDA orphan device frameworks accelerate pediatric hydrocephalus and craniofacial malformation interventions at Tokyo and Osaka neurovascular hubs. METI industrial policy supports domestic production of braided nitinol constructs for intracranial stent applications. The Kanto region concentrates procedural demand for deep-brain electrode placement alongside tumor interventions.
Switzerland
Specialty machining suppliers in the Jura Arc fabricate surgical instruments requiring sub-millimeter tolerances for European device manufacturers. Swissmedic conformity assessment timelines remain predictable relative to EU MDR notified body bottlenecks. The Basel-Zurich corridor anchors supply chain qualification for ISO 13485 component vendors.
United Kingdom
NHS England specialized commissioning frameworks are consolidating spinal decompression referrals to high-volume centers in London and Manchester. MHRA post-Brexit regulatory autonomy is diverging from EU MDR implementation timelines for Class III neurosurgical implants. The Oxford-Cambridge arc is piloting intraoperative MRI convergence with robotic biopsy trajectories.
Minimally Invasive Neurosurgery Devices Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across navigation, visualization, and implant categories. The market structure concentrates around integrated surgical ecosystems that bundle capital equipment with disposable instruments. Three archetypes dominate: diversified medtech conglomerates with navigation platforms, specialized endoscope manufacturers with teaching hospital relationships, and neurovascular-focused firms with catheter-delivered stent portfolios. Competitive moves center on M&A absorption of robotic guidance capabilities and strategic partnerships for intraoperative imaging integration.
Within the diversified conglomerate tier, Medtronic and Stryker occupy positions defined by integrated surgical ecosystems spanning navigation and visualization. Karl Storz GmbH & Co. KG exemplifies the specialized optics archetype, with its corporate form indicating German engineering heritage and established presence in European academic medical centers. These three anchors represent the competitive spectrum from full-stack platform providers to focused instrument specialists.
| Leading Market Players |
|---|
| Medtronic |
| Stryker |
| Karl Storz GmbH & Co. KG |
| Olympus Corporation |
| NICO Corporation |
| Integra LifeSciences |
| Penumbra |
| NuVasive |
| Johnson & Johnson |
| Others |
Value Chain & Pricing Dynamics
Swiss and German precision machinists specializing in sub-millimeter tolerance instrument fabrication anchor labor-cost differentials that widen pricing-tier spreads between premium navigation platforms and commoditized surgical instruments.
Pricing Analysis
The bundled-vs-unbundled service split is reshaping contract structures across hospital procurement committees. Three-tier pricing structure across premium, standard, and economy levels separates integrated surgical ecosystems with full after-sales support from stripped-down capital equipment sold to ambulatory surgery centers. Price differentiation hinges on ISO 13485 certification tier and after-sales service bundling. Cost compression in the economy tier is intensifying because United States integrated delivery networks are standardizing unbundled maintenance procurement across Midwestern hospital clusters. Ambulatory surgery centers exhibit the highest price sensitivity; academic medical centers with established notified body relationships demonstrate the lowest.
Supply Chain Analysis
Braided nitinol supply rests on Japanese and German specialty metallurgy producers with captive expertise in catheter-delivered stent fabrication. German, Swiss, and Japanese suppliers dominate sub-millimeter tolerance machining, nitinol braiding, and optical component fabrication respectively. Raw material dependencies center on surgical-grade stainless steel, titanium alloys, and rare-earth-doped optical glass. Single-source vulnerability in braided nitinol expertise constrains capacity expansion for neurovascular stent assemblers. Distribution runs through hospital procurement committees and group purchasing organizations with consolidated neurosurgical capital allocation authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in minimally invasive neurosurgery devices rests on the shift toward unbundled service contracts that separate premium-tier navigation platforms from commoditized instrument replacement cycles.
For Market Incumbents: To counter robotic trajectory guidance systems absorbing frameless stereotaxy workflows, Medtronic and Stryker should deepen backward integration into optical tracking sensor production and expand capacity for intraoperative MRI-compatible navigation hardware. Channel control through exclusive hospital system partnerships remains the critical defensive lever against modular suppliers. For New Entrants and Emerging Players: Direct-to-ambulatory-surgery-center digital sales channels offer the most penetrable route around established GPO contracts. Target compact navigation systems with sub-hospital footprints for United States Midwestern outpatient facilities. White-space opportunities cluster in pediatric hydrocephalus interventions under Japan's PMDA orphan device framework and hybrid delivery protocol software. For Investors and Strategic Acquirers: Diversified medtech conglomerates with navigation platforms are the most active acquirer in this space, seeking robotic guidance capabilities to fill portfolio gaps. Acquisition targets should display braided nitinol expertise or frameless stereotaxy optical tracking IP. The signal to watch is FDA breakthrough device designation velocity for intracranial navigation systems.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Locks in multi-year navigation platform deployments across Cleveland Clinic and Mayo Clinic networks. |
| FDA Breakthrough Device Designation | Compresses premarket review timelines for robotic trajectory guidance and intraoperative MRI integration. |
| CE Marking Pathway Investment | Secures EU MDR notified body relationships ahead of capacity constraints for Class III implants. |
| Software Companion Development | Enables interoperability with fragmented hospital IT infrastructure and surgical planning systems. |
| Reimbursement Strategy | Aligns device coding with CMS Medicare coverage determinations for spinal decompression procedures. |
Study Parameters
Direct dialogue with neurosurgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers grounded the qualitative foundation, supplemented by FDA 510(k) filings, EU MDR notified body certificates, hospital procurement databases, and CMS Medicare reimbursement schedules. Secondary validation drew from SEC 10-K disclosures and patent assignment records. Bottom-up and top-down triangulation reconciled procedure volume estimates with capital equipment shipment data.
Bottom-up modeling segmented the market by product type, application, delivery mode, and end user across the analysis window. Top-down validation cross-checked aggregate manufacturer revenue disclosures against installed base expansion rates. CAGRs were derived from regression analysis of historical procedure growth and capital replacement cycles. Industry-specific forecast inputs included neurosurgeon fellowship graduation rates and EU MDR notified body capacity constraints.
The model assumes a particular technology adoption path; alternative pathways for robotic trajectory guidance convergence with intraoperative MRI would alter the outlook for conventional navigation hardware. Forecasts reflect assumptions around FDA breakthrough designation velocity, EU MDR certification timeline normalization, and ambulatory surgery center case-mix expansion. A small set of triggers—PMDA orphan device approval acceleration, braided nitinol supplier consolidation, and United States health system antitrust enforcement—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Therapeutic Contact Lenses Market
Medical Devices
Eccentric Tip Syringe Market
Medical Devices
X-Ray Stretchers Market
Medical Devices
Global Colposcopy Devices Market
Medical Devices
China Electrocardiograph (ECG) Market
Medical Devices
Global Peripheral IV Catheters Market
Medical Devices
Antibiotic-Loaded Bone Cement Market
Medical Devices
ECG Sensor Patch Market
Medical Devices
Digital Phoropter Market
Medical Devices
Smart Stairlift Market
Medical Devices
Global Cosmetic Contact Lens Market
Medical Devices
Asia-Pacific Ultrasound Probe Disinfection Market
Medical Devices
Pharmaceutical Filtration Devices Market
Medical Devices
Robotic Aseptic Syringe Filler Capper Market
Medical Devices
Walkers and Rollators Market
Medical Devices
Actigraphy Sensors & PSG Devices Market