
 Oxygen Therapy Devices Market | 2026-2036
Oxygen Therapy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Oxygen Therapy Devices Market Outlook
Homecare provider consolidation is expanding purchasing power across regional health networks. Fisher & Paykel Healthcare leverages its humidification technology leadership to anchor high-flow oxygen system sales in acute care settings. ResMed competes through integrated sleep-disordered breathing portfolios that bundle CPAP machines with oxygen adjuncts. Inogen Inc. specializes in portable concentrator design, sustaining direct-to-consumer channel control that bypasses traditional durable medical equipment distributors.
Oxygen therapy devices encompass mechanical and electrochemical systems engineered to deliver supplemental oxygen at flow rates from 0.5 to 60 liters per minute, with concentrators utilizing pressure swing adsorption to extract medical-grade oxygen from ambient air. These systems serve patients with chronic respiratory insufficiency, perioperative hypoxemia, and acute decompensated heart failure by maintaining arterial oxygen saturation above 88-92 percent. Portable concentrators capture expanding margin pools as ambulatory patients prioritize mobility over stationary liquid oxygen systems. CPAP machines retain mature volume positions within sleep apnea management, though reimbursement compression limits pricing flexibility. High-flow systems represent the fastest-growing technology segment, driven by ICU adoption of nasal cannula interfaces that reduce intubation rates.
The FDA's 510(k) premarket notification process governs oxygen concentrator and ventilator clearance in the United States, while the EU Medical Device Regulation (MDR) imposes stricter clinical evidence requirements for Class IIa and IIb respiratory devices entering European markets. ISO 80601-2-69 establishes international performance benchmarks for oxygen concentrator safety, creating harmonization pressure for manufacturers pursuing multi-jurisdiction registrations. Stakeholders must monitor evolving homecare reimbursement codes and clinical guideline shifts toward early oxygen intervention to align portfolio investments with payment and practice patterns.
Market Dynamics
The post-acute care migration from hospital to home is restructuring oxygen therapy device procurement, with ambulatory reimbursement codes in Germany and portable concentrator portability requirements in the US compressing stationary system volumes while expanding mobile device margin pools.
Growth Catalysts
- Pressure Swing Adsorption miniaturization:Advances in sieve bed engineering and compressor efficiency enable single-unit concentrators under five pounds, satisfying FAA portable oxygen requirements for in-flight medical use.
- High-flow nasal cannula adoption:ICU protocols in acute care settings favor non-invasive oxygen delivery over mechanical ventilation, expanding the addressable patient population for heated humidification systems.
- Japan's long-term care insurance expansion:METI reimbursement revisions for home oxygen therapy extend device rental coverage to mild COPD cases previously excluded from public support.
Market Restraints
- Zeolite supply concentration:Molecular sieve material for oxygen concentrators sources predominantly from Chinese rare earth processing clusters, exposing manufacturers to export quota volatility.
- EU MDR clinical evidence burden:Class IIb respiratory device re-certification demands extended patient outcome studies, extending product launch timelines by eighteen to thirty-six months.
- Liquid oxygen tank substitution:Refillable reservoir systems retain cost advantages for high-flow stationary patients above fifteen liters per minute, limiting concentrator penetration in severe hypoxemia cases.
Strategic Opportunities
- India's PLI scheme for medical devices:Production-linked incentives for domestic oxygen concentrator manufacturing reduce import dependency while creating tariff-advantaged export capacity for Southeast Asian markets.
- Telehealth-integrated pulse oximetry:Remote patient monitoring platforms pair with portable concentrators, enabling automated titration alerts that reduce emergency department utilization.
- Veterinary anesthesia oxygen delivery:Companion animal surgical volume growth creates unaddressed demand for compact, low-flow concentrators in specialty veterinary clinics.
Industry Challenges
- Biomedical technician certification gaps:Homecare device maintenance requires specialized training in pressure swing adsorption diagnostics that community college programs rarely cover.
- Legacy EMR integration:Oxygen saturation data from concentrator telemetry lacks standardized HL7 FHIR formatting, forcing manual entry into hospital electronic medical record systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oxygen Therapy Devices Market |
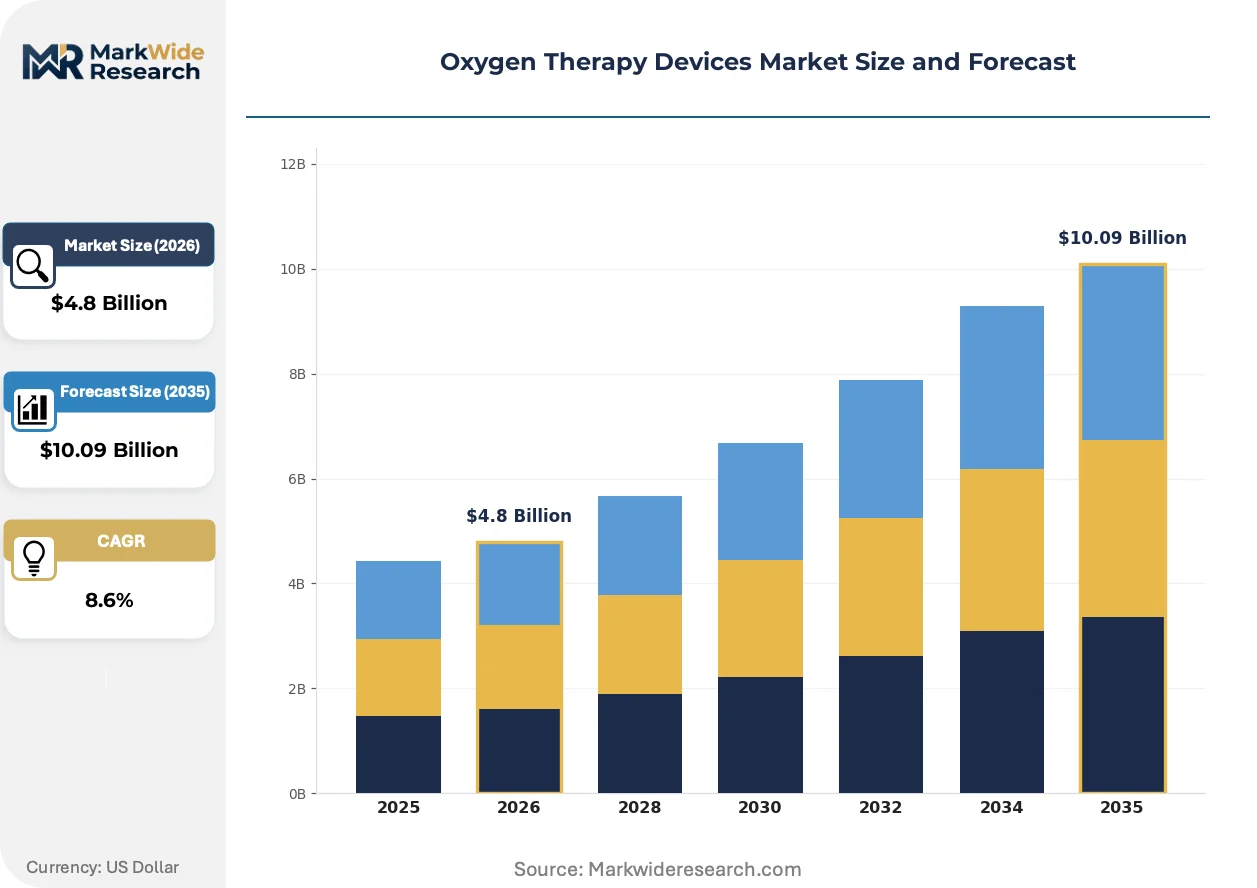
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.09 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Concentrators, Liquid Oxygen Systems, Continuous Flow Devices, CPAP Machines Application: Chronic Obstructive Pulmonary Disease, Sleep Apnea, Asthma, Congenital Heart Disease End User: Hospitals, Homecare, Rehabilitation Centers, Long-Term Care Facilities Technology: Electronic Oxygen Monitors, Ultrasonic Nebulizers, High-Flow Systems, Non-Invasive Ventilation |
| Companies Covered | Fisher & Paykel Healthcare, Drive DeVilbiss Healthcare, Philips Healthcare, Medtronic, Chart Industries, ResMed, Invacare Corporation, GE Healthcare, Inogen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oxygen Therapy Devices Market Strategic Shifts
Sensor fusion and machine learning are redefining oxygen delivery precision, with real-time SpO2 feedback loops enabling closed-loop titration that reduces clinician intervention while improving patient saturation stability.
Closed-loop oxygen control systems integrate pulse oximetry with variable-flow algorithms to maintain target saturation ranges without manual adjustment. Hospital systems in the Netherlands and Australia pilot these configurations for post-surgical wards. This automation is automating nursing workload redistribution toward higher-acuity patients.
The EU Medical Device Regulation's Unique Device Identification mandate requires oxygen concentrator serialization and post-market surveillance databases. Manufacturers must restructure quality management systems to capture field failure data. German notified bodies face audit backlogs that delay Class IIa device approvals into the second half of the decade.
Direct-to-patient subscription models bypass durable medical equipment distributors who traditionally captured forty to sixty percent of device margin. Inogen and emerging competitors operate e-commerce portals with insurance pre-authorization tools. This channel compression concentrates in the United States where Medicare competitive bidding has collapsed DME storefront networks.
Oxygen Therapy Devices Market Segmentation
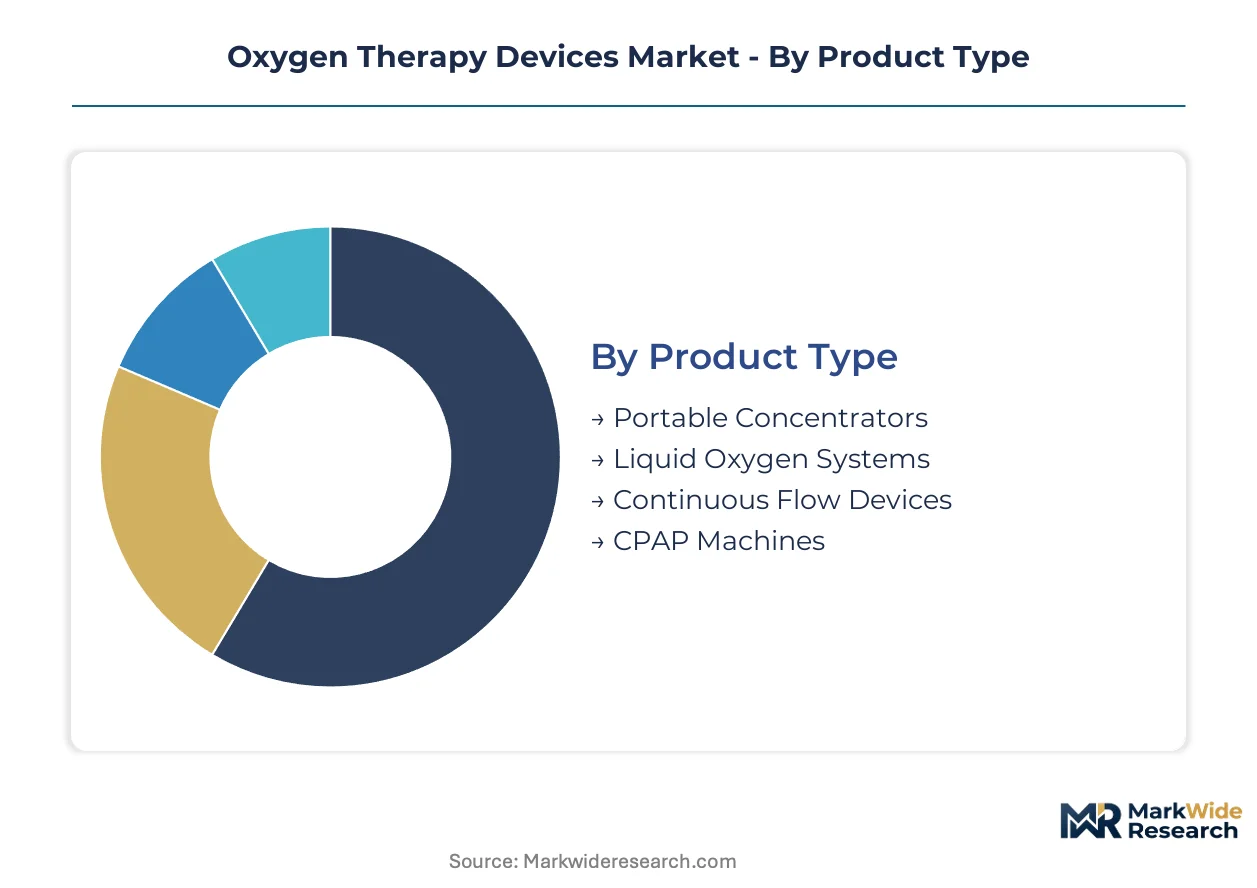
Product architecture, clinical indication, and care setting interlock to determine procurement patterns across oxygen therapy devices. Manufacturers must align R&D investment with the specific performance thresholds and reimbursement codes governing each segment boundary.
Product Type:
Patient mobility requirements and FAA certification status drive purchasing decisions across the four product categories.
- Portable Concentrators:Pressure swing adsorption systems under five pounds extract medical-grade oxygen from ambient air. Demand concentrates in the United States where Medicare competitive bidding and FAA in-flight medical use approvals support patient mobility over stationary alternatives.
- Liquid Oxygen Systems:Vacuum-insulated reservoirs store oxygen in cryogenic liquid form for high-flow delivery above fifteen liters per minute. Severe hypoxemia cases in German homecare settings retain this technology where ambulatory reimbursement policies still favor refillable tank models for stationary patients.
- Continuous Flow Devices:Fixed-output concentrators deliver steady oxygen streams without pulse-dose conservation.
- CPAP Machines:Positive airway pressure systems manage sleep-disordered breathing with optional oxygen adjunct capability.
Volume sits with CPAP Machines; growth tilts toward Portable Concentrators.
Application:
Clinical severity and disease prevalence reshape addressable patient populations across respiratory and cardiac indications.
- Chronic Obstructive Pulmonary Disease:Progressive airflow limitation creates chronic hypoxemia requiring long-term supplemental oxygen. Japan's METI reimbursement revisions for home oxygen therapy now extend device rental coverage to mild cases previously excluded from public support, expanding the eligible population.
- Sleep Apnea:Obstructive and central sleep-disordered breathing events respond to positive pressure with oxygen titration. Integrated diagnostic-to-treatment pathways in Australian hospital systems bundle pulse oximetry screening with automated CPAP-oxygen combination therapy.
- Asthma:Acute bronchospasm episodes occasionally require short-term oxygen support during exacerbations.
- Congenital Heart Disease:Cyanotic defects in pediatric populations demand precise flow-controlled oxygen to balance pulmonary and systemic circulation.
COPD anchors installed base volume; Sleep Apnea climbs the fastest on screening expansion.
End User:
Capital intensity and reimbursement methodology differentiate procurement behavior across care delivery settings.
- Hospitals:Acute care facilities deploy high-flow nasal cannula systems and non-invasive ventilation for ICU protocols favoring oxygen delivery over mechanical intubation. Dutch hospital systems pilot closed-loop saturation control for post-surgical wards, automating nursing workload redistribution.
- Homecare:Post-acute migration from hospital walls expands durable medical equipment procurement through consolidated regional health networks. Direct-to-patient subscription models in the United States bypass traditional distributors who previously captured forty to sixty percent of device margin.
- Rehabilitation Centers:Pulmonary rehabilitation programs utilize portable concentrators for exercise tolerance testing and ambulatory training.
- Long-Term Care Facilities:Skilled nursing environments balance stationary system reliability with overnight monitoring requirements.
Hospitals dominate capital expenditure; Homecare gains share fastest on reimbursement restructuring.
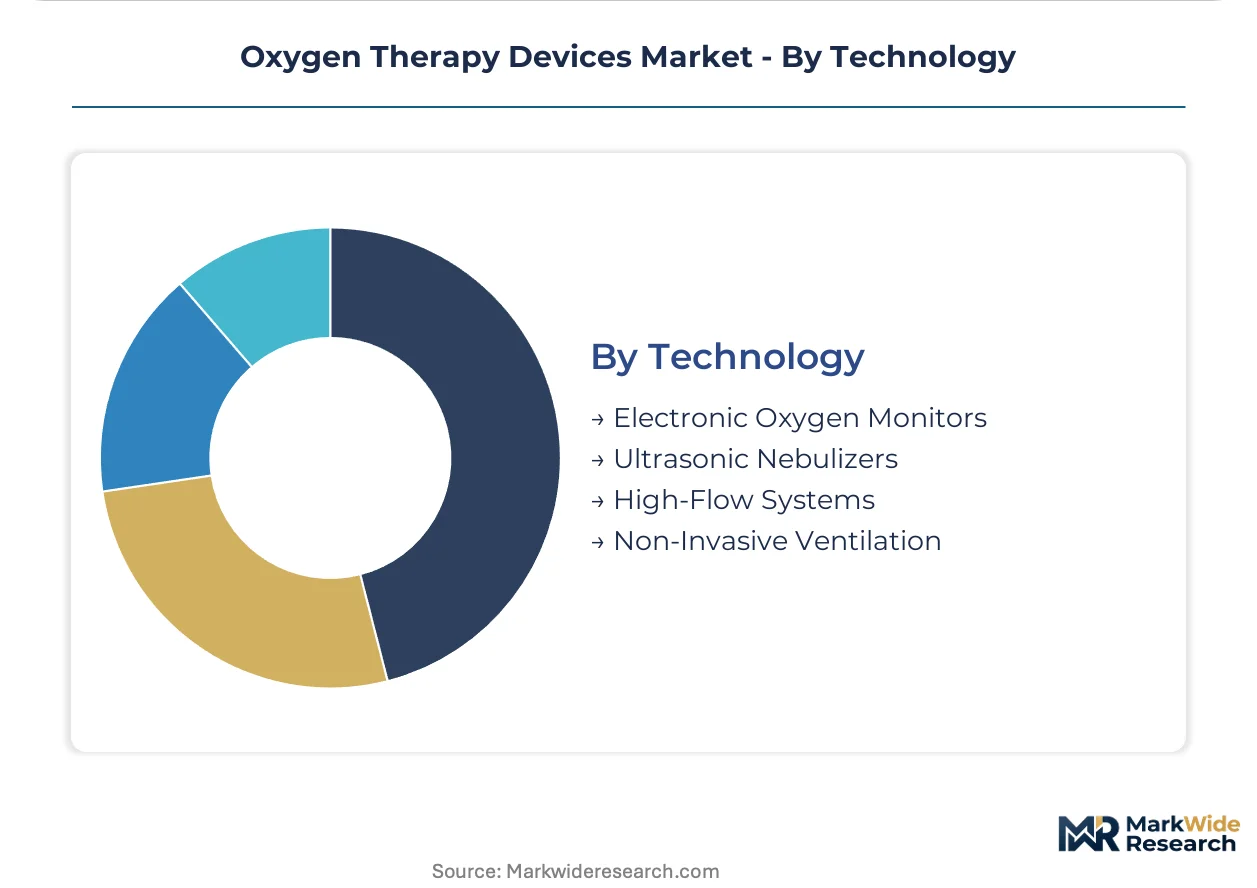
Technology:
Integration complexity and clinical outcome evidence determine adoption velocity across device generations.
- High-Flow Systems:Heated humidified oxygen delivery through nasal cannula interfaces reduces intubation rates in acute respiratory failure. ICU protocol adoption in the Netherlands and Australia positions this segment as the steepest expansion trajectory within oxygen delivery modalities.
- Non-Invasive Ventilation:Bi-level positive pressure combined with oxygen blending supports respiratory muscle fatigue without airway invasion. METI reimbursement alignment in Japan supports home-based nocturnal ventilation for neuromuscular disease populations.
- Electronic Oxygen Monitors:Pulse oximetry and fractional inspired oxygen sensors enable closed-loop titration algorithms.
- Ultrasonic Nebulizers:Aerosol medication delivery systems occasionally pair with oxygen flow for bronchodilator administration.
Electronic Oxygen Monitors penetrate widest; High-Flow Systems expand most quickly on ICU protocol shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zeolite molecular sieve deposits and rare earth processing clusters in China's Jiangxi and Inner Mongolia provinces anchor raw material supply for pressure swing adsorption systems worldwide. This feedstock geography shapes manufacturing cost structures and export quota exposure for concentrator producers across three continents.
United States
Medicare competitive bidding collapse and FAA portable oxygen certification drive patient mobility preferences toward lightweight concentrators. The FDA's 510(k) premarket notification pathway governs device clearance timelines. Device assembly concentrates in Minnesota and Ohio industrial corridors serving consolidated homecare networks.
Germany
Ambulatory oxygen reimbursement policies under statutory health insurance support portable device rental for COPD patients prioritizing mobility. The EU Medical Device Regulation's Unique Device Identification mandate imposes serialization requirements on Class IIa respiratory devices. Manufacturing and notified body certification clusters concentrate in North Rhine-Westphalia and Bavaria.
Japan
METI reimbursement revisions for home oxygen therapy extend device coverage to mild COPD cases previously excluded from public support. The PMDA oversees medical device approval under harmonized international standards. Tokyo-Osaka industrial corridors host concentrator assembly serving aging demographic demand.
India
Production-linked incentive schemes for domestic medical device manufacturing reduce import dependency for oxygen concentrators. The CDSCO regulates device registration under streamlined pathways for emergency use authorizations. Gujarat and Karnataka manufacturing zones develop tariff-advantaged export capacity for Southeast Asian markets.
Australia
Integrated diagnostic-to-treatment pathways in public hospital systems bundle pulse oximetry screening with automated therapy combinations. The TGA administers medical device inclusion in the Australian Register of Therapeutic Goods. Sydney and Melbourne clinical trial networks pilot closed-loop saturation control systems for post-surgical wards.
Oxygen Therapy Devices Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue telehealth-integrated monitoring and direct-to-patient subscription channels. Market structure tilts toward consolidation as homecare network purchasing power concentrates through regional health system mergers. Three archetypes dominate: diversified respiratory portfolio holders, portable concentrator specialists, and acute care high-flow system providers. Competitive moves center on strategic partnerships with telehealth platforms and backward integration into zeolite sieve bed manufacturing.
Among diversified portfolio holders, Fisher & Paykel Healthcare, ResMed, and Philips Healthcare exemplify scale-driven positioning across humidification, sleep-disordered breathing, and acute care oxygen delivery modalities. These entities occupy positions spanning hospital capital equipment through homecare durable medical equipment channels. Inogen Inc. represents the specialist archetype with concentrated exposure to portable concentrator design and direct-to-consumer distribution models.
| Leading Market Players |
|---|
| Fisher & Paykel Healthcare |
| Drive DeVilbiss Healthcare |
| Philips Healthcare |
| Medtronic |
| Chart Industries |
| ResMed |
| Invacare Corporation |
| GE Healthcare |
| Inogen Inc. |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up homecare distributors have compressed concentrator margins while consolidating purchasing power across regional health networks, forcing manufacturers to absorb zeolite cost volatility or cede shelf space to liquid oxygen alternatives.
Pricing Analysis
Volume concentrates in CPAP machines and stationary concentrators where Medicare competitive bidding has collapsed pricing power, while portable concentrator margins sustain premium positioning through FAA certification and direct-to-consumer subscription models. Price differentiation hinges on ISO 80601-2-69 compliance tier and after-sales service bundling, with German statutory insurance reimbursement codes supporting higher rental rates for ambulatory devices. Cost compression in the stationary segment is intensifying because liquid oxygen tank refill networks retain cost advantages for high-flow patients above fifteen liters per minute. Homecare procurement committees exhibit highest price sensitivity, whereas ICU capital equipment buyers prioritize clinical outcome evidence over unit cost.
Supply Chain Analysis
Biomedical technician certification gaps in Minnesota and Ohio industrial corridors constrain assembly capacity expansion for concentrator manufacturers serving consolidated US health networks. Feedstock sourcing draws from Chinese rare earth processing clusters in Jiangxi and Inner Mongolia for zeolite molecular sieves, Japanese precision compressor components, and German sensor modules. Single-source vulnerability concentrates in Chinese zeolite export quotas, which expose manufacturers to sudden feedstock cost spikes. Distribution runs through durable medical equipment distributors in legacy markets and direct-to-patient e-commerce portals in competitive bidding regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The oxygen therapy market sits in a technology-transition phase as closed-loop saturation control systems displace manual titration protocols in post-surgical wards.
For Market Incumbents: Deploy backward integration into zeolite sieve bed manufacturing to neutralize Chinese export quota volatility and protect concentrator gross margins. Consolidate hospital system partnerships around high-flow nasal cannula protocols that bundle heated humidification with oxygen delivery, defending against emerging entrants with telehealth-integrated monitoring. Invest in FDA 510(k) clearance acceleration for closed-loop control algorithms before EU MDR clinical evidence burdens extend competitor launch timelines. For New Entrants and Emerging Players: Launch via direct-to-patient subscription channels with insurance pre-authorization tools, bypassing DME distributors who captured forty to sixty percent of legacy device margins. Target India's PLI scheme for domestic oxygen concentrator manufacturing to access tariff-advantaged export capacity into Southeast Asian markets. Penetrate veterinary anesthesia oxygen delivery where companion animal surgical volume growth outpaces supply of compact low-flow concentrators. For Investors and Strategic Acquirers: Distressed-cycle entries favor portable concentrator specialists with captive direct-to-consumer channels in the United States, where Medicare competitive bidding has collapsed storefront networks and concentrated purchasing power. Long-term viability over a multi-year window hinges on reimbursement code alignment with ambulatory oxygen policies rather than acute care capital equipment cycles. Monitor FDA 510(k) clearance velocity for closed-loop control systems as the inflection indicator for technology transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements extend Class IIb respiratory device timelines through German notified body backlogs. |
| Hospital System Partnership | Dutch and Australian ICU protocols favor high-flow nasal cannula adoption over mechanical intubation. |
| Software Companion Development | Telehealth-integrated pulse oximetry enables automated titration alerts that reduce emergency department utilization. |
| Reimbursement Strategy | Japan's METI revisions extend home oxygen therapy coverage to mild COPD cases previously excluded. |
| Backward Integration | In-house zeolite sieve bed production neutralizes Chinese rare earth export quota exposure. |
Study Parameters
Multi-period observation of FDA 510(k) clearance timelines, Medicare competitive bidding outcomes, and METI reimbursement revisions anchored the trend analysis, supplemented by interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and homecare procurement directors. Secondary validation drew from FDA premarket notification databases, CMS Medicare claims data, EU MDR notified body certification records, and concentrator shipment customs filings. Bottom-up patient population modeling triangulated against top-down manufacturer revenue aggregation.
Segment-weighting across product architecture, clinical indication, care setting, and technology generation determined value allocation. The analytical framework modeled portable versus stationary concentrator substitution dynamics, high-flow system ICU penetration curves, and CPAP-oxygen combination therapy bundling patterns across the projection horizon. CAGRs derived from installed base turnover rates, reimbursement code expansion schedules, and ambulatory patient mobility preference shifts.
The model assumes a particular technology adoption path; alternative pathways for closed-loop oxygen control would alter the outlook if nursing workload automation protocols stall in post-surgical wards. Forecasts reflect assumptions regarding FAA portable oxygen certification continuity, EU MDR audit backlog resolution, and zeolite supply chain stability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Polyglyconate Sutures Market
Medical Devices
Global Oxygen Cylinders and Concentrators Market
Medical Devices
India Artificial Organs and Bionics Market
Medical Devices
Contraceptive Devices Market
Medical Devices
Global Biopsy Punch Market
Medical Devices
Global Hysteroscope Market
Medical Devices
Insulin Storage Devices Market
Medical Devices
Bioactive Fillings Market
Medical Devices
Bowel Irrigation System Market
Medical Devices
Foot Ulcer Sensors Market
Medical Devices
Spine Bone Stimulators Market
Medical Devices
Global Medical Suction Devices Market
Medical Devices
Global Catheter Stabilization Devices Market
Medical Devices
Europe Urinary Catheters Market
Medical Devices
Robotic Biopsy Devices Market
Medical Devices
Global Anastomosis Devices Market