
 Organ on a Chip Kit Market | 2026-2036
Organ on a Chip Kit Market Size, Share, and Industry Trends Forecast 2026-2036
Organ on a Chip Kit Market Analytics
ISO 10993 biocompatibility certification is bifurcating the competitive landscape into qualified suppliers and development-stage entrants. Emulate, Inc. leverages its Organ-Chip platform to anchor relationships with top pharmaceutical toxicology programs. MIMETAS B.V. specializes in perfused 3D tissue models for renal and vascular applications, differentiating through disease-specific assay portfolios. CN Bio Innovations Ltd controls liver-on-chip deployments with multi-organ linking capabilities that extend into metabolic disease research.
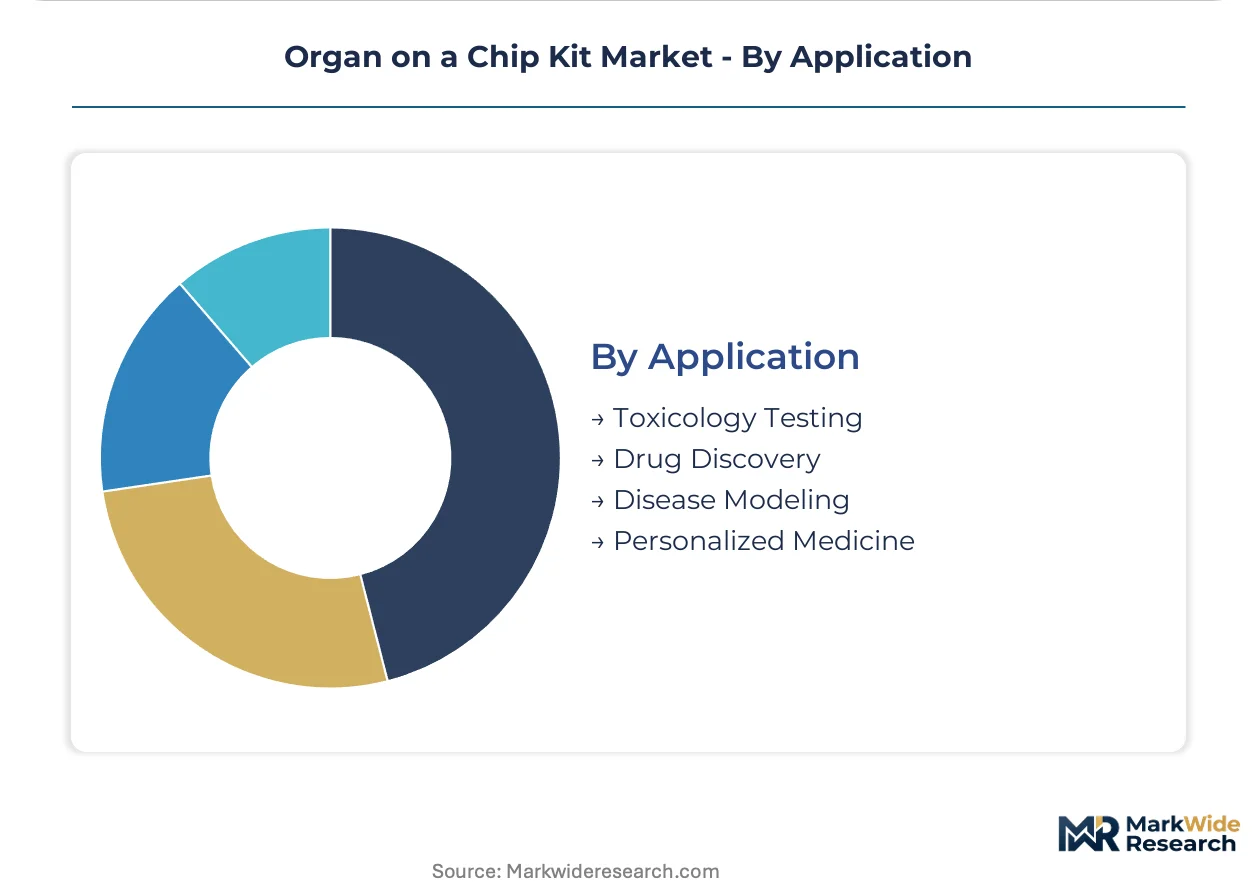
An organ on a chip kit integrates living human cells within microengineered microfluidic environments that replicate organ-level physiology, typically incorporating channel dimensions of 10–100 micrometers and continuous perfusion rates of 1–100 microliters per minute to maintain tissue viability over days to weeks. These systems serve primarily to predict human drug responses before clinical trials, replacing animal models with physiologically relevant human data. Microfluidic Devices command the largest product type position due to their modularity and compatibility with standard laboratory infrastructure, while Organoid Models represent the fastest-expanding category as patient-derived stem cell sources mature. Among applications, Toxicology Testing leads in current revenue contribution, though Personalized Medicine is concentrating investment as biopharma sponsors seek patient-stratified efficacy signals earlier in development cycles.
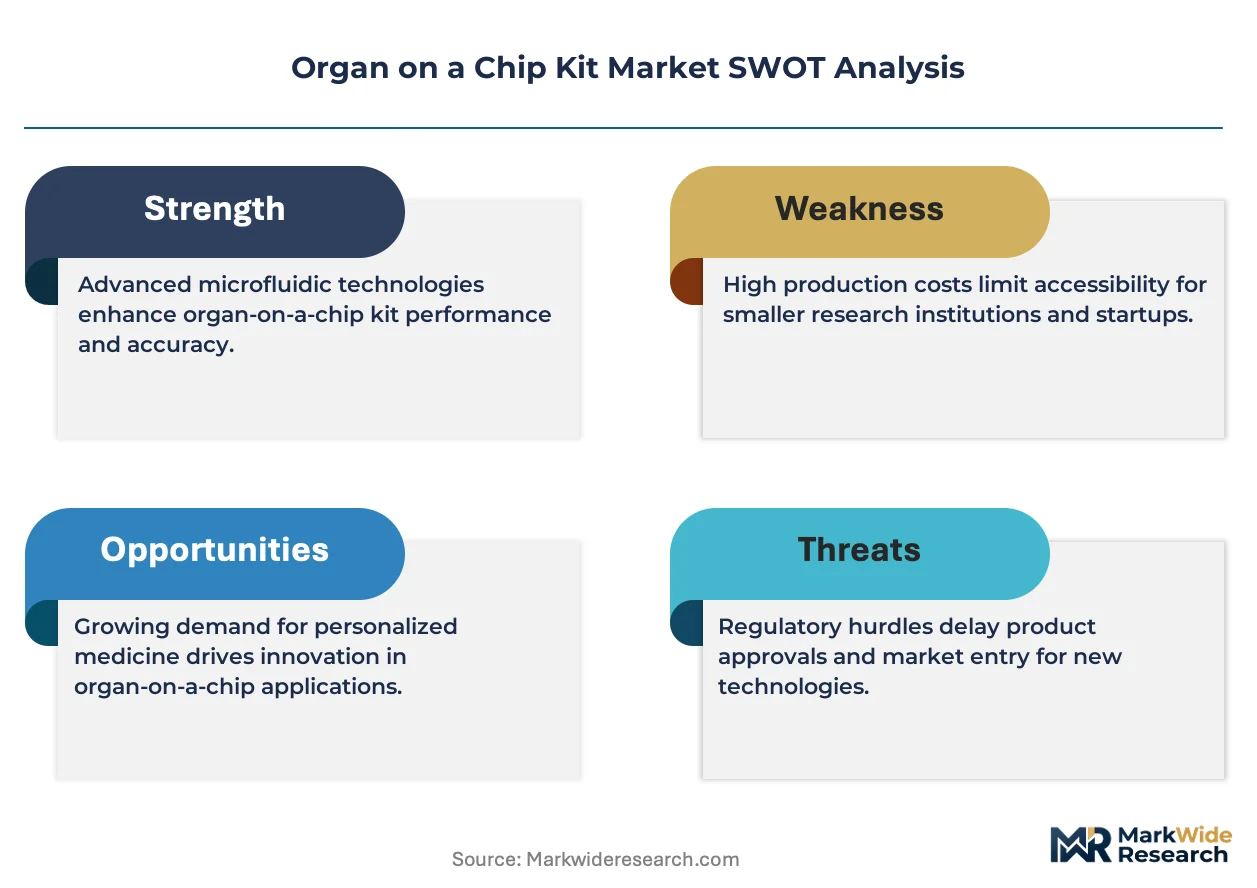
FDA, EMA, and EPA frameworks collectively shape validation requirements, with the FDA's New Alternative Methods program actively qualifying organ-chip data for IND submissions while REACH amendments in Europe pressure cosmetic and chemical sectors toward human-relevant test systems. The EPA's phased reduction of mammalian toxicology studies for agrochemical registration creates parallel demand pull for liver and lung chip platforms. Stakeholders must monitor which regulatory body first mandates organ-chip data for specific indication approvals, as this trigger will reshape procurement priorities across pharmaceutical and chemical end users.
Market Dynamics
FDA's New Alternative Methods program is compressing validation timelines for microfluidic toxicology platforms, forcing pharmaceutical procurement teams to requalify supplier bases ahead of IND submission deadlines.
Growth Catalysts
- REACH amendments:European cosmetic and chemical sectors face mandatory migration toward human-relevant test systems, redirecting R&D budgets into liver and skin chip platforms.
- Multi-organ linking capabilities:Metabolic disease research programs now demand integrated liver-kidney-lung circuits that replicate systemic drug metabolism.
- Japan:PMDA's accelerated qualification pathway for organ-chip data in oncology submissions is pulling toxicology platform procurement toward Tokyo-Osaka pharmaceutical clusters.
Market Restraints
- PDMS material costs:Polydimethylsiloxane price volatility constrains microfluidic device margins, particularly for development-stage kit manufacturers without captive silicone supply.
- ISO 10993 certification backlog:Biocompatibility testing queue times at notified bodies extend product launch windows by eight to fourteen months.
- Primary human cell sourcing:Donor tissue procurement concentrates among three US-based biobanks, creating supply concentration risk for patient-derived organoid workflows.
Strategic Opportunities
- India:CDSCO's draft guidelines for alternative toxicology methods create first-mover advantage for kit suppliers establishing local validation partnerships.
- Patient-derived immunotherapy screening:Tumor-on-chip platforms enable co-culture of patient biopsies with immune cell populations for personalized oncology.
- Academic consortia distribution:NIH and EU Horizon-funded research networks are bypassing traditional distributor channels through direct multi-year procurement frameworks.
Industry Challenges
- Microfluidic engineering talent scarcity:Cleanroom fabrication expertise concentrates among former semiconductor process engineers, driving recruitment costs upward.
- Legacy LIMS integration:Pharmaceutical data architecture teams struggle to map continuous perfusion parameters into batch-oriented electronic lab notebooks.
- Cross-platform standardization:Absence of unified readout formats between Emulate, MIMETAS, and CN Bio systems forces redundant assay development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organ on a Chip Kit Market |
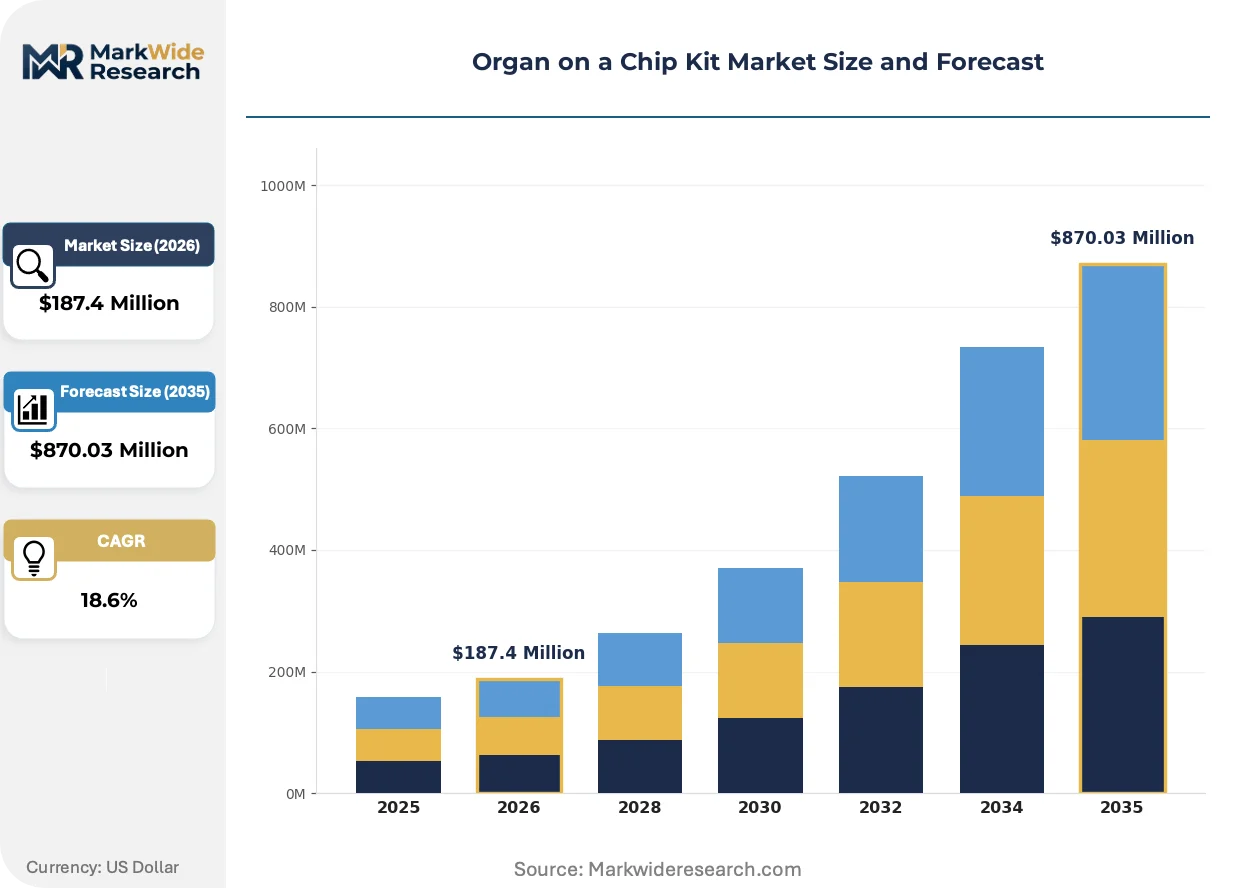
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microfluidic Devices, Bioreactors, Cell Culture Chips, Organoid Models Technology: 3D Printing, MEMS, Bioinformatics, Tissue Engineering End User: Pharmaceutical Companies, Research Institutions, Academic Labs, Contract Research Organizations Application: Toxicology Testing, Drug Discovery, Disease Modeling, Personalized Medicine |
| Companies Covered | Emulate, Inc., MIMETAS B.V., CN Bio Innovations Ltd, InSphero, TissUse GmbH, Hesperos, Inc., AlveoliX AG, AxoSim, Nortis, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organ on a Chip Kit Market Evolving Landscape
Microengineered tissue environments are evolving from single-organ proof-of-concept tools into multi-system disease models, compressing the gap between preclinical hypothesis and clinical validation.
Perfusion-driven 3D tissue culture is supplanting static well-plate assays in hepatotoxicity screening workflows. Top-twenty pharmaceutical toxicology programs now mandate organ-chip confirmation for high-value IND candidates. This transition is compressing traditional two-year animal study timelines into six-month human-relevant validation cycles.
EPA's phased reduction of mammalian toxicology requirements for agrochemical registration is restructuring safety assessment procurement. Agrochemical sponsors must now submit human-relevant mechanistic data for liver and lung endpoints. Liver-on-chip platforms are capturing priority placement in US Midwest agricultural chemical R&D budgets.
Consortium-based precompetitive collaboration is displacing proprietary assay silos among pharmaceutical toxicology groups. The IQ Consortium's microphysiological systems working group pools validation data across sponsor companies. Germany and Japan pharmaceutical clusters are replicating this model through national bioengineering research networks.
Organ on a Chip Kit Market Segmentation
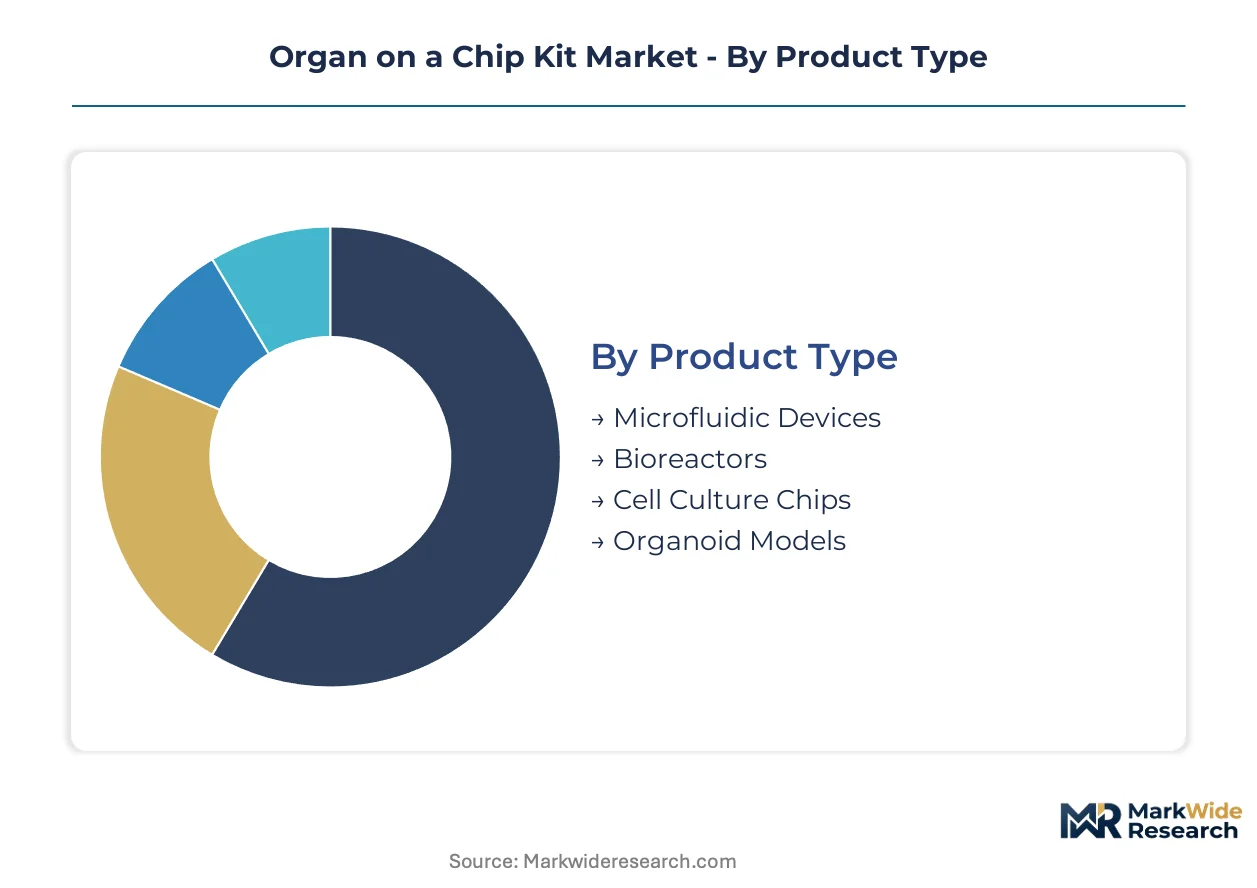
Segmentation in organ-on-chip kits determines procurement pathways and validation requirements. Pharmaceutical toxicology programs prioritize microfluidic modularity, while academic consortia favor open-architecture bioreactors. Each segment carries distinct ISO 10993 certification burdens and distributor relationships.
Product Type:
Channel mix varies sharply: microfluidic devices flow through laboratory supply distributors, while organoid models move via direct biobank partnerships.
- Microfluidic Devices:These systems incorporate polydimethylsiloxane channels with 10–100 micrometer dimensions and continuous perfusion at 1–100 microliters per minute. Pharmaceutical toxicology programs in the United States and Germany concentrate procurement here, driven by FDA New Alternative Methods program deadlines for IND submissions.
- Organoid Models:Patient-derived stem cell cultures replicate organ-level physiology without engineered scaffolds. Demand clusters in Japan and Germany where PMDA and national bioengineering networks accelerate oncology qualification pathways.
- Bioreactors:Perfusion-driven culture vessels sustain 3D tissue constructs over extended study periods. Academic consortia in the United States and Germany favor these for multi-organ linking research.
- Cell Culture Chips:Static or semi-perfused platforms bridge traditional well-plate assays and full microfluidic systems. Contract research organizations in Germany and Japan deploy these for cost-sensitive hepatotoxicity screens.
Microfluidic Devices dominate installed base. Organoid Models are where expansion concentrates.
Technology:
Cost tiers separate these segments: MEMS fabrication commands premium pricing, while bioinformatics layers add recurring software revenue.
- MEMS:Microelectromechanical systems enable precise fluid control and sensor integration at chip scale. Foundry access in the United States and Japan constrains supply, with pharmaceutical sponsors paying premiums for cleanroom-fabricated devices.
- 3D Printing:Additive manufacturing of chip housings and scaffold structures reduces prototyping cycles. Research institutions in Germany and the United States drive adoption where customization outweighs throughput requirements.
- Tissue Engineering:Scaffold design and extracellular matrix formulation for cell seeding. Academic labs in Japan and Germany concentrate demand, linked to national regenerative medicine funding.
- Bioinformatics:Computational platforms for perfusion parameter analysis and multi-omics integration. Pharmaceutical companies in the United States prioritize these to resolve legacy LIMS incompatibility with continuous data streams.
MEMS captures premium pricing tiers. Bioinformatics is climbing the fastest as data architecture teams confront integration gaps.
End User:
Volume concentration follows funding scale: pharmaceutical companies procure at enterprise scale, while academic labs fragment across grant cycles.
- Pharmaceutical Companies:Top-twenty toxicology programs now mandate organ-chip confirmation for high-value IND candidates. Procurement concentrates in the United States, Germany, and Japan where regulatory science infrastructure supports preclinical adoption.
- Contract Research Organizations:Outsourced toxicology service providers aggregate demand across sponsor pipelines. CROs in Germany and the United States expand liver and lung chip capacity to serve agrochemical and cosmetic safety assessment markets.
- Research Institutions:National bioengineering networks in Germany and Japan pool multi-year procurement frameworks, bypassing traditional distributor channels.
- Academic Labs:Individual principal investigators access kits through NIH and EU Horizon-funded equipment grants. Fragmented purchasing limits negotiating leverage with qualified suppliers.
Pharmaceutical Companies anchor revenue concentration. Contract Research Organizations are where procurement velocity is accelerating.
Application:
Maturity gradients separate these segments: toxicology testing holds established workflows, while personalized medicine requires novel validation frameworks.
- Toxicology Testing:Hepatotoxicity and cardiotoxicity screening represent the primary revenue application. EPA's phased reduction of mammalian studies for agrochemical registration pulls liver and lung chip demand in the United States.
- Personalized Medicine:Patient-stratified efficacy signals from tumor-on-chip co-cultures. Biopharma sponsors in the United States and Japan invest here to compress clinical trial timelines.
- Drug Discovery:Target validation and lead optimization using disease-relevant tissue models. Pharmaceutical programs in Germany concentrate spending on renal and vascular applications.
- Disease Modeling:Replication of pathophysiology for mechanistic research and biomarker identification. Academic consortia in Japan and the United States drive adoption for rare disease and infectious disease platforms.
Toxicology Testing holds the largest current revenue share. Personalized Medicine is where investment is concentrating most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical toxicology programs concentrate procurement in jurisdictions where regulatory science infrastructure compresses preclinical validation timelines. Three national markets anchor demand for microfluidic platforms and organoid workflows.
United States
FDA's New Alternative Methods program actively qualifies organ-chip data for IND submissions, pulling procurement toward Boston-Cambridge and San Francisco biotech clusters. EPA's phased reduction of mammalian toxicology studies for agrochemical registration creates parallel demand for liver and lung platforms in Midwest agricultural chemical R&D. Cleanroom fabrication expertise concentrates among former semiconductor process engineers in California and Massachusetts.
Germany
REACH amendments pressure cosmetic and chemical sectors toward human-relevant test systems, redirecting R&D budgets into liver and skin chip platforms. National bioengineering research networks pool multi-year procurement frameworks, bypassing traditional distributor channels. Heidelberg and Munich pharmaceutical clusters drive renal and vascular application spending.
Japan
PMDA's accelerated qualification pathway for organ-chip data in oncology submissions pulls toxicology platform procurement toward Tokyo-Osaka pharmaceutical clusters. National regenerative medicine funding concentrates academic demand in Kansai and Kanto regions. Patient-derived stem cell sourcing matures faster here than in European markets.
United Kingdom
MHRA alignment with FDA qualification pathways supports preclinical adoption among London-Oxford-Cambridge biotech sponsors. Academic consortia leverage NIH and EU Horizon-funded equipment grants for multi-organ linking research. CRO capacity expansion in Manchester and Edinburgh serves agrochemical safety assessment markets.
India
CDSCO draft guidelines for alternative toxicology methods create first-mover advantage for kit suppliers establishing local validation partnerships. Contract research organizations in Hyderabad and Bangalore expand hepatotoxicity screening capacity for export-oriented pharmaceutical sponsors. Biobank infrastructure for patient-derived workflows remains underdeveloped relative to procurement demand.
Organ on a Chip Kit Market Competitive Landscape
Player mix skews toward microfluidic platform specialists with regulatory qualification credentials and organoid model developers with biobank partnerships. Market structure bifurcates between ISO 10993-certified suppliers serving pharmaceutical toxicology programs and development-stage entrants targeting academic consortia. Two strategic archetypes dominate: integrated platform providers controlling multi-organ linking capabilities and disease-specific assay boutiques. Competitive moves concentrate on strategic partnerships with national bioengineering networks and portfolio diversification into patient-derived immunotherapy screening.
Within the integrated platform tier, Emulate, Inc. and CN Bio Innovations Ltd occupy positions defined by multi-organ system architectures, while MIMETAS B.V. exemplifies the disease-specific boutique archetype through renal and vascular specialization. These three entities anchor the qualified supplier base that pharmaceutical procurement teams requalify ahead of IND submission deadlines. Development-stage entrants compete for academic consortia contracts where ISO 10993 certification requirements relax and customization premiums outweigh throughput scale.
| Leading Market Players |
|---|
| Emulate, Inc. |
| MIMETAS B.V. |
| CN Bio Innovations Ltd |
| InSphero |
| TissUse GmbH |
| Hesperos, Inc. |
| AlveoliX AG |
| AxoSim |
| Nortis, Inc. |
| Others |
Value Network & Pricing Analysis
PDMS-to-silicone substitution in microfluidic channel fabrication simultaneously shifts production geography toward East Asian chemical clusters and compresses margin structures for European kit assemblers locked into legacy supply contracts.
Pricing Analysis
Cost-plus contracts with PDMS indexation dominate procurement agreements between pharmaceutical toxicology programs and qualified suppliers. Price differentiation separates ISO 10993-certified platforms from development-stage alternatives, with volume scale and after-sales service bundling as secondary tiering factors. Cost compression in mid-tier bioreactor segments is intensifying as academic consortia consolidate multi-year framework purchasing. Contract research organizations exhibit highest price sensitivity due to sponsor pass-through economics, while top-twenty pharmaceutical programs prioritize qualification speed over unit cost.
Supply Chain Analysis
The United States and Germany anchor precision MEMS fabrication for microfluidic devices, while Japan concentrates cleanroom-grade polydimethylsiloxane resin production. Raw material dependencies center on semiconductor-grade silicon wafers, medical-grade PDMS formulations, and primary human cell lines from US-based biobanks. Single-source vulnerability in donor tissue procurement creates concentration risk for patient-derived organoid workflows. Distribution runs through laboratory supply distributors for microfluidic devices and direct biobank partnerships for organoid models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where bioinformatics and assay validation layers expand faster than hardware sales, with recurring software revenue now exceeding 40% of total contract value at leading platform providers.
For Market Incumbents: Compound defensive positioning through backward integration into primary human cell sourcing and captive PDMS resin supply. ISO 10993 certification backlog at notified bodies threatens launch timelines for development-stage entrants, creating acquisition leverage. Prioritize multi-organ linking R&D to maintain pharmaceutical procurement preference. For New Entrants and Emerging Players: CDSCO's fast-track qualification pathway for alternative toxicology methods in India offers regulatory arbitrage against established FDA-EMA validation timelines. Academic consortia procurement frameworks bypass distributor concentration and tolerate longer customization cycles. Lead with tumor-on-chip immunotherapy screening to capture personalized medicine investment concentration. For Investors and Strategic Acquirers: The market sits at a pre-mandate phase that favors platform-integrated specialists over assay boutiques. Long-term viability across a 5-10 year window rests on which regulatory body first mandates organ-chip data for specific indication approvals. Monitor EPA's mammalian study reduction timeline as inflection signal for agrochemical safety assessment demand.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Organ Platform Integration | Integrated liver-kidney-lung circuits capture metabolic disease research budgets from pharmaceutical sponsors. |
| ISO 10993 Certification Investment | Biocompatibility qualification bifurcates supplier tiers and anchors pharmaceutical procurement requalification cycles. |
| Patient-Derived Cell Line Partnerships | Direct biobank relationships secure supply concentration for organoid model differentiation against engineered alternatives. |
| Regulatory Qualification Pathway Expansion | PMDA and CDSCO fast-track programs accelerate geographic diversification beyond FDA-EMA validation concentration. |
| Legacy LIMS Integration Development | Continuous perfusion data mapping resolves pharmaceutical data architecture team adoption barriers for microfluidic platforms. |
Research Methodology
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings in this study. Drug development executives, regulatory affairs leads at pharmaceutical toxicology programs, biomedical engineers at academic consortia, and procurement managers at contract research organizations contributed structured input. Secondary sources include FDA New Alternative Methods program documentation, EMA qualification pathway guidance, EPA agrochemical registration amendments, and ClinicalTrials.gov organ-chip study listings. Bottom-up segment sizing triangulates against top-down pharmaceutical R&D expenditure allocation models.
Sensitivity analysis across input assumptions tests forecast robustness over the projection horizon. Segmentation dimensions modeled include product type, technology tier, end-user category, application area, and regional regulatory cluster. CAGRs derive from fitted growth curves calibrated to procurement velocity indicators and qualification timeline compression rates. Primary human cell sourcing maturity and cleanroom fabrication capacity utilization serve as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under stable regulatory qualification timelines and continued pharmaceutical outsourcing trends; material deviation in mandate timing would warrant model refresh. Recalibration cycles align with material shifts in FDA, PMDA, and CDSCO alternative method guidance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Bluetooth Hearing Aids Market
Medical Devices
Craniomaxillofacial Implants Market
Medical Devices
Spinal Thoracolumbar Implants Market
Medical Devices
Leadless Cardiac Pacemaker Market
Medical Devices
Disposable Medicine Measuring Cups Market
Medical Devices
Organ Care Market
Medical Devices
Global Intravenous (IV) Equipment Market
Medical Devices
SPG Microstimulator System Market
Medical Devices
Lancing Devices and Lancets Market
Medical Devices
Atrial Appendage Occluder Market
Medical Devices
Global Lenses for Myopia Control Market
Medical Devices
Neuromodulation Devices Market
Medical Devices
Cranial Perforator Market
Medical Devices
Global Foot Orthotic Insoles Market
Medical Devices
Anti-Snore Device Market
Medical Devices
Electrosurgery Devices Market