
 Vitreous Detachment Treatment Market | 2026-2036
Vitreous Detachment Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Vitreous Detachment Treatment Market Insights
Ophthalmology clinics is rebalancing toward minimally invasive outpatient procedures as patient preference shifts away from extended hospital stays. Alcon leverages its integrated surgical platform portfolio to sustain dominance across vitrectomy instrument ecosystems. Bausch + Lomb anchors its position through specialized diagnostic and therapeutic combinations for posterior segment disorders. Carl Zeiss Meditec AG differentiates via precision imaging systems that guide real-time surgical decision-making.
Vitreous detachment treatment encompasses surgical, pharmacological, and laser-based interventions designed to address symptomatic posterior vitreous separation and its complications, typically involving instrumentation capable of sub-millimetre manipulation within the vitreous cavity or targeted photocoagulation at wavelengths between 532 nm and 577 nm. The primary commercial purpose centers on preventing retinal tear progression, reducing debilitating floaters, and preserving visual acuity in patients over fifty years of age. Laser Devices command expanding share within the product type matrix as clinic-based YAG vitreolysis gains procedural acceptance for floater management. Minimally Invasive delivery modes capture the fastest growth trajectory, displacing traditional inpatient paradigms through reduced recovery intervals and lower complication profiles. Diagnostic Tools concentrate margin pools where optical coherence tomography integration enables preoperative stratification and treatment planning.
FDA 510(k) pathways govern device commercialization in the United States, while the EU MDR and CE marking framework impose strengthened clinical evidence requirements for ophthalmic surgical instruments across European markets. Japan's PMDA maintains distinct technical standards for laser ophthalmic equipment, creating segmented approval strategies for manufacturers seeking multi-regional presence. Stakeholders must monitor evolving reimbursement classifications for outpatient retinal procedures and anticipate how regulatory divergence between major markets will shape portfolio prioritization and clinical trial investment.
Market Dynamics
Minimally invasive laser-based interventions are compressing procedural recovery timelines and redirecting patient volume away from conventional vitrectomy suites toward outpatient ophthalmology clinics.
Growth Catalysts
- Aging Demographics:Expanding populations over fifty years of age in the United States, Germany, and Japan generate sustained demand for symptomatic floater management and retinal tear prevention protocols.
- FDA 510(k) Pathways:Streamlined device clearance mechanisms accelerate commercialization timelines for novel YAG vitreolysis platforms and specialized ophthalmic laser systems.
- Outpatient Infrastructure:Specialist retinal care networks in Japan and Germany deploy clinic-based photocoagulation capabilities that reduce hospital admission requirements.
Market Restraints
- Specialized Instrument Costs:Precision vitrectomy instrumentation and integrated imaging platforms require substantial capital deployment, constraining smaller clinic adoption.
- EU MDR Compliance Burden:Strengthened clinical evidence requirements for CE marking extend product development cycles and elevate regulatory expenditure for European market entry.
- Technical Limitations:YAG laser vitreolysis demonstrates variable efficacy across floater densities and anatomical locations, restricting addressable patient populations.
Strategic Opportunities
- Underpenetrated Markets:Brazil and Saudi Arabia exhibit expanding specialist ophthalmology infrastructure without proportional laser-based vitreolysis penetration.
- Technology Convergence:Integration of optical coherence tomography with real-time surgical navigation enables preoperative stratification and intraoperative precision guidance.
- Reimbursement Evolution:Outpatient retinal procedure classifications in the United States are shifting toward value-based frameworks that favor minimally invasive modalities.
Industry Challenges
- Vitreoretinal Surgeon Scarcity:Subspecialty fellowship training programs produce insufficient practitioners to match procedural demand growth in aging markets.
- Equipment Integration Complexity:Legacy diagnostic platforms in established clinics resist seamless connectivity with next-generation laser delivery systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vitreous Detachment Treatment Market |
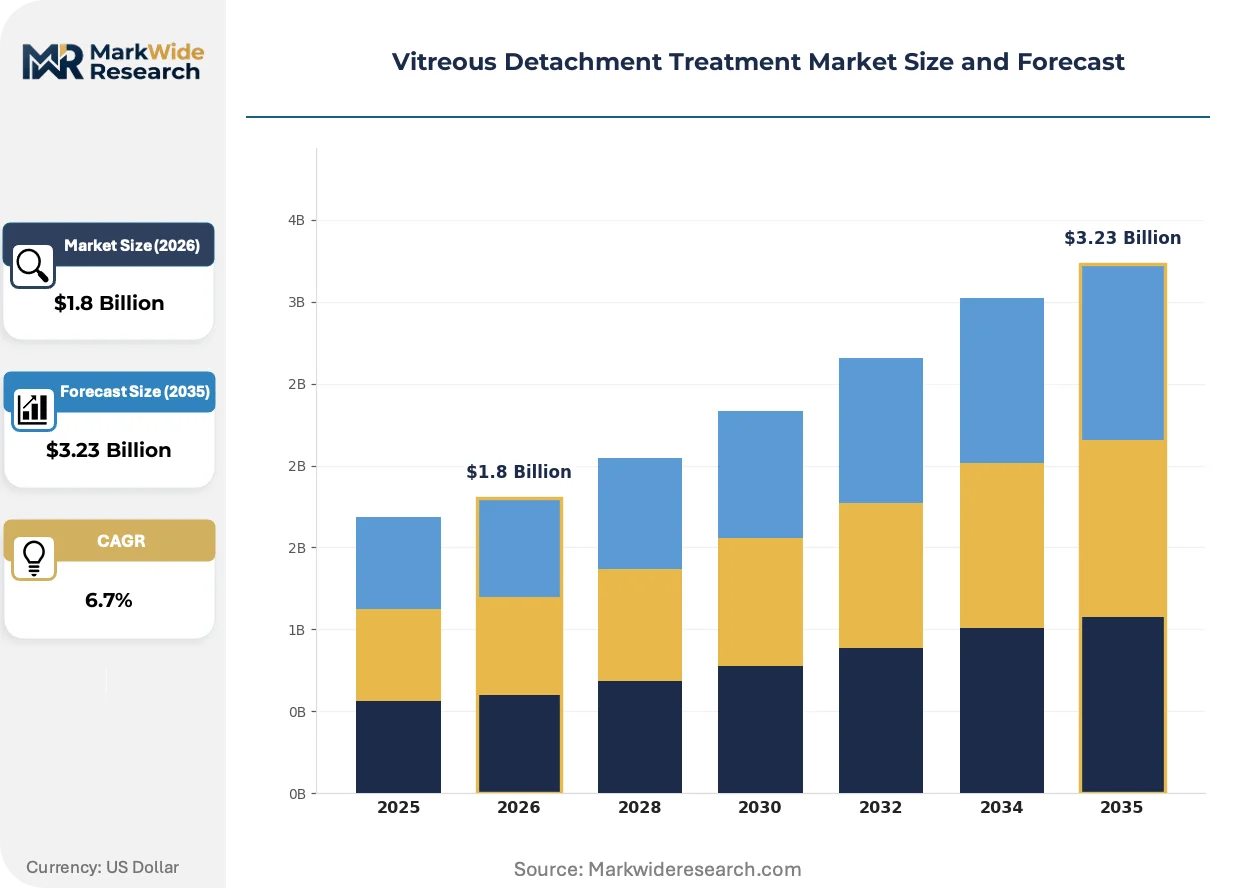
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Instruments, Laser Devices, Injection Agents, Diagnostic Tools Application: Retinal Detachment, Floaters, Macular Holes, Vision Correction Delivery Mode: Invasive, Minimally Invasive, Outpatient, Inpatient End User: Ophthalmology Clinics, Hospitals, Research Labs, Home Care |
| Companies Covered | Alcon, Bausch + Lomb, Carl Zeiss Meditec AG, Ellex Medical Lasers Ltd., NIDEK CO., LTD., Iridex Corporation, Topcon Corporation, Dutch Ophthalmic Research Center, Geuder AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vitreous Detachment Treatment Market Trends and Innovations
Precision imaging integration and regulatory pathway evolution are restructuring how vitreous detachment interventions are planned, delivered, and reimbursed across major ophthalmology markets.
Laser vitreolysis technology is consolidating market share within symptomatic floater management as ophthalmology clinics in the United States and Japan adopt 532 nm to 577 nm wavelength systems for outpatient procedures. Retinal specialists favor these platforms for their reduced complication profiles compared to pars plana vitrectomy. The technology is consolidating previously fragmented treatment approaches into standardized clinic-based protocols.
The EU MDR framework imposes strengthened clinical evidence requirements for ophthalmic surgical instruments, compelling manufacturers to expand premarket trial investments and extend European commercialization timelines. Device sponsors must now demonstrate sustained safety and performance across broader patient cohorts. Laser equipment categories face particular scrutiny given their classification as active therapeutic devices.
Patient preference patterns favor reduced recovery intervals and same-day discharge protocols, compressing demand toward ambulatory surgical centers and specialized ophthalmology clinics. Traditional hospital-based vitrectomy suites encounter volume pressure as reimbursement frameworks align with outpatient efficiency metrics. Germany and Japan demonstrate the most pronounced channel migration, where specialist clinic networks already dominate retinal disease management.
Vitreous Detachment Treatment Market Segmentation
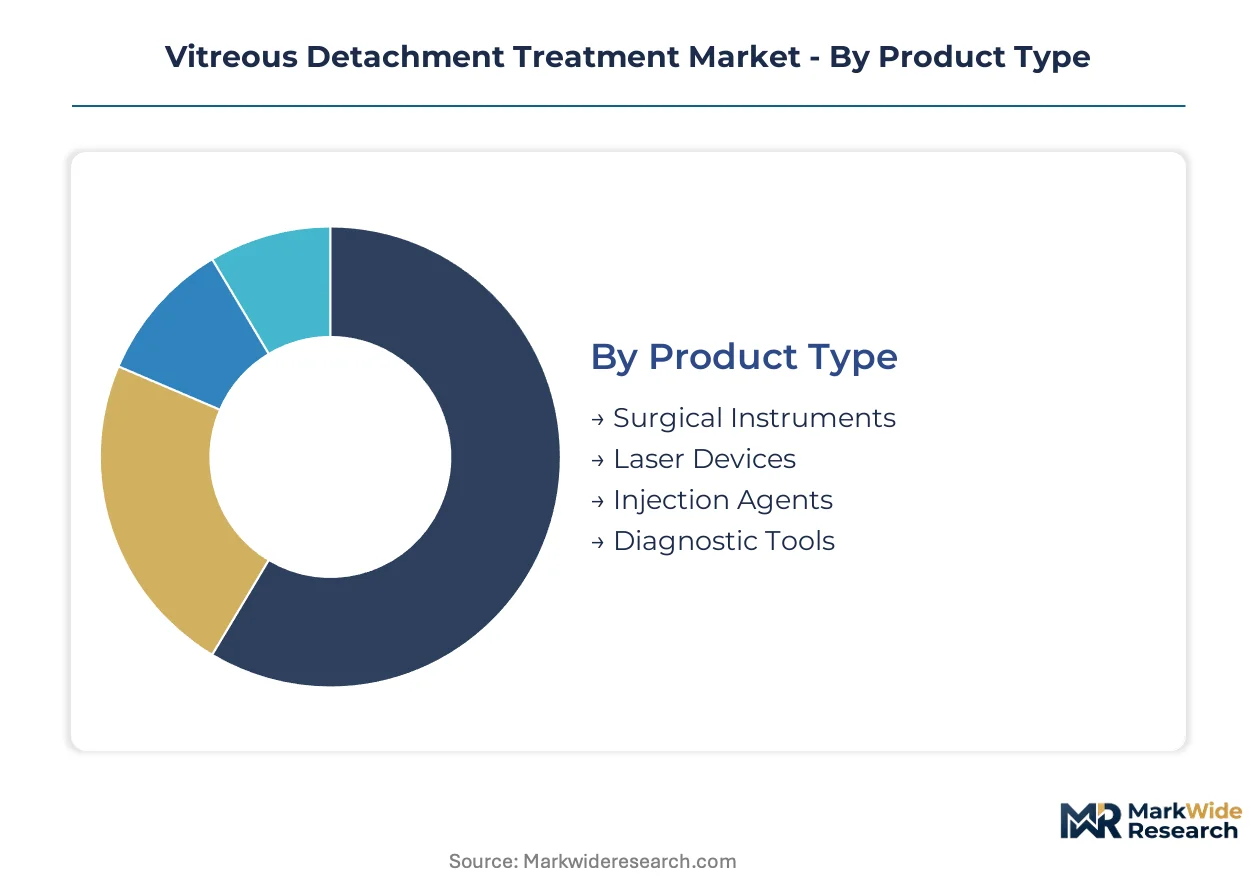
Segmentation in vitreous detachment treatment reveals how technology specialization and care setting preferences fragment commercial opportunity across distinct equipment categories and patient pathways. Understanding these divisions enables targeted portfolio positioning against reimbursement and infrastructure variations.
Product Type:
Customization intensity spans from commoditized consumables to precision-engineered capital equipment requiring extensive clinical validation.
- Surgical Instruments:Pars plana vitrectomy packs and microforceps dominate procedural volume in hospital settings. Demand concentrates in Germany and Japan where vitreoretinal fellowship training sustains complex surgical caseloads.
- Laser Devices:YAG vitreolysis platforms operating at 532 nm to 577 nm wavelengths enable outpatient floater fragmentation. United States ophthalmology clinics drive adoption as FDA 510(k) pathways accelerate commercial deployment.
- Injection Agents:Pharmacological vitreolytics target enzymatic posterior vitreous separation.
- Diagnostic Tools:Optical coherence tomography systems guide preoperative stratification and surgical planning.
Most installed capacity flows through Surgical Instruments. Expansion is steepest in Laser Devices.
Application:
Clinical urgency and reimbursement generosity create divergent margin profiles across indication severity.
- Retinal Detachment:Emergency surgical intervention prevents permanent vision loss. United States hospital systems maintain dedicated on-call protocols given medicolegal exposure and sight-threatening progression risk.
- Floaters:Symptomatic vitreous opacities drive elective YAG laser demand. Japanese specialist clinics report highest procedural density as aging demographics amplify patient presentation rates.
- Macular Holes:Centrally located retinal defects require precise surgical closure.
- Vision Correction:Refractive outcomes influence device selection in premium service tiers.
Retinal Detachment commands premium pricing. Floaters are gaining share fastest.
Delivery Mode:
Capital intensity and recovery economics determine channel viability across care settings.
- Invasive:Traditional pars plana vitrectomy requires operating room infrastructure and general anesthesia. German university hospitals retain substantial volume given complex case referrals.
- Minimally Invasive:Laser-based and small-gauge approaches reduce tissue trauma. United States ambulatory surgical centers favor these modalities under shifting reimbursement incentives.
- Outpatient:Same-day discharge protocols align with patient preference and payer efficiency metrics.
- Inpatient:Extended stays concentrate in complicated cases requiring multidisciplinary management.
Outpatient settings absorb the majority of procedural volume. Minimally Invasive approaches show the steepest expansion trajectory.
End User:
Purchasing sophistication and budget authority vary sharply across institutional types.
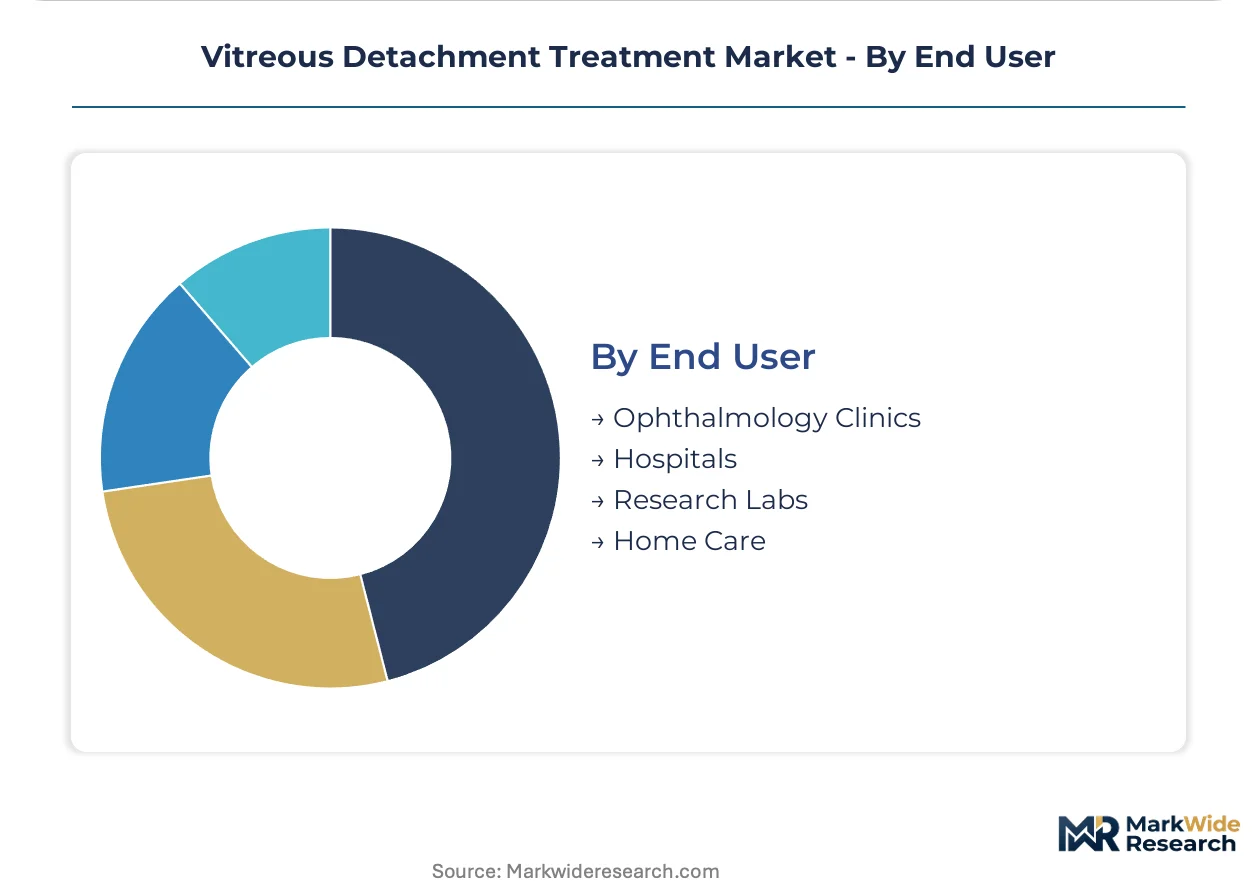
- Ophthalmology Clinics:Specialist retinal practices prioritize integrated diagnostic-laser platforms. Japan's clinic networks demonstrate highest equipment density per capita among aging populations.
- Hospitals:Academic medical centers sustain vitrectomy volume for complex surgical training. United States tertiary centers anchor referral networks for complicated detachments.
- Research Labs:Preclinical development sites evaluate novel vitreolytic compounds.
- Home Care:Monitoring applications remain nascent given procedural invasiveness constraints.
Ophthalmology Clinics represent the primary revenue channel. Research Labs are expanding most quickly as pharmaceutical sponsors advance vitreolytic pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping commercialization sequencing as manufacturers prioritize FDA 510(k) pathways over EU MDR compliance timelines, compressing United States market entry ahead of European launches. Divergent reimbursement frameworks and specialist infrastructure density create sharply contrasting addressable markets across major economies.
United States
Outpatient surgical center expansion and value-based reimbursement shifts accelerate YAG vitreolysis adoption. FDA 510(k) pathways enable faster commercial deployment of laser platforms compared to European counterparts. Retinal specialist concentration in metropolitan clusters like Boston and Manhattan drives highest procedural density per capita.
Germany
University hospital networks sustain complex vitrectomy caseloads while ambulatory clinic infrastructure proliferates. EU MDR compliance requirements extend product registration timelines and elevate clinical evidence burdens. The Rhine-Ruhr and Bavarian medical technology corridors concentrate precision instrument manufacturing and surgeon training capacity.
Japan
Aging demographics exceeding global averages generate sustained symptomatic floater presentation rates. PMDA technical standards for laser ophthalmic equipment create distinct approval pathways requiring localized clinical data. Tokyo and Osaka specialist clinic networks demonstrate highest per-capita density of integrated diagnostic-laser platforms.
Brazil
Expanding private ophthalmology infrastructure in São Paulo and Rio de Janeiro outpaces public sector retinal care capacity. ANVISA regulatory frameworks for active therapeutic devices require adapted submission strategies versus North American or European precedents. Southeast regional medical hubs attract investment in outpatient photocoagulation capabilities.
Saudi Arabia
Vision 2030 healthcare privatization drives specialist clinic construction and medical tourism positioning. SFDA medical device regulations increasingly align with international standards while maintaining Gulf-specific requirements. Riyadh and Jeddah ophthalmology centers import premium laser platforms to serve affluent domestic and regional patient flows.
Vitreous Detachment Treatment Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated surgical platform vendors commanding premium positioning in hospital settings while specialized laser OEMs capture outpatient clinic volume. Market structure tilts toward consolidated leadership among multi-product ophthalmology conglomerates with established vitrectomy instrument ecosystems. Three archetypes dominate: full-stack surgical platform providers, precision laser specialists, and diagnostic-imaging integrators. Competitive dynamics center on strategic partnerships with retinal specialist networks and portfolio diversification into adjacent posterior segment indications.
Within the full-stack surgical platform tier, Alcon and Bausch + Lomb exemplify archetypes combining consumable recurring revenue with capital equipment placement. Carl Zeiss Meditec AG occupies a differentiated position at the diagnostic-surgical convergence point. These three entities anchor competitive intensity through their respective emphases on integrated workflow solutions, specialized therapeutic combinations, and precision imaging guidance systems.
| Leading Market Players |
|---|
| Alcon |
| Bausch + Lomb |
| Carl Zeiss Meditec AG |
| Ellex Medical Lasers Ltd. |
| NIDEK CO., LTD. |
| Iridex Corporation |
| Topcon Corporation |
| Dutch Ophthalmic Research Center |
| Geuder AG |
| Others |
Pricing and Supply Chain Analysis
Outpatient clinic procurement consolidation toward integrated diagnostic-laser platforms is compressing vendor margins and forcing manufacturers to bundle service contracts with capital equipment, reshaping how pricing power distributes across supply tiers.
Pricing Analysis
Distributor margins on YAG vitreolysis systems absorb 15-25 point spreads before clinic placement, with premium configurations commanding brand premiums tied to FDA 510(k) pedigree and real-time OCT integration. Three-tier pricing structure across premium, standard, and economy levels stratifies by imaging resolution, laser wavelength precision, and after-sales service bundling. Pricing pressure stems from ambulatory surgical center purchasing coalitions consolidating volume leverage in the United States. Hospital systems demonstrate lowest price sensitivity given bundled reimbursement protocols, while independent ophthalmology clinics negotiate most aggressively on capital equipment lease terms.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from integrated surgical platform vendors, while specialized laser OEMs rely on regional distributor networks for clinic penetration. Precision optical components concentrate in Germany and Japan, with final assembly gravitating toward United States and Swiss manufacturing hubs. Supply chains draw from rare-earth laser crystal suppliers, precision motion control subsystems, and medical-grade optical coatings. Single-source vulnerability runs through specialized ytterbium-doped laser crystal foundries. Distribution runs through GPO contracts for hospital systems and direct sales forces for high-volume clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Vitreous Detachment Treatment Market compounds steadily as aging demographics in developed economies generate irreversible procedural demand expansion with limited substitution risk.
For Market Incumbents: Extend platform ecosystem lock-in by integrating proprietary OCT guidance software with laser delivery hardware, creating switching costs against standalone competitors. Deepen backward integration into precision optical component manufacturing to defend margin compression from Asian component suppliers. Prioritize CE marking pathway investments ahead of EU MDR clinical evidence requirements to maintain European market access against delayed-entrant rivals.
For New Entrants and Emerging Players: Capture underpenetrated floater management volume in Brazil and Saudi Arabia where specialist clinic infrastructure expands without proportional laser vitreolysis deployment. Target mid-tier ophthalmology clinics in United States metropolitan clusters seeking FDA-cleared alternatives to premium-tier incumbents. Lead with subscription-based service models that bundle equipment, maintenance, and per-procedure consumables to reduce capital barrier for independent practices.
For Investors and Strategic Acquirers: Asymmetric upside sits with precision laser specialists possessing proprietary wavelength optimization patents and established PMDA approval track records in Japan. Long-term viability hinges on reimbursement durability for outpatient retinal procedures across value-based care transitions. Monitor FDA 510(k) clearance velocity for novel vitreolytic agents as inflection signal for pharmacological disruption risk to device-centric business models.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates commercial deployment of YAG vitreolysis platforms in United States outpatient channels. |
| CE Marking Pathway | Enables European market access under strengthened EU MDR clinical evidence requirements. |
| Hospital System Partnership | Secures volume commitments through GPO contracts and integrated service line agreements. |
| Software Companion Development | Integrates real-time OCT navigation to differentiate surgical precision and reduce complication rates. |
| Reimbursement Strategy | Aligns procedure coding with CMS value-based frameworks favoring minimally invasive modalities. |
Research Methodology
Multiple input streams — structured interviews with vitreoretinal surgeons and clinic administrators, regulatory filing analysis, and procurement database mining — were reconciled to construct market sizing and growth trajectories. Primary fieldwork encompassed retinal specialists, biomedical engineers, GPO contracts managers, and ophthalmology clinic operations directors across United States, German, and Japanese markets. Secondary validation drew from FDA 510(k) clearances, PMDA approvals, CMS reimbursement schedules, and hospital equipment procurement records. Bottom-up procedural volume estimates and top-down equipment shipment data were triangulated to anchor forecast confidence intervals.
Data-stream reconciliation across product type, application severity, delivery mode, and end-user channel dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate modeling applied to baseline equipment installation bases and replacement cycle assumptions. Forecast inputs incorporated aging demographic projections, regulatory approval velocity differentials, and reimbursement classification evolution for outpatient retinal procedures.
Regulatory pathway delays, reimbursement reclassification events, and vitreoretinal surgeon training pipeline constraints are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions regarding procedural adoption curves and equipment replacement cycles. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Global Ophthalmic Perimeters Market
Ophthalmology
Macular Edema Treatment Market
Ophthalmology
CNV (Choroidal Neovascularization) Market
Ophthalmology
Global Advanced Ophthalmology Technologies Market
Ophthalmology
Eye Melanoma Market
Ophthalmology
Ischemic Optic Neuropathy Treatment Market
Ophthalmology
Personalized LASIK Surgery Market
Ophthalmology
Global Glaucoma Treatment Market
Ophthalmology
Blepharitis Treatment Market
Ophthalmology
Ophthalmology Devices Market
Ophthalmology
Global Diabetic Macular Edema Market
Ophthalmology
Conjunctivitis Treatment Market
Ophthalmology
Herpes Simplex Keratitis Treatment Market
Ophthalmology
Vitrectomy Machines Market
Ophthalmology
Uveal Melanoma Treatment Market
Ophthalmology
Global Ophthalmic Knives Market