
 Sweden Ophthalmic Devices Market | 2026-2036
Sweden Ophthalmic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden Ophthalmic Devices Market Analytics
Software-defined diagnostic features bundled with maintenance subscriptions is repositioning how ophthalmic equipment vendors capture recurring revenue in Sweden. Alcon Inc. leverages its surgical consumables ecosystem to sustain long-term contracts with regional hospital networks. Carl Zeiss Meditec AG anchors its position through integrated imaging-to-surgery workflows that dominate premium care settings. Johnson and Johnson competes on phacoemulsification platform reliability across Sweden's public procurement frameworks.
Ophthalmic devices comprise precision-engineered instruments, optical systems, and implantable products designed for vision correction, disease diagnosis, and surgical intervention, typically manufactured to tolerances within micrometers and sterilized for intraocular or periocular use. Their primary purpose is restoring, preserving, or enhancing visual function through mechanical, optical, or laser-based mechanisms. Diagnostic Equipment leads product type revenue due to replacement cycles tied to digital imaging upgrades, while Laser Surgery commands technology segment margins through femtosecond platform differentiation. Vision Correction applications are expanding fastest among working-age populations seeking refractive solutions outside public reimbursement.
Swedish market access requires compliance with EU MDR CE marking, ISO 13485 quality management certification, and oversight by the Swedish Medical Products Agency for post-market surveillance and vigilance reporting. These frameworks elevate compliance costs for non-European manufacturers while creating structural advantages for established suppliers with notified body relationships. Stakeholders must monitor reimbursement rate negotiations between Sweden's regional health authorities and device vendors, as these determine adoption velocity for premium technologies outside essential care bundles.
Market Dynamics
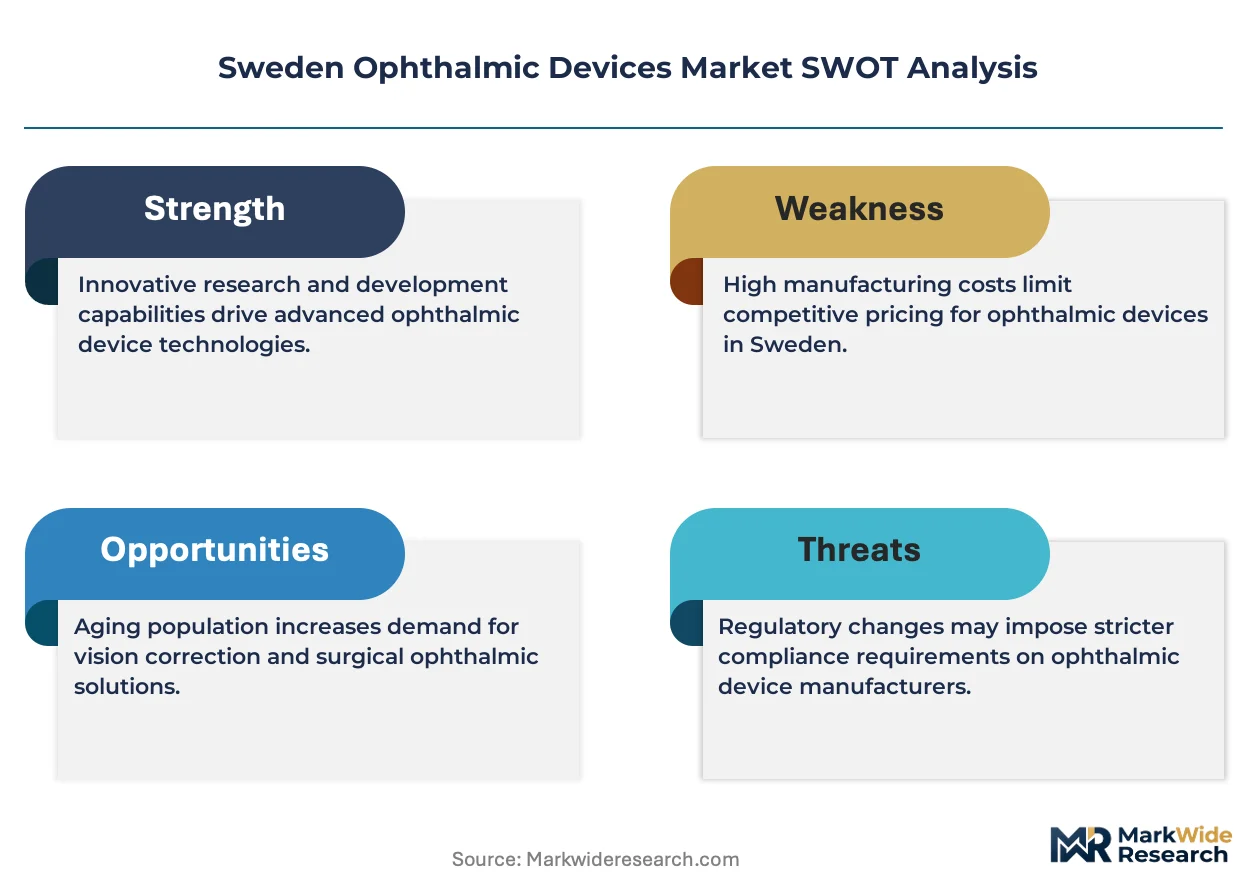
EU MDR CE marking requirements are restructuring Sweden's ophthalmic device procurement, elevating compliance costs for non-European manufacturers while cementing advantages for established suppliers with notified body relationships.
Growth Catalysts
- EU MDR implementation:The Medical Device Regulation mandates stricter clinical evidence standards, favoring manufacturers with robust post-market surveillance infrastructure and accelerating hospital consolidation around trusted vendors.
- Digital imaging upgrades:Swedish university hospitals are replacing legacy diagnostic platforms with integrated optical coherence tomography systems, triggering replacement cycles in Stockholm's metropolitan care cluster.
- Refractive surgery demand:Working-age populations in Sweden's urban centers are pursuing premium vision correction outside public reimbursement frameworks, expanding private clinic procurement of femtosecond laser platforms.
Market Restraints
- Notified body bottleneck:Limited EU MDR certification capacity is extending product registration timelines for implantable intraocular lenses, delaying market entry for emerging manufacturers.
- Single-source optical component dependency:Precision laser sources and high-resolution sensors concentrate among German and Japanese suppliers, exposing Swedish distributors to supply chain disruption risk.
- Public procurement price compression:Sweden's regional health authorities negotiate standardized reimbursement bundles that marginalize premium surgical technologies outside essential care categories.
Strategic Opportunities
- Software-defined diagnostics:AI-powered image analysis modules bundled with hardware subscriptions are creating recurring revenue streams independent of capital equipment sales cycles.
- Gothenburg and Malmö regional expansion:Secondary metropolitan clusters outside Stockholm are developing specialized eye care capacity, opening procurement channels for mid-tier diagnostic systems.
- Integrated imaging-to-surgery workflows:Convergence of preoperative planning software with femtosecond laser platforms enables vendors to capture procedure-level consumables revenue across the care continuum.
Industry Challenges
- Biomedical engineering talent scarcity:Swedish medical device manufacturers face acute competition for optical system designers and regulatory affairs specialists fluent in MDR technical documentation requirements.
- Legacy equipment interoperability:Hospital IT departments struggle to integrate new diagnostic platforms with existing PACS infrastructure, prolonging deployment timelines and eroding vendor margins.
- Post-market surveillance capacity:Vigilance reporting obligations to the Swedish Medical Products Agency demand dedicated pharmacovigilance infrastructure that smaller distributors lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden Ophthalmic Devices Market |
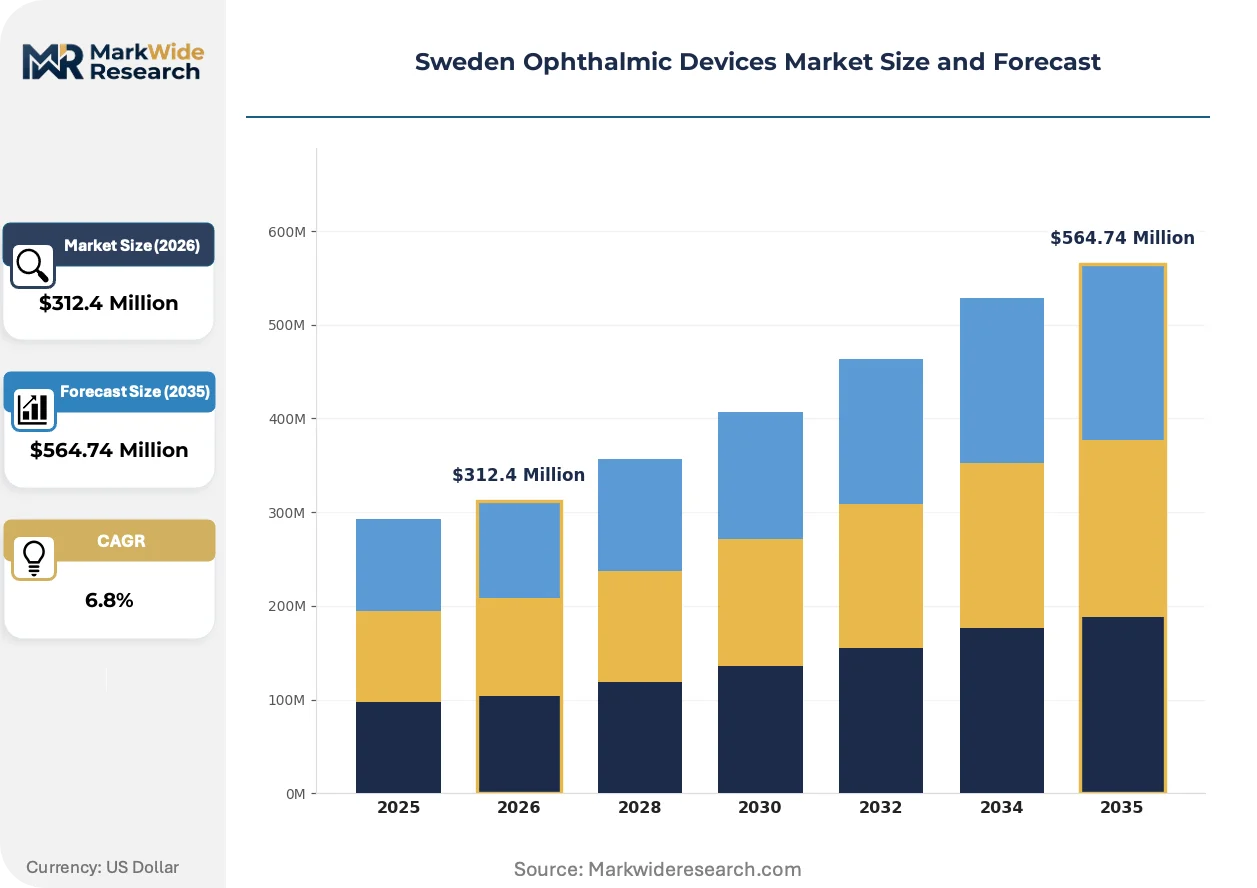
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glasses, Contact Lenses, Surgical Instruments, Diagnostic Equipment Application: Vision Correction, Cataract Surgery, Retinal Disorders, Diagnostic Tests End User: Hospitals, Eye Clinics, Retail Optical Stores, Home Care Providers Technology: Laser Surgery, Optical Coherence Tomography, Fundus Imaging, Adaptive Optics |
| Companies Covered | Alcon Inc., Carl Zeiss Meditec AG, Johnson and Johnson, Bausch Health Companies Inc., Ziemer Group AG, Topcon Corporation, Nidek Co. Ltd, Hoya Corporation, iSTAR Medical SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden Ophthalmic Devices Market Evolving Landscape
Sweden's ophthalmic device landscape is being reshaped by the fusion of diagnostic and surgical platforms, regulatory digitization, and evolving procurement models that privilege total cost-of-ownership over upfront capital expenditure.
Femtosecond laser technology is converging with intraoperative aberrometry systems, enabling real-time surgical feedback that reduces refractive prediction error. Swedish premium clinics are adopting these platforms at accelerating pace, compressing the traditional separation between diagnostic planning and surgical execution into unified workflow environments.
The EU Medical Device Regulation's EUDAMED database requirements are mandating standardized unique device identification and traceability systems. This policy shift is forcing Swedish hospitals to upgrade inventory management infrastructure, with implantable lens categories facing the most intensive compliance adaptation as they navigate serialized product tracking obligations.
Swedish regional health authorities are consolidating ophthalmic device procurement through framework agreements that bundle maintenance, training, and consumables into multi-year contracts. This behavioral shift is displacing transactional equipment sales with performance-based partnerships, most visible in Stockholm County Council's centralized sourcing of cataract surgical platforms.
Sweden Ophthalmic Devices Market Segmentation
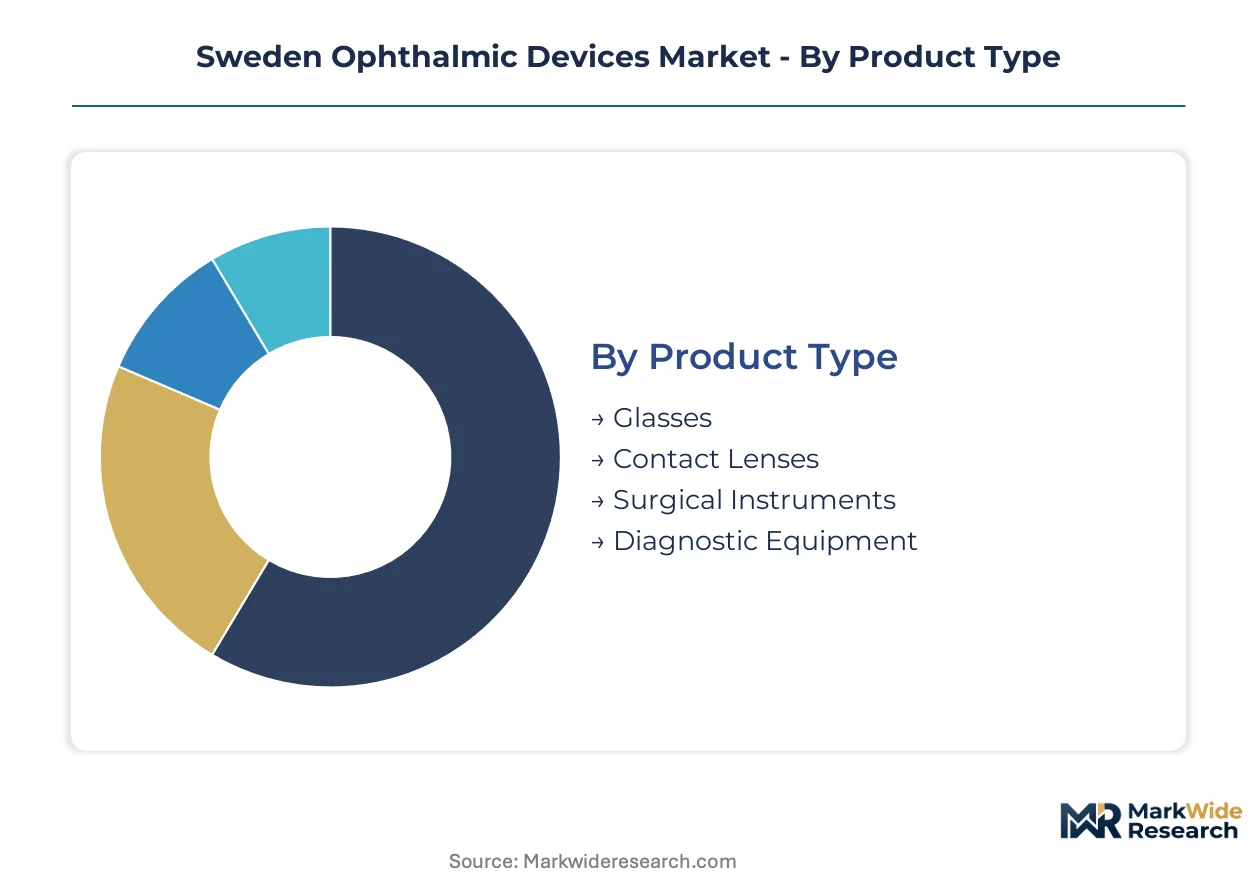
Sweden's ophthalmic device market fragments across four distinct dimensions that determine procurement patterns, reimbursement pathways, and vendor competitive strategy. Each segmentation axis reveals divergent buyer priorities—from clinical workflow integration to patient accessibility—that shape how manufacturers position their portfolios.
Product Type:
Procurement budgets diverge sharply between capital-intensive hospital systems and high-volume retail channels.
- Diagnostic Equipment:Integrated optical coherence tomography systems and digital fundus cameras command premium pricing through university hospital procurement frameworks in Stockholm. Replacement cycles accelerate as Swedish medical centers pursue AI-enhanced imaging capabilities for early glaucoma detection.
- Surgical Instruments:Phacoemulsification handpieces and femtosecond laser delivery systems concentrate demand within specialized cataract surgery units. Regional health authorities negotiate multi-year consumables bundles that lock in vendor relationships across Sweden's seven healthcare regions.
- Glasses:Prescription eyewear flows through retail optical chains and independent opticians serving Sweden's aging demographic with progressive lens technologies.
- Contact Lenses:Daily disposable silicone hydrogel variants dominate Swedish consumer preference, with subscription models displacing transactional purchasing.
Volume sits with Glasses; growth tilts toward Diagnostic Equipment.
Application:
Clinical outcomes and reimbursement eligibility determine technology adoption velocity across Swedish care settings.
- Vision Correction:Refractive surgery demand concentrates among working-age professionals in Stockholm, Gothenburg, and Malmö seeking laser-based alternatives to corrective eyewear. Private clinic chains capture this patient segment outside public reimbursement frameworks.
- Cataract Surgery:Sweden's regional health authorities prioritize femtosecond laser-assisted procedures within essential care bundles, driving standardized platform procurement across county council networks.
- Retinal Disorders:Age-related macular degeneration management requires sustained diagnostic monitoring, expanding OCT utilization in specialized retinal clinics.
- Diagnostic Tests:Glaucoma screening and pediatric vision assessment protocols generate recurring demand for automated perimetry and autorefractor systems in primary care optometry.
Procedure volume concentrates in Cataract Surgery; expansion accelerates most rapidly in Vision Correction.
End User:
Facility type dictates purchasing authority, technical specifications, and service contract structures.
- Hospitals:Swedish university hospitals anchor demand for integrated surgical suites combining diagnostic planning with intraoperative guidance. EU MDR compliance requirements favor established vendors with notified body relationships for implantable device categories.
- Eye Clinics:Specialized ophthalmology centers in metropolitan clusters pursue premium femtosecond platforms and advanced imaging systems to differentiate their refractive surgery offerings.
- Retail Optical Stores:High-street opticians and chain outlets drive volume in corrective eyewear and contact lens distribution, with digital refraction technology reducing dependency on hospital-based diagnostic referrals.
- Home Care Providers:Low-vision aids and portable diagnostic devices serve Sweden's rural elderly population through municipal healthcare delivery structures.
Capital deployment dominates in Hospitals; patient contact volume peaks at Retail Optical Stores.
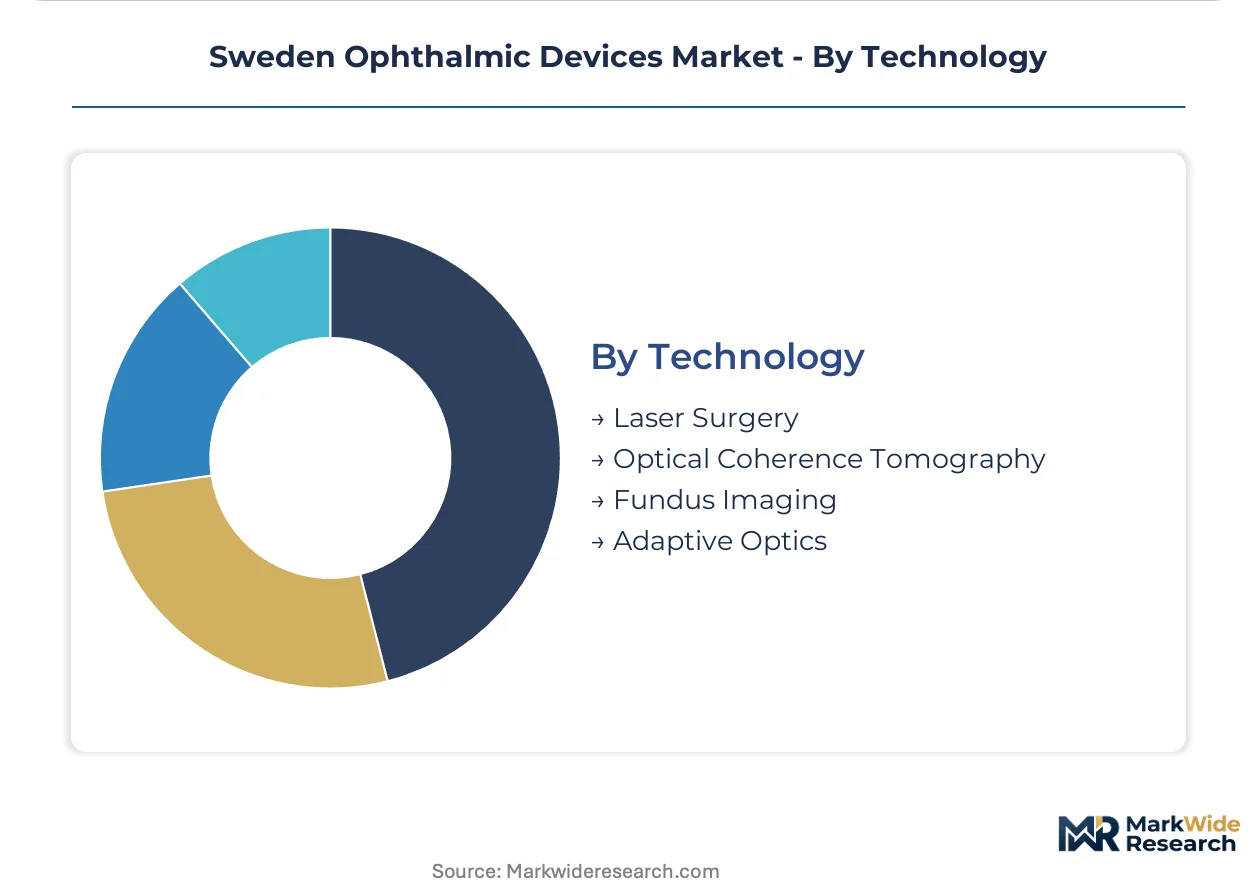
Technology:
Platform convergence between diagnostic and surgical modalities is compressing traditional category boundaries.
- Laser Surgery:Femtosecond platforms for corneal flap creation and lens fragmentation command highest technology segment margins. Swedish premium clinics adopt these systems to reduce refractive prediction error and capture procedure-level consumables revenue.
- Optical Coherence Tomography:Swept-source and anterior segment OCT systems anchor diagnostic workflows in Swedish retinal and glaucoma practices, with software subscription models creating recurring revenue independent of hardware replacement cycles.
- Fundus Imaging:Wide-field and ultra-wide-field retinal photography systems support diabetic retinopathy screening programs across Sweden's regional healthcare networks.
- Adaptive Optics:High-resolution cellular imaging technology remains concentrated in research-oriented university hospital settings, with clinical translation pending cost reduction and workflow integration.
Installed base concentrates in Optical Coherence Tomography; Adaptive Optics holds steepest expansion trajectory pending commercialization milestones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stockholm's metropolitan care cluster concentrates Sweden's ophthalmic device procurement, with university hospitals driving adoption of integrated diagnostic-surgical platforms across the capital region's specialized eye clinics.
Stockholm County
Sweden's largest healthcare region anchors demand for premium femtosecond laser systems and optical coherence tomography platforms through Karolinska University Hospital and St. Erik Eye Hospital procurement frameworks. The Swedish Medical Products Agency enforces EU MDR post-market surveillance requirements for implantable devices distributed through this cluster. Private refractive surgery chains in central Stockholm capture working-age professionals seeking vision correction outside public reimbursement.
Västra Götaland
Gothenburg's Sahlgrenska University Hospital drives adoption of advanced retinal imaging systems for age-related macular degeneration management across western Sweden. Regional health authority framework agreements bundle maintenance and training into multi-year surgical platform contracts. The city's specialized ophthalmology centers are expanding capacity for premium cataract procedures using femtosecond-assisted techniques.
Skåne
Malmö's university hospital network standardizes phacoemulsification platform procurement across southern Sweden's regional healthcare system. Skåne County Council negotiates centralized consumables agreements that lock in vendor relationships for intraocular lens categories. Private clinic operators in the Öresund region target Danish cross-border patients for refractive surgery procedures.
Uppsala
Uppsala University Hospital's academic research orientation concentrates demand for experimental adaptive optics systems and clinical trial infrastructure. The Swedish Medical Products Agency coordinates vigilance reporting for novel implantable devices tested through this northern hub. Regional procurement prioritizes diagnostic equipment with integrated AI-powered image analysis capabilities.
Sweden Ophthalmic Devices Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Sweden's ophthalmic device procurement landscape. Established European manufacturers with notified body relationships dominate premium surgical platform categories, while specialized diagnostic vendors capture recurring software subscription revenue. Three archetypes define competitive positioning: integrated imaging-to-surgery workflow providers, consumables-anchored surgical ecosystem vendors, and standalone diagnostic equipment specialists. Consolidation through framework agreement capture and backward integration into optical component supply chains represent the dominant competitive vectors.
Among Swiss and German precision manufacturers, Alcon Inc., Carl Zeiss Meditec AG, and Johnson and Johnson occupy positions reflecting divergent strategic archetypes. Alcon exemplifies the consumables-anchored ecosystem model through long-term service contracts with Swedish regional hospital networks. Carl Zeiss Meditec represents integrated workflow convergence between preoperative planning and intraoperative guidance systems. Johnson and Johnson sits within the reliability-focused platform tier competing across Sweden's public procurement frameworks.
| Leading Market Players |
|---|
| Alcon Inc. |
| Carl Zeiss Meditec AG |
| Johnson and Johnson |
| Bausch Health Companies Inc. |
| Ziemer Group AG |
| Topcon Corporation |
| Nidek Co. Ltd |
| Hoya Corporation |
| iSTAR Medical SA |
| Others |
Value Network & Pricing Analysis
Swedish optical system designers and regulatory affairs specialists concentrated in Stockholm's metropolitan cluster command wage premiums that compress margins on mid-tier diagnostic equipment while enabling sustained pricing power for femtosecond laser platforms requiring MDR-certified engineering talent.
Pricing Analysis
Outcome-based pricing anchors premium surgical platform contracts across Sweden's regional health authority frameworks, with femtosecond laser systems commanding value tied to refractive prediction accuracy and procedure throughput guarantees. Three-tier pricing structure across premium, standard, and economy levels separates university hospital integrated suites from municipal clinic diagnostic units and retail optical refraction services. Cost compression in standard-tier phacoemulsification platforms is intensifying because framework agreement bundling favors consumables-anchored vendors. Retail optical stores exhibit highest price sensitivity due to patient out-of-pocket payment structures, while specialized eye clinics absorb premium positioning for differentiated refractive surgery offerings.
Supply Chain Analysis
Direct-to-hospital channels handle university health system procurement of integrated imaging-to-surgery platforms, while distributor networks serve private clinic and retail optical segments. Precision laser sources and high-resolution sensors concentrate among German and Japanese suppliers, with Swedish distributors drawing from these geographies for femtosecond platform core components. Single-source optical component dependency exposes the market to supply chain disruption risk from geopolitical friction or semiconductor fabrication constraints. Distribution runs through notified body-certified logistics partners required for EU MDR traceability compliance on implantable intraocular lens categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sweden's ophthalmic device sector sits in a technology-transition phase as femtosecond laser platforms displace mechanical microkeratome systems for corneal flap creation across premium vision correction procedures.
For Market Incumbents: Deepen backward integration into optical component supply chains to mitigate single-source laser source vulnerability from German and Japanese suppliers. Secure multi-year framework agreement renewals with Stockholm County Council and Sahlgrenska University Hospital before EU MDR certification bottlenecks enable emerging competitors to establish notified body relationships.
For New Entrants and Emerging Players: Begin with software-defined diagnostic modules bundling AI-powered image analysis with hardware subscriptions, targeting Gothenburg and Malmö secondary metropolitan clusters where specialized eye care capacity is expanding fastest. Position through mid-tier OCT systems with integrated training packages to bypass entrenched vendor relationships in Stockholm's saturated procurement environment.
For Investors and Strategic Acquirers: Re-rating potential sits with diagnostic equipment specialists possessing EUDAMED database integration capabilities given the EU MDR's serialized product tracking obligations for implantable categories. Long-term viability hinges on software recurring revenue models decoupled from capital equipment replacement cycles. Watch framework agreement consolidation velocity across Sweden's seven healthcare regions as the primary inflection indicator for vendor market share shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR certification through notified body relationships unlocks procurement access to Karolinska University Hospital frameworks. |
| Hospital System Partnership | Multi-year service contracts with Stockholm County Council anchor consumables revenue across cataract surgical platforms. |
| Software Companion Development | AI-powered OCT analysis modules bundled with subscriptions create recurring revenue independent of hardware cycles. |
| Reimbursement Strategy | Negotiation with regional health authorities determines adoption velocity for premium technologies outside essential care bundles. |
| Backward Integration | Captive supply of precision laser sources reduces dependency on German and Japanese component suppliers. |
Research Methodology
Document review covered EU MDR technical documentation requirements, Swedish Medical Products Agency vigilance reporting databases, and regional health authority procurement frameworks, complemented by interviews with biomedical engineers, hospital purchasing committee members, ophthalmic clinic directors, and regulatory affairs specialists at notified bodies. Secondary validation drew from Swedish Medical Products Agency post-market surveillance records, EU EUDAMED database filings, ISO 13485 certification registries, and regional county council framework agreement disclosures. Bottom-up equipment installation data and top-down healthcare expenditure flows were triangulated to establish market sizing.
Cross-referencing historical procurement patterns against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application, end user, and technology platform convergence patterns. CAGRs were derived from equipment replacement cycle analysis and software subscription adoption curves. Forecast inputs incorporated EU MDR implementation timelines and Swedish regional health authority consolidation trajectories.
Underlying measurement precision varies by segment; diagnostic equipment and laser surgery categories carry tighter precision than retail optical and home care segments due to concentrated procurement data availability. Forecasts reflect assumptions regarding EU MDR certification capacity expansion and regional framework agreement standardization velocity. Periodic stress-testing of base assumptions is recommended given notified body bottleneck risks and supply chain concentration exposures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Medical Device Contract Manufacturing Market
Medical Devices
Global Vagus Nerve Stimulation Market
Medical Devices
Medical Bionic Implant Market
Medical Devices
Syndesmosis Repair System Market
Medical Devices
Brazil Minimally Invasive Surgery Devices Market
Medical Devices
Arthroscopy Visualization Systems Market
Medical Devices
Global Airway Stent/Lung Stent Market
Medical Devices
Arteriosclerosis Detector Market
Medical Devices
Global Electrotherapy System Market
Medical Devices
Invasive SEEG Depth Electrodes Market
Medical Devices
Breast Prosthesis Market
Medical Devices
Cellular Encapsulation Market
Medical Devices
Global Microkeratome Market
Medical Devices
Medical Devices Reimbursement Market
Medical Devices
Solar Surgical Light Market
Medical Devices
Platelet Concentration Systems Market