
 Urolithiasis Management Devices Market | 2026-2036
Urolithiasis Management Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Urolithiasis Management Devices Market Outlook
MDR compliance in Europe is broadening the cost-of-entry calculus for urological device manufacturers seeking CE marking. Boston Scientific Corporation leverages its integrated laser and disposable portfolio to sustain market presence across multiple geographies. Olympus Corporation anchors its competitive stance through rigid and flexible ureteroscope specialization. KARL STORZ competes on optical precision and surgical visualization systems that dominate premium hospital procurement cycles.
Urolithiasis management devices encompass instruments designed to fragment, extract, or bypass urinary tract calculi, typically employing holmium:YAG laser energy at 2100 nm wavelength, pneumatic ballistic force, or ultrasonic oscillation at 23-25 kHz to achieve stone comminution with minimal mucosal trauma. These systems serve the primary clinical purpose of restoring urinary drainage while preserving renal function through percutaneous, ureteroscopic, or extracorporeal approaches. Laser lithotripters command the highest margin pool due to recurring fiber and tip consumables, while robotic-assisted technology represents the fastest-growing segment as hospitals seek to standardize outcomes across operator experience levels. Ambulatory surgical centers increasingly shape volume distribution by shifting lower-complexity procedures away from inpatient settings.
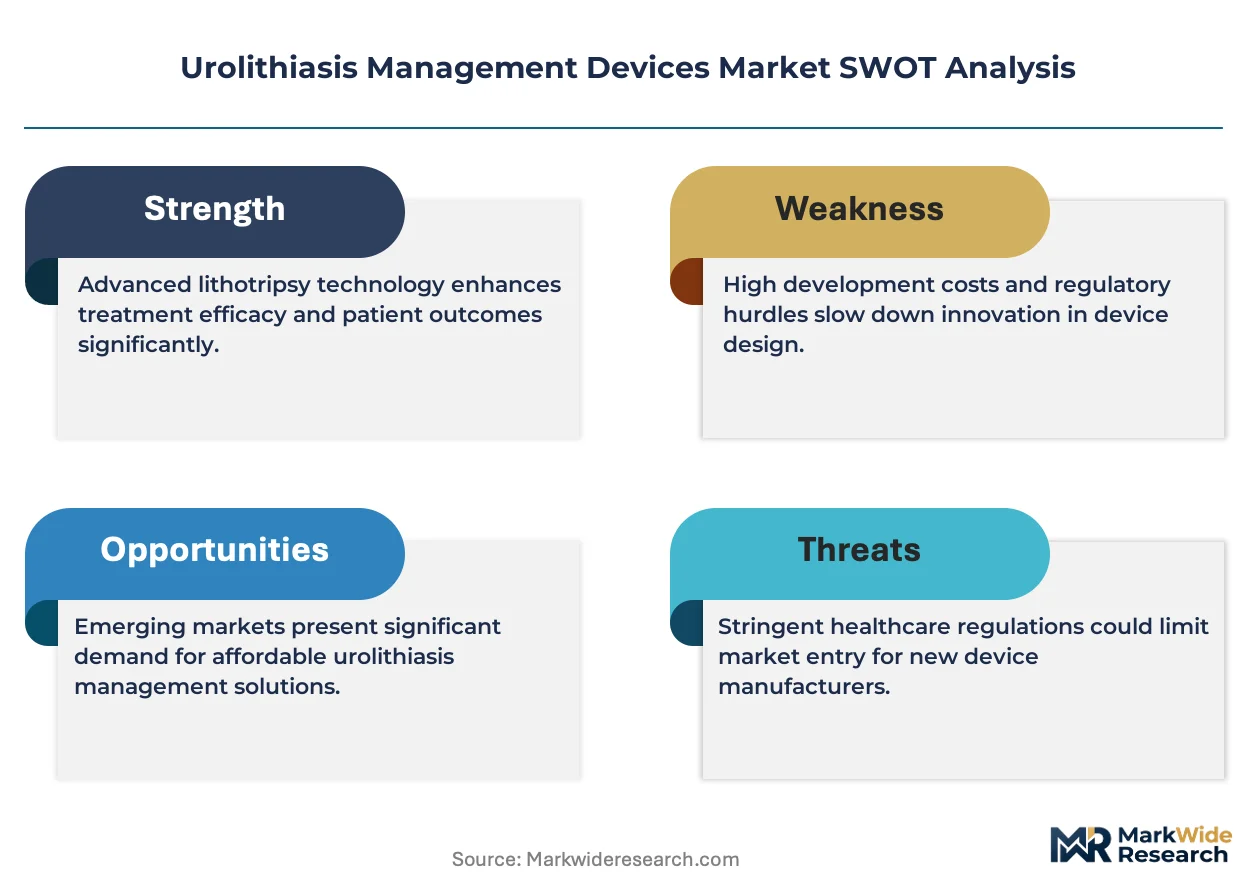
FDA 510(k) pathways, EU MDR technical documentation requirements, and Japan's PMDA foreign manufacturer registration collectively govern market access timelines and clinical evidence standards for stone management platforms. These frameworks elevate R&D allocation toward predicate-device equivalence studies and biocompatibility testing that extend development cycles. Stakeholders must monitor reimbursement coding revisions for office-based ureteroscopy and emerging value-based procurement models that tie device selection to procedural bundle economics.
Market Dynamics
Minimally invasive stone removal systems are compressing procedural recovery windows and redirecting capital allocation from open surgical suites toward laser-equipped endoscopy towers. Hospital procurement committees now weight single-use ureteroscope economics against reprocessing labor costs, fundamentally restructuring vendor selection criteria.
Growth Catalysts
- Holmium:YAG laser refinement:Fiber-optic delivery systems at 2100 nm wavelength enable precise stone fragmentation with reduced retropulsion. Academic medical centers in the United States are standardizing this energy platform across stone management protocols.
- Japan's PMDA streamlined foreign manufacturer registration:Accelerated market entry timelines for CE-marked devices reduce commercialization lag. Japanese urology departments are expanding lithotriper installations in response.
- Ambulatory surgical center expansion:Lower-complexity ureteroscopy procedures are migrating from inpatient settings. Facility reimbursement stability in Germany supports this volume shift.
Market Restraints
- EU MDR technical documentation burdens:Clinical evidence requirements for CE marking have extended development cycles by eighteen to thirty-six months. Small manufacturers face disproportionate compliance costs.
- Holmium laser fiber supply concentration:Premium silica fiber production clusters in specialized German and Japanese optical manufacturing facilities. Disruption risks elevate procurement contingency planning.
- Ultrasonic lithotripsy technical ceiling:Hard stone compositions exceeding 1500 HV resist comminution at standard 23-25 kHz oscillation frequencies. Operators must switch modalities mid-procedure.
Strategic Opportunities
- Robotic-assisted ureteroscopy convergence:Haptic feedback integration with flexible endoscopy platforms standardizes outcomes across operator experience levels. Japanese and German hospital systems are piloting these hybrid configurations.
- Office-based procedural reimbursement recoding:United States CMS valuation adjustments for outpatient ureteroscopy create margin expansion for integrated device-service bundles. Urology group practices are consolidating purchasing authority.
- Thulium fiber laser technology:Lower water absorption coefficients enable reduced operating power with equivalent fragmentation efficiency. Early adopters in academic settings are validating clinical protocols.
Industry Challenges
- Endoscope reprocessing certification complexity:Spaulding classification compliance for semi-critical devices demands dedicated sterile processing infrastructure. Staff turnover in this function creates operational vulnerability.
- Laser safety officer training scarcity:ANSI Z136.3-compliant credentialing programs for operating room personnel have limited geographic availability. Hospitals absorb premium labor costs or delay platform activation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urolithiasis Management Devices Market |
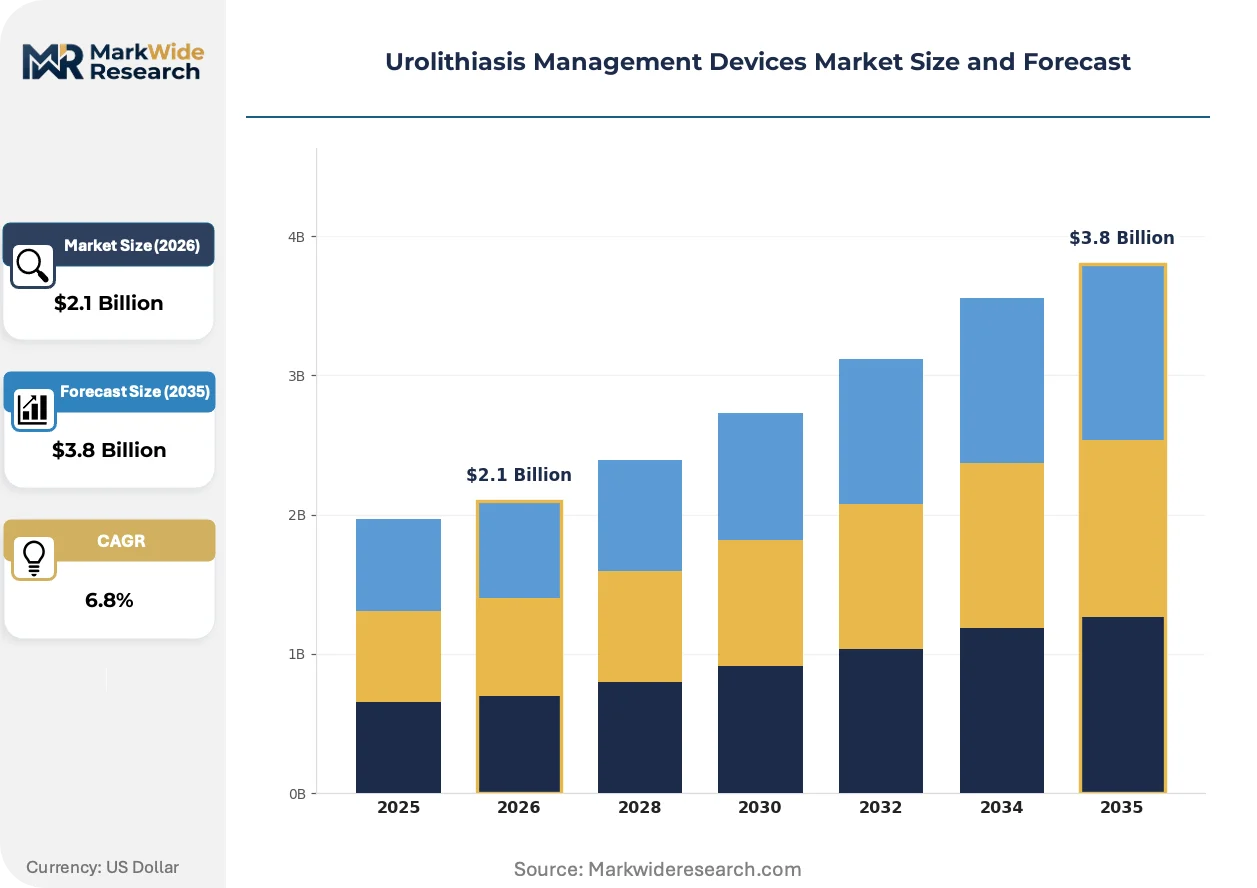
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Lithotripters, Pneumatic Lithotripters, Ultrasound Lithotripters, Retrograde Ureteroscopes Application: Hospital Settings, Ambulatory Surgical Centers, Specialty Clinics, Diagnostic Laboratories End User: Urologists, Surgeons, Nurses, Technicians Technology: Minimally Invasive, Robotic-Assisted, Smart Devices, Traditional Approaches |
| Companies Covered | Boston Scientific Corporation, Olympus Corporation, Cook Medical, KARL STORZ, Richard Wolf GmbH, DirexGroup, Dornier MedTech, BD, ConMed Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urolithiasis Management Devices Market Strategic Shifts
Digital integration and energy platform miniaturization are compressing the footprint of stone management systems while expanding their functional range. Vendors are racing to embed real-time stone composition analysis and automated parameter adjustment into next-generation consoles.
Robotic endoscope manipulation systems are automating sheath advancement and laser fiber positioning during ureteroscopic procedures. Tertiary care hospitals in the United States and Germany are deploying these platforms to reduce fluoroscopy exposure and standardize stone-free rates across resident training cases. The technology is automating previously operator-dependent motions that historically required hundreds of procedural repetitions to master.
EU MDR post-market surveillance requirements are mandating systematic clinical follow-up data collection for all class IIa and above urological devices. Manufacturers must establish periodic safety update reports and trend analysis protocols that extend far beyond legacy vigilance obligations. High-volume lithotripter installations in French and Italian hospital networks face the steepest documentation adaptation curves.
Consolidated purchasing by United States urology super-groups is displacing individual hospital procurement autonomy in device selection. These entities negotiate multi-year supply agreements covering lasers, scopes, and disposables as unified bundles. The concentration of buying power is most visible in Florida, Texas, and California where private equity-backed practice aggregations have achieved regional scale.
Urolithiasis Management Devices Market Segmentation
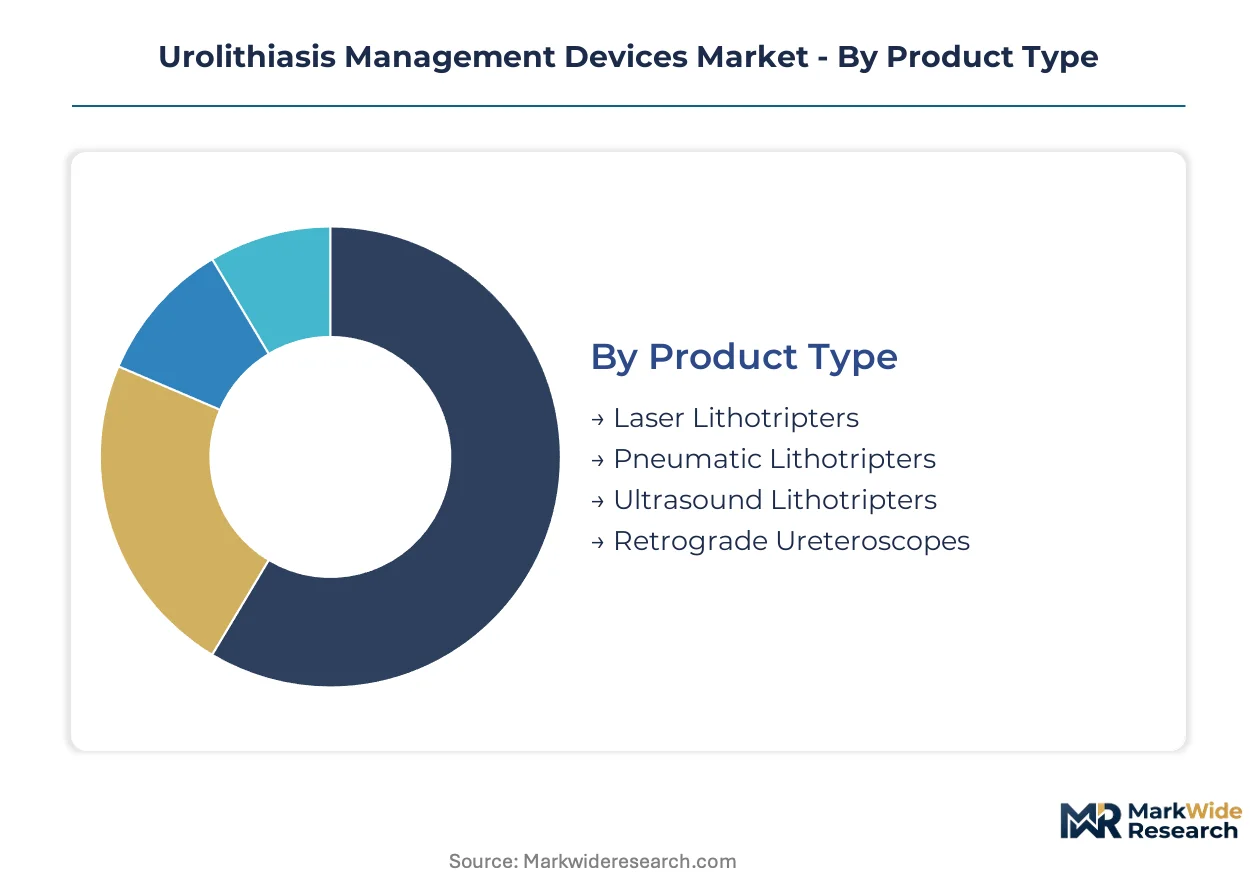
Segmentation in urolithiasis management reveals how capital equipment, disposable economics, and clinical setting requirements fragment purchasing authority across healthcare systems. Understanding these divides is essential for aligning product portfolios with procurement committee priorities and reimbursement pathways.
Product Type:
Customization intensity spans from configurable laser platforms with modular fiber delivery to standardized pneumatic consoles with fixed parameter sets.
- Laser Lithotripters:Holmium:YAG systems at 2100 nm wavelength dominate premium hospital installations through precise stone fragmentation and reduced retropulsion. United States academic medical centers are standardizing this energy platform across stone management protocols.
- Pneumatic Lithotripters:Ballistic force delivery through rigid probes offers lower capital cost entry points for facilities with constrained budgets. German ambulatory surgical centers favor these systems for uncomplicated lower ureteral calculi.
- Ultrasound Lithotripters:23-25 kHz oscillation frequencies target soft to medium stone compositions in percutaneous applications.
- Retrograde Ureteroscopes:Flexible and rigid optical platforms enable direct stone visualization and extraction across ureteral segments.
Leading the category by volume: Laser Lithotripters. Growing fastest: Retrograde Ureteroscopes.
Application:
Volume distribution tracks reimbursement stability and facility infrastructure investment cycles across inpatient and outpatient settings.
- Hospital Settings:Tertiary care centers house comprehensive stone management suites combining multiple energy modalities and imaging capabilities. Japan's aging demographics are expanding procedural volumes in these facilities.
- Ambulatory Surgical Centers:Lower-complexity ureteroscopy procedures are migrating from inpatient settings where reimbursement efficiency and faster turnover matter most. United States CMS valuation adjustments support this volume shift.
- Specialty Clinics:Urology-focused practices concentrate diagnostic and minor interventional services outside hospital systems.
- Diagnostic Laboratories:Stone composition analysis and metabolic workup services support treatment planning and recurrence prevention.
Procurement concentration: Hospital Settings. Expanding most quickly: Ambulatory Surgical Centers.
End User:
Training requirements and liability exposure create distinct purchasing influence patterns across clinical roles.
- Urologists:Board-certified specialists drive technology selection through direct procedural experience and academic affiliation preferences. German hospital departments weight their input heavily in capital equipment decisions.
- Surgeons:Generalists and subspecialists perform stone interventions alongside other urological procedures, favoring versatile platform configurations.
- Nurses:Circulating and scrub staff influence disposable selection through reprocessing workflow preferences and infection control priorities.
- Technicians:Biomedical and laser safety officers maintain equipment uptime and compliance certification requirements.
Primary decision authority: Urologists. Fastest-growing training investment: Technicians.
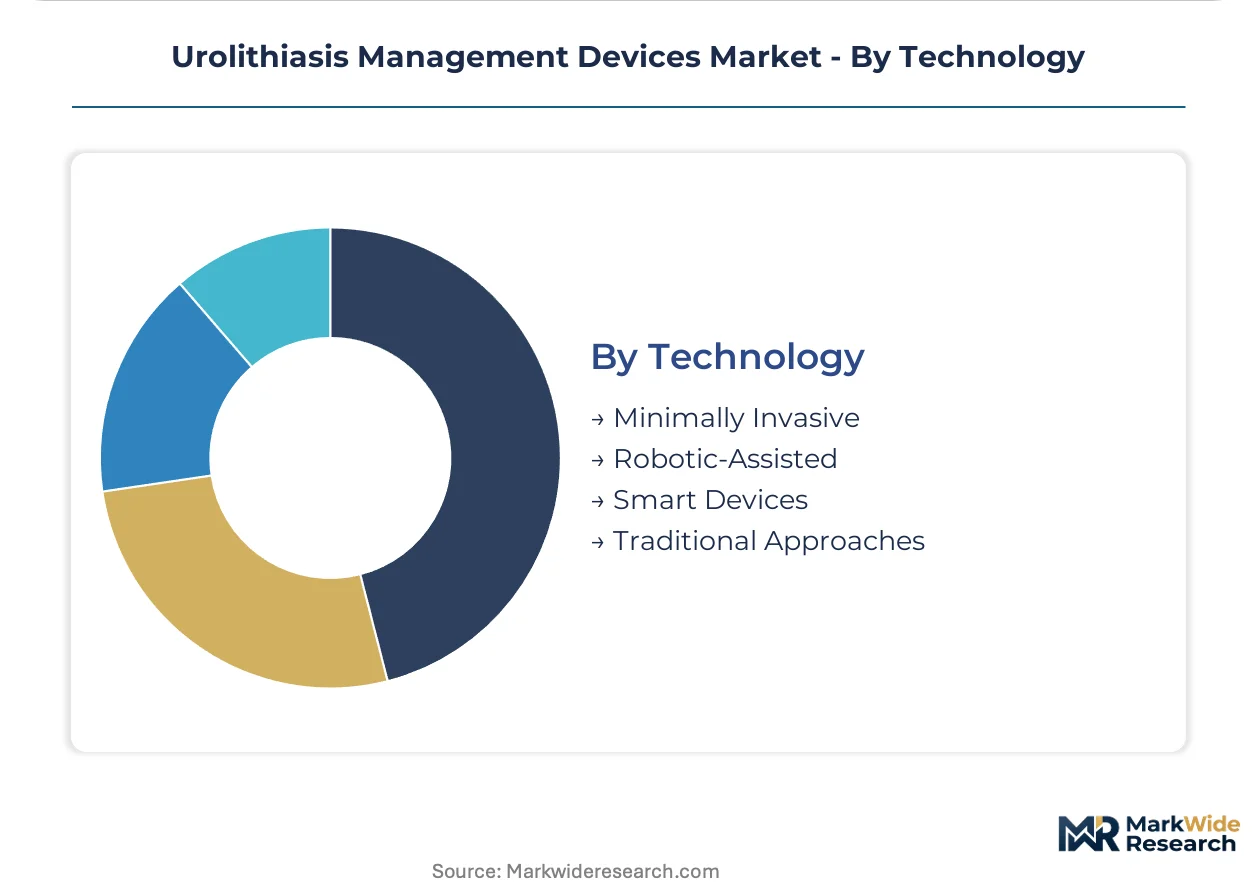
Technology:
Adoption maturity separates established minimally invasive platforms from emerging robotic and connected device architectures.
- Minimally Invasive:Ureteroscopic and percutaneous approaches have displaced open stone surgery through reduced recovery windows and preserved renal function. United States hospital systems completed this transition over the past two decades.
- Robotic-Assisted:Haptic feedback integration with flexible endoscopy platforms standardizes outcomes across operator experience levels. Japanese and German hospital systems are piloting these hybrid configurations.
- Smart Devices:Real-time stone composition analysis and automated parameter adjustment capabilities are entering next-generation console designs.
- Traditional Approaches:Open surgical and blind basket extraction techniques persist in resource-constrained settings with limited endoscopic infrastructure.
Volume foundation: Minimally Invasive. Steepest expansion trajectory: Robotic-Assisted.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical device special economic zones in Costa Rica and Puerto Rico concentrate lithotripter component manufacturing for North American distribution. These zones attract producers through tariff exemptions and streamlined FDA premarket notification pathways.
United States
Academic medical centers in Boston and Houston drive holmium:YAG laser standardization across stone management protocols. FDA 510(k) clearance pathways for predicate-device equivalence compress commercialization timelines for laser lithotripter manufacturers. The Minneapolis-St. Paul corridor houses optical fiber production facilities serving premium silica supply chains.
Germany
Baden-Württemberg and Bavaria anchor European demand through aging demographics and reimbursement stability for minimally invasive procedures. EU MDR technical documentation requirements extend CE marking cycles by eighteen to thirty-six months for manufacturers seeking market access. Tuttlingen hosts surgical instrument clusters specializing in rigid ureteroscope fabrication.
Japan
Tokyo and Osaka metropolitan areas concentrate urology department expansion responding to rising renal calculus incidence among elderly populations. PMDA streamlined foreign manufacturer registration accelerates market entry for CE-marked devices. Nagoya medical device zones support lithotripter assembly for domestic hospital procurement.
China
Shanghai and Beijing tertiary hospitals drive adoption of robotic-assisted ureteroscopy platforms for outcome standardization. NMPA medical device registration requirements govern import substitution strategies for domestic laser lithotripter producers. Shenzhen manufacturing clusters supply electromechanical components for endoscope positioning systems.
Urolithiasis Management Devices Market Competitive Environment
United States producers anchor the premium laser lithotripter tier; German specialists hold dominant positions in optical precision and surgical visualization. The vendor base concentrates around integrated platform providers with recurring consumable revenue streams and modular fiber delivery architectures. Three archetypes define competitive positioning: diversified medical technology conglomerates with broad urology portfolios, specialized endoscope manufacturers with rigid and flexible platforms, and regional equipment fabricators serving cost-constrained facilities. M&A activity targets disposable fiber supply chains and robotic manipulation capabilities.
Within the diversified conglomerate tier, Boston Scientific Corporation and Olympus Corporation exemplify integrated portfolio strategies spanning lasers, scopes, and single-use disposables. KARL STORZ represents the specialized optical precision archetype through surgical visualization systems that dominate premium hospital procurement cycles. These three entities occupy positions that shape vendor selection criteria across academic medical centers and ambulatory surgical networks.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Olympus Corporation |
| Cook Medical |
| KARL STORZ |
| Richard Wolf GmbH |
| DirexGroup |
| Dornier MedTech |
| BD |
| ConMed Corporation |
| Others |
Value Chain & Pricing Dynamics
Premium silica fiber sourced from specialized German and Japanese optical manufacturing facilities flows through three distinct pricing tiers before reaching hospital procurement committees. This input concentration grants upstream suppliers substantial leverage over lithotripter manufacturers competing on fragmentation precision and fiber durability.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent separate urgent replacement fiber orders from scheduled procurement cycles. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance status and CE marking tier. Cost compression in economy-tier pneumatic systems is intensifying as Chinese manufacturers expand regional distribution. Ambulatory surgical centers exhibit highest price sensitivity due to reimbursement constraints, while United States academic medical centers prioritize fragmentation efficiency over unit economics.
Supply Chain Analysis
Direct-to-hospital channels handle premium laser lithotripter installations requiring specialized training and service bundling. Manufacturing concentrates in Germany, Japan, and the United States for optical components, electromechanical assemblies, and console fabrication. Supply chains rest on holmium-doped YAG crystal supply, silica fiber drawing capacity, and precision surgical steel forging. Single-source vulnerability in premium fiber production elevates procurement contingency planning among tier-one manufacturers. Distribution runs through specialized medical device distributors with GPO contracting relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Upstream control over consumable fiber supply and downstream capture of ambulatory surgical center volume define the vertical-integration race reshaping competitive economics. Players securing both levers position for sustainable margin architecture.
For Market Incumbents: Deepen captive supply arrangements for holmium-doped YAG crystals and silica fiber drawing capacity to insulate against Japanese and German optical manufacturer concentration. Consolidate service technician networks across United States urology super-groups to preempt disposable switching. Thulium fiber laser substitution threat demands accelerated R&D allocation toward wavelength optimization protocols. For New Entrants and Emerging Players: The mid-tier price-point gap between Boston Scientific premium installations and economy pneumatic systems offers entry leverage. Target German ambulatory surgical centers with CE-marked pneumatic platforms featuring simplified maintenance protocols. White-space concentration in office-based ureteroscopy reimbursement coding creates margin expansion for integrated device-service bundles without capital equipment overhead. For Investors and Strategic Acquirers: PMDA streamlined foreign manufacturer registration acceleration is the leading indicator that Japanese hospital procurement volumes will outpace historical growth trajectories. Long-term viability centers on recurring consumable revenue attachment rates rather than console placement economics. Acquisition targets should demonstrate fiber supply backward integration or robotic-assisted platform development capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation requirements extend cycles but secure premium hospital access. |
| Hospital System Partnership | United States urology super-groups consolidate purchasing authority across multi-state networks. |
| Software Companion Development | Real-time stone composition analysis modules differentiate next-generation console offerings. |
| Reimbursement Strategy | CMS valuation adjustments for outpatient ureteroscopy shift volume toward ambulatory settings. |
| Backward Integration | Captive silica fiber production insulates against German and Japanese supply concentration. |
Study Parameters
FDA 510(k) premarket notification database, EU MDR technical documentation registries, and Japanese PMDA foreign manufacturer registration records formed the secondary backbone. Primary interviews with urologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers validated procedural volume assumptions and procurement criteria weightings. Bottom-up installation data triangulated against top-down healthcare expenditure estimates across the analysis window.
Historical trendline analysis of holmium:YAG laser adoption curves informed projection frameworks across product type, application setting, end user specialty, and technology maturity segments. CAGRs derived from regression modeling of procedural volume growth against capital equipment replacement cycles. Forecast inputs incorporated aging demographic trajectories, reimbursement coding revisions, and regulatory pathway evolution without specifying timeline endpoints.
Inputs from hospital procurement databases and GPO contract repositories were available through the study window; gaps in real-time ambulatory surgical center installation tracking introduce uncertainty bands around outpatient volume projections. Forecasts reflect assumptions regarding PMDA registration efficiency and EU MDR documentation adaptation timelines. Periodic stress-testing of base assumptions against regulatory announcement velocity and reimbursement adjustment frequency is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Endoscope Reprocessing Device Market
Medical Devices
Jet Nebulizers Market
Medical Devices
Intracranial Pressure (ICP) Monitoring Devices Market
Medical Devices
Steroid Releasing Implant Market
Medical Devices
Global Plastic Surgery Devices Market
Medical Devices
Osteosynthesis Devices Market
Medical Devices
Organ Preservation Market
Medical Devices
North America Wearable Medical Devices Market
Medical Devices
Nano Healthcare Technology for Medical Equipment Market
Medical Devices
Europe Invisible Orthodontics Market
Medical Devices
Global Occlusion Devices Market
Medical Devices
Global Coagulation-Hemostasis Analyzer Market
Medical Devices
Gel Implants Market
Medical Devices
Brazil Contraceptive Devices Market
Medical Devices
Bluetooth Hearing Aids Market
Medical Devices
Infrared Heating Pad Market