
 Refsum Disease Treatment Market | 2026-2036
Refsum Disease Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Refsum Disease Treatment Market Analysis
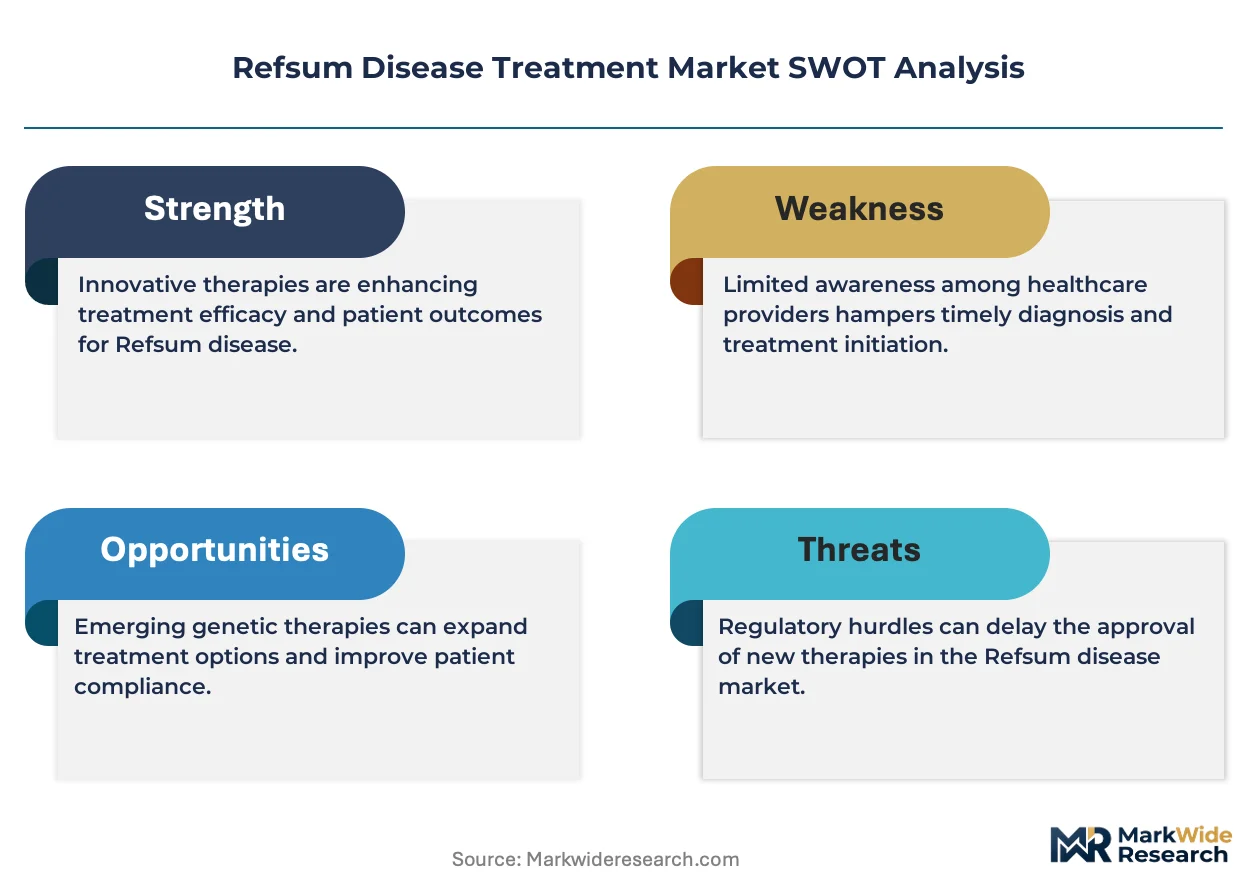
The gap between gene therapy premiums and dietary management commoditization is expanding in Refsum disease care. Rocket Pharmaceuticals sustains R&D intensity in lentiviral platforms for peroxisomal disorders. REGENXBIO anchors its position through AAV9 vector leadership in neurological gene delivery. Travere Therapeutics differentiates via small molecule approaches to rare metabolic pathways.
Refsum disease treatment encompasses therapeutic interventions targeting the peroxisomal disorder characterized by defective phytanoyl-CoA hydroxylase enzyme activity, which causes accumulation of phytanic acid in plasma and tissues with consequent neurological and cardiac damage. The primary purpose is to prevent irreversible retinitis pigmentosa, cardiomyopathy, and peripheral neuropathy through plasma phytanic acid reduction below specific thresholds. Gene therapy represents the fastest-expanding segment as AAV and lentiviral platforms advance toward clinical validation, while dietary management remains the mature baseline with limited margin expansion. Small molecule drugs occupy an intermediate structural position where pharmacological chaperones and substrate reduction therapies attract development capital but face biochemical complexity.
FDA orphan drug designation and EMA's PRIME eligibility framework accelerate clinical trial timelines and market exclusivity for Refsum disease developers. REACH compliance and ISO 13485 quality standards govern vector manufacturing and dietary supplement sourcing across European and North American supply chains. Stakeholders must monitor regulatory precedent from FDA gene therapy guidance and EMA advanced therapy medicinal product classification as these frameworks determine reimbursement thresholds and manufacturing scale requirements.
Market Dynamics
The Refsum Disease Treatment Market pivots on the tension between gene therapy platform maturation and the entrenched dominance of dietary management protocols, with vector manufacturing scale and reimbursement arbitrage determining competitive viability across metabolic disorder centers.
Growth Catalysts
- FDA Orphan Drug Designation:Accelerated clinical trial timelines and extended market exclusivity incentivize biopharmaceutical investment in peroxisomal disorder therapeutics, compressing development-to-commercialization cycles.
- Metabolic Disorder Centers:Specialty clinics in Germany, Japan, and the United States are expanding dedicated protocols for phytanic acid reduction, creating concentrated demand nodes for advanced therapeutics.
- Lentiviral Vector Platforms:Gene delivery technology advances are enabling durable transgene expression in hepatocytes, addressing the enzymatic deficiency underlying phytanic acid accumulation.
Market Restraints
- Plasma-Derived Raw Material Volatility:Apheresis capacity constraints and donor availability fluctuations create input cost instability for therapeutic plasma exchange procedures.
- Vector Manufacturing Concentration:AAV and lentiviral production capabilities cluster among a limited set of contract development and manufacturing organizations, creating supply bottleneck vulnerability.
- Biochemical Complexity of Small Molecules:Pharmacological chaperone development faces substrate specificity limitations that impede broad applicability across peroxisomal enzyme deficiencies.
Strategic Opportunities
- EMA PRIME Eligibility Framework:Priority medicines designation offers enhanced regulatory support and accelerated assessment pathways for novel Refsum disease therapeutics entering European markets.
- Substrate Reduction Therapy Convergence:Combination approaches pairing gene therapy with dietary restriction protocols present untapped efficacy optimization potential.
- Direct-to-Patient Distribution Models:Telemedicine-enabled metabolic disorder management is opening channel access for geographically dispersed patient populations previously underserved by specialty clinic density.
Industry Challenges
- Gene Therapy Manufacturing Talent Scarcity:Vector process development and analytical characterization expertise remains concentrated among a limited pool of specialists, constraining operational scaling.
- ISO 13485 Certification Timelines:Quality management system validation for vector manufacturing facilities extends facility qualification periods, delaying commercial supply readiness.
- Legacy Dietary Protocol Integration:Established phytanic acid restriction regimens create clinical inertia that complicates novel therapeutic adoption and reimbursement justification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refsum Disease Treatment Market |
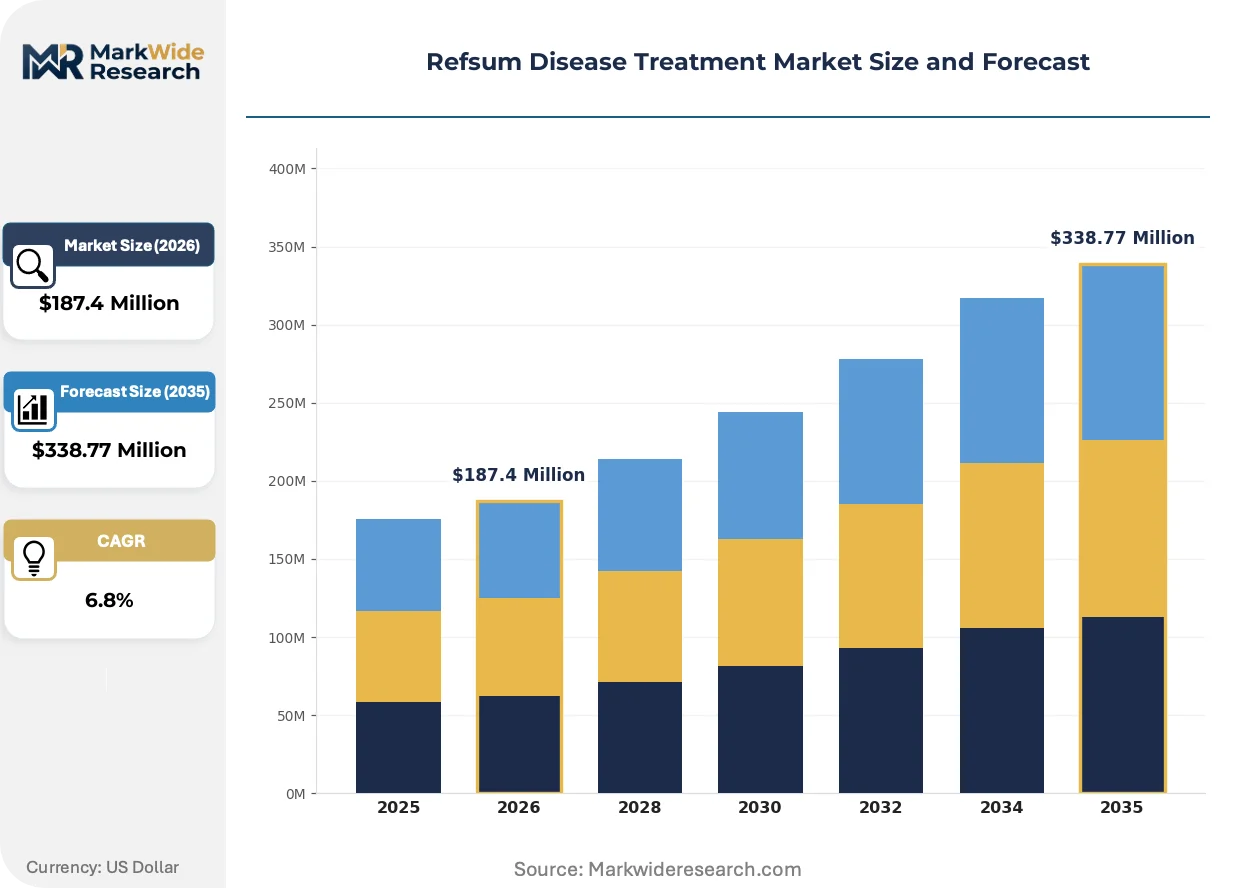
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Therapeutic Enzymes, Small Molecule Drugs, Dietary Supplements, Gene Therapy Therapy Area: Neurological Disorders, Metabolic Disorders, Cardiovascular Complications, Sensory Impairments End User: Specialty Clinics, Metabolic Disorder Centers, Research Institutions, Genetic Counseling Facilities Delivery Mode: Oral Administration, Intravenous Infusion, Subcutaneous Injection, Dietary Management |
| Companies Covered | Rocket Pharmaceuticals, REGENXBIO, Travere Therapeutics, Alnylam, Orchard Therapeutics, PTC Therapeutics, Apellis, Pharnext, BioMarin Pharmaceutical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refsum Disease Treatment Market Emerging Trajectories
Gene therapy platform evolution is fragmenting the Refsum disease treatment landscape, with vector manufacturing advances and regulatory pathway refinements enabling new competitive entry modes while compressing margins for conventional management approaches.
AAV9-based neurological gene delivery is decentralizing the treatment paradigm for peroxisomal disorders by enabling single-administration correction of hepatic enzyme deficiency. Metabolic disorder centers in the United States are adopting these platforms for patient cohorts with rapidly progressive retinitis pigmentosa. The technology is decentralizing treatment location requirements from tertiary academic centers toward community-based specialty clinics with apheresis support capabilities.
REACH compliance mandates for vector manufacturing raw materials are tightening supply chain traceability requirements across European production networks. EMA advanced therapy medicinal product classification guidelines are creating tiered manufacturing standards that differentiate commercial-grade from clinical-trial material. Gene therapy developers with European market ambitions are responding by qualifying alternative plasmid suppliers and establishing redundant viral vector production sites.
Patient advocacy organizations are consolidating purchasing influence through centralized referral network coordination, compressing manufacturer pricing autonomy. Metabolic disorder foundations in Germany and Japan are establishing preferred provider agreements with gene therapy developers, displacing traditional physician-driven prescription patterns. This concentration is most visible in the United States, where consolidated patient registries now direct substantial volume toward designated treatment centers with integrated dietary and gene therapy protocols.
Refsum Disease Treatment Market Segmentation
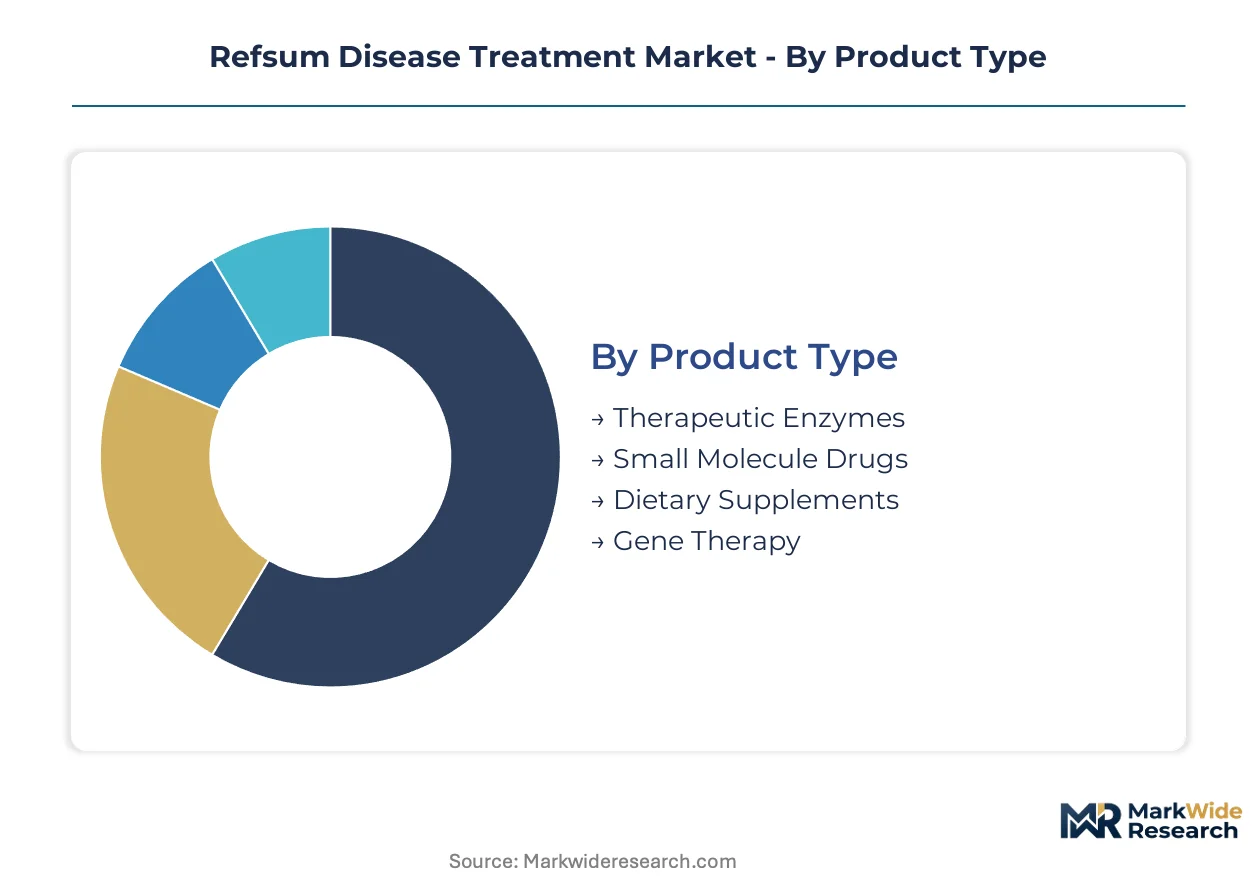
Refsum disease treatment segments diverge sharply on regulatory burden, with gene therapy vectors requiring EMA advanced therapy medicinal product classification and FDA gene therapy guidance compliance, while dietary supplements face lighter quality standards. Understanding these tiered approval pathways enables developers to allocate capital across development stages and manufacturing readiness requirements.
Product Type:
FDA orphan drug designation and EMA PRIME eligibility create divergent certification timelines across product categories, with gene therapy platforms facing the most stringent analytical characterization requirements.
- Gene Therapy:AAV9 and lentiviral vector platforms deliver functional PAHX gene copies to hepatocytes for durable enzymatic correction. Demand concentrates in metabolic disorder centers across Germany and the United States where apheresis infrastructure supports combination protocols. FDA gene therapy guidance and EMA ATMP classification govern manufacturing scale-up and facility qualification timelines.
- Dietary Supplements:Phytanic acid-free nutritional formulations provide baseline disease management through strict restriction of dairy, ruminant fat, and certain seafood sources. Demand clusters in Japan and community-based specialty clinics with limited gene therapy access. ISO 22000 and HACCP standards govern production, with lighter regulatory burden than pharmaceutical pathways.
- Therapeutic Enzymes:Recombinant enzyme replacement approaches target peroxisomal function restoration.
- Small Molecule Drugs:Pharmacological chaperones and substrate reduction compounds address biochemical complexity of peroxisomal enzyme deficiencies.
Gene Therapy sits at the top of the volume ranking, with Dietary Supplements climbing the fastest through expanded metabolic disorder center protocols.
Therapy Area:
End-use application determines reimbursement coding complexity, with neurological indications commanding distinct prior authorization pathways from cardiovascular or sensory impairment categories.
- Neurological Disorders:Peripheral neuropathy and cerebellar ataxia represent the most clinically urgent manifestations requiring rapid plasma phytanic acid reduction. Demand concentrates in tertiary academic centers across the United States with integrated neurology and metabolic genetics departments. Progression risk to irreversible nerve damage drives prioritization of gene therapy access.
- Metabolic Disorders:Systemic phytanic acid accumulation underlies multi-organ pathology and requires coordinated endocrine and hepatology management. Demand clusters in German university hospitals with established peroxisomal disorder expertise. EMA PRIME eligibility accelerates novel therapeutic assessment for this indication cluster.
- Cardiovascular Complications:Arrhythmia and cardiomyopathy prevention through lipid management protocols.
- Sensory Impairments:Retinitis pigmentosa progression mitigation through combined dietary and emerging gene therapy approaches.
Metabolic Disorders commands the largest addressable population, with Neurological Disorders expanding most quickly through accelerated FDA approval pathways.
End User:
Facility certification tier determines product access levels, with research institutions operating under investigational new drug exemptions distinct from commercial dispensing sites.
- Metabolic Disorder Centers:Dedicated rare disease units with integrated dietary, genetic, and advanced therapy capabilities serve as gatekeepers for gene therapy patient selection. These facilities concentrate in Boston, Munich, and Tokyo metropolitan areas with established peroxisomal disorder registries. FDA Risk Evaluation and Mitigation Strategy programs mandate specific site qualifications for vector product handling.
- Specialty Clinics:Community-based metabolic genetics practices manage stable patients through dietary protocols and periodic phytanic acid monitoring. Geographic dispersion across mid-size United States cities and Japanese prefectures creates channel access challenges for advanced therapeutics. Telemedicine integration is expanding reach for geographically isolated patient cohorts.
- Research Institutions:Academic medical centers conducting clinical trials under IND protocols.
- Genetic Counseling Facilities:Pre-symptomatic screening and family planning support sites with limited therapeutic dispensing.
Metabolic Disorder Centers dominate current volume, with Specialty Clinics gaining share fastest through telemedicine-enabled protocol expansion.
Delivery Mode:
Route of administration dictates manufacturing facility requirements, with parenteral modes requiring ISO 13485 certification and sterile fill-finish capabilities distinct from oral or dietary management approaches.
- Intravenous Infusion:Lentiviral vector delivery and therapeutic plasma exchange require apheresis suite availability and specialized nursing protocols. Demand concentrates in German and United States academic medical centers with dedicated metabolic infusion units. Vector stability requirements limit storage duration and create cold chain complexity.
- Dietary Management:Phytanic acid restriction protocols rely on specialized nutritionist counseling and patient compliance monitoring rather than pharmaceutical manufacturing. Implementation spans home-based settings and outpatient clinic visits across Japan and community United States markets. Lower capital intensity enables broader geographic penetration.
- Oral Administration:Small molecule and supplement formulations for patient-managed daily regimens.
- Subcutaneous Injection:Emerging depot formulations for sustained enzyme or vector release.
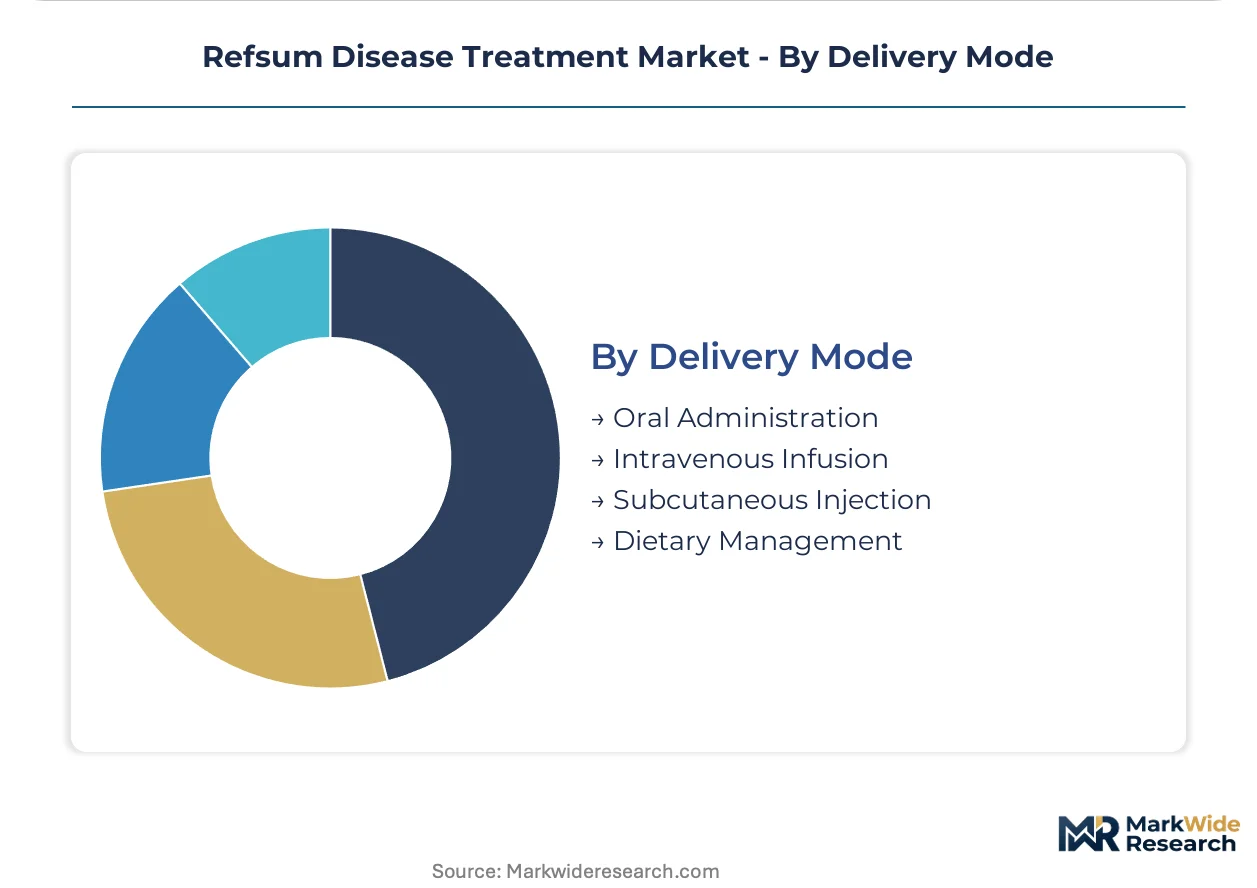
Dietary Management leads current volume distribution, with Intravenous Infusion climbing fastest through gene therapy platform maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gene therapy manufacturing talent clusters in Boston, Munich, and Tokyo anchor geographic demand for Refsum disease treatment infrastructure. These metropolitan concentrations drive specialized apheresis capacity and vector production facility development. Regulatory pathway sophistication varies sharply across national jurisdictions.
United States
FDA orphan drug designation accelerates clinical trial timelines for peroxisomal disorder therapeutics. The agency's gene therapy guidance mandates specific Risk Evaluation and Mitigation Strategy programs for vector product handling. Boston and San Francisco metropolitan areas concentrate metabolic disorder centers with integrated neurology and hepatology departments.
Germany
EMA PRIME eligibility offers enhanced regulatory support for novel Refsum disease therapeutics entering European markets. REACH compliance mandates tighten supply chain traceability requirements for vector manufacturing raw materials. Munich and Heidelberg university hospitals anchor peroxisomal disorder expertise with established patient registries.
Japan
PMDA accelerated approval pathways for rare diseases compress development-to-commercialization cycles for metabolic disorder therapeutics. METI funding programs support domestic vector manufacturing capacity expansion. Tokyo and Osaka metropolitan areas concentrate specialty clinics with telemedicine-enabled protocol expansion for geographically dispersed patients.
United Kingdom
NHS specialized commissioning frameworks determine reimbursement thresholds for advanced therapy medicinal products in metabolic genetics. MHRA alignment with EMA ATMP classification guidelines governs manufacturing standards for commercial-grade vector materials. London and Cambridge biotech clusters host gene therapy developers targeting peroxisomal enzyme deficiencies.
Switzerland
Swissmedic streamlined assessment procedures for orphan medicines attract gene therapy developers seeking European market entry. The country's precision medicine initiatives fund metabolic disorder research consortia. Basel and Zurich pharmaceutical hubs concentrate contract development organizations with peroxisomal disorder therapeutic expertise.
Refsum Disease Treatment Market Vendor Landscape
Top-tier vendors anchor gene therapy platform development, while mid-tier specialists concentrate on small molecule and dietary management approaches. The vendor base stratifies across vector manufacturing capabilities, regulatory pathway sophistication, and metabolic disorder center relationships. Three archetypes dominate: lentiviral platform developers, AAV vector specialists, and small molecule pathway modulators. Competitive moves center on strategic partnerships for vector manufacturing capacity and geographic expansion into German and Japanese metabolic disorder networks.
Within the gene therapy archetype, Rocket Pharmaceuticals, REGENXBIO, and Travere Therapeutics exemplify divergent platform strategies. Rocket Pharmaceuticals represents lentiviral vector approaches targeting hepatic enzyme correction. REGENXBIO anchors AAV9-based neurological gene delivery capabilities. Travere Therapeutics occupies a position emphasizing small molecule approaches to rare metabolic pathways. These three entities collectively illustrate the competitive fragmentation between viral vector platforms and pharmacological intervention strategies in peroxisomal disorder therapeutics.
| Leading Market Players |
|---|
| Rocket Pharmaceuticals |
| REGENXBIO |
| Travere Therapeutics |
| Alnylam |
| Orchard Therapeutics |
| PTC Therapeutics |
| Apellis |
| Pharnext |
| BioMarin Pharmaceutical |
| Others |
Supply Flow & Price Mechanics
AAV9 vector manufacturing scale-up simultaneously compresses per-dose production costs and concentrates supply among contract development organizations with ISO 13485 certification. This dual effect reshapes pricing power across gene therapy tiers while tethering margin structures to plasma-derived raw material availability and apheresis capacity utilization in Germany and the United States.
Pricing Analysis
The bundled-vs-unbundled service split separates comprehensive metabolic disorder center protocols from standalone dietary management offerings. Gene therapy developers command premium positioning through integrated apheresis-vector-dietary bundles at tertiary centers, while phytanic acid-free nutritional formulations compete on ISO 22000 certification and volume scale in community clinics. Cost compression in dietary supplements intensifies as Japanese metabolic disorder foundations consolidate purchasing through preferred provider agreements. Community-based specialty clinics exhibit highest price sensitivity due to reimbursement coding limitations, whereas academic medical centers with FDA Risk Evaluation and Mitigation Strategy qualifications absorb premium tiering for novel vectors.
Supply Chain Analysis
Plasmid DNA supply rests on United States and European contract manufacturers with EMA advanced therapy medicinal product qualification. Lentiviral vector production draws from German and Swiss facilities with redundant viral vector capabilities, while apheresis equipment sourcing centers on Japanese and United States medical device specialists. Single-source vulnerability pervades AAV9 capsid supply where limited qualified suppliers create bottleneck exposure. Distribution runs through cold chain logistics networks serving metabolic disorder centers in Boston, Munich, and Tokyo metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Refsum disease treatment market functions as a stable compounder where orphan drug designation pathways and expanding metabolic disorder center infrastructure sustain steady therapeutic demand expansion.
For Market Incumbents: Lock in vector manufacturing capacity through long-term agreements with ISO 13485-certified contract development organizations in Germany and Switzerland. Secure preferred provider status with Japanese metabolic disorder foundations before patient registry consolidation accelerates. Gene therapy platform differentiation and EMA PRIME eligibility investment defend against emerging small molecule substrate reduction competitors.
For New Entrants and Emerging Players: FDA orphan drug designation in the United States opens a window for accelerated clinical trial entry with compressed development timelines. Target community-based specialty clinics in Japanese prefectures with telemedicine-enabled dietary management protocols as the most penetrable white space. Pursue substrate reduction therapy convergence approaches pairing pharmacological chaperones with established phytanic acid restriction regimens.
For Investors and Strategic Acquirers: Valuations sit cheapest among small molecule pathway modulators facing biochemical complexity constraints that limit near-term clinical validation. The five-to-ten year viability window favors gene therapy platform developers with demonstrated hepatocyte transgene expression durability. Watch EMA advanced therapy medicinal product manufacturing scale-up approvals as the critical inflection signal for European market entry readiness.
| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA and EMA pathways compress clinical trial timelines and extend exclusivity for peroxisomal disorder therapeutics. |
| Vector Manufacturing Scale-Up | ISO 13485 facility qualification in Germany and Switzerland enables commercial-grade AAV9 and lentiviral supply. |
| Metabolic Disorder Center Partnership | Preferred provider agreements with Boston, Munich, and Tokyo tertiary centers secure patient access and reimbursement. |
| Substrate Reduction Therapy Development | Pharmacological chaperone programs address biochemical complexity gaps in peroxisomal enzyme deficiency correction. |
| Telemedicine Protocol Expansion | Remote dietary management reaches geographically dispersed Japanese and United States patient cohorts beyond clinic density. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with gene therapy development executives, regulatory affairs leads at EMA and FDA, metabolic disorder center directors, and payer access specialists with secondary validation. FDA orphan drug designation filings, EMA advanced therapy medicinal product submissions, ClinicalTrials.gov entries, and metabolic disorder foundation registry data anchored bottom-up and top-down triangulation.
Segment-weighting approaches distributed volume and value across gene therapy vectors, dietary supplements, small molecule drugs, and therapeutic enzymes by therapy area and end-user facility tier. The analytical framework modeled neurological, metabolic, cardiovascular, and sensory impairment indications across the projection horizon, with CAGRs derived from patient population epidemiology, treatment penetration assumptions, and pricing trajectory analysis. Vector manufacturing capacity expansion timelines and EMA PRIME eligibility decisions served as key forecast inputs.
Revisions become necessary when regulatory pathway delays, vector manufacturing batch failures, or metabolic disorder center reimbursement coding changes materialize. Forecasts reflect documented assumptions about clinical trial progression, manufacturing scale-up success, and patient registry consolidation trajectories. A small set of named triggers warrants ongoing watch: EMA ATMP manufacturing approvals, FDA gene therapy guidance updates, and Japanese PMDA accelerated assessment decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Hemorrhoids Treatment Market
Medical Treatment
Nasopharyngeal Carcinoma Treatment Market
Medical Treatment
Lung Cancer Surgery Market
Medical Treatment
Tendonitis Treatment Market
Medical Treatment
Transarterial Chemoembolization (TACE) Market
Medical Treatment
Adenomyosis Treatment Market
Medical Treatment
Hyperbaric Oxygen Therapy (HBOT) Market
Medical Treatment
Inguinal Hernia Market
Medical Treatment
Andersen Tawil Syndrome Treatment Market
Medical Treatment
Thyroid Deficiency Treatment Market
Medical Treatment
Cholera Treatment Market
Medical Treatment
Spain Hair Transplant Market
Medical Treatment
Rett Syndrome Treatment Market
Medical Treatment
Stereotactic Body Radiation Therapy Market
Medical Treatment
Iron Deficiency Anemia Treatment Market
Medical Treatment
Tissue Repair Technologies Market