
 Veterinary X-Ray Illuminators Market | 2026-2036
Veterinary X-Ray Illuminators Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary X-Ray Illuminators Market Analytics
Veterinary equipment distribution through regional medical supply cooperatives is rewriting how smaller clinics access imaging accessories. GE Healthcare leverages its installed base of radiology platforms to bundle illuminator sales with service contracts. Wolf X-Ray specializes in manual-film viewing equipment for price-sensitive practices that have not transitioned to fully digital PACS workflows. DRE Veterinary competes through direct e-commerce channels that bypass traditional distributor markups on replacement lamps and viewing panels.
Veterinary X-Ray Illuminators are backlit viewing devices, typically employing LED arrays rated at 4000–6000 Kelvin color temperature, designed to render radiographic film density for diagnostic interpretation in animal healthcare settings. Their primary commercial purpose is to enable veterinarians to evaluate skeletal, thoracic, and abdominal films with consistent luminance uniformity across the viewing surface. LED Illuminators now dominate new procurement as their 50,000-hour lamp life and dimmable output reduce total cost of ownership versus legacy Fluorescent Illuminators with ballast-dependent maintenance cycles. Portable Illuminators represent the fastest-growing product configuration, driven by mobile veterinary services and field-based equine practices that require battery-operated, lightweight units for on-site radiograph review.
The FDA Center for Veterinary Medicine oversees diagnostic device quality standards for equipment used in animal drug development studies, while ISO 60601-1 electrical safety requirements apply to illuminator manufacturing for clinical installations. The EU MDR framework imposes stricter post-market surveillance obligations on devices sold into European veterinary clinics, elevating documentation burdens for non-digital product lines. Stakeholders must monitor how national veterinary practice accreditation standards evolve to specify minimum viewing-brightness thresholds, as these criteria will determine replacement timing for aging fluorescent units across clinic networks.
Market Dynamics
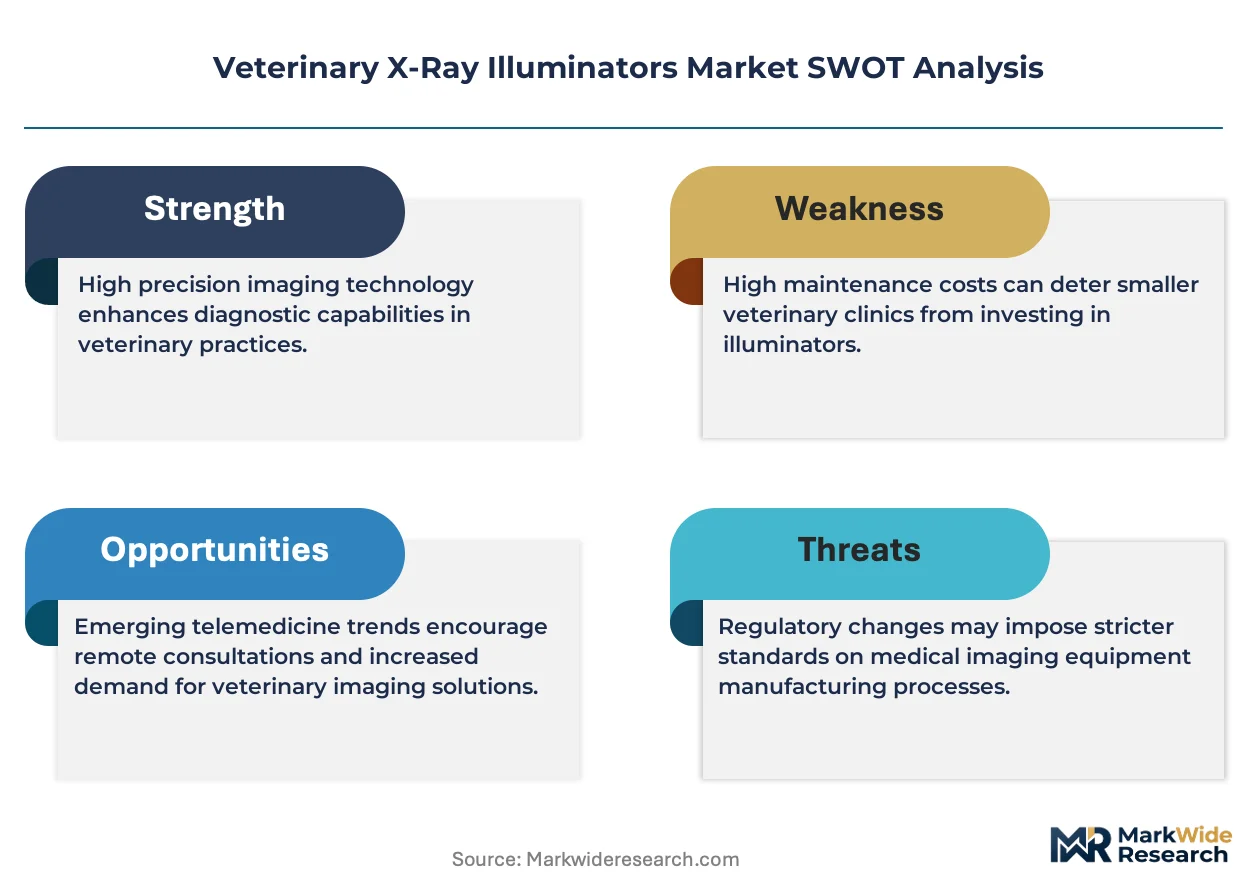
LED backlighting technology is systematically displacing fluorescent tube illuminators across veterinary diagnostic suites, compressing replacement cycles as clinic networks consolidate and standardize equipment procurement protocols.
Growth Catalysts
- Veterinary Practice Consolidation:Large clinic networks in the United States mandate uniform imaging standards across acquired locations, accelerating capital equipment refresh timelines for viewing devices.
- ISO 60601-1 Electrical Safety Standards:Compliance requirements for clinical installations drive replacement of aging fluorescent units that cannot meet updated grounding and insulation specifications.
- Mobile Veterinary Services:Field-based equine practices and rural companion animal services demand battery-operated portable illuminators for on-site radiograph interpretation.
Market Restraints
- LED Array Input Costs:Semiconductor component pricing volatility constrains margin flexibility for manufacturers assembling high-luminance viewing panels rated at 4000–6000 Kelvin.
- Digital PACS Substitution:Fully digitized radiology workflows in university teaching hospitals eliminate physical film viewing requirements entirely.
- EU MDR Documentation Burden:Stricter post-market surveillance obligations elevate compliance costs for non-digital illuminator product lines sold into European veterinary clinics.
Strategic Opportunities
- Suburban Clinic Expansion:United States companion animal clinics outside metropolitan cores are constructing dedicated diagnostic imaging suites with dedicated viewing stations.
- E-Commerce Distribution Channels:Direct-to-practice sales platforms bypass traditional medical supply cooperative markups on replacement lamps and viewing panels.
- Service Contract Bundling:Radiology platform vendors integrate illuminator procurement into multi-year maintenance agreements covering entire diagnostic suites.
Industry Challenges
- Legacy Fluorescent Ballast Expertise:Maintenance technicians skilled in magnetic and electronic ballast troubleshooting face obsolescence as LED driver circuits dominate new installations.
- Digital-Analog Workflow Integration:Hybrid practices maintaining both film and digital systems require dual-compatible viewing infrastructure with inconsistent software protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary X-Ray Illuminators Market |
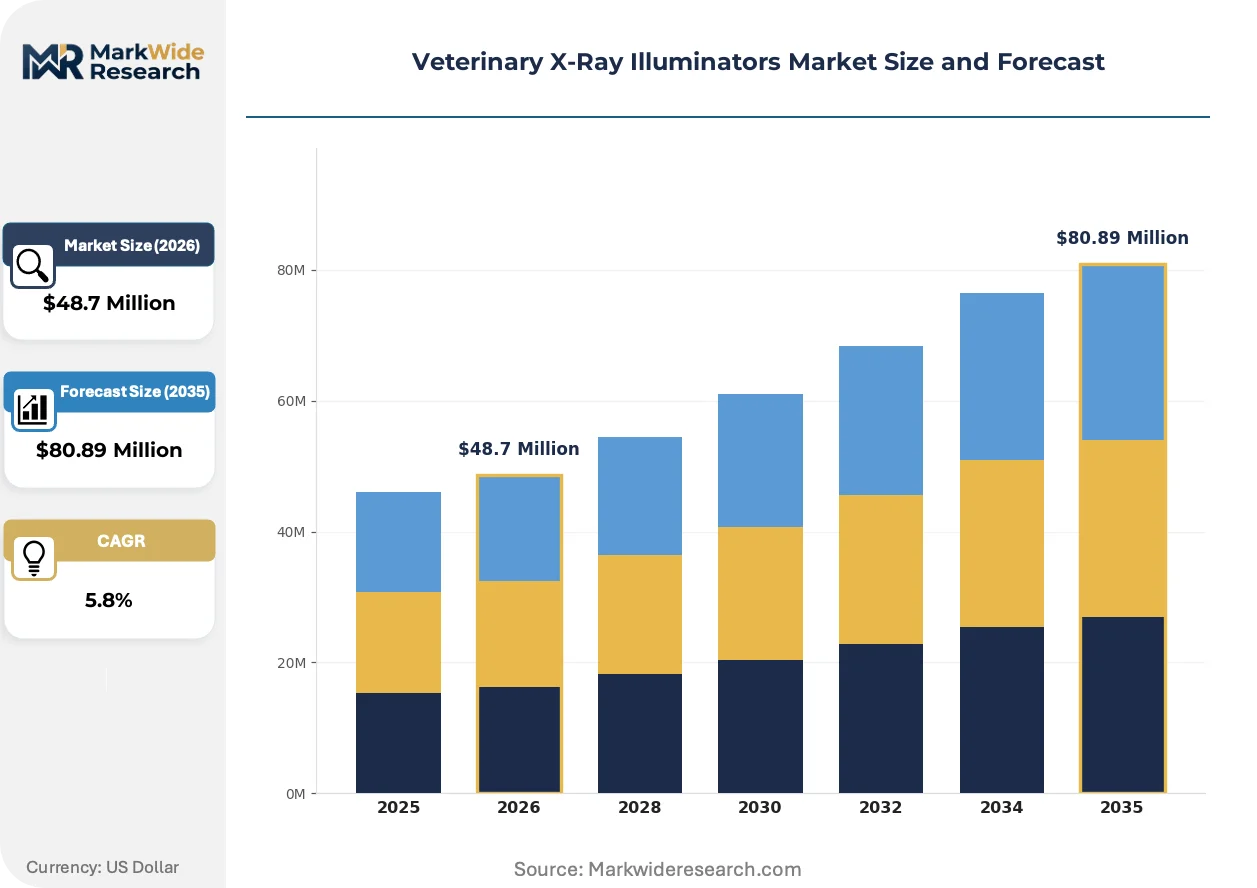
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $80.89 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Illuminators, Fluorescent Illuminators, Arc Illuminators, Portable Illuminators Technology: Digital Imaging, Analog Imaging, Electroluminescent Technology, LCD Technology End User: Veterinary Clinics, Animal Hospitals, Research Institutions, Mobile Veterinary Services Application: Diagnostics, Surgical Guidance, Educational Purposes, Research Analysis |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips N.V., Carestream Health, Fujifilm Holdings Corporation, DRE Veterinary, Wolf X-Ray, Paragon Medical Supply, Protech Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary X-Ray Illuminators Market Evolving Landscape
Diagnostic imaging workflows in animal healthcare are undergoing fundamental restructuring as hardware, software, and service delivery models converge around efficiency and standardization imperatives.
LED illuminator technology is digitizing the radiographic interpretation process by embedding dimmable driver circuits and luminance sensors directly into viewing panels. Suburban companion animal clinics in North America are adopting these units at accelerated rates during facility renovations. This transition is digitizing legacy quality control procedures that previously relied on manual visual calibration against reference films.
The EU MDR framework imposes expanded technical documentation and post-market surveillance obligations on veterinary device manufacturers selling into European clinics. Compliance teams must now maintain clinical evidence files and vigilance reporting systems previously required only for human medical devices. German and French veterinary equipment distributors are restructuring supplier qualification processes to accommodate these elevated traceability requirements.
Regional medical supply cooperatives are losing procurement influence as price-sensitive practices migrate toward direct e-commerce channels for replacement components. Independent companion animal clinics in the United States increasingly source lamps and viewing panels through manufacturer-direct portals that eliminate distributor margin stacking. This channel disintermediation is most pronounced among smaller practices operating outside consolidated network structures.
Veterinary X-Ray Illuminators Market Segmentation
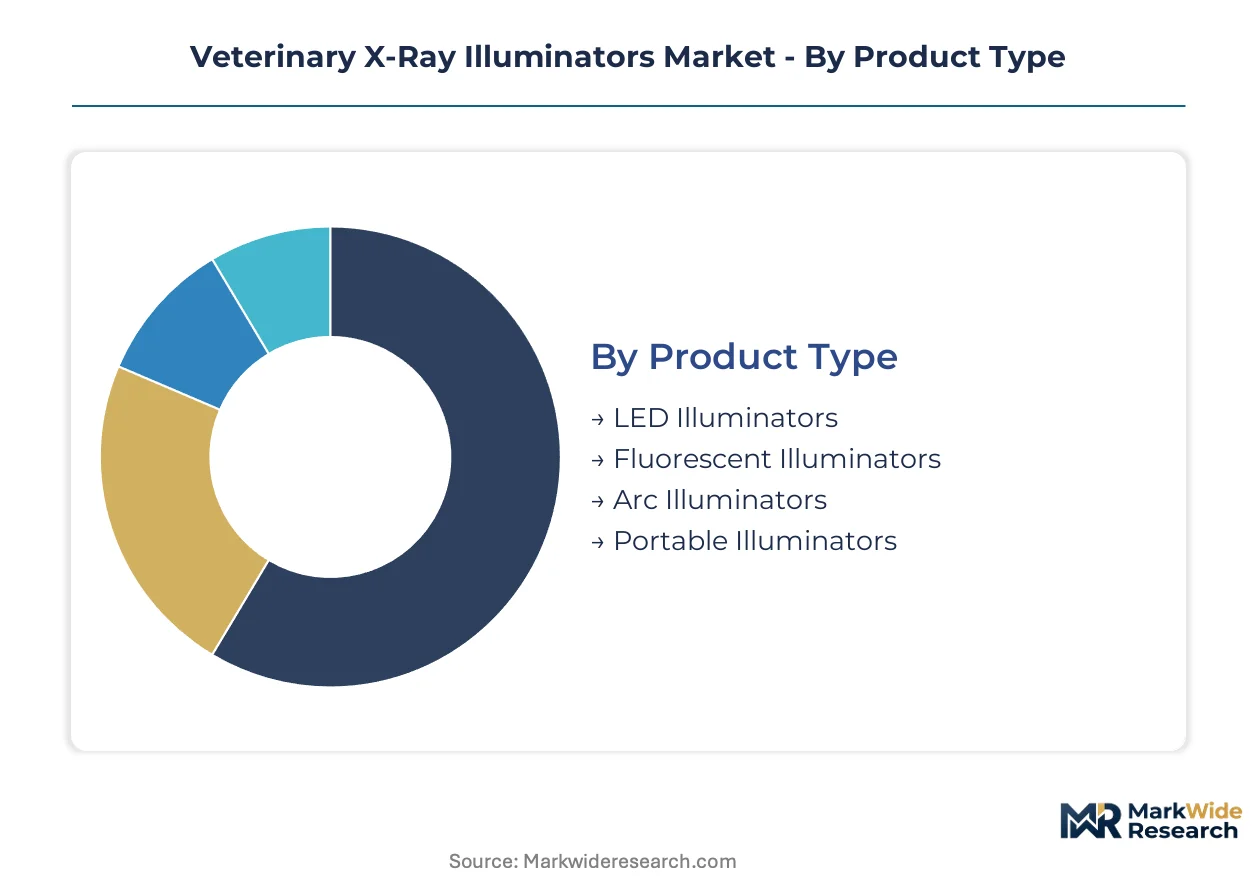
Veterinary X-Ray Illuminators divide across four intersecting dimensions that determine procurement priorities. Product type and technology choices reflect capital constraints and workflow digitization status. End user and application segments reveal where clinical demand concentrates versus where research and educational requirements create specialized specifications.
Product Type:
Mature fluorescent installations coexist with emerging LED configurations as clinics navigate replacement timing and budget cycles.
- LED Illuminators:Solid-state arrays rated at 4000–6000 Kelvin deliver 50,000-hour operational life with dimmable output control. United States companion animal clinics in suburban expansion zones specify these units for new diagnostic imaging suites, driven by total cost of ownership calculations that favor reduced maintenance intervals over higher upfront capital outlay.
- Portable Illuminators:Battery-operated, lightweight viewing panels enable field-based radiograph interpretation without fixed electrical infrastructure. Mobile veterinary services and equine practices across rural Germany and Japan deploy these units for on-site diagnostics, with demand climbing fastest where geographic dispersion limits clinic network density.
- Fluorescent Illuminators:Legacy tube-and-ballast systems dominate installed base in price-sensitive practices that deferred capital refresh.
- Arc Illuminators:Specialized high-intensity discharge units serve niche research applications requiring extreme luminance uniformity.
LED Illuminators handle the majority of throughput; Portable Illuminators are gaining share fastest.
Technology:
Cost tier stratification separates premium digital configurations from economy analog alternatives that persist in constrained budgets.
- Digital Imaging:Integrated sensor arrays and automated calibration protocols eliminate manual luminance verification. University teaching hospitals in Japan and the United States deploy these systems where PACS integration mandates standardized output, though full digitization removes physical film viewing requirements entirely at the highest investment tiers.
- Analog Imaging:Passive viewing surfaces without embedded electronics maintain lowest acquisition cost. Small independent clinics in Germany retain these units where film-based workflows persist alongside limited digital infrastructure, constrained by capital access rather than clinical preference.
- Electroluminescent Technology:Thin-film phosphor layers provide uniform backlighting in compact form factors for space-constrained installations.
- LCD Technology:Active matrix liquid crystal panels enable software-controlled brightness adjustment and color temperature shifting.
Digital Imaging commands premium positioning; Analog Imaging retains volume leadership in absolute unit terms.
End User:
Customer type determines specification intensity, with institutional buyers demanding integration capabilities that independent operators often bypass.
- Veterinary Clinics:Companion animal and mixed-practice facilities constitute the core commercial channel. Suburban United States clinics expanding diagnostic capabilities drive replacement cycles, with procurement decisions influenced by regional medical supply cooperative relationships or direct e-commerce migration.
- Animal Hospitals:Multi-specialty referral centers require viewing infrastructure compatible with high-throughput radiology departments. German and Japanese hospital networks standardize equipment across consolidated locations, creating volume concentration for vendors capable of service contract bundling.
- Research Institutions:Academic and pharmaceutical research facilities demand calibrated luminance for reproducible imaging studies under FDA Center for Veterinary Medicine oversight.
- Mobile Veterinary Services:Field-operating practices prioritize battery autonomy and transport durability over fixed-installation features.
Veterinary Clinics generate the highest absolute demand; Mobile Veterinary Services show the steepest expansion trajectory.
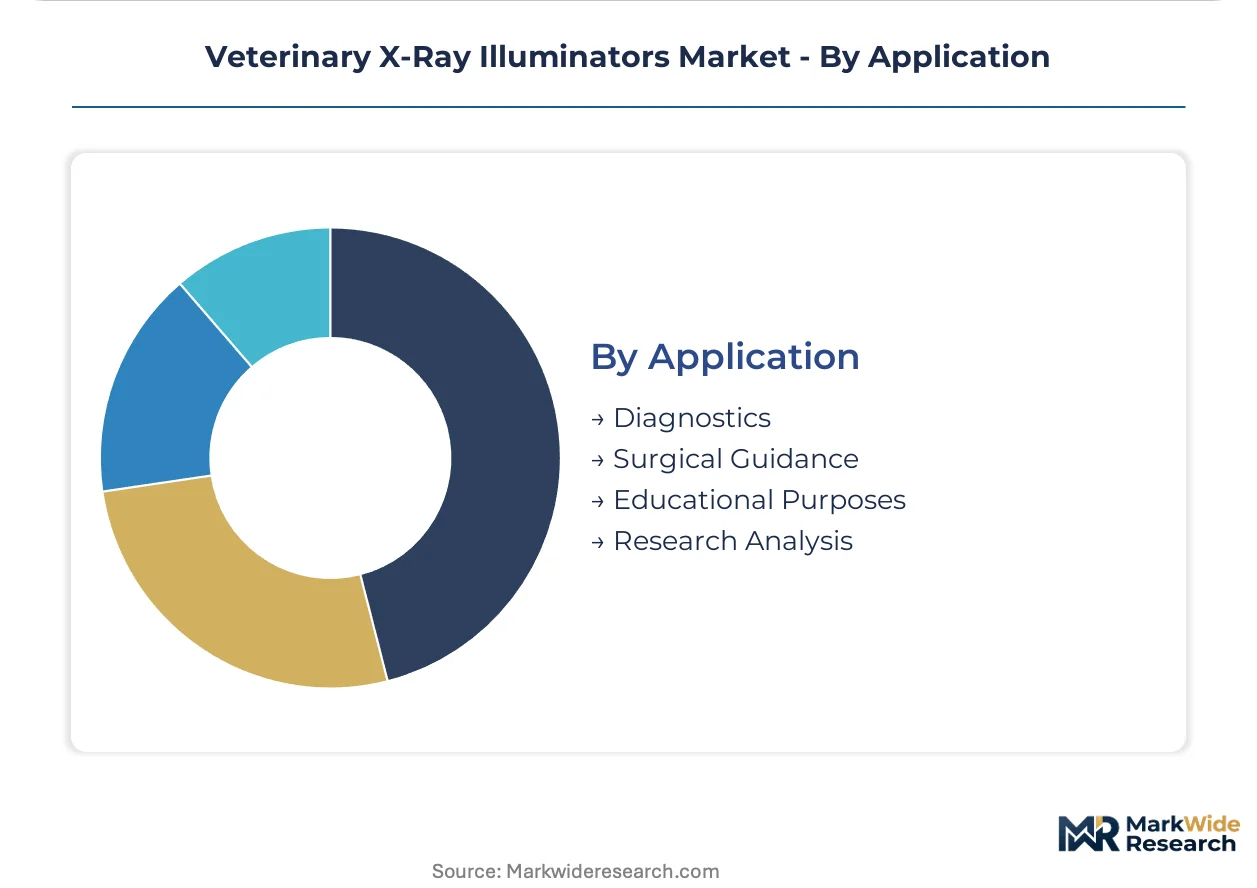
Application:
Volume concentrates in routine diagnostics while margin accumulates in specialized procedural and research contexts.
- Diagnostics:Standard radiograph interpretation for skeletal, thoracic, and abdominal evaluation represents the foundational use case. Every clinic network, from United States suburban expansion projects to Japanese metropolitan hospitals, maintains viewing capacity for this core function regardless of digitization status.
- Surgical Guidance:Intraoperative film review for orthopedic and soft-tissue procedures requires portable or ceiling-mounted viewing stations. German equine surgical centers and United States specialty hospitals invest in dedicated units for operating suite integration.
- Educational Purposes:Veterinary schools and training programs utilize illuminators for instructional film review and competency assessment.
- Research Analysis:Controlled studies and pharmaceutical safety testing demand calibrated, documented viewing conditions under regulatory compliance protocols.
Diagnostics absorbs the largest equipment base; Surgical Guidance delivers the highest per-unit specification premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Center for Veterinary Medicine oversight shapes equipment standards across the United States, while ISO 60601-1 electrical safety requirements apply universally to clinical installations. National veterinary practice accreditation standards vary by jurisdiction, creating differentiated replacement timelines for aging fluorescent units.
United States
Companion animal clinics in suburban expansion zones are constructing dedicated diagnostic imaging suites with LED-equipped viewing stations. Large clinic networks mandate uniform imaging standards across acquired locations, accelerating capital equipment refresh cycles. The Greater Boston and Pacific Northwest veterinary corridors concentrate procurement activity among multi-site operators.
Germany
Veterinary practice consolidation in Bavaria and North Rhine-Westphalia drives standardization of viewing infrastructure across hospital networks. EU MDR post-market surveillance obligations elevate documentation burdens for equipment distributors serving German and French clinics. The Stuttgart veterinary equipment cluster hosts distributors restructuring supplier qualification processes.
Japan
University teaching hospitals in the Kanto region deploy digital-integrated illuminators where PACS compatibility mandates standardized output. METI industrial standards influence electrical safety specifications for clinical installations. The Osaka-Kobe corridor concentrates demand from metropolitan referral centers with high-throughput radiology departments.
United Kingdom
Independent companion animal practices in the Southeast retain analog viewing equipment where capital constraints limit digital transition. The country's national veterinary regulator monitors diagnostic device quality standards for research applications. London satellite clinics drive replacement demand among mixed-practice operators upgrading legacy fluorescent installations.
Canada
Health Canada oversight applies to diagnostic equipment used in pharmaceutical safety studies, creating specialized specifications for research-oriented installations. Ontario and Quebec veterinary networks standardize procurement across provincial clinic cooperatives. The Toronto-Waterloo corridor concentrates academic veterinary medicine demand from teaching hospitals.
Veterinary X-Ray Illuminators Market Competitive Landscape
Full-line radiology platform vendors and specialized illuminator fabricators split the market between bundled service contracts and component replacement sales. Tiered concentration prevails: three multinational imaging conglomerates anchor premium procurement channels, while regional equipment specialists capture price-sensitive independent practices. Strategic archetypes include platform-integrated suppliers, standalone viewing equipment manufacturers, and direct-to-practice e-commerce distributors. Competitive moves center on service contract bundling and channel disintermediation through online replacement part portals.
Among diversified health technology conglomerates, GE Healthcare and Siemens Healthineers occupy positions representing the platform-integrated archetype, leveraging installed radiology bases to attach illuminator sales. Koninklijke Philips N.V. exemplifies the premium-tier multinational structure. Specialized standalone manufacturers including Wolf X-Ray and DRE Veterinary anchor the independent equipment segment, with the latter representing direct e-commerce distribution models that bypass traditional medical supply cooperative markups.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips N.V. |
| Carestream Health |
| Fujifilm Holdings Corporation |
| DRE Veterinary |
| Wolf X-Ray |
| Paragon Medical Supply |
| Protech Medical |
| Others |
Value Network & Pricing Analysis
The Shenzhen-Guangzhou electronics corridor anchors LED array manufacturing capacity for veterinary illuminator panels, with component availability fluctuations translating directly into margin compression for downstream viewing equipment assemblers serving price-sensitive clinic networks.
Pricing Analysis
United States-Germany price spreads exceed thirty percent for equivalent LED illuminator specifications, with premium tiers commanding ISO 60601-1 certification premiums and extended warranty bundling while economy analog units face cost compression from direct e-commerce channel disintermediation. Three-tier pricing structure across premium, standard, and economy levels separates digital-integrated hospital systems from suburban clinic expansion projects and legacy fluorescent replacement demand. Pricing pressure stems from semiconductor input cost volatility constraining manufacturer margin flexibility. Independent companion animal clinics exhibit highest price sensitivity, while consolidated hospital networks absorb premium positioning through multi-year service contracts.
Supply Chain Analysis
LED driver circuits and phosphor-coated substrates feed from concentrated manufacturing bases in China, Taiwan, and South Korea, with veterinary illuminator assemblers drawing from these upstream electronics clusters for dimmable control modules and color-temperature-calibrated arrays. Raw material dependencies center on rare-earth phosphors, aluminum substrate stock, and semiconductor wafer supply. Single-source vulnerability in LED chip fabrication creates exposure to regional logistics disruptions affecting component lead times. Distribution runs through regional medical supply cooperatives for traditional procurement, though direct manufacturer portals increasingly capture replacement lamp and panel demand from smaller independent practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary X-Ray Illuminators represent an early-cycle equipment refresh story as LED backlighting penetration in animal healthcare diagnostic suites remains below saturation, with suburban clinic construction and mobile veterinary service expansion providing sustained adoption tailwinds.
For Market Incumbents: Entrench service contract bundling advantages by integrating illuminator procurement into multi-year radiology platform maintenance agreements covering entire diagnostic suites, while accelerating backward integration into LED driver circuit production to offset semiconductor pricing volatility and defend margin structures against direct e-commerce distributors. For New Entrants and Emerging Players: Battery-operated portable illuminators for field-based equine practices in rural Germany and Japan represent the most penetrable entry point, with lightweight diagnostic viewing for mobile veterinary services offering lowest competitive density; pursue direct-to-practice digital channels that bypass traditional medical supply cooperative markups on replacement components. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because veterinary practice network standardization mandates will progressively eliminate fragmented independent equipment suppliers; target acquisition profiles center on regional distributors with established clinic relationships and service infrastructure. The signal to watch is national veterinary accreditation standards specifying minimum viewing-brightness thresholds that trigger accelerated fluorescent replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| LED Technology Transition | LED illuminator procurement displaces fluorescent installations in suburban United States clinic expansion projects. |
| Service Contract Bundling | Multi-year maintenance agreements integrate viewing equipment into radiology platform vendor relationships. |
| Direct E-Commerce Channel Development | Manufacturer portals bypass distributor markups on replacement lamps and viewing panels for independent practices. |
| EU MDR Compliance Investment | Enhanced technical documentation capabilities satisfy post-market surveillance obligations for European veterinary clinic sales. |
| Portable Product Line Expansion | Battery-operated illuminator development captures mobile veterinary services and field-based equine practice demand. |
Research Methodology
Operator-level perspectives from veterinary clinic procurement managers, biomedical equipment technicians, regional distributor sales directors, and GPO contract administrators anchored the qualitative base, cross-referenced with FDA Center for Veterinary Medicine device registrations, ISO 60601-1 certification databases, EU MDR vigilance reports, and veterinary practice consolidation transaction records. Bottom-up demand modeling from clinic-level equipment refresh cycles combined with top-down market sizing from manufacturer shipment data to establish volume baselines.
Scenario-bracketing across LED adoption pace, veterinary practice consolidation velocity, and mobile service expansion rates framed the projection horizon, with segmentation across product type, technology tier, end-user category, and application area informing granular demand allocation. CAGRs were derived from equipment replacement cycle analysis and capital expenditure trajectory modeling, incorporating semiconductor pricing indices and regional construction permits for veterinary diagnostic facilities as industry-specific inputs.
Stress conditions across LED component supply disruptions, EU MDR documentation compliance delays, and digital PACS substitution acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against veterinary equipment trade association shipment surveys and hospital procurement database benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
US Patient Positioning Systems Market
Medical Devices
Distraction Osteogenesis Devices Market
Medical Devices
Soft Tissue Release Systems Market
Medical Devices
Robot Assisted PCI Market
Medical Devices
Wireless Handheld Ultrasound Devices Market
Medical Devices
Left Atrial Appendage (LAA) Closure Device Market
Medical Devices
Global Digital Therapeutic Devices Market
Medical Devices
Global Surgical Drills Market
Medical Devices
Bowel Irrigation System Market
Medical Devices
Next Generation Blood Gas Monitors System Market
Medical Devices
Electrophysiology Ablation Market
Medical Devices
North America Insulin Delivery Devices Market
Medical Devices
Medical Device Films Market
Medical Devices
Europe Sperm Separation Devices Market
Medical Devices
Global Female Stress Urinary Incontinence Treatment Devices Market
Medical Devices
Infant Oxygen Hoods Market