
 IV Fluid Transfer Drugs Devices Market | 2026-2036
IV Fluid Transfer Drugs Devices Market Size, Share, and Industry Trends Forecast 2026-2036
IV Fluid Transfer Drugs Devices Market Foresight
European sterile device manufacturing is realigning capacity toward closed-system transfer devices and needle-free connectors. B. Braun Melsungen leverages its German production base to dominate European gravity set supply. Baxter International anchors North American hospital contracts through integrated fluid therapy portfolios. ICU Medical competes on proprietary needle-free valve technology that reduces bloodstream infection risk.
IV fluid transfer drugs devices comprise closed and open systems for sterile movement of pharmaceuticals, electrolytes, blood products, and nutritional solutions between containers, infusion sets, and patient vascular access points, typically operating under gravity, mechanical pressure, or electronic pump control at flow rates from 0.1 mL/hr to 999 mL/hr with occlusion and air-in-line sensors. Their primary purpose is to eliminate contamination, dosage error, and occupational exposure during parenteral administration. Infusion pump technology captures the largest margin pool as hospitals prioritize dose-error reduction software and drug library integration. Smart wireless systems represent the fastest-expanding technology segment as telemetry-enabled pumps integrate with electronic health records and central monitoring stations. Gravity sets remain the volume backbone in cost-constrained clinics and emerging ambulatory settings.
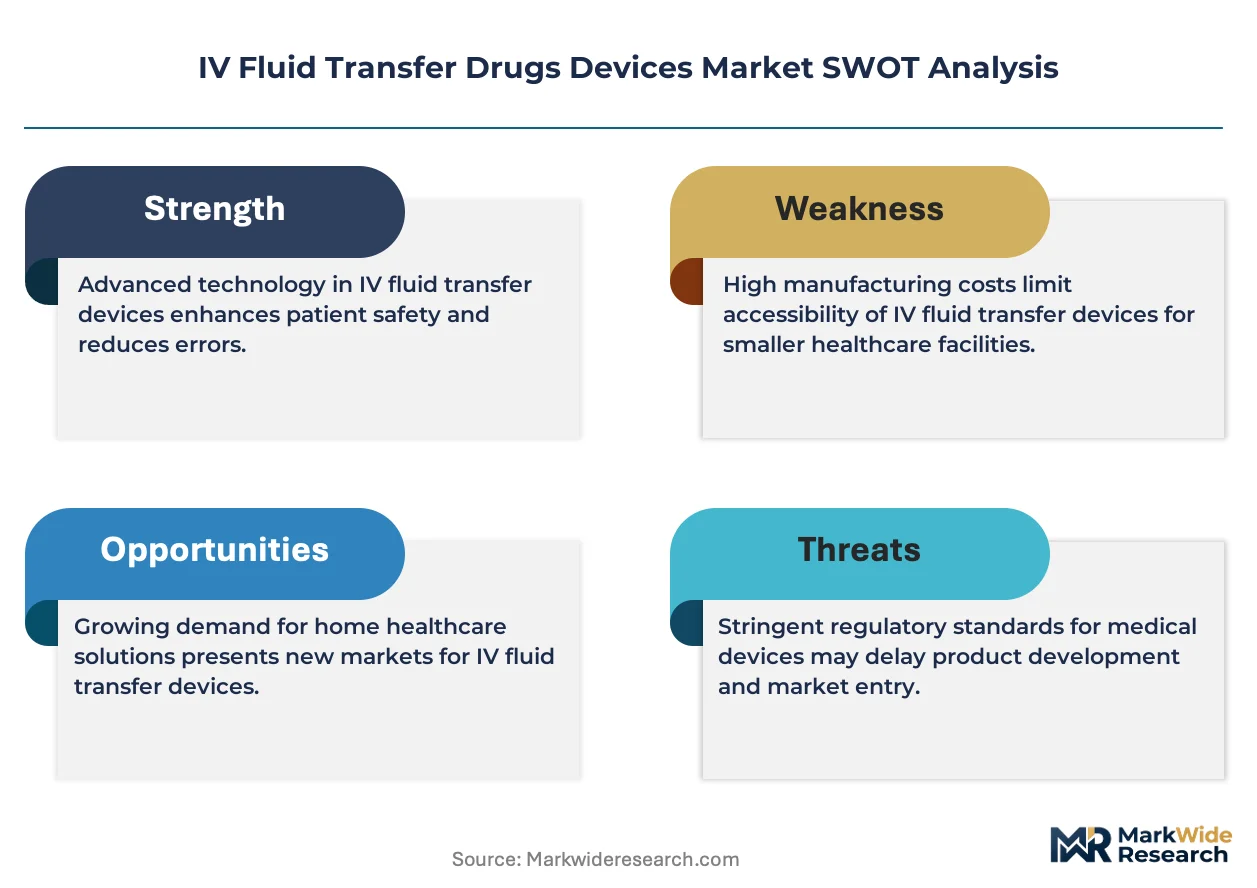
The FDA's infusion pump guidance and the EU Medical Device Regulation (MDR) impose escalating clinical evidence and post-market surveillance requirements that favor manufacturers with established quality management systems and predicate device histories. ISO 80369 small-bore connector standards are reshaping product interoperability and forcing redesign cycles across legacy device portfolios. Stakeholders must monitor regulatory divergence between FDA software-as-medical-device frameworks and EU AI Act implications for smart pump algorithms to anticipate compliance cost trajectories and competitive moat durability.
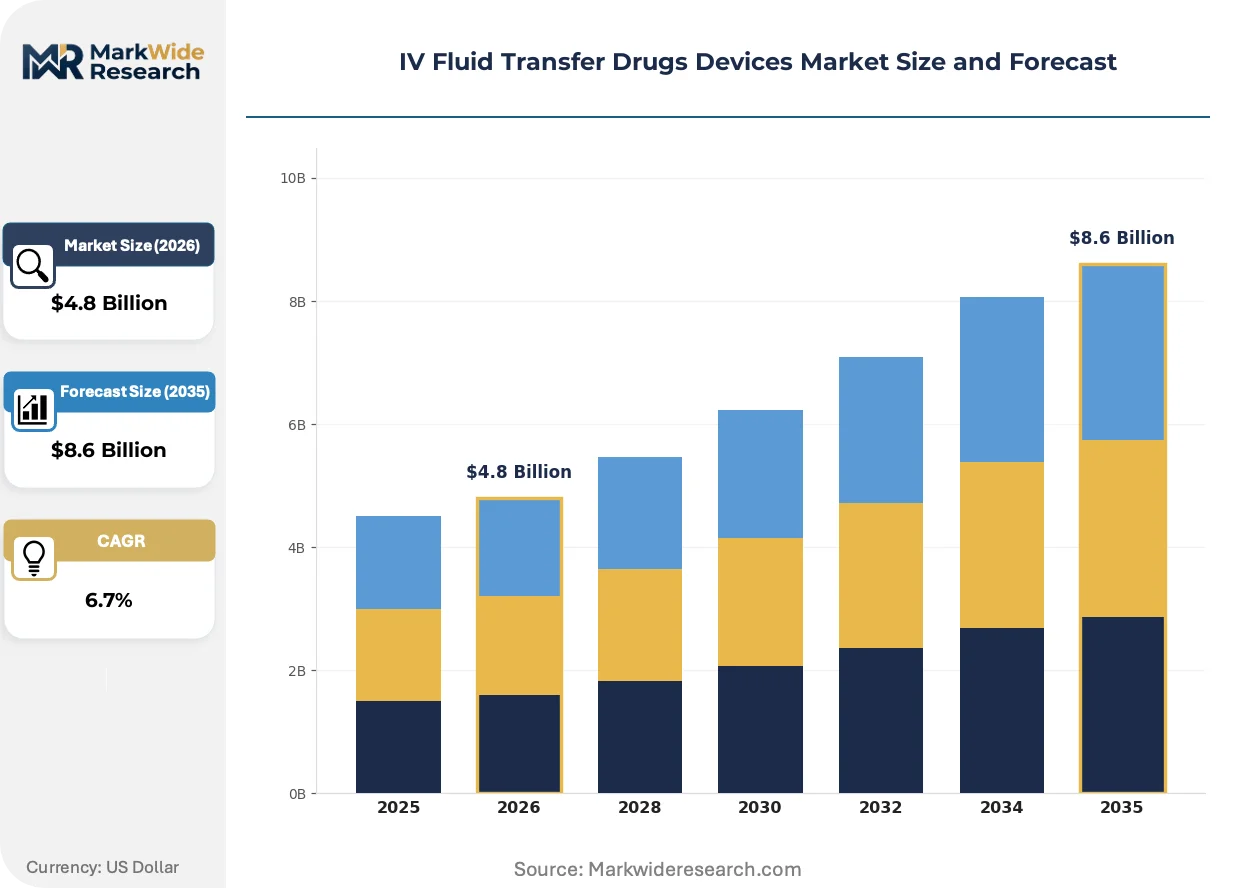
Market Dynamics
Smart infusion systems with wireless EHR integration are restructuring hospital procurement priorities and compressing replacement cycles for legacy gravity sets across acute care networks.
Growth Catalysts
- Ambulatory infusion expansion:Homecare services in Germany and Japan are scaling portable pump deployments for oncology and pain management, creating pull for lightweight, battery-operated transfer devices.
- FDA software validation mandates:Tighter guidance on infusion pump cybersecurity and dose-error reduction systems is forcing hospital upgrades and expanding the addressable base for compliant manufacturers.
- Needle-free connector adoption:Closed-system transfer devices with needle-free valve technology are displacing traditional spike connections in US oncology units to reduce clinician exposure and bloodstream infection risk.
Market Restraints
- Polymer input volatility:Medical-grade PVC and DEHP plasticizer supply disruptions from Asian petrochemical hubs are squeezing margins on disposable gravity sets and extension tubing.
- European MDR compliance costs:The EU Medical Device Regulation's clinical evidence requirements for Class IIa infusion devices are extending time-to-market and favoring incumbents with predicate device histories.
- Gravity set commoditization:Standard low-cost infusion sets face substitution pressure from integrated smart pump systems in tertiary hospitals, compressing pricing power in the high-volume segment.
Strategic Opportunities
- Underpenetrated homecare markets:Japan's aging demographic and reimbursement shifts toward outpatient parenteral antimicrobial therapy are opening demand for patient-operated infusion pumps with simplified transfer interfaces.
- ISO 80369-3 enteral convergence:Small-bore connector standardization across IV and enteral lines is enabling cross-platform device portfolios and reducing SKU complexity for manufacturers with unified design platforms.
- EU AI Act algorithmic compliance:Early alignment with forthcoming artificial intelligence liability frameworks for smart pump dose calculation modules will create competitive moats against late-adapting rivals.
Industry Challenges
- Biomedical engineering talent scarcity:Shortages of firmware developers with IEC 62304 medical software lifecycle expertise are delaying smart pump validation timelines and stretching R&D budgets.
- Legacy system integration friction:Hospital IT departments face complexity bridging proprietary pump telemetry protocols with existing electronic health record architectures, slowing wireless system rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IV Fluid Transfer Drugs Devices Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gravity Set, Infusion Pump, Syringe Pump, Flow Regulator End User: Hospitals, Clinics, Homecare, Long-term Care Facilities Technology: Mechanical, Electronic, Wireless, Smart Application: Hydration, Nutritional Support, Medication Administration, Blood Transfusion |
| Companies Covered | B. Braun Melsungen, Hospira, Becton, Dickinson and Company, Advance Medical Designs, Unilife Corporation, ICU Medical, CODAN Companies, Q.I. Medical, Baxter International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IV Fluid Transfer Drugs Devices Market Shifts & Advancements
Wireless-enabled infusion ecosystems are collapsing the boundary between device-level control and enterprise-wide medication management, forcing architectural decisions across hardware, software, and data infrastructure layers.
Closed-system drug transfer devices with integrated barrier technology are overtaking open spike-and-drip chamber configurations in US hospital pharmacy compounding and oncology administration. Acute care facilities are prioritizing these systems for hazardous drug handling to meet USP <800> containment requirements. The shift is compressing demand for conventional vented vial adapters and repositioning infection prevention as a procurement decision driver rather than secondary consideration.
The EU Medical Device Regulation's post-market surveillance requirements are extending clinical follow-up obligations for infusion pump manufacturers beyond traditional vigilance reporting. Device makers must now maintain active registries for software-upgradable systems and demonstrate real-world performance data to notified bodies. German and French hospital procurement consortiums are incorporating MDR compliance certification into tender evaluation criteria, disadvantaging non-EU suppliers without established European authorized representatives.
Hospital buying committees are consolidating infusion device contracts under single-source agreements that bundle pumps, sets, and software subscriptions. Group purchasing organizations in the United States are negotiating multi-year partnerships with integrated therapy providers, displacing fragmented procurement of gravity sets from secondary distributors. This concentration is most pronounced in IDN-affiliated facilities where standardization across member hospitals drives volume commitments and locks out standalone device vendors lacking full portfolio breadth.
IV Fluid Transfer Drugs Devices Market Segmentation
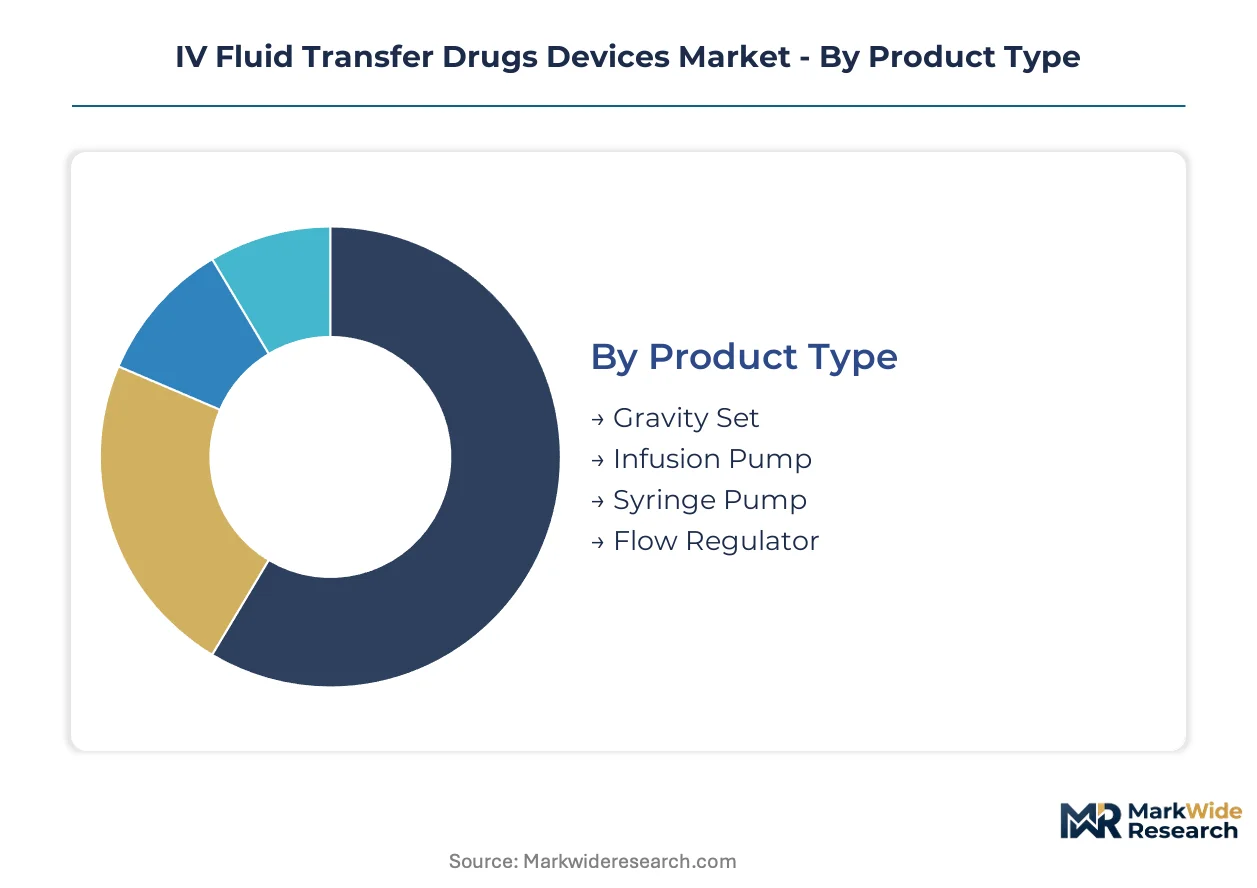
IV fluid transfer devices fragment across four intersecting dimensions that determine procurement logic: acute versus ambulatory care settings, standalone versus integrated technology architectures, mechanical versus electronic control mechanisms, and therapeutic application specificity. Understanding these segment boundaries clarifies why hospital buying committees now prioritize bundled smart pump contracts over discrete gravity set purchases.
Product Type:
Gravity sets function as standalone mechanical devices requiring no external power, while infusion pumps embed into centralized medication management ecosystems with software-dependent dosing protocols.
- Gravity Set:Disposable tubing assemblies utilizing hydrostatic pressure differential without electronic components. Demand concentrates in German and Japanese homecare networks where battery independence and cost minimization drive ambulatory therapy selection.
- Infusion Pump:Programmable electromechanical devices with dose-error reduction software and drug library integration. US hospital procurement committees prioritize these for oncology and critical care units under FDA software validation mandates.
- Syringe Pump:Precision piston-driven systems for low-volume high-accuracy delivery in neonatal and anesthesia applications.
- Flow Regulator:Mechanical dial-controlled devices bridging gravity and electronic functionality for intermediate-cost clinical settings.
Gravity sets lead volumes today; smart infusion pumps are gaining share fastest.
End User:
Customer type determines device complexity requirements, with acute facilities demanding enterprise integration and home settings prioritizing portability and error-proofing.
- Hospitals:Tertiary medical centers requiring centralized fleet management, wireless EHR connectivity, and FDA-compliant dose-error reduction systems for high-risk medication protocols.
- Clinics:Outpatient facilities balancing cost constraints against infection prevention needs, driving needle-free connector adoption in US oncology infusion centers.
- Homecare:Patient-operated settings in Japan and Germany where lightweight battery-operated pumps with simplified interfaces serve aging demographics receiving outpatient parenteral therapy.
- Long-term Care Facilities:Skilled nursing environments with limited biomedical engineering support favoring robust mechanical devices over software-dependent systems.
Hospitals dominate absolute unit consumption; homecare demonstrates the steepest expansion trajectory.
Technology:
Technology tiers stratify by data connectivity depth, with mechanical systems operating in isolation and smart platforms feeding real-time telemetry into clinical decision support infrastructure.
- Mechanical:Passive pressure-driven systems without electronic components or data transmission capability, serving cost-constrained markets.
- Electronic:Microprocessor-controlled pumps with localized programming but no network connectivity, common in mid-tier hospital deployments.
- Wireless:Telemetry-enabled devices transmitting pump status to central monitoring stations, accelerating fastest in US integrated delivery networks.
- Smart:AI-augmented systems with predictive occlusion detection and automated drug library updates, subject to emerging EU AI Act algorithmic compliance requirements.
Mechanical technology anchors current installed base; smart systems climb the fastest among replacement purchases.
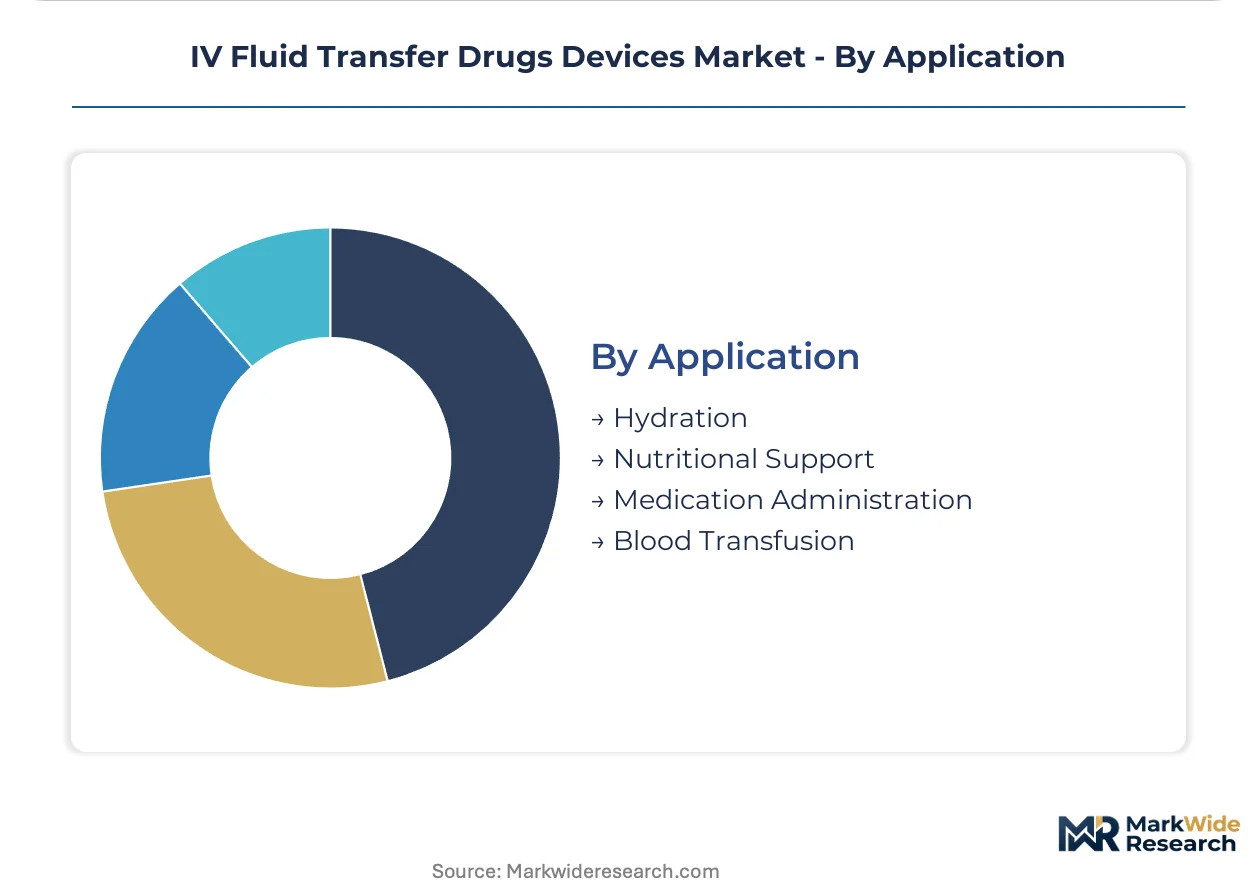
Application:
Therapeutic use case dictates flow rate precision requirements and contamination risk profiles, with hazardous drug handling demanding closed-system transfer architectures.
- Hydration:High-volume electrolyte replacement therapy utilizing standard gravity sets in emergency departments and ambulatory surgery centers.
- Nutritional Support:Enteral and parenteral feeding applications where ISO 80369-3 connector standardization enables cross-platform device portfolio consolidation.
- Medication Administration:Chemotherapy and antimicrobial delivery requiring needle-free closed-system transfer devices to meet USP 800 containment standards in US hospital pharmacies.
- Blood Transfusion:Specialized warming and filtration-integrated sets for hemovigilance compliance in transfusion services.
Medication administration commands premium pricing; nutritional support shows the strongest standardization tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing footprints as EU MDR compliance costs drive some producers toward US FDA pathways, while Asian hubs capture component sourcing for cost-constrained gravity set segments.
United States
Hospital procurement committees prioritize wireless EHR-integrated smart pumps under FDA's tightened software validation guidance. The FDA's dose-error reduction system mandates are accelerating replacement cycles for legacy devices. Boston and Minneapolis medical device clusters concentrate R&D for telemetry-enabled infusion ecosystems.
Germany
Ambulatory homecare expansion for oncology and pain management is scaling portable pump demand. The EU MDR's clinical evidence requirements for Class IIa devices favor domestic incumbents with predicate device histories. Melsungen anchors European gravity set supply through vertically integrated sterile manufacturing.
Japan
Aging demographics and reimbursement shifts toward outpatient parenteral antimicrobial therapy are opening patient-operated infusion pump demand. PMDA post-market surveillance aligns with MDR-equivalent vigilance standards. Tokyo-Osaka medical technology corridors concentrate development of simplified patient interfaces.
United Kingdom
NHS procurement consolidation favors single-source agreements bundling pumps, sets, and software subscriptions. MHRA recognition of EU MDR certificates temporarily eases market access post-Brexit. Cambridge and Oxfordshire clusters focus on AI-augmented dose calculation modules.
India
Cost-constrained clinics drive gravity set volume demand while tertiary hospitals pilot electronic pump adoption. CDSCO's medical device rules are tightening registration requirements for imported infusion systems. Hyderabad and Bengaluru emerging as contract manufacturing hubs for disposable tubing assemblies.
IV Fluid Transfer Drugs Devices Market Competitive Landscape
German producers anchor one tier through integrated sterile manufacturing; US specialists hold another via software-dependent smart pump ecosystems. The market stratifies into three tiers: full-portfolio integrated therapy providers, component-focused disposable manufacturers, and regional contract fabricators. Consolidation pressures intensify as hospital buying committees demand bundled contracts spanning hardware, consumables, and data infrastructure. Capacity expansion and strategic partnerships dominate competitive moves as firms seek MDR compliance scale and EHR integration capabilities.
Within the integrated therapy tier, Baxter International and B. Braun Melsungen exemplify full-portfolio positioning spanning pumps, sets, and fluid therapy systems. ICU Medical occupies a specialist position through proprietary valve technology. Among US-based innovators, Becton, Dickinson and Company represents the convergence of vascular access and infusion control architectures.
| Leading Market Players |
|---|
| B. Braun Melsungen |
| Hospira |
| Becton, Dickinson and Company |
| Advance Medical Designs |
| Unilife Corporation |
| ICU Medical |
| CODAN Companies |
| Q.I. Medical |
| Baxter International |
| Others |
Supply & Pricing Matrix
Family-owned German sterile device manufacturers anchor European gravity set supply through vertically integrated Melsungen production, translating captive polymer compounding capacity into pricing discipline that resists Asian import erosion despite DEHP plasticizer cost volatility.
Pricing Analysis
Distributor margins on disposable gravity sets compress under GPO consolidated procurement, while smart pump vendors command subscription-based recurring revenue through software licensing and drug library maintenance fees. Price differentiation hinges on FDA 510(k) clearance tier and ISO 80369-3 connector interoperability certification. Cost compression in mechanical sets intensifies as Indian contract manufacturers scale PVC tubing output for cost-constrained clinics. Homecare segments in Japan exhibit highest price sensitivity; US integrated delivery networks demonstrate lowest sensitivity due to bundled enterprise contracts.
Supply Chain Analysis
Refurbishment flows for infusion pump fleets concentrate through authorized service depots in Germany and the United States, extending asset lifecycles and creating secondary parts demand for legacy electronic components. Medical-grade PVC resin and DEHP plasticizer draw from South Korean and Chinese petrochemical hubs, tethering disposable set margins to Asian feedstock pricing. Single-source vulnerability in precision pump motor assemblies sourced from Japanese suppliers elevates supply risk. Distribution runs through hospital GPOs and specialty distributors serving ambulatory infusion centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR compliance costs for Class IIa device clinical evidence exceed US FDA 510(k) predicate pathways by substantial margins, creating geographic-arbitrage incentives for manufacturers prioritizing North American market entry over European expansion.
For Market Incumbents: Lock in hospital system partnerships through multi-year bundled contracts spanning pumps, sets, and software subscriptions before GPO consolidation displaces fragmented procurement channels. Expand sterile manufacturing capacity in Germany to defend against MDR compliance barriers favoring domestic incumbents with predicate device histories. Prioritize IEC 62304 firmware development talent acquisition to accelerate smart pump validation timelines threatened by biomedical engineering scarcity.
For New Entrants and Emerging Players: Capture Japan's patient-operated homecare pump segment where simplified interfaces for aging demographics remain underpenetrated by Western vendors. Target India's cost-constrained clinic gravity set demand through Hyderabad contract manufacturing partnerships. Pursue needle-free valve technology licensing from established suppliers to bypass proprietary IP barriers in US oncology unit procurement.
For Investors and Strategic Acquirers: Valuations sit cheapest among component-focused disposable manufacturers facing gravity set commoditization pressure from integrated smart pump ecosystems. Five-to-ten year viability favors targets with established EU authorized representative infrastructure and MDR technical documentation portfolios. Monitor FDA software validation guidance enforcement intensity as inflection indicator for hospital replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software Validation Pathway | Accelerates hospital upgrade cycles under tightened cybersecurity and dose-error reduction mandates. |
| CE Marking Pathway | Secures EU MDR compliance for Class IIa infusion devices through notified body clinical evidence review. |
| Hospital System Partnership | Locks multi-year volume commitments through integrated delivery network standardization programs. |
| Software Companion Development | Enables wireless EHR integration and drug library telemetry for smart pump ecosystem positioning. |
| Reimbursement Strategy | Aligns device pricing with CMS Medicare outpatient parenteral antimicrobial therapy coverage expansion. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and infusion pharmacy supervisors with secondary validation against FDA 510(k) filings, EU MDR notified body certificates, hospital procurement databases, and CMS Medicare reimbursement schedules. Bottom-up device shipment modeling triangulated against top-down therapy expenditure estimates.
Segment-weighting applied product type, end user, technology tier, and therapeutic application dimensions across the analysis window. CAGRs derived from installed base replacement cycle analysis, ambulatory expansion trajectories, and software-enabled upgrade penetration curves. Forecast inputs incorporated FDA guidance enforcement timelines and EU AI Act algorithmic compliance cost projections.
Regulatory enforcement delays, polymer supply disruption severity, and hospital IT integration friction are the dominant revision risks. Forecasts reflect assumptions regarding MDR transition completion and smart pump wireless adoption curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Endometrial Ablation Devices Market
Medical Devices
Arthroscopy Devices Market
Medical Devices
Gamma Knife Market
Medical Devices
At-Home Blood Collection Kits and Devices Market
Medical Devices
Varicose Vein Treatment Devices Market
Medical Devices
North America Refractive Surgery Devices Market
Medical Devices
Non-Invasive Glucose Monitoring Devices Market
Medical Devices
Global Artificial Skin Market
Medical Devices
Europe Electroencephalography Devices Market
Medical Devices
Inhaled Corticosteroid Device Market
Medical Devices
Australia Ultrasound Devices Market
Medical Devices
Large Volume Nebulizers Market
Medical Devices
Spain Respiratory Devices Market
Medical Devices
Gel Implants Market
Medical Devices
T-Piece Resuscitator Market
Medical Devices
Medical Device Tester Market