
 Water Flosser Market | 2026-2036
Water Flosser Market Size, Share, and Industry Trends Forecast 2026-2036
Water Flosser Market Intelligence
The proliferation of asset-light, direct-to-consumer business models is fragmenting the established market structure. This shift allows newer entrants to challenge incumbents without massive capital outlay for physical retail channels. Waterpik sustains its leadership through strong brand recognition and clinical validation. Meanwhile, Burst Oral Care competes effectively using a subscription-based sales model, while Procter & Gamble leverages its vast distribution network for its Oral-B brand.
A water flosser is an oral hygiene device that directs a stream of high-pressure, pulsating water between teeth and along the gumline. These devices typically feature adjustable pressure settings ranging from 10 to 100 PSI to dislodge food particles and plaque. While Countertop models lead in power and water capacity, the Cordless segment is expanding most rapidly due to convenience. Technology is also evolving, with advanced Ultrasonic systems offering improved cleaning efficiency over traditional Pulsating mechanisms.
Product safety and performance standards are governed by multiple international bodies. In the United States, the FDA regulates these devices, while CE marking under the Medical Device Regulation (MDR) is mandatory for access to the European market. Similarly, China’s NMPA imposes its own stringent approval processes. Navigating these varied regulatory requirements for materials and electrical safety is critical for companies aiming for market share across different regions.
Market Dynamics
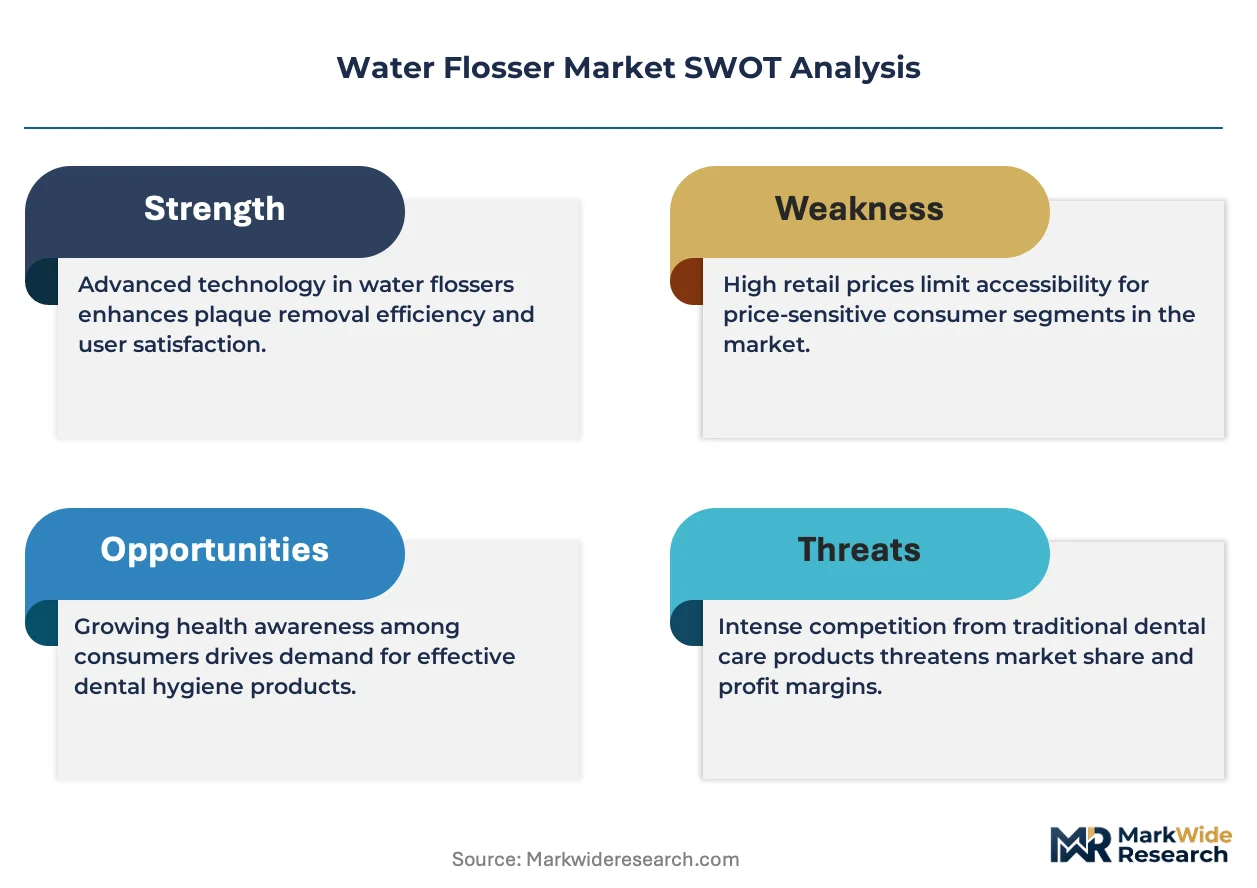
The central tension in the water flosser market arises from the convergence of consumer electronics and medical devices. Manufacturers must navigate dual compliance frameworks, satisfying FDA and NMPA medical device safety standards while integrating consumer-tech features that trigger data privacy obligations under GDPR or HIPAA.
Growth Catalysts
- Clinical Endorsement:Growing recommendations from dental associations and practitioners for managing gingivitis and periodontal disease are driving patient-led demand for professional-grade water flossers.
- E-commerce Expansion:The rise of direct-to-consumer and marketplace platforms in populous markets like India and Brazil provides new brands with low-cost channels to reach a wide consumer base.
- Preventive Healthcare Focus:Public health campaigns and insurance incentives in countries like Germany and Japan that promote oral hygiene as essential for overall health stimulate consumer interest and adoption.
Market Restraints
- Substitution by Traditional Methods:Strong consumer habits and the perceived lower cost of traditional string floss and interdental brushes remain a significant barrier to adoption, particularly in price-sensitive segments.
- Regulatory Compliance Costs:Securing market access requires navigating expensive and lengthy approval processes, such as FDA 510(k) clearance in the US and CE marking under the MDR in Europe.
- Device Maintenance Requirements:The need for regular descaling in hard water regions to prevent mineral buildup and maintain performance can be a deterrent for users seeking low-maintenance hygiene solutions.
Strategic Opportunities
- Teledentistry Integration:Developing smart devices with sensor technology that syncs with teledentistry platforms, enabling remote monitoring and personalized feedback from dental professionals.
- Geriatric and Assisted Living:Designing ergonomic, easy-to-handle cordless models specifically for the aging population and residents of care facilities, a key demographic in Japan and parts of Europe.
- Specialized Solution Formulations:Collaborating with oral care companies to create and co-market therapeutic additives for reservoirs, such as antiseptic or anti-inflammatory rinses, for targeted treatments.
Industry Challenges
- Counterfeit Product Proliferation:The influx of uncertified and counterfeit water flossers on major online marketplaces jeopardizes consumer safety, damages brand reputation, and creates pricing pressure.
- Component Supply Chain Risks:Dependence on a concentrated number of suppliers for critical components like specialized micro-pumps and rechargeable batteries creates vulnerability to geopolitical and logistical disruptions.
- Consumer Education on Efficacy:A persistent challenge is educating consumers on the proper technique, pressure settings, and distinct benefits of water flossing compared to traditional methods to ensure effective use and satisfaction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Flosser Market |
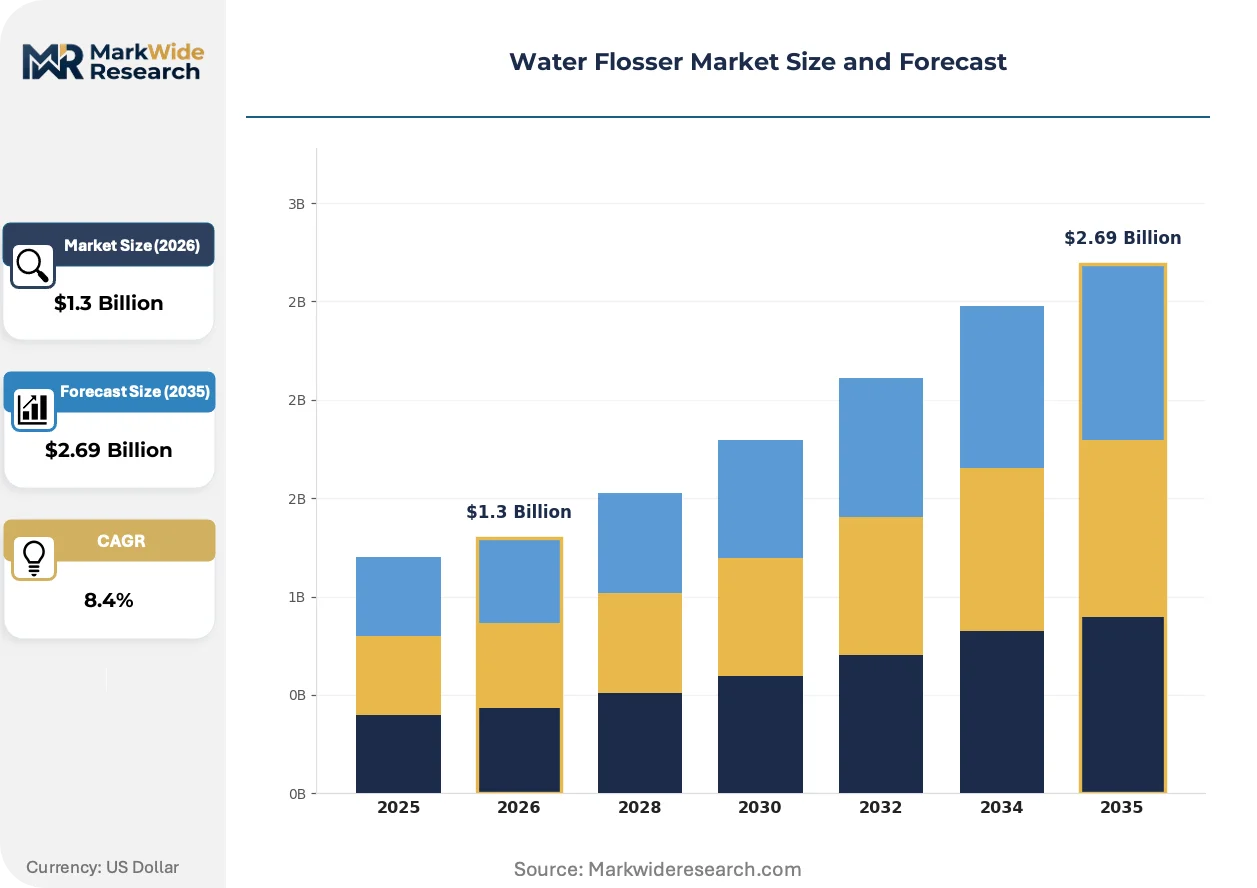
| Market Size in 2026 | $1.3 Billion |
| Market Size in 2035 | $2.69 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop, Cordless, Portable, Shower Technology: Pulsating, Continuous, Pressure Control, Ultrasonic End User: Households, Dental Practices, Clinics, Hotels Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Direct Sales |
| Companies Covered | Procter & Gamble, Church & Dwight, Waterpik, Burst Oral Care, Colgate-Palmolive, Koninklijke Philips N.V., MySmile, Hydro Floss, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Flosser Market Strategic Shifts & Innovations
The market's product trajectory is defined by the fusion of digital health monitoring with daily oral hygiene. This evolution is transforming the water flosser from a standalone mechanical tool into an interactive data-gathering device within a connected personal wellness ecosystem.
Smart sensors and Bluetooth connectivity are increasingly integrated into premium water flossers to track coverage, duration, and pressure. Patients undergoing orthodontic treatment and health-conscious consumers are the earliest adopters of these connected models. This embedded technology is virtualizing the user's hygiene routine, generating a digital log that dental professionals can analyze to provide tailored advice and monitor treatment compliance remotely.
Europe's Medical Device Regulation (MDR) establishes more rigorous requirements for clinical evidence and post-market surveillance. This regulation compels manufacturers to implement robust systems for collecting and analyzing real-world performance data throughout a product's lifecycle to maintain their CE marking. The cordless device segment, with its complex battery and power management systems, faces heightened scrutiny regarding long-term electrical safety and performance consistency.
Subscription-based business models for delivering replacement nozzles and even the devices themselves are gaining momentum. This approach directly challenges the conventional one-time purchase model dominant in brick-and-mortar retail channels like drugstores and mass-market merchandisers. The trend is most visible in North America and Western Europe, where direct-to-consumer brands leverage it to build customer loyalty and a predictable recurring revenue stream.
Water Flosser Market Segmentation
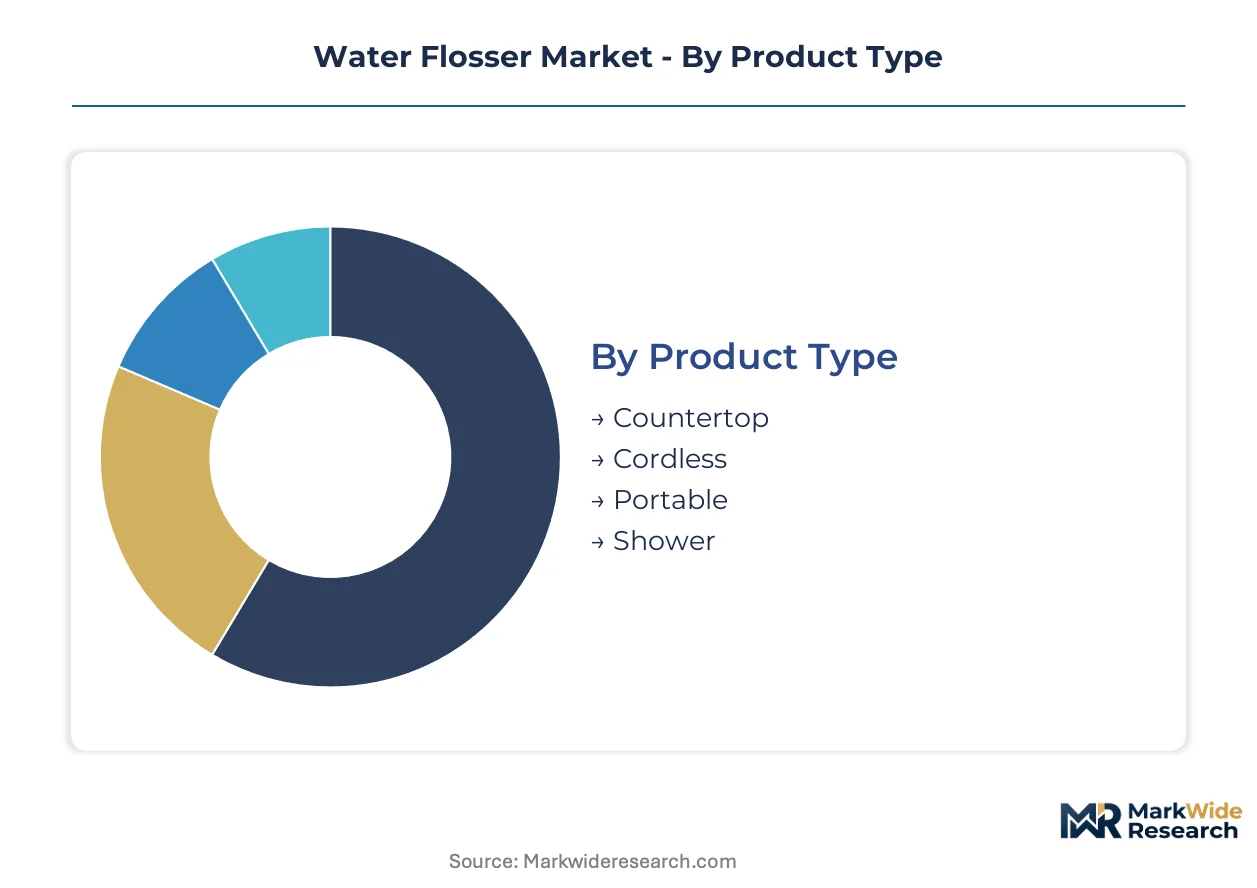
The water flosser market comprises distinct segments, each exhibiting unique characteristics in product design, technological sophistication, end-user applications, and distribution pathways. Understanding these segment dynamics is crucial for manufacturers to tailor product development and market penetration strategies effectively.
Product Type:
The product type segment illustrates the varying maturity levels and consumer preferences across device form factors.
- Cordless:These compact, battery-operated devices offer enhanced portability and ease of use, making them ideal for travel and smaller bathrooms. Demand concentrates in densely populated urban centers like Tokyo and New York, driven by convenience-seeking consumers and mobile lifestyles.
- Countertop:Larger units typically powered by an electrical outlet, offering superior water capacity and a wider range of pressure settings. Demand is robust in established markets such as Germany and Canada, where households prioritize consistent performance and advanced features for daily oral care routines.
- Portable:Smaller, travel-friendly versions designed for occasional use away from home, often with limited water reservoir capacity. These devices cater to business travelers and vacationers seeking to maintain their oral hygiene regimen on the go.
- Shower:Devices designed for use within the shower, leveraging existing water pressure and offering convenience by integrating into the showering routine. This niche segment appeals to users seeking to streamline their daily hygiene practices.
Countertop models retain volume leadership; Cordless products hold the steepest expansion curve.
Technology:
This category highlights the performance characteristics and cleaning mechanisms integrated into water flosser devices.
- Ultrasonic:Utilizes high-frequency vibrations to create microbubbles that enhance cleaning efficacy, dislodging plaque and bacteria from hard-to-reach areas. This advanced technology sees strong adoption in dental clinics across South Korea and France, where practitioners prioritize superior patient outcomes.
- Pulsating:Employs a rapid, intermittent stream of water to massage gums and remove food particles, representing the traditional and widely adopted mechanism. Consumer demand remains high in price-sensitive markets like India and Brazil, valuing effective yet accessible oral care solutions.
- Continuous:Delivers a steady stream of water, providing a gentler cleaning experience suitable for individuals with sensitive gums or specific dental conditions. This technology is often found in entry-level models, appealing to new users of water flossers.
- Pressure Control:Features adjustable settings that allow users to customize the water pressure, accommodating varying sensitivities and cleaning needs. This functionality is standard in mid-to-high-end devices, enhancing user comfort and effectiveness.
Pulsating technology captures significant market share; Ultrasonic innovations are gaining traction rapidly.
End User:
This segmentation reflects the primary consumer groups and institutional buyers driving demand for water flosser products.
- Households:Individual consumers and families purchasing water flossers for personal oral hygiene routines within their homes. This segment represents the largest volume contributor in countries like the United States and the United Kingdom, driven by general health awareness.
- Dental Practices:Professional dental clinics and orthodontist offices utilizing medical-grade water flossers for patient treatment, education, and pre-procedure cleaning. Demand is growing in nations with advanced dental care infrastructure, such as Australia and Switzerland, for specialized applications.
- Clinics:Medical and healthcare clinics, including periodontology and oral surgery centers, employing water flossers as part of comprehensive patient care plans. These institutions require devices that meet stringent hygiene and performance standards.
- Hotels:Hospitality establishments offering water flossers as an amenity in premium guest rooms or health spas to enhance the guest experience. This segment focuses on user-friendly and aesthetically pleasing designs.
Households represent the largest user base; Dental Practices exhibit robust demand for specialized units.
Distribution Channel:
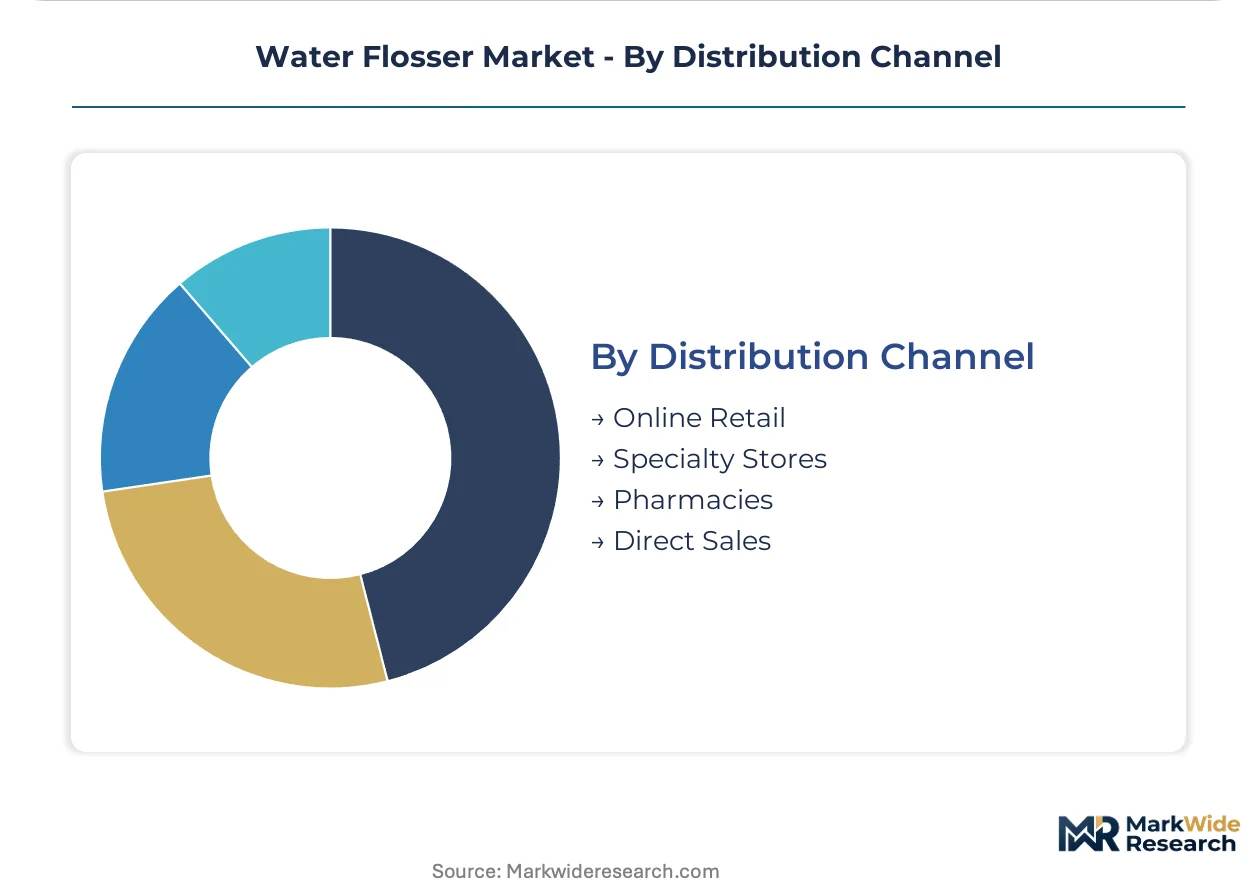
This category outlines the various avenues through which water flosser products reach their end consumers.
- Online Retail:Sales conducted through e-commerce platforms, brand websites, and digital marketplaces, offering broad product selection and direct-to-consumer models. This channel dominates in digitally mature economies like China and South Korea, facilitating convenient purchasing.
- Pharmacies:Retail outlets specializing in health and wellness products, including over-the-counter oral care devices, often with professional advice available. This channel remains significant in European countries such as Italy and Spain, benefiting from consumer trust in pharmacists.
- Specialty Stores:Retailers focusing exclusively on health, beauty, or dental care products, providing curated selections and expert guidance. These stores cater to consumers seeking high-end or niche oral hygiene solutions.
- Direct Sales:Products sold directly by manufacturers to consumers, often through subscription models or dedicated sales representatives. This channel allows for direct customer engagement and personalized service.
Online Retail channels are expanding quickly; Pharmacies maintain a steady presence for consumer access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The water flosser market exhibits varied regional dynamics, reflecting diverse consumer preferences and regulatory landscapes. This creates a complex export-import balance, with certain nations driving innovation and others absorbing established product lines. Manufacturing capabilities often concentrate in specific geographies, influencing global supply chains.
China
China's water flosser demand stems from a growing middle class prioritizing personal health. The NMPA imposes stringent approval processes for medical devices, ensuring product quality. Shenzhen, a major manufacturing hub, sees significant production and export of these devices.
Germany
Germany's market for water flossers benefits from established oral care routines and a focus on consistent performance. CE marking under the Medical Device Regulation (MDR) is mandatory for market access. Bavaria, a region known for medical technology, fosters innovation in advanced oral hygiene solutions.
United States
United States households are significant consumers, driven by general health awareness and clinical endorsements. The FDA regulates these devices, ensuring safety and efficacy standards. California, particularly its tech-centric regions, sees early adoption of connected smart water flossers.
Japan
Japan's aging population and strong preventive healthcare focus stimulate demand for ergonomic water flossers. METI guidelines influence product safety and electrical standards for consumer devices. Tokyo, a densely populated urban center, leads in adopting portable and advanced models.
India
India's market expansion is fueled by e-commerce platforms reaching a wide consumer base in price-sensitive segments. BIS standards for consumer goods apply to these devices, ensuring quality. Bangalore, a hub for digital innovation, is seeing growth in online sales channels for oral care products.
Water Flosser Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, where established oral care giants coexist with agile direct-to-consumer entrants. This dynamic creates distinct competitive archetypes: long-standing incumbents, innovative D2C specialists, and diversified consumer electronics companies. Dominant competitive moves include leveraging extensive distribution networks for widespread market penetration and establishing subscription-based sales models to build customer loyalty and predictable revenue streams.
Within this competitive arena, established brands like Waterpik exemplify leadership through strong brand recognition and clinical validation, particularly in professional dental channels. Burst Oral Care represents the disruptive force of direct-to-consumer models, effectively utilizing subscription-based sales to capture market share among younger, tech-savvy consumers. Procter & Gamble, with its Oral-B brand, occupies a position of strength, leveraging its vast distribution network to reach a broad consumer base across various retail channels, from traditional pharmacies to large mass merchandisers globally.
| Leading Market Players |
|---|
| Procter & Gamble |
| Church & Dwight |
| Waterpik |
| Burst Oral Care |
| Colgate-Palmolive |
| Koninklijke Philips N.V. |
| MySmile |
| Hydro Floss |
| Panasonic Corporation |
| Others |
Cost & Logistics Intelligence
Overcapacity in key manufacturing hubs like Shenzhen influences supplier behavior and pricing posture across the water flosser market. This dynamic creates competitive pressure on product margins.
Pricing Analysis
Industrial OEM buyers anchor per-unit transactional pricing for core components like micro-pumps. Price differentiation stems from ultrasonic technology integration and stringent regulatory compliance like CE marking. Pricing softness reflects intense competition from counterfeit products on online marketplaces. Households exhibit high price sensitivity, contrasting with dental practices that prioritize performance and clinical validation.
Supply Chain Analysis
Component supply chain risks due to concentrated micro-pump and rechargeable battery suppliers dominate the water flosser market. Manufacturing primarily centers in China, especially Shenzhen, which sources specialized plastics globally. This reliance on a few key component providers creates vulnerability to logistical disruptions. Distribution runs through online retail platforms and traditional pharmacies, adapting to regional purchasing habits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The water flosser market presents an early-cycle expansion story, driven by a growing focus on preventive healthcare and overall oral hygiene. This shift stimulates consumer interest and adoption across diverse demographics.
For Market Incumbents: Pre-empt market share erosion from agile D2C entrants by accelerating investment in smart device R&D. Strengthen clinical validation for advanced ultrasonic systems to differentiate against lower-cost alternatives. Reinforce brand reputation through rigorous quality control to combat counterfeit product proliferation. Leverage existing distribution networks in pharmacies for wider market penetration.
For New Entrants and Emerging Players: Build out niche product lines targeting underserved segments like geriatric populations with ergonomic cordless models. Integrate sensor technology with teledentistry platforms to offer personalized oral care feedback. The cordless segment in urban centers represents a penetrable market due to convenience-seeking consumers. Utilize subscription-based models for device and nozzle delivery to establish recurring revenue streams.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across the smart water flosser sub-segment, signaling long-term value creation. The market's viability is robust, supported by sustained public health campaigns promoting oral hygiene. Target acquisition archetypes include innovative D2C brands with strong subscription bases or specialized sensor technology developers. Watch for increased FDA or NMPA classification of smart devices as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Teledentistry Platform Integration | Enhances remote monitoring capabilities and personalized patient care. |
| Ergonomic Cordless Model Development | Caters to the aging population and improves user accessibility. |
| Therapeutic Additive Collaborations | Creates co-marketed solutions for targeted oral health treatments. |
| Advanced Ultrasonic R&D Investment | Drives product differentiation and superior cleaning efficacy. |
| Subscription Service Expansion | Builds customer loyalty and establishes predictable revenue streams. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted, combining primary interviews with extensive secondary validation. Stakeholders included dental hygienists, product development engineers, retail procurement managers, and direct-to-consumer brand founders. Secondary data sources comprised NMPA approval records, European MDR guidelines, and e-commerce platform sales analytics. Bottom-up and top-down triangulation ensured data integrity across the analysis.
The calibration approach involved assessing historical market growth rates and correlating them with macroeconomic indicators over the projection horizon. Segmentation dimensions modeled included product type, cleaning technology, end-user demographics, and distribution pathways. Compound Annual Growth Rates were derived from an assessment of market drivers and restraints. Key forecast inputs included consumer discretionary spending on health and dental professional recommendations.
The forecast holds incumbent behavior within observed patterns; aggressive moves by D2C disruptors or major consumer electronics firms would shift outcomes. Assumptions reflect current regulatory landscapes and component supply chain stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Smart Lenses Market
Medical Devices
Plethysmograph Market
Medical Devices
Refurbished Medical Devices Market
Medical Devices
Dynamic Spinal Tethering Systems Market
Medical Devices
Steroid Releasing Implant Market
Medical Devices
Global Ligation Devices Market
Medical Devices
Electrophysiology Market
Medical Devices
Smart Wheelchairs Market
Medical Devices
Germany Spinal Surgery Devices Market
Medical Devices
Breast Cancer Core Needle Biopsy Market
Medical Devices
Pannus Retraction Device Market
Medical Devices
Nerve Monitoring Devices Market
Medical Devices
Surgical Mesh Market
Medical Devices
Vaginal Specula Market
Medical Devices
Global Trauma Fixation Devices Market
Medical Devices
Internal Nasal Dilators Market