
 United States Idiopathic Pulmonary Fibrosis Treatment Market | 2026-2036
United States Idiopathic Pulmonary Fibrosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
United States Idiopathic Pulmonary Fibrosis Treatment Market Intelligence
Risk-sharing arrangements and outcomes-based contracting is narrowing the field of competitors with sufficient balance-sheet depth to participate in US payer negotiations. Boehringer Ingelheim leverages its established pulmonology infrastructure to sustain reimbursement relationships with integrated delivery networks. Roche differentiates through biomarker-linked companion diagnostic strategies that anchor precision positioning in academic medical centers. United Therapeutics competes through vertical control of its specialty pharmacy distribution channel.
Idiopathic Pulmonary Fibrosis Treatment encompasses pharmaceutical and supportive interventions targeting progressive, irreversible scarring of lung parenchyma of unknown etiology, with antifibrotic agents such as nintedanib and pirfenidone functioning as tyrosine kinase inhibitors that slow forced vital capacity decline by approximately 50% annually versus placebo. The primary purpose centers on delaying disease progression, reducing acute exacerbation frequency, and preserving quality of life in a patient population with median survival of three to five years without intervention. Antifibrotic Agents dominate current prescribing patterns and capture the majority of commercial value, while Oxygen Therapy represents a mature, lower-margin segment with stable replacement demand. The Oral administration route leads in patient preference and pharmacy benefit design, though Intravenous delivery occupies critical positioning in acute exacerbation protocols where hospital reimbursement structures favor infused therapy.
FDA orphan drug exclusivity provisions and breakthrough therapy designation pathways accelerate review timelines and extend market protection for novel IPF mechanisms, directly shaping portfolio prioritization decisions among developers. The Department of Health and Human Services Medicare coverage determinations and Medicaid best-price calculations constrain pricing flexibility and demand sophisticated value demonstration through forced vital capacity endpoint data. Stakeholders must monitor evolving FDA guidance on surrogate endpoint acceptability and CMS innovation center payment models for chronic disease management to anticipate competitive access dynamics.
Market Dynamics
Specialty pharmacy consolidation and FDA orphan drug exclusivity provisions are restructuring competitive access dynamics, concentrating distribution control among vertically integrated players while accelerating development timelines for novel antifibrotic mechanisms.
Growth Catalysts
- Orphan Drug Incentives:FDA exclusivity provisions and tax credits for rare disease development reduce clinical trial cost burdens and extend market protection periods for novel IPF therapies, incentivizing pipeline investment.
- Biomarker-Linked Diagnostics:Precision medicine infrastructure in academic medical centers enables patient stratification and targeted therapy selection, expanding addressable populations for antifibrotic agents.
- Integrated Delivery Networks:Hospital system consolidation across the Northeast and California creates concentrated prescribing channels that streamline formulary placement and patient access programs.
Market Restraints
- Reimbursement Compression:Medicare coverage determinations and Medicaid best-price calculations constrain pricing flexibility, forcing manufacturers to demonstrate value through forced vital capacity endpoint data.
- Clinical Trial Complexity:The progressive, irreversible nature of IPF pathology requires extended observation periods and large patient cohorts, elevating development costs and failure risks.
- Generic Substitution Pressure:Patent cliffs on established antifibrotic agents expose originators to biosimilar competition, eroding margin structures in the oral administration segment.
Strategic Opportunities
- Combination Therapy Protocols:Emerging research on nintedanib-pirfenidone sequencing creates white space for developers with dual-mechanism portfolios or licensing arrangements.
- Acute Exacerbation Management:Intravenous delivery protocols for hospitalized patients remain underdeveloped relative to outpatient oral therapy, presenting channel expansion potential.
- Real-World Evidence Programs:CMS innovation center payment models for chronic disease management reward outcomes data collection, enabling risk-sharing arrangements with payers.
Industry Challenges
- Specialized Pulmonology Workforce:Interstitial lung disease expertise concentrates in tertiary referral centers, limiting community-based diagnosis and treatment initiation.
- Companion Diagnostic Integration:Biomarker assay standardization across laboratory networks creates friction in precision positioning strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Idiopathic Pulmonary Fibrosis Treatment Market |
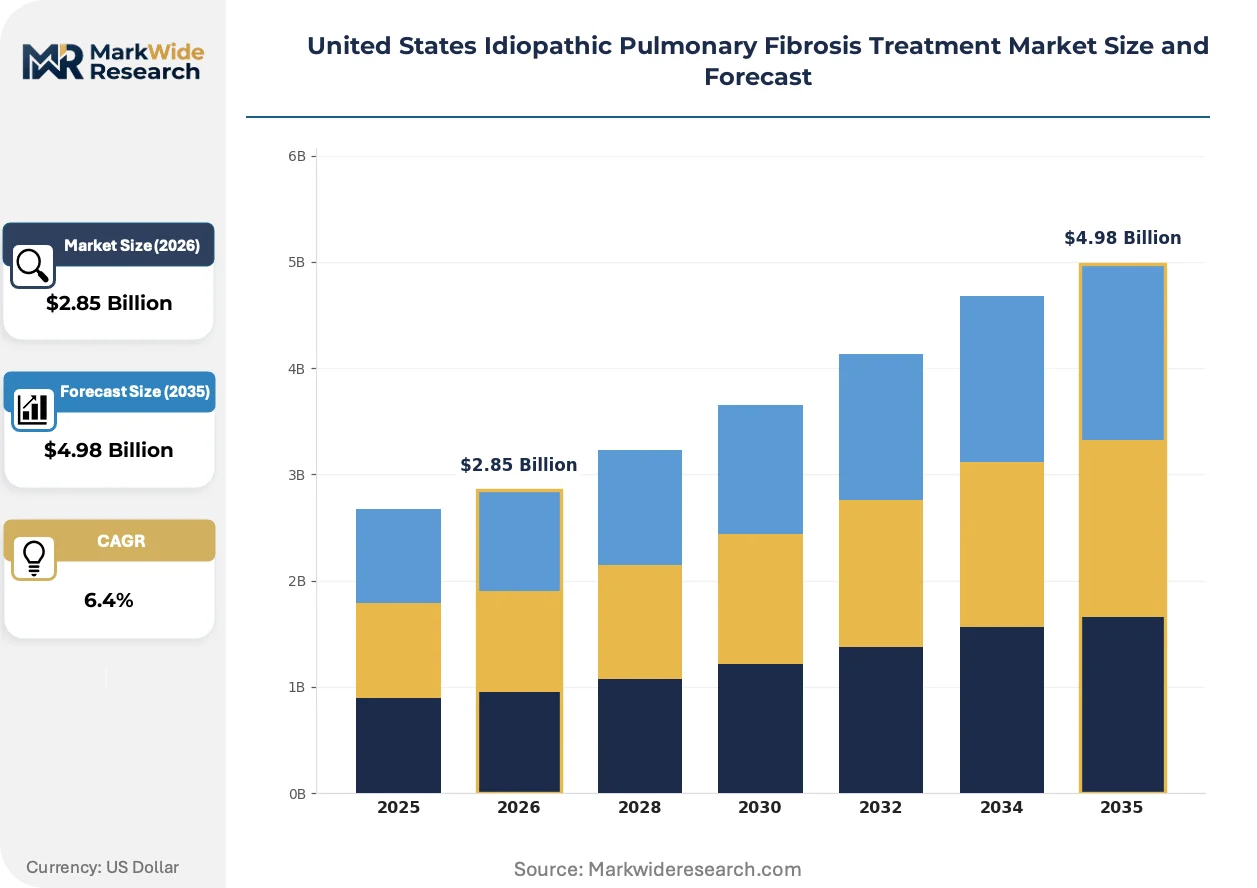
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $4.98 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antifibrotic Agents, Corticosteroids, Immune Modulators, Oxygen Therapy Indication: Acute Exacerbation, Progressive Fibrosis, Chronic Inflammation, Symptomatic Relief Administration Route: Oral, Intravenous, Inhalation, Subcutaneous End User: Hospitals, Clinics, Home Care, Specialty Pharmacies |
| Companies Covered | Boehringer Ingelheim, Roche, FibroGen, United Therapeutics, Pliant Therapeutics, Galapagos NV, Horizon Therapeutics, Bristol-Myers Squibb, Vicore Pharma, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Idiopathic Pulmonary Fibrosis Treatment Market Strategic Shifts & Innovations
Antifibrotic therapy development is pivoting toward mechanism diversification and delivery innovation, with digital biomarkers and remote monitoring compressing traditional clinical endpoint timelines.
Machine learning algorithms applied to high-resolution CT pattern recognition are collapsing the diagnostic pathway from symptom onset to treatment initiation. Community pulmonology practices in Texas and Florida are deploying FDA-cleared software for automated fibrosis quantification. This compression eliminates the referral bottleneck to academic centers and expands the prescriber base beyond ILD specialists.
The FDA's breakthrough therapy designation pathway is compressing review timelines for novel IPF mechanisms with surrogate endpoint packages. Developers with forced vital capacity or quantitative lung fibrosis data are securing priority review vouchers and accelerated approval pathways. Academic medical centers in Massachusetts and Pennsylvania are adapting their clinical trial infrastructure to accommodate compressed enrollment and data lock timelines.
Patient adherence programs are migrating from pharmacy call centers to mobile-enabled digital therapeutics platforms. Specialty pharmacies in California are unbundling traditional dispensing services from coaching and monitoring functions. This channel disintermediation is most visible in Medicare Advantage populations where star rating incentives reward sustained medication possession ratios.
United States Idiopathic Pulmonary Fibrosis Treatment Market Segmentation
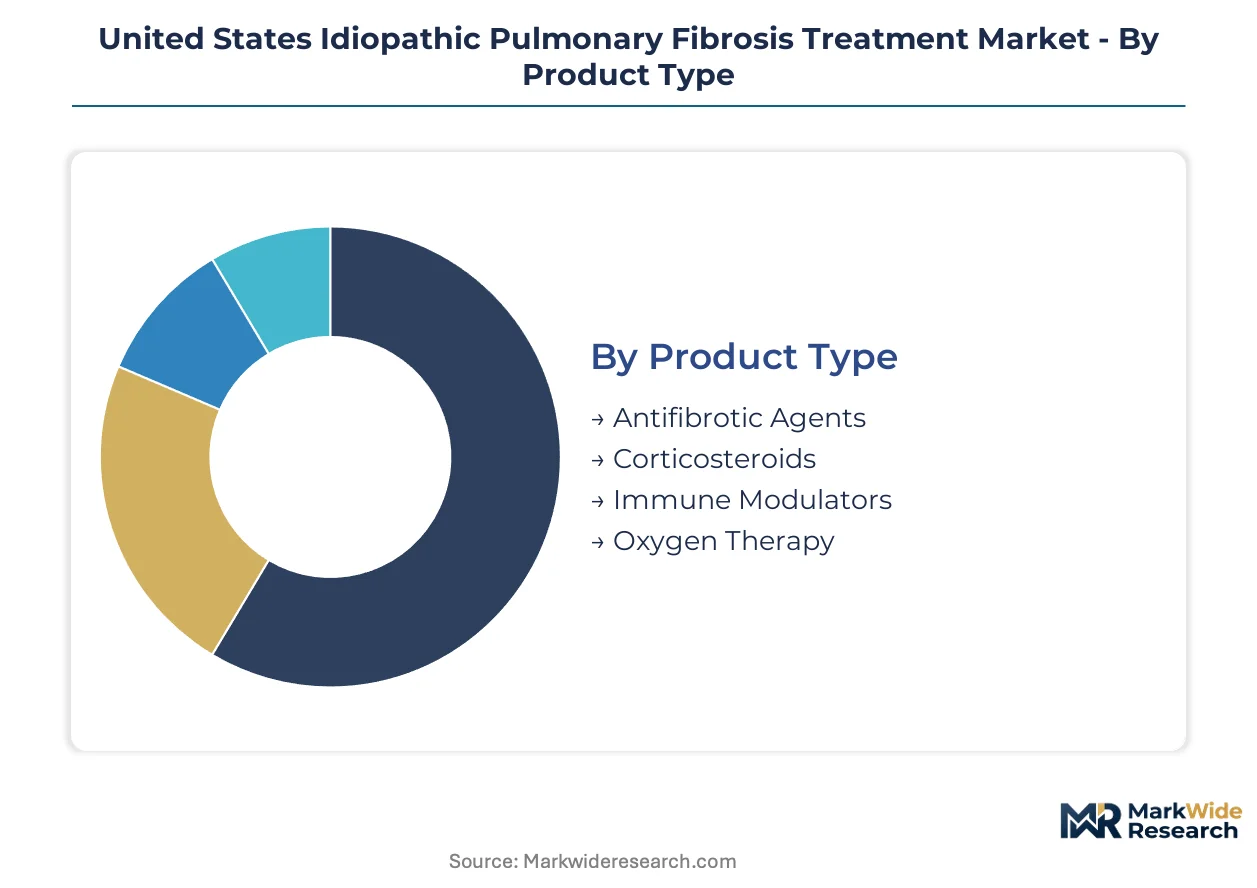
Segmentation in the United States Idiopathic Pulmonary Fibrosis Treatment Market reveals distinct service intensity profiles across product and channel dimensions. After-sales monitoring requirements vary dramatically between chronic oral therapy management and acute hospital-based interventions.
Product Type:
After-sales service intensity peaks with antifibrotic agents requiring continuous patient monitoring and adherence coaching through specialty pharmacy networks.
- Antifibrotic Agents:Tyrosine kinase inhibitors including nintedanib and pirfenidone slow forced vital capacity decline by approximately half versus placebo. Northeast hospital clusters and California academic medical centers concentrate demand, driven by Medicare Advantage star rating programs that reward sustained medication possession ratios.
- Oxygen Therapy:Long-term supplemental oxygen delivery systems require equipment maintenance, tank replacement logistics, and respiratory therapist home visits. Stable replacement demand concentrates in Medicare fee-for-service populations across Florida and Texas, constrained by competitive bidding program pricing compression.
- Corticosteroids:Systemic anti-inflammatory protocols for acute exacerbation management carry intensive nursing support requirements during tapering regimens.
- Immune Modulators:Biologic agents targeting interstitial lung disease subsets demand specialized infusion center coordination and immunosuppression monitoring.
By volume, Oxygen Therapy leads. By growth pace, Antifibrotic Agents is ahead.
Indication:
Cost tier stratification separates high-acuity hospital episodes from lower-intensity chronic management protocols.
- Progressive Fibrosis:The core addressable population for antifibrotic therapy with documented forced vital capacity decline. Massachusetts and Pennsylvania academic centers drive protocol development, supported by FDA breakthrough therapy designation pathways that accelerate novel mechanism evaluation.
- Acute Exacerbation:Sudden respiratory decompensation requiring hospitalization and IV intervention carries the highest per-episode cost. California integrated delivery networks are piloting bundled payment models for these events, creating accountability for readmission reduction.
- Chronic Inflammation:Persistent immune-mediated parenchymal injury subsets targeted by emerging biologic modifiers.
- Symptomatic Relief:Palliative-focused interventions addressing cough and dyspnea without disease-modifying intent.
By patient count, Progressive Fibrosis dominates. By revenue per case, Acute Exacerbation commands premium positioning.
Administration Route:
Customer type differentiation separates self-administered outpatient therapy from facility-dependent acute care delivery.
- Oral:Self-administered capsules and tablets dominate patient preference and pharmacy benefit design. Texas and Florida community pulmonology practices are expanding prescribing authority through FDA-cleared diagnostic software that reduces referral bottlenecks to academic centers.
- Intravenous:Hospital reimbursement structures favor infused therapy for acute exacerbation protocols. Northeast tertiary centers maintain concentrated expertise, though access gaps persist in rural service areas.
- Inhalation:Aerosolized antifibrotic formulations under development target direct lung delivery with reduced systemic exposure.
- Subcutaneous:Emerging biologic agents explore patient-administered injection alternatives to infusion center dependency.
By prescription volume, Oral administration leads. By development pipeline activity, Inhalation formulations are expanding most quickly.
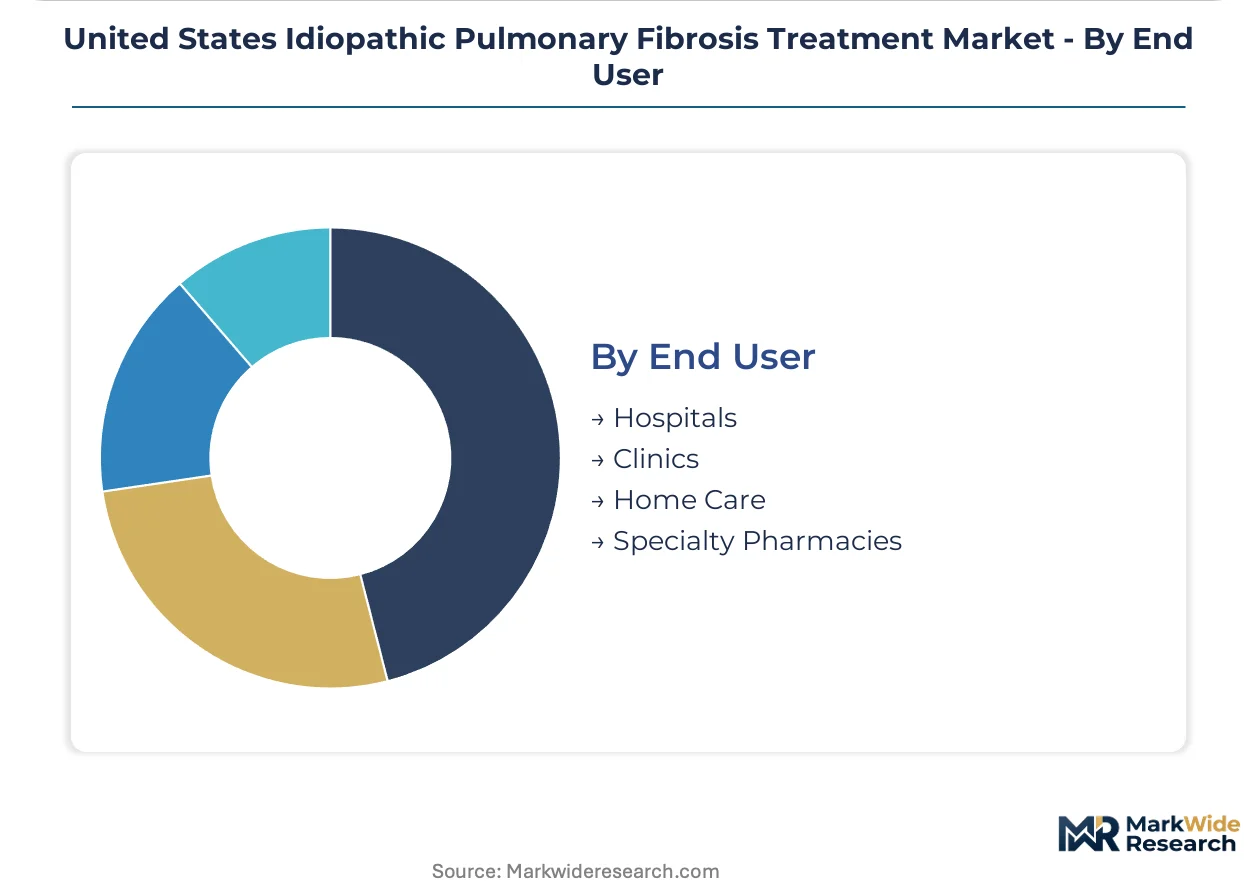
End User:
Supply concentration patterns channel product flow through vertically integrated specialty pharmacies and consolidated hospital systems.
- Specialty Pharmacies:Vertically controlled distribution networks anchor patient access and adherence programs. California-based operators are unbundling traditional dispensing from digital coaching services, creating new margin pools in Medicare Advantage populations.
- Hospitals:Integrated delivery networks across the Northeast and California concentrate formulary decision-making and clinical trial recruitment. CMS innovation center payment models for chronic disease management are reshaping procurement criteria toward outcomes demonstration.
- Clinics:Community pulmonology practices serve as diagnostic entry points with growing therapy initiation authority.
- Home Care:Oxygen therapy delivery and remote patient monitoring extend institutional protocols into residential settings.
By prescription fulfillment volume, Specialty Pharmacies lead. By strategic control over patient pathways, Hospitals are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains a net import position in specialized IPF therapeutics, with domestic production concentrated among a handful of vertically integrated manufacturers while diagnostic equipment and certain biologic inputs flow from European and Asian suppliers.
Northeast Corridor
Massachusetts and Pennsylvania academic medical centers anchor clinical trial recruitment and protocol development for novel antifibrotic mechanisms. FDA breakthrough therapy designation pathways accelerate review timelines for developers with forced vital capacity endpoint packages. Boston and Philadelphia hospital clusters concentrate Medicare Advantage enrollment and star rating program incentives that reward sustained medication possession ratios.
California
Integrated delivery networks across Los Angeles and San Francisco Bay Area pilot bundled payment models for acute exacerbation episodes. CMS innovation center payment models for chronic disease management reshape procurement criteria toward outcomes demonstration. Specialty pharmacy operators in San Diego unbundle traditional dispensing from digital coaching services, creating new margin pools in Medicare Advantage populations.
Texas
Community pulmonology practices in Houston and Dallas deploy FDA-cleared diagnostic software for automated fibrosis quantification, eliminating referral bottlenecks to academic centers. Stable replacement demand for long-term oxygen therapy concentrates in Medicare fee-for-service populations across the state, constrained by competitive bidding program pricing compression. Texas Medical Center anchors respiratory therapist training and home care logistics networks.
Florida
Medicare fee-for-service enrollment drives oxygen therapy equipment maintenance and tank replacement logistics across Miami and Tampa metropolitan areas. The state's pulmonology workforce distribution limits community-based diagnosis relative to Northeast benchmarks. Orlando and Jacksonville health systems expand telemedicine protocols to bridge access gaps for rural patients requiring antifibrotic therapy initiation.
Pacific Northwest
Seattle and Portland hospital systems concentrate biomarker-linked companion diagnostic strategies that anchor precision positioning in academic medical centers. Research collaborations between University of Washington and Oregon Health & Science University advance machine learning applications for high-resolution CT pattern recognition. The region's smaller patient populations limit commercial scale but attract early-phase clinical trial investment.
United States Idiopathic Pulmonary Fibrosis Treatment Market Key Industry Players
On the supply side, the industry is consolidating around vertically integrated players with sufficient balance-sheet depth to execute risk-sharing arrangements and outcomes-based contracting with US payers. Three strategic archetypes dominate: established pharmaceutical manufacturers leveraging pulmonology infrastructure, precision medicine specialists deploying biomarker-linked diagnostic strategies, and vertically controlled specialty pharmacy operators. M&A activity targets digital therapeutics platforms and companion diagnostic capabilities, while portfolio diversification into combination therapy protocols reshapes R&D prioritization.
Among established pharmaceutical manufacturers, Boehringer Ingelheim and Roche occupy positions representing contrasting strategic approaches to reimbursement relationship management and precision positioning. United Therapeutics exemplifies the vertically integrated archetype through captive specialty pharmacy distribution channel control. These three anchors illustrate the competitive tension between scale-driven formulary negotiation and targeted patient stratification strategies in concentrated hospital prescribing channels.
| Leading Market Players |
|---|
| Boehringer Ingelheim |
| Roche |
| FibroGen |
| United Therapeutics |
| Pliant Therapeutics |
| Galapagos NV |
| Horizon Therapeutics |
| Bristol-Myers Squibb |
| Vicore Pharma |
| Others |
Cost & Logistics Intelligence
Undercapacity in specialized biologic API manufacturing across the United States and Western Europe is tightening supplier leverage and compressing margin structures for originators negotiating with integrated delivery networks. This utilization squeeze propagates through antifibrotic agent pricing tiers and forces manufacturers toward captive production investments or long-term offtake commitments with contract manufacturers.
Pricing Analysis
Medicare Advantage payers anchor value-based contracting structures that stratify reimbursement across forced vital capacity endpoint achievement tiers. Price differentiation hinges on biomarker-linked diagnostic integration and specialty pharmacy adherence program bundling, with Massachusetts and California hospital systems commanding premium positioning through outcomes guarantees. Cost compression in the oral administration segment intensifies as patent cliffs approach on established tyrosine kinase inhibitors. Community pulmonology practices in Texas and Florida exhibit highest price sensitivity due to competitive bidding program exposure, while academic medical centers in the Northeast maintain lowest sensitivity through research funding offsets.
Supply Chain Analysis
Lonza, Catalent, and Samsung Biologics hold concentrated capacity for monoclonal antibody and biologic modifier production serving IPF pipeline candidates. Active pharmaceutical ingredient sourcing draws from Switzerland, Ireland, and Singapore for high-potency compounds, with excipient and packaging materials resting on Chinese and Indian suppliers. Single-source vulnerability pervades the companion diagnostic reagent segment, where FDA-cleared assay components face tariff exposure from concentrated East Asian manufacturing. Distribution runs through vertically integrated specialty pharmacy networks that unbundle traditional dispensing from digital coaching services in California and Florida Medicare Advantage populations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from a cyclical trough driven by generic substitution pressure on first-generation antifibrotic agents, with pipeline replenishment and breakthrough therapy designations signaling upward momentum.
For Market Incumbents: Harden formulary position through biomarker-linked companion diagnostic exclusivity arrangements with Massachusetts and Pennsylvania academic medical centers. Deepen backward integration into specialty pharmacy distribution channels to counter United Therapeutics' vertical control, while accelerating FDA submissions for combination therapy protocols ahead of nintedanib and pirfenidone patent cliffs.
For New Entrants and Emerging Players: Pursue acute exacerbation intravenous delivery protocols as the most penetrable white space, where hospital reimbursement structures favor infused therapy and Northeast tertiary centers maintain concentrated expertise. Target Texas and Florida community pulmonology practices with FDA-cleared diagnostic software partnerships that eliminate referral bottlenecks. Anchor go-to-market strategy through Medicare Advantage star rating program alignment.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialty pharmacy operators with digital therapeutics platform integration, positioning them as preferred acquisition archetypes over traditional drug developers. Long-term viability across the projection horizon rests on real-world evidence collection infrastructure that satisfies CMS innovation center payment models. Monitor quarterly FDA breakthrough therapy designation grants as the primary inflection signal for pipeline value realization.
| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker-Linked Diagnostic Development | FDA-cleared companion assays anchor precision positioning in academic medical centers and secure formulary preference. |
| Specialty Pharmacy Vertical Integration | Captive distribution channels enable patient adherence program control and Medicare Advantage star rating optimization. |
| Combination Therapy Protocol Advancement | Nintedanib-pirfenidone sequencing research creates white space for dual-mechanism portfolio expansion. |
| Real-World Evidence Infrastructure | CMS innovation center payment models reward outcomes data collection and enable risk-sharing arrangements. |
| Acute Exacerbation IV Delivery Expansion | Hospital bundled payment models create accountability for readmission reduction and channel expansion potential. |
Research Approach
Desk research of FDA orphan drug designations, CMS coverage determinations, and ClinicalTrials.gov protocols preceded structured interviews with formulary directors, specialty pharmacy operations executives, pulmonology department chairs, and payer access specialists. Secondary validation drew from Medicare Advantage star rating program disclosures, integrated delivery network procurement databases, and antifibrotic agent prescription audit data. Bottom-up patient flow modeling and top-down pharmaceutical revenue triangulation anchored market sizing across the analysis window.
Assumptions regarding FDA breakthrough therapy designation pathway utilization, CMS innovation center payment model adoption rates, and specialty pharmacy consolidation velocity were held fixed while varying Medicare Advantage enrollment growth and generic substitution timelines across sensitivity scenarios. Segmentation dimensions modeled encompassed product type, administration route, indication severity, and regional hospital cluster concentration. CAGRs were derived from forced vital capacity endpoint adoption curves and real-world evidence program penetration rates, with acute exacerbation episode frequency and medication possession ratio trends serving as key forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in Medicare reimbursement policy, FDA surrogate endpoint guidance, or biosimilar approval timelines would shift the trajectory. Forecasts reflect these assumptions without claiming predictive certainty. Quarterly review of FDA designation grants, CMS payment model pilots, and specialty pharmacy M&A activity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
Pediatric Respiratory Disease Therapeutics Market
Respiratory Therapy
Breathing Disorders Treatment Market
Respiratory Therapy
Respiratory Trainer Market
Respiratory Therapy
Lung (Pulmonary) Airway Disease Treatment Market
Respiratory Therapy
Croup Treatment Market
Respiratory Therapy
Respiratory Inhaler Market
Respiratory Therapy
Respiratory Gating Market
Respiratory Therapy
Global Pulmonary Surfactant Market
Respiratory Therapy
Pleural Effusion Treatment Market
Respiratory Therapy
Respiratory Biologics Market
Respiratory Therapy
Asia Pacific Respiratory Therapeutic Devices Market
Respiratory Therapy
Home Respiratory Therapy Market
Respiratory Therapy
Global Pneumonia Therapeutics Market
Respiratory Therapy
Bronchial Thermoplasty Market
Respiratory Therapy
Pediatric Respiratory Disease Treatment Market
Respiratory Therapy
Asthma and COPD Biomarkers Market