
 China Drug Delivery Devices Market | 2026-2036
China Drug Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
China Drug Delivery Devices Market Outlook
Hospital procurement consolidation in China's tier-one cities is shifting purchasing power toward centralized tendering platforms. BD leverages its manufacturing scale to anchor supply contracts with provincial health commissions. Gerresheimer AG specializes in high-barrier pharmaceutical packaging that sustains premium positioning within domestic injectable supply chains. China Meheco Group Co., Ltd competes through state-backed distribution networks that control hospital channel access across multiple provinces.
Drug delivery devices are engineered systems designed to administer therapeutic agents through controlled release mechanisms, incorporating specifications such as 29-gauge needle walls, siliconized barrel surfaces, and ISO 11608-1 dose accuracy tolerances for injectable formats. These devices serve the primary commercial purpose of improving bioavailability, reducing patient variability, and enabling self-administration in chronic disease management. Injectable devices occupy the dominant revenue position due to biologics expansion, while smart delivery systems represent the fastest-growing technology segment as connected pen injectors integrate dose tracking and adherence monitoring. Polymer-based devices capture concentrated margin pools where biodegradable excipients enable sustained-release parenteral formulations.
NMPA's Medical Device Registration regulations and GB/T 1962 luer taper standards shape product design requirements and market access timelines for both domestic and imported devices. The dual carbon goals from MEE influence polymer sourcing decisions and sterilization energy profiles across manufacturing facilities. Stakeholders must monitor NMPA's evolving innovative device approval pathways and assess whether in-house production of electronic dosing components or captive supply partnerships better secure smart device competitiveness.
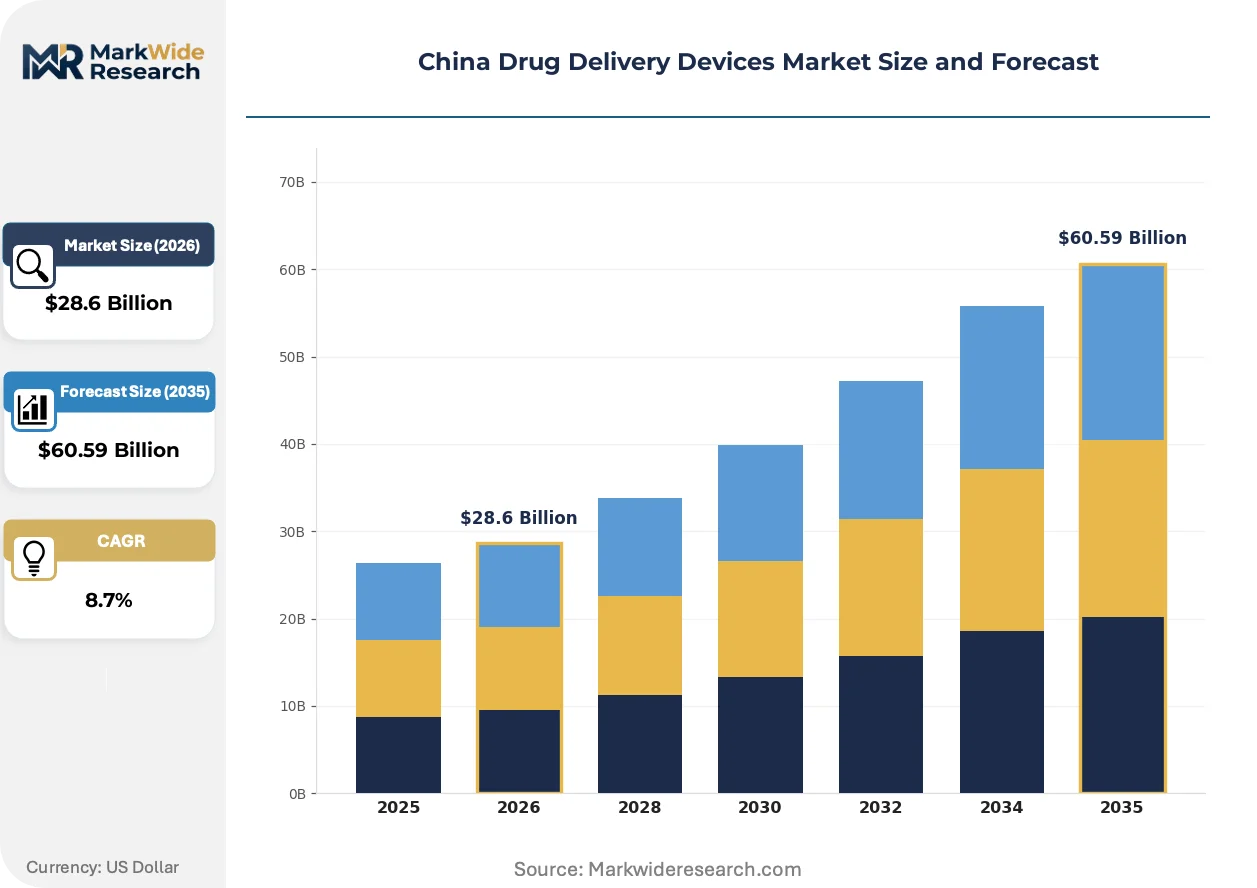
Market Dynamics
Hospital procurement consolidation across China's tier-one cities is compressing vendor margins while NMPA's accelerated review pathways for innovative devices reward first-movers with extended exclusivity windows. This dual pressure is restructuring competitive positioning toward scale-backed contract manufacturers and regulatory-specialized innovators.
Growth Catalysts
- Biologics manufacturing expansion:Domestic CDMO capacity for monoclonal antibodies and cell therapies is pulling demand for prefillable syringes and autoinjectors into Beijing-Tianjin-Hebei clusters. NMPA's priority review vouchers for rare disease devices accelerate commercialization timelines.
- MEE dual carbon mandates:The Ministry of Ecology and Environment's emissions targets are forcing polymer suppliers to certify bio-based feedstocks, creating first-mover advantage for device makers with validated sustainable material streams.
- Self-administration protocols:Chronic disease management programs in Shanghai and Guangzhou are reimbursing connected pen injectors that transmit adherence data to hospital EHR systems.
Market Restraints
- High-purity polymer import dependence:Cyclo-olefin polymer for syringe barrels remains concentrated with Japanese and German suppliers, exposing device margins to yen-euro volatility and ocean freight premiums.
- Provincial tendering fragmentation:While tier-one cities consolidate procurement, tier-two and tier-three provinces maintain fragmented purchasing platforms that prevent national pricing harmonization.
- Siliconization chemistry limitations:Barrel lubrication technologies from legacy suppliers create particulate contamination risks that NMPA's 2023 injectable particulate guidance has tightened further.
Strategic Opportunities
- Central China manufacturing relocation:Hubei and Sichuan provinces offer tax incentives and lower labor costs for secondary packaging and final assembly operations serving western hospital networks.
- SAMR innovative device fast-track:The State Administration for Market Regulation's breakthrough pathway offers reduced clinical data requirements for combination products addressing unmet oncology needs.
- Bluetooth-enabled dose logging:Integration of Nordic Semiconductor chipsets with disposable pen platforms creates adherence data streams that pharmaceutical sponsors will subsidize for real-world evidence collection.
Industry Challenges
- Electromechanical engineering talent scarcity:Connected device development requires firmware and sensor expertise that domestic universities have not scaled to match demand from automotive and consumer electronics competitors.
- ISO 11608-1 certification timelines:Dose accuracy testing for variable-dose pen injectors requires extended stability protocols that compress launch windows against fast-follower competition.
- Legacy ERP integration:Hospital procurement platforms in older tier-two cities run on systems that cannot parse UDI barcodes or electronic tender submissions without middleware investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Drug Delivery Devices Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable Devices, Inhalation Devices, Infusion Pumps, Transdermal Patches Delivery Mode: Needle-Free, Pre-Filled Syringes, Aerosol, Microneedle End User: Hospitals, Home Care, Nursing Facilities, Pharmacies Technology: Smart Delivery Systems, Biosensors, Nanotechnology, Polymer-Based Devices |
| Companies Covered | BD, Pfizer Inc, Gerresheimer AG, Novartis AG, Baxter, Teleflex Medical, Teva Pharmaceutical Industries Ltd, China Meheco Group Co., Ltd, West Pharmaceutical Services, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Drug Delivery Devices Market Strategic Shifts
Connected drug delivery platforms are rewiring value capture from hardware margins toward data-enabled service contracts, while polymer science advances and regulatory science reforms simultaneously reshape device economics and market access velocity.
Connected pen injectors with integrated dose sensors and Bluetooth Low Energy transmission are consolidating competitive advantage around adherence data ownership. Chronic disease management centers in Beijing and Shanghai are piloting these devices for diabetes and growth hormone therapies. The technology is consolidating vendor relationships toward platforms that can demonstrate measurable HbA1c improvement in real-world studies.
NMPA's 2023 revision to Medical Device Registration regulations introduced conditional approval pathways for breakthrough devices addressing life-threatening conditions. Domestic manufacturers with established quality management systems are leveraging this to compress time-to-market for novel autoinjector formats. Oncology supportive care applications are most affected, with several sponsors pursuing parallel development of device and drug-device combination submissions.
Centralized provincial procurement platforms are displacing hospital-level purchasing autonomy across Jiangsu, Zhejiang, and Guangdong provinces. Medical device distributors with exclusive territorial agreements are losing channel control to commission-based logistics providers that interface directly with tendering databases. This restructuring is most visible in disposable injectable formats where volume commitments now determine supplier selection rather than clinical preference alone.
China Drug Delivery Devices Market Segmentation
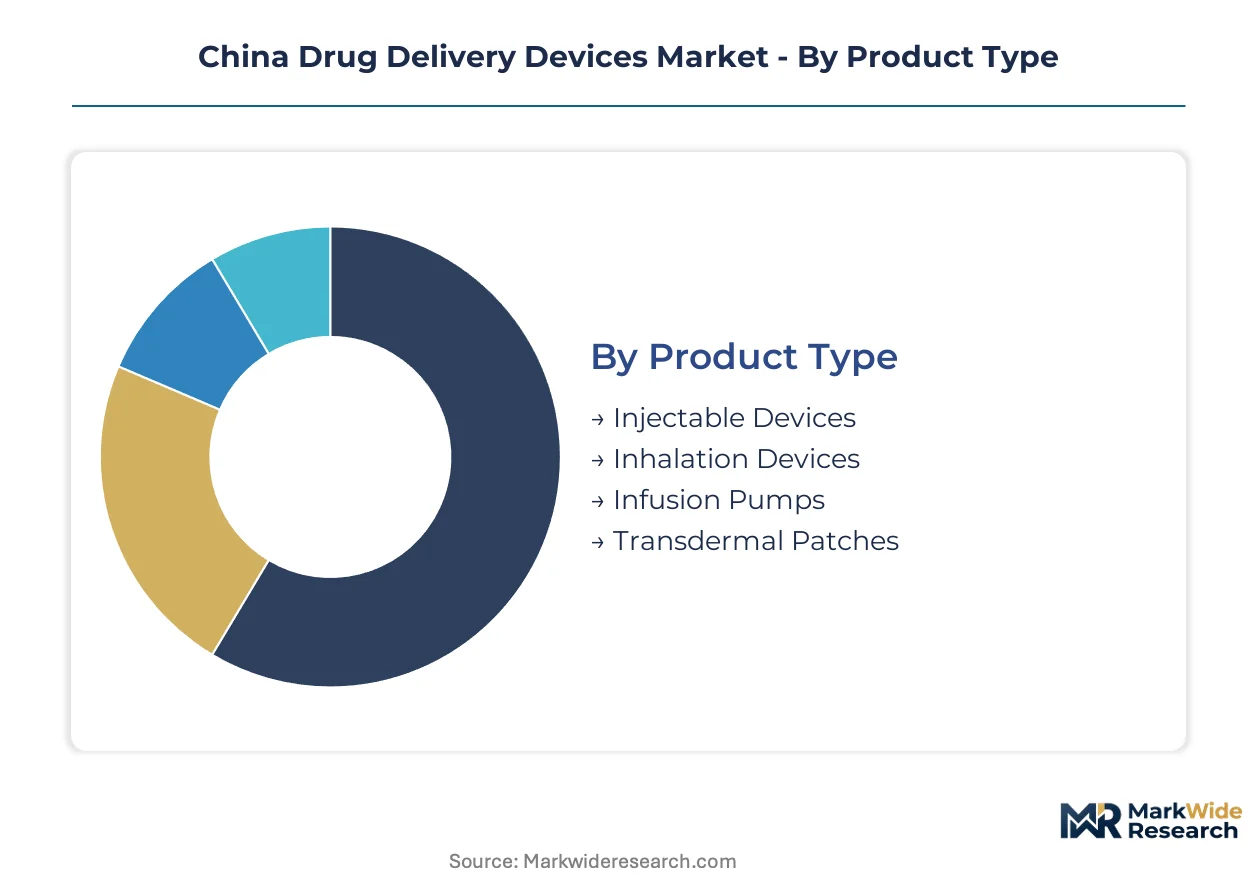
Device specification and delivery mechanism dictate procurement pathways across China's hospital networks. Segmentation reveals where NMPA regulatory pressure and biologics manufacturing expansion concentrate commercial opportunity.
Product Type:
Material composition and sterility requirements differentiate manufacturing investment intensity across device formats.
- Injectable Devices:Prefillable syringes and autoinjectors incorporate 29-gauge needles with siliconized barrels meeting ISO 11608-1 dose accuracy tolerances. Demand clusters in Beijing-Tianjin-Hebei biologics manufacturing corridors where CDMO expansion for monoclonal antibodies pulls device procurement.
- Smart Delivery Systems:Connected pen injectors integrate Nordic Semiconductor Bluetooth chipsets for dose logging and adherence monitoring. Shanghai chronic disease management pilots subsidize these devices for diabetes protocols requiring EHR data transmission.
- Inhalation Devices:Metered-dose and dry-powder formats serve respiratory therapeutic categories with lung deposition efficiency specifications.
- Infusion Pumps:Ambulatory and large-volume pumps manage parenteral nutrition and chemotherapy delivery with programmable flow control.
- Transdermal Patches:Matrix and reservoir designs enable sustained release through skin permeation for pain management and hormone therapies.
Injectable Devices lead on scale; Smart Delivery Systems lead on momentum.
Delivery Mode:
Patient interface design determines reimbursement eligibility and self-administration protocol adoption across China's tiered hospital system.
- Pre-Filled Syringes:Glass-barrel formats with staked needles reduce medication preparation errors in oncology supportive care. Provincial tendering platforms in Jiangsu and Zhejiang consolidate volume commitments for these formats.
- Microneedle:Dissolving and hydrogel-form arrays enable intradermal vaccine delivery with reduced cold-chain dependency. Development concentrates in Guangdong biomedical clusters targeting pediatric and elderly compliance improvement.
- Needle-Free:Jet injector and transdermal powder systems eliminate sharps disposal requirements for mass immunization programs.
- Aerosol:Nebulizer and inhaler formats optimize particle size distribution for pulmonary deposition in chronic obstructive pulmonary disease management.
Pre-Filled Syringes dominate procurement volume; Microneedle platforms climb the fastest on technology investment.
End User:
Care setting infrastructure determines device complexity requirements and data connectivity specifications.
- Hospitals:Tertiary facilities in tier-one cities anchor demand for infusion pumps and connected injectables with centralized monitoring capabilities. NMPA registration requirements favor established quality management systems for institutional procurement.
- Home Care:Self-administration protocols in Shanghai and Guangzhou reimburse Bluetooth-enabled pen injectors transmitting adherence data to hospital EHR systems.
- Nursing Facilities:Long-term care institutions require simplified device interfaces for staff with variable training levels.
- Pharmacies:Retail channels distribute prefilled syringes for specialty pharmaceuticals with cold-chain requirements.
Hospitals concentrate purchasing power; Home Care gains share fastest on reimbursement policy expansion.
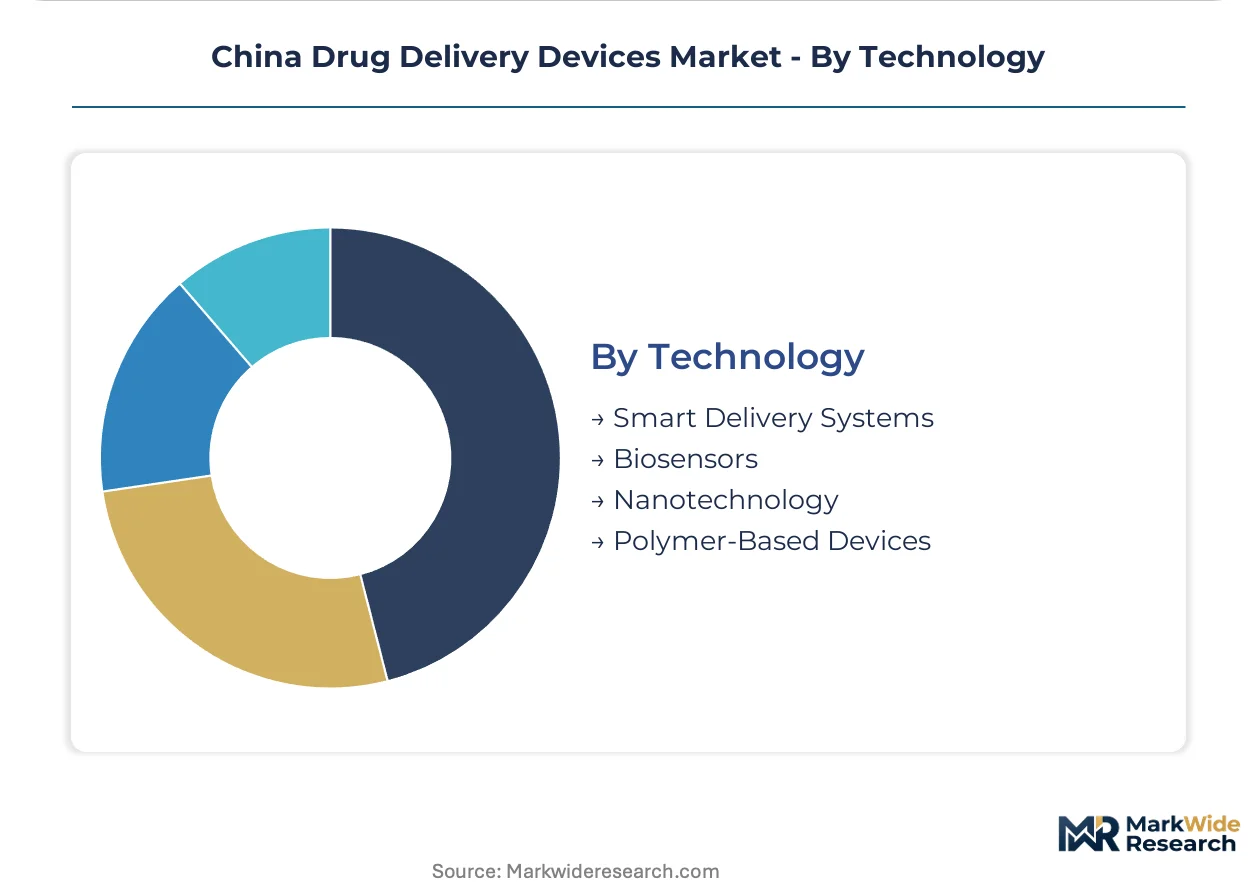
Technology:
Embedded electronics and material science capabilities separate premium positioning from commodity competition.
- Smart Delivery Systems:Dose sensors, Bluetooth Low Energy transmission, and mobile application integration create adherence data ownership. Real-world evidence contracts with pharmaceutical sponsors subsidize device costs.
- Polymer-Based Devices:Cyclo-olefin polymer barrels and biodegradable excipients enable sustained-release parenteral formulations. Japanese and German suppliers dominate high-purity resin feedstocks.
- Biosensors:Continuous glucose monitoring integration with insulin delivery enables closed-loop therapeutic control.
- Nanotechnology:Lipid nanoparticle and polymeric carrier systems enhance bioavailability for poorly soluble APIs.
Polymer-Based Devices anchor manufacturing scale; Smart Delivery Systems show steepest expansion trajectory on data monetization potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biomedical engineering talent pools concentrate in coastal provinces where device manufacturing clusters have matured around hospital procurement networks and regulatory review centers.
Beijing-Tianjin-Hebei
Prefillable syringe demand from monoclonal antibody CDMOs anchors manufacturing investment in this northern corridor. NMPA's priority review vouchers for rare disease devices accelerate commercialization timelines for local sponsors. Beijing's biomedical clusters host the highest density of innovative device startups targeting oncology supportive care applications.
Yangtze River Delta
Shanghai chronic disease management pilots subsidize connected pen injectors transmitting adherence data to hospital EHR systems. SAMR's breakthrough pathway offers reduced clinical data requirements for combination products addressing unmet oncology needs. Suzhou and Hangzhou device fabricators specialize in polymer-based sustained-release formulations for parenteral delivery.
Pearl River Delta
Guangdong's microneedle development targets pediatric and elderly compliance improvement through intradermal vaccine delivery formats. MEE dual carbon mandates force polymer suppliers to certify bio-based feedstocks, creating first-mover advantage for device makers with validated sustainable material streams. Shenzhen electronics manufacturers supply Nordic Semiconductor chipsets for Bluetooth-enabled dose logging platforms.
Sichuan-Chongqing
Central China manufacturing relocation incentives attract secondary packaging and final assembly operations serving western hospital networks. Provincial tendering fragmentation in tier-two and tier-three provinces prevents national pricing harmonization despite tier-one consolidation. Chengdu's biomedical parks cultivate domestic electromechanical engineering talent for connected device firmware development.
China Drug Delivery Devices Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across China's hospital procurement networks. Market structure tilts toward scale-backed contract manufacturers serving consolidated provincial tendering platforms alongside regulatory-specialized innovators pursuing NMPA accelerated pathways. Three archetypes dominate: multinational device manufacturers with manufacturing scale, domestic state-backed distributors controlling hospital channel access, and polymer science specialists sustaining premium positioning through high-barrier packaging technologies. Competitive moves concentrate on strategic partnerships with CDMOs and capacity expansion into central China tax incentive zones.
Within the multinational manufacturing tier, BD and Baxter anchor supply relationships with provincial health commissions through volume-backed tendering strategies. Gerresheimer AG exemplifies the polymer specialization archetype with positioning in high-barrier pharmaceutical packaging for injectable supply chains. China Meheco Group Co., Ltd represents state-backed distribution networks that control hospital channel access across multiple provinces. These three players illustrate the competitive tension between foreign manufacturing scale, materials science premium positioning, and domestic regulatory-navigating distribution power.
| Leading Market Players |
|---|
| BD |
| Pfizer Inc |
| Gerresheimer AG |
| Novartis AG |
| Baxter |
| Teleflex Medical |
| Teva Pharmaceutical Industries Ltd |
| China Meheco Group Co., Ltd |
| West Pharmaceutical Services |
| Others |
Value Chain & Pricing Dynamics
MEE dual carbon mandates gate qualified supply for polymer-based devices and determine premium-tier pricing access for manufacturers with validated sustainable material streams. Hospital procurement consolidation across tier-one cities amplifies this bifurcation, as centralized tendering platforms award volume contracts only to suppliers meeting both emission certification and NMPA quality standards.
Pricing Analysis
Bundled device-plus-data service contracts separate premium positioning from commodity hardware sales, with connected pen injectors commanding sustained margins through adherence monitoring subscriptions. Price differentiation rests on ISO 11608-1 certification tier and after-sales service bundling, with NMPA breakthrough pathway designation enabling 15-20% premiums. Cost compression in standard disposable formats is intensifying because provincial tendering platforms consolidate volume commitments. Tier-two and tier-three hospital networks show highest price sensitivity; Beijing and Shanghai tertiary facilities prioritize certification grade over unit cost.
Supply Chain Analysis
GB/T 1962 luer taper certification and ISO 11608-1 dose accuracy qualification gate supplier access to NMPA-registered procurement channels. High-purity cyclo-olefin polymer feedstocks draw from Japan and Germany, while Nordic Semiconductor chipsets for connected devices source from European foundries. Single-source vulnerability concentrates in Japanese cyclo-olefin resin suppliers exposed to yen volatility and ocean freight premiums. Distribution runs through state-backed distributors and commission-based logistics providers interfacing directly with provincial tendering databases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder, where NMPA's 2023 Medical Device Registration revision and accelerated review pathways for innovative devices continuously expand addressable demand for qualified manufacturers.
For Market Incumbents: Cement scale advantages by anchoring multi-year supply contracts with consolidating provincial health commissions before tendering platforms finalize vendor shortlists. Backward integration into polymer compounding operations mitigates yen-euro volatility exposure from Japanese and German resin suppliers. Prioritize NMPA breakthrough pathway submissions for connected autoinjector formats to secure extended exclusivity windows against fast-follower competition. For New Entrants and Emerging Players: Direct-to-hospital digital procurement platforms offer lower-friction entry than legacy distributor relationships controlled by China Meheco Group and state-backed incumbents. Microneedle vaccine delivery formats targeting Guangdong pediatric compliance improvement represent the most penetrable white-space segment. Lead with EHR integration capabilities and real-world evidence generation partnerships to differentiate against established hardware vendors. For Investors and Strategic Acquirers: Roll-up economics work for regional device fabricators with validated ISO 11608-1 quality systems because provincial tendering consolidation is displacing fragmented hospital-level purchasing and concentrating volume with scaled suppliers. Acquisition targets should demonstrate established NMPA registration histories and existing relationships with Beijing-Tianjin-Hebei biologics CDMOs. Watch for SAMR conditional approval pathway designations as inflection indicators for premium valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Breakthrough Pathway Submission | Accelerated review compresses time-to-market timelines for novel autoinjector oncology formats. |
| Backward Integration into Polymer Compounding | In-house cyclo-olefin resin processing reduces yen-euro volatility exposure and secures supply. |
| Bluetooth-Enabled Dose Logging Platform | Nordic Semiconductor integration creates adherence data streams subsidized by pharmaceutical sponsors. |
| Central China Manufacturing Relocation | Hubei and Sichuan tax incentives lower secondary packaging costs for western hospital networks. |
| Hospital System EHR Integration Partnership | Direct data transmission to Shanghai chronic disease management centers secures reimbursement eligibility. |
Study Parameters
Direct dialogue with hospital procurement managers, biomedical engineers at Beijing and Shanghai tertiary facilities, NMPA regulatory affairs consultants, and polymer supply chain directors grounded qualitative findings in operational reality. Secondary validation drew from NMPA Medical Device Registration filings, provincial health commission tendering databases, GB standards documentation, and CDMO capacity expansion announcements. Bottom-up demand modeling across device formats triangulated against top-down market sizing from manufacturing capacity and import-export flows.
Top-down macroeconomic drivers and bottom-up segment-level unit economics converged across the projection horizon. Segmentation dimensions modeled include product type, delivery mode, end-user care setting, and technology sophistication tier. CAGRs derived from weighted average of historical volume trajectories, capacity expansion pipelines, and reimbursement policy elasticity estimates. Forecast inputs incorporated NMPA review timeline distributions and MEE dual carbon compliance cost curves.
The model assumes a particular technology adoption path for connected pen injectors; alternative pathways for closed-loop biosensor integration would alter the outlook for insulin delivery market share. Forecasts reflect assumptions regarding provincial tendering consolidation velocity and NMPA staffing capacity for accelerated reviews. A model refresh is warranted upon material change in SAMR breakthrough pathway eligibility criteria or MEE emission standard enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Brazil Aesthetic Equipment Market
Medical Devices
Medication Management System Market
Medical Devices
US Mechanical Ventilator Market
Medical Devices
Flexible and Semi-Rigid Ureteroscopy Market
Medical Devices
Asia-Pacific Electroencephalography Devices Market
Medical Devices
Global Digital Dentistry Devices Market
Medical Devices
Lung Preservation Systems Market
Medical Devices
Handheld Ultrasound Devices Market
Medical Devices
Global Orthopedic Power Tools Market
Medical Devices
Endoscopic Mucosal Resection Device Market
Medical Devices
Centrifugation-Free Sperm Separation Systems Market
Medical Devices
Veterinary Respiratory Ventilators Market
Medical Devices
Smart Medical Devices Market
Medical Devices
Implantable Defibrillators Market
Medical Devices
Wireless Portable Medical Devices Market
Medical Devices
Global Diagnostic Catheter Market