
 Pressure Ulcer Detection Devices Market | 2026-2036
Pressure Ulcer Detection Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Pressure Ulcer Detection Devices Market Analytics
Software-defined analytics subscriptions are decoupling hardware sales from recurring revenue in pressure ulcer detection, shifting unit economics toward per-patient-per-month models. Hill-Rom Holdings, Inc. leverages its installed base of hospital beds to bundle sensor hardware with cloud-based risk scoring. Bruin Biometrics LLC anchors its commercial strategy on proprietary sub-epidermal moisture detection, avoiding direct competition with commoditized surface sensors. XSENSOR Technology Corp. specializes in high-resolution pressure mapping for operating theaters and wound clinics, occupying a premium niche with limited direct rivals.
Pressure ulcer detection devices comprise sensor-based systems that measure tissue deformation, perfusion, or moisture levels beneath the skin to identify early-stage tissue damage before visible breakdown occurs. These systems typically employ capacitive or piezoelectric arrays with spatial resolutions below 10 mm to capture pressure redistribution across bony prominences such as the sacrum and heels. Wearable sensors and pressure mapping systems lead current revenue generation due to established reimbursement pathways and proven clinical utility in hospital settings, while thermal imaging and electrical impedance technologies represent faster-growing segments as they promise earlier detection of deep tissue injury. Long-term care facilities and home healthcare channels are expanding fastest among end users, driven by CMS reimbursement incentives for remote patient monitoring and the shift toward decentralized geriatric care.
FDA clearance pathways for Class II medical devices govern software-as-medical-device claims, while CMS National Coverage Determinations shape whether hospitals and skilled nursing facilities receive reimbursement for continuous monitoring. The European Medical Device Regulation imposes stricter clinical evidence requirements on novel sensing modalities, extending time-to-market for ultrasound and optical sensor platforms. Stakeholders must monitor evolving payer evidence requirements to determine whether to prioritize randomized trial investment or pursue de novo regulatory strategies for emerging biomarker-based detection methods.
Market Dynamics
Software-defined analytics subscriptions are decoupling hardware sales from recurring revenue streams across pressure ulcer detection, fundamentally altering how vendors capture lifetime value from hospital and long-term care customers.
Growth Catalysts
- CMS Remote Patient Monitoring Reimbursement:Medicare reimbursement codes for continuous skin monitoring incentivize skilled nursing facilities to adopt sensor-based prevention systems, expanding addressable demand beyond acute care settings.
- Geriatric Care Infrastructure Expansion:Japan, Germany, and the United States are mandating pressure injury prevention protocols in aged care facilities, creating regulatory pull for automated detection technologies.
- Sub-Epidermal Moisture Sensing:Proprietary detection methods measuring fluid accumulation beneath intact skin enable intervention 3-5 days before visible tissue breakdown, improving clinical outcomes and justifying premium pricing.
Market Restraints
- Piezoelectric Sensor Input Concentration:High-resolution pressure mapping arrays depend on specialized polymer substrates manufactured by a concentrated supplier base in East Asia, exposing device makers to supply volatility.
- European Medical Device Regulation Clinical Evidence Burden:MDR requirements for novel optical and ultrasound sensing platforms extend regulatory timelines by 18-24 months versus predicate device pathways.
- Commoditized Surface Sensor Substitution:Low-cost capacitive pressure mats from industrial automation suppliers threaten margin compression in basic fall-risk and positioning applications.
Strategic Opportunities
- Home Healthcare Channel Expansion:Reimbursement parity between institutional and home-based remote monitoring in the United States creates direct-to-patient revenue models previously inaccessible to device manufacturers.
- Thermal-Imaging AI Convergence:Integration of infrared thermography with machine learning algorithms enables non-contact detection of inflammation patterns, opening surgical and intensive care applications where adhesive sensors face contamination risks.
- India Aged Care Policy Incentives:National Programme for Health Care of the Elderly expansion and proposed medical device manufacturing incentives under PLI schemes position the country as an emerging demand center and production alternative.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Shortage of specialists combining wound care clinical knowledge with sensor hardware and cloud architecture expertise constrains product development velocity for mid-tier manufacturers.
- Electronic Health Record Integration Complexity:Proprietary data formats from legacy hospital information systems require costly custom API development, delaying deployment timelines and inflating implementation budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pressure Ulcer Detection Devices Market |
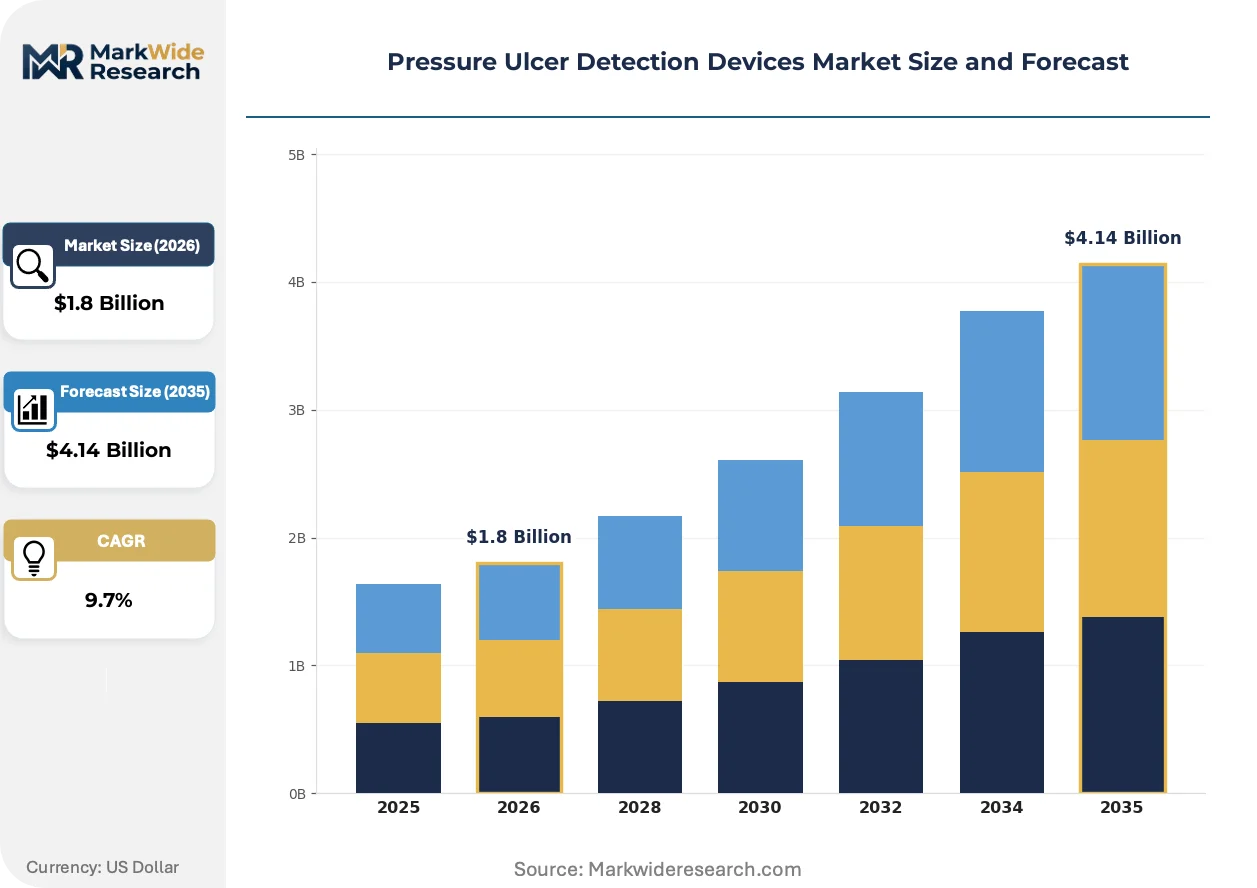
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Sensors, Imaging Systems, Pressure Mapping Systems, Surface Monitoring Devices End User: Hospitals, Long-Term Care Facilities, Home Healthcare, Rehabilitation Centers Technology: Thermal Imaging, Ultrasound, Electrical Impedance, Optical Sensors Application: Chronic Wound Management, Patient Monitoring, Risk Assessment, Prevention Strategies |
| Companies Covered | GE Healthcare, Hill-Rom Holdings, Inc., Bruin Biometrics LLC, 3M Company, Smith & Nephew, Stryker Corporation, XSENSOR Technology Corp., Medline Industries, LP, Arjo AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pressure Ulcer Detection Devices Market Evolving Landscape
Artificial intelligence is compressing detection latency while regulatory frameworks accelerate software-as-medical-device validation, reshaping competitive requirements across hardware and analytics segments simultaneously.
Machine learning-based risk scoring algorithms trained on multi-parameter sensor fusion are consolidating market position for integrated platform vendors over standalone hardware suppliers. Hospital systems in the United States and Germany are prioritizing procurement of unified bed-sensor-cloud systems that reduce nurse documentation burden. This technology convergence is consolidating vendor relationships, as facilities favor single-source accountability for both hardware uptime and algorithm performance.
The FDA's evolving guidance on predetermined change control plans for AI-enabled devices is enabling iterative algorithm updates without repeated 510(k) submissions. This regulatory flexibility reduces validation costs for cloud-based analytics providers and accelerates feature deployment cycles. Software-as-medical-device developers targeting the United States market are restructuring quality management systems to exploit this pathway, while European counterparts face stricter MDR scrutiny of continuous learning algorithms.
Long-term care procurement departments are demanding unbundled hardware and software pricing to compare total cost of ownership across competing platforms. Facility administrators in Japan and Germany negotiate separate contracts for sensor maintenance and analytics subscriptions, reversing previous bundled purchasing patterns. This behavioral shift pressures vendors to demonstrate standalone value for each component and exposes pure hardware manufacturers to margin compression from specialized analytics competitors.
Pressure Ulcer Detection Devices Market Segmentation
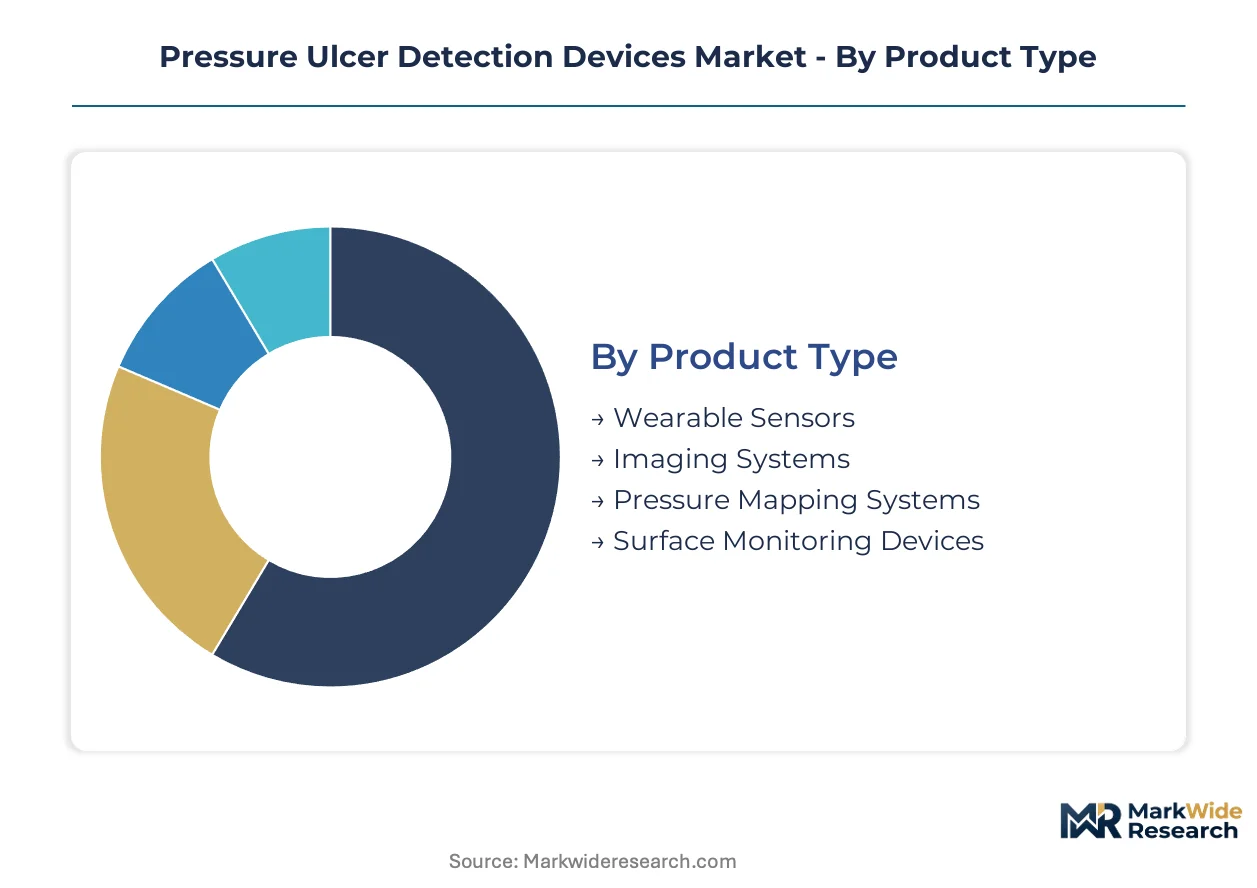
Pressure ulcer detection devices fragment across hardware form factors, care settings, sensing modalities, and clinical use cases. Each dimension carries distinct regulatory pathways, reimbursement codes, and procurement criteria that shape vendor strategy and customer economics.
Product Type:
FDA Class II clearance governs wearable sensors and pressure mapping systems under 510(k) pathways, while imaging systems face more stringent clinical evidence requirements under MDR in Europe. Surface monitoring devices often qualify as general wellness products with lighter regulatory burdens.
- Wearable Sensors:Adhesive patches or belt-mounted units employing capacitive or piezoelectric elements to track tissue deformation at bony prominences. Demand concentrates in United States skilled nursing facilities where CMS remote patient monitoring reimbursement codes directly offset hardware costs.
- Pressure Mapping Systems:High-resolution sensor arrays embedded in mattresses or overlays, typically with spatial resolution below 10 mm and sampling rates above 10 Hz. German hospital systems represent the strongest demand cluster, driven by mandatory pressure injury prevention protocols in acute care settings.
- Imaging Systems:Infrared thermography and structured light platforms for non-contact tissue assessment. Japanese long-term care operators pilot these for sacral screening in immobile patients.
- Surface Monitoring Devices:Passive pressure-distribution mats and positioning pads without active analytics. Home healthcare agencies in the United States adopt these for fall-risk correlation alongside pressure monitoring.
Pressure Mapping Systems sits at the top of the volume ranking, with Wearable Sensors climbing the fastest.
End User:
Procurement authority and reimbursement eligibility vary sharply across institutional versus decentralized care settings, fragmenting sales cycles and contract structures.
- Hospitals:Integrated health systems with centralized biomedical engineering departments and established EHR infrastructure. United States IDNs negotiate enterprise-wide contracts bundling hardware, software, and implementation services.
- Long-Term Care Facilities:Skilled nursing and assisted living operators with thinner IT staff and stronger price sensitivity. CMS reimbursement shifts for remote patient monitoring are accelerating sensor adoption in this channel.
- Home Healthcare:Visiting nurse associations and home health agencies serving post-acute patients. Reimbursement parity with institutional settings in the United States is unlocking direct-to-patient revenue models.
- Rehabilitation Centers:Inpatient and outpatient facilities managing spinal cord injury and stroke recovery populations. Pressure injury prevention integrates with mobility restoration protocols in German and Japanese facilities.
Hospitals dominate absolute spending, though Home Healthcare is gaining share fastest as reimbursement frameworks mature.
Technology:
Clinical validation requirements and time-to-market timelines diverge substantially across sensing modalities, with electrical impedance and optical platforms facing longer regulatory trajectories than established thermal methods.
- Thermal Imaging:Infrared cameras detecting inflammation-induced temperature differentials at skin surface. Operating theaters in Japan and Germany deploy these for sterile-field compliance where adhesive sensors are prohibited.
- Ultrasound:Sub-epidermal tissue imaging for deep tissue injury detection before surface breakdown. MDR clinical evidence requirements in Europe extend commercialization timelines versus predicate device pathways.
- Electrical Impedance:Bioimpedance spectroscopy measuring fluid accumulation beneath intact skin. United States long-term care pilots demonstrate 3-5 day advance warning versus visual inspection.
- Optical Sensors:Multi-spectral imaging and photoplethysmography for perfusion monitoring. Emerging platforms target ICU applications in United States academic medical centers.
Thermal Imaging holds the largest installed base, with Electrical Impedance showing the steepest expansion trajectory.
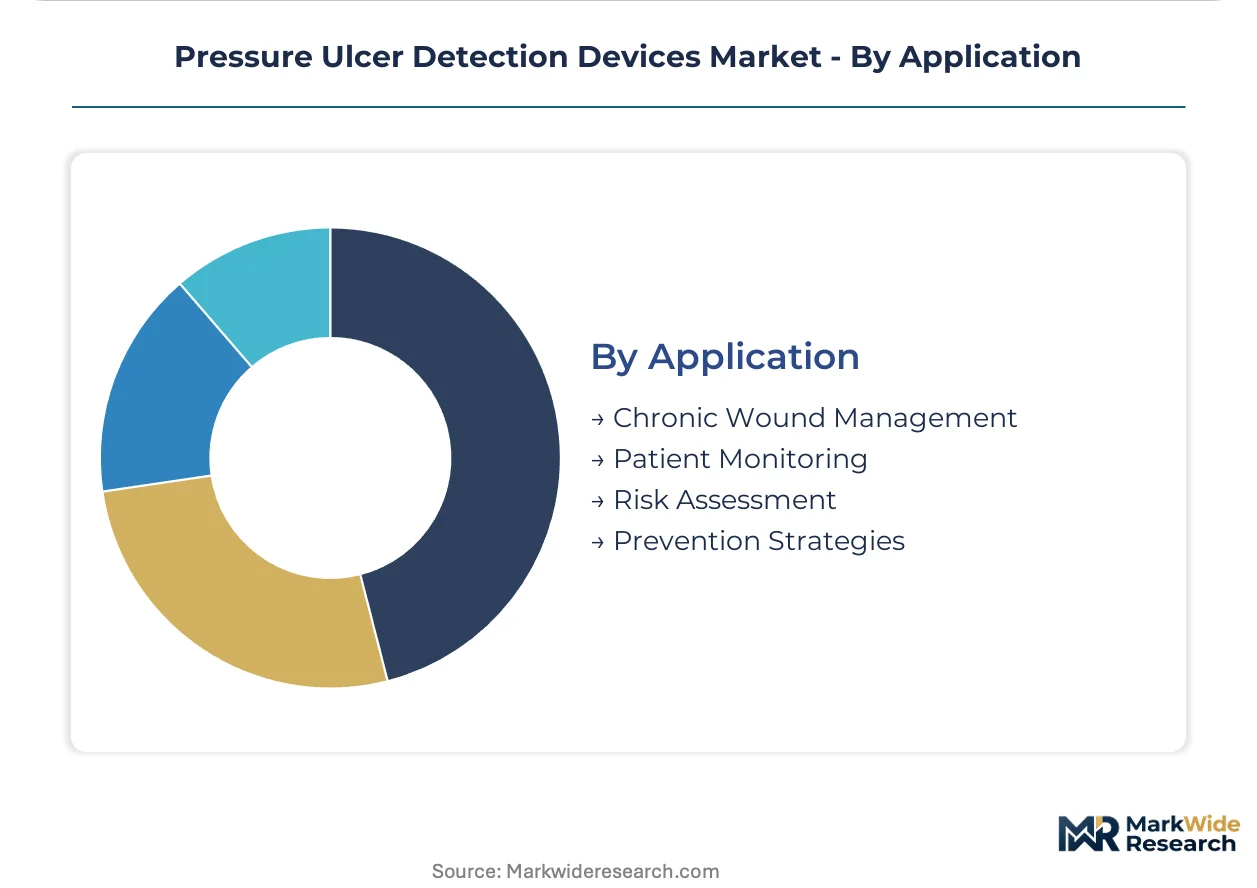
Application:
Reimbursement codes and clinical workflow integration requirements differ across proactive prevention versus reactive wound management, shaping product feature prioritization.
- Chronic Wound Management:Monitoring of existing pressure injuries for healing progression and recurrence prevention. Wound clinics in Germany combine pressure mapping with debridement scheduling.
- Patient Monitoring:Continuous or intermittent surveillance of at-risk patients across care transitions. United States hospitals prioritize EHR-integrated dashboards reducing nurse documentation burden.
- Risk Assessment:Structured screening protocols using Braden Scale automation and sensor-derived mobility scores. Long-term care facilities in Japan mandate quarterly assessments driving standardized tool adoption.
- Prevention Strategies:Proactive repositioning alerts and support surface optimization. Home healthcare agencies in the United States deploy these for readmission reduction contracts with accountable care organizations.
Patient Monitoring generates the highest revenue concentration, while Prevention Strategies is expanding most quickly as value-based payment models mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany enforces stricter pressure injury prevention mandates than the United States, yet both markets expand geriatric care infrastructure at comparable investment intensity. Japan's regulatory framework accelerates adoption of non-contact detection technologies in sterile environments. India emerges as a production alternative under manufacturing incentive schemes.
United States
CMS reimbursement codes for remote patient monitoring directly offset hardware acquisition costs in skilled nursing facilities. FDA digital health guidance enables iterative algorithm updates without repeated 510(k) submissions for AI-enabled devices. Hospital systems in Texas and Florida negotiate enterprise-wide contracts bundling sensor hardware with cloud analytics.
Germany
Mandatory pressure injury prevention protocols in acute care settings drive procurement of high-resolution pressure mapping arrays. MDR clinical evidence requirements extend regulatory timelines for novel optical and ultrasound sensing platforms versus predicate pathways. Medical device clusters in Baden-Württemberg concentrate sensor manufacturing and wound care research facilities.
Japan
Long-term care operators pilot thermal imaging systems for sacral screening in immobile patients where adhesive sensors face contamination risks. METI standards and PMDA oversight govern software-as-medical-device claims for continuous monitoring platforms. Kanto region hospitals integrate detection systems with established geriatric care infrastructure.
India
National Programme for Health Care of the Elderly expansion creates demand for cost-effective prevention technologies in aged care facilities. PLI scheme incentives for medical device manufacturing position the country as an emerging production alternative to East Asian suppliers. Maharashtra and Karnataka host pilot programs for sub-epidermal moisture detection in tier-1 hospital networks.
Pressure Ulcer Detection Devices Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated platform vendors capturing recurring revenue through software subscriptions while hardware-focused suppliers face margin compression. The vendor landscape organizes into three tiers: diversified medical technology conglomerates with installed base advantages, pure-play sensor specialists with proprietary detection methods, and contract manufacturers supplying commoditized pressure mat components. Consolidation pressures intensify as hospital procurement departments demand single-source accountability for hardware uptime and algorithm performance. Strategic moves center on backward integration into specialized polymer substrates and technology licensing partnerships for EHR integration capabilities.
Among diversified medical technology conglomerates, GE Healthcare and Stryker Corporation exemplify scale-driven platform strategies leveraging existing hospital relationships. Hill-Rom Holdings, Inc. occupies a distinct position bundling sensor hardware with cloud-based risk scoring through its installed base of hospital beds. Bruin Biometrics LLC and XSENSOR Technology Corp. represent the specialist tier, with the former anchoring commercial strategy on proprietary detection methods and the latter occupying a premium niche in high-resolution pressure mapping for surgical applications.
| Leading Market Players |
|---|
| GE Healthcare |
| Hill-Rom Holdings, Inc. |
| Bruin Biometrics LLC |
| 3M Company |
| Smith & Nephew |
| Stryker Corporation |
| XSENSOR Technology Corp. |
| Medline Industries, LP |
| Arjo AB |
| Others |
Value Network & Pricing Analysis
Software-as-medical-device transitions are simultaneously compressing hardware margins and concentrating supply leverage among specialized polymer substrate manufacturers, creating divergent cost economics across subscription analytics and sensor hardware tiers. This structural shift rewards vendors with captive cloud infrastructure while exposing pure hardware suppliers to input cost volatility from East Asian manufacturing clusters.
Pricing Analysis
Capacity additions in India under PLI medical device incentives are reshaping price floors for commoditized pressure mat components, though premium sensing arrays retain margin insulation. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared clinical systems from general wellness positioning pads. Cost compression in the economy tier stems from industrial automation suppliers repurposing capacitive sensors for healthcare applications. Home healthcare agencies exhibit highest price sensitivity, while United States IDNs prioritize total cost of ownership over unit acquisition costs.
Supply Chain Analysis
ISO 13485 and FDA 21 CFR Part 820 certification requirements gate entry for polymer substrate suppliers, concentrating qualified capacity in Japan, Germany, and South Korea. High-resolution piezoelectric arrays draw from specialized fluoropolymer films and conductive ink formulations. Single-source vulnerability persists for medical-grade silicone adhesives used in wearable sensor patches. Distribution runs through regional medical device distributors with GPO contracting relationships in the United States and direct hospital sales forces in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where CMS reimbursement expansion for remote patient monitoring creates sustained demand pull independent of macroeconomic cycles.
For Market Incumbents: To counter margin erosion from industrial automation suppliers entering surface sensor segments, prioritize backward integration into specialized polymer substrate production and deepen software subscription attach rates through EHR-integrated analytics platforms. Capacity additions in India offer cost-competitive manufacturing alternatives to East Asian suppliers. For New Entrants and Emerging Players: Home healthcare agencies serving post-acute patients represent the most penetrable buyer archetype, given reimbursement parity with institutional settings and thinner incumbent presence. Target direct-to-patient subscription models bypassing hospital procurement committees, leveraging FDA digital health guidance for streamlined 510(k) pathways. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play hardware manufacturers lacking recurring revenue streams, presenting consolidation targets for platform vendors seeking sensor capabilities. Watch CMS National Coverage Determination expansions as the inflection signal for home healthcare channel acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Software-as-Medical-Device Development | FDA predetermined change control plans enable iterative algorithm deployment without repeated submissions. |
| Sub-Epidermal Moisture Detection Platform | Proprietary bioimpedance spectroscopy creates 3-5 day detection advantage over visual inspection protocols. |
| Hospital System Partnership | Enterprise-wide contracts with United States IDNs bundle hardware, analytics, and implementation services. |
| Reimbursement Strategy | CMS remote patient monitoring codes directly offset hardware costs in skilled nursing facilities. |
| CE Marking Pathway | MDR clinical evidence requirements extend timelines for novel optical and ultrasound sensing platforms. |
Research Methodology
Coverage spans the United States, Germany, Japan, and India, with primary inputs from each market cluster. The analysis combines structured interviews with wound care clinicians, hospital purchasing committees, biomedical engineers, and GPO contracts managers with secondary validation against FDA 510(k) databases, CMS Medicare reimbursement filings, and hospital procurement records. Bottom-up unit economics modeling triangulates against top-down market sizing from trade data and industry association disclosures.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon. Segmentation dimensions include product type, end-user setting, sensing modality, and clinical application, with additional granularity on reimbursement eligibility tiers. CAGRs derive from regression analysis of historical adoption curves adjusted for regulatory milestone impacts. Forecast inputs incorporate CMS coverage determination timelines and MDR implementation enforcement patterns.
Underlying measurement precision varies by segment; wearable sensors and pressure mapping systems carry tighter precision than emerging thermal imaging and electrical impedance categories due to established reimbursement coding. Forecasts reflect assumptions on regulatory pathway efficiency and payer evidence requirements. A model refresh is warranted upon material change in CMS remote patient monitoring reimbursement scope or MDR clinical evidence precedent for AI-enabled devices.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Digital Intraoral Camera Market
Medical Devices
Global Foot Orthotic Insoles Market
Medical Devices
Genitourinary Prosthetics Market
Medical Devices
Liquid Oxygen Devices Market
Medical Devices
Pressotherapy Systems Market
Medical Devices
Pelvic Muscle Probes Market
Medical Devices
Biomedical Warming and Thawing Devices Market
Medical Devices
Bioimpedance Analyzers Market
Medical Devices
Global Hemostasis Valves Market
Medical Devices
Manometry System Market
Medical Devices
Middle East and Africa Refractive Surgery Devices Market
Medical Devices
Spine Surgery Robots Market
Medical Devices
Medical Connector Market
Medical Devices
Vascular Closure Device (VCD) Market
Medical Devices
Global Bone Screw System Market
Medical Devices
Global External Fixators Market