
 Australia Ultrasound Devices Market | 2026-2036
Australia Ultrasound Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Ultrasound Devices Market Outlook
Australian medical device manufacturing capacity is hardening around specialized imaging components and localized service networks. GE Healthcare leverages its established distribution infrastructure across tertiary hospitals in Sydney and Melbourne. Siemens Healthineers AG anchors its position through sustained R&D investment in AI-integrated diagnostic platforms. Koninklijke Philips N.V. differentiates via portable ultrasound systems tailored to emergency and rural deployment.
Ultrasound devices generate acoustic images through piezoelectric transducer arrays operating at frequencies between two and eighteen megahertz, enabling non-invasive visualization of soft tissue, blood flow, and fetal development without ionizing radiation. Diagnostic systems dominate hospital procurement budgets, while portable units represent the fastest-expanding product category as ambulatory care networks decentralize imaging services. Digital technology platforms command premium positioning against analog and hybrid alternatives, though fiber optic architectures gain traction in research lab settings requiring high-fidelity signal transmission.
TGA governs device registration and post-market surveillance, while the Medical Device Single Audit Program streamlines international quality compliance for manufacturers serving Australia. The Therapeutic Goods Administration's evolving software classification rules are forcing vendors to restructure regulatory submissions for AI-enhanced diagnostic features. Stakeholders must monitor how TGA alignment with international harmonization initiatives reshapes approval timelines and competitive entry barriers for emerging ultrasound technologies.
Market Dynamics
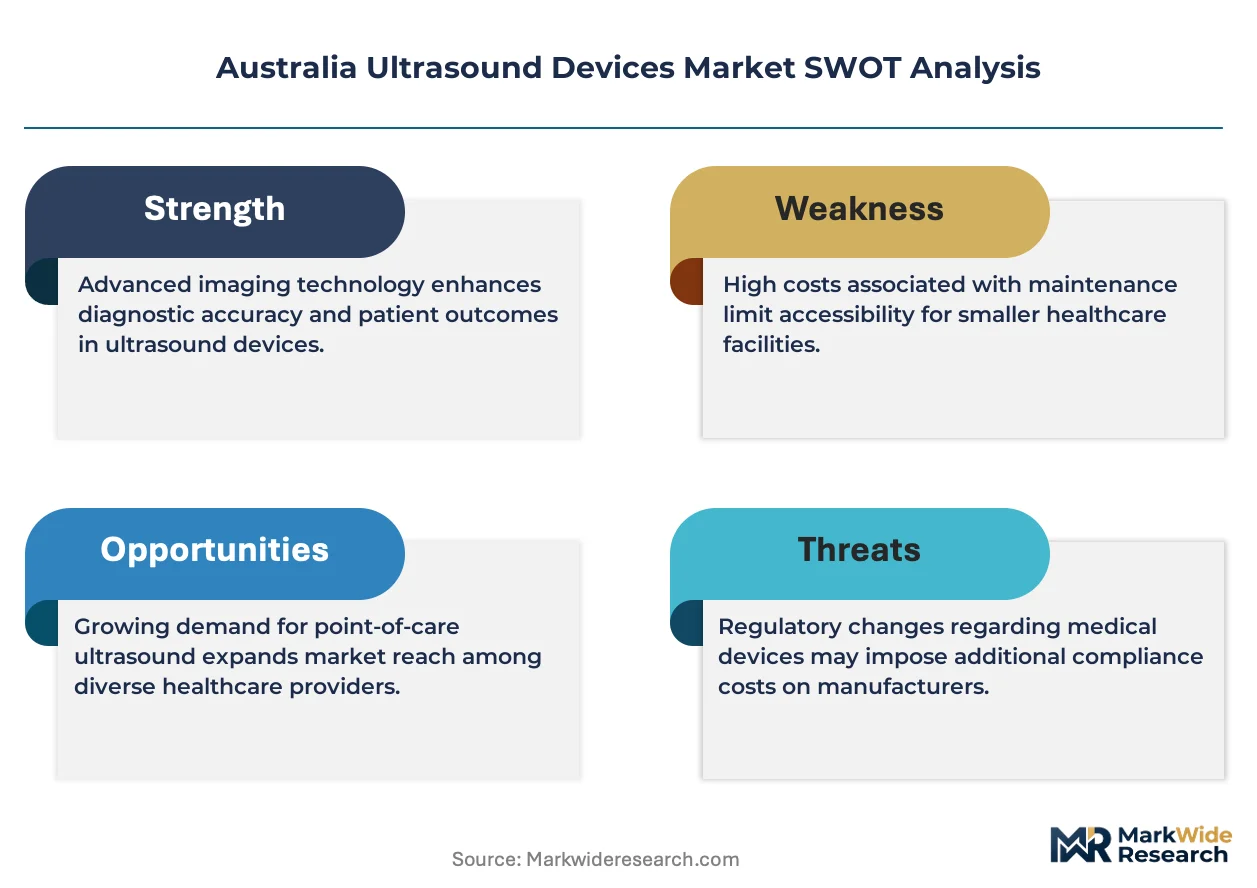
Point-of-care ultrasound expansion across Australian rural health networks is compressing replacement cycles for legacy radiology infrastructure while forcing vendors to restructure service delivery models around decentralized deployment.
Growth Catalysts
- AI-enabled diagnostic software:Machine learning algorithms embedded in ultrasound platforms accelerate image interpretation workflows. TGA software-as-a-medical-device pathways legitimize these tools for clinical reimbursement.
- Rural healthcare access mandates:Australian government funding for remote primary care drives portable ultrasound procurement. Mobile diagnostic units address specialist shortages in Queensland and Western Australia outback regions.
- Aging radiology infrastructure:Hospital networks in New South Wales and Victoria face end-of-life replacement decisions for analog systems. Digital platform upgrades align with federal digital health interoperability standards.
Market Restraints
- Capital intensity of AI integration:Computational hardware requirements for real-time image processing inflate unit costs. Smaller regional hospitals defer procurement decisions.
- Specialized sonographer shortages:Australian workforce pipelines fail to match point-of-care expansion velocity. Training program accreditation bottlenecks limit operational deployment.
- Import dependency for piezoelectric components:Domestic manufacturing lacks capacity for high-frequency transducer arrays. Supply concentration in East Asian component suppliers exposes procurement to currency volatility.
Strategic Opportunities
- Tasmanian and Northern Territory penetration gaps:Underserved island and remote mainland territories lack established imaging networks. First-mover vendors capture long-term service contracts.
- Veterinary ultrasound crossover:Companion animal diagnostic demand from Australian veterinary chains creates adjacent revenue streams. Platform modularity enables species-specific preset configurations.
- Telemedicine integration standards:Federal digital health infrastructure investments mandate remote consultation capabilities. Ultrasound vendors embedding secure transmission protocols qualify for priority procurement lists.
Industry Challenges
- TGA software classification complexity:Evolving regulatory guidance for AI-enhanced features creates submission uncertainty. Vendors face extended approval timelines for algorithm updates.
- Legacy PACS integration friction:Hospital picture archiving systems operate on incompatible data standards. Middleware development consumes implementation resources.
- Service technician geographic dispersion:Sparse population density across Western Australia and South Australia stretches maintenance response times. Remote diagnostic capabilities require capital investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Ultrasound Devices Market |
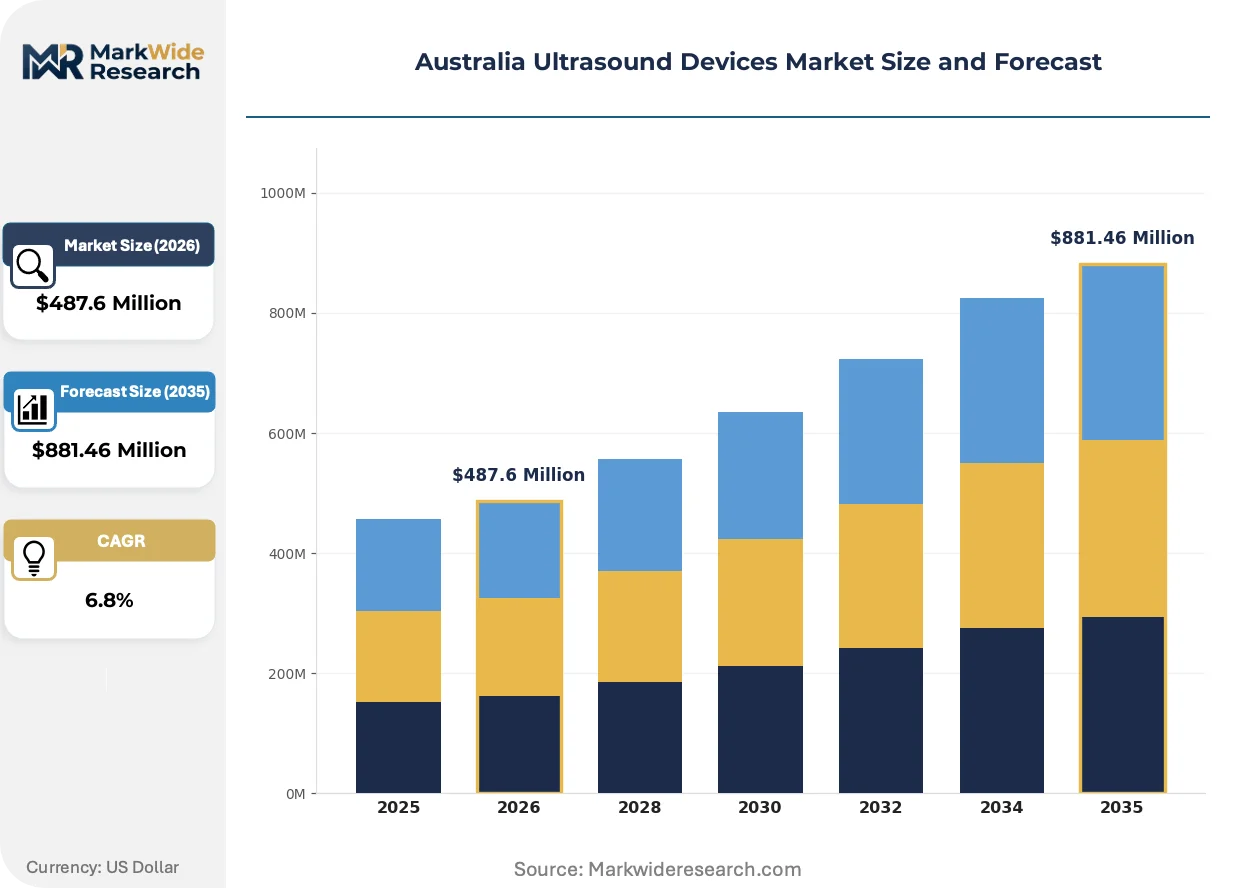
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic, Therapeutic, Portable, 3D/4D End User: Hospitals, Clinics, Research Labs, Imaging Centers Technology: Analog, Digital, Hybrid, Fiber Optic Application: Obstetrics, Cardiology, Urology, Gastroenterology |
| Companies Covered | GE Healthcare, Siemens Healthineers AG, Koninklijke Philips N.V., Fujifilm Holdings Corporation, Mindray Medical, Canon Medical Systems Corporation, Samsung Medison, Esaote SPA, Hologic Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Ultrasound Devices Market Strategic Shifts
Three distinct forces are reshaping Australian ultrasound deployment: semiconductor advances enabling edge computing, regulatory frameworks catching up to software-defined devices, and procurement patterns tilting toward operational expenditure models over capital ownership.
Capacitive micromachined ultrasound transducers are electrifying portable system architectures. These semiconductor-fabricated arrays replace traditional piezoelectric crystals with silicon-based emitters. Emergency departments in Queensland metropolitan hospitals adopt handheld units for triage acceleration. The technology is electrifying competitive positioning by collapsing size-weight-performance tradeoffs that previously constrained rural deployment.
TGA software classification rules are tightening evidentiary requirements for AI diagnostic features. The Therapeutic Goods Administration now demands clinical validation datasets specific to Australian patient populations. Algorithm developers face restructuring of technical documentation for premarket submissions. Cardiology and obstetrics applications encounter the most scrutiny given high-risk diagnostic contexts.
Subscription-based equipment access is displacing traditional capital purchase arrangements. Australian private radiology groups favor per-scan pricing models that align costs with patient throughput. Equipment financiers and original manufacturers establish direct operational partnerships. New South Wales ambulatory care networks demonstrate the strongest uptake of this procurement restructuring.
Australia Ultrasound Devices Market Segmentation
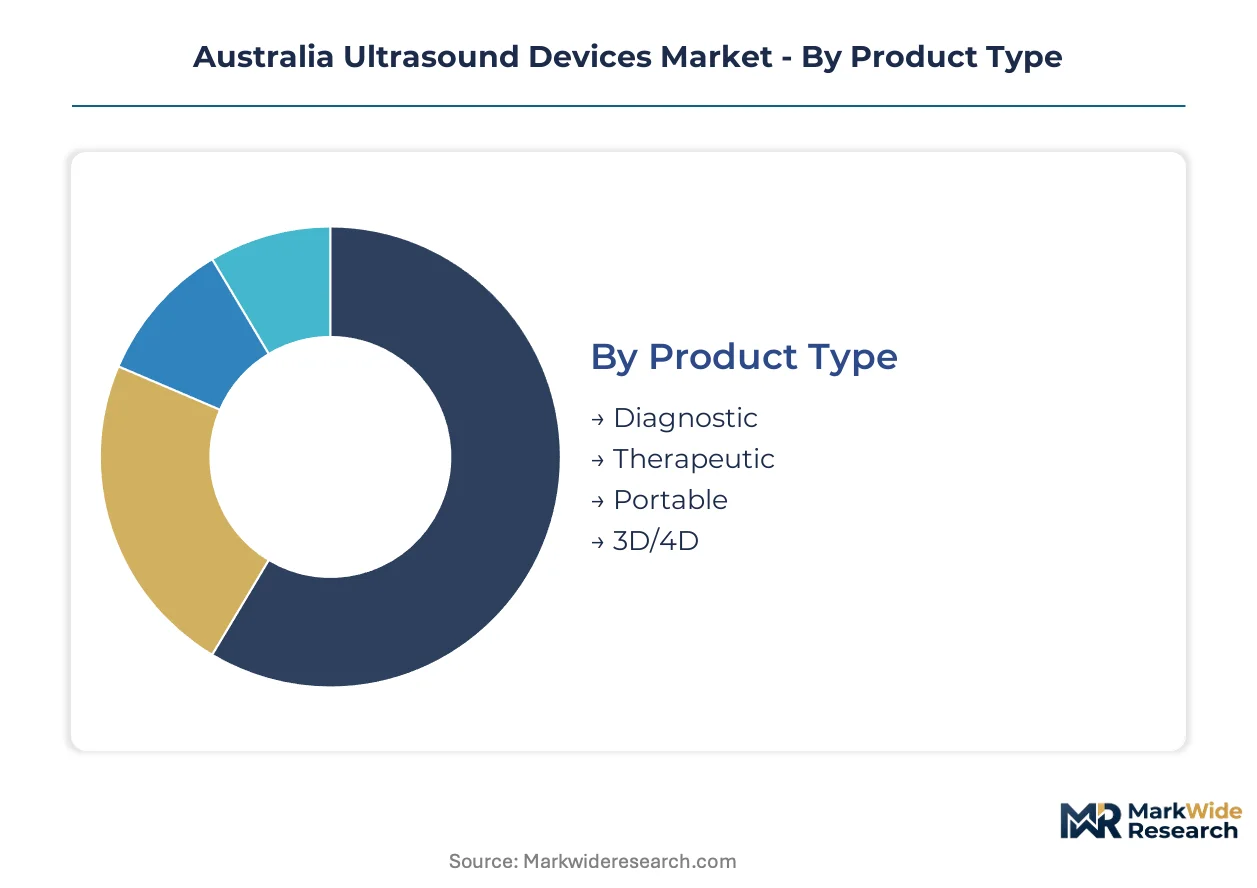
Ultrasound device procurement across Australian healthcare networks follows distinct technical and operational logics. Segmentation reveals how replacement priorities differ between metropolitan hospital systems and decentralized rural deployment models.
Product Type:
Replacement cycles for aging radiology infrastructure concentrate procurement decisions around performance tier and mobility requirements rather than brand loyalty alone.
- Diagnostic:Cart-based systems with multi-frequency transducer arrays dominate tertiary hospital radiology departments in Sydney and Melbourne. New South Wales metropolitan health networks prioritize these units for high-throughput imaging workflows despite capital intensity.
- Portable:Handheld and laptop-configured units address Queensland and Western Australia rural access mandates. Battery-operated systems with wireless DICOM transmission qualify for federal mobile diagnostic unit funding streams.
- Therapeutic:Focused ultrasound and HIFU platforms serve interventional radiology and physiotherapy applications. Australian private clinics adopt these for musculoskeletal and pain management protocols.
- 3D/4D:Real-time volumetric imaging systems command premium positioning in obstetric and cardiac applications. TGA software validation requirements extend approval timelines for algorithm-dependent rendering features.
Diagnostic systems sit at the top of the volume ranking, with Portable climbing the fastest.
End User:
Customer type determines service contract structures and regulatory compliance burdens across the Australian market.
- Hospitals:Public and private acute care facilities in Victoria and New South Wales drive replacement demand for end-of-life analog systems. TGA post-market surveillance obligations concentrate vendor resources on these high-volume accounts.
- Clinics:General practice and specialist outpatient settings in Queensland adopt point-of-care units for same-day diagnosis. Medicare reimbursement pathways for clinic-based ultrasound procedures accelerate procurement decisions.
- Research Labs:University medical schools and CSIRO facilities require high-fidelity signal processing for experimental protocols. Fiber optic architectures gain traction in these settings for noise immunity.
- Imaging Centers:Private radiology groups in metropolitan areas favor subscription-based equipment access over capital purchase. Per-scan pricing models align costs with patient throughput volatility.
Hospitals capture the dominant revenue share, though Clinics are expanding most quickly.
Technology:
Platform architecture choices reflect tradeoffs between image fidelity, computational requirements, and integration with legacy hospital infrastructure.
- Digital:Fully digital beamforming and signal processing architectures align with federal digital health interoperability standards. These systems command premium positioning against legacy alternatives in Victorian hospital procurement.
- Analog:Legacy systems with discrete component signal chains face end-of-life replacement pressure. Maintenance part scarcity accelerates retirement decisions in regional South Australia facilities.
- Hybrid:Mixed-signal architectures balance cost and performance for mid-tier clinic deployments. These units serve transitional upgrade paths for facilities with constrained capital budgets.
- Fiber Optic:Optical signal transmission enables electromagnetic immunity for specialized research and surgical environments. Australian teaching hospitals adopt these for intraoperative imaging applications.
Digital platforms lead installed base value, with Fiber Optic gaining share fastest in specialized niches.
Application:
Clinical use case determines transducer specification requirements and software feature prioritization in vendor development roadmaps.
- Obstetrics:Fetal biometric measurement and anomaly screening drive demand for high-resolution linear and curvilinear probes. TGA scrutiny of AI-enhanced diagnostic features intensifies for this high-risk application.
- Cardiology:Echocardiography systems require phased array transducers and Doppler processing for hemodynamic assessment. Victorian cardiac centers prioritize portable units for bedside and emergency deployment.
- Urology:Transrectal and renal imaging applications concentrate in metropolitan urology practices. Prostate biopsy guidance features differentiate vendor offerings in this segment.
- Gastroenterology:Endoscopic ultrasound and abdominal imaging support diagnostic and interventional procedures. Queensland health networks expand these capabilities for hepatobiliary disease management.
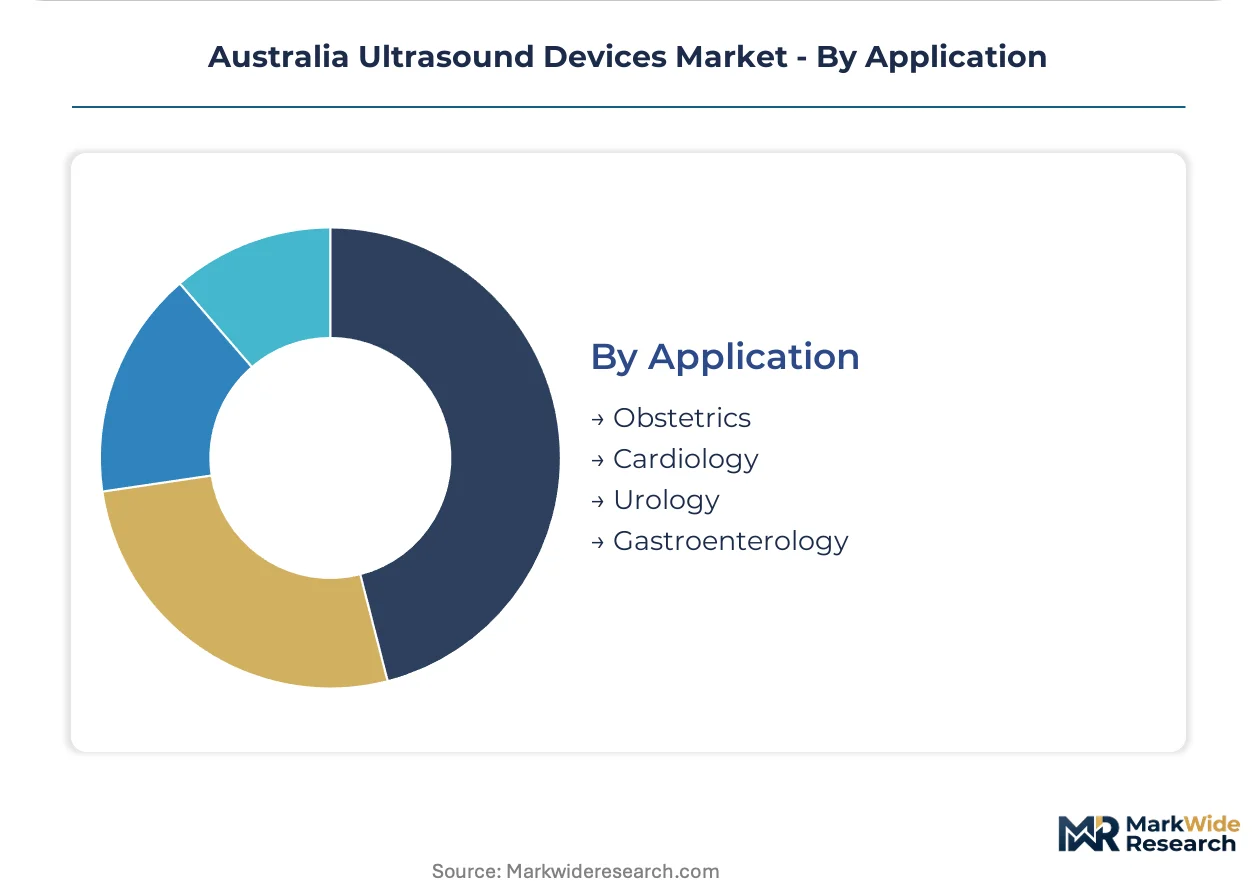
Obstetrics maintains the largest procedure volume, while Cardiology shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are minimal in Australia's ultrasound devices market given TGA's stringent software-as-a-medical-device pathways, yet sub-regional demand fragmentation creates localized procurement advantages for vendors with decentralized service networks.
New South Wales
Metropolitan Sydney health networks drive replacement cycles for aging radiology infrastructure. TGA post-market surveillance obligations concentrate vendor resources on these high-volume accounts. The Sydney-Western Sydney corridor hosts the densest concentration of tertiary hospital imaging departments.
Victoria
Melbourne cardiac centers prioritize portable units for bedside and emergency deployment. Federal digital health interoperability standards accelerate digital platform upgrades across public hospital networks. The Melbourne biomedical precinct anchors AI-integrated diagnostic platform validation.
Queensland
Rural access mandates propel portable ultrasound procurement across outback primary care networks. Medicare reimbursement pathways for clinic-based procedures accelerate point-of-care adoption. Brisbane metropolitan hospitals adopt handheld units for triage acceleration.
Western Australia
Specialist shortages in remote regions drive mobile diagnostic unit deployment. Sparse population density stretches service technician response times, forcing remote diagnostic capability investment. Perth anchors the state's radiology infrastructure while Pilbara and Kimberley regions depend on fly-in-fly-out specialist services.
South Australia
Maintenance part scarcity accelerates retirement decisions for legacy analog systems in regional facilities. Adelaide metropolitan networks balance cost and performance through hybrid architecture transitional upgrades. The Barossa Valley and Fleurieu Peninsula clinic networks represent underserved penetration opportunities.
Australia Ultrasound Devices Market Competitive Environment
North American and European producers anchor the premium tier; Asian specialists hold mid-market positioning through cost-optimized manufacturing. The vendor base consolidates around three strategic archetypes: diversified healthcare conglomerates with established distribution infrastructure, pure-play imaging specialists with targeted R&D focus, and emerging platform vendors leveraging semiconductor advances. Dominant competitive moves include AI diagnostic feature integration and subscription-based equipment access models displacing traditional capital purchase arrangements.
Within the diversified healthcare conglomerate tier, GE Healthcare, Siemens Healthineers AG, and Koninklijke Philips N.V. occupy positions defined by sustained infrastructure investment across Australian tertiary hospital networks. These Netherlands, German, and US-origin entities exemplify archetypes ranging from distribution-anchored market presence to AI-integrated diagnostic platform development and portable system specialization for emergency and rural deployment.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers AG |
| Koninklijke Philips N.V. |
| Fujifilm Holdings Corporation |
| Mindray Medical |
| Canon Medical Systems Corporation |
| Samsung Medison |
| Esaote SPA |
| Hologic Inc. |
| Others |
Value Chain & Pricing Dynamics
Silicon wafer spot indices and rare-earth magnet pricing cascades through ultrasound device manufacturing tiers, compressing margins on entry-level portable units while AI-enabled diagnostic platforms maintain pricing power through software differentiation and TGA validation barriers.
Pricing Analysis
Distributor margins of 15-25 percent on cart-based systems and direct-to-hospital discounts on volume contracts stratify procurement economics across Australian health networks. Three-tier pricing structure across premium AI-integrated, standard digital, and economy analog levels reflects transducer array sophistication and computational hardware load. Cost compression in the portable segment intensifies as CMUT semiconductor fabrication matures and Asian specialists flood mid-market battery-operated units. Regional hospitals in Western Australia and South Australia exhibit highest price sensitivity due to constrained capital budgets, while metropolitan tertiary centers in Sydney prioritize performance specifications over unit cost.
Supply Chain Analysis
Ocean freight rate volatility from East Asian component hubs to Australian ports injects landed cost uncertainty into procurement cycles for piezoelectric crystal arrays and GPU chipsets. Manufacturing concentration in China, South Korea, and Japan for high-frequency transducer materials and Taiwan for semiconductor beamforming processors creates geographic dependency for Australian vendors. Single-source vulnerability in CMUT foundry capacity exposes procurement timelines to fab allocation decisions. Distribution runs through authorized medical device distributors with TGA establishment registration, supplemented by direct OEM service contracts for major metropolitan health networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australian ultrasound procurement has shifted toward late-cycle quality specifications as hospital networks prioritize AI-integrated diagnostic platforms with proven TGA software-as-a-medical-device registration over unvalidated point-of-care alternatives.
For Market Incumbents: To counter emerging CMUT-based handheld specialists from Asian semiconductor ecosystems, GE Healthcare and Siemens Healthineers AG should deepen backward integration into AI training dataset curation and secure exclusive radiology informatics partnerships with New South Wales and Victorian hospital networks. Certification investment in TGA software validation for cardiology and obstetrics algorithms preserves premium positioning against algorithm-native entrants. For New Entrants and Emerging Players: Underserved general practice networks in Tasmania and Northern Territory present viable beachheads for portable ultrasound platforms with embedded telemedicine transmission protocols. Subscription-based equipment access models align with Australian private radiology group preference for operational expenditure structures. A direct GPO contracting strategy bypasses incumbent distributor relationships in Queensland ambulatory care expansion zones. For Investors and Strategic Acquirers: Asymmetric upside sits with veterinary ultrasound crossover specialists possessing species-specific preset IP and established service networks in Australian companion animal clinic chains. Five-to-ten year viability hinges on platform modularity enabling human diagnostic pivot. The signal to watch is TGA alignment with FDA software pre-certification pathways accelerating AI diagnostic feature approval velocity.| Strategic Initiative | Industry Significance |
|---|---|
| TGA Software-as-a-Medical-Device Registration | Legitimizes AI diagnostic algorithms for Medicare reimbursement in Australian hospital procurement. |
| CMUT Semiconductor Platform Development | Collapses size-weight-performance tradeoffs enabling Queensland emergency department triage acceleration. |
| Rural Health Network Service Partnership | Captures long-term maintenance contracts in Western Australia fly-in-fly-out specialist coverage zones. |
| Telemedicine Integration Certification | Qualifies vendors for federal digital health infrastructure priority procurement lists. |
| Veterinary Diagnostic Preset Licensing | Opens adjacent revenue streams through Australian companion animal clinic chain partnerships. |
Study Parameters
Multiple input streams — structured interviews with biomedical engineers and hospital purchasing committees, GPO contract database analysis, and TGA registration filing review — were reconciled against secondary validation from CMS Medicare reimbursement schedules and Australian Institute of Health and Welfare procedure statistics. Bottom-up triangulation across portable and cart-based system shipments was cross-checked with top-down expenditure estimates from state health department capital budgets.
Data-stream reconciliation applied across product type, end user, technology platform, and clinical application dimensions over the projection horizon. CAGRs were derived from logistic diffusion curves fitted to replacement cycle data and federal rural health access mandate funding trajectories. Forecast inputs incorporated TGA software classification rule evolution and semiconductor foundry capacity allocation trends for CMUT fabrication.
Underlying measurement precision varies by segment; metropolitan hospital diagnostic system valuations carry tighter precision than remote mobile unit deployment estimates. Forecasts reflect assumptions on TGA approval timeline stability and Australian dollar exchange rate bands against East Asian component sourcing currencies. A model refresh is warranted upon material change in Therapeutic Goods Administration software evidentiary requirements or federal digital health interoperability standard adoption velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Middle East and Africa Non-Surgical Procedures Market
Medical Devices
Thermal Ablation Devices Market
Medical Devices
Europe Surgical Visualization Products Market
Medical Devices
Global Medical Implants Market
Medical Devices
Medical Polyimide Tubing Market
Medical Devices
India Artificial Organs and Bionics Market
Medical Devices
Waterproof Orthotics Market
Medical Devices
GCC and UAE Diabetes Devices Market
Medical Devices
MRI Guided Drug Delivery Market
Medical Devices
Interventional Cardiology Devices Market
Medical Devices
Asia-Pacific Intraoral Scanners Market
Medical Devices
Home-Use Water Flosser Market
Medical Devices
Craniomaxillofacial Devices Market
Medical Devices
Pulmonary Heart Valve Replacement Market
Medical Devices
Middle East and Africa Hip and Knee Reconstruction Devices Market
Medical Devices
Neuromuscular Transmission Monitor Market