
 Operating Room Integration Market | 2026-2036
Operating Room Integration Market Size, Share, and Industry Trends Forecast 2026-2036
Operating Room Integration Market Intelligence
The emphasis on energy efficiency within hospital infrastructure, underscored by initiatives like the EU Green Deal, is broadening the criteria for system selection to include power consumption and hardware longevity. Stryker Corporation leverages its extensive portfolio of surgical equipment to offer comprehensive integrated solutions. Siemens Healthineers positions its systems to seamlessly connect with its advanced imaging modalities. Steris PLC specializes in infection prevention and procedural products, integrating them into a cohesive OR environment for enhanced safety and workflow.
Operating room integration refers to the networking of disparate medical devices, audiovisual equipment, and information systems into a centralized control platform. These systems facilitate the routing of high-resolution video, often 4K UHD, and patient data in standardized formats like DICOM. The primary purpose is to streamline surgical workflows, enhance team communication, and improve access to critical information during procedures. Integrated displays and video management units constitute a significant portion of hardware sales, while demand for surgical navigation applications is accelerating.
Regulatory frameworks such as the FDA's requirements for medical device interoperability in the United States and the EU's Medical Device Regulation (MDR) mandate stringent data security and system validation. In Japan, compliance with standards set by the PMDA is essential for market access, influencing product development cycles. Stakeholders must now decide whether to prioritize scalable, cloud-based platforms or secure, on-premises solutions to meet evolving cybersecurity threats and data management needs.
Market Dynamics
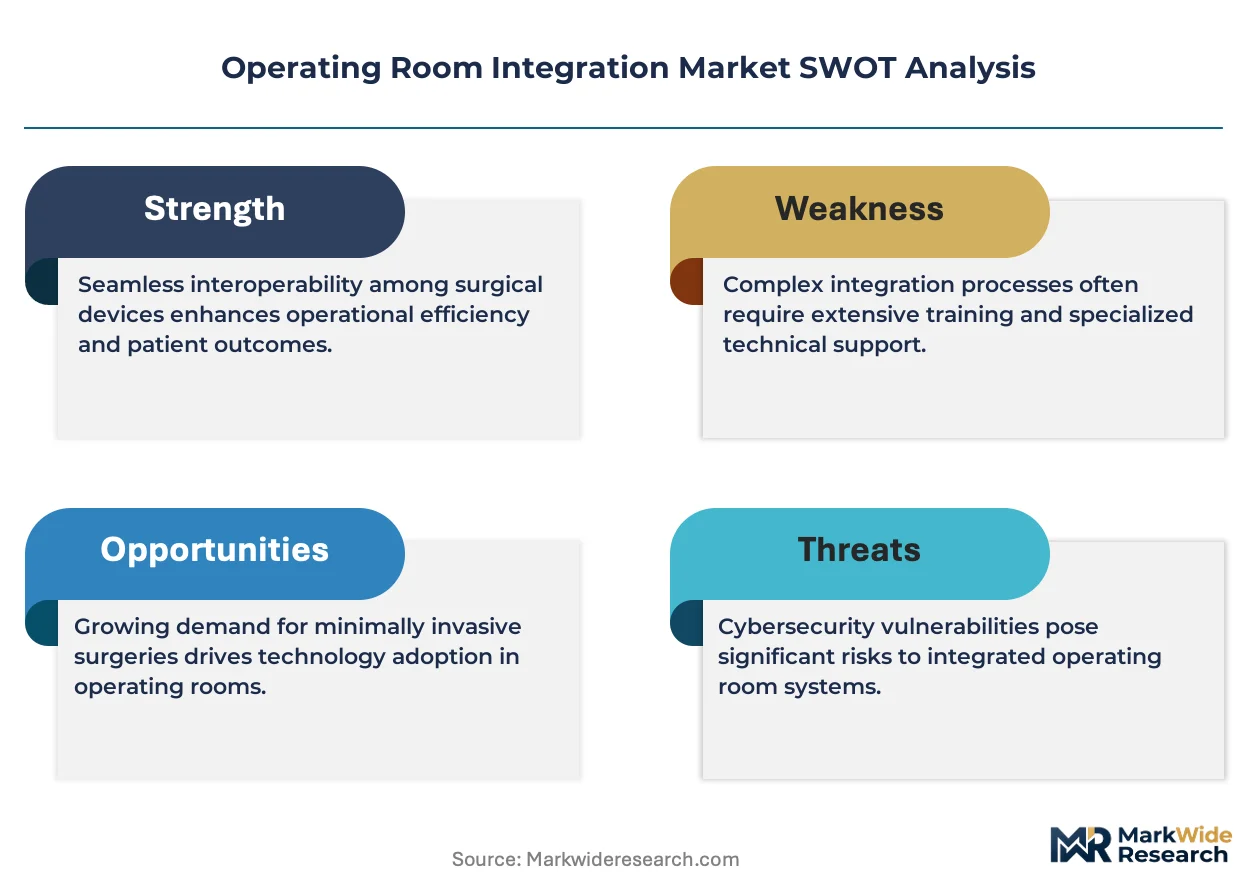
The central dynamic in the operating room integration market is the push for standardized, interoperable data exchange, driven by regulations like the EU's MDR, clashing with the escalating need for robust cybersecurity measures against network-connected device vulnerabilities.
Growth Catalysts
- Regulatory Mandates:The European Union's Medical Device Regulation (MDR) is compelling manufacturers to enhance device traceability and data integration, directly stimulating demand for systems that can meet these stringent documentation and connectivity requirements.
- Ambulatory Center Expansion:A rising volume of procedures performed in ambulatory surgery centers (ASCs) creates demand for integration systems that improve surgical workflow efficiency, patient throughput, and operational cost-effectiveness in outpatient settings.
- Advanced Visualization Demand:The adoption of 4K UHD and 3D imaging in surgery necessitates advanced video routing and management capabilities, pushing healthcare facilities to upgrade their OR infrastructure to handle high-bandwidth data streams.
Market Restraints
- High Capital Investment:The substantial upfront cost of purchasing and installing comprehensive OR integration systems, including hardware and software, presents a significant financial barrier for smaller hospitals and independent surgical centers.
- Legacy System Interoperability:Integrating new platforms with a hospital's existing, often proprietary, legacy medical devices and IT infrastructure creates significant technical complexity, compatibility issues, and potential workflow disruptions.
- Data Security Risks:The increased connectivity of surgical devices and systems introduces new vectors for cybersecurity attacks, raising concerns over patient data privacy and system integrity that can slow adoption.
Strategic Opportunities
- AI and Analytics Integration:Incorporating artificial intelligence and machine learning into OR platforms offers a significant opportunity to provide real-time decision support, predictive analytics on procedural workflows, and automated instrument tracking.
- Cloud-Based PaaS Models:Developing scalable, cloud-based Platform-as-a-Service (PaaS) solutions can lower the barrier to entry for smaller facilities by replacing large capital expenditures with predictable, subscription-based operational costs.
- Emerging Market Modernization:Targeting hospital infrastructure projects in rapidly developing economies, particularly in Southeast Asia and Latin America, provides new avenues for growth as these regions upgrade their surgical capabilities.
Industry Challenges
- Data Standardization Gaps:A lack of universal communication standards across all medical device manufacturers complicates the creation of truly vendor-neutral, plug-and-play integrated operating rooms, leading to integration challenges.
- Specialized Talent Shortage:A deficit of IT professionals and biomedical engineers with expertise in both medical device technology and modern network security protocols hinders the effective implementation and maintenance of these complex systems.
- Complex Regulatory Pathways:Navigating the intricate and varied regulatory approval processes for software as a medical device (SaMD) across different jurisdictions, such as from the FDA and PMDA, extends product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Operating Room Integration Market |
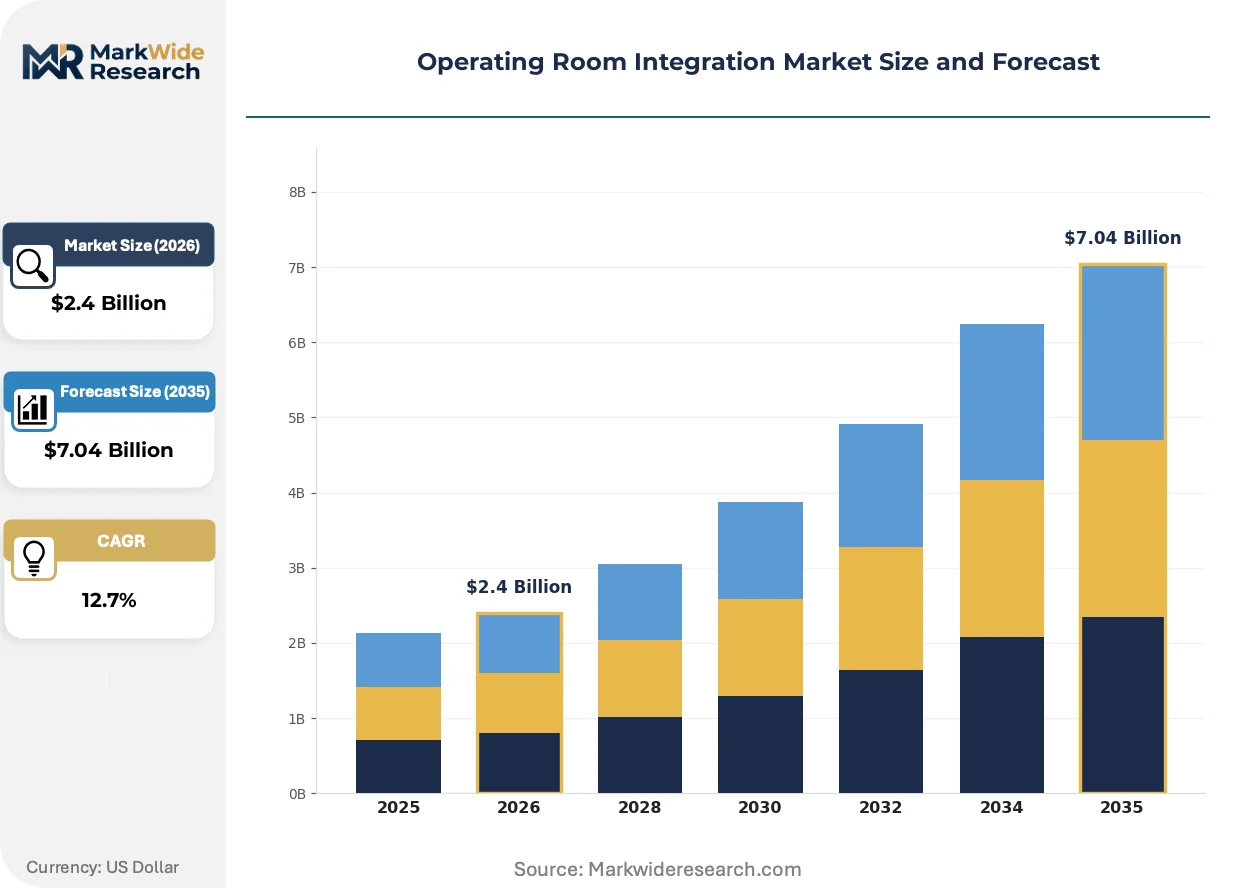
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $7.04 Billion |
| CAGR (2026 – 2036) | 12.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Systems, Integrated Displays, Control Consoles, Video Management Units, Networking Devices Application: Surgical Navigation, Patient Monitoring, Imaging Integration, Anesthesia Management, Communication Coordination End User: Ambulatory Centers, Surgical Clinics, Medical Universities, Specialty Procedure Suites Deployment Model: Cloud-Based, On-Premises, Hybrid Solutions, Managed Services |
| Companies Covered | Steris PLC, Drägerwerk AG & Co. KGaA, Stryker Corporation, Brainlab AG, Barco NV, Olympus Corporation, Getinge AB, Siemens Healthineers, Karl Storz SE & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Operating Room Integration Market Strategic Shifts & Innovations
The convergence of data management and audiovisual technologies is defining the next generation of surgical environments. This evolution moves beyond simple device connectivity toward creating intelligent, context-aware platforms that actively support surgical teams and automate non-clinical tasks for improved efficiency and safety.
Vendor-neutral archives (VNAs) and interoperability platforms using standards like DICOM are central to modern OR integration. Large hospital networks and consolidated health systems are rapidly adopting these technologies to break down proprietary data silos between departments. This technology is unifying disparate imaging modalities, patient data from EHRs, and live video sources into a single, cohesive interface for the entire surgical team.
In Japan, the Pharmaceutical and Medical Devices Agency (PMDA) is enforcing stricter requirements for software as a medical device (SaMD) and cybersecurity. This policy shift mandates more rigorous pre-market validation and vulnerability management for all network-connected OR systems. The surgical navigation and robotic-assisted surgery segments are most affected, as developers must now integrate comprehensive cybersecurity plans into their product lifecycle for market access.
A clear shift is occurring from one-time capital equipment purchases toward managed service agreements and subscription-based software licensing. This model disrupts the traditional sales channel, as hospitals seek predictable operational expenses and continuous access to the latest technology without large upfront capital outlays. This procurement trend is most visible in the United States and Western Europe, where healthcare networks prioritize financial flexibility and long-term vendor partnerships.
Operating Room Integration Market Segmentation
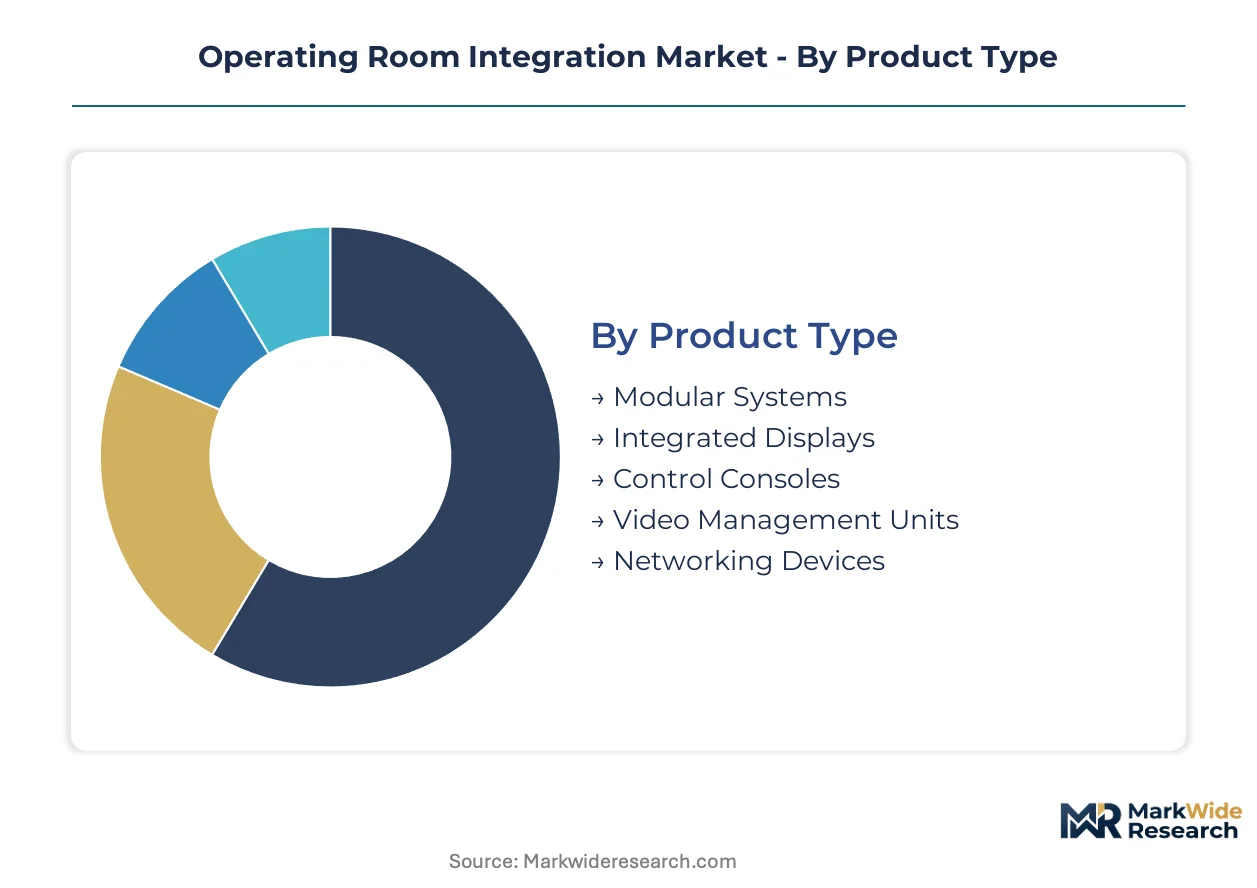
The operating room integration market segments reflect diverse technological requirements and user preferences across healthcare settings. Understanding these distinctions helps stakeholders identify specific investment areas and tailor solutions to address unique operational demands. This segmentation provides clarity on the various components and applications driving market expansion.
Product Type:
Buyer priorities in product type often differentiate based on immediate infrastructure needs and desired levels of system modularity. Some facilities require comprehensive upgrades, while others seek targeted enhancements for specific functions.
- Integrated Displays:These high-resolution monitors, frequently 4K UHD, present critical patient data and live surgical video within the sterile field. Demand concentrates in advanced surgical suites seeking enhanced visual clarity for complex procedures.
- Video Management Units:These systems manage and route multiple video inputs and outputs, including 4K UHD streams, across the integrated OR. Large hospital networks drive demand for these units to centralize video distribution and archiving.
- Modular Systems:These configurable platforms allow healthcare facilities to build integrated ORs in phases, adapting to budget cycles.
- Control Consoles:These central interfaces provide surgeons and staff with intuitive control over various integrated devices and systems.
- Networking Devices:These components ensure secure and high-bandwidth data transfer between all connected OR devices and hospital IT networks.
Volume sits with Integrated Displays; growth tilts toward Video Management Units.
Application:
The functional requirements of operating room integration vary significantly based on the surgical specialty and procedural complexity. Different applications address distinct challenges within the surgical workflow.
- Surgical Navigation:These applications provide real-time guidance to surgeons using imaging data, enhancing precision during intricate procedures. Demand for surgical navigation is accelerating in orthopedic and neurosurgical specialties across the United States.
- Imaging Integration:This involves unifying diverse imaging modalities, such as MRI and CT scans, with live video feeds and EHR data into a single interface. Large hospital networks widely adopt imaging integration to break down proprietary data silos.
- Patient Monitoring:Integrated systems display vital signs and physiological data from various devices directly within the OR environment.
- Anesthesia Management:These applications streamline the delivery and monitoring of anesthetic agents, integrating with patient data for enhanced safety.
- Communication Coordination:Systems facilitate seamless audio and video communication between the surgical team and remote specialists or consultation rooms.
The most prevalent application is Patient Monitoring, while Surgical Navigation is experiencing the steepest expansion trajectory.
End User:
The scale of operations and investment capacity are primary differentiators among end-user segments for integrated OR solutions. Each type of facility has unique infrastructure and patient throughput objectives.
- Ambulatory Centers:These outpatient facilities prioritize integration systems that optimize surgical workflow efficiency and patient throughput for same-day procedures. The rising volume of procedures performed in these centers drives significant demand.
- Specialty Procedure Suites:Dedicated suites for specific surgical disciplines, often within larger hospitals, require highly customized integration to support advanced technologies. Investment in these suites is strong in the United States.
- Surgical Clinics:Smaller facilities focus on cost-effective integration solutions that enhance basic procedural safety and data accessibility.
- Medical Universities:These institutions utilize integrated ORs for surgical training, research, and live case broadcasting to educational audiences.
Ambulatory Centers currently account for the largest share of deployments; Specialty Procedure Suites are gaining share fastest.
Deployment Model:
Customer preferences for deployment models hinge on factors like cybersecurity posture, capital expenditure budgets, and IT resource availability. Decisions often balance control with operational flexibility.
- Cloud-Based:These solutions offer scalability and reduced upfront capital expenditure, providing access to integrated OR functionalities via subscription models. Smaller facilities and those prioritizing operational costs often prefer cloud-based platforms.
- On-Premises:These solutions involve hardware and software installed and managed directly within the hospital's own infrastructure, offering maximum data control and security. Large hospital networks often opt for on-premises solutions due to stringent regulatory frameworks.
- Hybrid Solutions:These models combine elements of both cloud and on-premises deployments, balancing data security with remote access capabilities.
- Managed Services:Providers handle the full lifecycle of OR integration, including installation, maintenance, and upgrades, for a predictable fee.
On-Premises solutions dominate established markets, while Cloud-Based models are expanding most quickly among new deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The operating room integration market exhibits a notable production-consumption divide, with advanced economies driving innovation and demand for sophisticated systems, while emerging regions focus on infrastructure modernization. Regulatory environments significantly influence market adoption and product development across diverse geographies. Investment patterns reflect differing healthcare priorities and economic capacities.
United States
Demand for OR integration systems in the United States stems from hospital network consolidation and investment in specialty procedure suites. The FDA's requirements for medical device interoperability mandate stringent data security and system validation. Major metropolitan areas like Boston and Houston serve as hubs for medical technology innovation and adoption, fostering integrated OR solutions.
Germany
European Union's Medical Device Regulation (MDR) strongly influences the German market, pushing manufacturers to enhance device traceability and data integration. Energy efficiency within hospital infrastructure, underscored by the EU Green Deal, broadens system selection criteria. The Rhine-Main region, including cities like Frankfurt, sees significant adoption of advanced medical imaging and integration technologies.
Japan
Compliance with standards set by the Pharmaceutical and Medical Devices Agency (PMDA) is essential for market access in Japan, influencing product development cycles. The PMDA's stricter requirements for software as a medical device (SaMD) and cybersecurity mandate rigorous pre-market validation. Tokyo and Osaka remain key centers for advanced surgical robotics and integrated OR deployments.
Brazil
Modernization efforts in hospital infrastructure across Brazil provide new avenues for growth in operating room integration. Investment in upgrading surgical capabilities drives demand for efficient workflow solutions and advanced visualization. São Paulo and Rio de Janeiro lead in adopting integrated systems to enhance patient throughput and operational cost-effectiveness.
India
Healthcare infrastructure projects in India contribute to the rising demand for integrated OR solutions, particularly in rapidly developing urban centers. The need for improved surgical efficiency and patient safety in a growing healthcare sector fuels adoption. Cities like Bengaluru and Mumbai are witnessing increased investment in advanced medical technologies and integrated surgical suites.
Operating Room Integration Market Key Industry Players
The competitive structure tilts toward established medical technology conglomerates offering comprehensive integrated solutions, alongside specialized firms focusing on niche components. The market features a mix of large-scale providers and innovative smaller players. Dominant competitive moves include portfolio diversification to offer end-to-end solutions and strategic partnerships to enhance technological capabilities.
Within the integrated solutions tier, Stryker Corporation leverages its extensive surgical equipment portfolio to provide comprehensive offerings. Siemens Healthineers positions its systems to seamlessly connect with its advanced imaging modalities, exemplifying a focus on imaging integration. Steris PLC, specializing in infection prevention and procedural products, integrates these into a cohesive OR environment for enhanced safety and workflow.
| Leading Market Players |
|---|
| Steris PLC |
| Drägerwerk AG & Co. KGaA |
| Stryker Corporation |
| Brainlab AG |
| Barco NV |
| Olympus Corporation |
| Getinge AB |
| Siemens Healthineers |
| Karl Storz SE & Co. KG |
| Others |
Cost & Logistics Intelligence
The EU Green Deal's emphasis on energy efficiency gates qualified supply access and influences premium-tier pricing for compliant OR integration systems. This mandate drives hardware longevity requirements and shapes component sourcing decisions.
Pricing Analysis
Outcome-based pricing, tied to improved patient throughput and operational uptime, anchors OR integration system valuations. Subscription-based software licensing and managed service agreements represent dominant pricing models, alongside project-based hardware installations. Customization levels for specialty procedure suites and comprehensive after-sales service drive significant price differentiation. Pricing softness stems from smaller facilities seeking predictable operational expenses over large capital outlays, making Ambulatory Centers highly price-sensitive, while large hospital networks prioritize long-term value.
Supply Chain Analysis
Direct sales teams and specialized medical technology distributors manage the complex delivery of OR integration systems. Supply concentration for advanced components centers in Germany, Japan, and the United States, particularly for high-resolution displays and specialized networking devices. The market draws from a global base of advanced imaging sensors and custom software modules. Single-source vulnerability for highly specialized components poses a structural supply chain risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates under a supply constraint, primarily due to the limited availability of specialized IT and biomedical engineering talent. This talent bottleneck props up pricing for comprehensive integration services and complex system implementations.
For Market Incumbents: Extend existing product portfolios to offer full-suite, end-to-end integrated OR solutions, mitigating the threat from niche component specialists. Consolidate market share by acquiring smaller firms with advanced AI and analytics capabilities, enhancing real-time decision support. Invest in certification for new regulatory mandates like the EU MDR to maintain market access and differentiate offerings. Develop robust cybersecurity frameworks to counter network-connected device vulnerabilities and build customer trust.
For New Entrants and Emerging Players: Value-added resellers offer a viable go-to-market angle by targeting underpenetrated ambulatory centers and surgical clinics with cloud-based PaaS models. Focus on developing modular systems that integrate seamlessly with legacy infrastructure, addressing a significant technical complexity. Specialize in surgical navigation applications for orthopedic and neurosurgical specialties, where demand is accelerating. Prioritize compliance with regional regulatory frameworks like the FDA's interoperability requirements for faster market entry.
For Investors and Strategic Acquirers: Increased adoption of cloud-based PaaS models is the leading indicator that the market's long-term viability favors subscription-based revenue streams. Identify acquisition targets with proprietary AI algorithms for real-time surgical support or robust cybersecurity platforms. The shift from capital expenditure to operational expenditure models signals a need for financially flexible solutions. Monitor regulatory updates from the PMDA and FDA for their impact on product development cycles and market access.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Powered Decision Support | Enhances surgical precision and automates non-clinical tasks for improved efficiency. |
| Cloud-Based PaaS Development | Lowers entry barriers for smaller facilities, shifting to predictable operational costs. |
| Cybersecurity Integration | Addresses data security risks and meets stringent regulatory requirements for connected devices. |
| Emerging Market Expansion | Captures growth in rapidly developing economies upgrading their hospital infrastructure. |
| MDR Compliance Programs | Ensures market access in the European Union and validates device traceability. |
Research Approach
Independent corroboration across clinician interviews, hospital procurement committee discussions, and biomedical engineer field reports underwrites the qualitative findings of this study. Primary interviews with GPO contracts managers and medical device R&D directors further informed market dynamics. Secondary validation involved analysis of FDA filings, PMDA guidelines, and EU MDR documentation. This approach employed both bottom-up and top-down triangulation.
Rate-of-change decomposition modeled market expansion across the analysis window, considering product type, application, end-user, and deployment model. The framework also integrated regional regulatory clusters and technological adoption rates as key dimensions. Compound annual growth rates were derived from historical data trends and projected market drivers. Forecast inputs included surgical procedure volumes and hospital infrastructure investment trends.
Caveats apply where unforeseen shifts in medical device interoperability standards or major cybersecurity breaches could materially shift the outlook. Forecasts reflect assumptions regarding healthcare spending and regulatory stability. Practitioners should monitor new regulatory mandates and technological breakthroughs for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
North America Portable Medical and Healthcare Devices Market
Medical Devices
India Anesthesia Devices Market
Medical Devices
Medical Hydrophilic Coatings Market
Medical Devices
Medical LED Headlight Market
Medical Devices
Global Medical Kiosk Market
Medical Devices
China Aesthetic Devices Market
Medical Devices
Transcatheter Bioprosthesis Market
Medical Devices
Australia Contraceptive Devices Market
Medical Devices
Electrocautery Devices Market
Medical Devices
Intraoperative Sensor Market
Medical Devices
Knee Reconstruction Devices Market
Medical Devices
Struts Implants Market
Medical Devices
Wrist Fixator Procedure Kit Market
Medical Devices
Chronic Total Occlusion Devices Market
Medical Devices
North America Insulin Delivery Devices Market
Medical Devices
Cough Assist Devices Market