
 Soft Tissue Markers Market | 2026-2036
Soft Tissue Markers Market Size, Share, and Industry Trends Forecast 2026-2036
Soft Tissue Markers Market Analytics
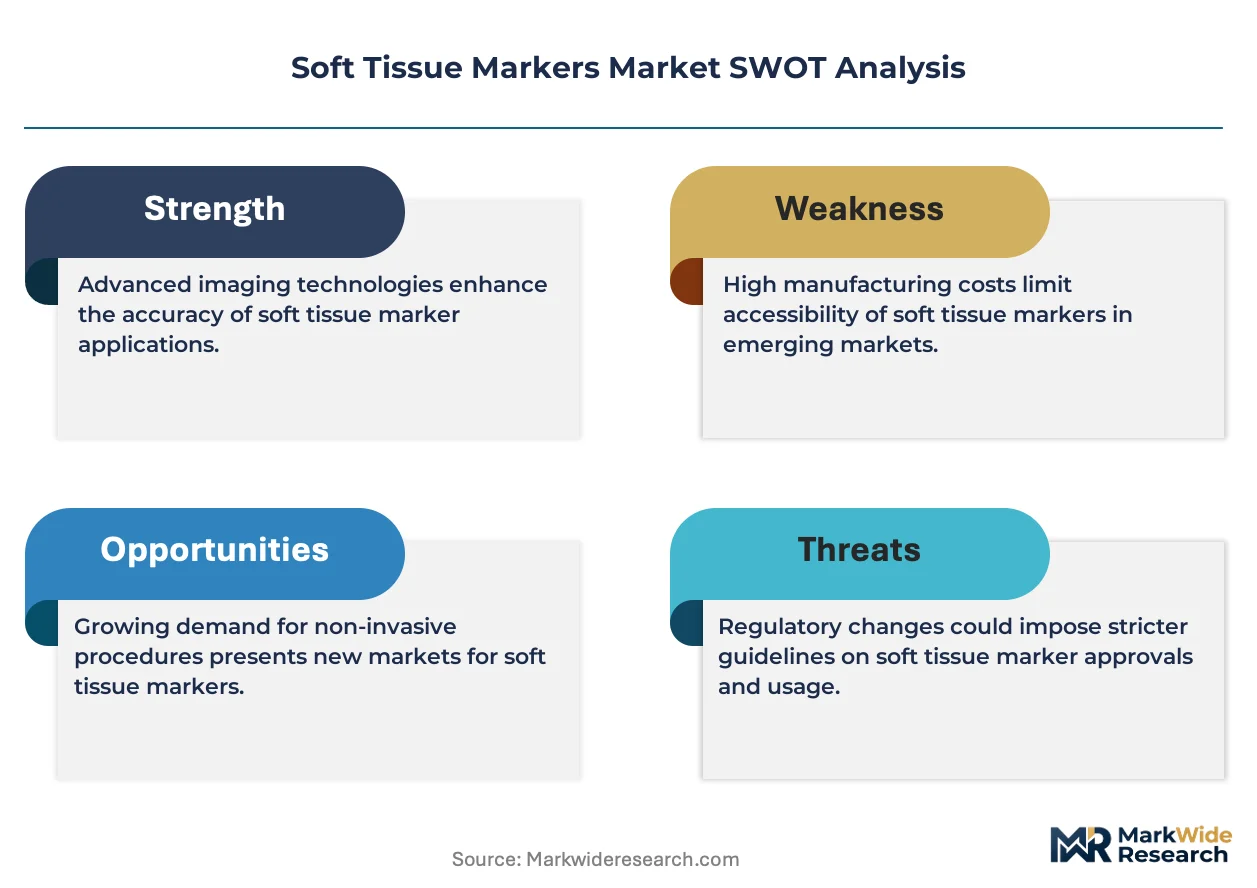
The gap between premium and commodity tiers is broadening as imaging resolution demands split product specifications. BD anchors its position through backward integration into biocompatible polymer supply chains. Hologic differentiates via proprietary ultrasound-visible marker architectures that command higher reimbursement rates.
Soft tissue markers are implantable devices placed during biopsy or surgical procedures to identify lesion locations for subsequent imaging or excision, typically manufactured from titanium, stainless steel, or polymers with radiopaque fillers to ensure visibility under X-ray, ultrasound, or MRI modalities. Biopsy markers occupy the largest volume share as core needle biopsy volumes rise across outpatient settings, while imaging markers represent the fastest-expanding margin pool as multimodal visibility becomes standard. Radiology applications sustain premium pricing due to procedural complexity and reimbursement alignment, whereas orthopedic applications compete on cost efficiency.
The FDA governs soft tissue markers as Class II medical devices under 510(k) premarket notification pathways, while the EU MDR imposes stricter clinical evidence requirements for implantable markers sold in Europe. Health Canada's PMRA and Australia's TGA enforce biocompatibility testing protocols that manufacturers must satisfy for market access. Stakeholders must monitor evolving radiopacity standards across jurisdictions to align product development with divergent regulatory timelines.
Market Dynamics
Integrated delivery networks in the United States are consolidating procurement authority across multi-site cancer centers, compressing vendor lists and forcing manufacturers to demonstrate total cost-of-ownership advantages beyond unit pricing.
Growth Catalysts
- Rising core needle biopsy volumes:Outpatient oncology clinics in the United States are expanding same-day biopsy services, driving implant volumes for titanium and polymer-based localization devices.
- FDA 510(k) pathway efficiency:The premarket notification framework for Class II implantable devices accelerates time-to-market for radiopaque marker innovations relative to European regulatory timelines.
- Multimodal imaging adoption:MRI-ultrasound fusion platforms in radiology departments require markers with simultaneous visibility across modalities, upgrading replacement demand.
Market Restraints
- Titanium feedstock concentration:Sponge production concentrates in a limited supplier base, exposing marker manufacturers to input cost volatility and long-term contract renegotiation cycles.
- EU MDR clinical evidence burden:Stricter biocompatibility documentation requirements for implantable devices extend European market entry timelines and inflate regulatory compliance spending.
- Non-implantable localization alternatives:Wire-guided and radar-based non-implant systems compete for breast lesion localization cases, pressuring marker pricing in select oncology applications.
Strategic Opportunities
- Underpenetrated outpatient surgery centers:Ambulatory surgical facilities in the United States lack standardized marker protocols, creating white space for procedure-specific product bundles and training programs.
- Bioresorbable polymer convergence:Polylactic acid and polyglycolic acid formulations that eliminate secondary removal procedures align with patient preference trends in cosmetic-sensitive applications.
- Integrated delivery network procurement centralization:Multi-hospital systems negotiating enterprise contracts reward vendors with logistics integration and consignment inventory capabilities.
Industry Challenges
- Biocompatibility testing bottlenecks:ISO 10993 cytotoxicity and sensitization studies face laboratory capacity constraints, delaying product launches and inflating preclinical timelines.
- Legacy PACS integration complexity:Marker visibility standardization across disparate radiology information systems requires custom DICOM configuration, fragmenting technical support demands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soft Tissue Markers Market |
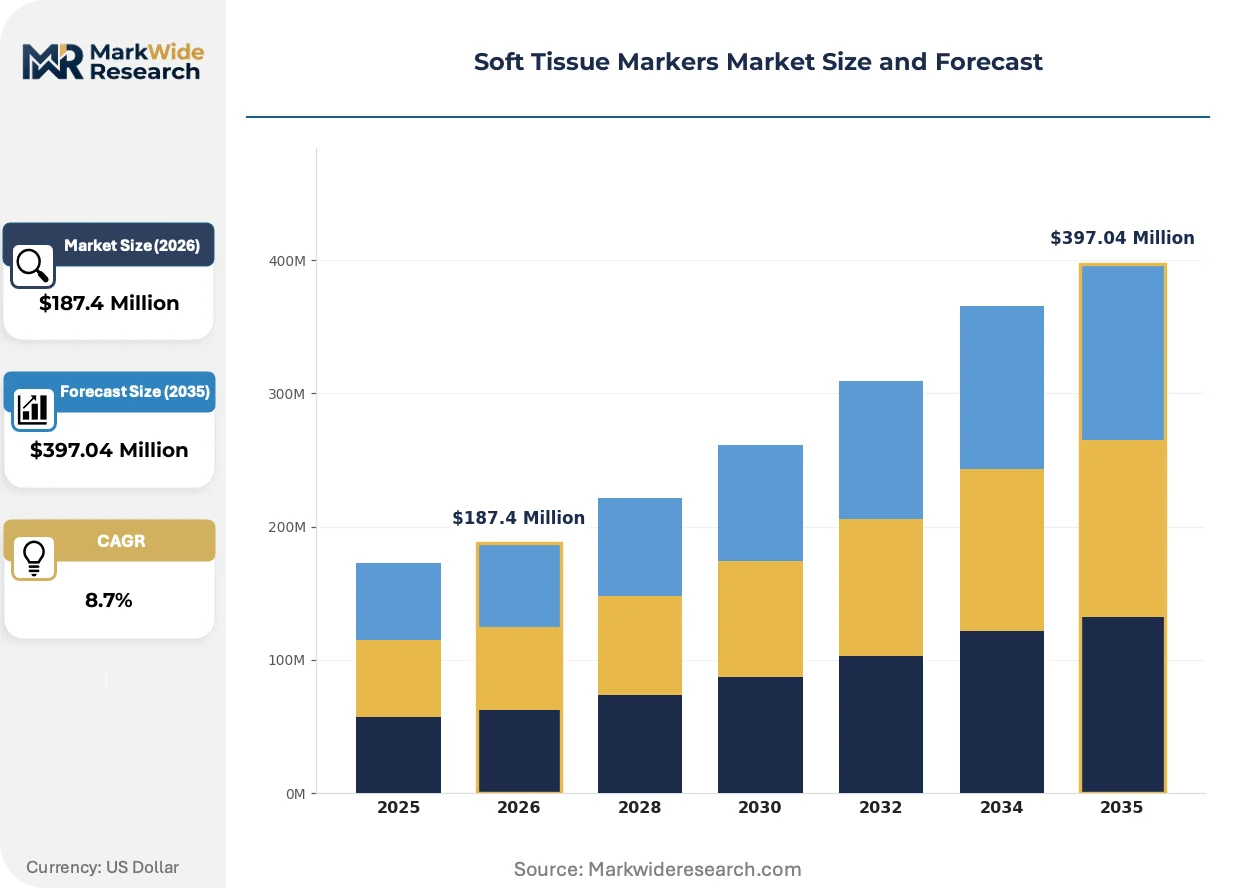
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biopsy Markers, Localization Markers, Imaging Markers, Surgical Markers Application: Oncology, Orthopedics, Cardiology, Radiology End User: Hospitals, Diagnostic Centers, Research Laboratories, Outpatient Facilities Delivery Mode: Injectable, Wire, Clip, Others |
| Companies Covered | BD, Hologic, INRAD, Carbon Medical Technologies, Mermaid Medical, CIVCO Medical Solutions, Medtronic, IZI Medical Products, Mammotome, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soft Tissue Markers Market Evolving Landscape
Marker visibility standards are fragmenting across imaging modalities as radiology departments deploy hybrid MRI-ultrasound systems and 3D mammography platforms with divergent contrast requirements.
Ultrasound-visible polymer architectures with proprietary echogenic surface patterning are converging with traditional radiopaque metal cores, enabling single-implant multimodal localization that eliminates the need for dual-marker placement procedures in breast biopsy workflows.
The FDA's updated guidance on radiopaque implantable devices tightens material verification requirements for titanium alloy compositions and polymer filler distributions, compelling manufacturers to implement spectroscopic testing protocols that extend quality assurance cycles but reduce adverse event reporting exposure.
Hospital supply chain directors are consolidating vendor relationships through value-analysis committees that evaluate total procedural cost rather than unit price, rewarding marker suppliers with consignment inventory programs and direct-to-procedure-cart logistics integration in high-volume United States cancer centers.
Soft Tissue Markers Market Segmentation
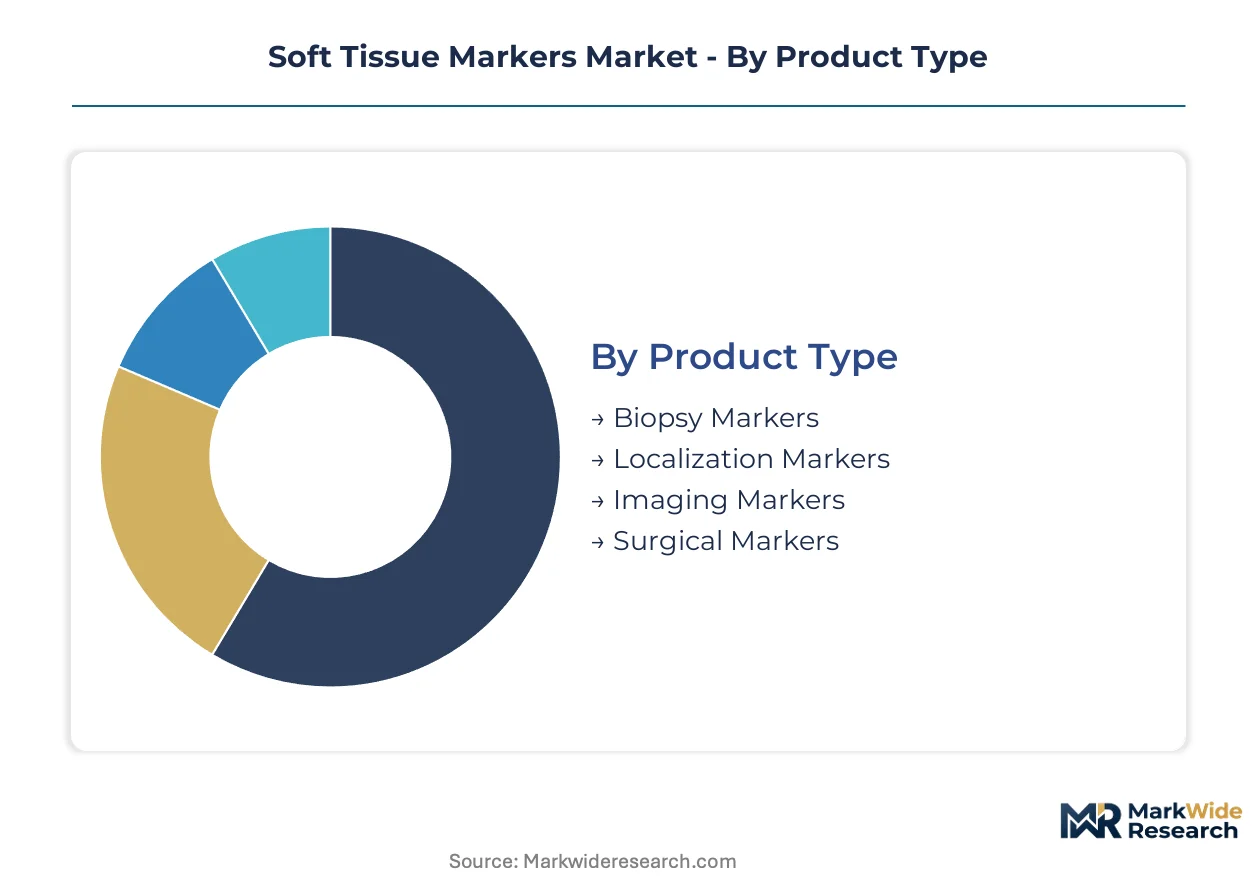
Soft tissue marker segmentation reflects divergent clinical workflows and reimbursement economics. Product specifications split between high-volume biopsy applications and premium multimodal imaging platforms, while end-user concentration in hospital systems reshapes distribution requirements.
Product Type:
Volume concentrates in single-modality metal markers, while premium margins accrue to polymer architectures with engineered visibility across imaging platforms.
- Biopsy Markers:Titanium and stainless steel devices with standardized radiopacity dominate core needle biopsy procedures. United States outpatient oncology clinics drive implant volumes as same-day diagnostic services expand, though titanium feedstock concentration exposes manufacturers to contract renegotiation cycles.
- Imaging Markers:Polymer formulations with proprietary echogenic surface patterning enable simultaneous MRI-ultrasound visibility. Radiology departments deploying fusion platforms in the United States upgrade replacement demand, commanding higher reimbursement rates through multimodal functionality.
- Localization Markers:Deployed for pre-surgical lesion marking with emphasis on dimensional stability.
- Surgical Markers:Designed for intraoperative placement with compatibility across excision workflows.
Today's leader: Biopsy Markers. Tomorrow's challenger: Imaging Markers.
Application:
Revenue gravity shifts from cost-competitive orthopedic localization toward oncology workflows with aligned reimbursement and procedural complexity premiums.
- Oncology:Breast and soft tissue tumor localization commands premium pricing through integrated delivery network procurement. United States cancer centers standardize marker protocols across multi-site systems, compressing vendor lists while elevating total cost-of-ownership requirements.
- Radiology:Multimodal visibility specifications for MRI-ultrasound fusion and 3D mammography platforms sustain technical barriers. FDA 510(k) pathway efficiency accelerates United States market entry relative to European MDR timelines, concentrating innovation investment.
- Orthopedics:Competes on unit cost efficiency with pressure from commodity titanium sourcing.
- Cardiology:Emerging deployment for structural heart procedure marking with evolving visibility standards.
Oncology commands current revenue concentration. Radiology represents the steepest expansion trajectory.
End User:
Procurement authority centralization favors vendors with logistics integration over pure product differentiation.
- Hospitals:Value-analysis committees evaluate total procedural cost rather than unit price, rewarding consignment inventory and direct-to-procedure-cart capabilities. United States integrated delivery networks negotiate enterprise contracts spanning multi-site cancer centers.
- Outpatient Facilities:Ambulatory surgical centers lack standardized marker protocols, creating white space for procedure-specific bundles. Training program requirements and inventory management systems determine vendor selection in this fragmented channel.
- Diagnostic Centers:Focus on high-throughput biopsy services with emphasis on workflow efficiency.
- Research Laboratories:Specialized requirements for investigational device protocols and custom specifications.
Hospitals anchor procurement volume. Outpatient Facilities offer the fastest penetration opportunity.
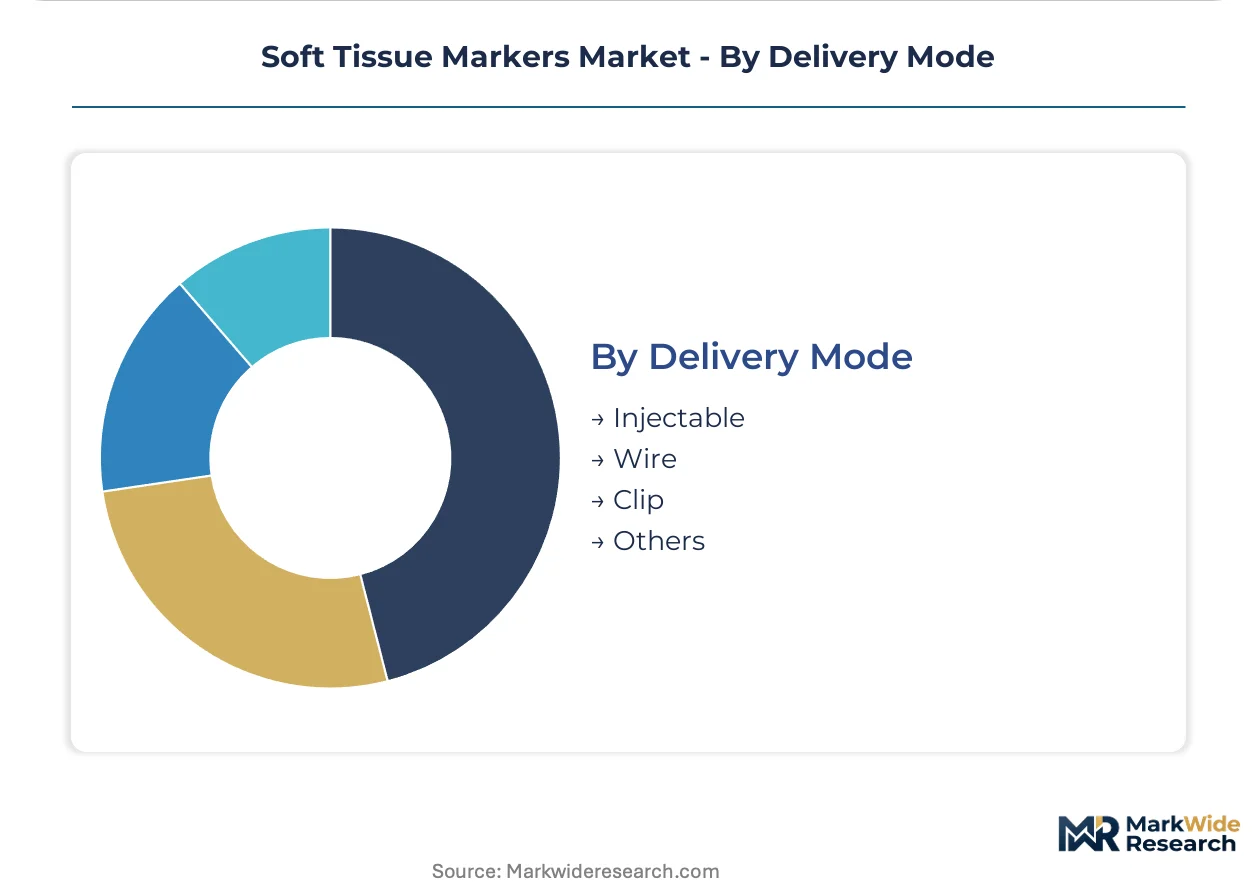
Delivery Mode:
Placement mechanism selection reflects lesion characteristics, imaging modality compatibility, and physician training pathways.
- Injectable:Polymer and metal particulate suspensions enable minimally invasive deployment through standard biopsy needles. United States outpatient clinics favor injectable formats for same-day procedures, aligning with patient throughput targets.
- Wire:Traditional hookwire systems face competitive pressure from implantable alternatives in breast localization.
- Clip:Mechanical fixation devices for specific tissue types and excision requirements.
- Others:Emerging radar-based and magnetic localization technologies competing for select applications.
Injectable formats dominate current utilization. Clip and emerging modalities challenge in specialized workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands procurement volume through integrated delivery network consolidation, while Germany faces extended regulatory timelines under EU MDR clinical evidence requirements that compress market entry velocity for implantable device manufacturers.
United States
Outpatient oncology clinics in Texas and Florida are expanding same-day biopsy services, driving titanium marker implant volumes through high-throughput ambulatory networks. The FDA's 510(k) premarket notification pathway accelerates time-to-market for radiopaque innovations relative to European counterparts. Hospital value-analysis committees in the Southeast negotiate enterprise contracts spanning multi-site cancer centers in Georgia and North Carolina.
Germany
University hospitals in Bavaria and North Rhine-Westphalia deploy MRI-ultrasound fusion platforms that demand multimodal marker visibility specifications. The EU MDR imposes stricter biocompatibility documentation requirements for implantable devices, extending regulatory compliance timelines. Medical technology clusters around Munich and Düsseldorf concentrate manufacturing capabilities for polymer-based localization devices.
Japan
Metropolitan Tokyo cancer centers standardize marker protocols across prefectural hospital networks, concentrating procurement authority in the Kanto region. PMDA reviews Class II implantable devices under streamlined pathways that favor manufacturers with prior FDA clearance. Osaka-based distributors manage logistics integration for consignment inventory programs serving high-volume biopsy facilities.
China
Provincial cancer hospitals in Jiangsu and Guangdong provinces are upgrading to 3D mammography platforms with divergent radiopacity requirements. NMPA regulates soft tissue markers as Class III medical devices, imposing clinical trial requirements that extend registration timelines. The Yangtze River Delta manufacturing corridor hosts polymer compounding facilities supplying domestic marker producers.
Australia
Diagnostic imaging networks in New South Wales and Victoria are consolidating procurement through national purchasing cooperatives. TGA enforces ISO 10993 biocompatibility testing protocols that manufacturers must satisfy for market access. Sydney and Melbourne radiology departments drive replacement demand for ultrasound-visible marker architectures.
Soft Tissue Markers Market Competitive Landscape
Top-tier vendors anchor premium multimodal imaging segments, while mid-scale specialists compete on cost efficiency in high-volume biopsy applications. The vendor base stratifies across three archetypes: diversified medical device conglomerates with backward integration into polymer supply chains, radiology-focused specialists with proprietary echogenic surface technologies, and regional fabricators serving price-sensitive orthopedic localization workflows. Dominant competitive moves include strategic partnerships with integrated delivery networks for consignment inventory programs and technology licensing agreements for MRI-compatible material formulations.
Within the diversified conglomerate tier, BD and Medtronic exemplify scale-driven positioning through captive supply chain control and multi-modality portfolio breadth. Hologic occupies a distinct archetype as a radiology-focused specialist, anchoring premium-tier positioning through proprietary ultrasound-visible architectures that command favorable reimbursement alignment. Among regional specialists, CIVCO Medical Solutions and IZI Medical Products represent mid-scale competitors concentrating on procedure-specific bundles and training program integration for ambulatory surgical channels.
| Leading Market Players |
|---|
| BD |
| Hologic |
| INRAD |
| Carbon Medical Technologies |
| Mermaid Medical |
| CIVCO Medical Solutions |
| Medtronic |
| IZI Medical Products |
| Mammotome |
| Others |
Value Network & Pricing Analysis
Integrated delivery networks in the United States concentrate procurement authority across multi-site cancer centers, compressing vendor lists and forcing manufacturers toward total cost-of-ownership pricing models that bundle consignment inventory with procedure-cart logistics.
Pricing Analysis
Bundled service contracts dominate enterprise negotiations with hospital value-analysis committees, while unbundled per-unit transactions persist in fragmented outpatient surgical channels. Three-tier pricing structure across premium multimodal markers, standard radiopaque devices, and economy titanium cores reflects differentiation by imaging modality compatibility and biocompatibility certification grade. Cost compression in the economy tier intensifies because titanium feedstock volatility squeezes contract manufacturers serving price-sensitive orthopedic applications. Ambulatory surgical centers exhibit highest price sensitivity due to capital constraints, whereas integrated delivery networks prioritize logistics integration over unit cost.
Supply Chain Analysis
Domestic-content mandates in China's NMPA registration pathways and India's phased manufacturing programs are reshaping sourcing patterns for polymer compounding and metal finishing operations. Titanium sponge production draws from concentrated suppliers in China, Japan, and Russia, while biocompatible polymer formulations rest on specialized compounding capabilities in Germany and the United States. Single-source vulnerability in medical-grade titanium alloy supply exposes marker manufacturers to contract renegotiation cycles and input cost volatility. Distribution runs through GPO-affiliated distributors serving hospital systems alongside direct consignment programs with integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where manufacturers leverage FDA 510(k) pathway efficiency to capture United States revenue before navigating EU MDR clinical evidence burdens that extend European market entry timelines and inflate compliance spending.
For Market Incumbents: Hedge titanium feedstock exposure through long-term offtake agreements with sponge producers in Japan and alternative alloy qualification programs. Secure backward integration into biocompatible polymer compounding to defend margin position against commodity pressure from regional fabricators. Prioritize consignment inventory capabilities that align with integrated delivery network procurement centralization. For New Entrants and Emerging Players: Ambulatory surgical centers represent the most penetrable channel due to absence of standardized marker protocols and limited vendor relationships. Target procedure-specific bundles combining training programs with injectable polymer formats for same-day biopsy workflows. Pursue partnerships with regional distributors managing logistics integration for outpatient facilities in Texas and Florida. For Investors and Strategic Acquirers: Diversified medical device conglomerates are the most active acquirer in this space, seeking radiology-focused specialists with proprietary echogenic surface technologies. Long-term viability hinges on multimodal imaging convergence and bioresorbable polymer adoption curves. Monitor FDA adverse event reporting databases for material verification failures as an inflection indicator for quality-assurance differentiation.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Expedites United States market entry ahead of EU MDR clinical evidence timelines. |
| Hospital System Partnership | Secures enterprise contracts with integrated delivery networks through consignment inventory integration. |
| Bioresorbable Polymer Development | Aligns product pipelines with patient preference trends in cosmetic-sensitive oncology applications. |
| Backward Integration into Polymer Supply | Captures margin pool from biocompatible compounding and reduces feedstock volatility exposure. |
| Reimbursement Strategy | Positions multimodal visibility markers for favorable coding alignment in radiology fusion platforms. |
Research Methodology
Multiple input streams — primary interviews with hospital purchasing committees, biomedical engineers, and GPO contracts managers; secondary validation through FDA 510(k) filings, CMS Medicare reimbursement databases, and hospital procurement records; plus trade data from customs authorities — were reconciled through bottom-up implant volume modeling and top-down market sizing triangulation.
Data-stream reconciliation across product type, application, end user, and delivery mode dimensions anchored the analytical framework over the projection horizon. CAGRs were derived from segment-level growth trajectory modeling incorporating core needle biopsy volume expansion, multimodal imaging platform deployment rates, and integrated delivery network procurement consolidation patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU MDR enforcement variability, titanium alloy supply disruptions, and non-implantable localization technology substitution rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Elbow Fixation Systems Market
Medical Devices
Next-Generation Neurofeedback Device Market
Medical Devices
Europe Viscosupplementation Market
Medical Devices
Asthma Inhaler Device Market
Medical Devices
North America Intraocular Lens Market
Medical Devices
Reprocessed Medical Devices Market
Medical Devices
Aesthetic Devices Market
Medical Devices
North America Electrophysiology Market
Medical Devices
South Korea Drug Delivery Devices Market
Medical Devices
ePTFE Vascular Prosthesis Market
Medical Devices
Skin Revitalizing Handheld Devices Market
Medical Devices
Buccal Cavity Devices Market
Medical Devices
Intra-Abdominal Pressure Measurement Devices (IPMD) Market
Medical Devices
United Arab Emirates Drug Delivery Devices Market
Medical Devices
Global IVF Devices Market
Medical Devices
Gum Grafting Market