
 Diabetic Retinopathy Treatment Market | 2026-2036
Diabetic Retinopathy Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Diabetic Retinopathy Treatment Market Analysis
Buyer concentration among hospital outpatient departments is pivoting as ophthalmology clinics and ambulatory surgery centers fragment the patient pathway across decentralized settings. Regeneron Pharmaceuticals dominates the anti-VEGF segment with Eylea through sustained manufacturing scale and channel control. Bayer AG competes on geographic breadth, leveraging its retinal portfolio across European and Asian markets. Novartis AG anchors the competitive set with Beovu, positioning its dosing innovation against entrenched rivals.
Diabetic retinopathy treatment encompasses pharmacologic, laser-based, and surgical interventions targeting microvascular damage to the retinal capillary network, with anti-VEGF agents functioning as vascular endothelial growth factor inhibitors that reduce macular edema and neovascularization. The primary commercial purpose is preserving visual acuity in diabetic patients while delaying or preventing progression to proliferative disease. Anti-VEGF drugs occupy the dominant revenue pool due to repeat dosing requirements and superior efficacy in diabetic macular edema, whereas optical coherence tomography leads diagnostic technology adoption by enabling non-invasive retinal layer visualization that guides treatment decisions. Laser therapy retains a mature, cost-effective position in resource-constrained settings despite anti-VEGF displacement in premium markets.
FDA ophthalmic biologics pathways, EMA's MDR compliance requirements for retinal diagnostic devices, and Japan's PMDA priority review vouchers collectively elevate clinical evidence standards and extend development timelines. These frameworks shape demand by restricting market access to validated therapies while accelerating breakthrough designations for sustained-release formulations. Stakeholders must monitor regulatory divergence between accelerated approval and full confirmatory trial requirements as biosimilar entry reshapes pricing dynamics across reimbursed markets.
Market Dynamics
Anti-VEGF intravitreal injection protocols are compressing treatment intervals and pulling patient volume from laser photocoagulation centers into hospital outpatient departments and ophthalmology clinics. This shift in care delivery location is restructuring referral patterns and capital allocation across the retinal therapy ecosystem.
Growth Catalysts
- EMA MDR Compliance Pathways:Accelerated device approval frameworks for retinal diagnostic platforms are shortening time-to-market for optical coherence tomography systems in European hospital networks.
- Japan PMDA Priority Review Vouchers:Sustained-release formulation candidates receive expedited regulatory assessment, incentivizing biologics developers to prioritize diabetic macular edema indications.
- Reimbursed Screening Programs:Germany's statutory health insurance fund coverage for annual diabetic eye examinations expands addressable patient pools and treatment initiation rates.
Market Restraints
- Anti-VEGF Manufacturing Concentration:Bulk biologics production clusters among contract development organizations in Switzerland and Ireland, creating single-source vulnerability for fill-finish operations.
- Intravitreal Injection Skill Bottleneck:Retina specialist training programs in the United States produce insufficient proceduralists to match patient volume growth in Medicare Advantage plans.
- Laser Device Cost Compression:Mature photocoagulation equipment faces price erosion from refurbished system availability, constraining capital returns for original manufacturers.
Strategic Opportunities
- Home-Based Monitoring Convergence:Smartphone-connected fundus cameras paired with artificial intelligence diagnostic algorithms enable remote screening in rural United States counties lacking ophthalmology coverage.
- India CDSCO Biosimilar Pathways:Abbreviated approval frameworks for ranibizumab and aflibercept biosimilars open volume penetration in price-sensitive diabetic populations.
- Telemedicine Channel Expansion:Virtual consultation platforms integrated with diagnostic device data streams capture follow-up visits that previously defaulted to academic medical centers.
Industry Challenges
- Retina Specialist Workforce Scarcity:Fellowship program capacity in the United States and Germany fails to match incident diabetic retinopathy case growth, extending appointment wait times.
- Optical Coherence Tomography Standardization Delays:Divergent image acquisition protocols across device manufacturers complicate longitudinal patient tracking and multi-site clinical trial data pooling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diabetic Retinopathy Treatment Market |
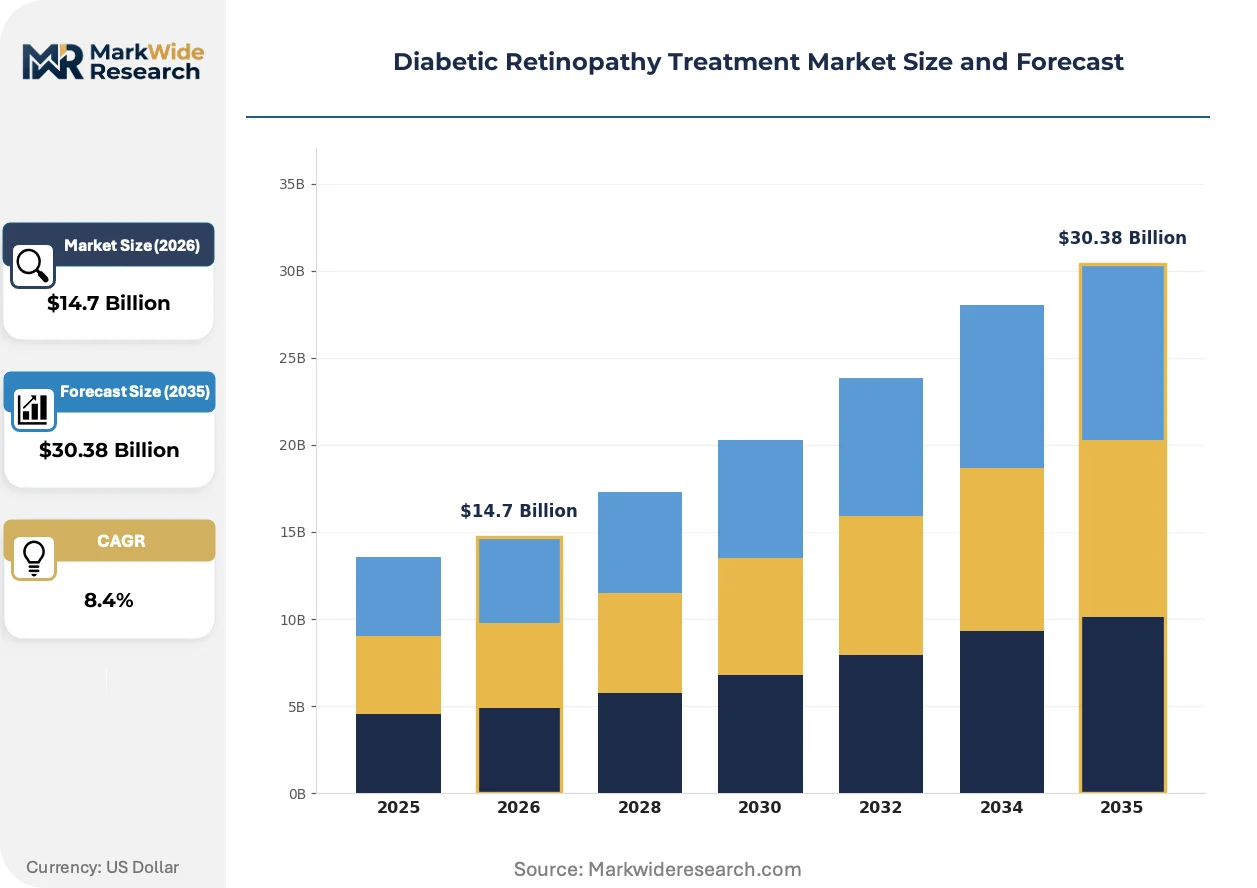
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.38 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anti-VEGF Drugs, Corticosteroids, Laser Therapy, Surgery Delivery Mode: Intravitreal Injection, Sub-Tenons Injection, Systemic Delivery, Topical End User: Ophthalmology Clinics, Hospital Outpatient Departments, Specialty Hospitals, ASCs Technology: Fluorescein Angiography, Optical Coherence Tomography, Fundus Cameras, Retinal Implants |
| Companies Covered | Bayer AG, Genentech, Regeneron Pharmaceuticals, Abbott Laboratories, AbbVie Inc., F. Hoffmann-La Roche Ltd, Alimera Sciences, Oxurion NV, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diabetic Retinopathy Treatment Market Emerging Trajectories
Sustained-release drug delivery systems and artificial intelligence diagnostic platforms are converging to compress treatment burdens and accelerate disease detection. These technology trajectories are redrawing competitive boundaries between pharmaceutical and device manufacturers.
Port delivery systems with refillable ranibizumab reservoirs are rewriting the anti-VEGF treatment paradigm by eliminating monthly injection requirements. Hospital outpatient departments in the United States and Japan are piloting these implants for high-burden patients with persistent diabetic macular edema. The technology is rewriting adherence expectations and threatening the repeat-dose revenue model that has sustained intravitreal therapy economics.
FDA ophthalmic biologics accelerated approval pathways are compressing confirmatory trial timelines for sustained-release formulations while tightening post-market surveillance obligations. Developers must now deploy real-world evidence collection infrastructure concurrent with commercial launch. The policy shift most affects mid-cap biologics manufacturers lacking integrated patient registry capabilities.
Buyer concentration among hospital outpatient departments is fragmenting as ambulatory surgery centers and independent ophthalmology clinics capture stable diabetic macular edema cases. United States Medicare site-of-service payment differentials incentivize this volume migration. The behavioral shift concentrates complex neovascular cases in academic centers while commoditizing routine anti-VEGF maintenance.
Diabetic Retinopathy Treatment Market Segmentation
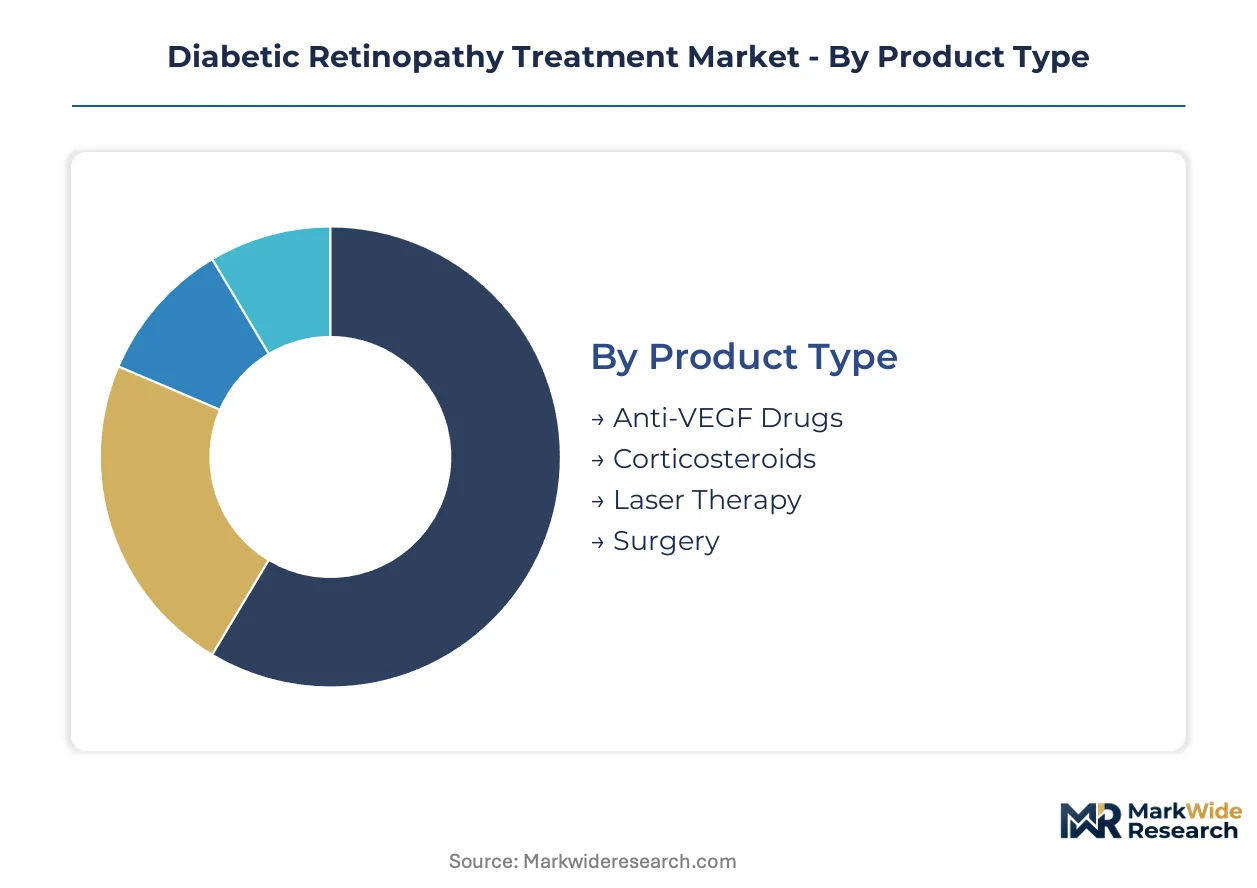
Treatment modality segmentation reveals divergent margin structures across pharmacologic and procedural interventions. Anti-VEGF biologics command premium pricing through repeat dosing protocols, while laser and surgical segments compete on capital efficiency and reimbursement stability.
Product Type:
Anti-VEGF drugs capture the premium tier through chronic administration requirements, while laser therapy and surgery occupy cost-sensitive volume positions in emerging markets and public health systems.
- Anti-VEGF Drugs:Vascular endothelial growth factor inhibitors including ranibizumab, aflibercept, and biosimilar equivalents function as first-line therapy for diabetic macular edema. Demand concentrates in United States Medicare Advantage plans and Japan's statutory health insurance system where monthly injection protocols sustain reimbursement continuity.
- Laser Therapy:Focal and panretinal photocoagulation systems deliver thermal ablation of ischemic retinal tissue. Deployment clusters in India's tier-2 cities and Brazil's public hospital networks where device amortization costs undercut biologic therapy pricing.
- Corticosteroids:Intravitreal steroid implants and periocular injections address persistent edema in anti-VEGF non-responders.
- Surgery:Vitrectomy and membrane peeling procedures manage tractional retinal detachment complications.
Mature deployment sits with laser therapy. Newer deployment is concentrated in anti-VEGF drugs.
Delivery Mode:
Route of administration segmentation tracks the tension between efficacy optimization and patient burden reduction, with invasive intravitreal routes dominating efficacy-sensitive indications.
- Intravitreal Injection:Direct drug delivery into the vitreous cavity achieves therapeutic concentrations at the retinal surface. Volume concentrates in hospital outpatient departments across Germany and Japan where retina specialist density supports high-frequency injection protocols.
- Sub-Tenons Injection:Transscleral delivery via the episcleral space offers intermediate invasiveness for corticosteroid administration. Adoption spreads through United Kingdom ophthalmology clinics seeking to reduce endophthalmitis risk versus intravitreal routes.
- Systemic Delivery:Oral and intravenous routes address systemic vascular complications concurrent with retinal disease.
- Topical:Eye drop formulations target anterior segment inflammation with limited posterior segment penetration.
Intravitreal injection maintains the steepest expansion trajectory. Sub-Tenons approaches are gaining share fastest in corticosteroid-sensitive populations.
End User:
Site-of-service segmentation reflects Medicare payment differentials and capital intensity requirements reshaping patient flow across the care continuum.
- Hospital Outpatient Departments:Academic medical centers and community hospital retina services manage complex neovascular cases requiring multimodal therapy. United States volume clusters in Medicare-designated outpatient departments where facility fees augment physician reimbursement.
- Ambulatory Surgery Centers:Freestanding surgical facilities capture stable diabetic macular edema cases eligible for protocol-driven anti-VEGF administration. Growth concentrates in Florida and Texas markets where certificate-of-need restrictions are absent.
- Ophthalmology Clinics:Private practice retina specialists deliver injection-only protocols in metropolitan United States counties.
- Specialty Hospitals:Dedicated eye hospitals in India and Thailand combine surgical volume with training program outputs.
Hospital outpatient departments retain complex case concentration. Ambulatory surgery centers are expanding most quickly in routine maintenance populations.
Technology:
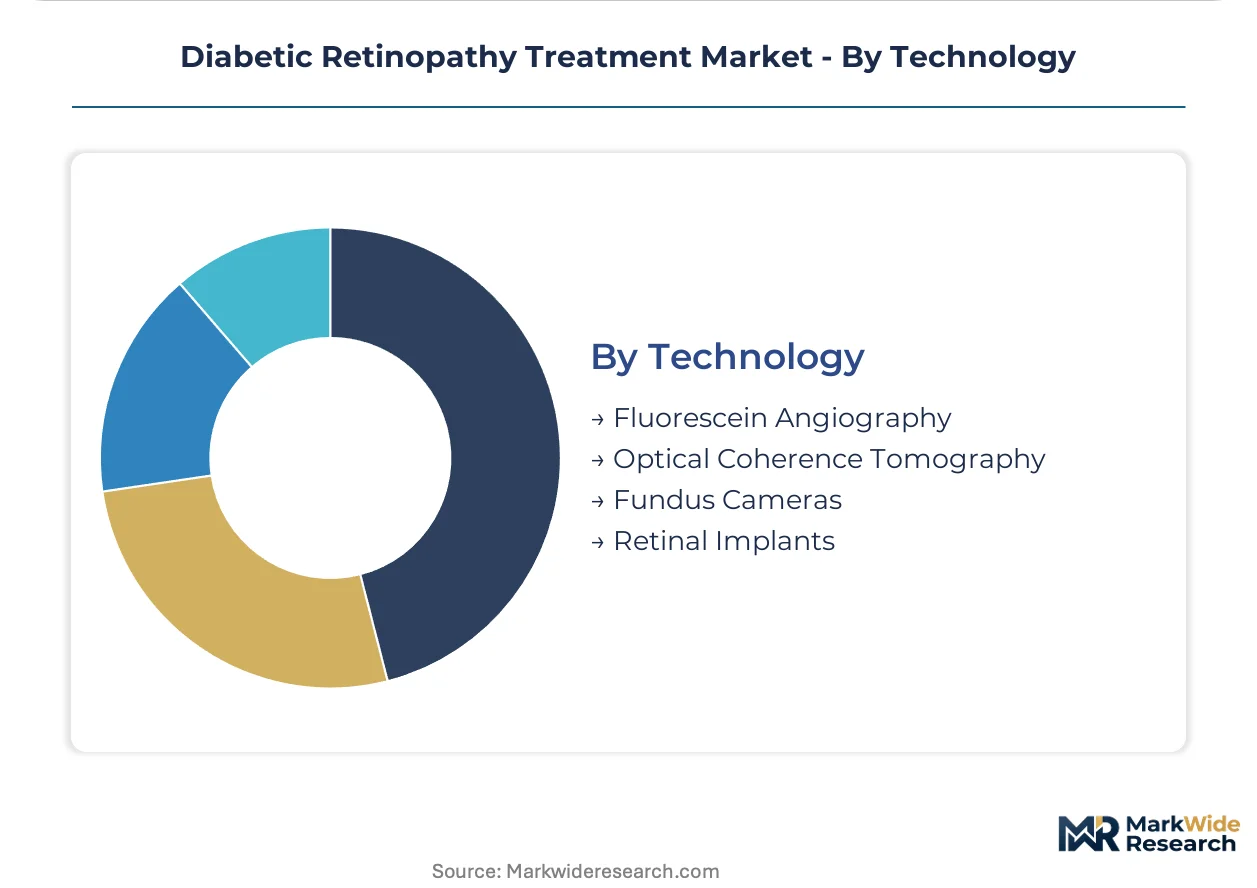
Diagnostic platform segmentation tracks the shift from invasive angiographic methods to non-invasive tomographic imaging reshaping treatment monitoring economics.
- Optical Coherence Tomography:Non-invasive cross-sectional retinal imaging enables quantitative edema monitoring and treatment response assessment. Deployment concentrates in Japanese university hospitals and German statutory insurance-funded screening networks where device reimbursement is standardized.
- Fundus Cameras:Color and wide-field imaging systems support diabetic retinopathy screening at the primary care interface. Volume spreads through India's national blindness control program and United Kingdom diabetic eye screening service contracts.
- Fluorescein Angiography:Intravenous dye-based vascular imaging retains niche utility for neovascular membrane characterization.
- Retinal Implants:Prosthetic devices address end-stage vision loss beyond reversible diabetic retinopathy stages.
Fluorescein angiography represents mature diagnostic deployment. Optical coherence tomography is climbing the fastest across reimbursed screening programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swiss and Irish contract manufacturing clusters anchor anti-VEGF biologics production, while patient demand concentrates in aging diabetic populations across reimbursed healthcare systems in the United States, Germany, and Japan.
United States
Medicare Advantage plans drive anti-VEGF injection volume through capitated reimbursement models. FDA accelerated approval pathways for ophthalmic biologics compress development timelines while tightening post-market surveillance. Retina specialist training programs in Baltimore and San Francisco produce insufficient proceduralists to match patient growth.
Germany
Statutory health insurance funds cover annual diabetic eye examinations, expanding addressable patient pools for early intervention. EMA MDR compliance requirements for retinal diagnostic devices elevate clinical evidence standards. Optical coherence tomography deployment concentrates in university hospital networks across Munich and Heidelberg.
Japan
PMDA priority review vouchers expedite regulatory assessment for sustained-release formulation candidates targeting diabetic macular edema. Hospital outpatient departments in Tokyo and Osaka pilot port delivery systems with refillable ranibizumab reservoirs. Aging diabetic populations and standardized device reimbursement accelerate diagnostic technology adoption.
India
CDSCO abbreviated approval frameworks for ranibizumab and aflibercept biosimilars open volume penetration in price-sensitive diabetic populations. National blindness control program contracts spread fundus camera deployment through tier-2 cities. Laser photocoagulation retains cost-sensitive positioning in public hospital networks across Maharashtra and Tamil Nadu.
Switzerland
Contract development organizations cluster bulk biologics production and fill-finish operations for European supply. Swissmedic regulatory frameworks align with EMA standards while offering specialized pathways for ophthalmic innovations. Basel and Zurich host manufacturing infrastructure serving hospital outpatient departments across the continent.
Diabetic Retinopathy Treatment Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue sustained-release delivery systems and artificial intelligence diagnostic platforms. The competitive set fragments across pharmaceutical biologics manufacturers, diagnostic device developers, and surgical equipment suppliers. Three archetypes dominate: integrated biologics developers with manufacturing scale, mid-cap specialists in drug delivery innovation, and diversified medtech conglomerates with imaging portfolios. Capacity expansion in Swiss and Irish fill-finish facilities and strategic partnerships for real-world evidence collection represent the dominant competitive moves.
Within the integrated biologics tier, Bayer AG, Regeneron Pharmaceuticals, and Novartis AG exemplify contrasting geographic and technological positioning. Bayer AG occupies a position leveraging European and Asian market breadth across its retinal portfolio. Regeneron Pharmaceuticals anchors the anti-VEGF segment through sustained manufacturing scale and channel control in United States hospital outpatient departments. Novartis AG sits within the competitive set with dosing innovation strategies against entrenched rivals, representing the mid-cap specialist archetype in sustained-release development.
| Leading Market Players |
|---|
| Bayer AG |
| Genentech |
| Regeneron Pharmaceuticals |
| Abbott Laboratories |
| AbbVie Inc. |
| F. Hoffmann-La Roche Ltd |
| Alimera Sciences |
| Oxurion NV |
| Novartis AG |
| Others |
Supply Flow & Price Mechanics
Fill-finish service pricing indices for biologics manufacturing cascade through Swiss and Irish contract development clusters into three distinct pricing tiers across anti-VEGF therapies. Hospital outpatient departments absorb premium bundled rates covering injection protocols and real-world evidence collection, while ambulatory surgery centers negotiate unbundled per-procedure pricing that excludes device warranties.
Pricing Analysis
Warranty and service bundling separates premium anti-VEGF contracts from economy laser therapy tiers. Three-tier pricing structure across premium, standard, and economy levels dominates: premium biologics bundle post-market surveillance and patient registry access, standard tiers cover injection-only protocols, and economy laser segments exclude maintenance contracts. Price differentiation rests on FDA breakthrough designation status and volume commitment scale. Cost compression in photocoagulation equipment intensifies as refurbished systems flood India's tier-2 cities. Public hospital networks in Brazil exhibit highest price sensitivity; Japanese statutory insurance plans demonstrate lowest sensitivity due to standardized reimbursement floors.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme for pharmaceuticals reshape active pharmaceutical ingredient sourcing toward indigenous manufacturers. Bulk biologics production concentrates in Switzerland, Ireland, and Singapore, with fill-finish operations drawing from German-engineered isolator technology and US-sourced single-use bioreactor components. Single-source vulnerability permeates the Swiss contract manufacturing network where three CDMOs control European anti-VEGF fill-finish capacity. Distribution runs through hospital procurement consortiums in Germany and Japan, with specialty distributors serving ophthalmology clinics in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from biosimilar entry and sustained-release formulation disruption will force sub-scale anti-VEGF manufacturers toward exit or acquisition within the analysis window.
For Market Incumbents: Anticipate ranibizumab biosimilar price erosion by securing backward integration into Swiss fill-finish capacity and accelerating port delivery system development. Retina specialist workforce scarcity in the United States threatens volume growth; defend channel control through exclusive ophthalmology clinic partnerships and real-world evidence infrastructure deployment concurrent with FDA accelerated approval launches. For New Entrants and Emerging Players: Ambulatory surgery center networks offer the most penetrable channel for sustained-release formulation candidates seeking to bypass hospital outpatient department incumbent lock-in. India's CDSCO abbreviated approval pathway for aflibercept biosimilars presents volume penetration opportunity in price-sensitive diabetic populations. Go-to-market execution should prioritize telemedicine-integrated diagnostic bundles that capture rural United States counties lacking ophthalmology coverage. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap drug delivery specialists with sustained-release platforms in Japan and United States markets where PMDA priority review vouchers compress regulatory timelines. Long-term viability centers on manufacturing scale and integrated patient registry capabilities rather than single-product dependencies. Watch FDA confirmatory trial requirement tightening as the inflection signal distinguishing sustainable revenue models from accelerated-approval vulnerabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Swiss CDMO capacity expansion secures European anti-VEGF supply continuity against single-source risk. |
| Regulatory Approval Pathway | PMDA priority review voucher acquisition accelerates sustained-release formulation assessment timelines. |
| Hospital System Partnership | Exclusive ophthalmology clinic contracts in Texas and Florida bypass hospital outpatient department concentration. |
| Pipeline Diversification | Corticosteroid implant development addresses anti-VEGF non-responder populations with distinct reimbursement codes. |
| Software Companion Development | AI diagnostic algorithms paired with smartphone fundus cameras enable remote screening revenue capture. |
Methodological Framework
Multi-period observation of anti-VEGF injection frequency, ophthalmology clinic expansion rates, and biosimilar approval timelines anchored the trend analysis, supplemented by interviews with retina specialists, hospital procurement managers, regulatory affairs leads at biologics manufacturers, and formulary directors at Medicare Advantage plans. Secondary validation drew from FDA ophthalmic biologics filings, EMA MDR submission databases, PMDA priority review voucher awards, ClinicalTrials.gov entries for diabetic macular edema indications, and CMS Medicare outpatient procedure data. Bottom-up patient volume modeling triangulated against top-down pharmaceutical revenue estimates across the analysis window.
Segment-weighting approaches distributed value projections across treatment modality, delivery mode, end-user site-of-service, and diagnostic technology dimensions. Anti-VEGF drug revenue trajectories incorporated dosing interval compression assumptions and sustained-release displacement scenarios. CAGRs derived from multivariate regression across reimbursed market penetration, retina specialist density, and screening program coverage variables. Forecast inputs included PMDA regulatory timeline distributions and CDSCO biosimilar approval velocity patterns.
Caveats apply where FDA confirmatory trial requirement tightening or EMA MDR compliance deadline shifts could materially shift the outlook for sustained-release formulation launches and diagnostic device deployments. Biosimilar pricing dynamics in India and Brazil, alongside Medicare site-of-service payment differential revisions, present additional revision triggers. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Nystagmus Market
Ophthalmology
Corneal Edema Treatment Market
Ophthalmology
Global Uveitis Treatment Market
Ophthalmology
USA Ophthalmic Devices Market
Ophthalmology
Global Hemianopsia Market
Ophthalmology
Ophthalmic Viscosurgical Devices Market
Ophthalmology
Epidemic Keratoconjunctivitis Treatment Market
Ophthalmology
Retinal Vein Occlusion Treatment Market
Ophthalmology
Bullous Keratopathy Market
Ophthalmology
Ophthalmic Photocoagulator Market
Ophthalmology
Global Retinal Detachment Treatment Market
Ophthalmology
Meibomian Gland Dysfunction Treatment Market
Ophthalmology
Tobramycin Eye Drop Market
Ophthalmology
Lazy Eye Market
Ophthalmology
Keratitis Treatment Market
Ophthalmology
India Ophthalmic Clinical Trials Market