
 Ingestible Smart Pills Market | 2026-2036
Ingestible Smart Pills Market Size, Share, and Industry Trends Forecast 2026-2036
Ingestible Smart Pills Market Outlook
Israel is tilting toward ingestible sensor manufacturing as Medtronic leverages its endoscopy infrastructure for capsule-based diagnostics. Olympus Corporation anchors Japanese precision optics into smart pill imaging modules. CapsoVision specializes in wireless transmission architectures that sustain competitive differentiation against larger device portfolios.
Ingestible smart pills are self-contained oral drug delivery systems integrating microsensors, wireless transmitters, and biocompatible housings to track ingestion events, physiological parameters, or gastrointestinal conditions in real time. Their primary commercial purpose centers on verifying medication adherence and capturing diagnostic data without invasive procedures. Capsule form factors dominate current volume owing to standardized manufacturing tooling and established patient familiarity, while biosensor-enabled tablets command premium positioning where real-time biomarker feedback justifies higher reimbursement. Data analytics layers represent the fastest-attaching revenue stream as healthcare providers seek actionable adherence intelligence beyond raw sensor outputs.
FDA digital health pre-certification and EMA medical device regulation shape product development timelines for wireless transmission platforms entering Western markets. Japan's PMDA reviews smart pill combinations under pharmaceutical-medical device convergence pathways that extend registration complexity. Stakeholders must monitor evolving data privacy frameworks governing patient-generated health data from ingestible sensors.
Market Dynamics
Regulatory convergence between pharmaceutical and medical device frameworks is compressing product development timelines while elevating compliance costs for wireless-enabled drug delivery systems.
Growth Catalysts
- FDA Digital Health Pre-Certification:Streamlined pathways for software-enabled drug-device combinations accelerate time-to-market for adherence-monitoring formulations in the United States.
- Hospital System Integration:Chronic disease management protocols in cardiology and psychiatry departments create institutional demand for real-time ingestion verification.
- Biosensor Miniaturization:Advances in microelectromechanical systems enable multi-parameter physiological monitoring within standard capsule geometries.
Market Restraints
- Precision Manufacturing Concentration:Biocompatible polymer housings and microbattery cell production cluster in East Asian supplier networks, creating single-source vulnerability.
- Data Privacy Fragmentation:HIPAA in the United States, GDPR in Europe, and Japan's APPI impose conflicting technical safeguards on patient-generated health data transmission.
- Reimbursement Uncertainty:Payers in Germany and Japan apply inconsistent coding for connected drug delivery, limiting prescriber confidence.
Strategic Opportunities
- EMA Medical Device Regulation Harmonization:Unified conformity assessment procedures reduce duplicate testing costs for manufacturers targeting multiple European markets.
- Oncology Protocol Expansion:Oral chemotherapy regimens with strict adherence requirements represent an underpenetrated therapeutic vertical for sensor-enabled verification.
- Direct-to-Provider Distribution:Bypassing wholesale pharmaceutical channels allows manufacturers to capture adherence analytics revenue streams previously retained by intermediaries.
Industry Challenges
- Cross-Disciplinary Talent Scarcity:Product development teams require simultaneous expertise in pharmaceutical formulation, RF engineering, and clinical trial design.
- Legacy Health Record Integration:Hospital IT departments face technical debt when connecting ingestible sensor data streams to established electronic medical record architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ingestible Smart Pills Market |
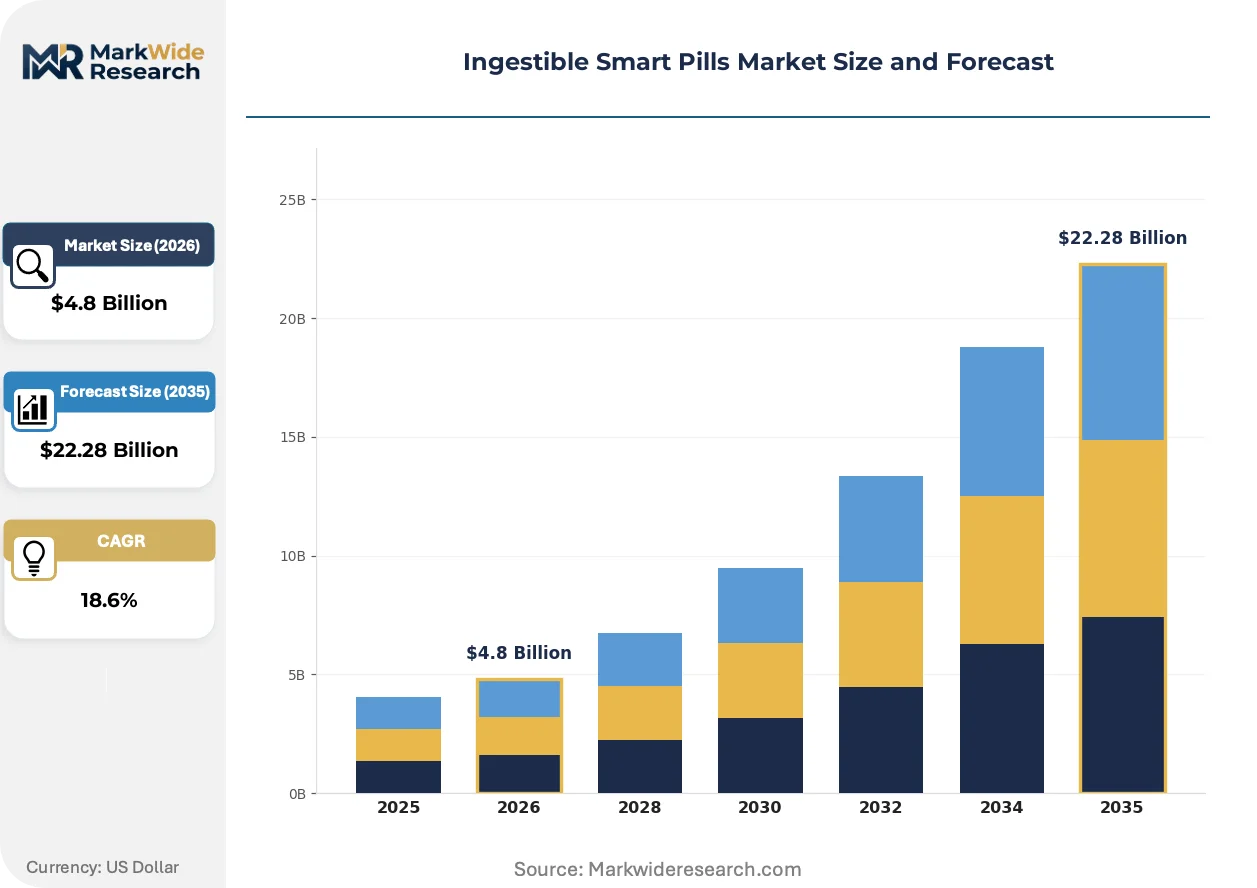
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsule, Tablet, Liquid Fill, Gel Technology: Wireless Transmission, Biosensors, Real-Time Monitoring, Data Analytics End User: Healthcare Providers, Research Institutions, Patients, Pharmacies Application: Chronic Disease Management, Medication Adherence, Diagnostic Monitoring, Patient Education |
| Companies Covered | Medtronic, Olympus Corporation, CapsoVision, Inc., IntroMedic Co., Ltd, BodyCap Medical, Check-Cap Ltd., Proteus Digital Health, Inc., Given Imaging Ltd., etectRx, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ingestible Smart Pills Market Strategic Shifts
Wireless transmission architectures are converging with advanced materials science to enable continuous biomarker detection previously confined to invasive procedures.
Multi-sensor capsule platforms are hybridizing electrochemical glucose detection with pH and temperature logging to create comprehensive metabolic profiles. Gastroenterology departments in tertiary care centers are piloting these systems for inflammatory bowel disease monitoring. The technology is hybridizing diagnostic and therapeutic functions into single-administration events that reduce patient burden and clinical visit frequency.
Japan's PMDA pharmaceutical-medical device convergence pathway is mandating combined quality management systems for smart pill submissions. Manufacturers must now maintain dual ISO 13485 and pharmaceutical GMP certifications throughout product lifecycles. European entrants are responding by pre-structuring regulatory dossiers to accommodate both EMA drug and notified body device reviews simultaneously.
Institutional procurement committees are consolidating vendor relationships around integrated adherence platforms rather than standalone sensor hardware. Health systems in the United States are displacing point-solution contracts with multi-year partnerships spanning device supply, data analytics, and clinical decision support. This concentration is most pronounced in integrated delivery networks managing large Medicaid and Medicare populations where medication non-adherence carries substantial penalty exposure.
Ingestible Smart Pills Market Segmentation
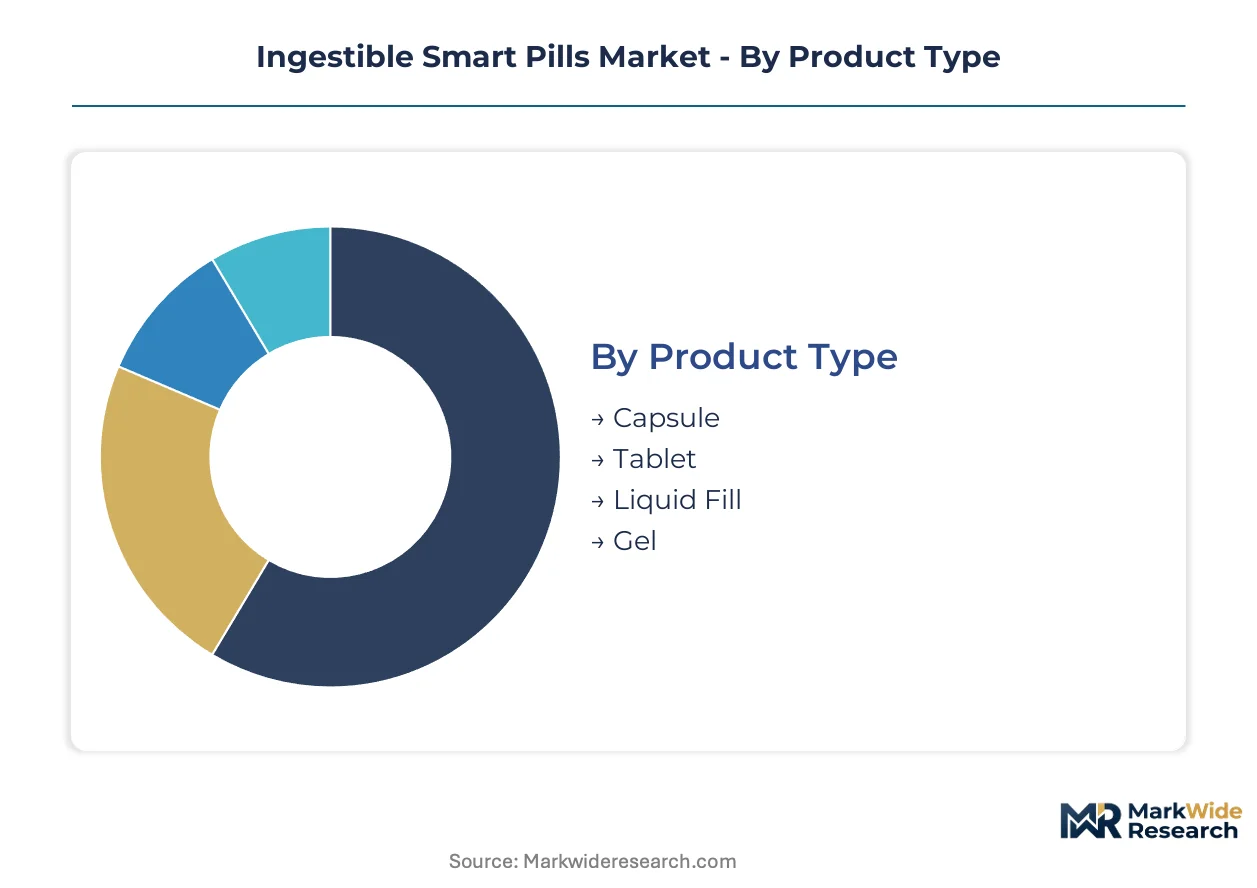
Segmentation in ingestible smart pills reveals how form factor, transmission architecture, and clinical setting interact to determine reimbursement pathways and manufacturing scale. Each dimension carries distinct regulatory obligations and margin profiles that shape portfolio prioritization.
Product Type:
Mature pharmaceutical tooling dominates high-volume manufacturing, while emerging geometries target specialized delivery requirements.
- Capsule:Standardized gelatin or HPMC shells accommodate microsensor arrays within established high-speed filling lines. Hospital systems in the United States and Germany prefer this format for psychiatric and cardiovascular adherence protocols where patient familiarity reduces training burden.
- Tablet:Compressed formulations integrate biosensor layers directly into excipient matrices, enabling real-time biomarker detection. Japan's PMDA convergence pathway favors tablet submissions for oncology applications requiring combined drug-device quality systems.
- Liquid Fill:Encapsulated fluid reservoirs suit temperature-sensitive biologics and pediatric formulations.
- Gel:Hydrogel matrices enable extended-release sensor activation for overnight monitoring scenarios.
Capsule retains volume leadership; tablet holds the steepest expansion curve.
Technology:
Cost tier stratification separates hardware-intensive platforms from software-layer revenue models.
- Wireless Transmission:RF-enabled pills transmit ingestion timestamps and physiological data to external receivers using biocompatible antenna designs. Precision manufacturing clusters in Israel and Japan supply Medtronic and Olympus with microbattery and substrate components.
- Biosensors:Electrochemical detection elements measure glucose, pH, and inflammatory markers through enzymatic reactions. Tertiary care centers in the United States pilot multi-parameter platforms for inflammatory bowel disease monitoring.
- Real-Time Monitoring:Continuous data streams require HIPAA-compliant cloud infrastructure and hospital IT integration.
- Data Analytics:Adherence intelligence platforms aggregate sensor outputs into clinical decision support dashboards.
Wireless transmission commands premium pricing; data analytics is climbing the fastest as recurring revenue models displace hardware margins.
End User:
Customer type determines procurement complexity and data ownership frameworks.
- Healthcare Providers:Integrated delivery networks in the United States consolidate vendor relationships around multi-year adherence platform partnerships spanning device supply and analytics.
- Research Institutions:Academic medical centers drive protocol innovation for novel biomarker detection.
- Patients:Direct-to-consumer channels remain limited by reimbursement gaps and privacy concerns.
- Pharmacies:Retail chains explore dispensing integration for specialty oral chemotherapy regimens.
Healthcare providers absorb the dominant procurement volume; research institutions are gaining share fastest through NIH and EU Horizon funding.
Application:
Application focus shifts margin structure from device sales toward outcome-based contracting.
- Chronic Disease Management:Cardiology and psychiatry departments deploy sensor-enabled regimens where non-adherence carries readmission penalties under Medicare quality programs.
- Medication Adherence:Ingestion verification addresses the estimated burden of treatment failure in oral chemotherapy and antipsychotic protocols.
- Diagnostic Monitoring:Capsule endoscopy alternatives target gastrointestinal screening gaps.
- Patient Education:Feedback loops reinforce behavioral modification in diabetes and hypertension self-management.
Chronic disease management anchors current revenue; diagnostic monitoring is expanding most quickly as gastroenterology departments pilot comprehensive metabolic profiling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biocompatible polymer housings and microbattery cell production cluster heavily in East Asian supplier networks, creating geographic vulnerability for manufacturers. FDA, EMA, and PMDA pathways are compressing development timelines while elevating compliance costs across Western and Japanese markets.
United States
Hospital systems in cardiology and psychiatry departments drive institutional procurement for adherence-monitoring formulations. FDA digital health pre-certification streamlines software-enabled drug-device combinations for domestic manufacturers. Greater Boston and the Research Triangle anchor clinical trial infrastructure for wireless transmission platforms.
Germany
Integrated delivery networks managing large Medicaid-equivalent populations seek multi-year adherence platform partnerships. EMA medical device regulation harmonization reduces duplicate testing costs for manufacturers targeting European markets. The Rhine-Ruhr corridor concentrates precision polymer processing for capsule housings.
Japan
PMDA pharmaceutical-medical device convergence pathways mandate combined quality management systems for smart pill submissions. METI funding supports biosensor miniaturization research in domestic manufacturing clusters. The Kanto region around Tokyo hosts Olympus Corporation's precision optics integration for imaging modules.
Israel
Medtronic leverages established endoscopy infrastructure for capsule-based diagnostic manufacturing expansion. The national pharmaceutical regulator maintains alignment with FDA technical standards for wireless-enabled drug delivery exports. Tel Aviv anchors startup activity in RF engineering and microsensor architecture design.
United Kingdom
NHS integrated care systems pilot outcome-based contracting for chronic disease management applications. GDPR technical safeguards impose specific encryption requirements on patient-generated health data transmission from ingestible sensors. The Oxford-Cambridge arc concentrates academic medical center protocol innovation for novel biomarker detection.
Ingestible Smart Pills Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in microbattery and substrate supply. The market structure tilts toward consolidation as institutional procurement committees favor multi-year partnerships spanning device supply, data analytics, and clinical decision support. Three archetypes dominate: diversified medical technology conglomerates with endoscopy heritage, precision optics manufacturers extending into imaging modules, and wireless transmission architecture specialists defending niche positions. Competitive moves concentrate on strategic partnerships for hospital IT integration and portfolio diversification into adherence analytics software.
Among diversified medical technology conglomerates, Medtronic exemplifies platform integration leveraging endoscopy infrastructure for capsule-based diagnostics. Olympus Corporation anchors Japanese precision optics manufacturing for smart pill imaging modules. CapsoVision occupies a specialist position in wireless transmission architectures that sustain competitive differentiation against larger device portfolios. These three represent the dominant competitive anchors across hardware manufacturing, optical systems, and RF engineering specializations.
| Leading Market Players |
|---|
| Medtronic |
| Olympus Corporation |
| CapsoVision, Inc. |
| IntroMedic Co., Ltd |
| BodyCap Medical |
| Check-Cap Ltd. |
| Proteus Digital Health, Inc. |
| Given Imaging Ltd. |
| etectRx, Inc. |
| Others |
Value Chain & Pricing Dynamics
East Asian precision polymer processing clusters in Taiwan and South Korea anchor biocompatible housing production, concentrating margin capture upstream while downstream device integrators compete on analytics-layer differentiation. This concentration pattern elevates input cost leverage for capsule shell suppliers against finished goods manufacturers seeking ISO 13485-certified component sourcing.
Pricing Analysis
FDA digital health pre-certification and Japan's PMDA convergence pathway dictate the pricing tier structure across wireless-enabled drug-device combinations. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared adherence platforms from CE-marked European entrants and uncertified research-grade sensors. Price differentiation hinges on wireless transmission range certification and cloud analytics bundling. Cost compression in standard-tier capsules is intensifying because hospital procurement committees consolidate multi-year vendor partnerships. Research institutions demonstrate highest price sensitivity due to grant-funded budget constraints, while integrated delivery networks absorb premium positioning for penalty-avoidance in Medicare quality programs.
Supply Chain Analysis
Contract manufacturing concentration sits with Foxconn Health Technology Business Group, Jabil Healthcare, and Flex medical device divisions holding precision microassembly capacity for ingestible sensor platforms. Component sourcing draws from Japanese microbattery specialists, Israeli RF substrate foundries, and German precision polymer extruders. Raw material dependencies include lithium-polymer microcells, biocompatible HPMC gelatin alternatives, and electrochemical biosensor membranes. Single-source vulnerability concentrates in East Asian microbattery cell production where geopolitical friction threatens supply continuity. Distribution runs through direct-to-provider channels displacing wholesale pharmaceutical intermediaries for adherence analytics revenue retention.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Institutional procurement consolidation around integrated adherence platforms fragments competitive space, creating specialist niches for wireless transmission architects and biosensor layer developers as hospital systems displace point-solution contracts.
For Market Incumbents: Build regulatory dossier moats through simultaneous FDA pre-certification and EMA MDR harmonization to compress competitor time-to-market. Deepen backward integration into microbattery cell production to offset East Asian supplier concentration risk. Acquire adherence analytics software capabilities to defend against pure-play data platform entrants capturing recurring revenue streams previously retained by hardware manufacturers. For New Entrants and Emerging Players: Oncology oral chemotherapy adherence verification in European hospital systems represents the most penetrable entry point given EMA MDR harmonization reducing duplicate testing costs. Tablet-form biosensor platforms for inflammatory bowel disease monitoring in United States tertiary care centers offer second-mover positioning against capsule-dominant incumbents. Pursue direct-to-provider distribution partnerships bypassing wholesale pharmaceutical channels to capture analytics-layer margins. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed wireless transmission specialists holding ISO 13485 certification and hospital IT integration capabilities. Five-to-ten year viability hinges on successful navigation of pharmaceutical-medical device convergence pathways across FDA, EMA, and PMDA jurisdictions. Acquisition target archetypes include electrochemical biosensor layer developers with multi-parameter detection IP and cloud infrastructure providers with HIPAA-compliant patient-generated health data architectures. Signal to watch: institutional procurement committee consolidation velocity around multi-year adherence platform partnerships versus standalone sensor hardware contracts.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Digital Health Pre-Certification | Streamlined pathway accelerates time-to-market for wireless-enabled drug-device combinations in United States hospital systems. |
| EMA Medical Device Regulation Harmonization | Unified conformity assessment reduces duplicate testing costs for manufacturers targeting multiple European markets simultaneously. |
| Hospital System Partnership | Multi-year adherence platform contracts displace point-solution procurement and capture recurring analytics revenue. |
| Software Companion Development | HIPAA-compliant cloud infrastructure transforms raw sensor outputs into clinical decision support dashboards for cardiology departments. |
| Reimbursement Strategy | Medicare quality program penalty exposure drives integrated delivery network willingness to pay premium for ingestion verification. |
Study Parameters
Cross-validation between primary interviews with biomedical engineers, hospital purchasing committee members, regulatory affairs specialists, and GPO contracts managers anchors the qualitative findings against secondary validation through FDA 510(k) filings, EMA medical device registration databases, PMDA submission records, and hospital procurement contract disclosures. Bottom-up segment sizing triangulates against top-down market reconstruction across product type, technology architecture, end user category, and therapeutic application dimensions.
Calibration against historical wireless medical device adoption curves and pharmaceutical-medical device convergence regulatory timelines informs the projection framework. Segmentation modeling spans capsule versus tablet versus liquid fill form factors, wireless transmission versus biosensor versus data analytics technology tiers, healthcare provider versus research institution versus patient end users, and chronic disease management versus medication adherence versus diagnostic monitoring applications. CAGRs derive from fitted adoption curves incorporating reimbursement pathway maturation and biosensor miniaturization trajectory assumptions.
Practitioners should monitor FDA digital health pre-certification expansion scope, EMA MDR notified body capacity constraints, and PMDA convergence pathway processing timelines for early signals requiring forecast revision. Quarterly review of institutional procurement committee vendor consolidation announcements and microbattery supplier geographic diversification disclosures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe Manual Resuscitators Market
Medical Devices
Global Tumor Tracking Systems Market
Medical Devices
Support Surfaces Market
Medical Devices
Surgical Devices Market
Medical Devices
Global Dry Powder Inhaler (DPI) Market
Medical Devices
Global Medical Injection Molding Market
Medical Devices
Orbital Tissue Expander Market
Medical Devices
Anti-Fatigue Lenses Market
Medical Devices
Self-Sampling Blood Collection and Storage Devices Market
Medical Devices
Medical Smart Wearable Devices Market
Medical Devices
Global Peripheral IV Catheters Market
Medical Devices
Postpartum Hemorrhage (PPH) Devices Market
Medical Devices
Global Craniomaxillofacial Fixation Devices Market
Medical Devices
Inhaled Corticosteroid Device Market
Medical Devices
China Ultrasound Devices Market
Medical Devices
Peripheral Nerve Stimulators Market