
 Vein Illumination Devices Market | 2026-2036
Vein Illumination Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Vein Illumination Devices Market Intelligence
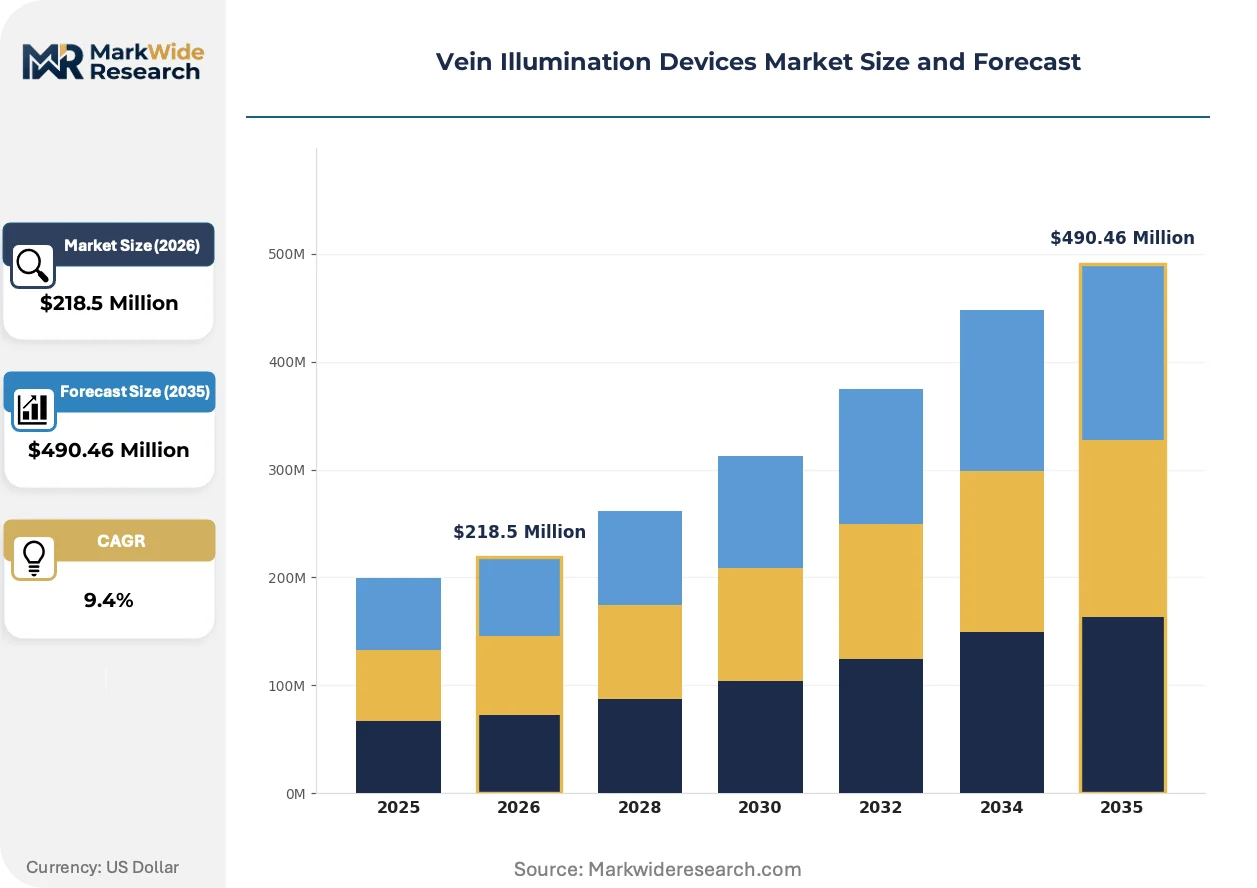
The market for vein illumination devices is pivoting from standalone, single-function units toward software-integrated systems bundled with electronic health record platforms. AccuVein Inc. specializes in highly portable, handheld devices, emphasizing ease of use in diverse clinical settings. Christie Medical Holdings Inc. competes with its projection-based technology that offers hands-free operation. Koninklijke Philips N.V. leverages its broader healthcare technology portfolio to offer integrated diagnostic solutions.
A vein illumination device is a non-invasive medical tool that uses near-infrared light to detect subcutaneous veins not visible to the naked eye. The device projects a real-time map of the vasculature directly onto the skin's surface, assisting clinicians with intravenous access. Infrared technology remains the dominant product type due to its proven efficacy. Clinical settings and emergency rooms represent the largest application segments, while homecare shows significant growth potential.
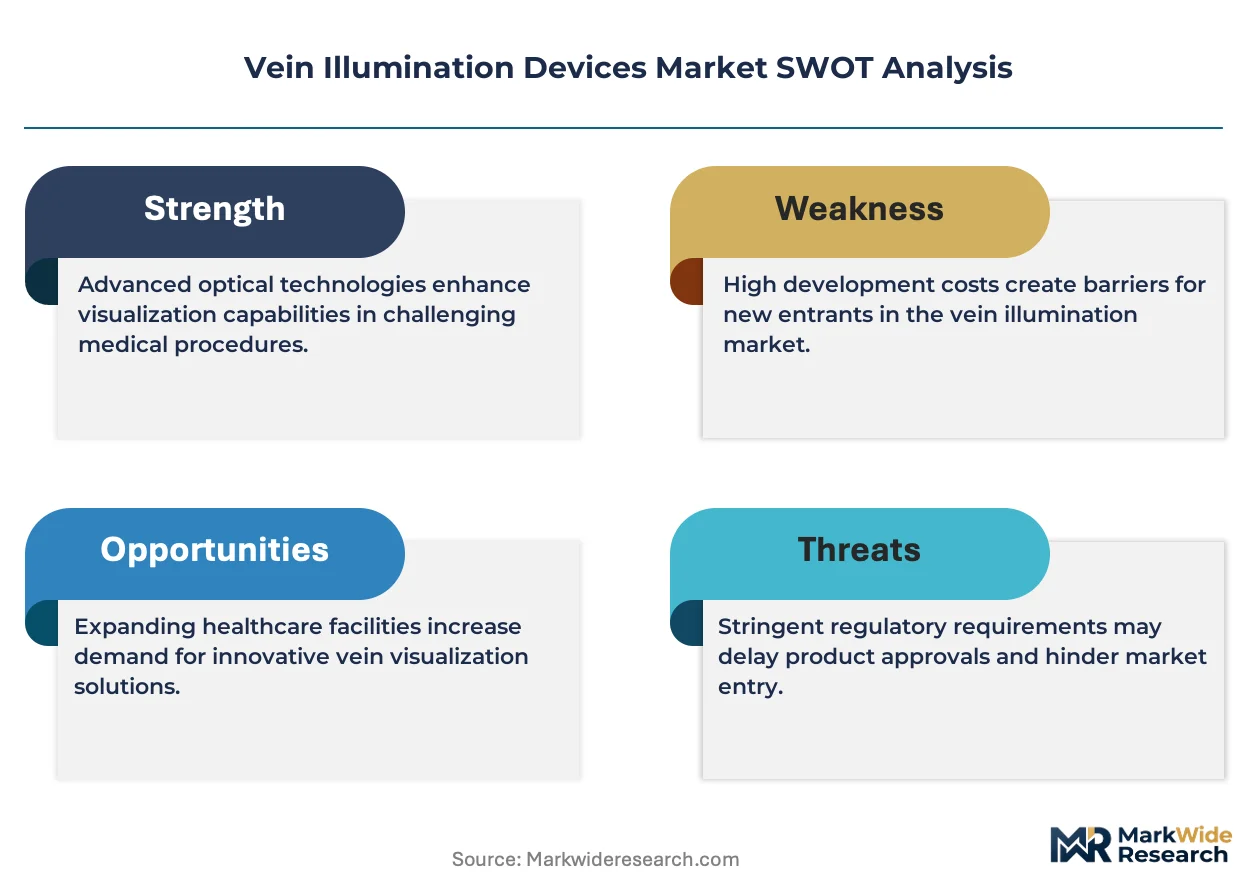
Market access is governed by stringent regulatory approvals, including the FDA's 510(k) clearance in the United States and CE marking under the Medical Device Regulation (MDR) in Europe. These frameworks mandate comprehensive testing for device safety, accuracy, and electromagnetic compatibility. Future competitive advantage will hinge on achieving greater device miniaturization and integrating AI-driven analytics for superior vein pattern recognition.
Market Dynamics
The central dynamic shaping the vein illumination device market is the shift from standalone hardware to software-integrated systems. This evolution transforms devices from simple visualization aids into data-rich nodes within hospital electronic health record (EHR) ecosystems, redefining their clinical value.
Growth Catalysts
- Pediatric Care Adoption:Expanding use within neonatal and pediatric units to minimize patient trauma during difficult venipuncture procedures is a significant demand driver, particularly in specialized children's hospitals.
- Regulatory Pathways:The FDA's established 510(k) clearance process in the United States provides a predictable, albeit rigorous, framework for introducing new devices, fostering sustained product development and innovation.
- Geriatric Patient Needs:A growing elderly population, especially in countries like Germany with advanced healthcare systems, increases the clinical need for technologies that assist with IV access in patients with fragile veins.
Market Restraints
- High Initial Cost:The capital expenditure required for projection-based vein finders can be prohibitive for smaller clinics, outpatient centers, and healthcare systems in emerging economies, limiting market penetration.
- Technical Performance Variables:Device efficacy can be reduced by factors such as deep veins, high levels of subcutaneous adipose tissue, and darker skin pigmentation, requiring skilled clinical judgment to overcome.
- Reimbursement Hurdles:A lack of specific and consistent reimbursement codes for the use of vein illumination in many healthcare systems disincentivizes adoption by removing a direct financial rationale for purchase.
Strategic Opportunities
- Home Healthcare Expansion:The growth of home infusion therapy and chronic disease management creates an opportunity for smaller, more portable, and user-friendly devices designed for use by visiting nurses.
- AI-Driven Vein Analytics:Integrating artificial intelligence algorithms to analyze vein patterns, predict puncture success, and guide catheter placement represents a major avenue for enhancing device value and accuracy.
- Veterinary Medicine Applications:The veterinary market remains a largely underpenetrated segment, offering a new growth frontier for adapting vein illumination technology for use on animals in clinical settings.
Industry Challenges
- Clinician Training Requirements:Achieving proficiency and ensuring consistent, effective use of the technology requires dedicated training programs, which places an operational and time burden on busy hospital staff.
- EHR Integration Complexity:Ensuring seamless, secure, and bidirectional data communication between vein illumination systems and a hospital's diverse electronic health record platforms is a significant technical hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vein Illumination Devices Market |
| Market Size in 2026 | $218.5 Million |
| Market Size in 2035 | $490.46 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infrared, Blue Light, Hybrid, LED Application: Clinical Setting, Emergency Room, Homecare, Pediatric Care End User: Hospitals, Clinics, Laboratories, Research Facilities Technology: Optical, Electromagnetic, Imaging, Software-Integrated |
| Companies Covered | AccuVein Inc., Christie Medical Holdings Inc., TransLite LLC, Venoscope LLC, B. Braun Melsungen AG, Koninklijke Philips N.V., ZD Medical Inc., Infinium Medical Inc., Vivolight, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vein Illumination Devices Market Strategic Shifts & Innovations
The market's evolution is defined by the device's transition from a visualization tool to an integral part of the connected, data-driven clinical workflow. This change is driven by advancements in miniaturization, stricter regulatory demands, and new procurement models in healthcare.
Miniaturized near-infrared sensors and compact laser projection modules are the core enabling technologies. Mobile phlebotomy services and emergency medical teams are rapidly adopting these smaller, handheld formats for use outside traditional hospital walls. This trend of component miniaturization is electrifying point-of-care diagnostics by allowing vein assessment to be performed in virtually any clinical or field setting.
Europe's Medical Device Regulation (MDR) is a significant regulatory force impacting device design and market access. The regulation mandates more extensive clinical evidence and rigorous post-market surveillance compared to its predecessor, the MDD. Manufacturers targeting the EU now face higher compliance costs and longer development timelines, especially for devices with integrated software functionalities.
Hospital procurement is shifting away from simple capital equipment transactions toward more comprehensive, service-oriented contracts. Large integrated delivery networks in the United States are leading this change, preferring bundled agreements that include the device, ongoing software updates, maintenance, and clinical training. This model aligns vendor success with long-term clinical utility rather than a one-time sale.
Vein Illumination Devices Market Segmentation
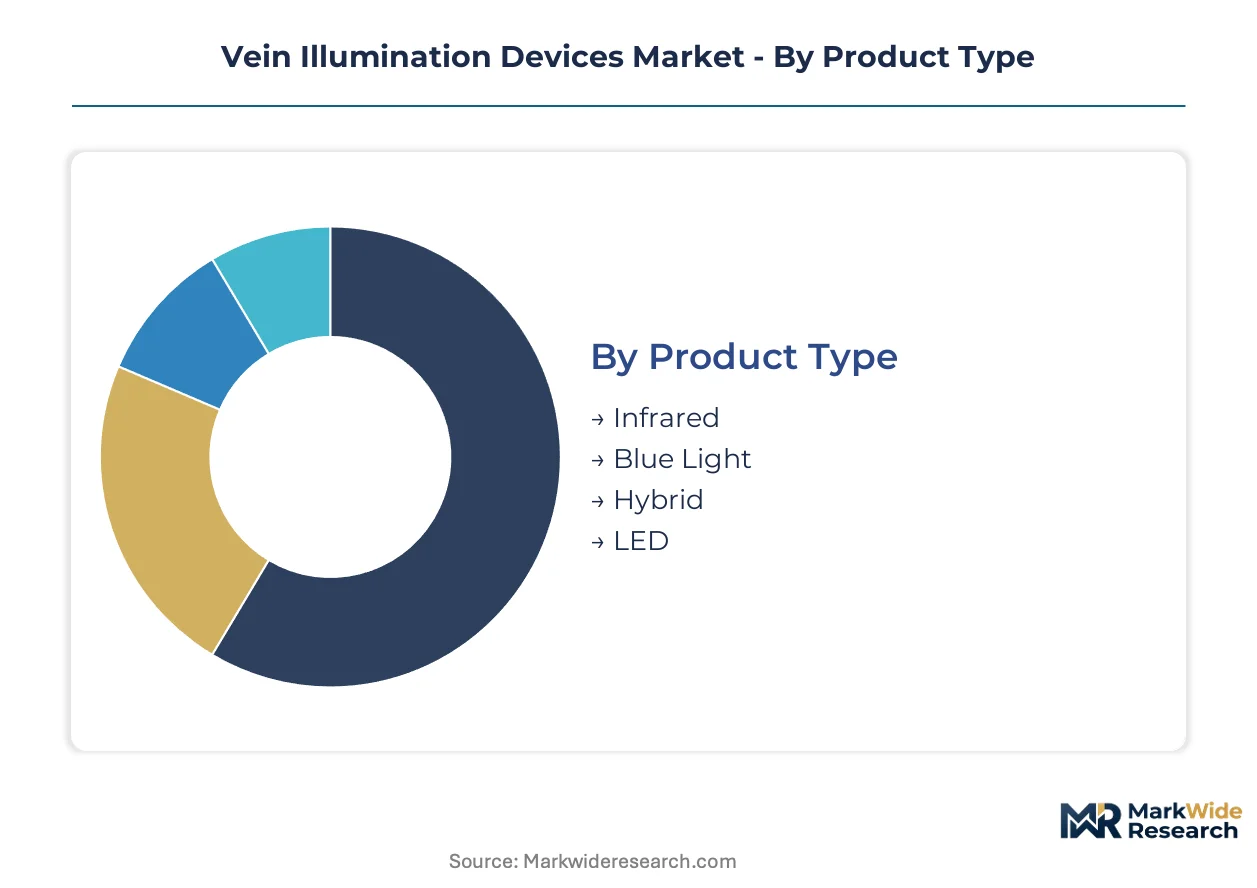
Understanding the segmentation within the vein illumination devices market is crucial for identifying targeted growth opportunities and addressing specific clinical needs. This analysis reveals how different product types, applications, end-users, and underlying technologies shape demand dynamics for these essential medical tools.
Product Type:
Device selection often hinges on the specific clinical requirements and desired visualization capabilities of the user.
- Infrared:This dominant product type uses near-infrared light to highlight deoxygenated hemoglobin, projecting a real-time vein map onto the skin. Demand concentrates in clinical settings due to its proven efficacy and non-invasive nature, assisting clinicians globally.
- Hybrid:These devices combine different light spectrums or imaging modalities to enhance vein visibility across varying skin tones and tissue depths. Pediatric care units in countries like the United States and Germany show increasing adoption for minimizing discomfort during venipuncture.
- Blue Light:This technology utilizes blue light wavelengths to visualize superficial veins, primarily for aesthetic procedures or very shallow vascular access.
- LED:Light-emitting diodes illuminate the skin, providing basic vein contrast for simpler venipuncture tasks in less complex medical environments.
Infrared leads on scale; Hybrid leads on momentum.
Application:
The sheer volume of procedures dictates the demand for vein illumination devices across various medical environments.
- Clinical Setting:This segment encompasses general hospital wards, outpatient clinics, and specialized medical offices where routine venipuncture is performed. These environments prioritize ease of use and integration with existing workflows to improve patient experience.
- Emergency Room:This application focuses on rapid, accurate intravenous access in critical situations, often under high-stress conditions. Devices here require durability, quick deployment, and reliable performance across diverse patient profiles.
- Homecare:This segment involves use by visiting nurses or caregivers for patients receiving infusions or monitoring at home, requiring highly portable and user-friendly devices.
- Pediatric Care:This specialized area focuses on minimizing trauma for young patients, where difficult venipuncture is common, driving demand for gentle and precise visualization tools.
Clinical Setting drives the largest volume; Homecare exhibits the steepest expansion trajectory.
End User:
The specific operational needs and patient demographics of each end-user type influence device procurement decisions.
- Hospitals:These institutions represent the primary purchasers of vein illumination devices, integrating them across various departments including emergency, surgery, and general wards. Large hospital systems often prefer comprehensive, software-integrated solutions for enterprise-wide deployment.
- Clinics:This category includes outpatient centers, specialized practices, and general practitioner offices, seeking cost-effective and portable devices for routine procedures. Smaller clinics often face higher initial cost barriers for projection-based systems.
- Laboratories:These facilities utilize vein illumination for blood draws and sample collection, requiring efficient and reliable tools for high-throughput environments.
- Research Facilities:These entities employ vein illumination devices in clinical trials or studies requiring precise vascular access, often for specialized or experimental procedures.
Hospitals account for the majority of installations; Clinics are gaining share fastest among outpatient settings.
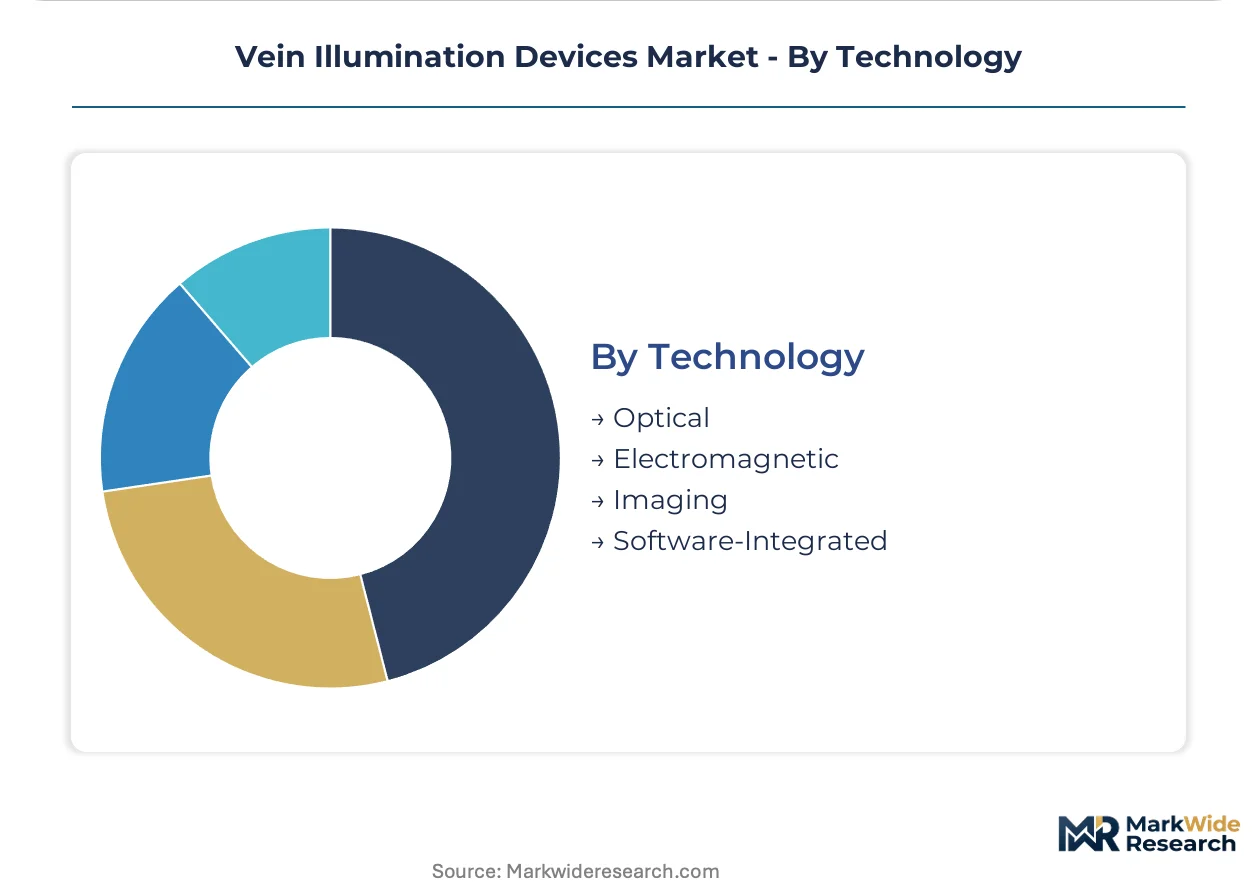
Technology:
The technological sophistication and integration capabilities determine the utility and long-term value of vein illumination systems.
- Imaging:This core capability refers to capturing and displaying subcutaneous vein patterns, typically using near-infrared light. This fundamental technology underpins most commercially available vein illumination devices for real-time visualization.
- Software-Integrated:This segment involves devices that connect with electronic health record (EHR) systems, allowing for data capture, analytics, and enhanced workflow management. This integration transforms devices into data-rich nodes, particularly within large hospital ecosystems.
- Optical:This broad category encompasses methods that use light for vein visualization, including both infrared and visible light spectrums, forming the basis of most current devices.
- Electromagnetic:This represents advanced or experimental technologies that might use electromagnetic fields to detect vascular structures, offering alternative visualization methods.
Optical technology provides the foundational capability; Software-Integrated solutions are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The vein illumination device market, initially scaled through foundational research and early adoption in the United States and Germany, now sees expansion across diverse global healthcare systems. These regions pioneered the integration of medical imaging technologies into clinical practice, establishing a precedent for device development and regulatory pathways. This early leadership positioned key countries as hubs for innovation and market penetration.
United States
Pediatric care units and large hospital systems are driving significant demand for vein illumination devices, minimizing patient discomfort during venipuncture. The FDA's established 510(k) clearance process provides a clear, albeit rigorous, pathway for new product introductions. Medical device clusters in Boston and California are actively developing software-integrated imaging solutions for enhanced clinical utility.
Germany
A growing geriatric population, coupled with an advanced healthcare system, fuels the need for precise IV access technologies. CE marking under the Medical Device Regulation (MDR) ensures high standards for device safety and efficacy across the European market. Bavaria and North Rhine-Westphalia serve as major centers for medical technology manufacturing and hospital network adoption.
Japan
Japan's rapidly aging demographic and emphasis on high-precision medical technology create a steady demand for vein illumination systems. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees stringent approval processes for medical devices, ensuring product quality. Tokyo and Osaka are hubs for medical device research and development, focusing on miniaturization and user-friendliness.
United Kingdom
Homecare expansion and the National Health Service (NHS) procurement strategies are increasing the deployment of portable vein illumination devices. The Medicines and Healthcare products Regulatory Agency (MHRA) provides regulatory oversight for medical devices within the UK. London and Cambridge are key innovation centers, exploring AI-driven analytics for improved vein pattern recognition.
China
Rapid expansion of hospital infrastructure and increasing access to advanced medical technologies contribute to market growth. The National Medical Products Administration (NMPA) regulates device approvals, influencing market entry and product specifications. The Yangtze River Delta and Pearl River Delta regions are experiencing significant adoption within their growing hospital networks.
Vein Illumination Devices Market Key Industry Players
Premium-margin players sit above commodity-margin players across the spectrum of technological sophistication, influencing market structure. The market exhibits a tiered structure, with established medical technology giants competing alongside specialized imaging device manufacturers. Strategic archetypes include providers of highly portable handheld devices, projection-based systems, and integrated diagnostic solutions. Companies are increasingly pursuing portfolio diversification and technology licensing to maintain their competitive positioning.
Within the integrated diagnostic solutions archetype, Koninklijke Philips N.V. leverages its broader healthcare technology portfolio, offering comprehensive medical systems. Specialists in highly portable handheld devices include AccuVein Inc., emphasizing ease of use across diverse clinical settings. Christie Medical Holdings Inc. occupies a position among projection-based technology providers, focusing on hands-free operation for clinical efficiency.
| Leading Market Players |
|---|
| AccuVein Inc. |
| Christie Medical Holdings Inc. |
| TransLite LLC |
| Venoscope LLC |
| B. Braun Melsungen AG |
| Koninklijke Philips N.V. |
| ZD Medical Inc. |
| Infinium Medical Inc. |
| Vivolight |
| Others |
Cost & Logistics Intelligence
Large hospital systems, particularly integrated delivery networks in the United States, drive demand for bundled agreements. These contracts often combine device acquisition with ongoing software updates and maintenance services.
Pricing Analysis
Bundled procurement contracts define the pricing structure for advanced vein illumination devices. Price differentiation stems from deep electronic health record integration and comprehensive after-sales service packages. Pricing softness runs through the standalone device segment due to competition from lower-cost alternatives. Smaller clinics and outpatient centers exhibit high price sensitivity, while large hospital systems prioritize long-term value and integrated solutions.
Supply Chain Analysis
Specialized engineering talent availability in the United States and Germany influences core component manufacturing for vein illumination devices. Supply concentration centers on these regions, alongside China for assembly and scaling. The production process relies on miniaturized near-infrared sensors and compact laser projection modules. A structural risk involves single-source vulnerability for highly specialized optical components. Distribution runs through direct sales teams to large hospital networks and medical device distributors for smaller clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vein illumination devices market presents a geographic-arbitrage opportunity, given the differing regulatory compliance costs between the United States' FDA 510(k) and Europe's Medical Device Regulation (MDR). This disparity influences market entry strategies and product development timelines.
For Market Incumbents: Anticipate the disruptive impact of AI-driven analytics by investing heavily in internal research and development for superior vein pattern recognition. Deepen existing electronic health record integration capabilities to reinforce clinical workflow value, countering the threat of standalone, low-cost alternatives. Expand clinical training programs across large hospital systems, ensuring consistent device efficacy and user proficiency. Pursue strategic acquisitions of specialized software firms to accelerate AI integration.
For New Entrants and Emerging Players: Launch via direct-to-consumer channels or specialized distribution partnerships, targeting underpenetrated segments like homecare and veterinary medicine. Develop highly portable, user-friendly devices specifically designed for visiting nurses, addressing the growing demand for home infusion therapy. Focus on achieving rapid regulatory approvals, such as the FDA 510(k), for niche applications where established players have less focus. Prioritize cost-effective solutions for smaller clinics in emerging economies.
For Investors and Strategic Acquirers: Large medical technology conglomerates are the most active acquirers in this space, seeking to integrate advanced imaging capabilities. The long-term viability over a 5-10 year window hinges on successful software integration and AI-driven analytics. Target acquisition archetypes include specialized firms developing miniaturized near-infrared sensors or advanced vein pattern recognition algorithms. The signal to watch is the establishment of specific and consistent reimbursement codes for vein illumination device usage.
| Strategic Initiative | Industry Significance |
|---|---|
| Software Companion Development | Integrating devices with existing electronic health record platforms enhances clinical workflow and data capture for large hospital systems. |
| CE Marking Pathway Acceleration | Expediting regulatory approvals under Europe's Medical Device Regulation (MDR) secures market access and competitive advantage in a key region. |
| Hospital System Partnership | Collaborating with large integrated delivery networks in the United States ensures broader device adoption and long-term service contracts. |
| Miniaturized Device Launch | Introducing highly portable, handheld devices expands market reach into homecare settings and mobile phlebotomy services. |
| AI-Driven Analytics Integration | Embedding artificial intelligence algorithms improves vein pattern recognition and guides catheter placement, boosting device accuracy for clinicians. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with robust secondary validation. Primary data involved discussions with clinicians, hospital procurement managers, medical device engineers, and regulatory affairs specialists. Secondary sources included FDA 510(k) filings, CE marking documentation, medical journal articles, and company annual reports. This approach facilitated bottom-up and top-down triangulation for comprehensive market understanding.
Historical market performance established the baseline for projecting growth across the analysis window. The analytical framework modeled key segmentation dimensions: product type, application, end-user, technology, and device portability. Compound annual growth rates were derived from a synthesis of historical trends and projected demand drivers. Key forecast inputs included healthcare expenditure trends and demographic shifts in geriatric populations.
Several conditions sit outside the modeled scope, including unforeseen technological breakthroughs and global pandemic impacts. Forecasts reflect assumptions regarding regulatory stability and healthcare infrastructure development. Material deviation in reimbursement policies or new regulatory frameworks warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Middle East and Africa Non-Surgical Procedures Market
Medical Devices
Intrapartum Monitors Market
Medical Devices
Transcutaneous Electrical Nerve Stimulation Market
Medical Devices
Neurovascular Devices Market
Medical Devices
Middle East and Africa Refractive Surgery Devices Market
Medical Devices
Global Wearable Healthcare Devices Market
Medical Devices
Ostomy Drainage Systems Market
Medical Devices
High Viscosity Bone Cement Market
Medical Devices
Global Ventilators Market
Medical Devices
North America Neurostimulation Devices Market
Medical Devices
Electric Heated Eye Mask Market
Medical Devices
Kidney Stone Management Devices Market
Medical Devices
Bone Anchored Hearing Aids Market
Medical Devices
Light Therapy Beauty Devices Market
Medical Devices
Small Bone and Joint Devices Market
Medical Devices
Global Intravenous (IV) Equipment Market